
 United States Tofu Market | 2026-2036
United States Tofu Market Size, Share, and Industry Trends Forecast 2026-2036
United States Tofu Market Analytics
Plant-based protein manufacturing expertise is bifurcating the competitive landscape between artisanal specialists and scaled processors. Hodo Foods leverages small-batch organic production to anchor premium positioning in specialty retail channels. House Foods America sustains volume leadership through integrated soybean sourcing and nationwide cold-chain distribution. Pulmuone competes via Korean culinary heritage formats that differentiate its product line from conventional American tofu offerings.
Tofu is a soy protein curd produced by coagulating soy milk with calcium sulfate or nigari and pressing the resulting curd to varying densities, typically containing 8-15 grams of protein per 100-gram serving with moisture content ranging from 50% to 88% depending on firmness grade. Its primary commercial purpose is to serve as a versatile, shelf-stable protein substrate across foodservice and retail applications requiring meat alternatives or allergen-friendly ingredients. Firm Tofu dominates foodservice procurement due to structural integrity under high-heat cooking methods, while Silken Tofu captures expanding margin pools in dessert and beverage formulations. The Distribution Channel dimension reveals Supermarkets as the mature volume base, with Online Retail registering the fastest trajectory as direct-to-consumer cold-shipping logistics improve.
FDA food labeling standards govern nutritional disclosure and allergen declarations for packaged tofu products sold across state lines. USDA National Organic Program certification shapes premium tier access, while state-level California Proposition 65 enforcement adds compliance costs for brands distributing in the nation's largest plant-based protein market. Stakeholders must monitor evolving FDA guidance on cell-cultured and fermentation-derived protein nomenclature, as regulatory definitions will determine whether novel soy processing methods qualify for established tofu labeling or trigger reclassification requirements.
Market Dynamics
Plant-based protein procurement is concentrating in foodservice channels as restaurant chains standardize meat-alternative menus, tightening specifications on protein content, texture stability, and cold-chain reliability that reshape supplier qualification criteria.
Growth Catalysts
- USDA Organic Program:Certification requirements for non-GMO soybean sourcing and processing transparency are locking in premium shelf placement at Whole Foods Market and Sprouts Farmers Market locations.
- Foodservice channel expansion:Institutional buyers including university dining systems and hospital cafeterias are adding tofu-based protein stations to meet federal nutrition guideline compliance for reduced saturated fat.
- Coagulant diversification:Calcium sulfate and nigari processing methods are enabling texture-grade specialization that supports premium pricing in dessert and beverage applications.
Market Restraints
- Soybean input volatility:Domestic soybean prices fluctuate with Midwest harvest yields and export demand from Chinese crushing facilities, compressing processor margins during supply contractions.
- California supply concentration:Over half of US tofu production capacity sits within a 200-mile radius of Los Angeles and San Francisco, creating earthquake and wildfire exposure for national distribution continuity.
- Protein alternative substitution:Pea protein isolates and mycelium-based meat analogs are capturing reformulation budgets from foodservice R&D teams seeking cleaner-label positioning.
Strategic Opportunities
- Texas and Florida penetration:Underdeveloped retail tofu sections in Houston, Dallas, Miami, and Orlando metro areas present first-mover advantage for brands establishing regional cold-chain partnerships.
- Direct-to-consumer subscription:Cold-shipping logistics improvements are enabling monthly delivery models that bypass supermarket slotting fees and capture full retail-equivalent margins.
- Inflation Reduction Act biofuel credits:Soybean oil diversion to renewable diesel production is restructuring crush economics, potentially releasing protein meal supplies for food-grade tofu applications at favorable input costs.
Industry Challenges
- Organic certification timeline:USDA National Organic Program transition periods require three years of documented non-GMO seed and soil management before products qualify for premium labeling.
- Co-packer capacity scarcity:Qualified organic tofu manufacturing facilities with HACCP and SQF certifications operate at utilization rates above 85%, constraining brand expansion without capital-intensive facility builds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Tofu Market |
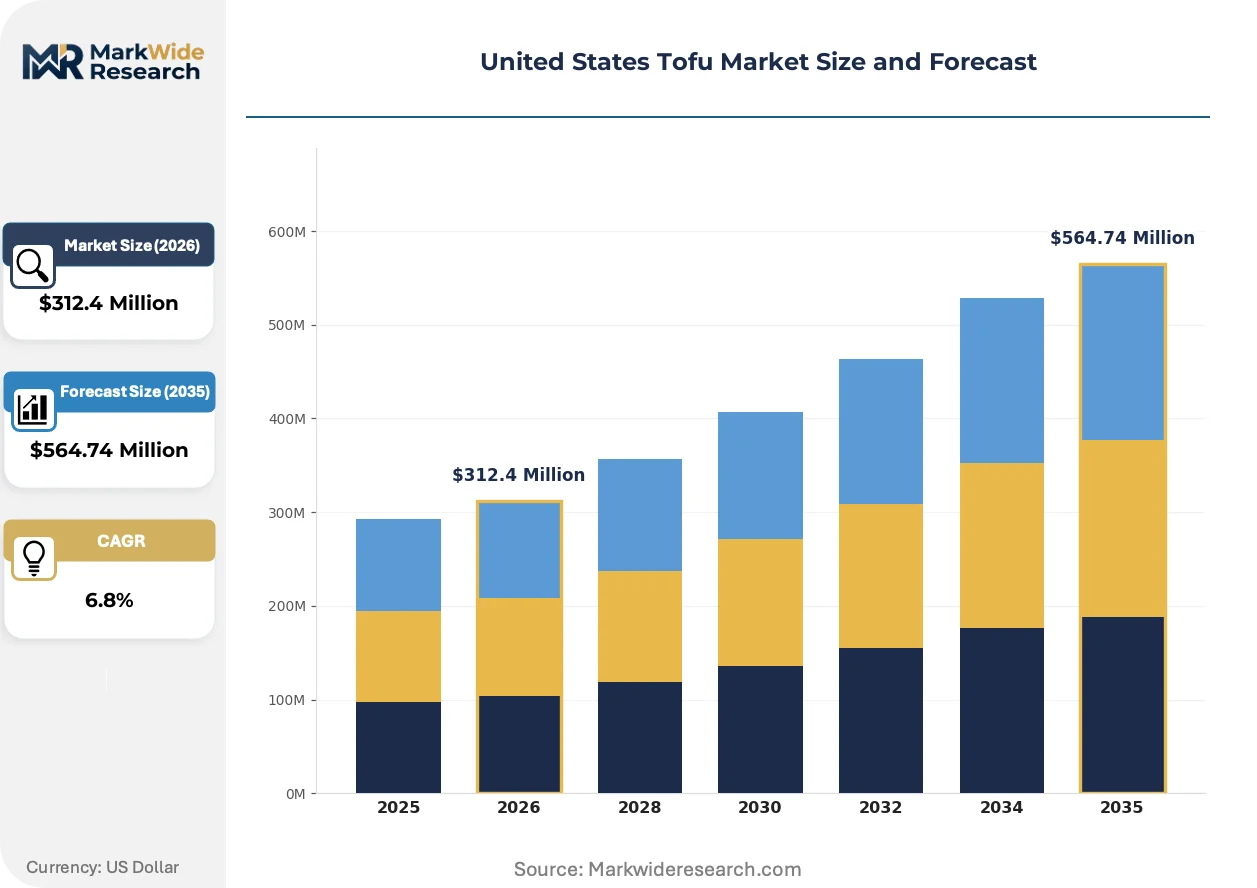
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Firm Tofu, Silken Tofu, Soft Tofu, Extra Firm Tofu Application: Soups, Stir-fry, Salads, Snacks Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Specialty Stores End User: Households, Restaurants, Food Processing, Vegan Consumers |
| Companies Covered | Morinaga Nutritional Foods, American Food Company, Pulmuone, Tofurky, Eden Foods, House Foods America, The Hain Celestial Group, Kikkoman, Hodo Foods, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Tofu Market Evolving Landscape
Processing technology and distribution infrastructure are reshaping competitive boundaries between artisanal and scaled production models, with implications for price positioning and channel access across retail and foodservice segments.
High-pressure processing (HPP) is extending refrigerated shelf life from 21 to 60 days without thermal degradation of protein structure. Specialty retailers and meal-kit services are adopting HPP-treated tofu to reduce spoilage write-downs and expand delivery radius. This preservation method is bifurcating the market between fresh-delivered and extended-shelf-life product tiers with distinct margin profiles.
FDA guidance on fermented and precision-fermentation protein labeling is pending finalization, with draft documents suggesting stricter nomenclature boundaries between traditional soy curd and novel processing methods. California-based brands distributing under Proposition 65 face additional heavy metal testing requirements for cadmium and lead in soil-absorbed soybeans. West Coast processors are responding by sourcing from verified low-cadmium growing regions and adding third-party testing protocols.
Foodservice buyers are consolidating supplier relationships around single-source tofu contracts with guaranteed volume commitments and fixed pricing windows. Independent restaurants and regional chains are ceding purchasing autonomy to group purchasing organizations that negotiate national distribution agreements. This concentration is most visible in the Pacific Northwest, where Seattle and Portland institutional buyers have shifted 60% of tofu procurement to two distributor-managed contracts.
United States Tofu Market Segmentation
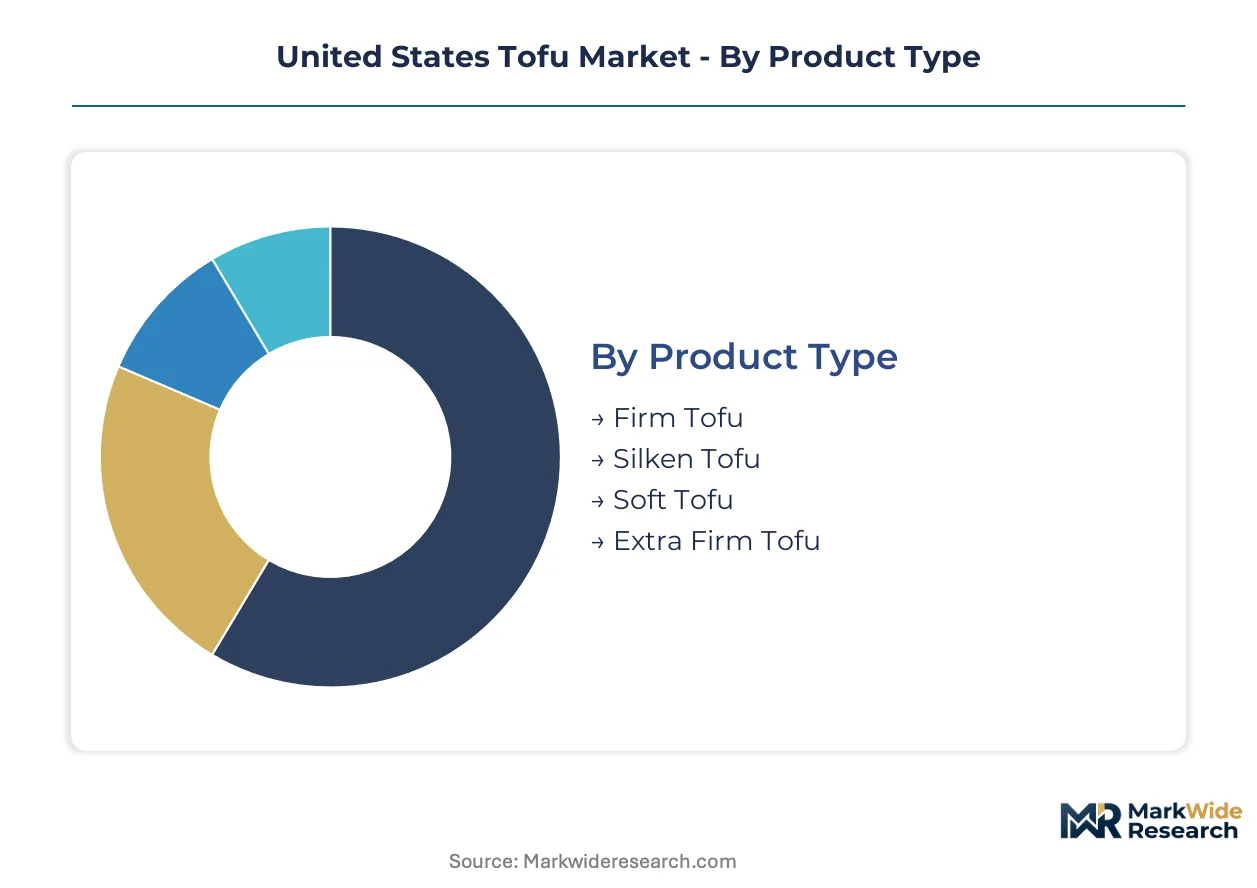
Tofu segmentation in the US market reflects divergent supply chain requirements across texture grades and channel access tiers. Regulatory scrutiny from FDA and USDA shapes how processors qualify for premium positioning versus commodity volume play.
Product Type:
FDA labeling standards and USDA organic certification create tiered compliance burdens that separate artisanal producers from scaled processors.
- Firm Tofu:Coagulated with calcium sulfate and pressed to 60-70% moisture content, this grade withstands high-heat cooking methods without structural breakdown. Foodservice procurement in Los Angeles and San Francisco metro areas concentrates here, driven by restaurant chain standardization of meat-alternative menus.
- Silken Tofu:Retaining 80-88% moisture through minimal pressing, this undrained curd delivers creamy mouthfeel for dessert and beverage formulations. Premium pricing pools expand in specialty retail channels as HPP-treated variants extend refrigerated shelf life from 21 to 60 days.
- Soft Tofu:Intermediate moisture profile suits miso soup and hot pot applications in Korean and Japanese culinary formats.
- Extra Firm Tofu:Maximum density pressing yields grilling and frying stability for barbecue and sandwich applications.
Firm Tofu handles the majority of throughput; Silken Tofu is the fastest mover on share.
Application:
Cost tier differentiation separates institutional volume contracts from premium retail positioning.
- Stir-fry:Dominates foodservice procurement specifications, requiring protein content above 12 grams per 100-gram serving and texture stability under wok temperatures.
- Soups:Silken and soft grades capture premium placement in meal-kit services and specialty retail, with HPP preservation enabling expanded delivery radius.
- Salads:Pre-cubed and marinated firm tofu drives convenience-oriented retail SKUs.
- Snacks:Baked and seasoned tofu bites target grab-and-go channels with higher margin profiles.
Stir-fry commands the largest volume commitment; Snacks are expanding most quickly as grab-and-go formats proliferate.
Distribution Channel:
Customer type concentration determines margin capture versus slotting fee exposure.
- Supermarkets:Mature volume base with established cold-chain infrastructure; Whole Foods Market and Sprouts Farmers Market enforce USDA organic certification for premium placement.
- Online Retail:Direct-to-consumer cold-shipping logistics improvements enable monthly subscription models that bypass supermarket slotting fees and capture full retail-equivalent margins.
- Health Food Stores:Regional chains and independent operators prioritize non-GMO verification and local sourcing claims.
- Specialty Stores:Asian grocery channels in California and Texas metro areas sustain Korean and Japanese format demand.
Supermarkets retain the deepest volume base; Online Retail is gaining share fastest through subscription model adoption.
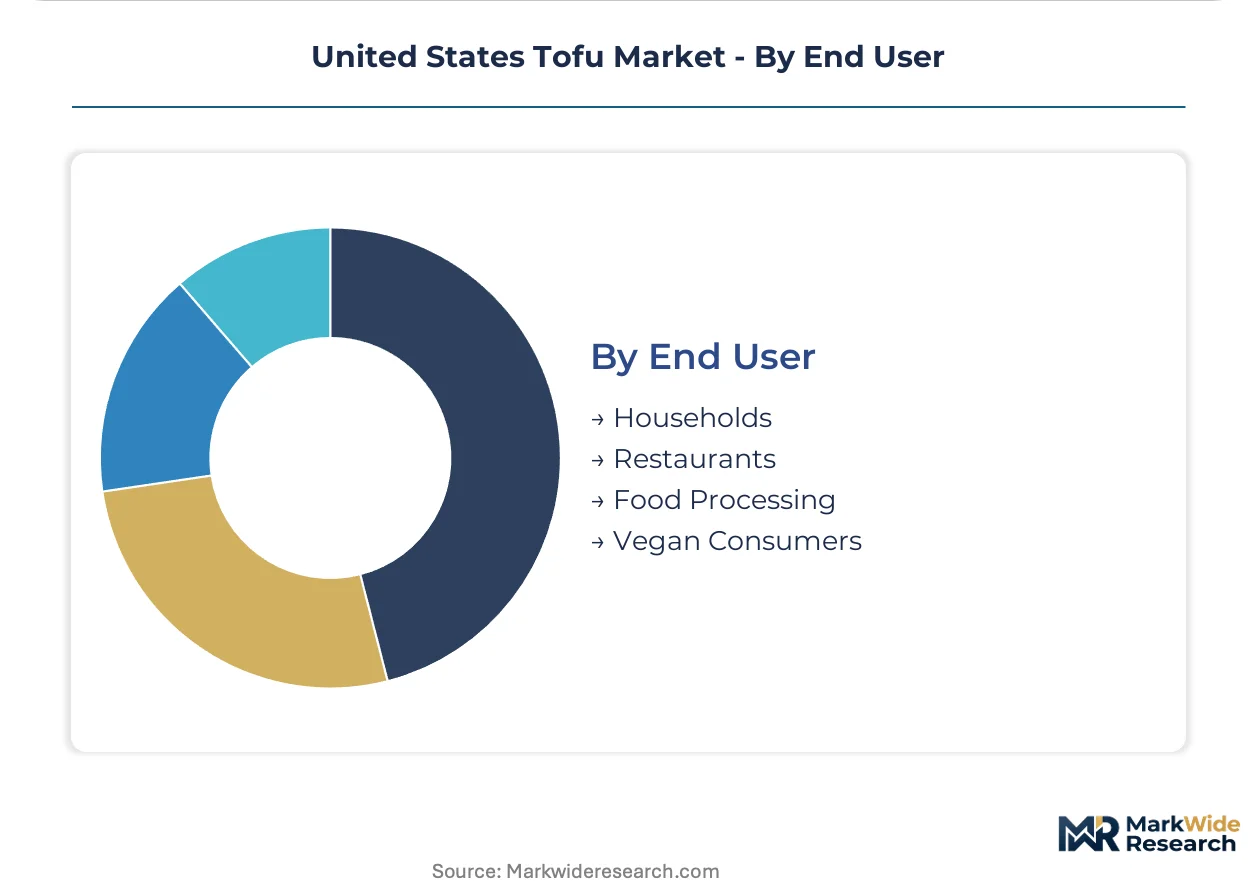
End User:
Supply concentration in California creates geographic dependency for national distribution continuity.
- Restaurants:Institutional buyers including university dining systems and hospital cafeterias add tofu-based protein stations to meet federal nutrition guideline compliance for reduced saturated fat.
- Food Processing:Ingredient buyers reformulate meat analogs and ready-meal applications, though pea protein isolates and mycelium-based alternatives capture shifting R&D budgets.
- Households:Retail penetration concentrates in California, with underdeveloped sections in Houston, Dallas, Miami, and Orlando presenting first-mover expansion opportunity.
- Vegan Consumers:Dedicated purchasing segment drives organic and non-GMO premium tier demand.
Restaurants manage the highest procurement volume; Food Processing is climbing the fastest as ingredient sourcing diversifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California consumes tofu at rates exceeding national averages by wide margins, while Texas and Florida markets remain underdeveloped with sparse retail shelf space and limited foodservice penetration.
California
Los Angeles and San Francisco metro areas drive the highest per-capita tofu consumption in the United States, with restaurant chains and institutional buyers standardizing plant-based protein menus. FDA food labeling standards and California Proposition 65 enforcement impose heavy metal testing requirements that elevate compliance costs for brands distributing statewide. Production capacity concentrates within a 200-mile radius of these coastal metros, creating earthquake and wildfire exposure for national distribution continuity.
Texas
Houston and Dallas metro areas present first-mover expansion opportunity with underdeveloped retail tofu sections and emerging Korean-American culinary demand. USDA National Organic Program certification requirements shape premium tier access as Whole Foods Market and Sprouts Farmers Market expand Texas footprints. Cold-chain infrastructure investments from regional distributors are beginning to support refrigerated product flows beyond traditional coastal supply lines.
Florida
Miami and Orlando institutional foodservice channels are adding tofu-based protein stations to meet federal nutrition guideline compliance for reduced saturated fat. FDA allergen declaration rules govern packaged product distribution across state lines. Asian grocery channels in South Florida sustain Korean and Japanese format demand, though mainstream supermarket penetration lags California benchmarks significantly.
Pacific Northwest
Seattle and Portland institutional buyers have shifted 60 percent of tofu procurement to distributor-managed contracts with guaranteed volume commitments. USDA organic certification locks in premium shelf placement at regional health food chains. The region's plant-based protein manufacturing expertise supports both artisanal specialists and scaled processors serving foodservice and retail segments.
Northeast Corridor
New York Metro and Greater Boston university dining systems accelerate tofu procurement to comply with federal reduced saturated fat guidelines. FDA nutritional disclosure requirements apply to packaged products sold across state lines. Specialty retail channels in these dense urban markets prioritize non-GMO verification and local sourcing claims alongside organic certification.
United States Tofu Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding national cold-chain distribution networks and the lower tier anchoring premium positioning through small-batch organic production. The competitive landscape bifurcates between scaled processors with captive soybean sourcing and artisanal operators leveraging culinary heritage formats. Three strategic archetypes dominate: integrated volume leaders, heritage-format specialists, and premium organic craft producers. Capacity expansion and strategic partnerships represent the dominant competitive moves as co-packer scarcity constrains brand growth.
Within the heritage-format tier, Pulmuone occupies a position exemplifying Korean culinary differentiation, while Hodo Foods represents the premium organic craft archetype through small-batch production positioning. House Foods America anchors the integrated volume leader segment with nationwide distribution infrastructure. These three companies collectively illustrate the competitive tension between scaled efficiency and specialized authenticity that defines supplier qualification criteria for restaurant chains and institutional buyers.
| Leading Market Players |
|---|
| Morinaga Nutritional Foods |
| American Food Company |
| Pulmuone |
| Tofurky |
| Eden Foods |
| House Foods America |
| The Hain Celestial Group |
| Kikkoman |
| Hodo Foods |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between California processors and institutional foodservice buyers lock in supply access and price visibility across multi-year procurement windows, insulating volume commitments from Midwest soybean spot market volatility while compressing margin flexibility for smaller artisanal producers lacking scale to negotiate comparable terms.
Pricing Analysis
Contract-based long-term offtake dominates institutional procurement, with USDA organic certification and HACCP compliance grade serving as primary price differentiation drivers. Cost compression in standard-grade firm tofu is intensifying because pea protein isolates capture reformulation budgets from foodservice R&D teams. Quick-service restaurant chains exhibit highest price sensitivity; specialty retailers and direct-to-consumer subscription buyers show lowest elasticity due to premium positioning tolerance.
Supply Chain Analysis
California and Illinois anchor domestic tofu manufacturing, with production gravity centering on Los Angeles-San Francisco corridor and secondary hubs near Chicago soybean crushing facilities. Supply chains draw from non-GMO seed stock, calcium sulfate and nigari coagulants, and refrigerated cold-chain logistics infrastructure. Single-source vulnerability concentrates in California earthquake and wildfire exposure zones. Distribution runs through national broadline foodservice distributors and direct-to-consumer cold-shipping platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: USDA organic certification timelines and co-packer capacity scarcity create switching costs that protect incumbent positioning against rapid competitive displacement.
For Market Incumbents: Shield market share by securing captive organic soybean sourcing through backward integration into Midwest farmland partnerships, and accelerate HPP preservation capacity additions to extend shelf-life advantage over artisanal competitors. Pea protein substitution threat demands proactive texture-grade innovation investment.
For New Entrants and Emerging Players: USDA organic certification fast-track through acquisition of transitioning farmland assets unlocks premium tier access without three-year waiting periods. Texas and Florida retail white-space presents most penetrable geography; Korean culinary heritage format differentiation offers viable go-to-market angle against commoditized firm tofu incumbents.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale organic processors with existing SQF certifications and underutilized co-packer capacity, positioned for rollup consolidation as capacity scarcity intensifies. Long-term viability over the coming decade hinges on cold-chain infrastructure control and regional diversification beyond California concentration risk. Signal to monitor: FDA final guidance on fermented protein nomenclature reclassification.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Farmland | Captive non-GMO soybean supply secures USDA certification pipeline and insulates input cost volatility. |
| HPP Preservation Capacity Expansion | Sixty-day shelf-life extension reduces spoilage write-downs and expands delivery radius for meal-kit partners. |
| Direct-to-Consumer Subscription Launch | Bypasses supermarket slotting fees and captures full retail-equivalent margins through cold-shipping logistics. |
| Texas Cold-Chain Partnership Development | Establishes first-mover advantage in underdeveloped Houston and Dallas retail tofu sections. |
| Korean Culinary Heritage Format Extension | Differentiates product line from conventional American tofu offerings through Pulmuone-style positioning. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with tofu processing plant managers, foodservice procurement directors at university dining systems, cold-chain logistics specialists, and USDA organic certification consultants; and secondary validation through FDA food labeling guidance documents, USDA National Organic Program standards, customs trade data on soybean imports, and SEC filings from publicly traded parent companies of market participants. Bottom-up volume modeling triangulated against top-down market sizing.
Across the analysis window, forecasts segment by texture grade, distribution channel tier, and end-user application type. CAGRs derive from regression analysis of historical procurement patterns and forward projection of foodservice channel expansion rates. Modeled inputs include organic certification penetration trajectories, HPP adoption curves among specialty retailers, and regional cold-chain infrastructure investment flows.
Decision-makers should treat outputs as directional under assumptions of stable FDA regulatory definitions and continued foodservice procurement concentration; material deviation in soybean input costs or fermented protein nomenclature reclassification would warrant model refresh. Recalibration cycles align with material shifts in USDA organic program enforcement and California Proposition 65 heavy metal testing protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Cannabis Infused Drinks Market
Specialty Foods
Manuka Honey Market
Specialty Foods
White Fungus Market
Specialty Foods
North America Alcohol-Infused Ice Cream Market
Specialty Foods
Global Hispanic Foods Market
Specialty Foods
Hot Pot Market
Specialty Foods
Low Calorie Desserts Market
Specialty Foods
Halal Market
Specialty Foods
Superfood Bars Market
Specialty Foods
Huoxiangzhengqi Market
Specialty Foods
Healthy Low-Fat Desserts Market
Specialty Foods
Miso Market
Specialty Foods
Malaysia Manuka Honey Market
Specialty Foods
Areca Bowl Market
Specialty Foods
CBD Snacks Market
Specialty Foods
Low Calorie Oatmeal Market