
 Hot and Sour Noodles Market | 2026-2036
Hot and Sour Noodles Market Size, Share, and Industry Trends Forecast 2026-2036
Hot and Sour Noodles Market Insights
China is tilting toward expanded instant noodle capacity to serve rising domestic and export appetite for hot and sour formats. Nongshim leverages its fermentation technology leadership to sustain premium positioning across Asian retail channels. Master Kong anchors mainland distribution through deep provincial penetration and localized flavor adaptation. Ottogi competes on Korean chili paste integration, differentiating its broth chemistry from mass-market alternatives.
Hot and sour noodles denote wheat or starch-based strands preserved through dehydration, flash-frying, or freezing, then paired with vinegar-forward, chili-oil-infused seasoning systems designed for sub-five-minute preparation. The category serves commercial foodservice, household convenience meals, and travel consumption occasions where equipment-free heating dominates. Instant formats lead volume throughput due to shelf stability and price accessibility, though fresh and frozen segments capture margin pools through refrigerated logistics and shorter ingredient decks. Bowl packaging outpaces packet growth in urban convenience channels, while rice and buckwheat ingredient sources attract consumers seeking alternatives to wheat-dominant formulations.
China's SAMR enforces GB standards on additive limits and sodium disclosure, tightening formulation latitude for manufacturers targeting domestic shelves. South Korea's MFDS and the EU's EFSA both scrutinize capsaicin levels and preservative thresholds in imported instant noodle shipments, conditioning market access protocols. India's FSSAI mandates vegetarian labeling distinctions that reshape seasoning oil sourcing for brands entering that market. Stakeholders must monitor how dual carbon goals across China's MEE and South Korea's METI redirect energy-intensive frying processes toward air-dried or fresh alternatives.
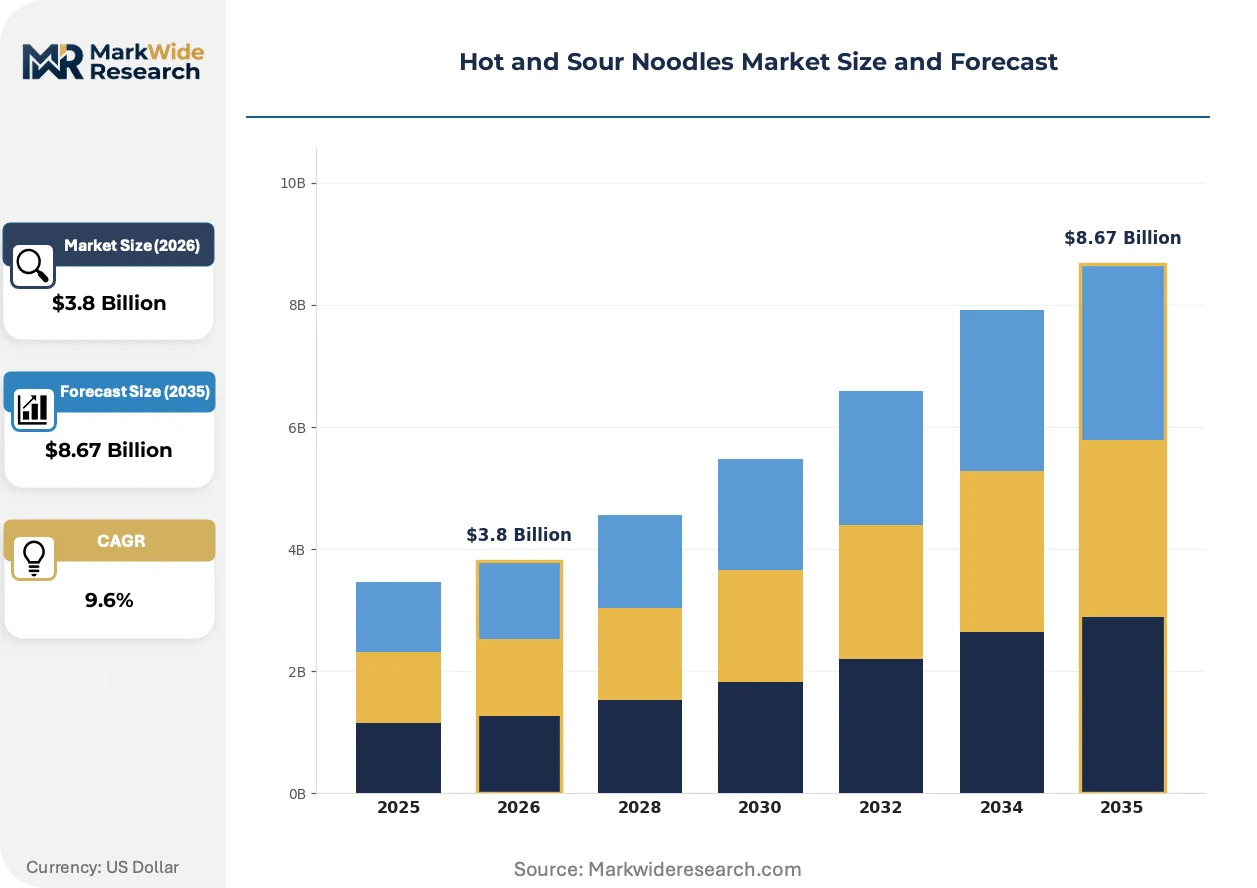
Market Dynamics
China's SAMR enforcement of GB food safety standards on sodium disclosure and additive limits is compressing formulation flexibility for manufacturers, forcing recipe reformulation and supply chain restructuring across the instant noodle value chain.
Growth Catalysts
- Urban Convenience Consumption:Young professionals in Vietnam and Thailand digitize street-food culture into packaged formats, expanding bowl-packaged instant noodle penetration in convenience retail channels.
- Dual Carbon Policy Pressure:China's MEE energy-efficiency mandates redirect capital toward air-dried noodle lines, reducing frying-process emissions while opening premium positioning for lower-oil products.
- Export Standard Harmonization:South Korea's MFDS capsaicin testing protocols create de facto quality benchmarks that Korean manufacturers leverage for regional shelf access.
Market Restraints
- Wheat Price Volatility:Input cost swings in Australian and Black Sea grain markets squeeze margin structures for wheat-dependent noodle producers.
- Preservative Threshold Friction:EFSA scrutiny of benzoate levels in EU-bound shipments creates batch-testing burdens that delay customs clearance for Asian exporters.
- Fresh Segment Logistics:Refrigerated cold-chain requirements for non-dehydrated formats limit distribution radius and inflate last-mile costs versus shelf-stable alternatives.
Strategic Opportunities
- India Vegetarian Labeling:FSSAI-mandated vegetarian distinctions create first-mover advantage for brands reformulating seasoning oils to capture India's underpenetrated instant noodle demand.
- Buckwheat Ingredient Pivot:Consumer migration from wheat-dominant formulations opens formulation white space for Korean and Japanese buckwheat-sourced product lines.
- Travel Retail Channel Expansion:Equipment-free heating formats align with airport and railway convenience store placement, capturing transit consumption occasions.
Industry Challenges
- Fermentation Technician Scarcity:Premium broth chemistry requires specialized workforce capabilities that outpace vocational training pipeline output in Southeast Asia.
- Legacy Frying Asset Stranding:Capital-intensive oil-frying lines face accelerated obsolescence under China's dual carbon timeline, complicating depreciation schedules.
- Cross-Border Certification Lag:Divergent sodium disclosure rules between China's SAMR and South Korea's MFDS force parallel testing regimes that extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hot and Sour Noodles Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.67 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant, Dried, Frozen, Fresh Flavor Profile: Spicy, Tangy, Savory, Umami Ingredient Source: Wheat, Rice, Buckwheat, Vegetable Packaging Type: Bowl, Packet, Cup, Tray |
| Companies Covered | Indomie, Nongshim, Ottogi, Nissin Foods, Samyang Foods, Master Kong, Nestlé, Maruchan, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hot and Sour Noodles Market Trends and Innovations
Non-fried dehydration technology, regulatory sodium compression, and digital-native distribution models are restructuring competitive advantage across the hot and sour noodle category.
Air-dried noodle processing eliminates the energy-intensive flash-frying stage while preserving texture through controlled hot-air circulation. Premium brands in South Korea and China adopt these lines to satisfy METI and MEE carbon accounting requirements. This capital reallocation is rendering obsolete the traditional oil-frying infrastructure that dominated twentieth-century instant noodle manufacturing.
REACH-compliant additive reformulation is reshaping seasoning chemistry for EU-bound exports. EFSA evaluations of capsaicin extract purity force suppliers to document supply chain provenance for chili oil components. European import channels now demand third-party laboratory certification that Asian manufacturers must integrate into quality assurance workflows.
Live-streaming commerce platforms in Vietnam and Thailand displace traditional distributor networks for youth-targeted launches. Influencer-led taste tests generate immediate demand signals that bowl-packaged SKUs fulfill through same-day delivery partnerships. This channel pivot concentrates marketing spend on short-video platforms rather than conventional retail slotting fees.
Hot and Sour Noodles Market Segmentation
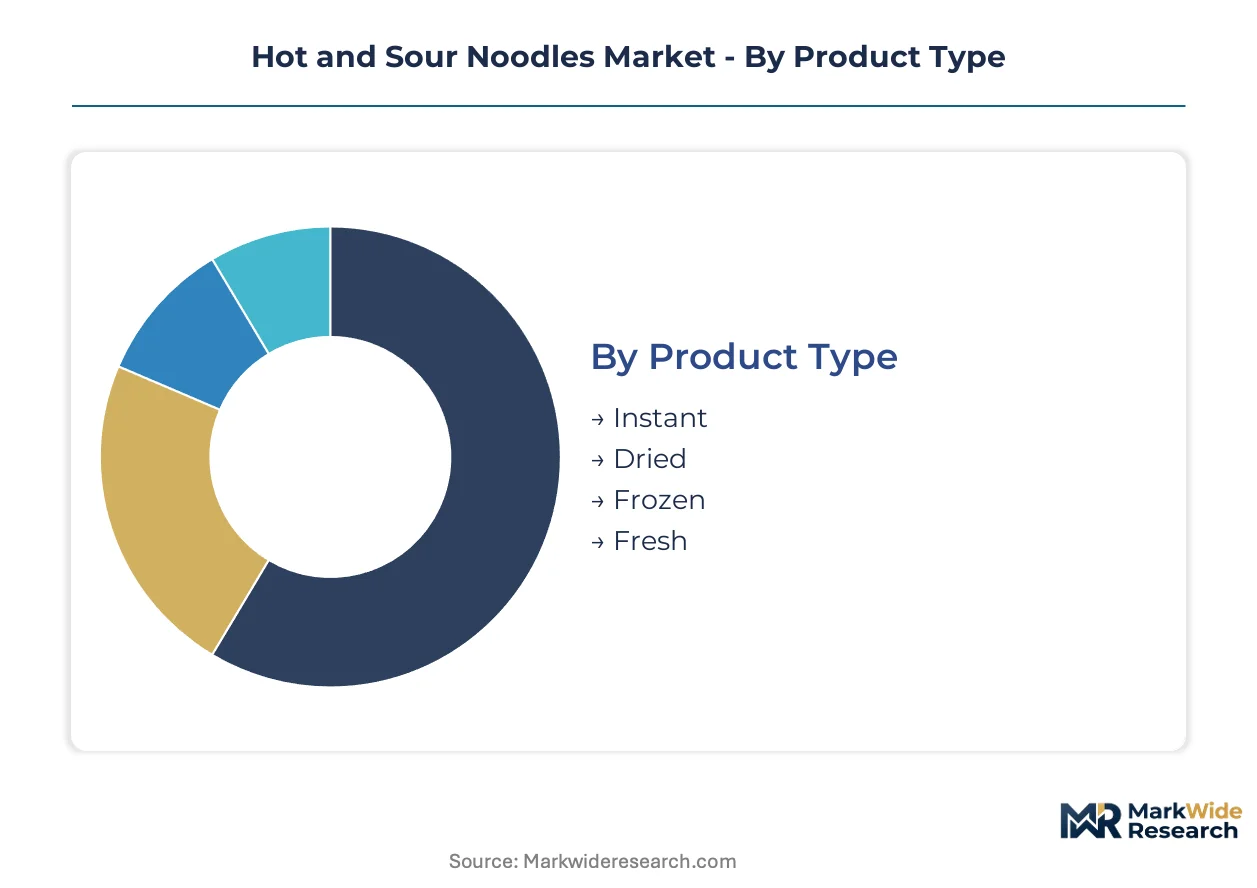
Segmentation in hot and sour noodles reveals how preservation technology, flavor chemistry, and format convenience split demand across distinct consumer occasions. Manufacturers configure production lines around these divides, with shelf stability and preparation speed determining channel access and margin capture.
Product Type:
Mature dehydration technologies dominate volume, while emerging preservation formats capture premium positioning through shorter ingredient decks and refrigerated logistics.
- Instant:Flash-fried or air-dried wheat strands paired with powdered seasoning sachets enable sub-three-minute preparation without cooking equipment. Vietnam and Thailand drive bowl-format adoption as young professionals digitize street-food consumption into convenience retail channels, though sodium disclosure rules under China's SAMR compress formulation flexibility.
- Dried:Traditional air-dried noodles require boiling but offer cleaner labels and lower oil content than fried alternatives. South Korean manufacturers leverage these lines to satisfy METI carbon accounting requirements, positioning them as premium alternatives to mass-market instant formats.
- Frozen:Par-cooked strands with separate broth blocks demand continuous cold chain but deliver restaurant-equivalent texture. Logistics costs limit distribution radius versus shelf-stable alternatives.
- Fresh:Refrigerated, short-shelf-life products with minimal processing attract health-conscious urban consumers in high-income Asian cities. Cold-chain requirements inflate last-mile costs.
Instant formats handle the majority of throughput; fresh products are expanding most quickly on share in premium urban channels.
Flavor Profile:
Cost tier stratification runs from commodity heat delivery to layered fermentation-based complexity, with chemistry sophistication determining export market access.
- Spicy:Capsaicin-forward heat levels calibrated to regional tolerance thresholds, with South Korea's MFDS testing protocols creating de facto quality benchmarks for regional shelf access. EFSA scrutiny of extract purity adds certification burdens for EU-bound shipments.
- Tangy:Vinegar-dominant profiles anchored in Sichuan and Shanxi culinary traditions, with acetic acid sourcing from rice or grain distillations determining authenticity signaling.
- Savory:Salt and hydrolyzed protein bases targeting mass-market palates across Southeast Asia, constrained by tightening sodium caps under China's GB standards.
- Umami:Fermented soybean, mushroom extract, and nucleotide-enhanced broth systems requiring specialized technician capabilities that outpace vocational training pipelines.
Savory formulations anchor volume in mass-market channels; umami profiles command the steepest price premiums and slowest volume scaling.
Ingredient Source:
Supply concentration in grain markets creates input cost volatility that reshapes margin structures across wheat-dependent versus alternative-carbohydrate formulations.
- Wheat:Standard gluten-based elasticity and neutral flavor absorption dominate global instant noodle manufacturing. Australian and Black Sea grain price swings squeeze producer margins unpredictably.
- Rice:Starch-based alternatives with distinct textural properties and hypoallergenic positioning, concentrated in Thai and Vietnamese production clusters serving domestic and export markets.
- Buckwheat:Korean and Japanese soba-derived formats attracting consumers migrating from wheat-dominant diets, with regional sourcing from Hokkaido and Gangwon-do creating supply bottlenecks.
- Vegetable:Spinach, carrot, or beet-infused strands for color differentiation and micronutrient claims, requiring careful moisture management during dehydration.
Wheat sources carry the bulk of global volume; buckwheat alternatives are climbing the fastest in premium positioning across health-conscious segments.
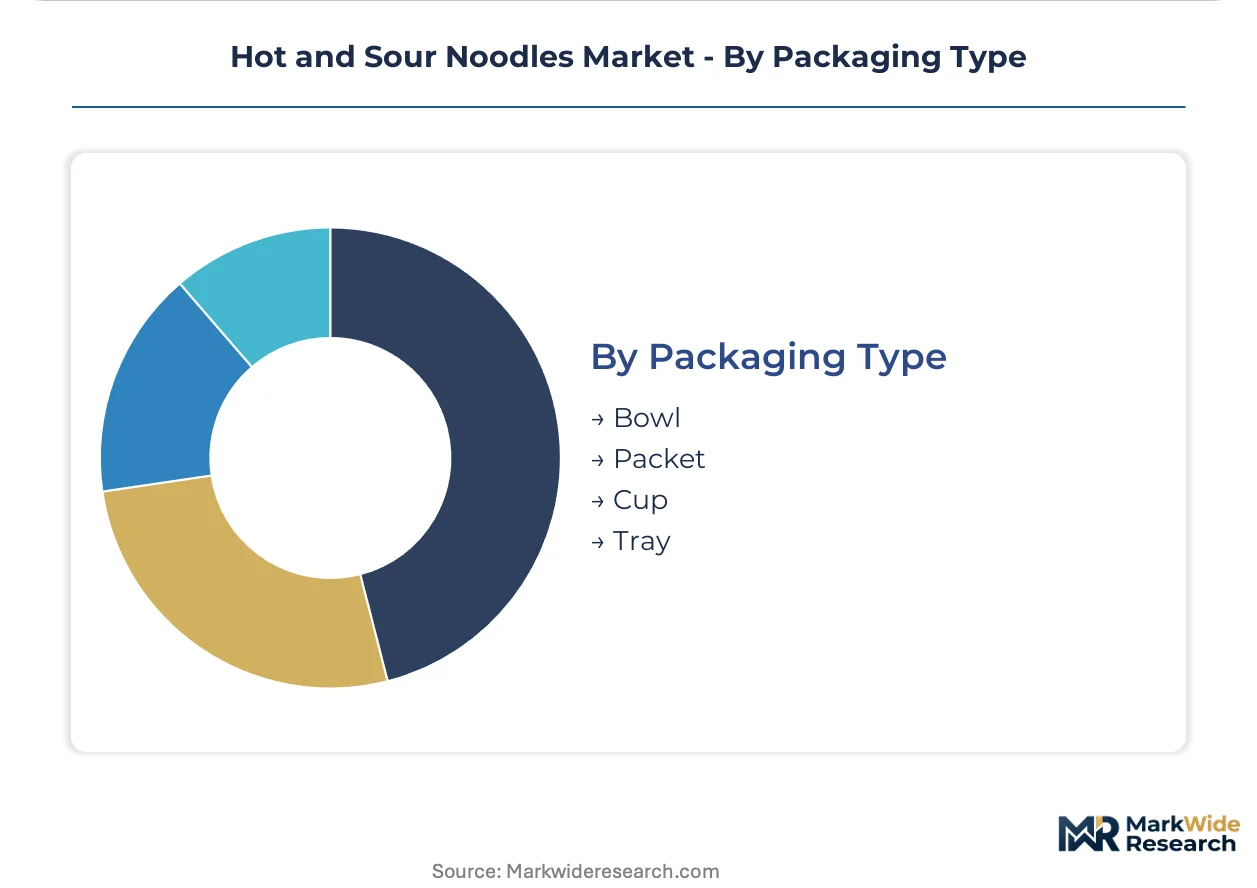
Packaging Type:
Customer type splits between single-serve immediate consumption and household stock-up economics, with format choice determining retail channel placement and logistics configuration.
- Bowl:Self-contained vessels with integrated lids and fold-out forks dominate convenience store and travel retail placement. Vietnam's live-streaming commerce platforms concentrate demand signals for bowl SKUs fulfilled through same-day delivery partnerships.
- Packet:Multi-serve bags targeting household pantry stocking, with lower per-gram packaging costs but requiring consumer-supplied cooking vessels.
- Cup:Compact cylindrical formats optimized for vending machine and office pantry channels, with thinner wall construction than bowls reducing material costs.
- Tray:Rectangular containers common in Japanese and Korean fresh noodle segments, suited for refrigerated retail display and premium positioning.
Bowl packaging commands the highest absolute revenue; cup formats are gaining share fastest in automated retail and transit channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR anchors regulatory gravity for hot and sour noodles through GB standards enforcement that reshapes formulation requirements across manufacturing hubs.
China
Provincial manufacturing clusters in Henan and Sichuan process the majority of domestic wheat supply into instant formats. The dual carbon goals under MEE redirect capital from oil-frying lines toward air-dried alternatives in Zhengzhou industrial zones. Master Kong leverages deep provincial distribution networks to adapt localized flavor profiles across county-level retail penetration.
South Korea
MFDS capsaicin testing protocols create de facto quality benchmarks that manufacturers leverage for regional export access. Seoul-based fermentation specialists supply premium broth chemistry to brands competing on umami complexity. Busan-Ulsan port infrastructure handles outbound shipments to Southeast Asian convenience retail channels.
Vietnam
Live-streaming commerce platforms concentrate demand signals for bowl-packaged SKUs among Ho Chi Minh City professionals digitizing street-food consumption. FSSAI-aligned vegetarian labeling experiments open reformulation pathways for seasoning oil sourcing. Da Nang logistics clusters support same-day delivery partnerships with short-video platform distributors.
Thailand
Bangkok metropolitan convenience retail channels absorb premium bowl formats targeting transit consumption occasions. Rice-based starch alternatives from Thai production clusters serve domestic and export markets seeking wheat diversification. Chiang Mai specialty producers experiment with localized chili-vinegar profiles for tourist-facing retail placement.
India
FSSAI-mandated vegetarian distinctions reshape seasoning oil sourcing for brands entering underpenetrated instant noodle demand. Maharashtra and Gujarat manufacturing zones adapt formulation lines to capture first-mover positioning. Mumbai and Delhi-NCR urban convenience channels test equipment-free heating formats for office pantry placement.
Hot and Sour Noodles Market Competitive Landscape
Capability concentration sits with fermentation-technology specialists; scale advantage sits with mass-market instant noodle conglomerates. The market structures around three tiers: premium broth-chemistry players, provincial distribution anchors, and diversified multinational food groups. Strategic moves concentrate on air-dried line conversion for carbon compliance and influencer-led channel pivots for youth demographic capture.
Within the fermentation-technology tier, Nongshim and Ottogi occupy positions defined by Korean chili paste integration and premium broth differentiation. Nissin Foods exemplifies the multinational scale archetype with diversified instant noodle portfolios spanning multiple Asian markets. Master Kong anchors the provincial penetration model through deep distribution networks and localized flavor adaptation across Chinese sub-regions.
| Leading Market Players |
|---|
| Indomie |
| Nongshim |
| Ottogi |
| Nissin Foods |
| Samyang Foods |
| Master Kong |
| Nestlé |
| Maruchan |
| Unilever |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Busan container corridor governs freight cost dynamics for wheat flour and chili oil shipments, concentrating supply power among Henan and Sichuan manufacturers while forcing downstream price stratification between air-dried premium tiers and mass-market fried alternatives.
Pricing Analysis
Geographic price spreads between Chinese provincial production and Southeast Asian retail endpoints exceed threefold for equivalent bowl formats. Three-tier pricing structure across premium, standard, and economy levels reflects fermentation complexity, sodium disclosure compliance costs under SAMR, and brand heritage positioning. Cost compression in economy tiers is intensifying because Australian wheat futures volatility squeezes margin structures. Street-food vendors and rural distributors exhibit highest price sensitivity; urban convenience retail channels absorb premium positioning with minimal volume elasticity.
Supply Chain Analysis
Tariff exposure between China and EU member states dominates supply chain risk planning for seasoning oil exporters facing EFSA benzoate scrutiny. Wheat sourcing concentrates in Australia, Ukraine, and domestic Chinese granaries; chili paste supply draws from Xinjiang and Sichuan processing clusters. Single-source vulnerability in Hokkaido buckwheat creates bottlenecks for Japanese soba-format alternatives. Distribution runs through provincial wholesale networks in China, live-streaming commerce platforms in Vietnam, and convenience retail chains in Thailand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment-free heating formats represent a service-attach opportunity where branded utensil bundles and subscription replenishment models expand faster than base product throughput.
For Market Incumbents: Insulate fermentation-technology advantages through captive supply of Sichuan peppercorn and aged vinegar stocks, countering emerging air-dried specialists threatening premium positioning. Deepen backward integration into Zhengzhou industrial zone air-drying capacity to satisfy MEE carbon accounting mandates before legacy frying asset obsolescence accelerates.
For New Entrants and Emerging Players: India's underpenetrated vegetarian-labeled instant noodle demand represents the most penetrable entry point, with Maharashtra manufacturing zones offering first-mover formulation adaptation. FSSAI-aligned seasoning oil sourcing combined with Mumbai office pantry channel partnerships provides defensible go-to-market positioning against established multinational distribution.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates with neglected instant noodle divisions lacking fermentation technician pipelines or air-dried line conversion capital. Long-term viability hinges on carbon-compliant processing infrastructure and influencer-channel access rather than legacy retail slotting relationships. Monitor MFDS capsaicin testing protocol adoption rates across Southeast Asian import authorities as inflection indicator for Korean manufacturer regional shelf access expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Air-Dried Line Conversion | MEE carbon accounting compliance redirects capital from obsolete oil-frying infrastructure toward premium positioning. |
| Vegetarian Labeling Reformulation | FSSAI-mandated distinctions unlock India's underpenetrated demand through seasoning oil supply chain restructuring. |
| Live-Streaming Commerce Partnership | Vietnam short-video platforms displace traditional distributor networks for youth-targeted bowl SKU launches. |
| Fermentation Technician Pipeline Investment | Seoul-based specialist scarcity constrains umami broth chemistry scaling across premium product tiers. |
| REACH-Compliant Additive Reformulation | EFSA capsaicin purity documentation requirements reshape EU-bound export quality assurance workflows. |
Research Methodology
A standing panel of fermentation R&D directors, provincial distribution managers, convenience retail category buyers, and SAMR regulatory compliance officers provided ongoing calibration across primary interview rounds. Secondary validation drew from Chinese customs wheat import records, MFDS food additive safety assessments, Vietnam e-commerce transaction databases, and EU REACH substance registration filings. Bottom-up production capacity modeling and top-down consumption survey triangulation anchored volume estimates.
Scenario-bracketing around carbon policy implementation pace and live-streaming channel penetration rates structured the analytical framework across the analysis window. Segmentation dimensions modeled include preservation technology, flavor chemistry sophistication, ingredient source, and packaging format convenience. CAGRs derived from production line investment trajectories, provincial retail audit data, and cross-border shipment manifests. Forecast inputs incorporated MEE dual carbon timeline uncertainty and EFSA additive threshold evolution.
Practitioners should monitor wheat futures volatility, SAMR sodium disclosure enforcement intensity, and short-video platform commission rate changes for early signals of forecast revision necessity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Acacia Honey Market
Specialty Foods
Edible Mushroom Market
Specialty Foods
Asia Pacific Cat Food Market
Specialty Foods
Hot Pot Market
Specialty Foods
Jams, Jellies & Preserves Market
Specialty Foods
Hairball Cat Food Market
Specialty Foods
Triphala Powder Market
Specialty Foods
Miso Market
Specialty Foods
Gluten-Free Oats Market
Specialty Foods
Wet Grain-Free Pet Food Market
Specialty Foods
Marine Thermal Water Ferments Market
Specialty Foods
High Protein Cat Food Market
Specialty Foods
Human Grade Pet Food Market
Specialty Foods
Dill Juice Market
Specialty Foods
Global Sauerkrauts Market
Specialty Foods
Europe Hummus Market