
 Industrial Margarine Market | 2026-2036
Industrial Margarine Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Margarine Market Analysis
Premium non-hydrogenated formulation tiers are rotating toward center stage as food processors reformulate to meet tightening trans-fat limits. Wilmar International leverages integrated palm oil refining networks across Southeast Asia to secure feedstock cost advantages. Bunge Limited anchors North American supply through soybean oil origination and crush capacity. Cargill competes on specialty fat customization for industrial bakeries requiring precise melting profiles.
Industrial margarine comprises a water-in-fat emulsion typically containing refined vegetable oils, water, emulsifiers, and flavoring agents, engineered to deliver specific plasticity and melting characteristics for commercial food production. The product type dimension shows block formats dominating high-volume bakery operations while spreadable variants capture growth in foodservice portion-control applications. Application segmentation reveals baking as the established volume anchor, with sauces emerging as a faster-growing niche driven by clean-label emulsion stability requirements. Formulation trends favor non-hydrogenated and low-fat categories where margin pools concentrate due to technical complexity and certification overhead.
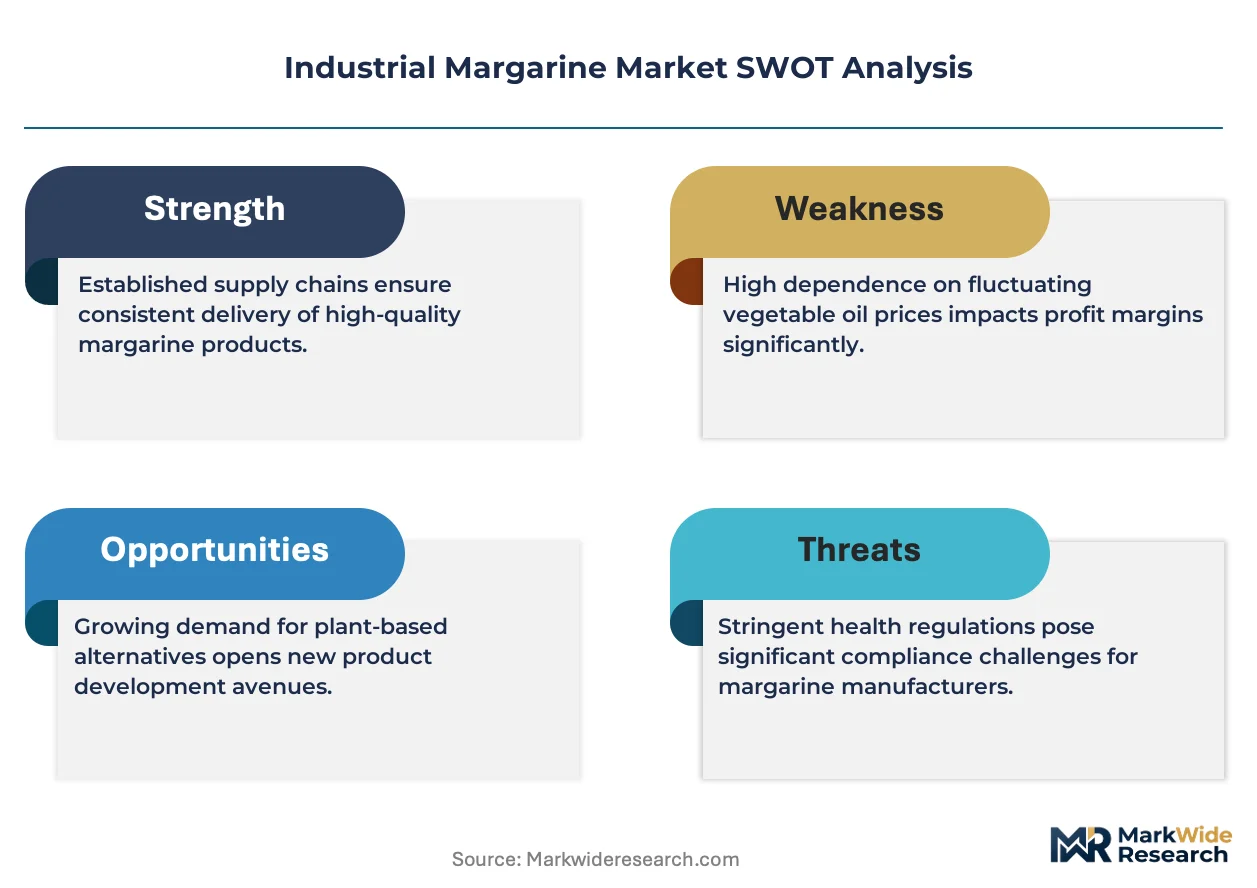
Regulatory frameworks including EU REACH restrictions on processing aids, FDA trans-fat labeling requirements in the United States, and WHO global trans-fat elimination targets collectively reshape product specifications and market access conditions. EFSA evaluations of novel emulsifier safety further influence formulation choices for suppliers targeting European food processors. Stakeholders must monitor evolving national implementations of WHO trans-fat limits and align R&D pipelines with region-specific compliance timelines to sustain commercial relevance.
Market Dynamics
WHO trans-fat elimination mandates are forcing industrial margarine manufacturers to abandon hydrogenation processes entirely, triggering a wholesale reformulation race across bakery and foodservice supply chains.
Growth Catalysts
- EU REACH restrictions on processing aids:Industrial bakers in Germany and France are accelerating adoption of clean-label emulsifiers to preempt compliance deadlines, creating pull-through demand for reformulated premium spreads.
- Indonesia's bakery chain consolidation:Centralized procurement by multi-outlet operators is standardizing non-hydrogenated specifications across Southeast Asian manufacturing hubs.
- Enzymatic interesterification:This process enables precise fat crystallization control without hydrogenation, allowing suppliers to replicate traditional margarine functionality while meeting trans-fat limits.
Market Restraints
- Palm oil price volatility:Feedstock cost swings in Malaysian and Indonesian supply basins compress margin predictability for bulk margarine producers.
- Refined vegetable oil supply concentration:Crush capacity limitations in Argentina and Brazil create bottleneck risk for soybean oil-dependent formulations.
- EFSA emulsifier safety reviews:Pending novel food assessments for alternative emulsifiers delay product registration timelines for European market entry.
Strategic Opportunities
- Vietnam foodservice expansion:Quick-service restaurant chains are scaling centralized kitchen operations, creating demand for portion-controlled spreadable formats.
- Clean-label sauce emulsions:Industrial sauce manufacturers are specifying non-hydrogenated fat bases to meet retailer clean-label requirements.
- US FDA trans-fat labeling:Enforcement of updated disclosure rules is displacing legacy formulations in American bakery operations, opening share for compliant imports.
Industry Challenges
- Reformulation R&D timelines:Matching precise melting profiles of hydrogenated predecessors requires extended pilot testing with industrial bakery partners.
- Emulsifier supply chain requalification:Switching to novel emulsifier systems demands re-validation of entire production lines and supplier audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Margarine Market |
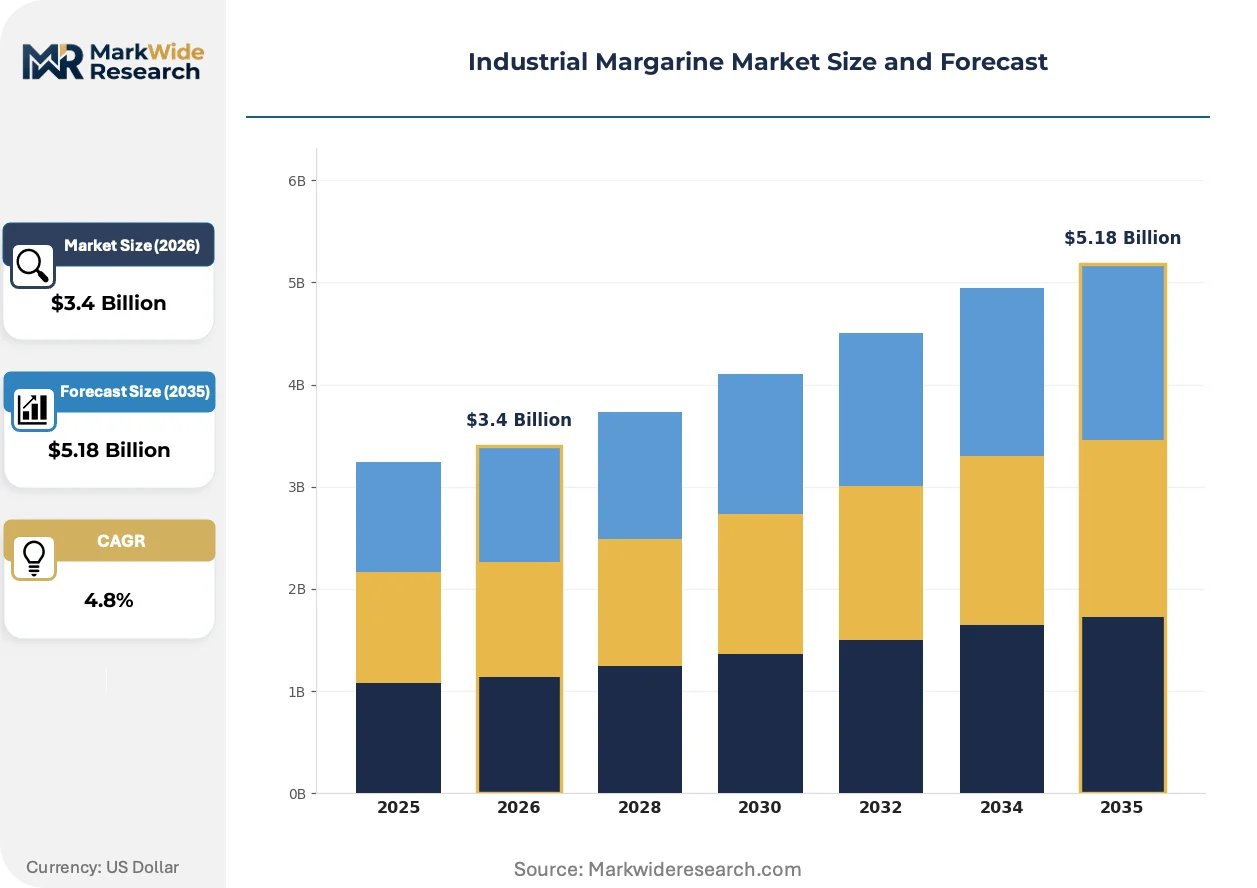
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.18 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Block, Liquid, Soft, Spreadable Application: Baking, Frying, Spreading, Sauces Formulation: Non-Hydrogenated, Low-Fat, Organic, Conventional End User: Bakers, Food Processors, Restaurants, Caterers |
| Companies Covered | Wilmar International, Bunge Limited, Cargill, Conagra Brands, Vandemoortele, Fuji Oil Holdings, AAK, Kerry Group, Puratos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Margarine Market Emerging Trajectories
Formulation science is pivoting toward enzymatic and physical processing methods that eliminate chemical hydrogenation while preserving functional fat crystallization. This shift is compressing traditional process technology and rewiring supplier R&D priorities.
High-pressure interesterification is miniaturizing. This technology rearranges fatty acid positions on triglyceride backbones without trans-fat generation. Industrial margarine producers in the Netherlands and Belgium are retrofitting batch plants with continuous high-pressure systems. The process is miniaturizing equipment footprints and enabling distributed production closer to bakery clusters rather than centralized mega-facilities.
EFSA novel food assessments are tightening emulsifier approval pathways. Manufacturers targeting European industrial bakers must submit comprehensive safety dossiers for alternative emulsifiers like enzymatically modified lecithins. Bakery ingredient divisions are front-loading toxicology studies to secure positive opinions ahead of competitor filings, compressing first-mover windows.
Centralized procurement by Southeast Asian bakery chains is consolidating supplier relationships. Multi-outlet operators in Jakarta and Ho Chi Minh City are negotiating direct supply agreements with margarine manufacturers, bypassing traditional ingredient distributors. This concentration is visible in Indonesia where three bakery chains now account for the majority of non-hydrogenated block volume, forcing smaller margarine brands to specialize in niche functional claims or exit the segment entirely.
Industrial Margarine Market Segmentation
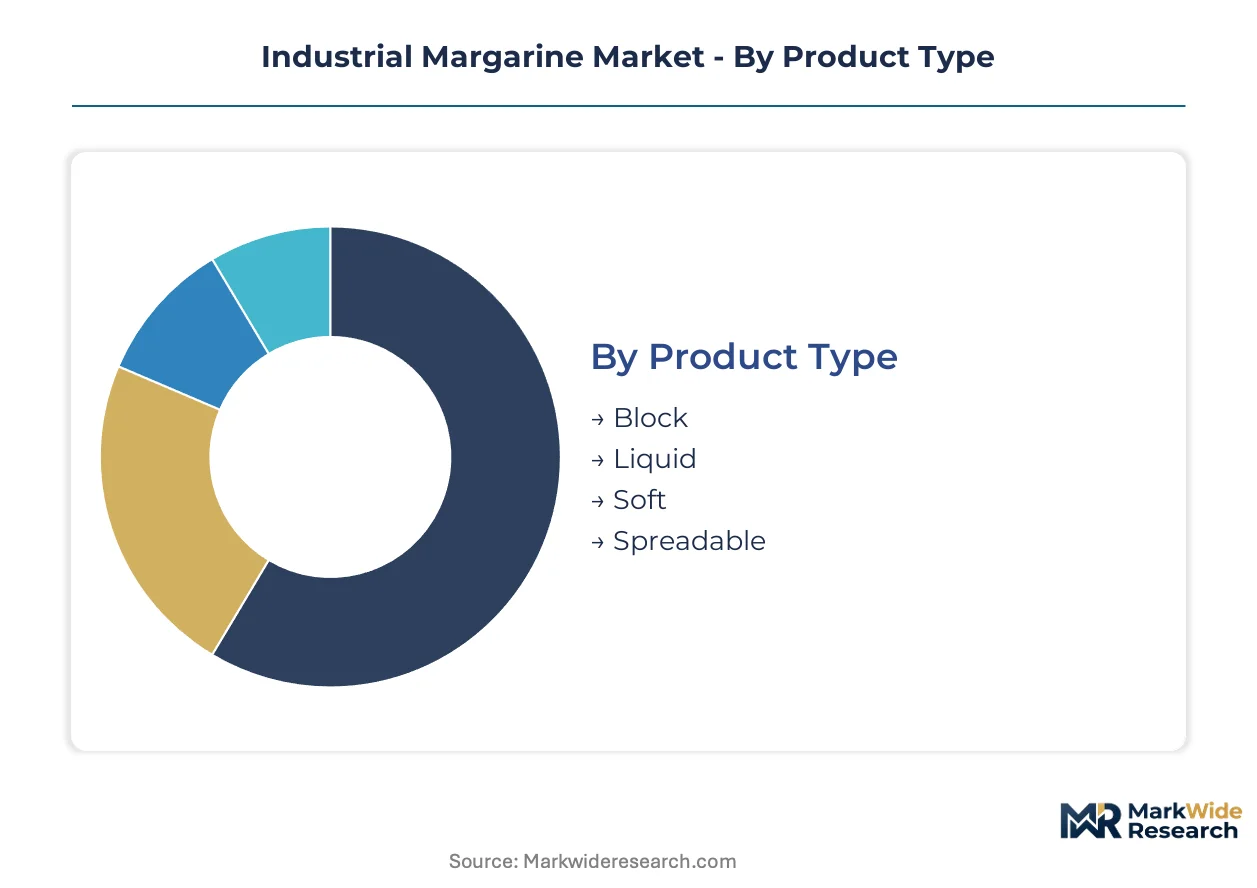
Industrial margarine segmentation reveals how margin pools concentrate in reformulated premium tiers and specialized functional formats. Manufacturers align production assets against specific application requirements and compliance-driven formulation shifts rather than pursuing undifferentiated volume.
Product Type:
Margin concentration sits in spreadable and soft formats where portion-control specifications and clean-label positioning command premium pricing over commodity block grades.
- Block:Dense, high-plasticity formats engineered for high-volume bakery laminating and puff pastry production. Industrial bakers in Indonesia and Vietnam specify block for centralized dough processing where precise fat layer distribution determines product consistency.
- Spreadable:Pumpable or portion-controlled textures with defined spreadability indices for foodservice and retail co-packing. Quick-service restaurant chains across Southeast Asia are scaling spreadable procurement for centralized kitchen sauce and filling applications where dispensing efficiency reduces labor cost.
- Liquid:Fluid emulsions for industrial frying and spray coating operations requiring uniform fat distribution without mechanical working.
- Soft:Intermediate plasticity formats bridging spreadability and structural integrity for artisan bakery and small-batch processing.
Block holds installed capacity. Spreadable is rotating up the share rankings.
Application:
Volume distribution follows bakery sector procurement patterns, though sauce applications are climbing fastest on clean-label emulsion stability requirements.
- Baking:Lamination, creaming, and shortening functions across industrial bread, pastry, and biscuit manufacturing. German and French industrial bakers are accelerating reformulation to non-hydrogenated baking fats ahead of EFSA compliance deadlines.
- Sauces:Emulsion stabilization for mayonnaise, dressings, and prepared sauces requiring freeze-thaw stability without hydrogenated fat bases. Sauce manufacturers specifying non-hydrogenated fat bases are capturing retailer clean-label shelf space in European and North American markets.
- Frying:High-temperature stability fats for industrial frying operations where smoke point and oxidative stability determine performance.
- Spreading:Direct consumption formats for foodservice portion packs and retail private label.
Baking commands current volume. Sauces are expanding most quickly on reformulation-driven specification changes.
Formulation:
Technical complexity and certification overhead concentrate margin in non-hydrogenated and organic tiers where enzymatic processing and feedstock traceability justify price premiums.
- Non-Hydrogenated:Fats processed via enzymatic or physical interesterification eliminating trans-fat generation while matching hydrogenated functional profiles. WHO trans-fat elimination mandates are forcing complete hydrogenation abandonment across bakery supply chains.
- Low-Fat:Reduced-fat emulsions with adjusted water content and stabilizer systems maintaining mouthfeel and processing characteristics. Health-focused bakery chains in Europe are specifying low-fat spreads for front-of-pack nutritional positioning.
- Organic:Certified organic feedstock chains with full traceability documentation for premium retail and foodservice positioning.
- Conventional:Legacy hydrogenated or partially hydrogenated formulations facing regulatory displacement and demand contraction.
Non-Hydrogenated holds reformulation investment. Low-Fat is gaining share fastest on dual health and clean-label positioning.
End User:
Procurement concentration among multi-outlet bakery chains is compressing supplier relationships and standardizing specifications across manufacturing hubs.
- Bakers:Industrial and artisan bakery operations requiring precise fat crystallization for dough handling and finished product texture. Centralized procurement by Indonesian bakery chains now accounts for majority non-hydrogenated block volume, forcing supplier consolidation.
- Food Processors:Prepared food and sauce manufacturers specifying functional fat bases for emulsion stability and shelf-life extension. Industrial sauce manufacturers are displacing legacy hydrogenated fats to meet retailer clean-label requirements.
- Restaurants:Foodservice operations requiring portion-controlled formats for consistency and labor reduction.
- Caterers:Institutional and event catering procurement of bulk formats for high-volume food preparation.
Bakers anchor specification-setting. Food Processors are rotating up the share rankings on sauce and prepared food reformulation cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian and Indonesian palm oil refining clusters concentrate feedstock supply for industrial margarine production. This geographic concentration shapes cost structures across downstream formulation tiers. Reformulation pressures in Europe and North America are redirecting trade flows toward enzymatic processing hubs.
United States
FDA trans-fat labeling enforcement is displacing legacy hydrogenated formulations in American bakery operations. Industrial bakers in Chicago and Minneapolis are accelerating procurement of interesterified fat bases. Midwest manufacturing corridors are retrofitting plants for continuous high-pressure processing to meet reformulated demand specifications.
Germany
EFSA emulsifier safety reviews are compressing product registration timelines for European market entry. REACH restrictions on processing aids are forcing industrial bakers in Bavaria and North Rhine-Westphalia toward clean-label emulsifier systems. Cologne-based ingredient distributors are consolidating supplier relationships around pre-certified formulation portfolios.
Indonesia
Centralized procurement by Jakarta and Surabaya bakery chains is standardizing non-hydrogenated specifications across Southeast Asian manufacturing. WHO trans-fat elimination targets are accelerating hydrogenation abandonment in domestic refining operations. Wilmar International leverages integrated palm oil networks across Sumatra and Kalimantan to secure feedstock cost positions.
Netherlands
High-pressure interesterification technology is miniaturizing equipment footprints in Belgian and Dutch batch plant retrofits. Rotterdam port logistics anchor European feedstock distribution for enzymatic processing inputs. Eindhoven-region equipment suppliers are shipping continuous processing systems to bakery clusters seeking distributed production models.
Vietnam
Quick-service restaurant chains in Ho Chi Minh City are scaling centralized kitchen operations for portion-controlled spreadable formats. Foodservice expansion is creating demand pull for pumpable textures with defined spreadability indices. Local distributors are bypassing traditional ingredient channels to negotiate direct supply agreements with regional margarine manufacturers.
Industrial Margarine Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the industrial margarine supply base. Integrated palm oil refiners command feedstock economics while specialty fat customizers capture premium formulation margins. The market structure separates into three archetypes: upstream-integrated agricultural processors, midstream formulation specialists, and downstream bakery ingredient distributors. Competitive moves concentrate on enzymatic processing licensing and direct procurement relationships with multi-outlet bakery chains.
Within the integrated processor tier, Wilmar International and Bunge Limited exemplify upstream control strategies anchored in Southeast Asian and North American oilseed origination respectively. Cargill occupies a position bridging agricultural supply with specialty fat customization for industrial bakeries requiring precise melting profile engineering. These three players represent contrasting geographic feedstock strategies rather than direct product competition.
| Leading Market Players |
|---|
| Wilmar International |
| Bunge Limited |
| Cargill |
| Conagra Brands |
| Vandemoortele |
| Fuji Oil Holdings |
| AAK |
| Kerry Group |
| Puratos |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Southeast Asian palm oil refiners and industrial bakery chains lock in feedstock access and price visibility across volatile commodity cycles. These arrangements concentrate procurement power among multi-outlet operators in Indonesia and Vietnam while compressing margin predictability for uncontracted spot buyers.
Pricing Analysis
WHO trans-fat elimination mandates dictate the pricing tier structure across industrial margarine formulations. Three-tier pricing structure across premium, standard, and economy levels separates enzymatically processed non-hydrogenated fats from legacy hydrogenated grades and commodity block formats. Price differentiation hinges on certification overhead for EFSA-compliant emulsifier systems and volume scale from centralized bakery chain procurement. Cost compression in standard tiers is intensifying because palm oil price volatility in Malaysian supply basins erodes producer margins. Small-batch artisan bakers exhibit highest price sensitivity due to limited procurement scale, while multinational quick-service chains absorb premium tier pricing for supply security.
Supply Chain Analysis
Strait of Malacca transit underwrites feedstock flows from Indonesian and Malaysian palm oil refining clusters to enzymatic processing hubs in the Netherlands and Belgium. Geographic supply concentration centers on Indonesia, Malaysia, and Brazil for soybean oil origination. Raw material dependencies draw from crude palm oil, refined soybean oil, and enzymatically modified lecithin emulsifiers. Single-source vulnerability in Malaysian palm kernel supply creates bottleneck exposure during monsoon logistics disruptions. Distribution runs through Rotterdam port consolidation for European industrial bakers and direct vessel charters to Jakarta and Ho Chi Minh City for Southeast Asian bakery chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across WHO trans-fat implementation timelines creates niche entry points for formulation specialists. Bakery chain consolidation in Southeast Asia fragments supplier relationships and opens white-space for certified clean-label providers.
For Market Incumbents: Secure enzymatic processing licensing agreements ahead of EFSA novel food assessment deadlines to preempt competitor emulsifier approvals. Deepen backward integration into Sumatran palm oil refining to offset feedstock cost volatility from Malaysian supply swings. Lock in multi-year direct supply contracts with Jakarta-based bakery chains to defend volume positions against emerging regional blenders. For New Entrants and Emerging Players: Lead with specialty sauce emulsion formulations for European food processors seeking clean-label fat bases with freeze-thaw stability. Target Vietnamese quick-service restaurant procurement for portion-controlled spreadable formats where incumbent coverage remains thin. Pursue toll-processing partnerships with underutilized Belgian high-pressure interesterification facilities to minimize capital intensity. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among enzymatic processing technology licensors with multi-year equipment supply contracts. Long-term viability over the projection horizon favors acquisition targets with pre-certified EFSA emulsifier dossiers and established relationships with Cologne-based ingredient distributors. Watch for inflection signals in national WHO trans-fat limit implementation deadlines that would accelerate hydrogenation abandonment and expand addressable market for compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Processing Licensing | Technology transfer agreements with Dutch equipment suppliers accelerate EFSA-compliant production capacity. |
| Backward Integration into Palm Refining | Captive supply of Indonesian crude palm oil insulates margin from Malaysian price volatility. |
| Direct Supply Agreement with Bakery Chains | Bypassing Jakarta distributors captures procurement concentration from multi-outlet operator consolidation. |
| EFSA Emulsifier Pre-Certification | Front-loaded toxicology studies compress first-mover windows for novel lecithin systems. |
| High-Pressure Interesterification Retrofit | Miniaturized continuous systems enable distributed production closer to Ho Chi Minh City bakery clusters. |
Methodological Framework
A spread of perspectives from industrial bakery procurement directors, enzymatic processing plant managers, palm oil refining executives, and EFSA regulatory consultants converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against customs trade data, SEC filings of listed agricultural processors, WHO trans-fat policy implementation trackers, and Rotterdam port throughput statistics. Bottom-up volume estimates from individual bakery chain procurement were triangulated with top-down palm oil consumption aggregates.
Segmentation dimensions modeled include formulation type, product format, application function, and end-user procurement scale across the analysis window. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion schedules from major processing hubs. Industry-specific forecast inputs incorporated EFSA novel food assessment timelines and national WHO trans-fat limit adoption trajectories.
The analysis sits within stated boundaries; outcomes outside EFSA positive opinion timelines or accelerated hydrogenation phase-outs would require recalibration. Forecasts reflect documented assumptions on emulsifier approval pathways and palm oil supply elasticity. Practitioners should keep alternative scenarios live as Indonesian bakery chain consolidation patterns and REACH processing aid restrictions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
United States Fresh Noodles Market
Processed Foods
North America Ice Cream Market
Processed Foods
Processed Mango Products Market
Processed Foods
Yogurt Dip Market
Processed Foods
Low Fat Puddings Market
Processed Foods
Margarine Market
Processed Foods
Asia-Pacific Food Spread Market
Processed Foods
Block Margarine Market
Processed Foods
Noodles Market
Processed Foods
Fruit Processing Market
Processed Foods
Ready to Serve Prefabricated Dishes Market
Processed Foods
Instant Cooking Food Market
Processed Foods
Instant Curry Market
Processed Foods
Fresh Pasta Market
Processed Foods
Fermented Foods Market
Processed Foods
Pizza Market