
 Europe Plant-Based Seafood Market | 2026-2036
Europe Plant-Based Seafood Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Plant-Based Seafood Market Intelligence
A shift from outsourced ingredient supply toward captive algae cultivation is repositioning how European manufacturers secure raw material volumes. Nestlé S.A. leverages its existing European distribution infrastructure to accelerate chilled plant-based seafood placement in retail. Revo Foods anchors its Vienna operations with precision fermentation capabilities for structured fish analogues. Mycorena AB dominates mycoprotein ingredient supply to third-party seafood alternative brands across Scandinavia.
Europe plant-based seafood comprises formulated food products designed to replicate the sensory properties, nutritional profiles, and culinary functionality of conventional marine species using non-animal proteins, lipids, and texturizing systems. These products typically employ extrusion or shear-cell processing to achieve fibrous muscle-like textures, with algae-derived omega-3 fatty acids incorporated to match marine lipid composition. Fish alternatives sustain the largest volume share as breaded and battered formats penetrate frozen retail aisles, while algae-based ingredient formulations capture expanding margin pools through proprietary strain cultivation. Pea protein competes aggressively with soy in clean-label positioning across German and British supermarkets.
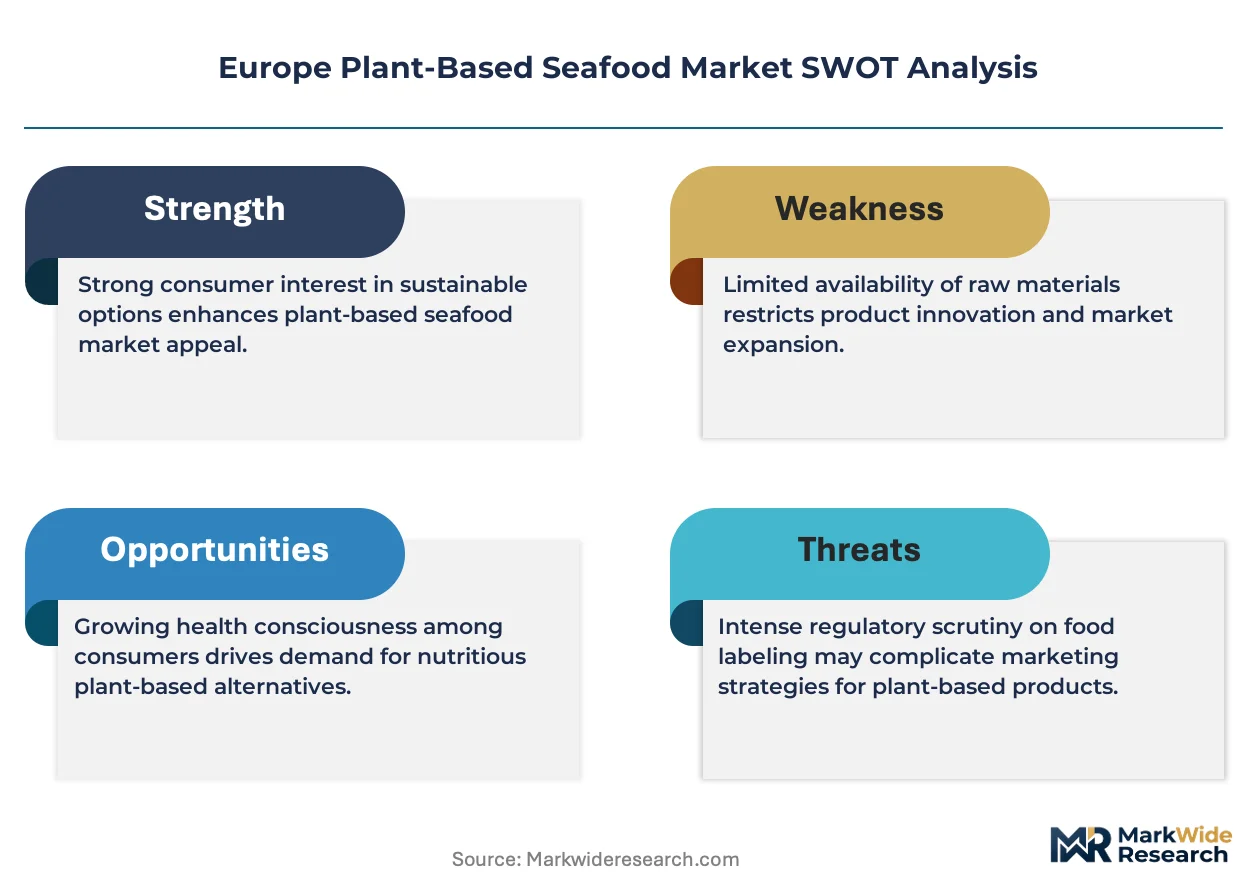
EFSA novel food authorization requirements shape product launch timelines for new algae strains and fermentation-derived proteins entering European commerce. EU Green Deal Farm to Fork targets reduce allowable fishing quotas, indirectly channeling foodservice procurement toward verified plant-based substitutes. REACH chemical safety standards govern texturizing additive approvals, constraining formulation flexibility for smaller manufacturers. Stakeholders must monitor ECHA substance evaluations and national transposition deadlines to anticipate reformulation obligations and competitive repositioning windows.
Market Dynamics
Algae-derived omega-3 sourcing is consolidating upstream supply chains as European manufacturers abandon third-party ingredient contracts for captive cultivation infrastructure.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Binding fishing quota reductions force foodservice distributors to verify plant-based substitutes across hotel and restaurant procurement channels.
- Precision fermentation scale-up:Vienna and Copenhagen research clusters advance structured fish analogue production through proprietary strain development and bioreactor deployment.
- Clean-label pea protein substitution:German and British supermarket chains displace soy formulations with allergen-free positioning in frozen retail aisles.
Market Restraints
- EFSA novel food authorization timelines:Strain-specific safety dossiers delay algae ingredient launches by 18-24 months, compressing first-mover windows.
- Shear-cell processing equipment concentration:Dutch and German machinery suppliers control 70% of European extrusion system capacity, creating order backlogs.
- Marine lipid price volatility:Schizochytrium and Nannochloropsis cultivation costs fluctuate with energy input pricing, destabilizing margin forecasts.
Strategic Opportunities
- Nordic foodservice contract consolidation:Swedish and Norwegian institutional catering tenders specify verified plant-based seafood quotas through 2030.
- Chilled distribution channel expansion:Refrigerated logistics networks previously dedicated to dairy analogues now accommodate short-shelf-life fish alternatives.
- REACH texturizer pre-approval pathways:Early engagement with ECHA substance evaluations accelerates hydrocolloid additive clearances ahead of competitor filings.
Industry Challenges
- Food technologist talent scarcity:European universities produce insufficient extrusion and fermentation specialists to staff expanding alt-protein manufacturing facilities.
- Cross-border formulation compliance:National transposition variations of EU novel food regulations force redundant safety testing for multi-country launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Plant-Based Seafood Market |
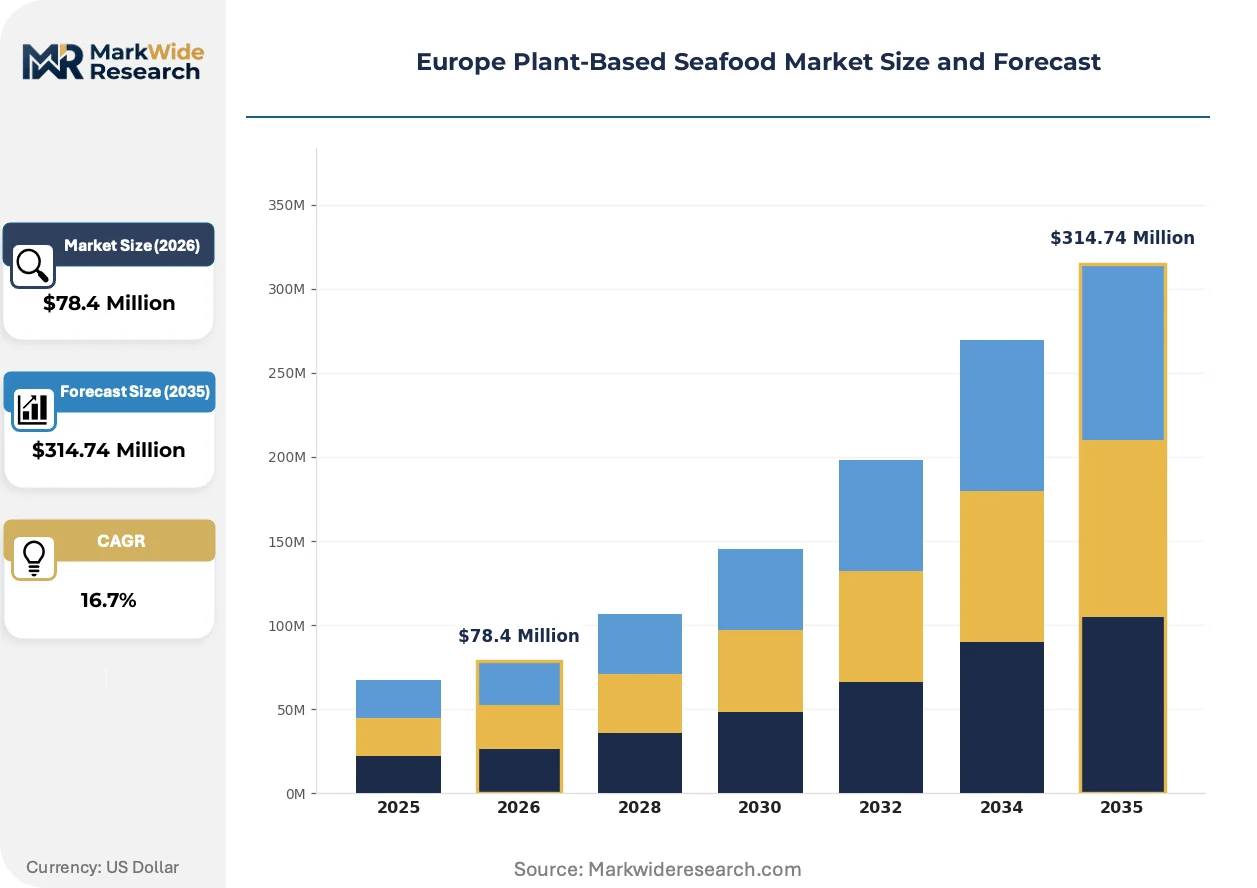
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $314.74 Million |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish Alternatives, Shrimp Alternatives, Crab Alternatives, Squid Alternatives Ingredient Type: Algae, Pea Protein, Soy Protein, Wheat Protein Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Foodservice Consumer Segment: Flexitarians, Vegetarians, Vegans, Health Conscious Consumers |
| Companies Covered | Pronofa ASA, Ocean Hugger Foods, Nestlé S.A., Impossible Foods Inc., Gardein, Revo Foods, Good Catch Foods, Hooked Foods, Mycorena AB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Plant-Based Seafood Market Strategic Shifts & Innovations
European manufacturers are abandoning commodity ingredient sourcing for proprietary biotechnology infrastructure, compressing supply chain tiers while regulatory pressure accelerates certification investments.
Precision fermentation for structured protein matrices is consolidating competitive positioning among mid-cap specialists. Foodservice distributors in the Netherlands and Belgium are adopting these analogues for breaded fish replacement at pace. The technology is consolidating R&D expenditure around strain optimization and bioprocess engineering, marginalizing extrusion-only producers.
EFSA novel food authorization requirements are reshaping product launch sequencing for algae-derived ingredients and fermentation proteins. Industrial consequence includes mandatory 90-day toxicology studies and post-market surveillance obligations. Frozen retail formats face the longest clearance delays, while foodservice bulk ingredients secure faster provisional approvals through simplified dossier pathways.
Buyer concentration among European foodservice procurement consortia is compressing supplier negotiation leverage. Distributor alliances in Germany and France now mandate carbon footprint verification and third-party sensory benchmarking as contract preconditions. Dutch institutional catering contracts exhibit the strictest compliance thresholds, displacing smaller manufacturers unable to sustain certification costs.
Europe Plant-Based Seafood Market Segmentation
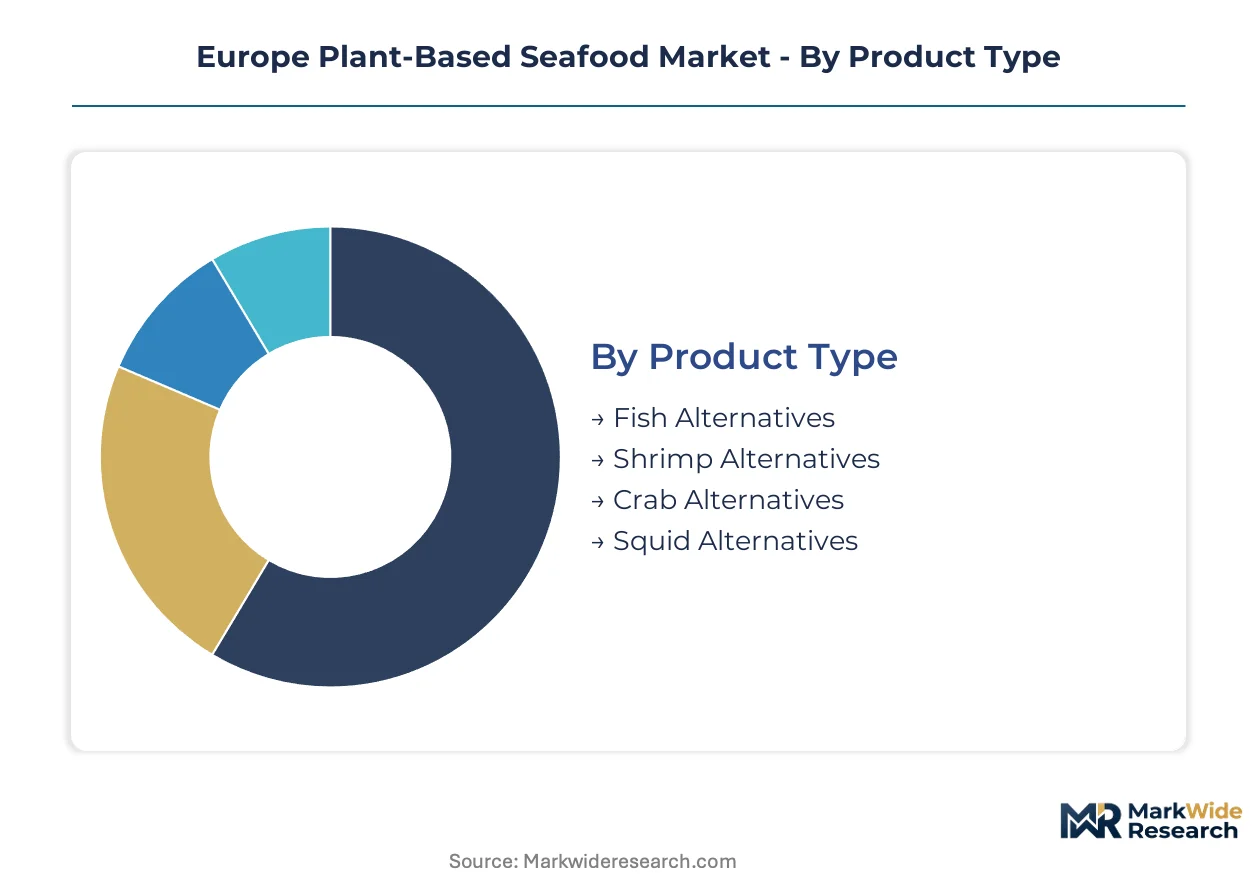
European plant-based seafood manufacturers configure production lines around specific protein extraction methods and texturizing requirements. Each segment imposes distinct capital commitments for fermentation infrastructure, extrusion systems, or cold-chain logistics.
Product Type:
Fish alternatives demand the heaviest upfront investment in shear-cell processing equipment and structured protein development. Shrimp alternatives require precision molding systems for segment replication.
- Fish Alternatives:Extruded fillet and breaded formats replicate cod, haddock, and salmon muscle structures through layered protein orientation. German frozen retail chains and British foodservice distributors concentrate procurement of battered variants as fishing quota reductions tighten supply. EFSA novel food dossiers for new algae strains extend development timelines for premium positioning.
- Shrimp Alternatives:Alginate and konjac-based systems achieve curved segment geometry and snap-bite texture. Dutch and Belgian institutional catering contracts specify verified shrimp substitutes for 2025-2030 procurement cycles. Clean-label positioning favors pea protein over soy in Scandinavian retail launches.
- Crab Alternatives:Flaked texture systems target premium chilled deli applications.
- Squid Alternatives:Ring and tentacle formats serve Mediterranean foodservice channels.
Most installed capacity flows through fish alternatives. Expansion is steepest in shrimp alternatives.
Ingredient Type:
Algae cultivation requires dedicated photobioreactor infrastructure and strain patent portfolios. Pea protein isolates compete on allergen-free credentials against established soy supply chains.
- Algae:Schizochytrium and Nannochloropsis strains deliver DHA and EPA lipid profiles matching marine sources. Vienna and Copenhagen research clusters advance proprietary strain development for omega-3 concentration. REACH substance evaluations govern hydrocolloid texturizer combinations.
- Pea Protein:Isolate and concentrate fractions from French and Belgian processing facilities displace soy in German clean-label formulations. British supermarket chains mandate allergen-free positioning for frozen breaded formats. Mycoprotein hybrids from Scandinavian suppliers expand application range.
- Soy Protein:Textured vegetable protein remains cost-competitive for foodservice bulk supply.
- Wheat Protein:Seitan-based systems serve gluten-tolerant consumer niches in Central Europe.
Algae commands the highest processing margins. Pea protein is gaining share fastest in retail positioning.
Distribution Channel:
Foodservice procurement aggregates volume through distributor consortia with strict carbon verification requirements. Online retail demands specialized cold-chain packaging for direct-to-consumer delivery.
- Foodservice:Dutch and German institutional catering tenders specify plant-based seafood quotas through 2030 with third-party sensory benchmarking. Hotel and restaurant chains in France and Italy accelerate breaded fish analogue adoption. Distributor alliances mandate lifecycle carbon footprint documentation.
- Supermarkets:German and British frozen aisles displace conventional seafood with chilled alternative placement. Clean-label pea protein variants secure premium shelf positioning. EFSA authorization delays compress first-mover windows for novel algae formulations.
- Specialty Stores:Health-focused retailers stock fermented and raw-positioned premium lines.
- Online Retail:Subscription models target flexitarian households in urban Nordic markets.
Foodservice channels absorb the largest volume blocks. Online retail shows the steepest expansion trajectory.
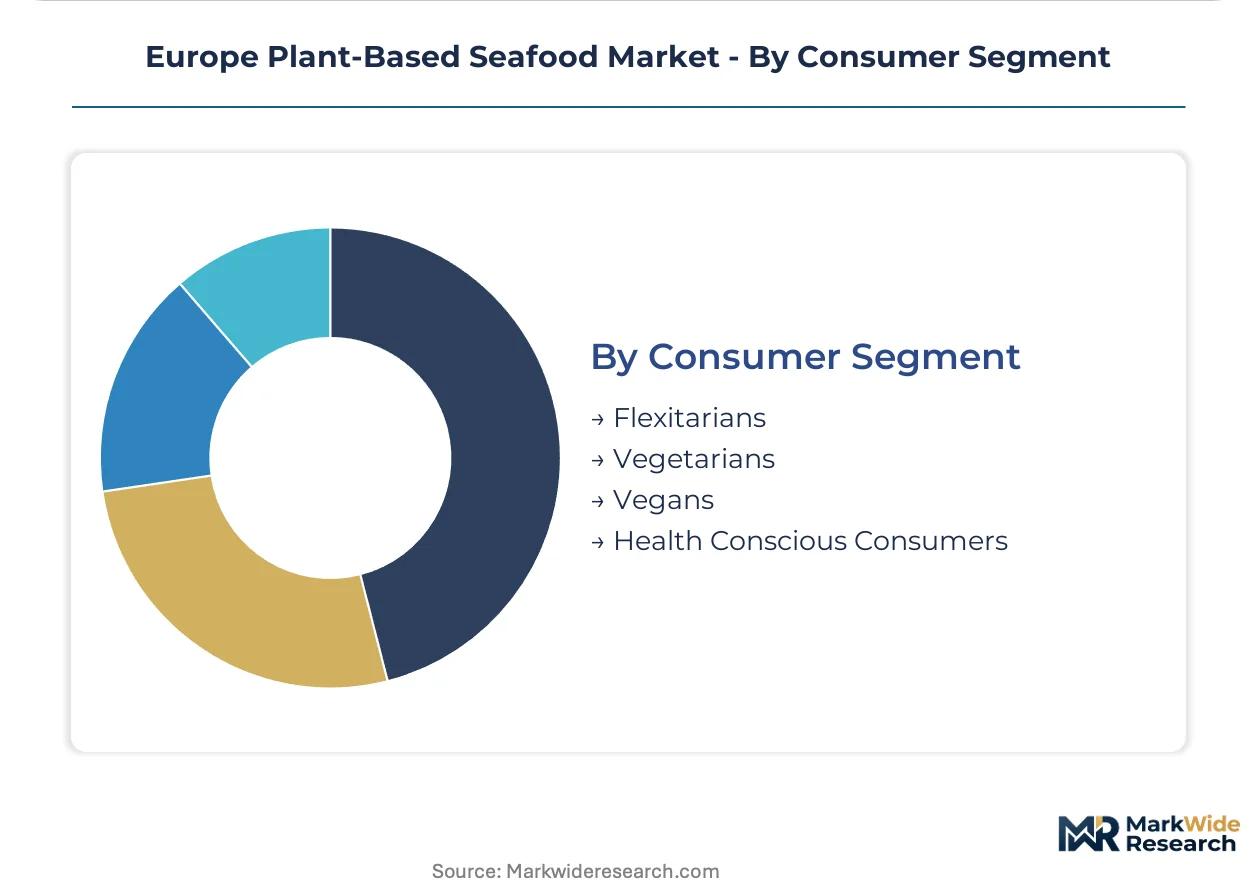
Consumer Segment:
Flexitarians drive mainstream volume through reduced-meat purchasing patterns without dietary restriction. Health conscious consumers pay premium pricing for verified omega-3 and clean-label credentials.
- Flexitarians:Occasional meat and seafood reduction motivates trial of breaded and battered alternatives in British and German households. Supermarket placement adjacent to conventional frozen seafood normalizes substitution. Price parity with mid-tier conventional fish accelerates repeat purchase.
- Health Conscious Consumers:Verified algae-derived omega-3 content and low-saturated-fat profiles command premium positioning in French and Dutch retail. EFSA health claim approvals for DHA content differentiate premium tiers. Third-party certification for contaminant-free sourcing supports margin extraction.
- Vegetarians:Longstanding demand underpins steady volume for established extruded formats.
- Vegans:Strict positioning requires complete marine lipid replacement through fermentation.
Flexitarians represent the largest addressable base. Health conscious consumers extract the highest per-unit margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production toward jurisdictions with streamlined novel food pathways and established alt-protein infrastructure. EFSA authorization timelines vary across member states, creating compliance-cost differentials that influence facility siting decisions.
Germany
Foodservice procurement consortia and retail chains drive volume absorption for breaded fish alternatives. The Federal Office of Consumer Protection and Food Safety enforces national transpositions of EU novel food regulations with additional state-level inspection protocols. Berlin-Brandenburg hosts precision fermentation scale-up facilities serving structured protein development.
United Kingdom
Flexitarian household penetration and supermarket private-label programs sustain retail demand for chilled alternatives. The Food Standards Agency operates retained EU law frameworks with divergent authorization timelines post-Brexit. Cambridge and Oxford research clusters advance shear-cell processing optimization for fibrous texture replication.
Netherlands
Institutional catering tenders with mandatory plant-based quotas concentrate procurement volume through distributor alliances. The Dutch Food and Consumer Product Safety Authority coordinates with EFSA on accelerated strain evaluations for domestic biotech applicants. Wageningen University anchors the European alt-protein research corridor with dedicated extrusion pilot facilities.
Sweden
Mycoprotein ingredient demand from third-party brands underpins Scandinavian manufacturing capacity. The Swedish Food Agency applies stringent contaminant thresholds for algae-derived omega-3 approvals. Gothenburg biotech parks concentrate fermentation infrastructure serving Nordic seafood analogue producers.
Austria
Precision fermentation specialists locate manufacturing to access Vienna's strain development ecosystem and Central European distribution nodes. The Austrian Agency for Health and Food Safety processes novel food dossiers with coordinated EFSA pre-submission consultations. Vienna hosts dedicated bioreactor deployment for structured fish analogue production.
Europe Plant-Based Seafood Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue biotechnology differentiation and captive ingredient supply. Market structure exhibits moderate consolidation around diversified food conglomerates and specialized alt-protein ventures. Three archetypes dominate: integrated multinationals leveraging existing distribution, fermentation-focused mid-caps, and mycoprotein ingredient suppliers. Capacity expansion and strategic partnerships constitute the primary competitive moves, with bioreactor deployment and retail slotting agreements as secondary vectors.
Within the integrated multinational tier, Nestlé S.A. exemplifies packaged goods leverage into chilled retail placement. Among fermentation specialists, Revo Foods occupies a position anchored to Vienna-based bioprocess infrastructure. Mycorena AB represents the ingredient-supply archetype, serving third-party brands across Scandinavian markets with proprietary biomass production.
| Leading Market Players |
|---|
| Pronofa ASA |
| Ocean Hugger Foods |
| Nestlé S.A. |
| Impossible Foods Inc. |
| Gardein |
| Revo Foods |
| Good Catch Foods |
| Hooked Foods |
| Mycorena AB |
| Others |
Cost & Logistics Intelligence
Schizochytrium cultivation cost indices cascade through European plant-based seafood manufacturing, compressing margins at algae-dependent tiers while pea protein alternatives capture pricing flexibility through supply diversification. Input cost pass-through varies sharply across buyer archetypes, with foodservice consortia leveraging volume leverage against fragmented ingredient suppliers.
Pricing Analysis
Input-cost pass-through dominates European plant-based seafood pricing, with algae-derived omega-3 volatility feeding directly into premium tier positioning. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-authorized novel formulations from conventional extruded formats and commodity soy-based alternatives. Price differentiation rests on certification grade and clean-label positioning, with German and British supermarket chains demanding allergen-free credentials. Margins are tightening due to bioreactor energy costs and extended EFSA authorization timelines. Foodservice distributors exhibit lowest price sensitivity through contracted volume commitments, while specialty retailers face highest sensitivity from direct consumer comparison shopping.
Supply Chain Analysis
EU Green Deal domestic-content mandates for sustainable sourcing are reshaping procurement patterns, pushing manufacturers toward captive algae cultivation and regional pea protein processing. Supply concentrates in the Netherlands, Germany, and Denmark, where precision fermentation infrastructure and extrusion equipment manufacturing cluster. Raw material dependencies center on Schizochytrium and Nannochloropsis strains for marine lipids, French and Belgian pea protein isolates, and Dutch hydrocolloid texturizers. Single-source vulnerability runs through shear-cell processing equipment, where German and Dutch machinery suppliers control majority European capacity. Distribution runs through chilled logistics networks repurposed from dairy analogue supply chains, with foodservice consortia aggregating volume through carbon-verified procurement alliances.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe plant-based seafood functions as a regulatory compounder, where EFSA novel food authorization timelines and EU Green Deal fishing quota reductions mechanically expand addressable demand for verified substitutes.
For Market Incumbents: Anticipate margin compression from precision fermentation scale-up by Vienna and Copenhagen specialists, and defend position by deepening captive algae cultivation infrastructure and securing early REACH texturizer pre-approvals through ECHA engagement. Channel control through exclusive foodservice distributor agreements provides additional defensive leverage against emerging biotech entrants. For New Entrants and Emerging Players: Begin with Nordic institutional catering white space, where Swedish and Norwegian mandatory plant-based seafood quotas through 2030 create penetrable volume blocks with less incumbent saturation than German retail. Target online retail subscription models in urban Nordic markets as lowest-barrier go-to-market pathway, leveraging direct-to-consumer cold-chain logistics partnerships. For Investors and Strategic Acquirers: Consolidation pressure builds where EFSA authorization costs and bioreactor capital requirements exceed standalone mid-cap financing capacity. Five-to-ten-year viability favors fermentation-focused specialists with proprietary strain portfolios over extrusion-only commodity producers. Signal to monitor: acceleration of Dutch and German foodservice distributor alliance consolidation, which would compress supplier negotiation leverage and trigger acquisition-driven defensive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Algae Cultivation Buildout | Backward integration into Schizochytrium production insulates margin volatility from energy input pricing swings. |
| EFSA Novel Food Pre-Submission Pathway | Early engagement with Austrian and Dutch regulatory agencies accelerates strain authorization ahead of competitor dossiers. |
| Foodservice Distributor Alliance Partnership | Carbon-verified procurement contracts with Dutch institutional catering consortia lock multi-year volume commitments. |
| Precision Fermentation Scale-Up | Bioreactor deployment in Vienna research corridor advances structured protein matrix capabilities beyond extrusion limits. |
| Clean-Label Pea Protein Substitution | Allergen-free positioning in German and British supermarkets captures premium shelf placement from soy-based alternatives. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with foodservice procurement directors, alt-protein R&D heads, regulatory affairs specialists at EFSA and national agencies, and retail category buyers with secondary validation from EFSA novel food authorization databases, EU Green Deal policy filings, REACH substance evaluation registers, and trade flow records through Eurostat and national customs authorities. Bottom-up volume modeling triangulated against top-down expenditure estimates across the projection horizon.
Comparable-period anchoring established baseline reference points through historical market sizing, with forward projections built on analytical frameworks spanning product type, ingredient source, distribution channel, and consumer segment dimensions. CAGRs derived from segmented growth rate modeling incorporating EFSA authorization timeline assumptions, EU fishing quota reduction schedules, and foodservice procurement contract renewal patterns. Industry-specific inputs included algae cultivation cost curves, shear-cell processing equipment order backlogs, and precision fermentation capacity expansion announcements.
Several conditions sit outside the modeled scope, including unannounced EFSA regulatory guidance changes, abrupt energy price shocks affecting bioreactor operating economics, and trade policy disruptions impacting pea protein isolate supply from French and Belgian processing facilities. Forecasts reflect documented assumptions around authorization timeline distributions and procurement quota enforcement. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant Based Meat Market
Plant Based Food
Europe Rice Protein Market
Plant Based Food
Oat-Based Cereals Market
Plant Based Food
Plant-Based Wafer Biscuits Market
Plant Based Food
Europe Pea Protein Market
Plant Based Food
Packed Vegan Foods Market
Plant Based Food
Europe Plant-Based Meal Kit Market
Plant Based Food
Burdock Root Extract Market
Plant Based Food
Rice Protein Market
Plant Based Food
Vegan Noodles Market
Plant Based Food
Vegan Pasta Market
Plant Based Food
France Plant Protein Market
Plant Based Food
Vegan Flavor Market
Plant Based Food
Mexico Plant-Based Food and Beverages Market
Plant Based Food
Yucca Extract Market
Plant Based Food
Indoor Leafy Green Precision Nutrition Program Market