
 Vegan Bacon Market | 2026-2036
Vegan Bacon Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Bacon Market Analytics
Single-serve pouch formats and breakfast-combo bundles is decoupling volume purchasing from traditional bulk-pack logic in retail channels. Beyond Meat Inc. leverages its broad retail footprint to sustain frozen-section visibility, while The Vegetarian Butcher anchors European foodservice supply through Unilever's institutional relationships. Hooray Foods differentiates via coconut-oil-based fat replication that mimics pork belly crispness without soy or gluten allergens.
Vegan bacon denotes thin strips of plant-derived protein, typically extruded from pea or soy isolates with added lipid layers, then smoked and cured to replicate the Maillard-reactive flavor profile and chew structure of cured pork belly. Its primary commercial purpose is to substitute into existing breakfast, sandwich, and recipe applications without altering preparation workflows or consumer expectations. Maple flavor and smoked variants dominate refrigerated case turns in North American supermarkets, where flexitarian households drive repeat purchase rates. Pea protein formulations command premium positioning due to cleaner-label appeal and allergen avoidance, while wheat-gluten-based products occupy value-tier placement in European discount channels.
The USDA's Food Safety and Inspection Service and the FDA jointly oversee cell-cultured meat labeling, creating compliance overhead for hybrid products that blend plant proteins with cultivated fats. EFSA novel-food assessments in Europe delay market entry for fermented-fat technologies that several suppliers now pilot. REACH chemical safety registrations for smoke-flavoring additives add formulation constraints for manufacturers exporting into EU member states. Stakeholders must monitor which regulatory pathway—plant-only, fermentation-enhanced, or hybrid—gains faster clearance, as this will determine which ingredient bases achieve scalable market access first.
Market Dynamics
Hybrid protein architectures—combining plant isolates with precision-fermented fats—are forcing a recalibration of manufacturing scale, regulatory compliance, and consumer communication strategies across the value chain.
Growth Catalysts
- Quick-service restaurant standardization:North American chains now mandate plant-based breakfast SKUs, creating predictable offtake volumes that justify dedicated production lines.
- EFSA novel-food pathway clarity:Fermented-fat approvals in Europe are accelerating, giving suppliers a regulatory template for cross-border market entry.
- Pea protein extraction yields:Wet-fractionation improvements are compressing input costs for allergen-free formulations.
Market Restraints
- Coconut oil price volatility:Fat-replication chemistries depend on tropical commodity markets exposed to climate disruption.
- Smoke-flavoring REACH registrations:ECHA compliance timelines extend 18-24 months, delaying EU launches for new curing formulations.
- Wheat-gluten substitution ceiling:European discount-channel products face technical barriers replicating pork-belly chew without soy or pea inputs.
Strategic Opportunities
- German foodservice penetration:Institutional catering contracts in Bavaria and North Rhine-Westphalia remain underpenetrated by plant-based breakfast proteins.
- Cell-cultured fat blending:USDA-FDA joint oversight frameworks are stabilizing, creating a pathway for hybrid products with superior Maillard performance.
- Single-serve pouch formats:Convenience-channel breakfast bundles are decoupling volume logic from legacy bulk-pack retail.
Industry Challenges
- Fermentation scale-up talent scarcity:Bioprocess engineers with food-grade GMP experience command premium compensation, constraining pilot-to-commercial timelines.
- Dual-labeling compliance complexity:Products spanning plant and cultivated ingredients must satisfy divergent USDA and FDA inspection protocols simultaneously.
- Smoke-chemistry IP fragmentation:Patent thickets around natural-flavor extraction are forcing licensing negotiations that extend R&D cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Bacon Market |
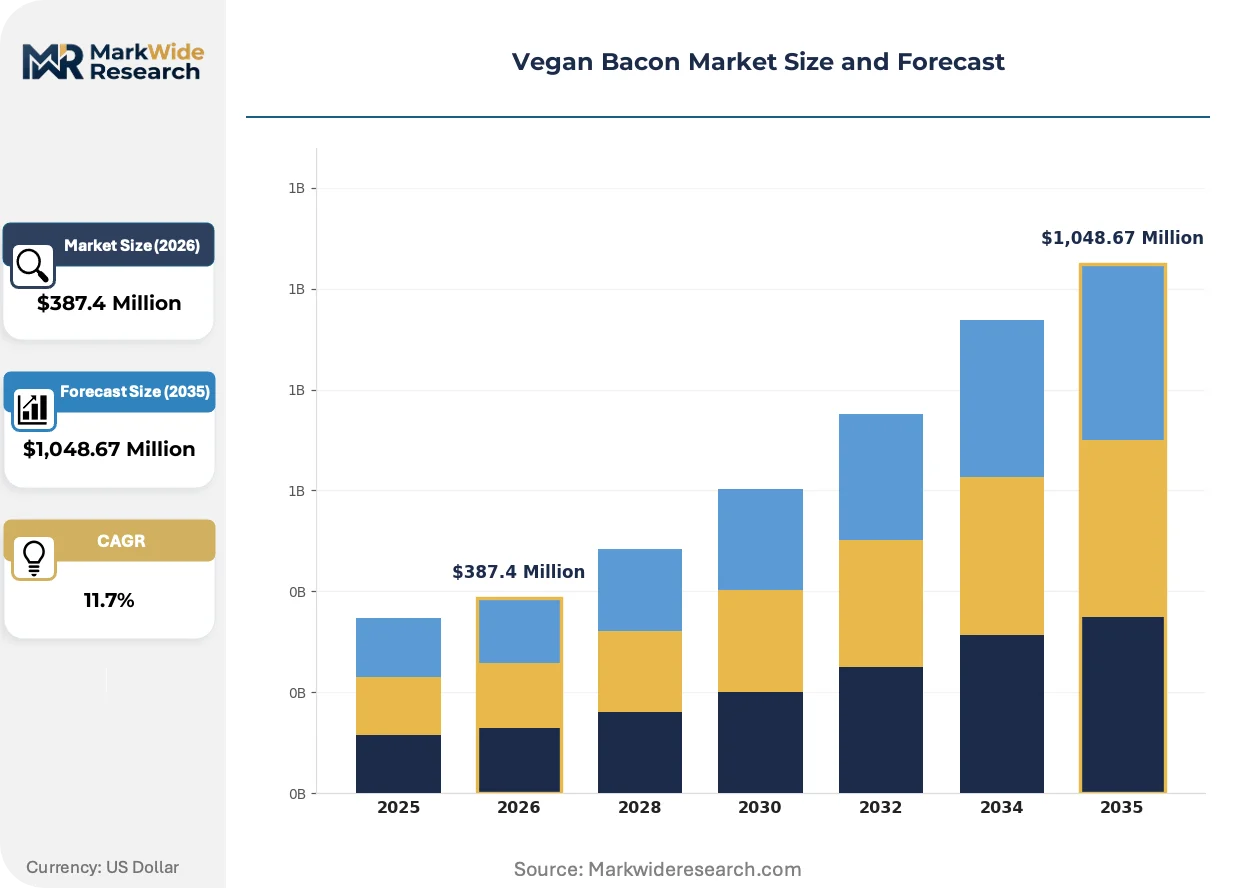
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $1,048.67 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Maple Flavor, Smoked, Spicy, Classic Ingredient Base: Pea Protein, Soy Protein, Coconut Oil, Wheat Gluten Distribution Channel: Supermarkets, Online Retailers, Health Food Stores, Restaurants Consumer Type: Vegans, Vegetarians, Flexitarians, Health-Conscious Consumers |
| Companies Covered | Beyond Meat Inc., Hooray Foods, Upton's Naturals, Lightlife (Greenleaf Foods), Tofurky, The Vegetarian Butcher (Unilever), Sweet Earth Foods (Nestlé), Umaro Foods, Zhenmeat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Bacon Market Evolving Landscape
Fermentation-derived lipid systems are converging with extrusion texturization to redefine what "crispness" means in plant-based cured strips, while regulatory clarity on hybrid compositions is unlocking formulation experimentation previously deferred.
Precision fermentation of heme and fat molecules is absorbing the technical risk that previously constrained plant-only products from achieving pork-belly sensory fidelity. Quick-service kitchen operators are adopting these inputs faster than retail brands, drawn by cook-time consistency and reduced consumer complaint rates. The structural consequence is that R&D investment is concentrating in biotech-enabled suppliers rather than legacy extrusion houses.
REACH registrations for pyroligneous acid derivatives and other smoke-flavoring additives are tightening formulation freedom for manufacturers exporting into EU member states. EFSA's expanded novel-food assessments now capture enzymatically modified lipids, extending safety documentation requirements. European discount-channel suppliers are responding by simplifying ingredient decks to avoid classification triggers, sacrificing some flavor complexity for speed-to-market.
Flexitarian households are compressing their purchase evaluation cycles, relying on front-of-pack certifications rather than ingredient list scrutiny. Supermarket private-label buyers are exploiting this by accelerating SKU rotation and truncating supplier qualification periods. This pattern is most visible in United Kingdom retail, where own-label vegan bacon ranges have captured disproportionate chilled-case space through rapid range expansion.
Vegan Bacon Market Segmentation
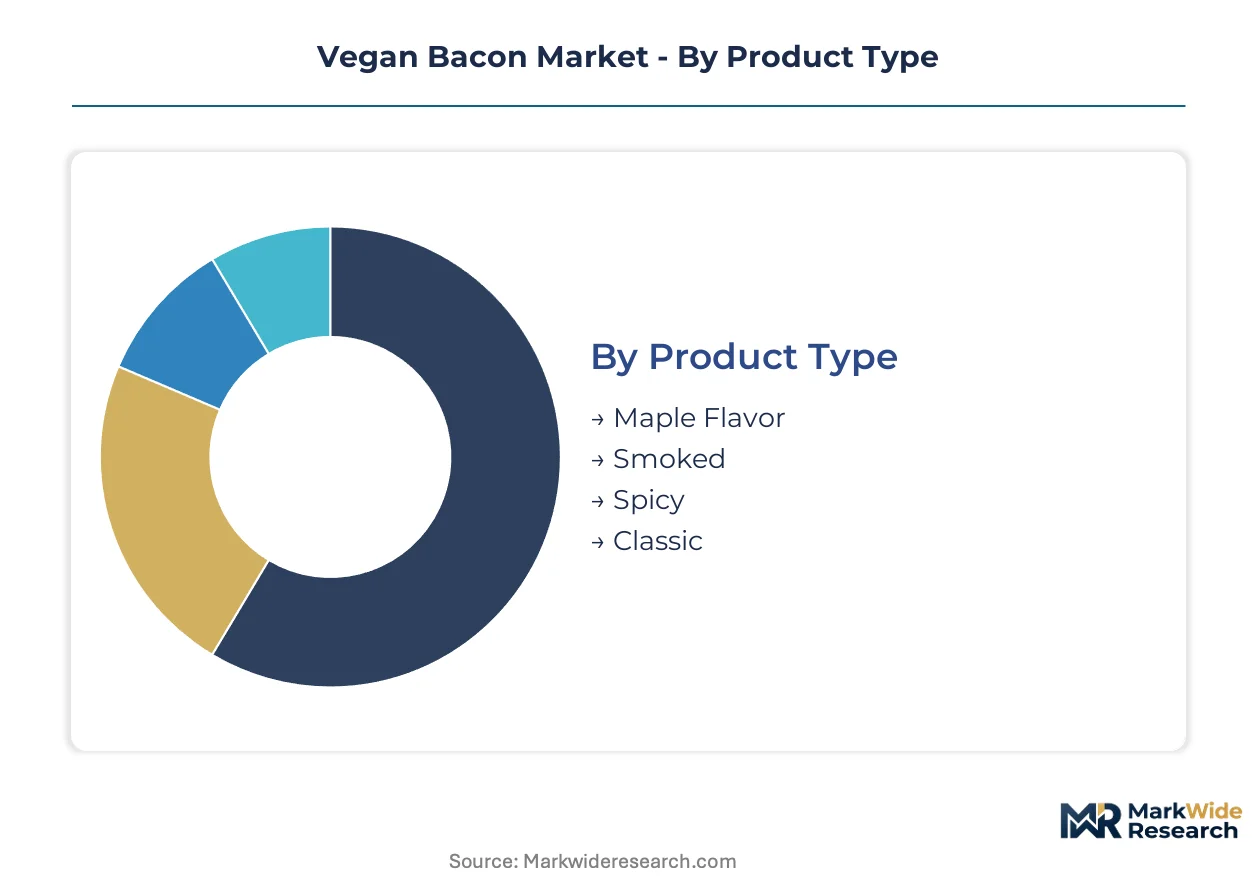
Vegan bacon segmentation reveals how formulation choices and channel strategies create divergent margin profiles across the value chain. Distinct consumer cohorts prioritize sensory fidelity, clean-label credentials, or price accessibility, fragmenting addressable markets into non-overlapping purchase missions.
Product Type:
Supply concentration among flavor-variant producers clusters around curing and smoking equipment capabilities, with smoke-house capacity determining regional production footprints.
- Maple Flavor:Formulations incorporate maple syrup solids or natural flavor extracts layered onto extruded protein bases, creating a sweet-savory profile that dominates North American breakfast sandwich applications. Quick-service restaurant chains in the United States specify this variant for standardized morning menu items, driving contract manufacturing consolidation around Midwest smokehouses.
- Smoked:Liquid smoke or pyroligneous acid applications replicate traditional hardwood curing, with hickory and applewood variants commanding refrigerated case premiums. United Kingdom supermarket private-label ranges favor this profile for own-label expansion, where British consumers associate smokiness with breakfast authenticity.
- Spicy:Chili extract or paprika oleoresin inclusions target younger demographics and sandwich-build applications requiring flavor intensity.
- Classic:Unflavored cured strips serve recipe-flexible households and foodservice operators seeking neutral protein substrates.
Today's leader: Smoked. Tomorrow's challenger: Maple Flavor.
Ingredient Base:
Cost tier stratification separates allergen-free premium positioning from commodity protein economics, with extraction technology determining input cost trajectories.
- Pea Protein:Wet-fractionated pea isolates deliver hypoallergenic positioning and cleaner-label appeal, commanding refrigerated premium placement. Wet-fractionation yield improvements are compressing input costs for suppliers serving flexitarian households in Germany and France.
- Soy Protein:Extruded soy concentrates occupy value-tier placement with established supply chains, though GMO and allergen concerns constrain growth in European markets.
- Coconut Oil:Saturated fat replication creates crispness and mouthfeel without hydrogenation, exposing formulations to tropical commodity price swings.
- Wheat Gluten:Seitan-derived textures dominate European discount channels but face technical barriers replicating pork-belly chew without soy or pea supplementation.
Pea protein holds the premium tier. Coconut oil formulations are climbing the fastest as fat-replication technologies mature.
Distribution Channel:
Volume concentration varies sharply by preparation format, with frozen bulk packs dominating retail and single-serve pouches penetrating convenience channels.
- Supermarkets:Chilled and frozen case placement drives household penetration, with United Kingdom retailers expanding own-label shelf space fastest.
- Online Retailers:Direct-to-consumer subscriptions and marketplace listings serve trial-resistant consumers seeking variety packs.
- Health Food Stores:Specialty retail channels prioritize certified organic and non-GMO variants with transparent ingredient decks.
- Restaurants:Foodservice specifications emphasize cook-time consistency and hold stability for breakfast and sandwich applications.
Supermarkets anchor current volume. Restaurants represent the steepest expansion trajectory as chain standardization accelerates.
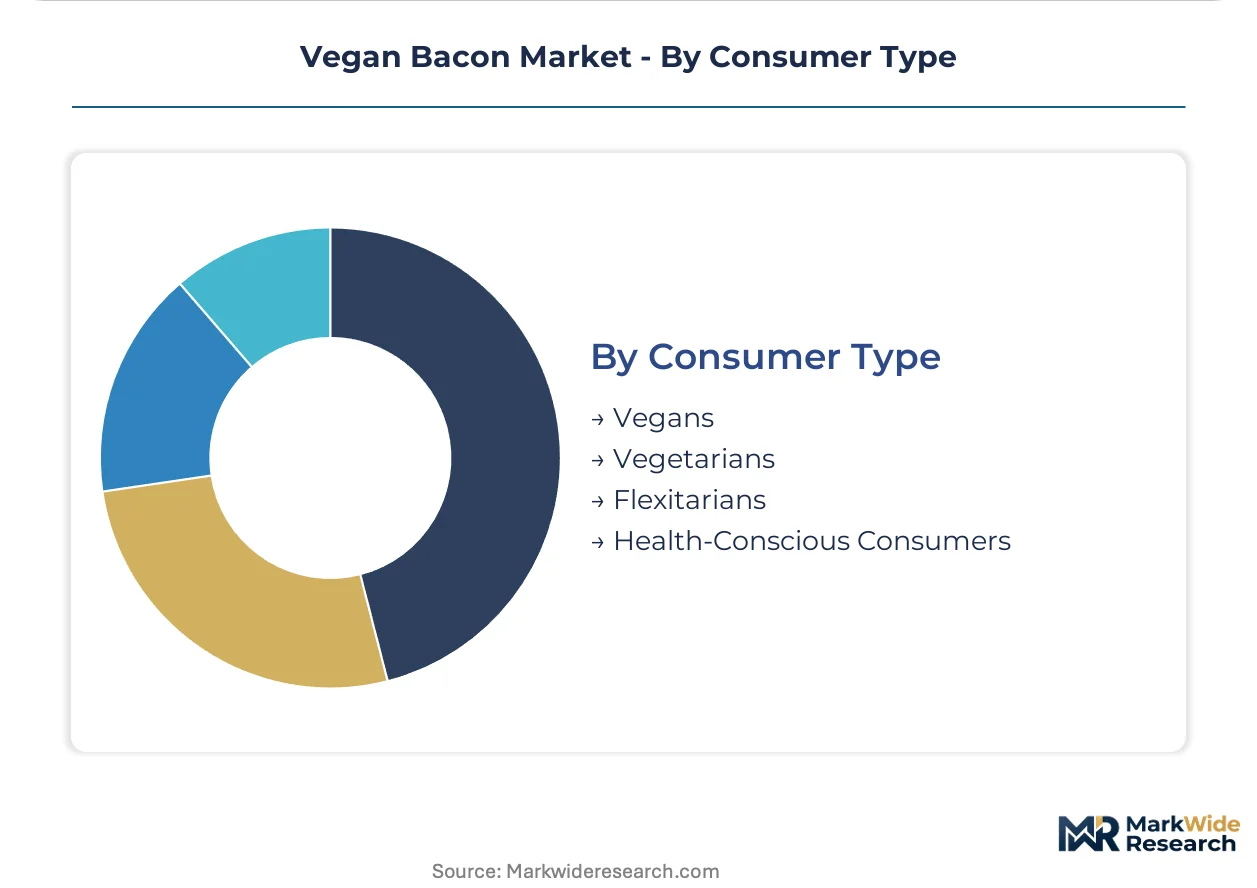
Consumer Type:
Margin structure diverges by purchase frequency and price sensitivity, with flexitarian households showing highest repeat rates but lowest per-transaction values.
- Vegans:Ethical consistency drives premium tolerance and brand loyalty, with purchase decisions weighing animal welfare credentials alongside sensory performance.
- Vegetarians:Longstanding meat avoidance creates established substitution habits, with this cohort serving as early adopters for novel protein technologies.
- Flexitarians:Intermittent meat reduction drives the largest addressable population, with United Kingdom and German households reducing pork consumption through breakfast protein rotation.
- Health-Conscious Consumers:Saturated fat and sodium reduction goals motivate trial, though sustained purchase depends on clean-label ingredient transparency.
Flexitarians dominate transaction volume. Health-conscious consumers are gaining share fastest as front-of-pack certifications simplify evaluation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United Kingdom pioneered commercial vegan bacon scaling through supermarket private-label programs that normalized plant-based breakfast proteins in mainstream retail. This historical foundation established regulatory templates and consumer acceptance patterns now diffusing across continental Europe and North America.
United Kingdom
Supermarket chains in London and the Southeast have expanded chilled-case shelf space for own-label vegan bacon ranges by double-digit percentages annually. The Food Standards Agency enforces novel-food notification requirements for fermented-fat ingredients entering the British market. Manufacturing concentration clusters in the Midlands, where smokehouse infrastructure originally built for traditional cured meats now serves hybrid protein production.
Germany
Flexitarian households in Bavaria and North Rhine-Westphalia drive breakfast protein rotation away from pork through institutional catering contracts and retail trial. EFSA novel-food assessments for precision-fermented lipids are accelerating, creating regulatory templates for cross-border formulation approval. The Berlin-Brandenburg corridor hosts pilot facilities testing enzymatically modified lipid systems for improved Maillard reaction performance.
United States
Quick-service restaurant chains headquartered in Chicago and the Midwest now mandate plant-based breakfast SKUs as standard menu offerings, creating predictable offtake volumes. The FDA's updated labeling guidance for cell-cultured and fermented proteins is reshaping manufacturer communication strategies on protein sourcing. Smokehouse capacity in the Midwest dominates contract manufacturing for maple-flavored variants specified by national chain accounts.
Netherlands
Foodservice distributors in the Randstad region anchor European supply for plant-based breakfast proteins through Unilever's institutional relationships. REACH registrations for pyroligneous acid derivatives and smoke-flavoring additives extend 18-24 months, delaying EU launches for new curing formulations. The Eindhoven Region hosts R&D facilities developing coconut-oil-based fat replication technologies for allergen-free crispness.
China
Urban consumers in Shanghai and the Yangtze River Delta are experimenting with plant-based cured strips through e-commerce trial packs and premium supermarket placement. SAMR oversight of novel protein labeling remains less prescriptive than Western frameworks, allowing faster formulation iteration. Zhejiang Province hosts extrusion equipment manufacturers supplying both domestic brands and export-oriented producers.
Vegan Bacon Market Competitive Landscape
The competitive structure tilts toward diversified food conglomerates with existing smokehouse infrastructure and frozen distribution networks. Tiered specialization separates premium allergen-free formulations from value-tier commodity extrusions. Three archetypes dominate: legacy meat-alternative specialists with decades of curing expertise, multinational CPG divisions leveraging institutional foodservice relationships, and biotech-enabled startups pursuing precision-fermented fat integration. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with smokehouse asset control and QSR contract qualification serving as primary barriers to volume scaling.
Within the multinational CPG tier, Beyond Meat Inc. and The Vegetarian Butcher occupy positions exemplifying divergent geographic strategies—one anchoring North American retail frozen-section visibility, the other leveraging European foodservice supply through parent-company institutional networks. Among allergen-focused specialists, Hooray Foods represents the coconut-oil-based fat replication archetype, differentiating through soy-free and gluten-free crispness technologies. These three companies collectively illustrate how formulation philosophy, channel concentration, and geographic anchoring segment competitive positioning in plant-based cured proteins.
| Leading Market Players |
|---|
| Beyond Meat Inc. |
| Hooray Foods |
| Upton's Naturals |
| Lightlife (Greenleaf Foods) |
| Tofurky |
| The Vegetarian Butcher (Unilever) |
| Sweet Earth Foods (Nestlé) |
| Umaro Foods |
| Zhenmeat |
| Others |
Value Network & Pricing Analysis
Pea protein-to-wheat gluten tier divergence splits vegan bacon into premium refrigerated placement and value-tier frozen discount channels, with wet-fractionation yield improvements compressing input costs for allergen-free formulations while coconut oil price volatility exposes fat-replication chemistries to tropical commodity swings. This bifurcation concentrates margin capture among suppliers controlling Midwest smokehouse infrastructure for quick-service contract manufacturing, while European discount-channel players sacrifice flavor complexity to avoid EFSA novel-food assessment delays.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels reflects ingredient base differentiation and certification status, with pea protein formulations commanding refrigerated case premiums due to cleaner-label appeal and soy-free positioning. Price differentiation stems from wet-fractionation extraction yields and REACH registration compliance timelines, with ECHA chemical safety reviews extending 18-24 months for smoke-flavoring additives. Cost compression in the wheat-gluten tier intensifies because European discount channels face technical barriers replicating pork-belly chew without soy or pea supplementation. Flexitarian households in the United Kingdom and Germany show lowest price sensitivity for allergen-free variants, while institutional catering buyers in Bavaria prioritize unit economics over sensory fidelity.
Supply Chain Analysis
Reverse-logistics flows for temperature-compromised chilled products remain underdeveloped, forcing write-offs that inflate net delivered costs for supermarket private-label ranges with short shelf lives. Geographic supply concentration clusters in the United States, the Netherlands, and China, with Midwest smokehouses anchoring North American maple-flavor contract manufacturing and Zhejiang Province supplying extrusion equipment to export-oriented producers. Raw material dependencies center on pea protein isolates, coconut oil, and pyroligneous acid derivatives for smoke flavoring. Single-source vulnerability in tropical lipid supply exposes formulations to climate disruption in Southeast Asian growing regions. Distribution runs through frozen bulk-pack retail for household penetration and single-serve pouch formats for convenience-channel breakfast bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EFSA novel-food pathway clarity for precision-fermented fats is accelerating cross-border formulation approval and reshaping competitive access.
For Market Incumbents: Deepen smokehouse asset control in the United States Midwest to defend quick-service contract manufacturing positions against biotech-enabled entrants pursuing hybrid protein architectures. Prioritize backward integration into wet-fractionated pea protein supply to compress input costs and maintain premium-tier margin separation from wheat-gluten value competitors. For New Entrants and Emerging Players: Institutional catering contracts in Bavaria and North Rhine-Westphalia represent an underserved buyer archetype with predictable offtake volumes and limited incumbent penetration. Target German foodservice distributors with cook-time-consistent maple-flavor formulations that satisfy flexitarian breakfast rotation demand without requiring retail shelf space qualification. For Investors and Strategic Acquirers: Consolidation pressure builds where fermentation scale-up talent scarcity constrains pilot-to-commercial timelines for precision-fat technologies. Long-term viability favors biotech-enabled suppliers with USDA-FDA dual-labeling compliance capabilities. Watch EFSA approval velocity for enzymatically modified lipids as the inflection signal determining which ingredient bases achieve scalable European market access first.| Strategic Initiative | Industry Significance |
|---|---|
| Smokehouse Capacity Expansion | Midwest infrastructure investments capture quick-service contract manufacturing consolidation. |
| Precision-Fermentation Scale-Up | Bioprocess engineering talent acquisition accelerates novel-fat commercialization timelines. |
| EFSA Novel-Food Registration | Regulatory pathway clarity unlocks cross-border European market entry for hybrid formulations. |
| Single-Serve Pouch Launch | Convenience-channel formats decouple volume logic from legacy bulk-pack retail economics. |
| Backward Integration into Pea Protein | Wet-fractionation yield improvements compress input costs for allergen-free premium positioning. |
Research Methodology
Bottom-up foodservice and retail channel modeling reconciled against top-down ingredient supply and smokehouse capacity tracking forms the analytical core of this study. Primary interviews with quick-service restaurant procurement directors, supermarket private-label buyers, contract manufacturing executives, and EFSA regulatory affairs specialists combined with secondary validation from FDA labeling guidance documents, EFSA novel-food assessment databases, REACH registration filings, and USDA-FSIS inspection protocols. Triangulation across these sources ensures volume estimates reflect actual offtake commitments rather than aspirational production capacity.
Input-output matrices map pea protein extraction yields, coconut oil commodity price trajectories, and smoke-flavoring additive regulatory status against end-use demand across quick-service, retail, and foodservice channels over the projection horizon. Segmentation dimensions include flavor variant, ingredient base, distribution channel, and consumer type, with CAGRs derived from contract manufacturing qualification timelines and supermarket shelf-space expansion rates. Forecast inputs incorporate wet-fractionation technology adoption curves and EFSA assessment velocity for precision-fermented lipids.
Underlying measurement precision varies by segment; quick-service restaurant offtake and United Kingdom retail velocity carry tighter precision than emerging market e-commerce trial volumes. Forecasts reflect assumptions about regulatory approval timelines and commodity price stability that could revise if EFSA novel-food pathways stall or tropical climate disruption accelerates coconut oil volatility. Practitioners should monitor EFSA assessment completion rates and Midwest smokehouse utilization for early signals of supply constraint or demand acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Europe Meat Substitutes Market
Plant Based Food
Pea Protein Isolate Market
Plant Based Food
Vegan Chocolate Market
Plant Based Food
Black Rice Protein Market
Plant Based Food
Plant-Based Ham Market
Plant Based Food
Vegan Alternatives Market
Plant Based Food
Plant-Based Sausages Market
Plant Based Food
Vegan Drink Mixes Market
Plant Based Food
Asia-Pacific Plant-Based Seafood Market
Plant Based Food
Plant-Based Margarine Market
Plant Based Food
Vegan Steak Market
Plant Based Food
Fermented Plant-Based Ingredient Market
Plant Based Food
Plant-Based Seafood Market
Plant Based Food
Europe Plant-Based Meal Kit Market
Plant Based Food
Vegan Diet Market
Plant Based Food
United States Plant Protein Market