
 Middle East Plant Protein Market | 2026-2036
Middle East Plant Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Plant Protein Market Foresight
Modular ingredient bundles combining protein isolates with flavor masking systems is broadening procurement options for Middle Eastern food manufacturers. Cargill leverages its regional oilseed processing footprint to secure raw material flows. Kerry Group differentiates through integrated taste and nutrition solutions tailored for local palates. Roquette anchors supply reliability with its pea protein extrusion capabilities serving Gulf markets.
Plant protein encompasses extracted, concentrated, or isolated proteinaceous fractions derived from legumes, oilseeds, and cereals, typically achieving protein contents ranging from 50% to 90% by dry weight depending on processing intensity; these ingredients function as functional binders, emulsifiers, and nutritional fortifiers in formulated foods. Protein isolates command premium positioning due to superior amino acid completeness and minimal off-flavor carryover, while textured proteins capture volume leadership through direct meat-analog applications in foodservice. Protein concentrates maintain cost advantages in nutritional supplements where solubility requirements are less stringent than in beverage systems.
Saudi Arabia's Food and Drug Authority and the UAE's Ministry of Climate Change and Environment enforce halal certification and novel food approval pathways that determine market entry timelines for imported plant protein ingredients. The Gulf Standards Organization harmonizes labeling requirements across member states, creating compliance economies for suppliers serving multiple markets. Stakeholders must track evolving national food security mandates that increasingly subsidize domestic processing capacity over raw material imports.
Market Dynamics
Halal certification requirements enforced by Saudi Arabia's Food and Drug Authority and the UAE's Ministry of Climate Change and Environment are restructuring ingredient sourcing protocols, forcing international suppliers to establish dedicated Middle East processing lines or forfeit foodservice contracts.
Growth Catalysts
- SFDA Novel Food Pathways:Saudi Arabia's streamlined approval frameworks for alternative proteins are compressing market entry timelines for textured vegetable protein suppliers targeting domestic manufacturing partnerships.
- Foodservice Chain Expansion:Burger chains and casual dining operators across the Gulf Cooperation Council states are mandating plant-based menu options, creating guaranteed offtake agreements for protein isolate processors.
- Domestic Extrusion Capacity:Industrial parks in Jeddah and Riyadh are attracting pea protein texturization equipment investments backed by national food security subsidies.
Market Restraints
- Water-Intensive Crop Inputs:Regional chickpea and fava bean cultivation faces irrigation cost volatility as groundwater depletion accelerates across the Arabian Peninsula.
- Single-Source Supply Concentration:European Union processors currently supply over seventy percent of high-purity isolates, exposing buyers to shipping lane disruptions through the Suez Canal corridor.
- Flavor Masking Technical Limitations:Persistent beany off-notes in locally sourced mung bean concentrates restrict beverage applications despite favorable cost positions.
Strategic Opportunities
- Qatar and Kuwait Penetration:Underdeveloped food manufacturing infrastructure in these markets creates first-mover advantages for modular ingredient bundle suppliers offering integrated taste systems.
- Hybrid Meat-Analog Formulations:Blended products combining plant proteins with cultured animal cells are expanding into premium retail channels as regulatory frameworks for novel foods mature.
- MOHAP Sustainability Incentives:The UAE Ministry of Health and Prevention's carbon labeling requirements for institutional catering are creating procurement preferences for locally processed isolates with verified supply chain footprints.
Industry Challenges
- Halal Certification Timeline Compression:Multi-month approval cycles for imported enzyme processing aids delay product launches despite completed formulation development.
- Extrusion Technician Scarcity:Limited regional expertise in high-moisture extrusion operations forces reliance on expatriate specialists, inflating operational costs for new production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Plant Protein Market |
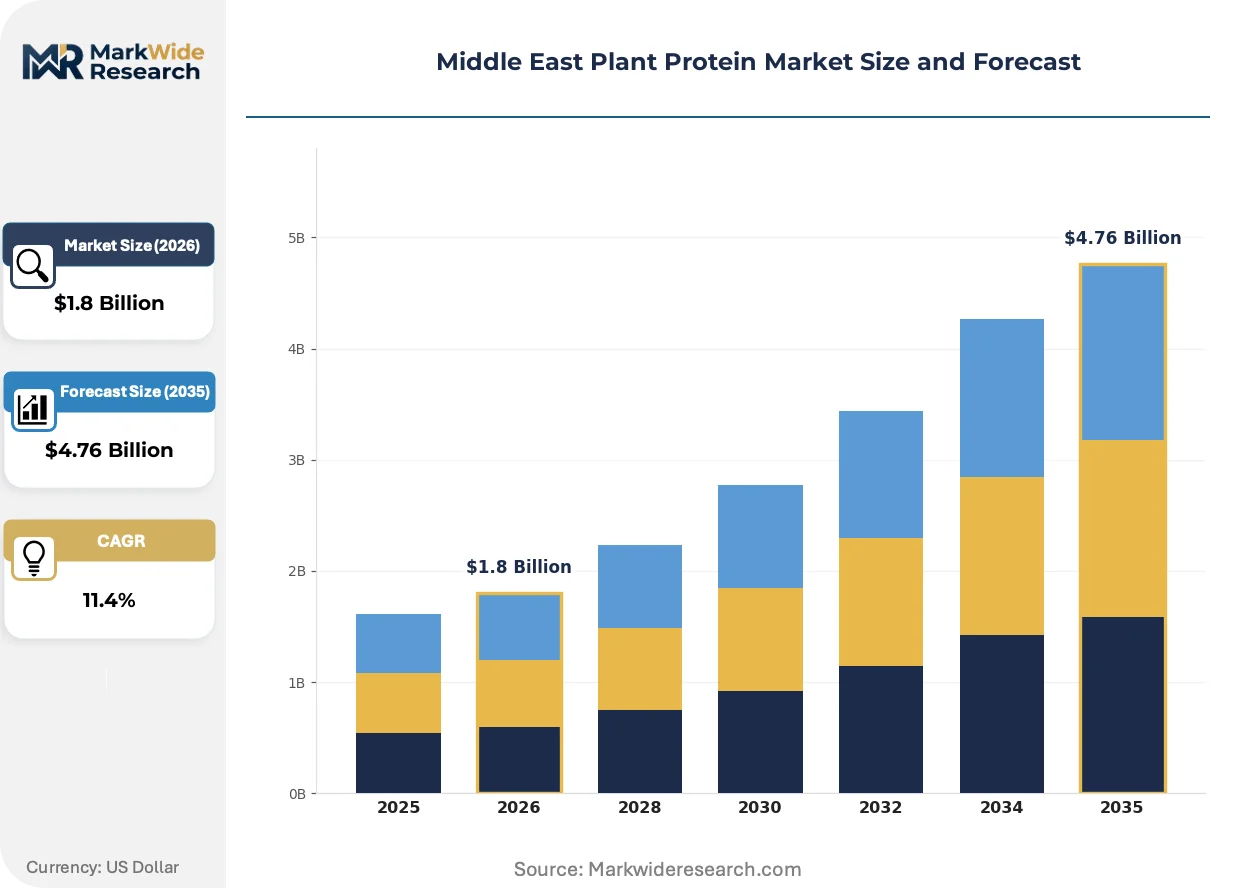
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Textured Protein, Protein Isolates, Protein Concentrates, Whole Protein Application: Food & Beverages, Nutritional Supplements, Animal Feed, Meat Alternatives Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Direct Sales End User: Households, Foodservice Industry, Retailers, Manufacturers |
| Companies Covered | Wilmar International, DuPont, Cargill, Roquette, Glanbia, Archer Daniels Midland Company, Ingredion, Axiom Foods, Kerry Group, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Plant Protein Market Shifts & Advancements
Precision fermentation-derived protein ingredients are disrupting traditional extraction economics, while regulatory harmonization efforts across Gulf Standards Organization member states are simplifying multi-market deployment strategies for formulation suppliers.
High-moisture extrusion technology is expanding into direct meat-analog production for foodservice chains. Hotel and restaurant procurement teams in Dubai and Abu Dhabi are adopting these textured proteins at accelerating rates to meet sustainability procurement mandates. This equipment shift is expanding into contract manufacturing arrangements that bypass traditional ingredient trading margins.
Gulf Standards Organization labeling harmonization protocols are eliminating redundant compliance testing across Saudi Arabia, UAE, Qatar, Bahrain, Kuwait, and Oman. Industrial ingredient suppliers now submit single documentation packages rather than country-specific filings. Food manufacturers with multi-market distribution networks capture the greatest administrative cost reductions from this regulatory consolidation.
Direct supplier relationships between protein isolate producers and foodservice chains are displacing traditional distributor intermediaries. Procurement teams at regional quick-service restaurant headquarters are negotiating volume commitments directly with Roquette and Cargill regional offices. This channel restructuring is most visible in the UAE, where Dubai-based chain headquarters exercise centralized purchasing authority over franchise operations spanning multiple Gulf markets.
Middle East Plant Protein Market Segmentation
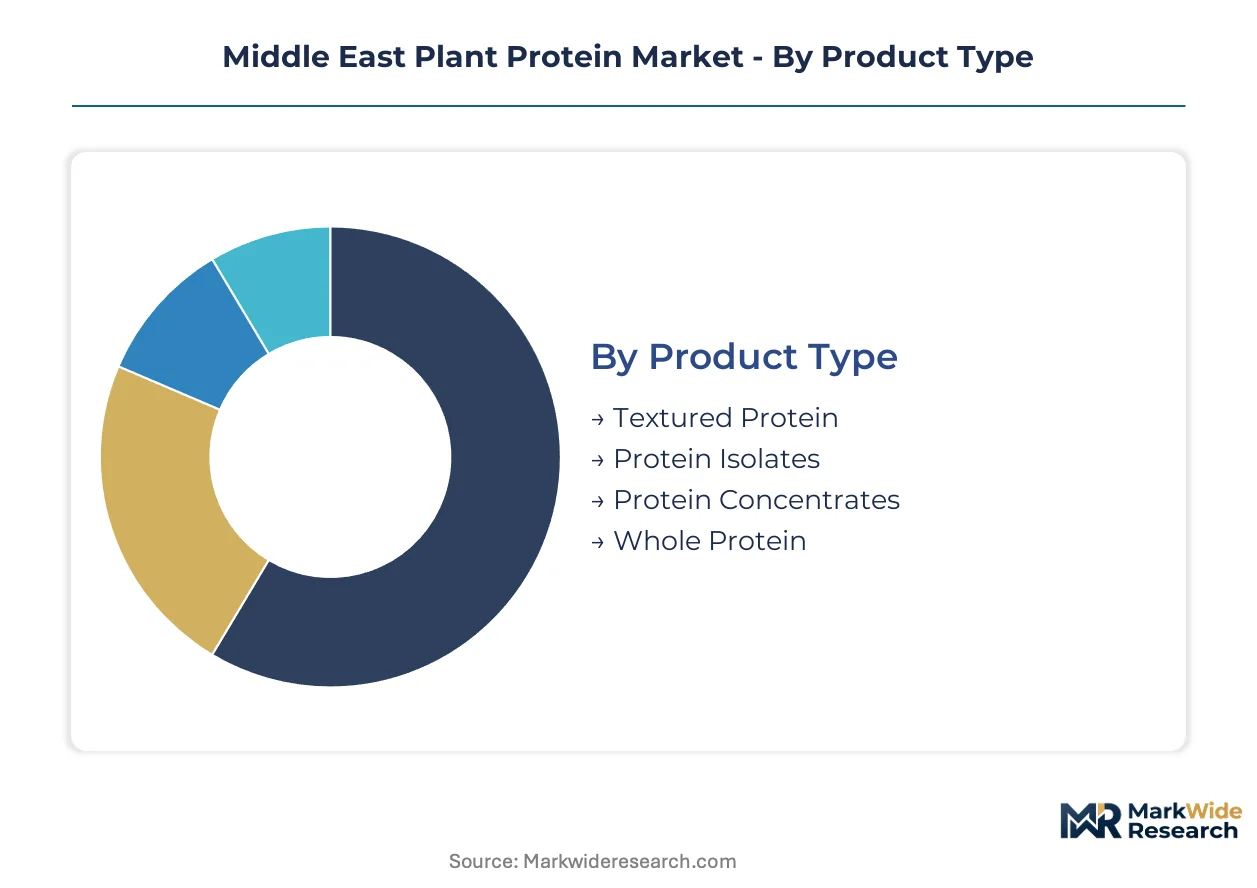
Product differentiation across extraction intensity and functional performance determines procurement priorities for Middle Eastern food manufacturers navigating halal certification requirements. Segmentation reveals where protein isolates command premium positioning against textured proteins driving foodservice volume.
Product Type:
Extraction technology and protein purity levels define the competitive axis, with processing intensity directly correlating to amino acid completeness and off-flavor mitigation.
- Protein Isolates:Achieving 85-90% protein content through isoelectric precipitation or membrane filtration, these ingredients deliver superior solubility and minimal beany notes. Demand concentrates in UAE beverage formulations and Saudi nutritional supplements where SFDA novel food approvals favor high-purity inputs.
- Textured Protein:High-moisture extrusion creates fibrous structures mimicking muscle tissue for direct meat-analog applications. Dubai and Abu Dhabi foodservice chains are adopting these proteins fastest to meet MOHAP sustainability procurement mandates in institutional catering.
- Protein Concentrates:50-70% protein fractions retain more fiber and carbohydrate carriers, finding cost-sensitive placement in nutritional supplements across Gulf Cooperation Council states where solubility requirements are less stringent than beverage systems.
- Whole Protein:Minimally processed flours and grits serve traditional Middle Eastern applications including falafel mixes and kibbeh formulations, with domestic fava bean and chickpea sourcing prioritized under Saudi national food security subsidies.
Mature deployment sits with textured proteins in foodservice meat analogs. Newer deployment is concentrated in protein isolates for halal-certified functional beverages.
Application:
End-use requirements for mouthfeel, label claims, and thermal stability create distinct procurement specifications across formulation categories.
- Meat Alternatives:High-moisture extruded proteins and binding systems replicate texture and juiciness in burger patties and sausages. Jeddah and Riyadh manufacturing partnerships are expanding fastest as domestic extrusion capacity attracts equipment investments backed by food security subsidies.
- Food & Beverages:Protein fortification in dairy alternatives, bakery, and beverages demands isolates with superior emulsification and minimal flavor masking requirements. UAE halal certification hubs in Dubai and Abu Dhabi concentrate import and formulation activity.
- Nutritional Supplements:Concentrates and isolates serve powder and ready-to-drink formats where cost-per-gram protein drives procurement decisions across Gulf retail channels.
- Animal Feed:Oilseed meals and lower-grade concentrates provide amino acid supplementation for poultry and aquaculture operations, with Saudi domestic crushing capacity reducing import dependency.
Volume leadership belongs to meat alternatives in foodservice. Margin expansion is climbing fastest in nutritional supplements targeting fitness and clinical nutrition segments.
Distribution Channel:
Channel selection reflects purchase frequency, technical consultation needs, and lot-size requirements across buyer types.
- Direct Sales:Roquette and Cargill regional offices negotiate volume commitments directly with Dubai-based quick-service restaurant headquarters, bypassing distributor margins for multi-market franchise procurement.
- Supermarkets:Hypermarket chains across Saudi Arabia and the UAE stock branded protein powders and meat-alternative retail SKUs, with shelf space allocation increasingly tied to halal certification documentation.
- Online Retail:E-commerce platforms serve specialized isolate grades and imported specialty proteins to households and small manufacturers, with delivery infrastructure expanding fastest in UAE urban corridors.
- Health Food Stores:Independent retailers in Abu Dhabi and Dubai cater to premium organic and non-GMO positioning, though volume remains constrained by higher price points.
Procurement consolidation is concentrating in direct sales for foodservice chains. Channel experimentation is expanding most quickly in online retail serving specialized formulation needs.
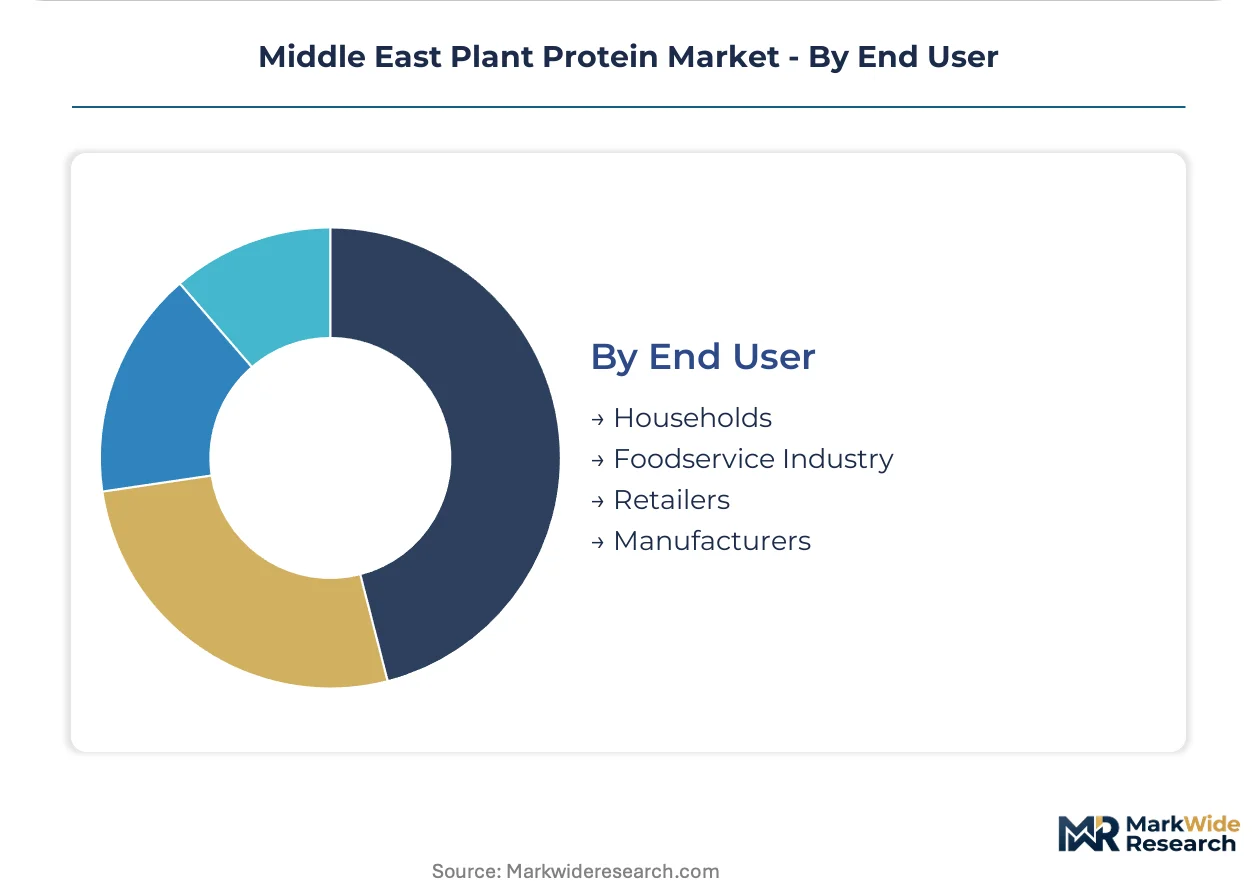
End User:
Buyer scale and technical capability determine whether procurement favors commodity concentrates or specification-grade isolates.
- Foodservice Industry:Hotel and restaurant procurement teams in Dubai and Abu Dhabi specify textured proteins for sustainability-mandated menu items, with centralized purchasing authority spanning multiple Gulf markets.
- Manufacturers:Industrial formulators in Jeddah and Riyadh industrial parks source isolates and concentrates for branded consumer goods, with domestic processing subsidies reducing landed cost differentials against European imports.
- Retailers:Private-label development teams at supermarket chains negotiate modular ingredient bundles combining protein bases with flavor masking systems from Kerry Group regional offices.
- Households:Direct consumer purchases concentrate in protein powders and meat-alternative retail products, with purchase decisions increasingly influenced by MOHAP carbon labeling visibility.
Contract volume anchors with foodservice industry procurement. Emerging demand is gaining share fastest among manufacturers building domestic production capacity under national food security mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic production capacity lags behind consumption growth across the Gulf Cooperation Council, forcing reliance on imported isolates and concentrates while Saudi Arabia and the UAE invest in local extrusion infrastructure.
Saudi Arabia
SFDA novel food approval pathways are accelerating textured protein partnerships between international suppliers and Jeddah-based manufacturers. The national food security strategy subsidizes domestic pea protein processing equipment in industrial parks outside Riyadh. Domestic fava bean cultivation receives irrigation priority despite groundwater constraints.
United Arab Emirates
MOHAP carbon labeling mandates for institutional catering are redirecting procurement toward verified low-footprint isolates. Dubai and Abu Dhabi function as halal certification hubs for re-export across Gulf markets. Hotel procurement teams in these emirates specify textured proteins for sustainability-mandated menu items at accelerating rates.
Qatar
Underdeveloped food manufacturing infrastructure creates first-mover positioning for modular ingredient bundle suppliers. The national development strategy prioritizes import substitution in processed foods. Doha-based distributors are negotiating exclusive supply arrangements with European isolate processors.
Kuwait
Limited domestic crushing capacity concentrates demand on imported soy and pea protein concentrates. The country's central food procurement authority is revising specifications to favor halal-certified inputs. Local trading houses are establishing direct relationships with Roquette and Cargill regional offices.
Oman
Port infrastructure at Sohar and Salalah offers transshipment advantages for isolates bound for Saudi Arabia's eastern province. The fisheries development fund is exploring aquafeed applications for lower-grade oilseed meals. Domestic food manufacturers remain dependent on UAE-based distributors for technical ingredient support.
Middle East Plant Protein Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across ingredient supply tiers. Market structure concentrates around three to five integrated processors controlling high-purity isolate flows, while regional trading houses fragment the concentrate segment. Strategic archetypes include oilseed crushers with backward integration into protein fractionation, taste-and-nutrition integrators, and extrusion technology licensors. Dominant competitive moves encompass direct sales channel establishment bypassing distributor intermediaries, and modular bundle offerings combining protein bases with flavor masking systems.
Within the diversified agribusiness tier, Cargill leverages its regional oilseed processing footprint to secure raw material flows into protein fractionation. Kerry Group exemplifies the taste-and-nutrition integrator archetype through bundled solutions. Roquette anchors the specialized protein processor position with extrusion capabilities serving Gulf markets directly.
| Leading Market Players |
|---|
| Wilmar International |
| DuPont |
| Cargill |
| Roquette |
| Glanbia |
| Archer Daniels Midland Company |
| Ingredion |
| Axiom Foods |
| Kerry Group |
| Others |
Supply & Pricing Matrix
Pea protein commodity benchmarks cascading through European Union processing hubs stratify Middle East procurement into three distinct tiers: pharmaceutical-grade isolates commanding premium positioning, foodservice-textured proteins capturing volume contracts, and feed-grade concentrates serving cost-sensitive aquafeed applications.
Pricing Analysis
Margin tightening in protein isolates reflects European Union processor concentration and Suez Canal logistics exposure. Three-tier pricing structure across premium isolates, standard concentrates, and economy whole proteins segments buyers by certification grade and volume scale. Cost-down pressure on textured proteins accelerates because Jeddah and Riyadh domestic extrusion capacity attracts food security subsidies. Foodservice chains demonstrate lowest price sensitivity due to sustainability mandate compliance requirements, while animal feed compounders exhibit highest elasticity.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg anchor hub-and-spoke patterns feeding Gulf Cooperation Council markets. Supply concentrates in the Netherlands, France, and Germany for high-purity isolates, while India and China anchor lower-grade concentrate flows. Raw material dependencies center on yellow pea, fava bean, and chickpea inputs. Single-source vulnerability through Suez Canal chokepoints creates structural risk. Distribution runs through Dubai-based trading houses with direct sales channels displacing traditional intermediaries for foodservice chain procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-moisture extrusion technology is displacing legacy dry extrusion systems across Gulf foodservice manufacturing, compressing equipment replacement cycles and reshaping technician training requirements.
For Market Incumbents: Deploy backward integration into regional oilseed crushing to secure raw material flows against European supply concentration. Cargill's regional footprint demonstrates this lever's efficacy. Secure halal certification investment ahead of SFDA timeline compression. Channel control through direct sales offices in Dubai bypasses distributor margin capture. For New Entrants and Emerging Players: E-commerce platforms serving specialized isolate grades offer lowest customer acquisition cost entry into UAE household segments. Qatar and Kuwait's underdeveloped food manufacturing infrastructure presents white-space positioning for modular ingredient bundle suppliers. Target institutional catering procurement teams in Abu Dhabi seeking MOHAP carbon label compliance. For Investors and Strategic Acquirers: The window for entry favors extrusion technology licensors with high-moisture equipment deployment capability. Long-term viability hinges on domestic processing subsidies persisting across Saudi national food security mandates. Watch SFDA novel food approval velocity as inflection indicator for textured protein partnership valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Extrusion Capacity Buildout | Jeddah industrial parks attract equipment investments backed by Saudi food security subsidies. |
| Halal Certification Fast-Track Investment | SFDA streamlined pathways compress approval timelines for textured vegetable protein suppliers. |
| Direct Sales Channel Establishment | Dubai-based quick-service restaurant headquarters negotiate volume commitments bypassing distributors. |
| Modular Ingredient Bundle Development | Kerry Group's integrated taste systems demonstrate procurement option expansion for regional manufacturers. |
| Precision Fermentation Partnership | Novel protein ingredients disrupt traditional extraction economics across Gulf beverage applications. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with foodservice procurement directors, extrusion equipment operators, halal certification specialists, and industrial park development officers combined with SFDA submission databases, Gulf Standards Organization harmonization protocols, and EU import statistics. Bottom-up volume modeling triangulated against top-down expenditure estimates.
Segmentation granularity operated at protein type, application, and distribution channel dimensions across the analysis window. CAGRs derived from slope-log regression against base-year anchoring. Modeled inputs included foodservice chain expansion commitments, domestic subsidy allocation trajectories, and MOHAP carbon labeling adoption curves.
The model holds under stable Suez Canal throughput and sustained Saudi subsidy frameworks; deviation in European processor capacity or groundwater irrigation restrictions would shift volume trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Oat Protein Market
Plant Based Food
Indoor Leafy Green Precision Nutrition Program Market
Plant Based Food
Global Chaga Mushroom-Based Products Market
Plant Based Food
Global Vegan Fast Foods Market
Plant Based Food
Plant-Based Hot Dogs Market
Plant Based Food
Plant Based Collagen Market
Plant Based Food
US Plant-Based Meat Market
Plant Based Food
Kava Root Extract Market
Plant Based Food
Indonesia Plant-Based Food and Beverages Market
Plant Based Food
Plant-Based Beef Market
Plant Based Food
United States Textured Vegetable Protein Market
Plant Based Food
Plant-Based Flour Market
Plant Based Food
Meatless Meat Market
Plant Based Food
China Plant Protein Market
Plant Based Food
Plant Based Ice Cream Market
Plant Based Food
Global Isolate Organic Soy Protein Market