
 India Meat Substitutes Market | 2026-2036
India Meat Substitutes Market Size, Share, and Industry Trends Forecast 2026-2036
India Meat Substitutes Market Foresight
Asset-light contract manufacturing and co-packing arrangements is narrowing the capital barrier for new entrants in India's meat substitute sector. Beyond Meat Inc. leverages its global formulation expertise to navigate India's price-sensitive environment through localized production partnerships. Wakao Foods anchors its position in jackfruit-based whole cuts, a segment where import dependence remains minimal. GoodDot Enterprises Private Limited controls extensive rural distribution networks that sustain penetration into tier-two and tier-three cities.
Meat substitutes comprise protein-rich food products engineered to replicate the sensory and nutritional properties of conventional meat, typically achieving moisture retention above 55% and protein content ranging from 15-25% by weight depending on base material. These products serve commercial and household consumers seeking alternatives to animal-derived protein without sacrificing texture or culinary functionality. Pea protein formulations command premium positioning due to their allergen-friendly profile and neutral flavor base, while soy protein maintains volume leadership through established supply chains and cost efficiency. Wheat protein, or seitan, occupies a niche among artisanal and foodservice channels where chewier textures differentiate menu offerings.
FSSAI mandates on protein labeling and allergen disclosure are tightening compliance costs for domestic manufacturers, while BIS standards for textured vegetable protein are gradually aligning with Codex Alimentarius frameworks to facilitate export eligibility. The PLI scheme for food processing incentivizes capital investment in extrusion and high-moisture protein texturization equipment, redirecting competitive focus toward manufacturing scale rather than brand marketing alone. Stakeholders must monitor how state-level agricultural policies in Punjab and Madhya Pradesh influence pulse protein raw material availability and pricing stability.
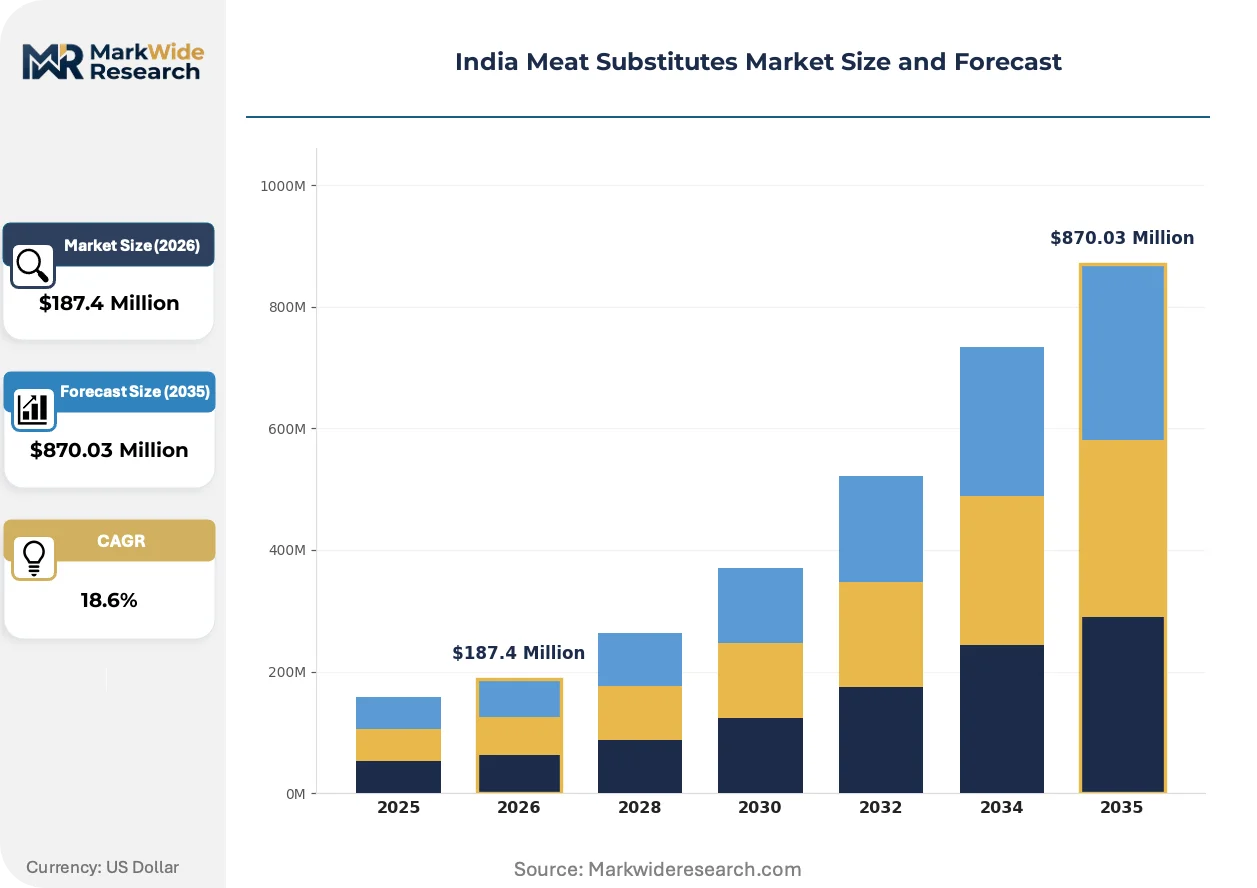
Market Dynamics
FSSAI's tightening protein labeling mandates are compressing formulation cycles across India's meat substitute sector, forcing manufacturers to rebuild recipes around verifiable nutritional claims rather than sensory mimicry alone.
Growth Catalysts
- PLI Scheme for Food Processing:Capital subsidies for extrusion and high-moisture protein texturization equipment are lowering entry barriers for domestic manufacturers seeking manufacturing scale.
- Quick-Service Restaurant Expansion:Chains in Mumbai and Delhi are accelerating plant-based menu trials, creating predictable offtake volumes for contract manufacturers.
- Pulse Protein Supply Concentration:Madhya Pradesh and Punjab's expanding mung and chickpea cultivation are stabilizing raw material costs for domestic protein isolators.
Market Restraints
- Import-Dependent Specialized Inputs:Pea protein isolate and methylcellulose binding agents remain concentrated in North American and European supplier bases, exposing margins to currency volatility.
- Price Sensitivity Ceiling:Urban Indian consumers demonstrate willingness-to-pay thresholds 40% below meat parity, constraining premium positioning for novel protein formats.
- Allergen Labeling Complexity:FSSAI's evolving soy and gluten disclosure requirements are extending product development timelines by 8-12 months for reformulated SKUs.
Strategic Opportunities
- Tier-Two City Penetration:Karnataka's secondary urban centers like Mysore and Hubli show rising trial rates for jackfruit-based whole cuts with minimal marketing spend.
- Co-Packing Network Expansion:Asset-light contract manufacturing partnerships allow brand builders to test regional flavor profiles without captive production facilities.
- Export-Grade BIS Alignment:Textured vegetable protein standards harmonizing with Codex Alimentarius frameworks are unlocking Middle Eastern and African market access for compliant manufacturers.
Industry Challenges
- Extrusion Technician Scarcity:High-moisture protein texturization requires specialized operators familiar with twin-screw parameter tuning, a skillset concentrated in Gujarat's snack food corridor.
- Refrigerated Last-Mile Gaps:Cold chain infrastructure deficits in Maharashtra's rural hinterlands limit distribution reach for chilled analog products with sub-30-day shelf lives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Meat Substitutes Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tofu, Tempeh, Seitan, Plant-Based Burger Source: Pea Protein, Soy Protein, Wheat Protein, Mushroom End User: Households, Restaurants, Cafés, Foodservice Chains Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Convenience Stores |
| Companies Covered | Beyond Meat Inc., Wakao Foods, GoodDot Enterprises Private Limited, Evo Foods, Ahimsa Food, Imagine Foods Pvt Ltd, Blue Tribe Foods, Mister Veg Foods Pvt Ltd, Vezlay Foods Pvt Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Meat Substitutes Market Shifts & Advancements
Formulation science and regulatory compliance are converging to reshape competitive advantage, with sensory performance now inseparable from verifiable nutritional architecture.
High-moisture extrusion is digitizing texture engineering in India's meat substitute sector. This technology enables precise fiber alignment through real-time screw speed and thermal gradient control. Foodservice manufacturers in Bangalore and Pune are adopting these systems to produce whole-muscle analogs with chew profiles matching poultry breast. The digitizing of texture parameters is compressing product development cycles from 18 months to under 8 months.
FSSAI's protein content claim verification protocols are tightening label integrity requirements for domestic manufacturers. The regulation mandates third-party laboratory certification for products bearing "high protein" or "protein source" descriptors. Small and mid-sized processors in Maharashtra face compliance cost burdens of 15-20% of annual R&D budgets. The sector is responding through collective testing consortiums and shared laboratory infrastructure in Mumbai's food technology clusters.
Direct-to-institutional procurement is displacing traditional distributor networks for plant-based protein ingredients. Hotel chains and corporate catering operations in Delhi-NCR are establishing annual volume contracts with manufacturers, bypassing multi-layered wholesale channels. This pattern concentrates demand planning visibility with a handful of large buyers capable of forecasting quarterly requirements. The shift is most visible in Maharashtra's hospitality sector, where procurement teams now specify moisture retention and shear force parameters in tender documents.
India Meat Substitutes Market Segmentation
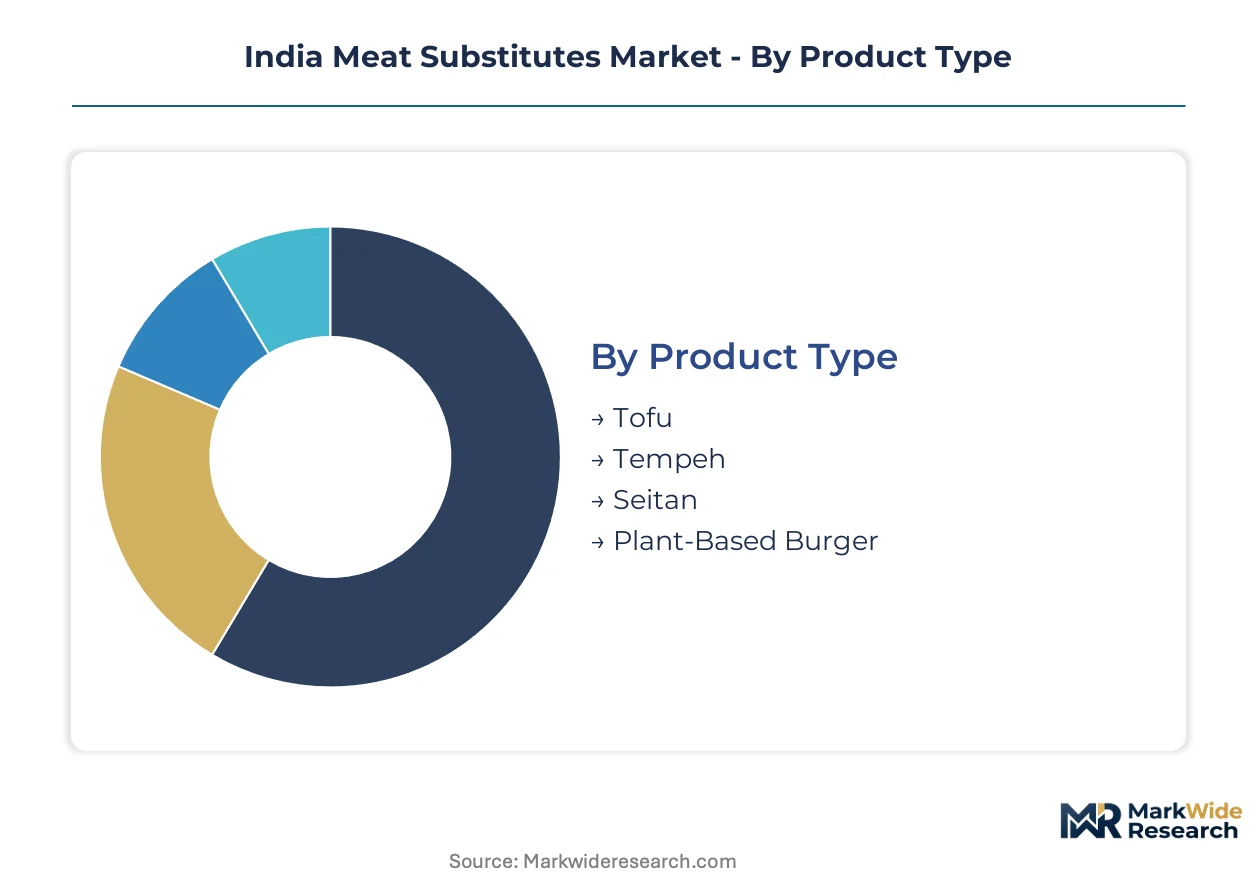
India's meat substitute market fragments across four distinct dimensions, each with divergent velocity profiles. Product type cycles reflect formulation complexity, while source material turnover tracks agricultural commodity volatility. End-user and channel dynamics reveal where trial converts to repeat purchase.
Product Type:
Tofu and tempeh turn inventory fastest due to established supply chains, while plant-based burgers require longer development cycles for FSSAI compliance.
- Plant-Based Burger:High-moisture extruded patties achieve 55-65% moisture retention with 18-22% protein content. Mumbai and Delhi quick-service restaurants specify shear force parameters in procurement tenders, compressing supplier qualification timelines.
- Tofu:Coagulated soy protein curds with neutral flavor profiles suit regional spice adaptation. Karnataka's urban households drive volume through weekly purchase patterns in modern trade formats.
- Tempeh:Fermented whole soybean cakes from Indonesian-origin starter cultures. Niche penetration concentrates in Bangalore's wellness-focused consumer segments.
- Seitan:Vital wheat gluten-based whole cuts with dense, fibrous textures. Artisanal foodservice channels in Pune and Hyderabad differentiate menus through this format.
Plant-based burger dominates installed base. Tofu is where expansion concentrates.
Source:
Cost tier stratification separates commodity inputs from premium isolates, with protein extraction technology determining margin structure.
- Soy Protein:Defatted soy flour and concentrate maintain volume leadership through Madhya Pradesh and Punjab cultivation corridors. FSSAI allergen labeling mandates extend reformulation cycles for legacy processors.
- Pea Protein:Isolates from yellow split peas command 30-40% price premiums over soy. Import dependence on North American suppliers exposes margins to rupee volatility.
- Wheat Protein:Vital gluten from domestic wheat processing supports cost-competitive seitan production. Maharashtra's milling infrastructure provides captive supply.
- Mushroom:Mycelium-based whole cuts from controlled-environment cultivation. Limited domestic capacity constrains scaling beyond premium positioning.
Soy protein anchors volume share. Pea protein is climbing the fastest.
End User:
Application intensity varies by preparation complexity and procurement centralization.
- Foodservice Chains:Centralized procurement with annual volume contracts and specified texture parameters. Delhi-NCR hotel chains bypass distributor networks through direct manufacturer relationships.
- Restaurants:Independent operators trial jackfruit-based whole cuts with minimal marketing support. Tier-two Karnataka cities like Mysore show rising adoption.
- Households:Urban Maharashtra and Karnataka consumers demonstrate highest trial rates for refrigerated analog products with sub-30-day shelf lives.
- Cafés:Limited-service formats favor ambient-stable formats with extended distribution reach. Cold chain gaps in rural hinterlands constrain penetration.
Foodservice chains dominate installed base. Restaurants are gaining share fastest.
Distribution Channel:
Customer type and purchase occasion determine channel throughput velocity.
- Supermarkets:Modern trade formats in Mumbai and Delhi stock refrigerated and frozen sections with 45-60 day inventory turns. FSSAI protein claim verification drives shelf-space negotiation.
- Online Retail:Direct-to-consumer platforms aggregate niche formats with limited retail distribution. Bangalore and Pune logistics clusters enable next-day chilled delivery.
- Specialty Stores:Health-focused retailers in urban Maharashtra curate premium pea protein formulations. Higher service levels justify elevated price positioning.
- Convenience Stores:Ambient-stable formats with extended shelf lives penetrate tier-three cities. GoodDot Enterprises leverages rural distribution networks for this channel.
Supermarkets dominate installed base. Online retail is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's meat substitute sector maintains a net import position for specialized protein isolates and binding agents, while domestic cultivation of soy, mung, and chickpea provides raw material surplus for regional processors. Export potential concentrates in textured vegetable protein formats aligned with Middle Eastern and African market specifications.
Maharashtra
Mumbai's quick-service restaurant chains drive procurement centralization with specified shear force parameters in annual volume contracts. FSSAI protein labeling mandates extend product development timelines for processors based in Pune and Nashik. The Mumbai-Pune food technology corridor hosts shared laboratory infrastructure reducing compliance cost burdens for mid-sized manufacturers.
Karnataka
Bangalore's wellness-focused consumer segments sustain niche demand for tempeh and fermented formats with weekly purchase patterns in modern trade. The state's expanding mung cultivation in Mandya district stabilizes raw material costs for domestic protein isolators. Mysore and Hubli secondary urban centers show rising trial rates for jackfruit-based whole cuts with minimal marketing expenditure.
Delhi-NCR
Hotel chains and corporate catering operations in Delhi-NCR establish direct manufacturer relationships bypassing traditional distributor networks. BIS standards alignment with Codex Alimentarius frameworks facilitates export-grade production from Noida and Gurugram facilities. The region's procurement teams specify moisture retention parameters in tender documents for plant-based protein ingredients.
Punjab
Expanding chickpea cultivation corridors sustain soy protein concentrate supply for legacy processors with established defatted flour operations. State agricultural policies influence pulse protein raw material availability and pricing stability for domestic manufacturers. Ludhiana's milling infrastructure provides captive wheat gluten supply for cost-competitive seitan production.
Gujarat
High-moisture protein texturization equipment operators concentrate in Gujarat's snack food corridor, creating skilled technician scarcity for competing regions. The PLI scheme for food processing redirects capital investment toward extrusion manufacturing scale rather than brand marketing alone. Surat and Ahmedabad host contract manufacturing partnerships enabling asset-light market entry for new brand builders.
India Meat Substitutes Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: global formulation specialists leveraging localized production partnerships, domestic whole-cut specialists anchored in indigenous raw materials, and rural distribution integrators penetrating tier-two and tier-three cities. Competitive positioning depends on manufacturing scale attainment, regulatory compliance infrastructure, and cold chain reach rather than brand marketing expenditure alone. Dominant competitive moves include co-packing network expansion for regional flavor testing and PLI scheme utilization for extrusion equipment acquisition.
Among global-origin specialists, Beyond Meat Inc. occupies a position representing international formulation expertise adapted to price-sensitive environments through partnership-based production. Wakao Foods exemplifies the indigenous whole-cut archetype with jackfruit-based formats minimizing import dependence. GoodDot Enterprises Private Limited anchors the rural distribution tier with network infrastructure sustaining penetration beyond metropolitan centers. These three represent distinct strategic vectors: global technology adaptation, domestic raw material leverage, and geographic reach expansion.
| Leading Market Players |
|---|
| Beyond Meat Inc. |
| Wakao Foods |
| GoodDot Enterprises Private Limited |
| Evo Foods |
| Ahimsa Food |
| Imagine Foods Pvt Ltd |
| Blue Tribe Foods |
| Mister Veg Foods Pvt Ltd |
| Vezlay Foods Pvt Ltd |
| Others |
Supply & Pricing Matrix
Undercapacity in Gujarat's high-moisture extrusion technician pool tightens labor premiums while compressing equipment utilization rates for competing regions, forcing manufacturers to absorb cost escalation or defer capacity expansion timelines. This utilization squeeze cascades into pricing postures across soy protein concentrate and pea protein isolate tiers, with contract manufacturers passing through skilled labor scarcity while ingredient buyers negotiate volume commitments against currency volatility.
Pricing Analysis
Foodservice chains anchor pricing structures through annual volume contracts with specified shear force and moisture retention parameters. Three-tier pricing separates premium pea protein isolates from standard soy concentrates and economy-grade wheat gluten formats, with certification under FSSAI's evolving protein claim protocols driving tier placement. Pricing pressure stems from urban consumer willingness-to-pay thresholds sitting below meat parity, forcing cost compression in mid-tier formulations. Quick-service restaurants in Mumbai and Delhi demonstrate highest price sensitivity, while specialty retailers in urban Maharashtra absorb premiums for allergen-friendly positioning.
Supply Chain Analysis
Import exposure between North American suppliers and Indian manufacturers dominates supply chain risk profiles, with pea protein isolate and methylcellulose binding agents concentrated in Canadian and U.S. processing facilities. Raw material sourcing draws from Madhya Pradesh and Punjab for domestic soy and mung cultivation, while wheat gluten feeds from Maharashtra's milling infrastructure. Single-source vulnerability in specialized extrusion equipment creates procurement bottlenecks for high-moisture texturization capacity. Distribution runs through modern trade supermarkets in Mumbai and Delhi, with direct-to-institutional procurement displacing traditional wholesale channels for foodservice volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's meat substitute sector operates as a substitution defense against conventional animal protein incumbents, with dairy and poultry price volatility threatening to erode alt-protein value propositions if feed grain costs normalize. Manufacturers must navigate this competitive pressure while building manufacturing scale before import-dependent input costs destabilize margin structures.
For Market Incumbents:Pre-empt margin erosion by securing captive supply through backward integration into Madhya Pradesh pulse protein processing, insulating against rupee volatility on North American isolate imports. Invest in FSSAI-compliant shared laboratory infrastructure to compress reformulation timelines and defend positioning against emerging contract manufacturers leveraging PLI scheme subsidies for extrusion equipment acquisition.
For New Entrants and Emerging Players:Establish a beachhead in Karnataka's tier-two urban centers like Mysore and Hubli, where jackfruit-based whole cuts demonstrate rising trial rates with minimal marketing expenditure. Target co-packing partnerships with Gujarat's snack food corridor facilities to test regional flavor profiles without captive production investment, then scale through direct procurement relationships with Delhi-NCR hotel chains specifying texture parameters in tender documentation.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting downward across contract manufacturing sub-segments as PLI scheme subsidies redirect competitive focus toward equipment scale rather than brand marketing spend. Acquire asset-light brand builders with proven regional flavor traction and established co-packing networks, avoiding pure manufacturing plays exposed to technician scarcity. Watch FSSAI protein labeling mandate enforcement timelines as the signal indicating compliance cost inflection for mid-sized processors.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Moisture Extrusion Capacity Expansion | PLI scheme subsidies lower capital barriers for domestic texturization equipment in Gujarat facilities. |
| Backward Integration into Pulse Processing | Madhya Pradesh cultivation corridors provide captive soy and mung isolate supply reducing import exposure. |
| FSSAI Compliance Infrastructure Sharing | Mumbai-Pune food technology clusters reduce third-party certification burdens for mid-sized manufacturers. |
| Direct-to-Institutional Procurement Relationships | Delhi-NCR hotel chains bypass distributor networks with annual volume contracts specifying shear force parameters. |
| Regional Flavor Profile Development | Co-packing partnerships enable asset-light testing of Karnataka and Maharashtra taste adaptations without captive facilities. |
Research Methodology
Initial hypotheses were tested against primary input from plant-based protein formulators, FSSAI regulatory affairs specialists, quick-service restaurant procurement managers, and contract manufacturing operators, then refined through secondary validation against FSSAI notification records, BIS standards documentation, PLI scheme disbursement disclosures, and customs trade data on pea protein isolate imports. Bottom-up volume estimates from state-level cultivation statistics and top-down demand projections from foodservice chain expansion plans were triangulated to constrain forecast variance.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by formulation complexity, source material tier by protein extraction technology, end-user intensity by procurement centralization, and channel velocity by cold chain requirements. CAGRs were derived from installed base penetration rates and trial-to-repeat conversion patterns in urban Maharashtra and Karnataka households. Industry-specific inputs included FSSAI compliance timeline assumptions and PLI scheme equipment subsidy uptake trajectories.
Sensitivities concentrate around FSSAI protein labeling mandate enforcement intensity, rupee-dollar volatility on North American isolate imports, and state-level agricultural policy shifts in Punjab and Madhya Pradesh affecting pulse cultivation economics. Forecasts embed assumptions on technician training pipeline expansion and cold chain infrastructure buildout in Maharashtra's rural hinterlands. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Hemp-Based Food Market
Plant Based Food
United States Meat Substitutes Market
Plant Based Food
Europe Plant-Based Food Market
Plant Based Food
Organic Rice Protein Market
Plant Based Food
Europe Pea Protein Market
Plant Based Food
Global Chaga Mushroom-Based Products Market
Plant Based Food
Vegan Gelatin Market
Plant Based Food
Plant-Based Vegan Eggs Market
Plant Based Food
North America Plant-Based Egg Market
Plant Based Food
Dandelion Root Extract Market
Plant Based Food
Africa Pea Protein Market
Plant Based Food
Canada Plant Protein Market
Plant Based Food
Europe Tofu Market
Plant Based Food
Tempeh Market
Plant Based Food
North America Textured Vegetable Protein Market
Plant Based Food
New Jersey Vegan Products Market