
 Low-Calorie Jelly Market | 2026-2036
Low-Calorie Jelly Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Calorie Jelly Market Foresight
Supermarket private-label consolidation is rebalancing procurement power toward large retail chains across North America and Western Europe. Jell-O leverages its brand heritage and shelf-space agreements to sustain volume leadership in powdered formats. Hartley's competes through flavored innovations targeting British health-conscious consumers. Gelita anchors the upstream supply chain with specialized collagen and plant-based gelling agent production.
Low-calorie jelly denotes a reduced-energy gelatin or pectin-based dessert typically containing fewer than 40 calories per 100-gram serving, manufactured through controlled hydrolysis of animal or plant-derived hydrocolloids with artificial or natural non-nutritive sweeteners. The product serves commercial and retail markets as a portion-controlled indulgence aligned with weight-management and glycemic-control dietary protocols. Sugar-free jelly leads volume contribution due to established diabetic and ketogenic consumer bases, while vegan jelly represents the fastest-expanding category as carrageenan and agar-agar formulations displace traditional porcine and bovine gelatin. Ready-to-serve cups capture the dominant margin pool through convenience premiums, whereas powdered mixes occupy the value-tier channel anchored by price-sensitive household preparation.
EFSA additive safety evaluations and FDA GRAS determinations for non-nutritive sweeteners shape permissible formulation palettes and cross-border product registration requirements. REACH compliance in Europe and evolving USDA organic certification pathways further constrain ingredient sourcing and label claim substantiation. Stakeholders must monitor regulatory divergence between jurisdictions to preempt reformulation costs and secure shelf placement in premium distribution channels.
Market Dynamics
Clean-label formulation mandates from EFSA and FDA are forcing manufacturers to reformulate artificial additive portfolios while maintaining sensory parity with legacy products.
Growth Catalysts
- Diabetic dietary protocols:Medical nutrition guidelines in Germany and Japan now explicitly recommend sugar-free gelatin desserts for glycemic control, expanding reimbursed purchase channels.
- REACH additive transparency:European chemical disclosure requirements are accelerating consumer trust in certified clean-label formulations, reducing purchase hesitation among health-conscious households.
- Ketogenic diet adoption:Carbohydrate-restricted eating patterns across United States metropolitan clusters are normalizing low-calorie jelly as a permissible indulgence, sustaining repeat purchase velocity.
Market Restraints
- Porcine gelatin supply concentration:Bovine and porcine collagen hydrolysis capacity clusters in Brazil and Argentina, exposing formulations to livestock disease quarantine disruptions and price volatility.
- Carrageenan regulatory friction:EFSA's ongoing re-evaluation of refined carrageenan safety is creating formulation uncertainty for vegan product lines awaiting definitive classification.
- Stevia aftertaste limitation:Reb-A sweetener formulations retain licorice off-notes at functional concentrations, constraining clean-label sugar-free variants from achieving full sensory parity.
Strategic Opportunities
- India functional snacking penetration:Urban middle-class households in Mumbai and Bangalore demonstrate nascent demand for portion-controlled desserts, with domestic hydrocolloid production reducing import dependency.
- Direct-to-subscription channel innovation:Customizable flavor rotation services bypass retail slotting fees while capturing consumer preference data for accelerated NPD cycles.
- EU Green Deal packaging mandates:Biodegradable cup and film requirements are creating first-mover advantage for manufacturers with integrated sustainable packaging capabilities.
Industry Challenges
- Food technologist talent scarcity:Formulation expertise spanning hydrocolloid rheology and natural sweetener synergy remains concentrated among senior specialists approaching retirement.
- Organic certification timeline compression:USDA and EU organic equivalence negotiations are delaying cross-border label claim deployment, forcing parallel certification investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Calorie Jelly Market |
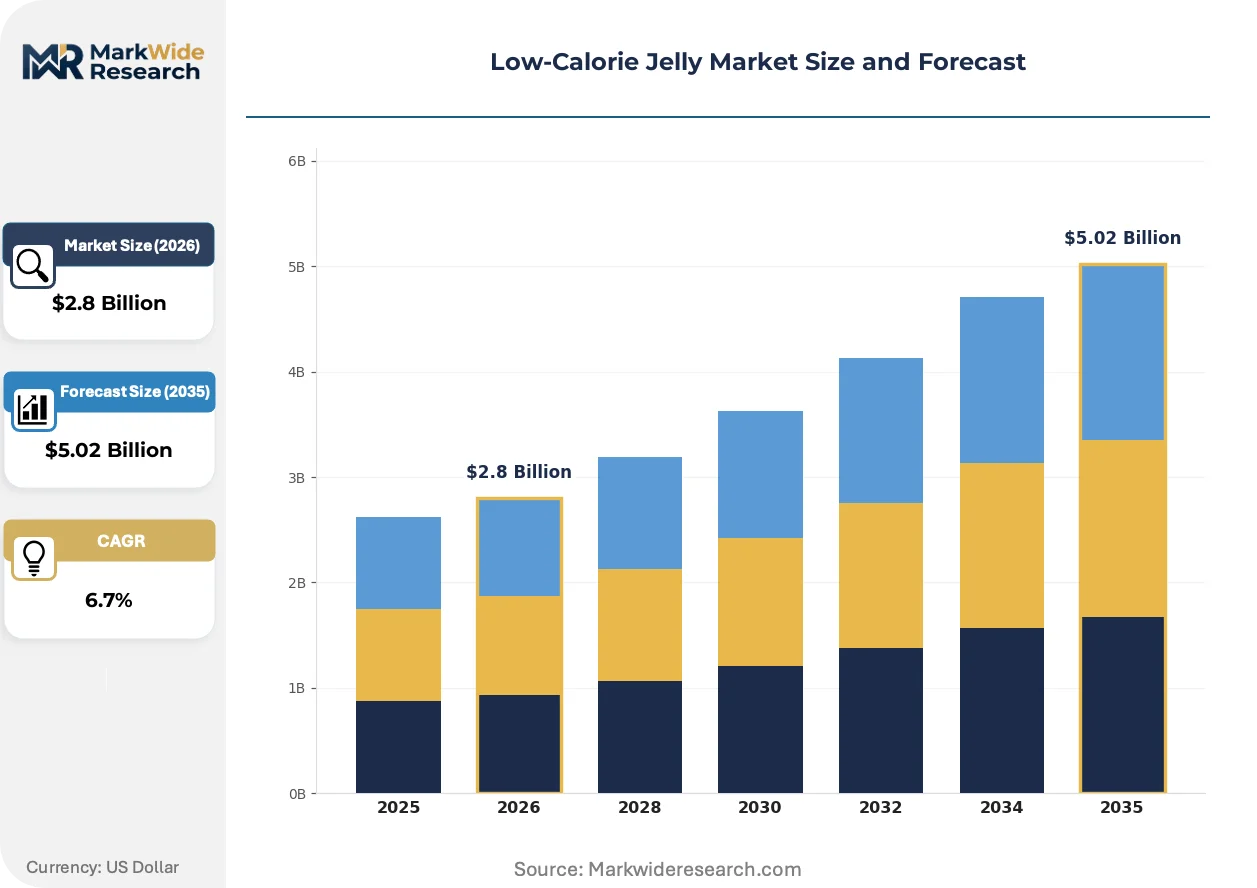
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit Jelly, Sugar-Free Jelly, Gelatin Dessert, Vegan Jelly End User: Health-Conscious Consumers, Athletes, Weight Watchers, Kids Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Convenience Stores Form: Powdered, Ready-to-Serve, Concentrate, Liquid |
| Companies Covered | Jell-O, Knox, Royal, Hartley's, Dole, Dr. Oetker, Panna, Sundia, Gelita, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Calorie Jelly Market Shifts & Advancements
Plant-derived hydrocolloid engineering and sweetener biotechnology are converging to reshape formulation possibilities while regulatory disclosure requirements intensify competitive pressure on ingredient transparency.
Agar-agar and konjac glucomannan blends are overtaking traditional gelatin in premium vegan product lines. German and Japanese manufacturers are adopting these systems at accelerated pilot scales. The shift is compressing margin structures for legacy animal-derived supply chains while enabling entirely new texture profiles previously unattainable with single-hydrocolloid systems.
EFSA's 2023 updated guidance on non-nutritive sweetener acceptable daily intakes is tightening maximum concentration thresholds for aspartame and acesulfame-K in children's food categories. Industrial consequence includes mandatory reformulation of family-oriented product portfolios. Ready-to-serve cup formats targeting pediatric consumption in France and Italy are responding with accelerated monk fruit and allulose substitution programs.
Retail buyer consolidation is compressing supplier negotiation timelines and unbundling historical service provisions. Supermarket private-label directors in the United States and United Kingdom now demand dedicated R&D collaboration and exclusive flavor development. The disintermediation of traditional broker networks is most visible in Walmart and Tesco direct-procurement programs, where approved vendor lists have contracted by half over eighteen months.
Low-Calorie Jelly Market Segmentation
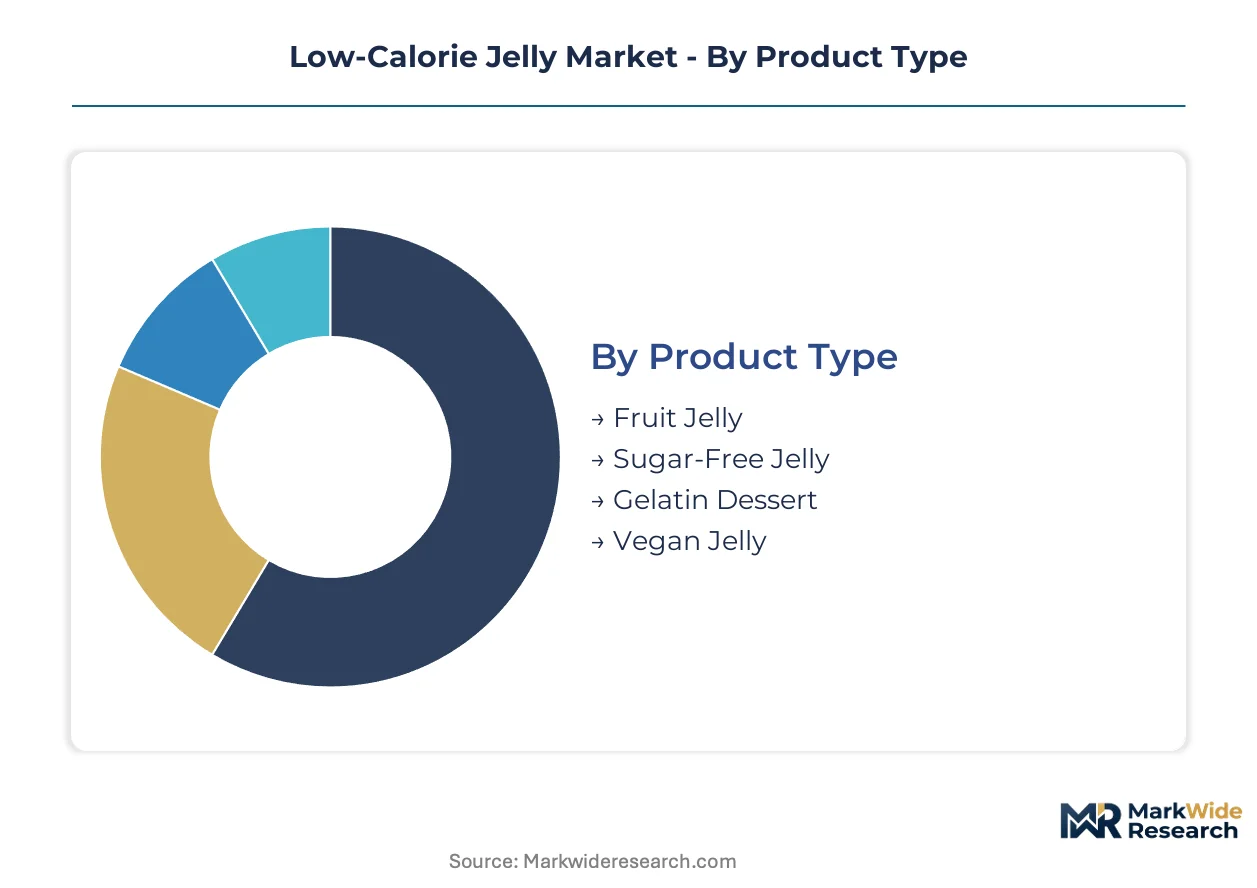
Segmentation in low-calorie jelly reveals divergent capital requirements and margin architectures across formulation technologies, distribution infrastructures, and consumer psychographics. Manufacturers must align production investments with the specific compliance burdens and shelf-life demands of each segment cluster.
Product Type:
Capital intensity peaks in vegan jelly manufacturing, where multi-hydrocolloid processing lines and clean-label certification infrastructure demand substantial upfront outlay.
- Sugar-Free Jelly:Formulations rely on aspartame, sucralose, or stevia Reb-A combined with gelatin or pectin bases to achieve sub-40 calorie per 100g targets. Demand concentrates in Germany and Japan where diabetic dietary protocols and ketogenic consumer bases sustain reimbursed and direct-purchase channels. EFSA and FDA GRAS determinations for non-nutritive sweeteners impose ongoing reformulation costs as acceptable daily intake thresholds tighten.
- Vegan Jelly:Carrageenan, agar-agar, and konjac glucomannan systems displace animal-derived hydrocolloids, requiring specialized hydration and gelling temperature controls. German and Japanese manufacturers are scaling pilot production fastest, though EFSA's pending refined carrageenan re-evaluation injects regulatory uncertainty into capacity planning.
- Fruit Jelly:Reduced-calorie variants using fruit juice concentrates and natural flavor systems occupy mid-tier retail positioning.
- Gelatin Dessert:Traditional porcine and bovine collagen formulations retain volume leadership in North American household preparation segments.
Sugar-free jelly absorbs the bulk of installed capacity; vegan jelly is expanding most quickly.
End User:
Application-specific formulation requirements create distinct R&D investment profiles, with medical nutrition protocols demanding the most rigorous clinical substantiation.
- Weight Watchers:Portion-controlled single-serve formats with precise calorie disclosure dominate this segment. United States metropolitan clusters show concentrated repeat purchase velocity as carbohydrate-restricted eating patterns normalize low-calorie jelly as permissible indulgence.
- Health-Conscious Consumers:Clean-label demands drive monk fruit and allulose substitution programs, particularly in pediatric-oriented product lines facing EFSA's tightened children's category sweetener thresholds.
- Athletes:Protein-fortified and electrolyte-enhanced variants target post-workout glycogen replenishment protocols.
- Kids:Colorant-free and allergen-excluded formulations face the most stringent additive safety evaluations.
Weight watchers command the deepest SKU proliferation; health-conscious consumers are driving the steepest premiumization trajectory.
Distribution Channel:
Channel selection dictates working capital intensity, with direct-to-retail programs requiring the most substantial trade financing and slotting fee commitments.
- Supermarkets:Private-label consolidation in the United States and United Kingdom has halved approved vendor lists over eighteen months, concentrating procurement power among Walmart and Tesco direct-procurement programs. Exclusive flavor development and dedicated R&D collaboration are now mandatory for shelf placement.
- Online Retail:Subscription-based customizable flavor rotation services bypass traditional slotting fees while capturing granular consumer preference data to accelerate new product development cycles.
- Health Food Stores:Certified organic and non-GMO variants command specialty retail premiums.
- Convenience Stores:Single-serve ready-to-eat cups target impulse purchase occasions with compressed margin structures.
Supermarkets retain the dominant volume position; online retail is climbing the fastest.
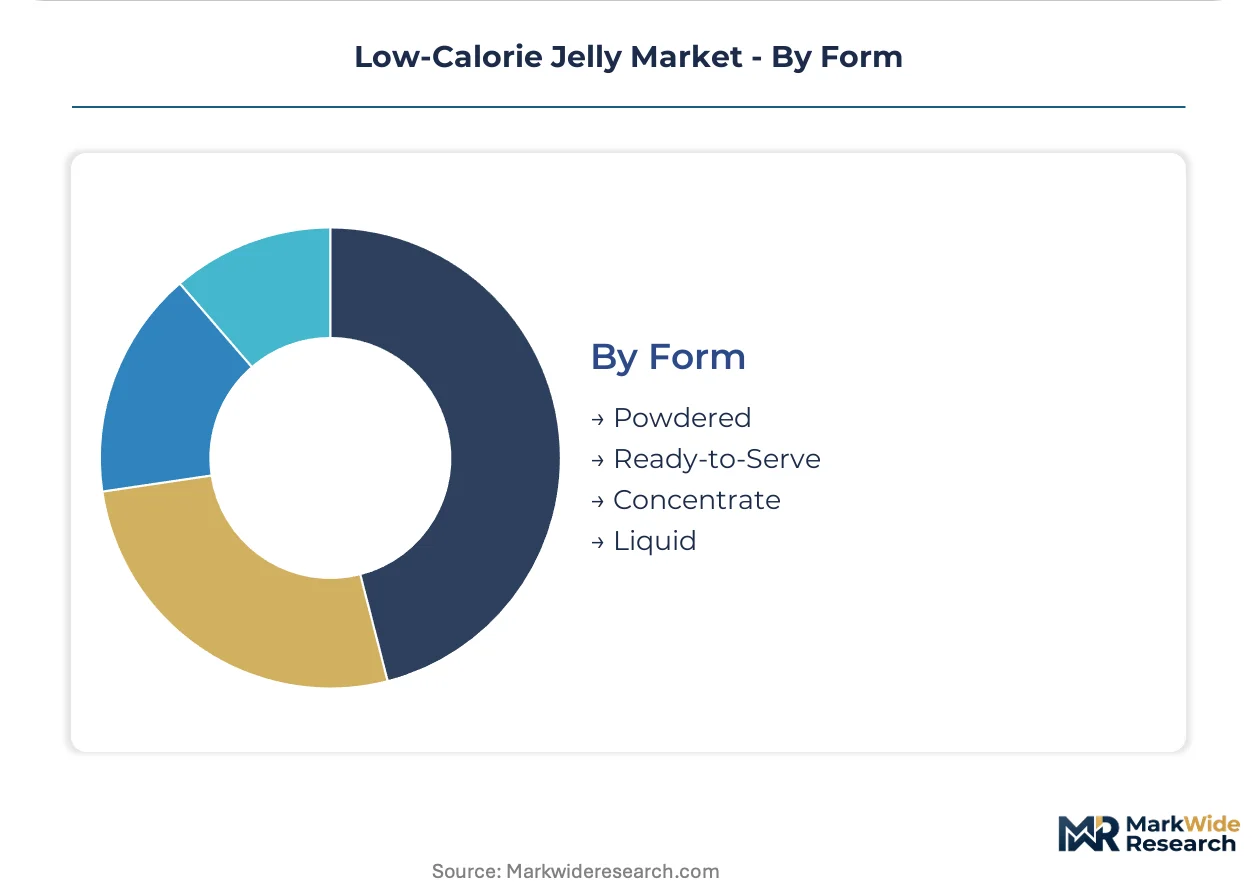
Form:
Processing technology differentiation separates capital-light blending operations from capital-intensive aseptic filling and extended shelf-life systems.
- Ready-to-Serve:Aseptically filled cups and pouches with multi-month ambient stability require retort or HPP infrastructure. This format captures the dominant margin pool through convenience premiums in Germany, Japan, and the United States where functional snacking habits are most entrenched.
- Powdered:Dry-blend sachets and canisters occupy the value-tier channel, anchored by price-sensitive household preparation. Jell-O sustains volume leadership through brand heritage and shelf-space agreements.
- Concentrate:Dilution-required formats reduce shipping weights for foodservice applications.
- Liquid:Refrigerated short-shelf-life variants target fresh perimeter placement in premium supermarket formats.
Ready-to-serve holds the widest installed base; powdered maintains the deepest geographic penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for low-calorie jelly concentrates in Germany, Japan, and the United States where functional snacking habits and diabetic dietary protocols are most entrenched. These three markets collectively absorb the dominant share of sugar-free and vegan product volumes. Each geography presents distinct regulatory hurdles and channel dynamics that shape localized competitive positioning.
United States
Ketogenic diet adoption across metropolitan clusters in California, Texas, and New York Metro sustains repeat purchase velocity for carbohydrate-restricted desserts. FDA GRAS determinations for non-nutritive sweeteners impose ongoing reformulation costs as acceptable daily intake thresholds tighten. Walmart's direct-procurement program in Bentonville, Arkansas has halved approved vendor lists over eighteen months, concentrating shelf-space negotiations among surviving suppliers.
Germany
Medical nutrition guidelines now explicitly recommend sugar-free gelatin desserts for glycemic control, expanding reimbursed purchase channels through statutory health insurance. EFSA additive safety evaluations and REACH compliance requirements accelerate consumer trust in certified clean-label formulations. Manufacturers in Bavaria and North Rhine-Westphalia are scaling pilot production of agar-agar and konjac glucomannan systems fastest among European peers.
Japan
Health-conscious consumers in Tokyo, Osaka, and Nagoya drive premiumization toward portion-controlled single-serve formats with precise calorie disclosure. METI standards for functional food claims constrain label substantiation requirements for products targeting weight-management protocols. Domestic hydrocolloid engineering capabilities in the Kanto region enable rapid iteration on plant-derived gelling agent blends.
United Kingdom
Tesco's private-label consolidation has rebalanced procurement power toward large retail chains, demanding dedicated R&D collaboration and exclusive flavor development. EFSA clean-label mandates align with British consumer preference for additive transparency in pediatric-oriented product lines. Hartley's competes through flavored innovations targeting health-conscious households in Greater London and the Southeast.
India
Urban middle-class households in Mumbai and Bangalore demonstrate nascent demand for portion-controlled desserts as functional snacking habits penetrate Western-influenced consumption patterns. FSSAI labeling requirements for non-nutritive sweeteners create compliance benchmarks for imported and domestic formulations alike. Domestic hydrocolloid production in Maharashtra and Gujarat reduces import dependency for carrageenan and pectin supply chains.
Low-Calorie Jelly Market Competitive Landscape
United States producers anchor one tier; German and British specialists hold differentiated positions in clean-label and heritage-brand segments. The vendor base spans multinational packaged-food conglomerates with powdered-format dominance, regional private-label contractors serving supermarket chains, and upstream hydrocolloid suppliers controlling specialized gelling agent production. Three archetypes define competitive positioning: brand-heritage incumbents leveraging shelf-space agreements, private-label manufacturers absorbing direct-procurement consolidation pressure, and ingredient-technology specialists supplying multi-hydrocolloid systems. Capacity expansion and exclusive flavor development partnerships represent the dominant competitive moves as retail buyer consolidation compresses supplier negotiation timelines.
Within the brand-heritage tier, Jell-O and Hartley's exemplify divergent geographic anchoring and format specialization. Jell-O occupies a position tied to powdered-mix volume leadership and household preparation segments across North American retail channels. Hartley's sits within the British market's premium-positioned flavored innovation vector. Gelita anchors the upstream supply chain archetype as a specialized collagen and plant-based gelling agent producer serving downstream formulation requirements. These three companies represent the spectrum from consumer-facing packaged goods to captive ingredient supply, illustrating how competitive advantage distributes across vertical positions in the low-calorie jelly value chain.
| Leading Market Players |
|---|
| Jell-O |
| Knox |
| Royal |
| Hartley's |
| Dole |
| Dr. Oetker |
| Panna |
| Sundia |
| Gelita |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up retail chains in North America and Western Europe now dictate procurement terms, compressing supplier margins while consolidating shelf-space negotiations into fewer hands. This ownership concentration tightens pricing discipline across both branded and private-label tiers, forcing manufacturers to absorb input volatility or sacrifice volume placement.
Pricing Analysis
Volume leadership sits with powdered-mix formats anchored by Jell-O's heritage positioning, while ready-to-serve cups capture margin premiums through convenience positioning. Pricing stratifies across premium clean-label vegan variants, standard sugar-free formulations, and economy-tier gelatin desserts differentiated by sweetener certification grade and hydrocolloid sourcing. Cost compression in standard tiers intensifies as Walmart and Tesco direct-procurement programs consolidate approved vendor lists. Price-sensitive household preparation segments in the United States resist premium migration, whereas German and Japanese health-conscious consumers accept clean-label premiums.
Supply Chain Analysis
Porcine and bovine collagen hydrolysis capacity clusters in Brazil and Argentina, tethering traditional gelatin supply to livestock disease quarantine exposure and feedstock price cycles. Carrageenan extraction draws from Philippine and Indonesian seaweed farming, while agar-agar production centers on Japanese and South Korean coastal processing. Single-source vulnerability in refined carrageenan supply chains intensifies as EFSA's pending safety re-evaluation constrains alternative formulation pathways. Distribution runs through supermarket direct-procurement programs and specialized hydrocolloid distributors serving industrial formulation customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EFSA's additive safety evaluations and FDA GRAS determinations erect regulatory moats favoring incumbents with dedicated certification infrastructure and reformulation capital.
For Market Incumbents: Anchor shelf-space dominance through exclusive flavor development partnerships with Walmart and Tesco procurement programs. Invest in backward integration into plant-based hydrocolloid production to offset porcine gelatin supply volatility from Brazilian and Argentinean livestock markets. Accelerate monk fruit and allulose substitution pipelines ahead of EFSA's tightened children's category sweetener thresholds. For New Entrants and Emerging Players: Capture white-space opportunity in India's urban middle-class households across Mumbai and Bangalore where functional snacking habits are nascent and domestic hydrocolloid production reduces import dependency. Target direct-to-subscription channel innovation with customizable flavor rotation services that bypass retail slotting fees while harvesting consumer preference data for accelerated NPD cycles. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap private-label manufacturers with established clean-label certification infrastructure in Germany and Bavaria-facing production clusters. Long-term viability hinges on five-to-ten year positioning around plant-derived hydrocolloid engineering capabilities as vegan formats displace animal-derived gelatin. Watch EFSA's refined carrageenan classification as the decisive inflection signal for vegan product line valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Certification Investment | EFSA and FDA compliance moats protect premium positioning against uncertified competitors. |
| Plant-Based Hydrocolloid Backward Integration | Captive agar-agar and konjac supply reduces exposure to Brazilian livestock disease cycles. |
| Direct-to-Subscription Channel Launch | Bypasses Walmart and Tesco slotting fees while capturing granular preference data. |
| Exclusive Retail Partnership Development | Secures shelf placement as approved vendor lists contract under procurement consolidation. |
| Sustainable Packaging Transition | EU Green Deal biodegradable mandates create first-mover advantage in German markets. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with hydrocolloid procurement managers, supermarket category buyers, food technology R&D directors, and regulatory affairs specialists at formulation houses. EFSA additive safety guidance, FDA GRAS determination databases, and REACH compliance registries provided cross-jurisdictional validation. Bottom-up segment sizing triangulated against top-down market aggregation across product type, end user, distribution channel, and form dimensions.
Data-stream reconciliation combined shipment volume tracking from customs authorities with retail audit data from Nielsen and Circana, calibrating sell-through velocity against production capacity disclosures. Segmentation modeling spanned formulation technology, consumer psychographic, and distribution infrastructure dimensions across the projection horizon. CAGRs derived from regression analysis of historical volume trajectories, adjusted for regulatory inflection points and channel consolidation patterns. Industry-specific inputs included hydrocolloid price indices and supermarket private-label penetration rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA carrageenan re-evaluation timing and livestock disease quarantine disruptions in South American collagen supply. Assumptions reflect current regulatory trajectories and procurement consolidation patterns. A small set of named triggers—EFSA additive classification, USDA-EU organic equivalence negotiations, and Indian FSSAI enforcement intensity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Liquorice Shellac Market
Confectionery
Europe Premium Chocolate Market
Confectionery
Diet Candy Market
Confectionery
Asia Pacific and Latin America Sugar Confectionery Market
Confectionery
Global Sugar Free Chewing Gums Market
Confectionery
Ruby Chocolate Market
Confectionery
Low Calorie Keto Desserts Market
Confectionery
Vegan Candies Market
Confectionery
White Chocolate Market
Confectionery
Confectionery Fillings Market
Confectionery
Japan Chocolate Market
Confectionery
Pralines Market
Confectionery
South Africa Confectionery Market
Confectionery
Low Calorie Hard Candy Market
Confectionery
Sugar Free White Chocolate Market
Confectionery
Middle East and Africa Chocolate Market