
 Vegan Cosmetics Market | 2026-2036
Vegan Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Cosmetics Market Intelligence
The direct-to-consumer e-commerce channel is tilting the competitive landscape away from traditional department store distribution. This shift benefits digitally native brands like Milk Makeup, which leverages social media for customer acquisition. In response, established giants such as L'Oreal SA extend their online presence and acquire smaller vegan-focused lines. Meanwhile, e.l.f. Beauty, Inc. differentiates with an accessible price point and widespread availability in mass-market retail.
Vegan cosmetics are beauty and personal care products formulated entirely without animal-derived ingredients or by-products, such as beeswax, carmine, or lanolin. Their core purpose is to provide consumers with ethical alternatives that align with cruelty-free principles. The skincare product type continues to command the largest share, driven by demand for facial care and anti-aging solutions. However, the makeup category, including products for lip care, is showing significant momentum among younger consumer demographics.
Product formulation and market access are heavily influenced by regulations like the EU's comprehensive ban on animal testing and the US FDA's requirements for ingredient labeling. In parallel, evolving NMPA rules in China regarding pre-market testing create new opportunities and compliance hurdles for brands. Authenticating the entire supply chain to verify vegan claims remains the central challenge for brand credibility and consumer trust.
Market Dynamics
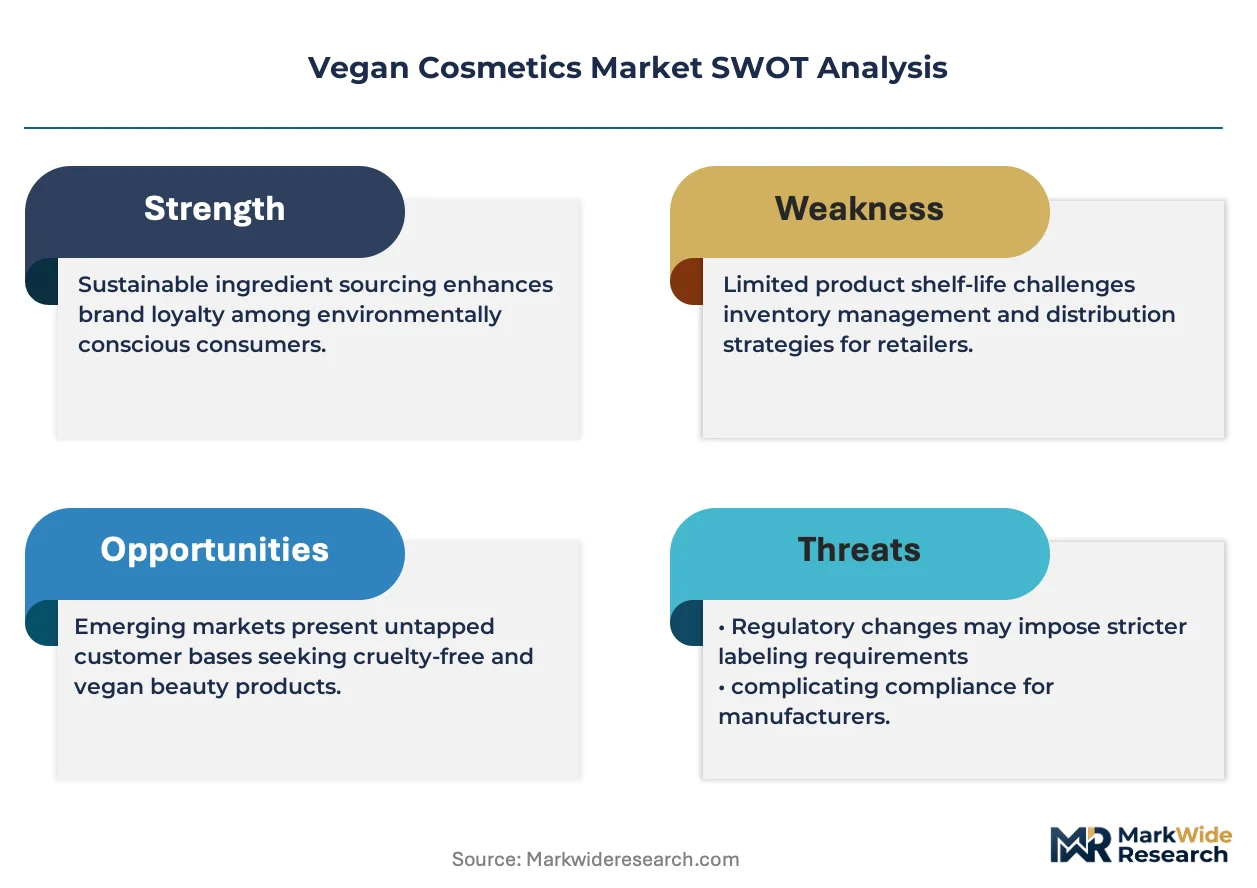
The vegan cosmetics market's primary dynamic is the structural tension between rising consumer demand for ethical transparency and the operational complexity of authenticating global supply chains. This friction forces brands to invest heavily in verification processes to substantiate marketing claims, shaping everything from ingredient sourcing to final product pricing.
Growth Catalysts
- Regulatory Benchmarks:The European Union's comprehensive ban on animal testing for cosmetics serves as a global standard, compelling brands worldwide to reformulate products to access this key market and meet consumer expectations for cruelty-free claims.
- Demographic Shifts:Younger consumer cohorts, particularly in North America and Europe, demonstrate a strong preference for products aligned with ethical and environmental values, driving significant momentum in discretionary categories like color cosmetics and lip care.
- E-commerce Accessibility:The expansion of direct-to-consumer and third-party online retail platforms dramatically increases product availability, allowing niche and emerging vegan brands to reach a global customer base without the need for traditional retail partnerships.
Market Restraints
- Ingredient Cost and Viability:High-performance vegan alternatives to conventional ingredients like animal-derived collagen, carmine, or lanolin often carry a significant cost premium and can present formulation challenges in achieving comparable texture and efficacy.
- Supply Chain Opacity:Verifying that every ingredient, from raw material to final formulation, is free from animal-derived substances is complex and costly, creating a substantial barrier to entry and a continuous risk to brand credibility.
- Performance Perception Gap:A lingering consumer perception in certain segments holds that vegan formulations, particularly in anti-aging skincare and long-wear makeup, may not offer the same level of performance as their traditional counterparts, slowing adoption.
Strategic Opportunities
- Biotechnology in Ingredient Sourcing:Advances in fermentation and cell culture create opportunities to develop novel, lab-grown ingredients like vegan collagen or squalane, offering high purity, stable supply chains, and strong ethical marketing narratives.
- Geographic Expansion in Asia:Evolving regulations in markets like China, which are relaxing mandatory animal testing requirements, create significant entry opportunities for established vegan brands to tap into a large and increasingly conscious consumer base.
- "Vegan Plus" Formulations:There is a clear opportunity to combine vegan claims with other in-demand attributes such as "clean," organic, or sustainable packaging, creating products that appeal to a broader spectrum of ethically-minded consumers.
Industry Challenges
- Navigating Certification Fragmentation:Brands face the challenge of managing multiple different vegan and cruelty-free certification standards across various regions, each with its own costs, criteria, and levels of consumer recognition, adding administrative complexity.
- Combating "Vegan-Washing":The industry must actively work to maintain consumer trust by providing transparent, verifiable claims in the face of "vegan-washing," where brands make misleading statements about their ethical credentials, which erodes market credibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Cosmetics Market |
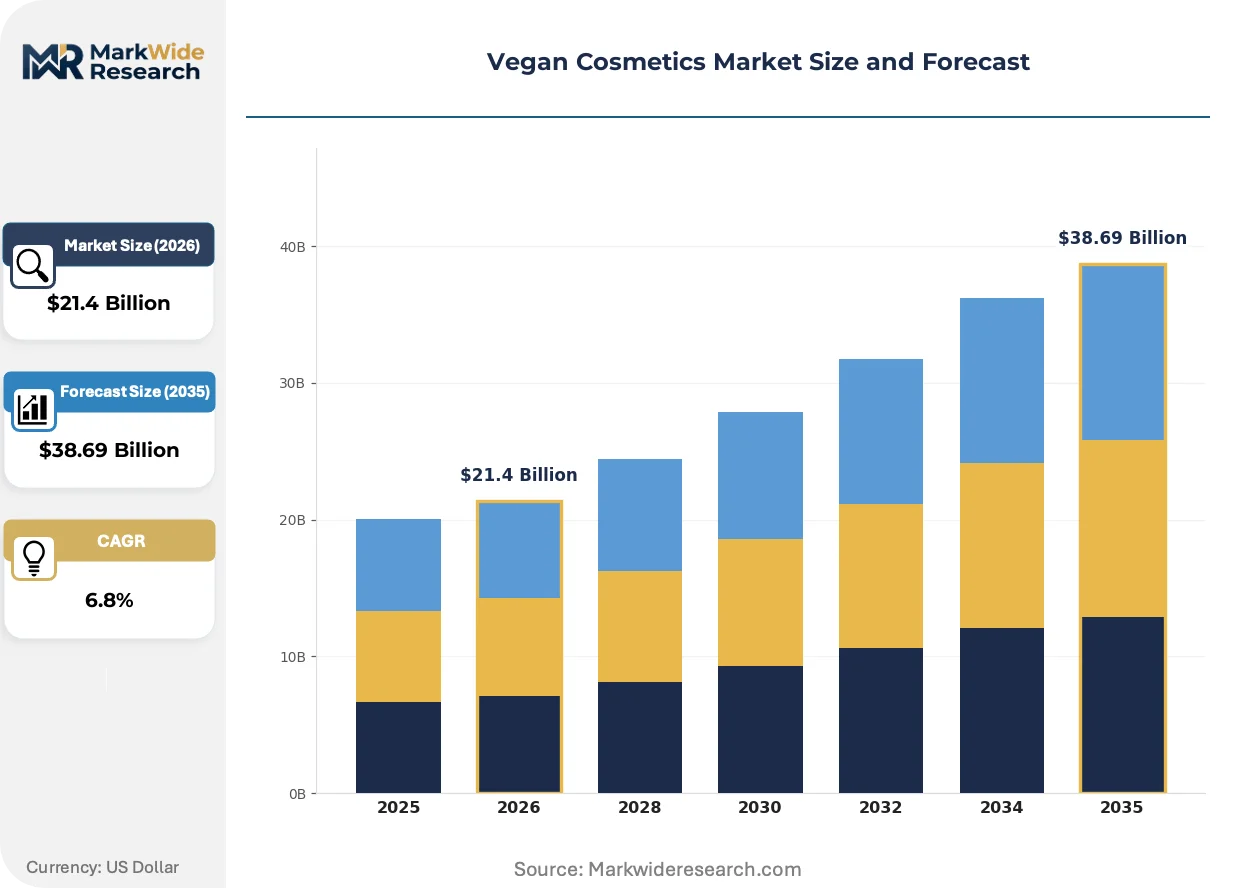
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $38.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Makeup, Fragrance, Body Care, Nail Care Application: Facial Care, Sun Care, Anti-Aging, Hair Treatment, Lip Care, Deodorants End User: Salons, Spas, Personal Care, Dermatology Clinics, Beauty Retailers, Online Shoppers Distribution Channel: Specialty Stores, E-commerce, Supermarkets, Pharmacies, Direct Sales, Department Stores |
| Companies Covered | Unilever PLC, Milk Makeup, L'Oreal SA, Tarte Cosmetics, Urban Decay, e.l.f. Beauty, Inc., Pacifica Beauty, Live Tinted, Coty Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Cosmetics Market Strategic Shifts & Innovations
The market is defined by a convergence of material science, regulatory evolution, and digital-first consumer engagement. These forces are compelling brands to innovate beyond simple ingredient exclusion, focusing instead on performance, transparency, and authentic communication to build loyalty.
Advanced material science is a core innovation engine. Biosynthetic ingredients, such as those produced through precision fermentation, provide pure, effective, and ethically sourced alternatives to traditional cosmetic components. Both prestige and mass-market brands are actively incorporating these new materials into skincare and makeup lines. This technology is hybridizing nature-identical compounds with lab-based consistency, creating a new class of high-performance vegan ingredients.
Regulatory changes in key markets are creating new commercial pathways. China's NMPA has updated its rules, ending mandatory pre-market animal testing for most general cosmetics imported into the country. This policy shift unlocks significant opportunities for cruelty-free and vegan brands that previously bypassed the market. The skincare and makeup categories are most affected, as brands must now navigate new registration and labeling requirements to gain access.
Consumer purchasing behavior is undergoing a fundamental shift away from legacy channels. Product discovery and purchasing decisions are increasingly influenced by social commerce and influencer marketing, particularly on visual platforms. This trend disrupts the traditional department store and pharmacy distribution models, benefiting digitally native brands that excel at online community building. The shift is most visible among Millennial and Gen Z consumers in developed Western markets.
Vegan Cosmetics Market Segmentation
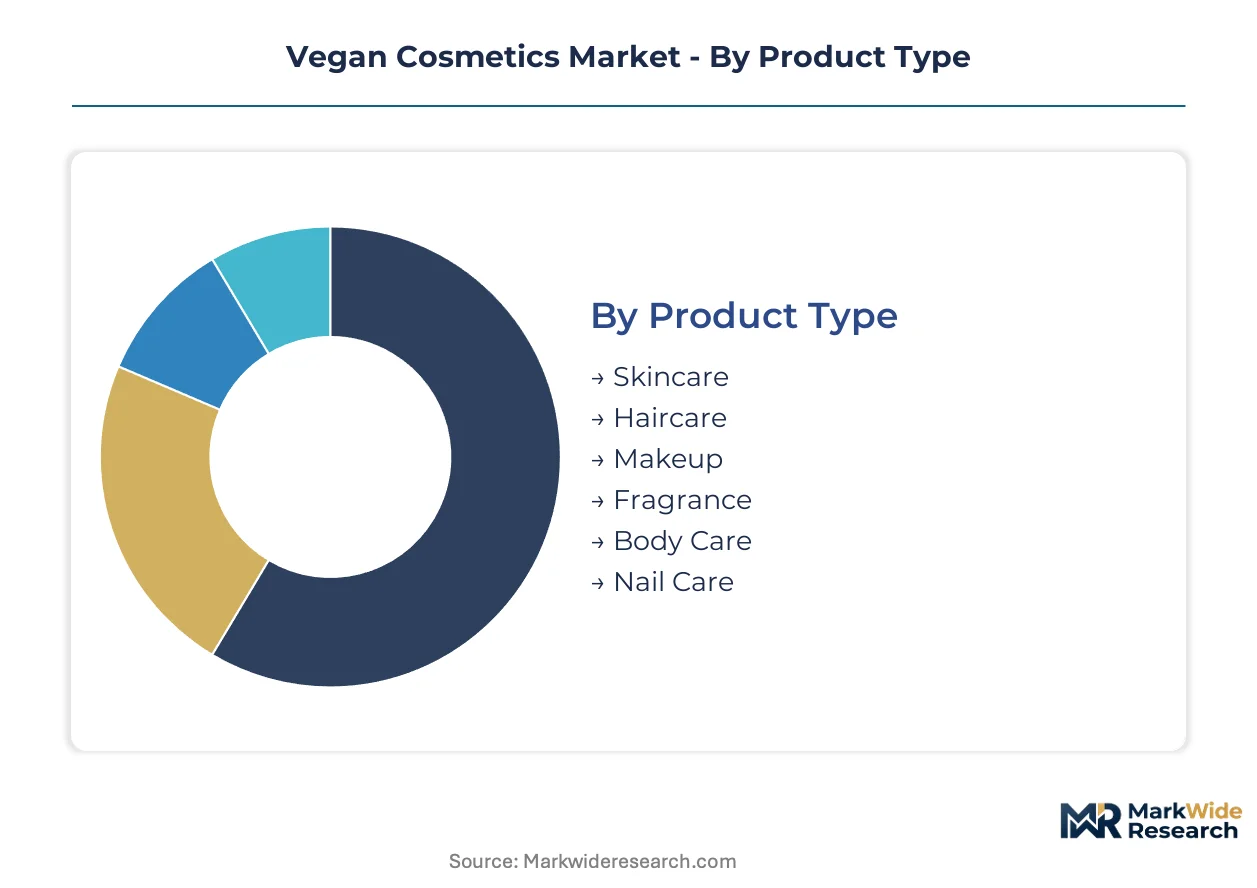
Market segmentation provides a granular view of the vegan cosmetics industry, highlighting distinct product offerings, consumer behaviors, and market access points. This detailed breakdown allows brands to tailor product development, marketing strategies, and distribution efforts to specific consumer needs and preferences, optimizing engagement across diverse segments.
Product Type:
Product type segmentation reveals the varying maturity levels of vegan cosmetic offerings.
- Skincare:Formulations designed for facial and body epidermal health, free from animal-derived ingredients like lanolin or collagen. Demand concentrates in facial care and anti-aging solutions, driven by consumer pursuit of ethical and effective formulations.
- Makeup:Color cosmetics and enhancement products formulated without animal by-products such as carmine or beeswax. Demand is concentrating among younger consumer demographics, particularly for lip care and eye products, influenced by social media trends.
- Haircare:Products for hair cleansing, conditioning, and styling, utilizing plant-based proteins and emollients.
- Fragrance:Scents derived from botanical extracts and synthetic molecules, avoiding animal musks or civet.
- Body Care:Moisturizers, cleansers, and treatments for the body, often featuring plant-based oils and butters.
- Nail Care:Polishes, treatments, and removers formulated without animal-derived pigments or gelatin.
Skincare retains volume leadership; Makeup holds the steepest expansion curve.
Application:
Application segmentation highlights where consumer volume is most pronounced across different product uses.
- Facial Care:Products specifically designed for the face, including cleansers, serums, and moisturizers, free from animal ingredients. Demand concentrates across all age groups, propelled by daily routine adherence and ethical sourcing preferences.
- Lip Care:Formulations for moisturizing, protecting, and coloring the lips, excluding animal waxes or carmine. Demand is strongest among younger demographics, driven by social media influence and desire for ethical color cosmetics.
- Sun Care:Protective formulations shielding skin from UV radiation, using mineral or plant-based filters.
- Anti-Aging:Specialized treatments targeting wrinkles and fine lines, often incorporating plant-derived peptides and antioxidants.
- Hair Treatment:Conditioners, masks, and serums addressing specific hair concerns, utilizing botanical extracts and oils.
- Deodorants:Products designed to control body odor, employing natural minerals and essential oils.
Facial Care applications dominate the market; Lip Care applications are expanding most quickly.
End User:
End user segmentation reflects the varying margin profiles and service requirements of different customer groups.
- Personal Care:Individual consumers purchasing vegan cosmetics for daily self-use through various channels. Demand concentrates on accessibility and ethical claims, driving purchases of skincare and makeup products.
- Online Shoppers:Consumers acquiring vegan cosmetic products via e-commerce platforms, including brand websites and third-party marketplaces. Demand is expanding product accessibility worldwide, particularly benefiting digitally native brands leveraging social media.
- Salons:Professional establishments offering hair and beauty services, utilizing vegan products for client treatments.
- Spas:Wellness centers providing therapeutic and aesthetic treatments, incorporating vegan formulations for holistic care.
- Dermatology Clinics:Medical facilities offering skin-specific treatments, sometimes integrating vegan, hypoallergenic products.
- Beauty Retailers:Physical stores specializing in cosmetic sales, offering curated selections of vegan brands.
Personal Care consumers represent the largest end-user segment; Online Shoppers are gaining share fastest.
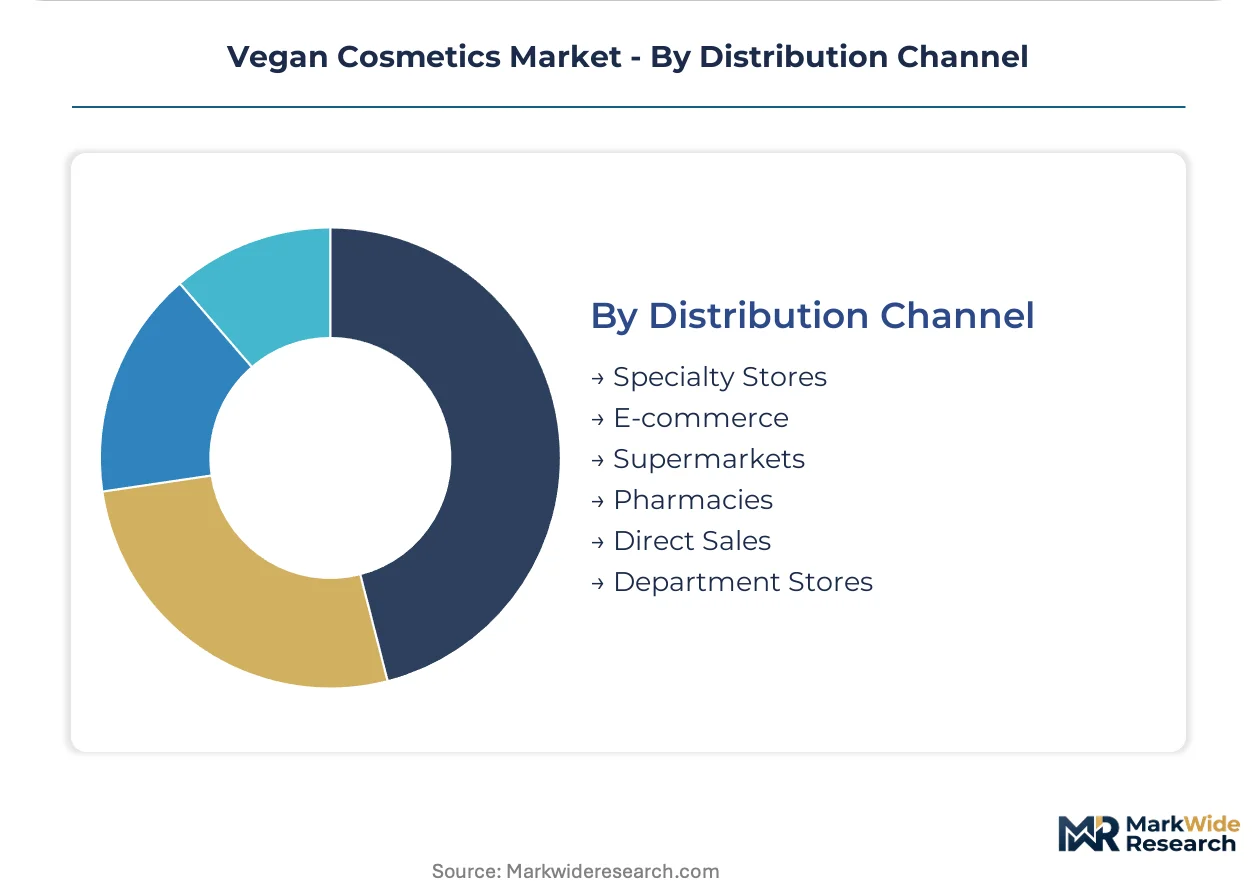
Distribution Channel:
Distribution channel segmentation illustrates how product supply concentrates across various retail and direct-to-consumer avenues.
- E-commerce:Online platforms, including direct-to-consumer websites and marketplace aggregators, facilitating global product reach. Demand is tilting the competitive landscape away from traditional distribution, benefiting digitally native brands.
- Supermarkets:Mass-market retail chains offering a broad selection of consumer goods, including accessible vegan cosmetic lines. Demand is driven by convenience and competitive pricing, making vegan products widely available to a diverse consumer base.
- Specialty Stores:Retail outlets focusing on specific product categories like beauty, offering curated vegan cosmetic selections.
- Pharmacies:Healthcare-focused retail locations, stocking vegan skincare and personal care products, often emphasizing gentle formulations.
- Direct Sales:Sales models where products are sold directly to consumers, often through independent consultants or multi-level marketing structures.
- Department Stores:Large retail establishments offering diverse product ranges, including prestige vegan cosmetic brands.
E-commerce is displacing traditional channels; Supermarkets provide broad consumer access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European Union's regulatory framework anchors ethical cosmetic product development, compelling brands to meet stringent cruelty-free standards. This influences global formulation practices and marketing claims for vegan cosmetics. Key markets worldwide demonstrate distinct demand drivers and regulatory landscapes.
Germany
German consumers demonstrate strong demand for ethically sourced beauty products, aligning with broader environmental consciousness. The EU's comprehensive ban on animal testing remains a central regulatory benchmark for market entry. Berlin serves as a hub for innovative, digitally native vegan beauty brands catering to a conscious consumer base.
United States
Demand for vegan cosmetics in the United States is driven by e-commerce accessibility and younger consumer cohorts seeking ethical alternatives. The US FDA's requirements for ingredient labeling ensure transparency, building consumer trust. California's beauty tech cluster fosters innovation in clean beauty, attracting investment in vegan product development.
China
China's market presents significant opportunities due to evolving consumer consciousness and recent regulatory shifts. The NMPA updated rules, relaxing mandatory pre-market animal testing for many general imported cosmetics, opening pathways for vegan brands. Shanghai's dynamic cosmetics industry hub attracts international brands establishing local operations.
Japan
Japanese consumers prioritize premium skincare and natural ingredients, driving demand for high-performance vegan formulations. While Japan does not mandate animal testing for cosmetics, brands emphasize transparency and ethical sourcing. Tokyo remains a center for beauty innovation, where prestige brands develop sophisticated vegan products.
France
French consumers seek prestige beauty products with strong ethical credentials, influencing demand for high-quality vegan cosmetics. The European Union's ban on animal testing significantly shapes product development and marketing strategies. Paris, a global capital for luxury cosmetics, houses R&D centers advancing vegan beauty formulations.
Vegan Cosmetics Market Key Industry Players
Digitally native brands and established giants split the market, each leveraging distinct strengths to capture consumer attention. The competitive landscape for vegan cosmetics is characterized by a blend of agile, direct-to-consumer players and large, diversified corporations seeking market share. Established players extend online presence and acquire smaller vegan-focused lines, while emerging brands build customer acquisition through social media engagement. This dynamic fosters both M&A activities and strategic partnerships across the industry's value chain.
Within the digitally native brand archetype, Milk Makeup exemplifies leveraging social media for customer acquisition and community building among younger demographics, establishing a strong online presence. L'Oreal SA, a global beauty giant, represents the strategy of extending its online presence and acquiring smaller vegan lines to diversify its extensive product portfolio. E.l.f. Beauty, Inc. demonstrates success through an accessible price point and widespread availability in mass-market retail channels, effectively reaching a broad consumer base with its ethical offerings.
| Leading Market Players |
|---|
| Unilever PLC |
| Milk Makeup |
| L'Oreal SA |
| Tarte Cosmetics |
| Urban Decay |
| e.l.f. Beauty, Inc. |
| Pacifica Beauty |
| Live Tinted |
| Coty Inc. |
| Others |
Cost & Logistics Intelligence
Shanghai's growing capacity for cosmetic ingredient production directly influences downstream pricing power across the Asia-Pacific region. This concentration of raw material supply impacts the cost structure for vegan cosmetic brands globally, affecting final product affordability.
Pricing Analysis
Geographic price spreads for vegan cosmetics vary significantly, with premium products commanding higher prices in Western Europe compared to mass-market offerings in North America. The dominant pricing structure is a three-tier model across premium, standard, and economy levels. Price differentiation stems from certification level, such as EU cruelty-free standards, and brand premium associated with digitally native labels. Pricing pressure intensifies for mass-market segments due to ingredient cost volatility. Personal care consumers in supermarkets exhibit the highest price sensitivity, while prestige buyers prioritize efficacy and ethical claims.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are becoming more prevalent for ingredient procurement, especially for novel biosynthetic compounds. Geographic supply concentration for key vegan ingredients draws from China for botanical extracts and the European Union for advanced fermentation-derived materials. Raw material dependencies include plant-based oils, natural emollients, and lab-grown proteins. Supply chain opacity in verifying vegan claims for every component presents a structural risk. Distribution primarily runs through e-commerce platforms and mass-market retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vegan cosmetics market is experiencing an early-cycle expansion, driven by the sustained tailwind of rising consumer demand for ethical and sustainable beauty solutions.
For Market Incumbents: Harden existing supply chain verification processes to counteract "vegan-washing" and maintain consumer trust. Acquire smaller, innovative digitally native brands to expand product portfolios and reach younger demographics. Invest heavily in R&D for biosynthetic ingredients to secure future-proof, high-performance formulations. Extend online presence through social commerce partnerships to compete with agile market entrants.
For New Entrants and Emerging Players: Asia's underpenetrated market, particularly China following NMPA rule changes, offers significant white-space opportunities for vegan brands. Target younger consumer demographics with lip care and color cosmetics, leveraging social media and influencer marketing as a primary go-to-market angle. Develop "vegan plus" formulations that combine ethical claims with other attributes like "clean" or organic to capture broader consumer interest.
For Investors and Strategic Acquirers: Carve-out targets emerge from large beauty conglomerates divesting non-core ethical brands or established ingredient suppliers seeking to specialize in vegan alternatives. The long-term viability of this market is framed by sustained ethical consumer demand and regulatory tailwinds. A key signal to watch is the harmonization of global vegan certification standards, indicating reduced market fragmentation and clearer investment pathways.
| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology Investment | Secures novel, high-performance vegan ingredients with transparent supply chains for future product lines. |
| Direct-to-Consumer Channel Expansion | Enhances brand control and customer engagement, reducing reliance on traditional retail distribution models. |
| Acquisition of Niche Vegan Brands | Diversifies product portfolios and captures specific consumer segments with established ethical credentials. |
| Certification Standard Alignment | Streamlines market access and builds consumer trust by simplifying complex vegan verification processes. |
| Geographic Expansion into Asia | Taps into large, evolving consumer bases in markets like China, leveraging relaxed regulatory testing requirements. |
Research Approach
A spread of perspectives from brand managers, R&D chemists, regulatory affairs specialists, and e-commerce platform managers converged on the working assumptions for this analysis. This involved combining primary interviews with industry stakeholders and secondary validation from EU regulatory documents, NMPA guidelines, and public company financial filings. The process employed both bottom-up and top-down triangulation to ensure data accuracy and consistency.
The demand-supply-balance framing underpins the analytical framework across the analysis window, projecting market evolution. Segmentation dimensions modeled include product type, application, end-user, distribution channel, and ingredient technology. Compound annual growth rates were derived from historical trends, projected consumer shifts, and anticipated regulatory impacts. Key industry-specific forecast inputs included e-commerce penetration rates and biosynthetic ingredient adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by digitally native brands or major ingredient suppliers would shift outcomes. Rapid shifts in consumer preferences or unexpected ingredient innovations are specific risk factors. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegan Cosmetics
Brazil Vegan Cosmetics Market
Vegan Cosmetics
India Vegan Cosmetics Market
Vegan Cosmetics
France Vegan Cosmetics Market
Vegan Cosmetics
Europe Vegan Cosmetics Market
Vegan Cosmetics
Vegan Face Cream Market
Vegan Cosmetics
Italy Vegan Cosmetics Market
Vegan Cosmetics
Canada Vegan Cosmetics Market
Vegan Cosmetics
US Vegan Cosmetics Market
Vegan Cosmetics
Argentina Vegan Cosmetics Market
Vegan Cosmetics
Germany Vegan Cosmetics Market
Vegan Cosmetics
China Vegan Cosmetics Market
Vegan Cosmetics
Chile Vegan Cosmetics Market
Vegan Cosmetics
Global Probiotic Cosmetics Market
Vegan Cosmetics
South Korea Vegan Cosmetics Market
Vegan Cosmetics
Organic Cosmetics Market
Vegan Cosmetics
Spain Vegan Cosmetics Market