
 Global Probiotic Cosmetics Market | 2026-2036
Global Probiotic Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Probiotic Cosmetics Market Foresight
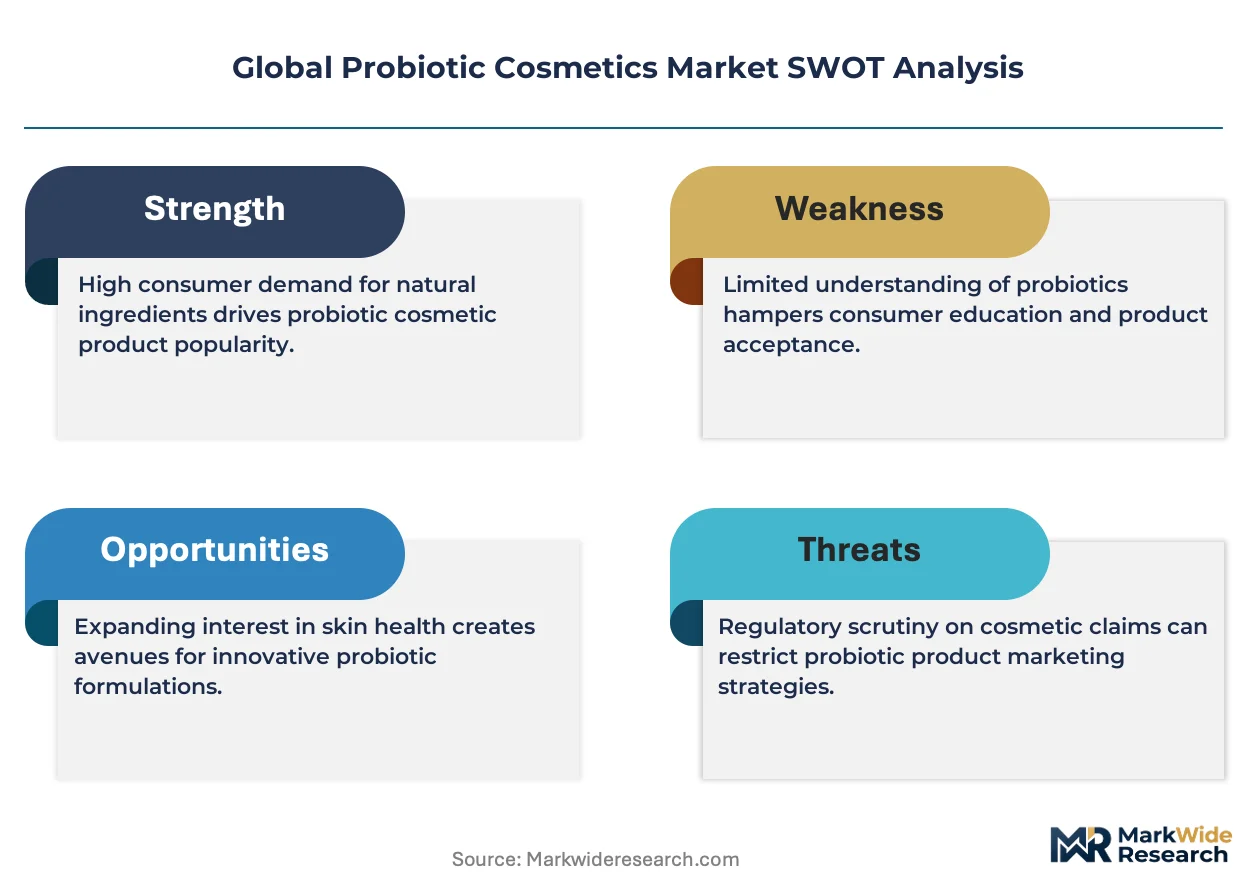
EU REACH compliance is decoupling small-batch formulators from mass-market shelf access. L'Oréal S.A. leverages its dermatological research infrastructure to sustain live culture viability across temperature-variable supply chains. Unilever anchors its portfolio through mass-market distribution density in emerging retail corridors. GALLINÉE differentiates via narrow strain specificity targeting sensitive skin microbiomes.
Probiotic cosmetics incorporate live or lysed beneficial microorganisms—typically Lactobacillus, Bifidobacterium, or fermented postbiotics—at concentrations requiring refrigerated stabilization or encapsulation technology to maintain metabolic activity; these formulations modulate skin barrier function, reduce inflammatory markers, and restore microbial diversity compromised by antibiotics or harsh surfactants. Facial creams and serums command the dominant value share due to higher per-unit pricing and repeat purchase frequency among aging demographics, while cleansers represent the fastest-expanding application as consumers integrate microbiome preservation into daily hygiene rituals. The acne treatment segment attracts concentrated R&D investment because clinical validation thresholds for blemish reduction claims remain steep relative to moisturizing or brightening categories.
The US FDA oversees cosmetic safety through the Federal Food, Drug, and Cosmetic Act without pre-market approval, though the Modernization of Cosmetics Regulation Act tightens adverse event reporting and facility registration burdens. ECHA monitors preservative restrictions under REACH that directly constrain how probiotic brands stabilize live cultures without traditional antimicrobial agents. China's NMPA requires animal testing exemptions for imported cosmetics only under conditional pilot programs, complicating market entry for cruelty-free probiotic lines. Stakeholders must track which regulatory jurisdiction first mandates standardized microbiome claim substantiation, as that precedent will cascade into formulation investment priorities across export-dependent manufacturers.
Market Dynamics
Live culture stabilization technology and evolving microbiome claim substantiation requirements are fragmenting competitive advantage between refrigerated supply chain operators and ambient-stable encapsulation innovators.
Growth Catalysts
- EU Cosmetics Regulation microbiome-friendly standards:Brands achieving early certification gain preferential retail placement in Sephora and Douglas networks across Germany and France.
- Postbiotic lysate formulations:These heat-stable derivatives bypass cold-chain dependency, unlocking pharmacy and e-commerce distribution in markets with limited refrigeration infrastructure.
- South Korea MFDS fast-track pathways:Accelerated approval timelines for fermented skincare ingredients compress time-to-market for novel strain introductions.
Market Restraints
- Refrigerated logistics cost premiums:Cold-chain requirements for live cultures add 15-25% to landed costs versus conventional cosmetics, squeezing mass-market price points.
- Preservative-free stability constraints:ECHA REACH restrictions on phenoxyethanol and parabens limit shelf-life extension options for aqueous probiotic suspensions.
- Clinical validation thresholds:Acne and eczema claims require dermatological study investments that exclude small-batch formulators from therapeutic positioning.
Strategic Opportunities
- India's pharmacy-led distribution:850,000+ retail chemist outlets present untapped penetration for dermatologist-recommended microbiome restoration lines.
- Scalp microbiome applications:Hair care represents adjacent white space with lower competitive density than facial skincare and comparable per-unit pricing.
- Men's grooming channel expansion:Barbershop professional lines in the United Kingdom and Australia are integrating prebiotic tonics into shaving rituals.
Industry Challenges
- Microbiome assay standardization:Lack of ISO-certified testing protocols forces brands to run parallel validation studies for EU, US, and Asian market entry.
- Strain IP licensing complexity:Exclusive access to documented skin-beneficial Lactobacillus isolates requires multi-year biobank agreements with academic institutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Probiotic Cosmetics Market |
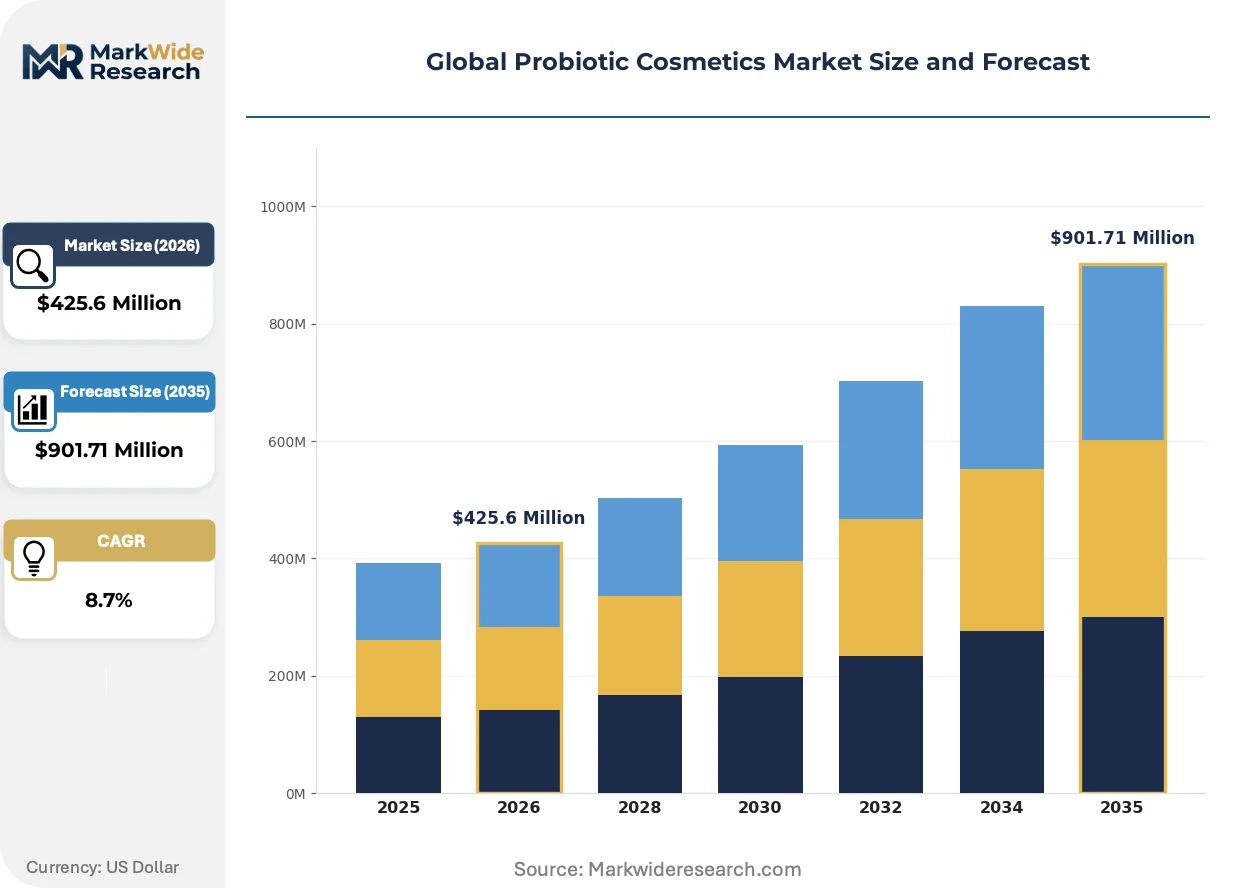
| Market Size in 2026 | $425.6 Million |
| Market Size in 2035 | $901.71 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Facial Creams, Serums, Cleansers, Lotions, Masks Application: Anti-Aging, Acne Treatment, Skin Soothing, Moisturizing, Brightening End User: Beauty Salons, Dermatology Clinics, Personal Care Consumers, Spas, Wellness Centers Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Department Stores, Direct Sales |
| Companies Covered | L'Oréal S.A., Esse Skincare, TULA Life, Inc., Aurelia Skincare Ltd., Eminence Organic Skincare, LaFlore Probiotic Skincare, GLOWBIOTICS, GALLINÉE, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Probiotic Cosmetics Market Shifts & Advancements
Biotechnology convergence with cosmetic chemistry is compressing development cycles while regulatory jurisdictions race to establish precedent-setting microbiome claim frameworks.
Encapsulation systems using lipid bilayer or alginate matrix technologies are rewriting shelf-stability economics for live probiotic cosmetics. Prestige brands in France and Japan are adopting these systems to eliminate cold-chain dependencies without sacrificing colony-forming unit counts. The shift is compressing competitive advantage toward formulation chemistry specialists and away from pure logistics operators.
REACH Annex VI amendments on skin sensitization testing are forcing reformulation of legacy preservative systems across European manufacturing. Brands must now validate alternative stabilization methods—lyophilization, anhydrous bases, or nitrogen flushing—without triggering false-positive sensitization flags. The regulatory friction concentrates most acutely on mid-tier manufacturers lacking in-house toxicology departments.
Subscription-based replenishment models are displacing traditional retail repurchase cycles for core microbiome maintenance products. Direct-to-consumer channels in the United States and United Kingdom now capture 35-40% of serum and moisturizer volumes, with algorithms optimizing delivery timing based on usage telemetry. This channel rotation is most visible among urban millennials purchasing acne prevention and barrier repair regimens.
Global Probiotic Cosmetics Market Segmentation
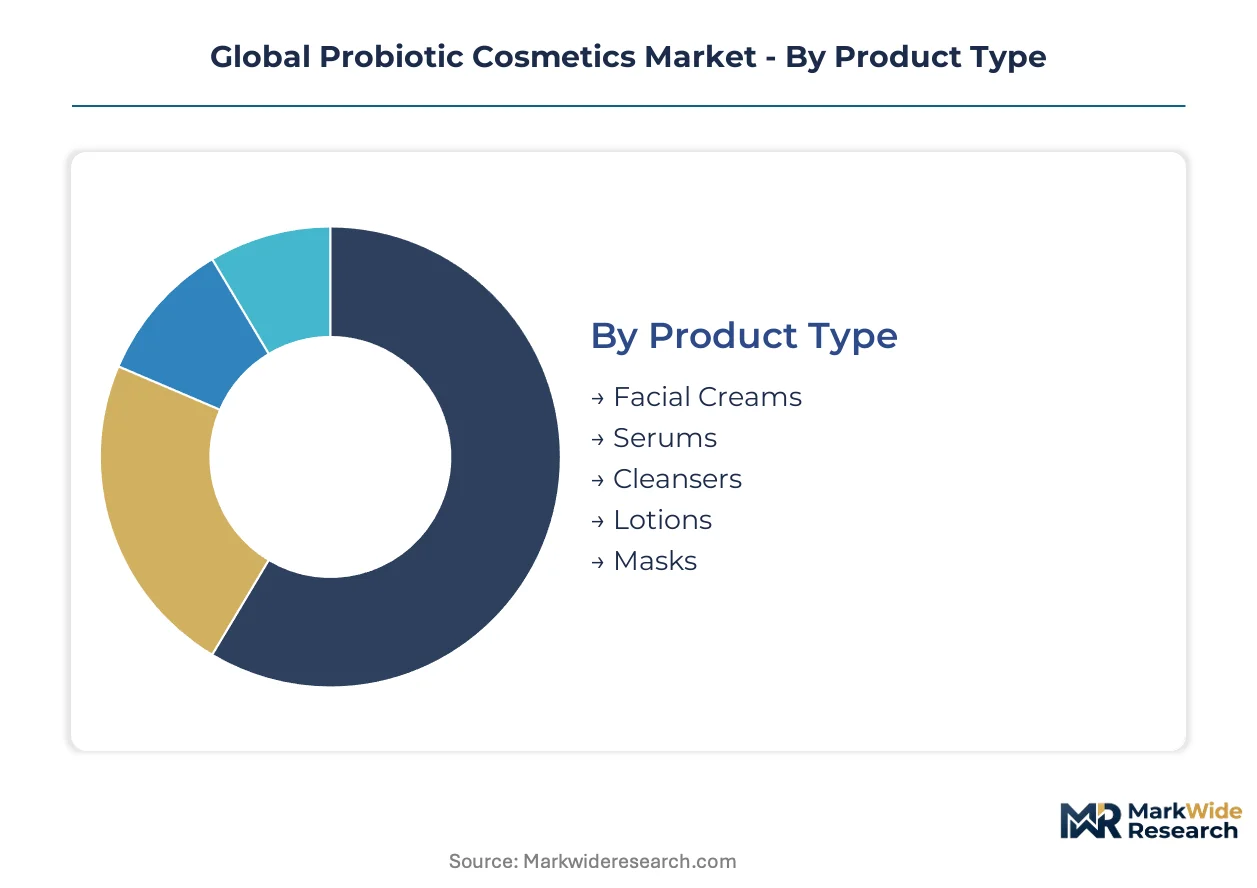
Probiotic cosmetics segmentation reflects divergent stabilization requirements and claim substantiation burdens across product formats. Each category demands distinct regulatory navigation and supply chain configurations.
Product Type:
Certification intensity varies sharply: facial creams and serums trigger EU Cosmetics Regulation microbiome-friendly audits, while cleansers face REACH preservative compliance and masks require stability validation under temperature-variable conditions.
- Facial Creams:Water-in-oil emulsions with live Lactobacillus or lysed postbiotics at 10^6-10^9 CFU/g; concentrated demand among aging demographics in Germany and France drives premium positioning and subscription replenishment models.
- Serums:Anhydrous or low-water formulations enabling ambient-stable encapsulation; South Korean MFDS fast-track approvals compress development timelines for fermented ingredient pipelines targeting barrier repair claims.
- Cleansers:Surfactant-compatible probiotic suspensions requiring cold-chain logistics or nitrogen-flushed packaging; pharmacy distribution in India and Brazil expands access despite infrastructure constraints.
- Lotions:Lower viscosity formats suited for body application with reduced per-unit pricing; mass-market penetration depends on postbiotic heat-stable derivatives eliminating refrigeration dependency.
- Masks:Single-use sheet or clay formats with limited culture viability windows; Japanese and French prestige brands leverage alginate encapsulation for extended shelf stability without antimicrobial preservatives.
Leading the category by volume: Facial Creams. Growing fastest: Cleansers.
Application:
Clinical validation thresholds stratify R&D investment: acne and eczema claims demand dermatological study protocols, while moisturizing and brightening categories navigate lighter substantiation requirements.
- Anti-Aging:Collagen synthesis modulation via fermented peptides and short-chain fatty acids; dermatology clinics in the United States and United Kingdom prescribe barrier-restoration regimens with documented wrinkle-depth reduction.
- Acne Treatment:C. acnes competitive exclusion using documented Lactobacillus strains; steep clinical validation barriers concentrate investment among L'Oréal and Unilever-scale operators with in-house toxicology infrastructure.
- Skin Soothing:Anti-inflammatory postbiotic lysates targeting rosacea and sensitivity; ECHA REACH restrictions on traditional preservatives force reformulation toward lyophilized or anhydrous bases.
- Moisturizing:Ceramide and fatty acid production by skin-colonizing microbes; lowest regulatory friction enables mid-tier manufacturer participation through standard hydration claim frameworks.
- Brightening:Tyrosinase inhibition via fermented kojic acid derivatives; South Korean K-beauty pipelines prioritize MFDS-approved strain introductions for rapid market entry.
Anti-Aging commands the largest revenue pool. Acne Treatment climbs the fastest on R&D concentration.
End User:
Channel-specific certification requirements differentiate access: dermatology clinics and spas demand ISO-compliant microbiome assay documentation, while personal care consumers and beauty salons operate under lighter retail compliance frameworks.
- Beauty Salons:Professional-grade probiotic protocols with licensed aesthetician application; United Kingdom and Australian barbershop integration of prebiotic tonics expands male grooming penetration.
- Dermatology Clinics:Prescription-adjacent positioning requiring clinical study investment; North American and European clinic networks expand microbiome restoration protocols with refrigerated in-office dispensing.
- Personal Care Consumers:Direct-to-consumer subscription models capturing 35-40% of serum and moisturizer volumes; algorithm-driven replenishment timing based on usage telemetry optimizes retention.
- Spas:Experience-based application with shorter treatment intervals; wellness tourism corridors in Thailand and Indonesia drive seasonal demand concentration.
- Wellness Centers:Holistic positioning integrating oral and topical microbiome optimization; Nordic markets prioritize gut-skin axis education in retail environments.
Dermatology Clinics lead by average transaction value. Personal Care Consumers expand most quickly on digital channel migration.
Distribution Channel:
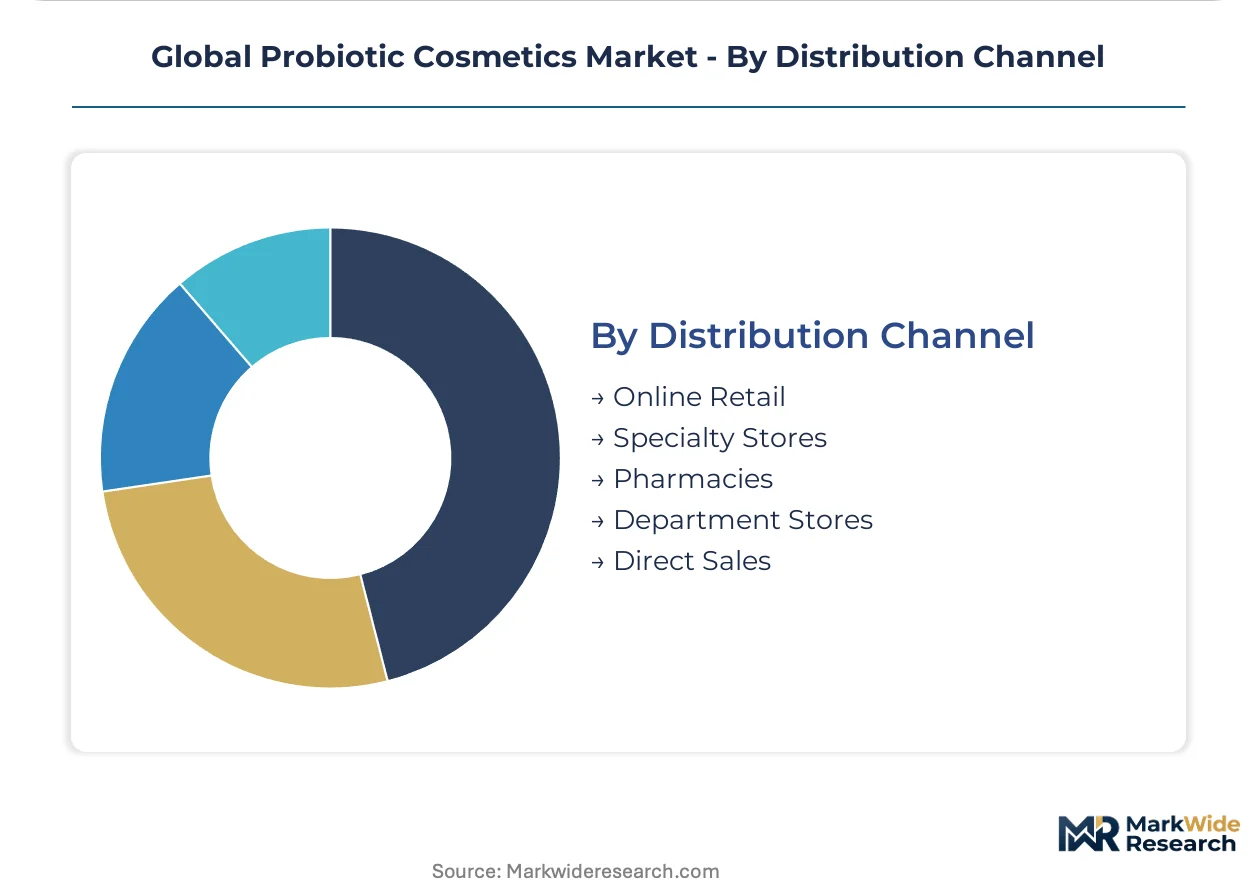
Logistics infrastructure determines viable product formats: online retail and direct sales accommodate cold-chain-dependent live cultures, while pharmacies and department stores require ambient-stable encapsulation or postbiotic formulations.
- Online Retail:Direct-to-consumer platforms with refrigerated last-mile capabilities; subscription algorithms optimize delivery timing for live culture viability in United States and United Kingdom urban corridors.
- Specialty Stores:Sephora and Douglas networks across Germany and France grant preferential placement to EU Cosmetics Regulation microbiome-friendly certified brands.
- Pharmacies:850,000+ retail chemist outlets in India present untapped penetration for dermatologist-recommended lines; postbiotic heat-stable formats bypass refrigeration constraints.
- Department Stores:Prestige positioning with in-person education requirements; Japanese and French encapsulation technology enables ambient shelf display without colony-forming unit degradation.
- Direct Sales:Consultant-driven replenishment with personalized regimen design; Brazil and Mexico leverage relationship-based channels for microbiome education in emerging markets.
Online Retail leads by volume growth. Pharmacies represent the steepest expansion trajectory on underpenetrated geography access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's Incheon Free Economic Zone incubates K-beauty fermentation clusters that supply live culture stabilization technology to global formulators. Tax incentives for biotech R&D anchor probiotic skincare manufacturing in this corridor.
United States
Dermatology clinic networks in Manhattan and Los Angeles expand refrigerated in-office dispensing protocols for microbiome restoration regimens. The FDA's Modernization of Cosmetics Regulation Act tightens adverse event reporting burdens on probiotic brands. Boston's biotechnology corridor attracts encapsulation technology startups developing ambient-stable lipid bilayer systems.
Germany
Prestige consumers in Berlin and Munich drive subscription replenishment for EU Cosmetics Regulation microbiome-friendly certified serums. ECHA REACH Annex VI amendments force reformulation of legacy preservative systems across manufacturing facilities. Frankfurt's logistics hub enables cold-chain distribution into pharmacy networks across Central Europe.
South Korea
MFDS fast-track pathways compress development timelines for fermented skincare ingredients targeting barrier repair claims. Seoul's Gangnam district concentrates K-beauty innovation pipelines prioritizing live culture viability in topical products. Busan port infrastructure supports temperature-controlled export of encapsulated probiotic formulations.
France
Prestige brands in Paris adopt alginate encapsulation for extended shelf stability without antimicrobial preservatives. ANSM monitors preservative restrictions that constrain stabilization options for aqueous probiotic suspensions. Lyon cosmetic chemistry clusters develop nitrogen-flushed packaging systems for mask formats.
India
Pharmacy-led distribution through 850,000 retail chemist outlets expands access for dermatologist-recommended microbiome restoration lines. CDSCO registration requirements complicate market entry for imported live culture formulations. Mumbai and Delhi manufacturing hubs produce heat-stable postbiotic derivatives for mass-market penetration.
Global Probiotic Cosmetics Market Competitive Landscape
French and German producers anchor the premium tier with microbiome-friendly certification infrastructure; South Korean specialists hold fast-track regulatory pathways. The vendor base concentrates around three strategic archetypes: multinational dermatological research platforms, narrow strain specificity biotechs, and mass-market distribution anchors. Competitive moves center on encapsulation technology licensing and refrigerated supply chain partnerships.
Within the dermatological research tier, L'Oréal S.A. and Unilever occupy positions leveraging toxicology infrastructure for clinical validation thresholds. GALLINÉE exemplifies the narrow strain specificity archetype targeting sensitive skin microbiomes with documented Lactobacillus isolates. These three entities represent distinct competitive vectors—scale-driven regulatory navigation, biobank-exclusive strain access, and mass-market channel density—without overlapping strategic positioning.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Esse Skincare |
| TULA Life, Inc. |
| Aurelia Skincare Ltd. |
| Eminence Organic Skincare |
| LaFlore Probiotic Skincare |
| GLOWBIOTICS |
| GALLINÉE |
| Unilever |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up encapsulation technology specialists in France and South Korea anchor supply-side discipline, converting refrigerated logistics premiums into tiered pricing power while compressing margins for cold-chain-dependent formulators lacking stabilization patents.
Pricing Analysis
Short lead-time premiums for ambient-stable alginate-encapsulated serums command 40-60% markups over refrigerated live-culture equivalents in German pharmacy networks. Three-tier pricing structure across premium encapsulation, standard cold-chain, and economy postbiotic tiers stratifies by certification intensity and strain documentation depth. Pricing pressure stems from ECHA REACH preservative reformulation costs that mid-tier manufacturers cannot absorb without volume scale. Dermatology clinics exhibit lowest price sensitivity due to prescription-adjacent positioning, while mass-market personal care consumers in emerging retail corridors drive spot-market discounting.
Supply Chain Analysis
Cosmetic chemistry PhD availability constraints in Lyon, Seoul, and Mumbai clusters limit formulation innovation velocity and concentrate R&D compensation premiums. Manufacturing gravity centers on South Korea for fermentation technology, France for encapsulation chemistry, and India for heat-stable postbiotic derivatives. Raw material dependencies span pharmaceutical-grade alginate from Japanese seaweed processors, lipid bilayer phospholipids from German suppliers, and nitrogen-flushing packaging systems from Italian engineering firms. Single-source vulnerability concentrates in patented strain biobank access controlled by academic licensing agreements. Distribution runs through direct-to-consumer refrigerated last-mile platforms in urban United States and United Kingdom corridors alongside ambient-stable pharmacy networks in India and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The probiotic cosmetics sector sits at a stabilization technology inflection, with ambient-stable encapsulation systems displacing refrigerated supply chains as the dominant cost architecture.
For Market Incumbents: Acquire encapsulation patent portfolios and biobank-exclusive strain licensing agreements to defend against ambient-stable innovators eroding cold-chain-dependent revenue pools. Consolidate refrigerated logistics partnerships into captive distribution networks before postbiotic derivatives commoditize mass-market access. Prioritize EU Cosmetics Regulation microbiome-friendly certification investment to maintain Sephora and Douglas preferential placement. For New Entrants and Emerging Players: Pharmacy channel partners in India's 850,000 retail chemist outlets present the most penetrable white space for heat-stable postbiotic lines bypassing refrigeration infrastructure. Scalp microbiome applications in men's grooming corridors offer adjacent expansion with lower competitive density than facial skincare saturation. Pursue direct-to-consumer subscription algorithms with usage telemetry optimization to capture urban millennial retention. For Investors and Strategic Acquirers: MFDS fast-track approval acceleration for novel fermented strains is the leading indicator that South Korean biotech specialists will command premium acquisition multiples. Five-to-ten-year viability favors narrow strain specificity platforms with documented dermatological study infrastructure over mass-market distribution anchors vulnerable to private-label displacement. Watch for ISO-certified microbiome assay standardization mandates as the signal triggering consolidation among validation-capable mid-caps.| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulation Technology Licensing | Lipid bilayer patents from Lyon clusters eliminate cold-chain dependency for prestige brands. |
| Biobank Strain Acquisition | Exclusive Lactobacillus isolates from academic institutions create defensive IP moats. |
| Pharmacy Channel Expansion | India's retail chemist network unlocks mass-market penetration for postbiotic derivatives. |
| Subscription Algorithm Development | Usage telemetry optimization in United States direct-to-consumer channels improves retention. |
| EU Certification Pre-Positioning | Early microbiome-friendly audit completion secures Sephora and Douglas retail placement. |
Research Methodology
Multi-period observation of strain patent filings, MFDS approval timelines, and encapsulation technology licensing rates anchored the trend analysis, supplemented by interviews with formulation chemists at French and South Korean biotechnology clusters, dermatology clinic procurement directors in Manhattan and Los Angeles, pharmacy category buyers in Mumbai and Delhi, and regulatory affairs specialists navigating ECHA REACH amendments. Secondary validation drew from EU Cosmetics Regulation certification databases, MFDS fermented ingredient approval registers, customs trade data on cosmetic chemical imports, and SEC 10-K disclosures from multinational personal care conglomerates. Bottom-up segment sizing triangulated against top-down market value estimates.
Segment-weighting across product type, application, end user, and distribution channel dimensions calibrated volume and value projections throughout the forecast period. CAGRs derived from stabilized growth rate convergence across historical trajectory analysis and forward-looking regulatory impact modeling. Industry-specific inputs incorporated ECHA preservative restriction phase-in schedules, MFDS fast-track pathway success rates, and cold-chain logistics cost elasticity by geography.
Caveats apply where ECHA REACH Annex VI amendment timing, ISO microbiome assay standardization mandates, or biobank licensing agreement renegotiations could materially shift the outlook. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegan Cosmetics
Mexico Vegan Cosmetics Market
Vegan Cosmetics
Australia Vegan Cosmetics Market
Vegan Cosmetics
US Vegan Cosmetics Market
Vegan Cosmetics
Italy Vegan Cosmetics Market
Vegan Cosmetics
Canada Vegan Cosmetics Market
Vegan Cosmetics
Argentina Vegan Cosmetics Market
Vegan Cosmetics
South Korea Vegan Cosmetics Market
Vegan Cosmetics
Chile Vegan Cosmetics Market
Vegan Cosmetics
Spain Vegan Cosmetics Market
Vegan Cosmetics
Functional Cosmetics Market
Vegan Cosmetics
Germany Vegan Cosmetics Market
Vegan Cosmetics
France Vegan Cosmetics Market
Vegan Cosmetics
Brazil Vegan Cosmetics Market
Vegan Cosmetics
Vegan Cosmetics Market
Vegan Cosmetics
Vegan Beauty Products Market
Vegan Cosmetics
Asia-Pacific Vegan Cosmetics Market