
 Vegan Face Cream Market | 2026-2036
Vegan Face Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Face Cream Market Insights
Subscription-based replenishment programs is pivoting how vegan face cream brands monetize customer relationships. Drunk Elephant leverages its skincare smoothie system to sustain high repeat-purchase rates. Pacifica Beauty anchors its market position through accessible price points and mass retail channel control.
Vegan face cream denotes a topical skincare formulation containing zero animal-derived ingredients, no animal byproducts, and no animal testing at any production stage, typically incorporating plant-based emollients such as squalane from sugarcane or bakuchiol as a retinol alternative. Its primary commercial purpose centers on delivering hydration, barrier repair, and anti-aging benefits to consumers who reject animal exploitation in personal care. Moisturizers dominate current revenue pools due to daily-use frequency and higher per-unit volumes, while serums capture disproportionate margin concentration through concentrated active formulations and premium positioning. Botanical ingredient sourcing leads volume demand, though fruit extracts represent the fastest-expanding category as brands compete on superfood narrative differentiation.
The EU Cosmetics Regulation and REACH framework mandate rigorous safety assessments without animal testing, effectively raising compliance barriers for non-vegan incumbents and accelerating clean-label transitions across European markets. The U.S. FDA maintains less prescriptive ingredient standards but California's Proposition 65 enforcement and the Federal Trade Commission's green marketing guidelines shape how brands communicate vegan claims to avoid litigation risk. Stakeholders must monitor evolving state-level cruelty-free legislation and third-party certification fragmentation as decisive variables for market access and consumer trust architecture.
Market Dynamics
Direct-to-consumer channel consolidation is restructuring how vegan face cream brands capture margin, with subscription mechanics displacing wholesale dependency as the dominant commercial architecture.
Growth Catalysts
- EU Cosmetics Regulation animal testing prohibition:The ban eliminates non-compliant competitors from European shelves, accelerating clean-label transitions and creating regulatory moats for certified vegan formulators.
- Bakuchiol extraction biotechnology:Advanced fermentation processes from sugarcane feedstocks are compressing retinol alternative production costs while preserving efficacy claims for sensitive-skin segments.
- California clean beauty cluster concentration:Los Angeles-based formulation labs and Santa Barbara ingredient suppliers are co-locating R&D with venture capital, shortening product development cycles.
Market Restraints
- Shea butter and squalane price volatility:West African supply disruptions and sugarcane harvest variability are compressing gross margins for mid-tier brands dependent on commodity plant emollients.
- Third-party certification fragmentation:Competing standards from Leaping Bunny, PETA, and Vegan Society create consumer confusion and duplicate compliance costs without unified market recognition.
- Preservative efficacy limitations:Plant-derived antimicrobial systems demonstrate shorter shelf stability versus synthetic parabens, constraining distribution reach and inventory turnover.
Strategic Opportunities
- Men's grooming vertical expansion:Underpenetrated male skincare adoption in Germany and the Netherlands offers first-mover positioning for gender-neutral vegan formulations.
- Refill and reuse packaging mandates:France's anti-gaspillage law and proposed EU Packaging Regulation are creating compliant infrastructure for circular business models ahead of enforcement.
- Biotechnology-plant extract convergence:Lab-grown ceramides combined with upcycled fruit waste streams enable novel texture profiles and carbon-negative sourcing narratives.
Industry Challenges
- Cosmetic chemist specialization scarcity:Formulation expertise bridging vegan ingredient compatibility with stability testing remains concentrated among legacy talent pools in France and the United States.
- Clean beauty litigation exposure:California Proposition 65 bounty hunter actions and FTC greenwashing enforcement are elevating compliance insurance costs and claim substantiation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Face Cream Market |
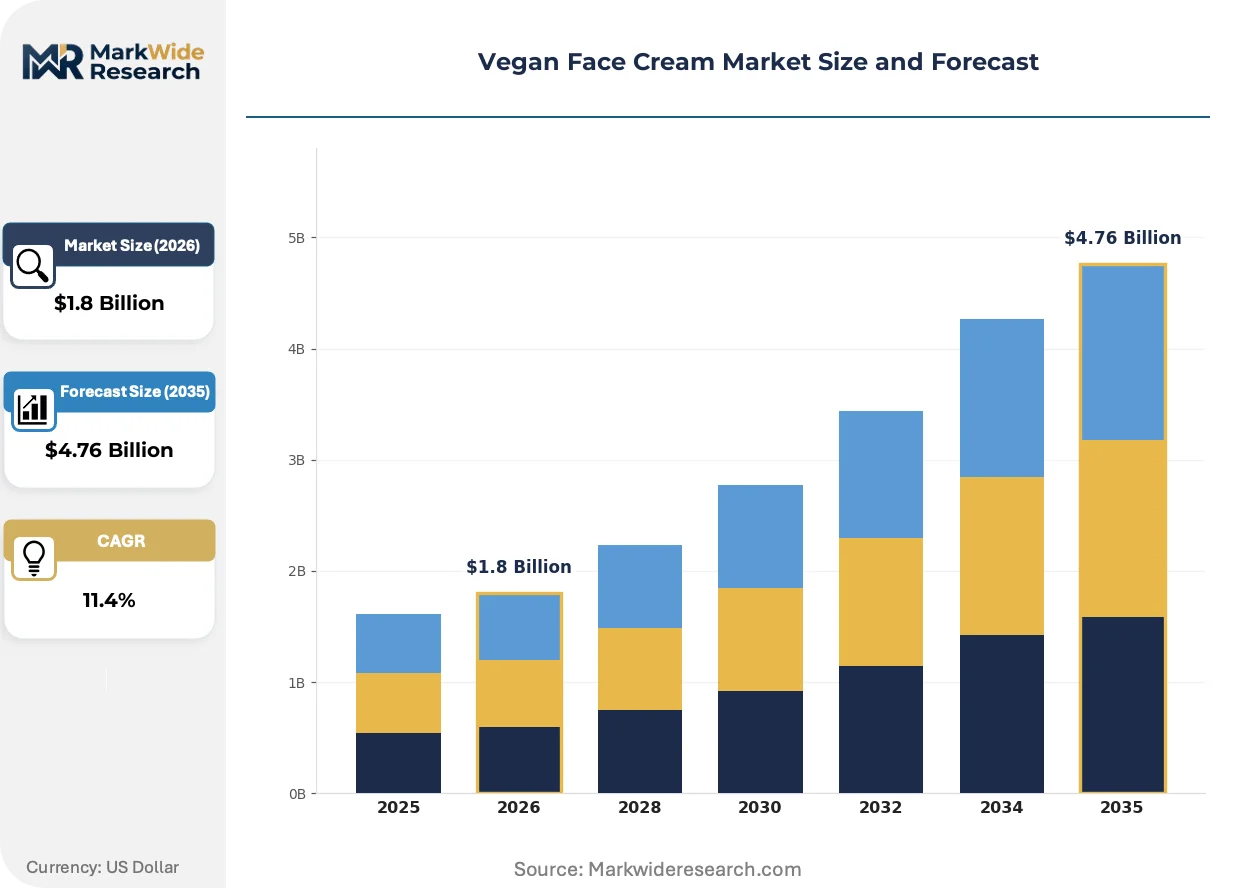
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Serums, Cleansers, Exfoliators Ingredient Source: Botanical, Fruit Extracts, Vegetable Oils, Minerals Packaging Type: Tubes, Jars, Pumps, Biodegradable End User: Women, Men, Teens, Professionals |
| Companies Covered | Drunk Elephant, Pacifica Beauty, Biossance, Tata Harper, Youth to the People, Herbivore, Pai Skincare, 100% Pure, Gabriel Cosmetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Face Cream Market Trends and Innovations
Biotechnology-derived actives and circular packaging systems are displacing conventional botanical extraction and single-use containers as the technical frontier for competitive differentiation.
Fermentation-based squalane production is decentralizing supply chain risk away from shark liver and olive oil dependencies. Gen Z skincare consumers in the United States and South Korea are adopting sugarcane-derived emollients at accelerated trial rates. This shift is compressing reliance on Mediterranean agricultural harvests while enabling year-round production consistency.
REACH framework updates and the EU Green Deal chemicals strategy are mandating stricter substance hazard classifications. Formulators must now document endocrine disruption screening for plant extracts previously assumed safe. Small and mid-size brands operating in Germany and the Netherlands are consolidating regulatory affairs functions to manage documentation burdens.
Subscription replenishment models are capturing recurring revenue from serum and moisturizer categories previously dominated by episodic retail purchases. Direct-to-consumer channels in California and New York are displacing Sephora and Ulta as primary discovery venues for trial-sized introductions. This behavioral pivot concentrates customer data ownership with brands while elevating logistics infrastructure requirements.
Vegan Face Cream Market Segmentation
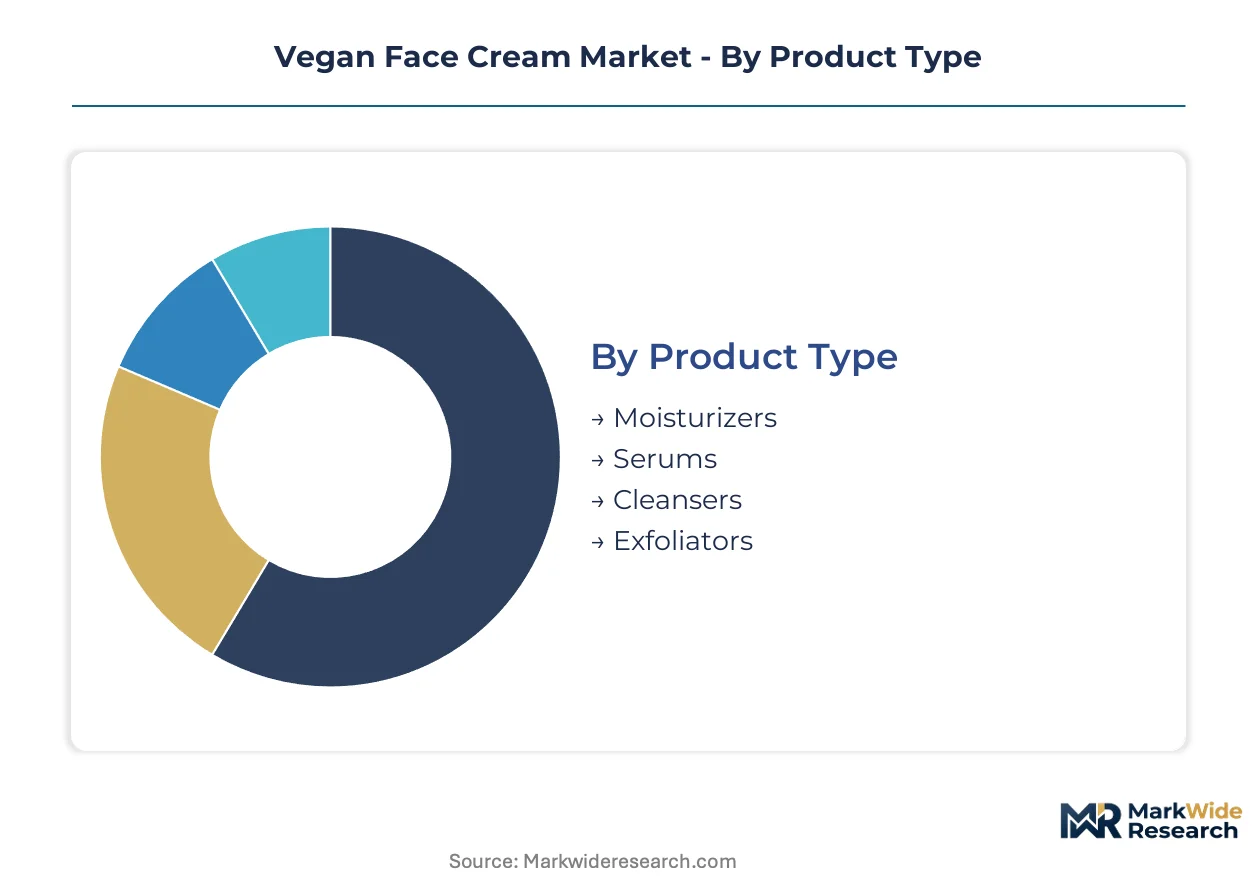
Vegan face cream segmentation reveals divergent margin architectures across formulation types and ingredient sourcing strategies. Product categories with daily-use frequency command volume concentration, while concentrated actives and premium packaging formats capture disproportionate value per unit.
Product Type:
Moisturizers function as standalone daily-use staples with the highest replenishment velocity, while serums operate as embedded treatment layers within multi-step routines.
- Moisturizers:These formulations combine plant-derived emollients like squalane and shea butter with barrier-repair ceramides from fermentation processes. Demand clusters in the United States and Germany where subscription replenishment models sustain repeat purchase cycles.
- Serums:Concentrated active delivery systems featuring bakuchiol, vitamin C from kakadu plum, or peptides from yeast fermentation command premium positioning. South Korean consumers and California's clean beauty cluster drive adoption of these higher-margin treatment products.
- Cleansers:Gentle surfactant systems derived from coconut glucosides or sugar beets form the routine entry point for vegan skincare converts.
- Exfoliators:Physical scrubs utilizing upcycled fruit seeds or enzymatic peels from papaya and pineapple extracts serve occasional-use treatment needs.
Volume placements concentrate in Moisturizers; the faster expansion belongs to Serums.
Ingredient Source:
Cost tier stratification separates commodity botanicals from biotechnology-enhanced extracts, with upcycled and lab-grown ingredients commanding manufacturing investment premiums.
- Botanical:Traditional plant extracts from aloe vera, chamomile, and calendula dominate mass-market formulations. Supply reliability challenges from climate-dependent harvests in Morocco and Egypt constrain margin stability for mid-tier brands.
- Fruit Extracts:Superfood-positioned actives from pomegranate, dragon fruit, and sea buckthorn enable narrative differentiation. South Korean and Australian brands leverage native fruit biodiversity for proprietary positioning.
- Vegetable Oils:Cold-pressed marula, rosehip, and jojoba oils provide emollient bases across price tiers.
- Minerals:Zinc oxide, magnesium, and silica derivatives support non-nano sun protection and mattifying functions in hybrid products.
Manufacturing scale clusters around Botanical sourcing; Fruit Extracts are climbing the fastest among ingredient investments.
Packaging Type:
Application method determines preservation requirements and consumer convenience expectations, with airless systems and refillable formats reshaping sustainability compliance costs.
- Tubes:Collapsible aluminum and sugarcane-derived bioplastic tubes suit travel-size and sampling formats. French and German regulatory pressure on single-use plastics is accelerating material transition costs.
- Jars:Wide-mouth glass containers with aluminum lids dominate premium positioning despite finger-dip contamination risks. California and New York premium retail corridors favor this format for shelf presence.
- Pumps:Airless dispensing systems extend shelf stability for antioxidant-rich formulations without synthetic preservatives.
- Biodegradable:Mushroom mycelium and seaweed-based packaging align with France's anti-gaspillage law and proposed EU Packaging Regulation mandates.
Current manufacturing capacity centers on Tubes; steepest expansion trajectory belongs to Biodegradable formats.
End User:
Customer type segmentation maps distinct routine complexity and price sensitivity profiles, with professional and male segments presenting underdeveloped addressable markets.
- Women:Established category participants with sophisticated multi-step routines spanning all product types. The United States and United Kingdom concentrate highest per-capita spending on premium vegan formulations.
- Men:Simplified routine preferences favor all-in-one moisturizers with subtle fragrance profiles. Germany and the Netherlands show accelerating trial rates for gender-neutral positioning.
- Teens:Acne-focused formulations with clean-label positioning target first skincare purchase decisions influenced by social media discovery.
- Professionals:Time-constrained urban consumers in Seoul, London, and New York prioritize portable formats and rapid-absorption textures for pre-work application.
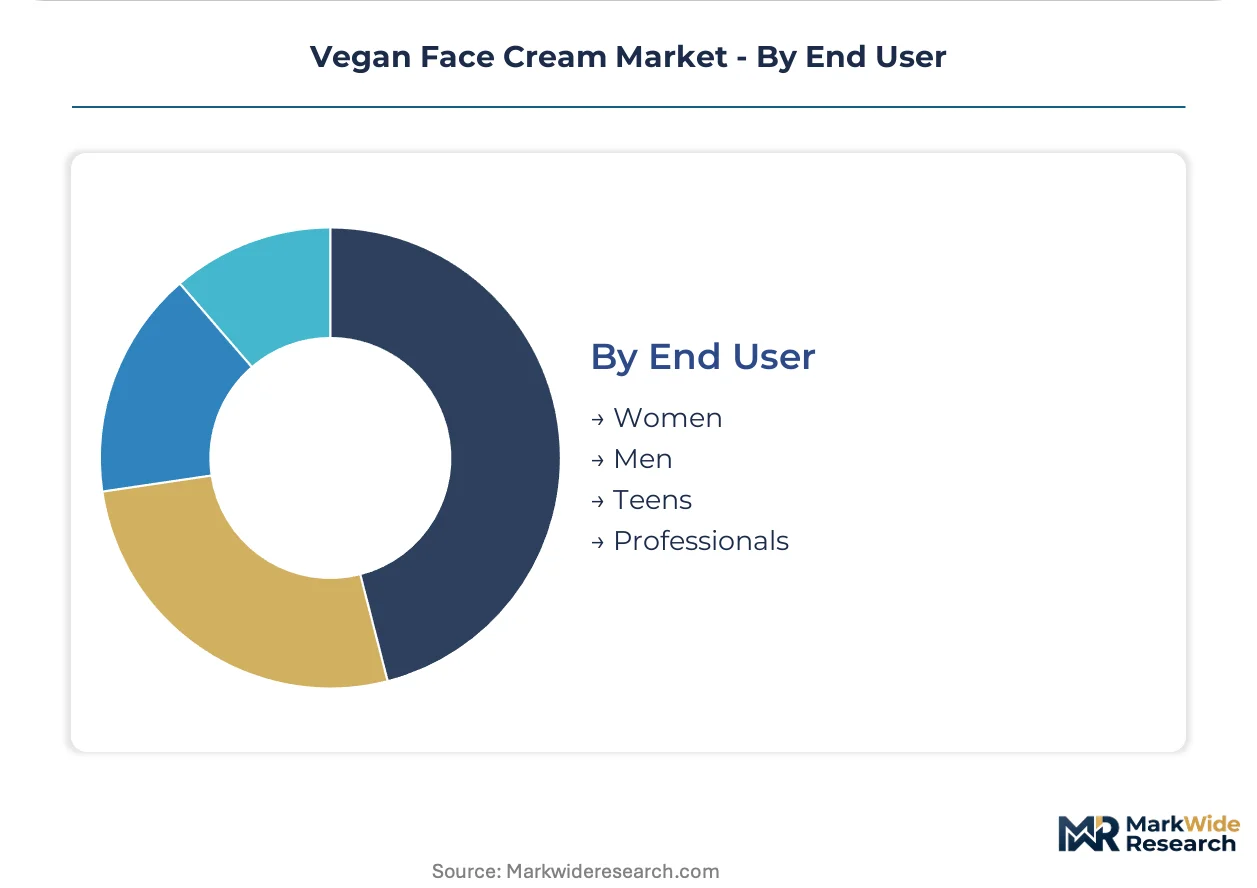
Revenue concentration remains with Women; Men represent the most rapid adoption acceleration among user categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors formulation innovation through its clean beauty cluster, where venture capital co-locates with R&D labs to compress product development cycles for vegan face cream brands.
United States
Gen Z and millennial consumers drive direct-to-consumer channel adoption through subscription replenishment mechanics. California's Proposition 65 enforcement and the FTC's green marketing guidelines shape vegan claim substantiation requirements. New York's premium retail corridor concentrates discovery venues for trial-sized serum introductions.
Germany
Men's grooming verticals show accelerating trial rates for gender-neutral vegan formulations in Berlin and Hamburg metropolitan areas. REACH framework updates mandate endocrine disruption screening for plant extracts previously assumed safe. Small and mid-size brands consolidate regulatory affairs functions in Frankfurt to manage documentation burdens.
France
Anti-gaspillage law mandates create compliant infrastructure for refill and reuse packaging ahead of broader EU enforcement. ANSM oversight of cosmetic safety assessments elevates preservative efficacy documentation requirements. Paris-based formulation houses specialize in airless dispensing systems for antioxidant-rich vegan serums.
South Korea
Seoul consumers adopt sugarcane-derived squalane emollients at accelerated trial rates, compressing reliance on Mediterranean agricultural harvests. MFDS cosmetic safety regulations align with EU Cosmetics Regulation standards on animal testing prohibitions. Busan-Ulsan corridor concentrates fermentation biotechnology facilities for lab-grown ceramide production.
United Kingdom
Post-Brexit regulatory divergence creates dual compliance tracks for brands serving EU and UK markets simultaneously. London concentrates per-capita spending on premium vegan formulations among established female category participants. Manchester and Birmingham logistics hubs support direct-to-consumer fulfillment infrastructure for subscription mechanics.
Vegan Face Cream Market Competitive Landscape
Capital-heavy producers compete with asset-light designers as biotechnology laboratories and contract manufacturers enable brand launches without captive production facilities. The vendor base spans venture-backed direct-to-consumer specialists, heritage clean beauty houses, and mass-market retail anchors. Three archetypes dominate: fermentation-technology formulators, superfood-narrative differentiators, and subscription-mechanics operators. Competitive moves concentrate on strategic partnerships with ingredient biotechnology firms and portfolio diversification into men's grooming verticals.
Within the biotechnology-formulator tier, Biossance exemplifies sugarcane-fermentation squalane production, while Drunk Elephant occupies a position anchoring the skincare smoothie subscription system. Pacifica Beauty sits within the mass-retail accessible price-point archetype. These three entities represent divergent margin-capture strategies across premium, standard, and economy tier positioning without overlapping customer acquisition channels.
| Leading Market Players |
|---|
| Drunk Elephant |
| Pacifica Beauty |
| Biossance |
| Tata Harper |
| Youth to the People |
| Herbivore |
| Pai Skincare |
| 100% Pure |
| Gabriel Cosmetics |
| Others |
Pricing and Supply Chain Analysis
Subscription-program participants in the direct-to-consumer channel anchor pricing power for vegan face cream brands, compressing wholesale-dependent competitors into reactive discounting cycles. California's clean beauty cluster and New York's premium retail corridor concentrate buyer leverage, while mid-tier mass-market entrants face margin erosion from commodity ingredient volatility.
Pricing Analysis
Certification-grade value-based pricing anchors the vegan face cream market, with Leaping Bunny and Vegan Society tiers commanding substantial premiums over uncertified alternatives. Price differentiation separates fermentation-derived biotechnology formulations from commodity botanical extracts, with the former capturing margin concentration through efficacy claims. Cost compression in the mid-tier intensifies because West African shea butter supply disruptions and sugarcane harvest variability feed raw material volatility. Mass-market consumers demonstrate highest price sensitivity, while premium segment buyers prioritize provenance transparency over per-unit cost.
Supply Chain Analysis
Squalane supply rests on Brazilian sugarcane fermentation facilities and Mediterranean olive oil processors, with emerging capacity in South Korean biotech corridors. Bakuchiol extraction draws from Indian babchi seed cultivation and advanced yeast fermentation in German pharmaceutical-grade facilities. Single-source vulnerability concentrates in West African shea butter cooperatives, where climate-dependent harvests and political instability threaten emollient availability. Distribution runs through direct-to-consumer subscription platforms and Sephora-Ulta retail networks, with refill infrastructure emerging in France and Germany ahead of EU Packaging Regulation enforcement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vegan face cream market operates as a vertical-integration race, with fermentation-technology control over squalane and ceramide supply emerging as the decisive upstream lever for margin defense.
For Market Incumbents: To counter biotechnology-entrant disruption, incumbents must secure captive supply of sugarcane-derived squalane through backward integration into Brazilian fermentation partnerships. Certification investment in unified Vegan Society standards reduces compliance duplication costs while building consumer trust architecture against fragmented third-party label confusion. For New Entrants and Emerging Players: The EU Cosmetics Regulation animal testing prohibition in Europe opens a window for clean-label positioning without legacy reformulation burdens. Germany and the Netherlands present the most penetrable geography for gender-neutral men's grooming verticals, with minimalist routine formats enabling rapid trial conversion through direct-to-consumer sampling programs. For Investors and Strategic Acquirers: The window for entry favors fermentation-technology specialists with lab-grown ceramide capabilities and established sugarcane feedstock relationships. Long-term viability hinges on circular packaging infrastructure compliance ahead of France's anti-gaspillage law expansion. Biotechnology-plant extract convergence velocity serves as the critical signal to watch for category inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive squalane supply from Brazilian sugarcane feedstock compresses cost volatility exposure. |
| Unified Certification Investment | Vegan Society standard consolidation reduces duplicate compliance burdens across EU and UK markets. |
| Men's Grooming Vertical Launch | Gender-neutral positioning in Berlin and Hamburg metropolitan areas captures underpenetrated trial demand. |
| Refill Infrastructure Deployment | France's anti-gaspillage law compliance creates first-mover circular packaging advantage. |
| Biotechnology R&D Partnership | Lab-grown ceramide collaboration with Busan-Ulsan fermentation facilities enables novel texture profiles. |
Research Methodology
Independent corroboration across cosmetic chemist interviews, brand formulation director consultations, and retail category buyer assessments underwrites the qualitative findings in this study. Primary fieldwork engaged R&D leads at clean beauty clusters in California and New York, regulatory affairs managers navigating REACH and FDA frameworks, and supply chain planners at sugarcane fermentation facilities. Secondary validation incorporated EU Cosmetics Regulation documentation, ANSM safety assessment filings, customs records for shea butter and squalane trade flows, and Nielsen retail audit data for subscription versus wholesale channel velocity. Bottom-up segmentation modeling and top-down market sizing triangulate volume and value estimates.
Rate-of-change decomposition across the analysis window separates volume expansion from price-mix effects, with segment-specific CAGRs derived from adoption curve modeling and replacement cycle dynamics. The forecast framework incorporates product type segmentation (moisturizers, serums, cleansers, exfoliators), ingredient sourcing strategy (botanical, fruit extracts, vegetable oils, biotechnology-derived), packaging format compliance costs, and end-user archetype penetration rates. Fermentation capacity buildout timelines and EU Packaging Regulation enforcement phasing serve as critical model inputs.
The model assumes a particular technology adoption path; alternative pathways for lab-grown ceramide production at commercial scale would alter the outlook. Forecasts reflect assumptions about regulatory harmonization between EU and UK post-Brexit frameworks, sugarcane harvest stability, and consumer willingness-to-pay for certification tiers. Biotechnology cost curves, men's grooming vertical acceptance velocity, and refill infrastructure rollout pace constitute the small set of triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegan Cosmetics
Functional Cosmetics Market
Vegan Cosmetics
Asia-Pacific Vegan Cosmetics Market
Vegan Cosmetics
Organic Cosmetics Market
Vegan Cosmetics
Italy Vegan Cosmetics Market
Vegan Cosmetics
US Vegan Cosmetics Market
Vegan Cosmetics
Australia Vegan Cosmetics Market
Vegan Cosmetics
Canada Vegan Cosmetics Market
Vegan Cosmetics
Brazil Vegan Cosmetics Market
Vegan Cosmetics
Vegan Beauty Products Market
Vegan Cosmetics
Vegan Cosmetics Market
Vegan Cosmetics
China Vegan Cosmetics Market
Vegan Cosmetics
Europe Vegan Cosmetics Market
Vegan Cosmetics
Germany Vegan Cosmetics Market
Vegan Cosmetics
South Korea Vegan Cosmetics Market
Vegan Cosmetics
Spain Vegan Cosmetics Market
Vegan Cosmetics
Chile Vegan Cosmetics Market