
 US Vegan Cosmetics Market | 2026-2036
US Vegan Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
US Vegan Cosmetics Market Insights
Gen Z buyers are redrawing the US vegan cosmetics landscape as their preference for ingredient transparency and digital-first discovery displaces traditional department-store loyalty. e.l.f. Beauty leverages mass-market accessibility and TikTok-native marketing to sustain volume leadership. ILIA Beauty anchors the clean-luxury tier with hybrid skincare-makeup formulations. Pacifica Beauty competes through cruelty-free certification and accessible price positioning.
US vegan cosmetics encompass beauty and personal care products formulated without animal-derived ingredients, animal testing, or by-products such as beeswax, carmine, or collagen substitutes, typically relying on plant-based emollients, synthetic peptides, and mineral pigments for functional performance. The primary commercial purpose centers on serving ethically motivated consumers while meeting dermatological efficacy benchmarks comparable to conventional alternatives. Skincare leads product type revenue contribution due to higher per-unit pricing and repeat purchase frequency, while fragrance represents the fastest-expanding category as indie houses pioneer alcohol-free, botanical-based compositions. Specialty stores capture disproportionate margin pools through curated assortments and educated staff, though online channels extend reach into secondary markets.
The FDA oversees cosmetic ingredient safety under the Modernization of Cosmetics Regulation Act, while California's Proposition 65 and Safer Consumer Products regulations impose stricter substance disclosure than federal minimums, effectively setting the compliance ceiling for national brands. The FTC monitors greenwashing claims, forcing brands to substantiate vegan and cruelty-free assertions with supply chain documentation. Stakeholders must monitor state-level chemical restriction expansions and evolving FTC guidance on environmental marketing to anticipate compliance cost trajectories.
Market Dynamics
Gen Z purchasing power is compressing traditional brand loyalty cycles while California's ingredient disclosure mandates force nationwide formula reformulation costs onto mid-tier manufacturers.
Growth Catalysts
- Modernization of Cosmetics Regulation Act:The FDA's expanded post-market surveillance authority accelerates ingredient safety documentation, rewarding brands with established supply chain transparency.
- Plant-derived emollients:Squalane from olive and sugarcane sources achieves parity with shark-derived alternatives in stability testing, removing performance barriers for prestige skincare.
- Los Angeles cluster:Indie formulators concentrate in the Atwater Village corridor, creating knowledge spillover effects that reduce R&D iteration costs for adjacent entrants.
Market Restraints
- Mica supply concentration:Ethically sourced mineral pigment procurement depends on limited Madagascar and Jharkhand mine certifications, creating batch-to-batch color variance risks.
- Beeswax substitution cost:Candelilla and carnauba wax blends require 40% higher loading levels to achieve equivalent emulsion stability in lip products.
- California Proposition 65:The state's expanding chemical warning list forces reformulation of preservative systems ahead of federal timelines, fragmenting national SKU strategies.
Strategic Opportunities
- Men's grooming vertical:Underpenetrated beard care and scalp treatment categories in Texas and Florida metro areas offer first-mover positioning for gender-neutral vegan positioning.
- Refill station partnerships:Specialty retailers in Chicago and Seattle pilot in-store bulk dispensing, cutting packaging costs while capturing recurring foot traffic.
- USDA BioPreferred program:Federal procurement preference for biobased content creates institutional sales channels for plant-derived surfactant suppliers.
Industry Challenges
- Cosmetic chemist specialization:Formulators with dual expertise in plant lipid chemistry and scale-up manufacturing command premium compensation that strains emerging brand burn rates.
- Leaping Bunny audit timelines:Cruelty-free certification requires 12-18 month supply chain documentation cycles that delay product launch windows.
- ERP integration:Legacy inventory systems at contract manufacturers struggle to segregate vegan-certified production lines from conventional batch runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Vegan Cosmetics Market |
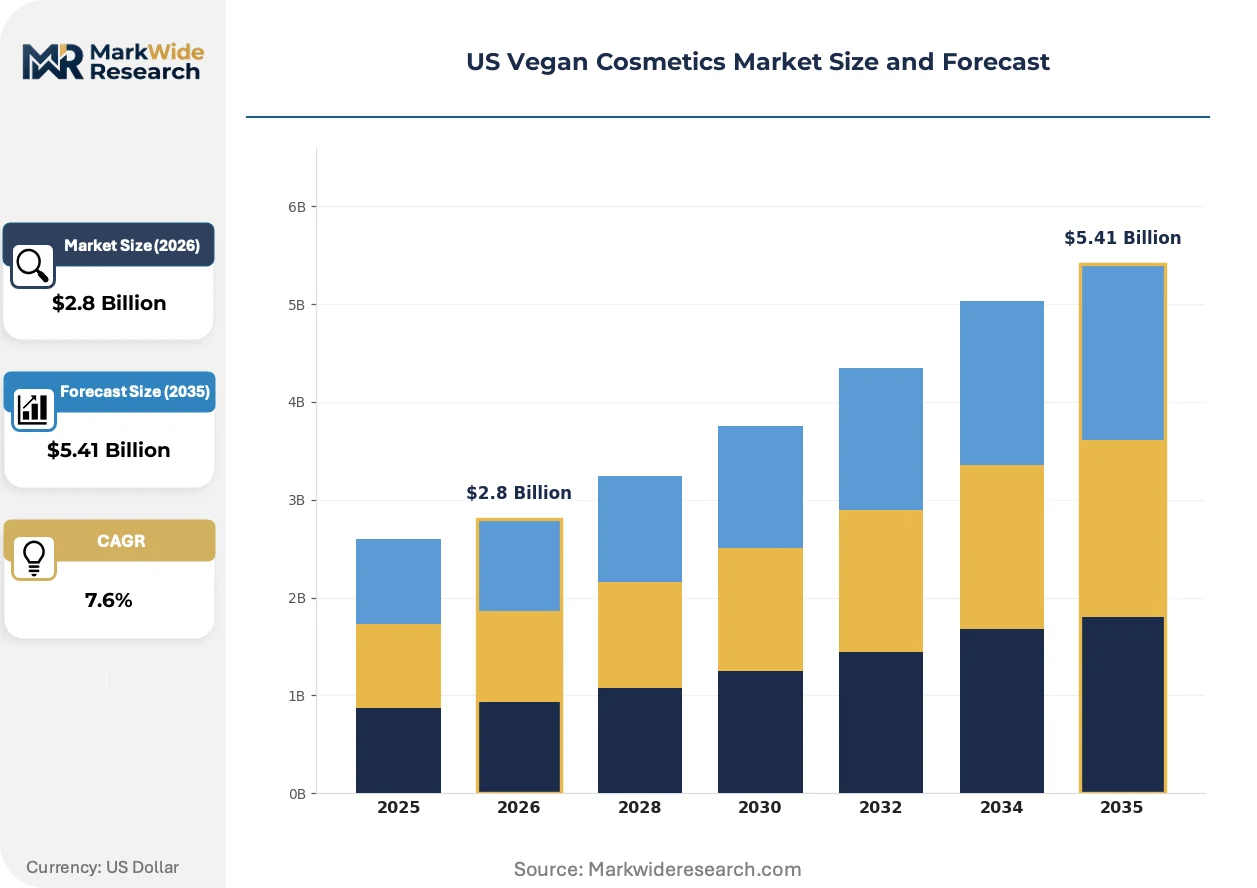
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Makeup, Skincare, Haircare, Fragrance Distribution Channel: Online, Specialty Stores, Drugstores, Department Stores Customer Type: Millennials, Gen Z, Eco-conscious Consumers, Luxury Shoppers Brand Positioning: Premium, Mass Market, Indie Brands, Established Brands |
| Companies Covered | e.l.f. Beauty, ILIA Beauty, Pacifica Beauty, Milk Makeup, Herbivore Botanicals, Rare Beauty, KVD Beauty, Saie, Tower 28 Beauty, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Vegan Cosmetics Market Trends and Innovations
Biofermentation-derived actives are collapsing the cost-performance tradeoff that historically separated vegan formulations from conventional efficacy benchmarks. Synthetic biology suppliers now compete directly with agricultural commodity markets.
Fermentation-produced ceramides and peptides are fragmenting the ingredient sourcing landscape. Gen Z buyers in New York and Los Angeles specialty channels prioritize these lab-grown alternatives for their supply chain traceability. The technology is fragmenting procurement relationships between finished goods brands and traditional agricultural suppliers.
California's Safer Consumer Products regulations are forcing national brands to eliminate per- and polyfluoroalkyl substances from waterproof mascara and long-wear foundation lines. The industrial consequence is a scramble for silicone-free film-forming polymers that meet performance benchmarks. Prestige color cosmetics manufacturers are responding by accelerating partnerships with Japanese specialty chemical suppliers.
Subscription box curation is displacing department store counter discovery for millennial and Gen Z buyers. Ipsy and Birchbox algorithms prioritize vegan certification badges in their matching engines, redirecting sampling budgets toward direct-to-consumer brands. The shift is most visible in secondary metro areas where specialty retail penetration remains thin.
US Vegan Cosmetics Market Segmentation
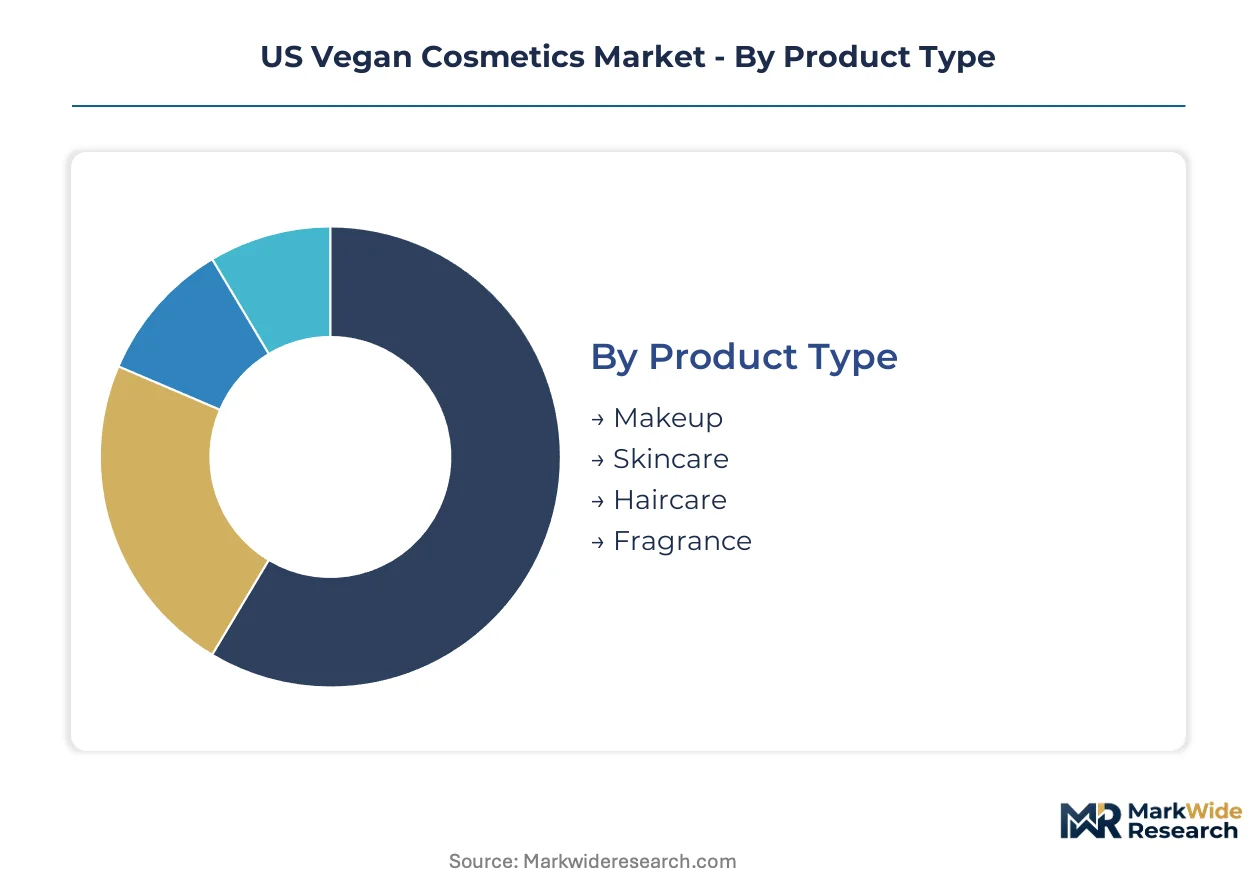
Vegan cosmetics segmentation reveals how ethical positioning intersects with price tolerance and channel preference across US consumer cohorts. Understanding these divides allows brands to allocate R&D and marketing resources against measurable purchase triggers rather than aspirational identity claims.
Product Type:
Skincare and makeup formulations dominate domestic manufacturing capacity, while fragrance relies more heavily on imported botanical alcohol bases and European compound houses.
- Skincare:Serums and moisturizers leverage plant-derived squalane and fermented ceramides to match conventional occlusion benchmarks. California formulators in Los Angeles and San Francisco drive concentration, with FDA Modernization of Cosmetics Regulation Act compliance costs favoring established documentation systems.
- Makeup:Color cosmetics substitute candelilla and carnauba waxes for beeswax in lip and eye products, requiring higher loading levels that elevate per-unit costs. New York specialty retail channels absorb this premium through educated staff who justify price deltas against performance claims.
- Haircare:Silicon-free conditioners and scalp treatments utilize quaternized plant proteins for detangling performance.
- Fragrance:Alcohol-free botanical compositions expand fastest as indie houses pioneer water-based extraction methods.
Skincare holds the largest share; momentum sits with fragrance.
Distribution Channel:
Channel selection determines margin capture versus scale tradeoffs, with digital-native routes compressing customer acquisition costs for emerging brands.
- Online:Direct-to-consumer platforms and TikTok-native discovery engines enable precise targeting of Gen Z buyers. Subscription algorithms prioritize vegan certification badges, redirecting sampling budgets from department store counters toward data-rich digital funnels.
- Specialty Stores:Curated assortments in New York, Los Angeles, and Chicago command disproportionate margin pools through educated staff and experiential merchandising. These locations justify premium positioning through ingredient storytelling and tester accessibility.
- Drugstores:Mass-market accessibility depends on e.l.f. Beauty and similar volume leaders who compress unit economics through scale manufacturing partnerships.
- Department Stores:Legacy counter models face displacement as millennial and Gen Z loyalty fragments toward digital discovery.
Online channels are climbing the fastest; specialty retail maintains margin leadership.
Customer Type:
Generational divides in discovery behavior and price elasticity reshape how brands architect product hierarchies and communication strategies.
- Gen Z:Digital-first discovery through TikTok and Instagram displaces traditional advertising, with ingredient transparency demands forcing supply chain documentation. This cohort compresses brand loyalty cycles and rewards authentic cruelty-free certification over aspirational positioning.
- Millennials:Subscription box curation via Ipsy and Birchbox algorithms prioritizes sampling efficiency, with vegan badges serving as filtering mechanisms in thin specialty retail markets like secondary Texas and Florida metros.
- Eco-conscious Consumers:USDA BioPreferred program awareness drives procurement preference for biobased surfactant content.
- Luxury Shoppers:Hybrid skincare-makeup formulations from clean-luxury tiers justify premium pricing through dermatological efficacy benchmarks.
Gen Z captures the steepest expansion trajectory; millennials anchor current revenue concentration.
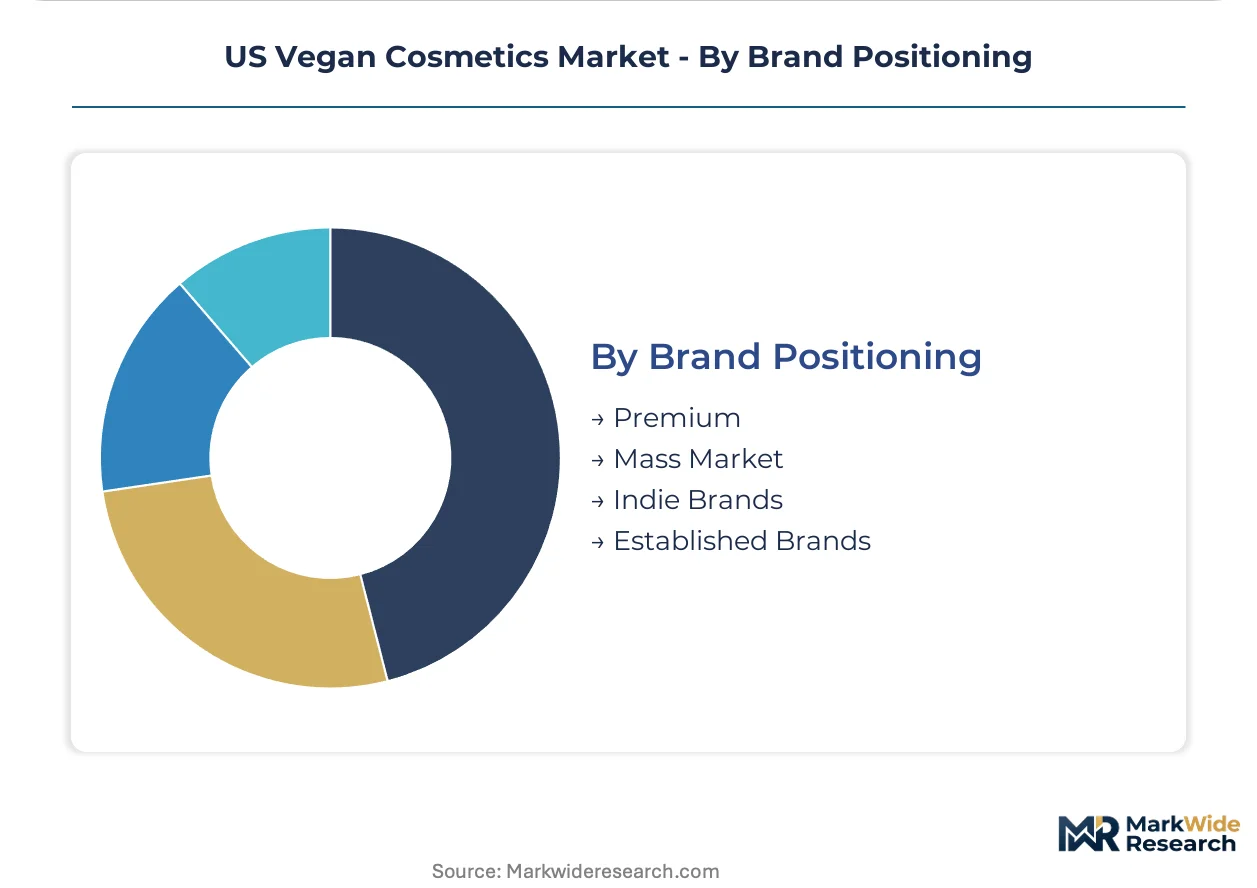
Brand Positioning:
Positioning tier determines manufacturing partnerships, with premium and mass-market routes diverging sharply in contract manufacturer selection and certification requirements.
- Premium:Clean-luxury tiers utilize Japanese specialty chemical suppliers for silicone-free film-forming polymers meeting California Safer Consumer Products regulations. These formulations command specialty retail placement and justify per-unit pricing through hybrid skincare-makeup positioning.
- Mass Market:Volume accessibility depends on mass-market manufacturing scale and TikTok-native marketing efficiency. e.l.f. Beauty sustains leadership through compressed price points that democratize vegan certification access.
- Indie Brands:Atwater Village corridor concentration in Los Angeles reduces R&D iteration costs through knowledge spillover effects among adjacent formulators.
- Established Brands:Legacy players face SKU fragmentation as California Proposition 65 chemical warning list expansions force preservative reformulation ahead of federal timelines.
Mass market holds volume dominance; indie brands are gaining share fastest through specialty channel penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulator talent and contract manufacturing capacity concentrate in coastal metropolitan corridors, with FDA Modernization of Cosmetics Regulation Act compliance costs favoring established documentation systems in California and New York.
California
Los Angeles anchors domestic vegan cosmetics manufacturing through the Atwater Village indie formulator cluster. Proposition 65 and Safer Consumer Products regulations impose stricter chemical disclosure than federal minimums, forcing national brands to reformulate preservative systems ahead of nationwide timelines. San Francisco and San Diego house biotech-derived active ingredient suppliers serving prestige skincare lines.
New York
Specialty retail concentration in Manhattan and Brooklyn commands disproportionate margin pools through educated staff and experiential merchandising. The state's Department of Environmental Conservation oversees chemical reporting that overlaps with California standards. Indie brand headquarters cluster in Williamsburg and Greenpoint, leveraging proximity to beauty media and influencer networks.
Texas
Dallas and Houston metro areas present underpenetrated demand for men's grooming vegan extensions, particularly beard care and scalp treatment categories. The Texas Commission on Environmental Quality regulates cosmetic manufacturing emissions with lighter compliance burdens than coastal states. Austin's tech workforce generates secondary demand for direct-to-consumer digital discovery channels.
Illinois
Chicago pilots refill station partnerships in specialty retail, cutting packaging costs while capturing recurring foot traffic. The Illinois Environmental Protection Agency administers chemical reporting requirements that align with broader Midwest manufacturing standards. Contract manufacturers in the broader Great Lakes region serve mass-market brands seeking central logistics positioning.
Florida
Miami and Tampa metro areas show expanding Gen Z demand for digital-native vegan brands, with subscription box penetration filling specialty retail gaps. The Florida Department of Agriculture and Consumer Services oversees cosmetic labeling requirements. Orlando's tourism economy creates seasonal demand spikes for travel-sized vegan formulations.
US Vegan Cosmetics Market Competitive Landscape
Concentration sits with mass-market digital-native players and clean-luxury indie specialists, creating a bifurcated structure where volume leadership and margin capture follow distinct operational models. The competitive terrain splits between TikTok-optimized accessibility and specialty-channel prestige positioning. Three archetypes dominate: mass-market scale operators, clean-luxury hybrid formulators, and indie cruelty-free certifiers. Dominant competitive moves include TikTok-native marketing efficiency and silicone-free polymer partnerships with Japanese specialty chemical suppliers.
Within the mass-market tier, e.l.f. Beauty exemplifies volume accessibility through compressed price points and algorithmic discovery optimization. ILIA Beauty and Pacifica Beauty anchor the clean-luxury and cruelty-free certification vectors respectively, representing how hybrid skincare-makeup positioning and accessible ethical claims capture divergent consumer segments. These three companies illustrate the strategic archetypes reshaping channel allocation and R&D prioritization across the domestic market.
| Leading Market Players |
|---|
| e.l.f. Beauty |
| ILIA Beauty |
| Pacifica Beauty |
| Milk Makeup |
| Herbivore Botanicals |
| Rare Beauty |
| KVD Beauty |
| Saie |
| Tower 28 Beauty |
| Others |
Pricing and Supply Chain Analysis
Twelve-to-eighteen-month Leaping Bunny certification timelines compress working capital cycles for emerging brands, concentrating pricing power with established players who amortize compliance costs across larger SKU portfolios while forcing newer entrants into premium positioning or margin sacrifice.
Pricing Analysis
California Proposition 65 dictates the pricing tier structure by forcing preservative reformulation costs onto national brands ahead of federal timelines. Three-tier pricing structure across premium, standard, and economy levels separates clean-luxury hybrid formulators from mass-market volume leaders and indie cruelty-free certifiers. Price differentiation rests on certification grade and brand premium, with silicone-free polymer partnerships commanding specialty retail placement. Cost compression in the mass tier is intensifying because TikTok-native marketing efficiency demands continuous sampling spend. Gen Z buyers show highest price sensitivity, while luxury shoppers absorb premium deltas for dermatological efficacy benchmarks.
Supply Chain Analysis
Ninety-day mica certification cycles from Madagascar and Jharkhand mines create inventory volatility that propagates through color cosmetics manufacturing. Raw material procurement draws from Brazilian carnauba wax plantations, Japanese specialty chemical suppliers, and Korean fermentation-derived active facilities. Component dependencies center on plant-derived squalane, candelilla wax blends, and biofermentation-produced ceramides. Single-source vulnerability in ethically sourced mineral pigments threatens batch-to-batch color consistency. Distribution runs through specialty retail flagships in New York and Los Angeles, direct-to-consumer platforms, and subscription box algorithms that prioritize vegan certification badges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic biology-derived actives pose a substitution threat to agricultural commodity sourcing, forcing incumbents to defend plant-based positioning against lab-grown alternatives that collapse cost-performance tradeoffs.
For Market Incumbents: Fortify supply chain transparency through backward integration into fermentation-derived active production or captive squalane sourcing partnerships. Accelerate documentation systems for FDA Modernization of Cosmetics Regulation Act compliance to extend lead times over emerging competitors. Channel control through refill station partnerships in Chicago and Seattle captures recurring foot traffic while building switching costs. For New Entrants and Emerging Players: Leaping Bunny certification fast-track programs in the Atwater Village corridor reduce time-to-market for indie formulators seeking cruelty-free positioning. Target men's grooming verticals in Dallas and Houston metros where beard care and scalp treatment categories remain underpenetrated. Go-to-market through TikTok-native discovery engines enables precise Gen Z targeting without specialty retail gatekeeping. For Investors and Strategic Acquirers: Long-term, this sits as a certification-arbitrage play because regulatory fragmentation between California and federal standards creates persistent compliance moats for documented supply chains. Acquisition targets should demonstrate established Leaping Bunny or PETA Cruelty-Free certification with scalable contract manufacturing relationships. The signal to watch is FTC greenwashing enforcement intensity, which would accelerate consolidation toward brands with defensible supply chain documentation.| Strategic Initiative | Industry Significance |
|---|---|
| Silicone-Free Polymer Partnership | Japanese specialty chemical supplier alliances enable California Safer Consumer Products compliance for prestige color cosmetics. |
| Refill Station Pilot Program | Chicago and Seattle specialty retail partnerships cut packaging costs while capturing recurring foot traffic and loyalty data. |
| Fermentation-Derived Active Investment | Biofermentation capabilities collapse cost-performance gaps against conventional formulations while improving supply chain traceability. |
| Men's Grooming Line Extension | Beard care and scalp treatment launches in Texas and Florida metros exploit underpenetrated demand for gender-neutral vegan positioning. |
| Direct-to-Consumer Platform Buildout | TikTok-native discovery engines reduce customer acquisition costs for Gen Z buyers while bypassing specialty retail margin capture. |
Research Methodology
Cross-validation between primary interviews with cosmetic formulators, specialty retail buyers, and contract manufacturing executives anchors the qualitative findings against secondary validation from FDA Modernization of Cosmetics Regulation Act filings, California Safer Consumer Products regulatory updates, and customs records for plant-derived emollient imports. Bottom-up and top-down triangulation reconciles SKU-level production data with channel shipment estimates across online, specialty retail, and mass-market routes.
Sensitivity analysis across the projection horizon tests demand elasticity for premium versus mass-market positioning, regulatory compliance cost trajectories, and raw material substitution scenarios. Segmentation dimensions modeled include product type, distribution channel, customer cohort, and brand positioning tier. CAGRs derive from historical trajectory analysis adjusted for Gen Z purchasing power inflection and biofermentation technology adoption curves. Forecast inputs incorporate California chemical warning list expansion schedules and FTC greenwashing enforcement patterns.
Decision-makers should treat outputs as directional under sustained Gen Z demand growth and stable mica supply certification capacity; material deviation in either assumption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegan Cosmetics
Canada Vegan Cosmetics Market
Vegan Cosmetics
Spain Vegan Cosmetics Market
Vegan Cosmetics
Vegan Face Cream Market
Vegan Cosmetics
Vegan Beauty Products Market
Vegan Cosmetics
India Vegan Cosmetics Market
Vegan Cosmetics
Mexico Vegan Cosmetics Market
Vegan Cosmetics
Argentina Vegan Cosmetics Market
Vegan Cosmetics
Germany Vegan Cosmetics Market
Vegan Cosmetics
Europe Vegan Cosmetics Market
Vegan Cosmetics
Italy Vegan Cosmetics Market
Vegan Cosmetics
South Korea Vegan Cosmetics Market
Vegan Cosmetics
Asia-Pacific Vegan Cosmetics Market
Vegan Cosmetics
Australia Vegan Cosmetics Market
Vegan Cosmetics
Vegan Cosmetics Market
Vegan Cosmetics
China Vegan Cosmetics Market
Vegan Cosmetics
France Vegan Cosmetics Market