
 Global Personal Care Emollients Market | 2026-2036
Global Personal Care Emollients Market Size, Share, and Industry Trends Forecast 2026-2036
Global Personal Care Emollients Market Intelligence
A shift from single-source to multi-source procurement for key ester and natural oil feedstocks is restructuring supplier relationships. This move aims to de-risk supply chains against raw material price volatility and regional disruptions. BASF SE leverages its extensive production network to offer a broad portfolio of both synthetic and natural-based emollients. Croda International Plc specializes in sustainable, plant-derived ingredients, while Evonik Industries AG competes on specialized silicone technologies for high-performance cosmetics.
Personal care emollients are functional ingredients that soften skin and hair by forming a layer to reduce moisture loss. These materials, which include esters and fatty alcohols, are critical for defining a cosmetic product's texture, spreadability, and final sensory feel. Natural oils and esters are displacing hydrocarbon oils, driven by consumer demand for 'clean beauty' products. The skin care application continues to command the largest volume, with sun care formulations showing significant expansion due to their need for specific sensory properties.
Ingredient safety and sourcing transparency are shaped by multiple regulatory bodies. The European Chemicals Agency (ECHA) under REACH and the US Food and Drug Administration (FDA) set stringent standards for cosmetic ingredient safety and claims substantiation. In China, the National Medical Products Administration (NMPA) enforces strict pre-market approval for new cosmetic ingredients, impacting market entry strategies. Formulators must navigate these complex rules while meeting consumer expectations for sustainable and high-efficacy products.
Market Dynamics
The personal care emollients market is defined by the tension between sustainability mandates and supply chain resilience. The push for biodegradability, codified by frameworks like the EU Green Deal, clashes with the price volatility of natural feedstocks, forcing a strategic shift toward multi-source procurement.
Growth Catalysts
- Biodegradability Mandates:Regulatory frameworks including the EU Green Deal incentivize the development and adoption of biodegradable emollients, pushing formulators away from persistent synthetic alternatives in skin care and hair care.
- Sun Care Expansion:The sun care segment's growth requires emollients that offer specific sensory properties, such as low tackiness and high spreadability, to improve consumer acceptance of high-SPF formulations.
- Sophisticated Consumer Demand:Advanced cosmetic markets, particularly South Korea, exhibit strong consumer preference for novel textures and proven efficacy, driving continuous innovation in high-performance natural and synthetic emollients.
Market Restraints
- Feedstock Price Volatility:The market's increasing reliance on natural oils and esters exposes manufacturers to significant price fluctuations and supply instability for key feedstocks like palm and coconut oil.
- Regulatory Entry Barriers:China's National Medical Products Administration (NMPA) requires a lengthy and stringent pre-market approval process for new cosmetic ingredients, slowing market access for innovative emollients.
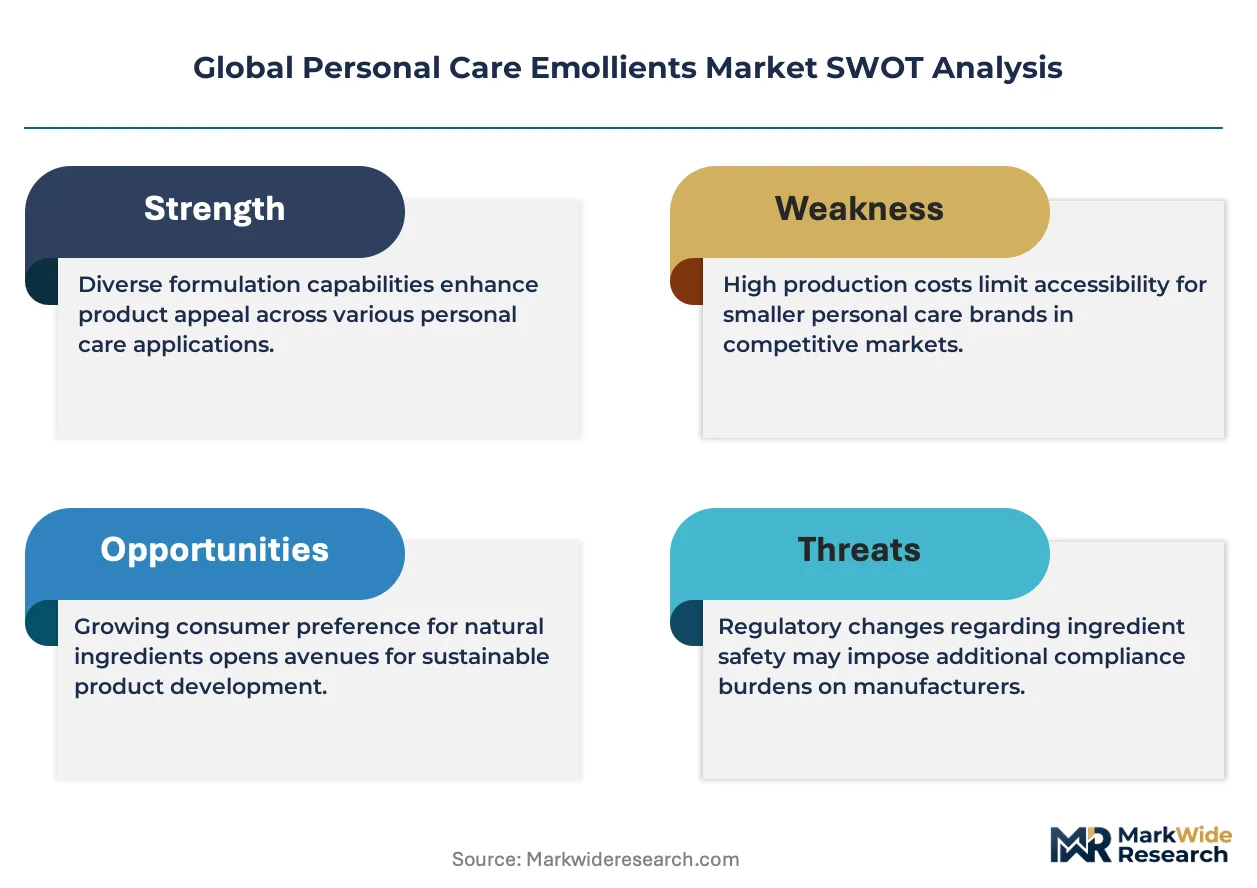
- Performance Trade-offs:While 'clean beauty' trends favor natural emollients, some plant-derived oils and esters face technical limitations in stability, odor, or color compared to their synthetic counterparts.
Strategic Opportunities
- Biotechnology Integration:The convergence of fermentation technology with cosmetic science opens opportunities for creating novel, high-performance emollients with unique sensory profiles and strong sustainability credentials.
- Male Grooming Formulations:Developing emollients specifically for the male grooming segment, focusing on lightweight, non-greasy textures for products like beard oils and moisturizers, addresses an underserved market.
- 'Clean Beauty' Certification:Obtaining certifications such as COSMOS or NATRUE for emollient portfolios provides a clear market advantage by appealing to brands and consumers demanding verifiable natural and organic ingredients.
Industry Challenges
- Navigating Divergent Regulations:Formulators face significant operational challenges in ensuring a single ingredient complies with the distinct safety and labeling requirements of ECHA in Europe, the FDA in the US, and the NMPA in China.
- Supply Chain Restructuring:The industry-wide shift from single-supplier relationships to a multi-source procurement model for key feedstocks creates logistical complexities and requires significant investment in supplier qualification and management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Personal Care Emollients Market |
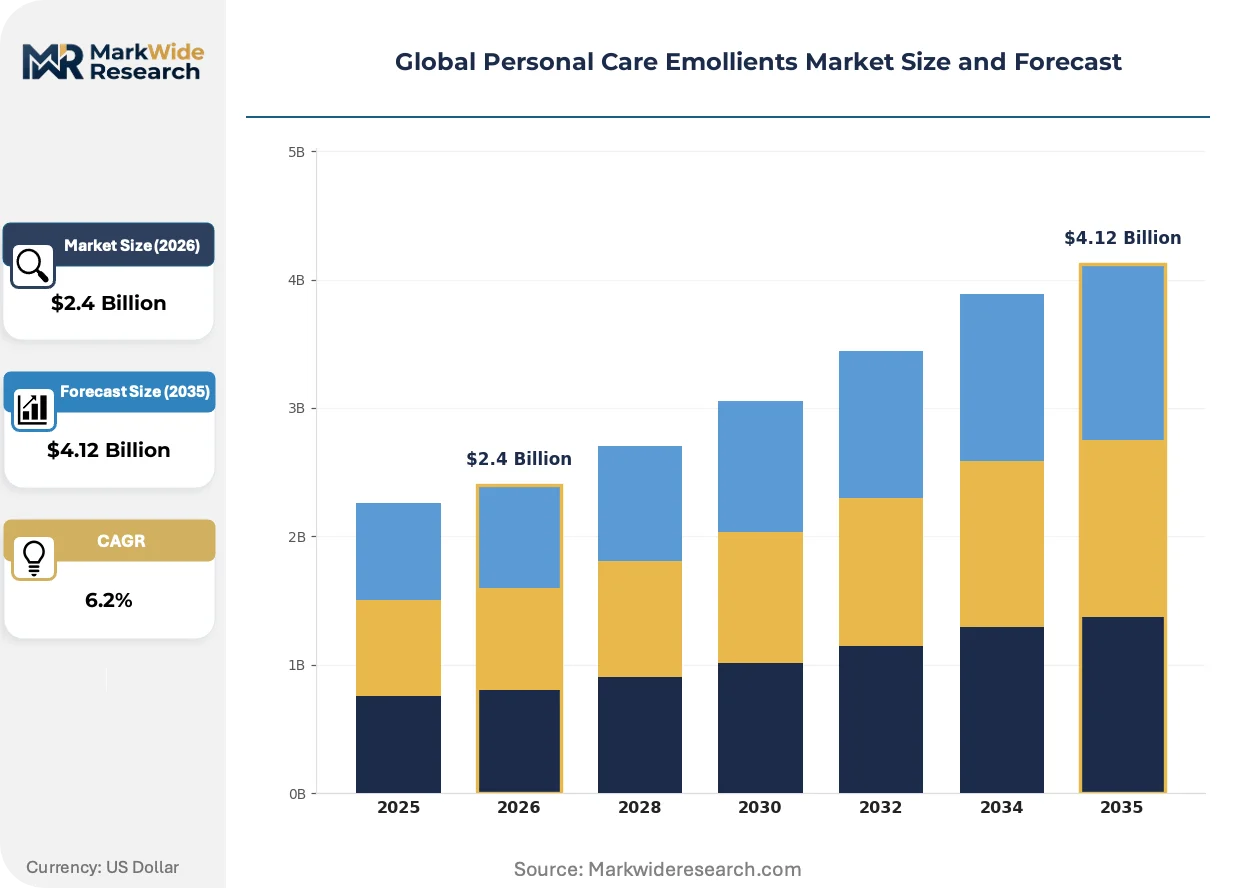
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.12 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Oils, Hydrocarbon Oils, Fatty Alcohols, Esters, Natural Oils Application: Skin Care, Hair Care, Sun Care, Color Cosmetics, Baby Care End User: Beauty Salons, Dermatology Clinics, Spas, Cosmetic Manufacturers Packaging Type: Plastic Bottles, Tubes, Jars, Airless Pumps, Sachets |
| Companies Covered | BASF SE, Croda International Plc, Evonik Industries AG, Clariant AG, Eastman Chemical Company, The Lubrizol Corporation, Ashland Global Holdings Inc., Covestro AG, Hallstar Innovations Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Personal Care Emollients Market Strategic Shifts & Innovations
The sector's evolution is centered on delivering advanced functional performance while meeting rigorous sustainability and ingredient transparency demands. Innovation is no longer just about sensory feel but about creating materials that are biocompatible, biodegradable, and supported by verifiable sourcing data to satisfy both regulators and consumers.
Bio-fermented emollients, produced using microorganisms like yeast, offer unique, lightweight sensory profiles and a sustainable manufacturing pathway. High-end skin care brands and 'clean beauty' startups are rapidly adopting these next-generation ingredients to differentiate their formulations. This new class of material is absorbing significant research and development investment that was previously directed toward traditional synthetic and plant-derived esters, enhancing performance in natural cosmetics.
European Chemicals Agency (ECHA) enforcement of REACH regulations is a dominant force, mandating extensive safety and toxicological data for all ingredients. This compels emollient manufacturers to undertake costly and time-consuming testing to ensure compliance for both new and existing substances. The skin care segment, a primary user of diverse esters and fatty alcohols, is most affected, prompting a focus on portfolios with robust, pre-existing safety dossiers.
A demand for radical ingredient transparency is altering procurement behavior among cosmetic brands. This shift pressures emollient suppliers to provide detailed traceability, from the agricultural source of feedstocks to the final processing method. Traditional B2B relationships are being disrupted in favor of partnerships that offer verifiable certifications and transparent supply chain data, a trend most visible in the North American and European premium beauty markets.
Global Personal Care Emollients Market Segmentation
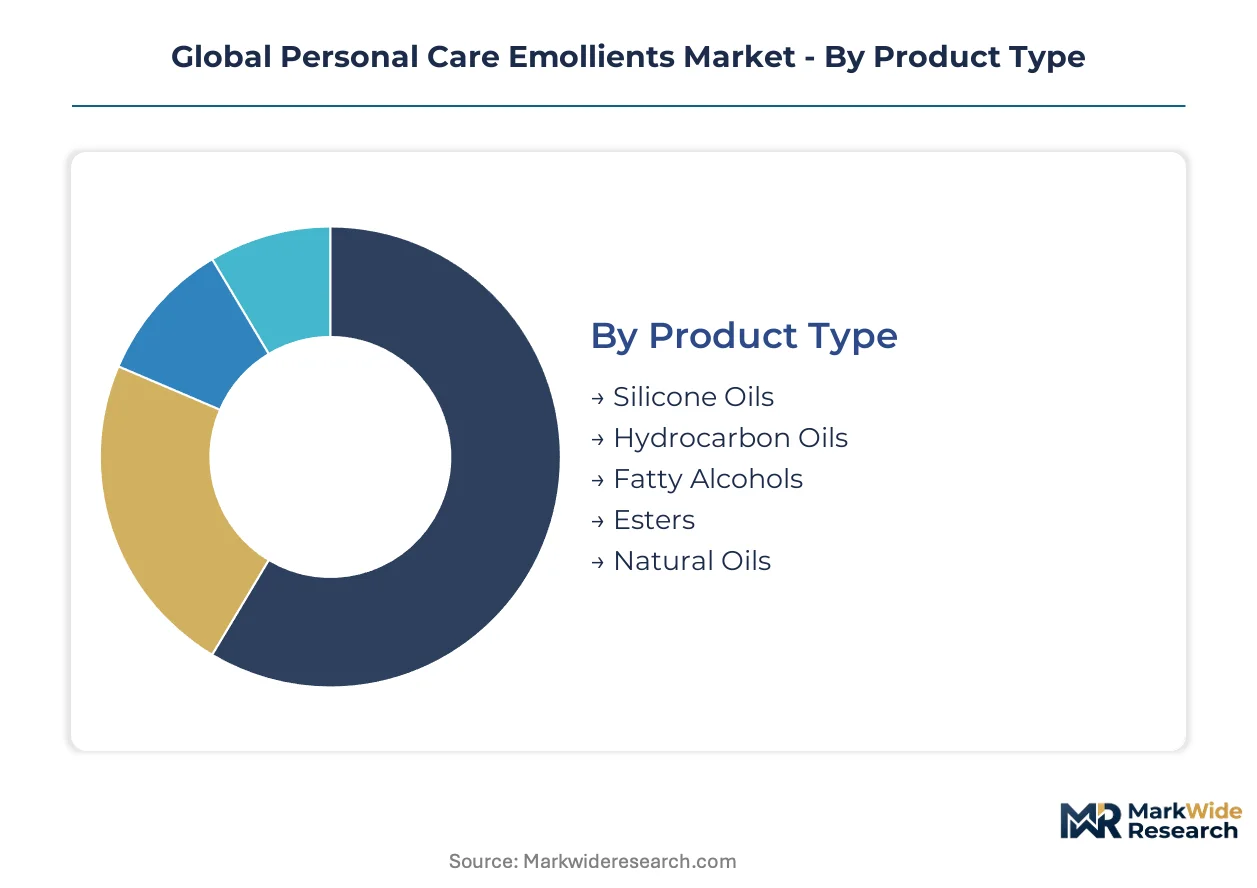
The personal care emollients market is segmented to reveal distinct value propositions and regulatory pathways across various ingredient types, applications, end-users, and packaging formats. Understanding these divisions helps stakeholders identify areas of concentrated demand and navigate specific compliance requirements. Each segment reflects unique performance attributes and market dynamics within the broader industry.
Product Type:
The regulatory burden for emollients varies significantly by product type, influencing market entry and compliance costs across different ingredient classes. Manufacturers must often provide extensive safety dossiers for novel chemistries.
- Esters:These are synthesized from fatty acids and alcohols, offering a wide range of sensory properties from light and dry to rich and occlusive. Demand is concentrating in high-performance skin care formulations requiring enhanced spreadability and a non-greasy feel.
- Natural Oils:Derived from botanical sources like coconut or jojoba, these emollients are valued for their biocompatibility and 'clean beauty' appeal. Consumer demand in North America and Europe is driving their integration into sustainable cosmetic lines, despite price volatility.
- Silicone Oils:These synthetic polymers provide a smooth, non-tacky feel and excellent spreadability, frequently used in hair care and color cosmetics for their unique textural benefits.
- Fatty Alcohols:Long-chain alcohols derived from natural fats and oils, serving as emollients, emulsifiers, and thickeners, particularly in creams and lotions.
- Hydrocarbon Oils:Petroleum-derived ingredients like mineral oil and petrolatum offer strong occlusive properties, but face declining preference due to consumer demand for natural alternatives.
Leading the category by volume: Esters. Growing fastest: Natural Oils.
Application:
Different applications command distinct price points for emollients, reflecting formulation complexity and consumer willingness to pay for specific sensory benefits. Each segment requires specialized ingredient profiles.
- Skin Care:This segment encompasses moisturizers, serums, and anti-aging products, requiring emollients that deliver hydration, barrier repair, and a desirable skin feel. Demand for novel textures and efficacy drives innovation in bio-fermented ingredients.
- Sun Care:High-SPF sunscreens need emollients that reduce tackiness, improve spreadability, and ensure even film formation without compromising UV filters. Regulatory scrutiny on ingredient safety and efficacy is particularly high in this segment.
- Hair Care:Shampoos, conditioners, and styling products utilize emollients to provide shine, manageability, and frizz control, with a focus on lightweight and non-greasy options.
- Color Cosmetics:Foundations, lipsticks, and mascaras employ emollients to enhance pigment dispersion, improve wear, and create a smooth application, often prioritizing specific sensory attributes.
- Baby Care:Formulations for infants require ultra-mild and hypoallergenic emollients, emphasizing ingredient safety and minimal irritation potential.
Skin Care drives the largest share, while Sun Care shows the steepest expansion trajectory.
End User:
Customer procurement patterns for emollients diverge across end-user segments, reflecting varying scales of operation and technical requirements. Each end-user type has distinct sourcing priorities.
- Cosmetic Manufacturers:These large-scale buyers source emollients in bulk for diverse product lines, prioritizing cost-effectiveness, consistent supply, and compliance with global regulations like ECHA REACH and NMPA.
- Dermatology Clinics:Specialized clinics demand high-purity, clinically proven emollients for therapeutic and sensitive skin formulations, often requiring detailed safety and efficacy data. Their procurement focuses on performance and patient compatibility.
- Beauty Salons:These businesses typically purchase finished products or concentrate ingredients in smaller volumes for professional treatments, focusing on immediate sensory results and client satisfaction.
- Spas:Spas procure emollients for massage oils, facial treatments, and body wraps, emphasizing natural origins, luxurious textures, and aromatic profiles to enhance the client experience.
Cosmetic Manufacturers account for the bulk of emollient consumption, with Dermatology Clinics demonstrating significant growth in specialized formulations.
Packaging Type:
The supply chain for emollient packaging is shaped by material availability and manufacturing capabilities, impacting lead times and cost efficiencies. Packaging choices reflect product stability and consumer convenience.
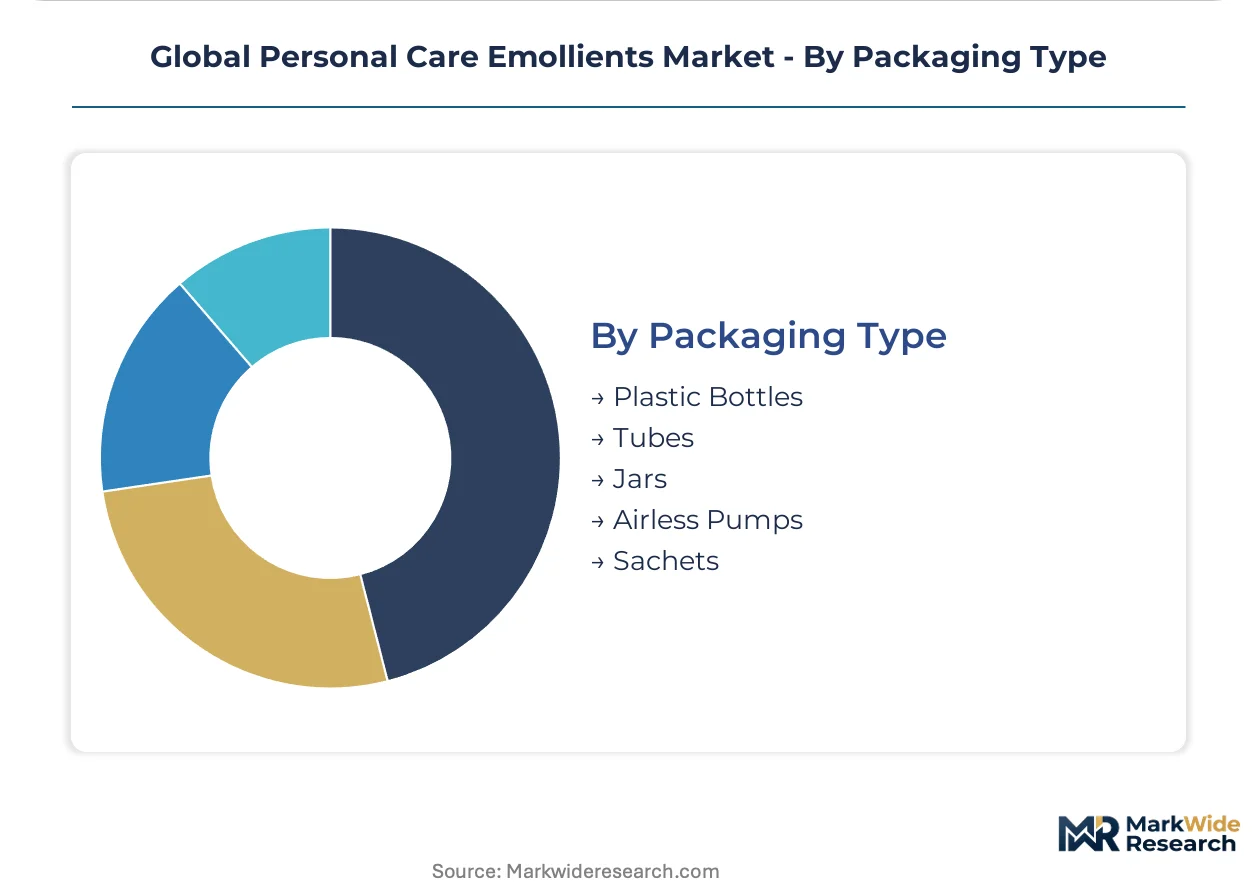
- Plastic Bottles:These are widely used for liquid and lotion emollients due to their versatility, cost-effectiveness, and ease of manufacturing. Sustainability concerns are driving demand for recycled content.
- Airless Pumps:This advanced packaging protects sensitive emollient formulations from air and contamination, preserving ingredient stability and extending shelf life. High-end brands adopt these for premium products.
- Tubes:Flexible tubes are common for creams, gels, and ointments, offering hygienic dispensing and portability, particularly for travel-sized products.
- Jars:Jars provide a traditional and often luxurious presentation for richer emollients and creams, though they expose contents to air upon opening.
- Sachets:Single-use sachets are employed for samples or travel-friendly portions of emollients, offering convenience and precise dosing.
Plastic Bottles remain the dominant packaging format, though Airless Pumps are gaining share due to enhanced product protection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Feedstock availability from diverse agricultural regions anchors global personal care emollient market dynamics. These regions, including Southeast Asia for palm oil and South America for plant-derived oils, influence supply chain stability and ingredient pricing. Consumer preference for natural ingredients further amplifies the importance of these localized sources.
United States
United States consumers drive demand for natural oils and bio-fermented emollients due to 'clean beauty' preferences. The US Food and Drug Administration (FDA) sets stringent safety standards for cosmetic ingredients. Research and development clusters in California lead in formulating advanced personal care products.
Germany
German manufacturers focus on sustainable formulations and high-performance emollients. European Chemicals Agency (ECHA) REACH regulations mandate extensive safety data for all substances. Chemical production hubs in the Rhine-Main area develop novel synthetic and bio-based emollient solutions.
South Korea
South Korean consumers exhibit strong demand for advanced cosmetic products with novel textures and proven efficacy. The Ministry of Food and Drug Safety (MFDS) regulates cosmetic ingredients, influencing development. Seoul's vibrant beauty industry fosters continuous innovation in high-performance emollients.
China
China's expanding middle class fuels demand for premium skin care products incorporating diverse emollients. The National Medical Products Administration (NMPA) enforces strict pre-market approval for new cosmetic ingredients. Manufacturing hubs in the Yangtze River Delta region are key centers for cosmetic production.
Brazil
Brazilian consumers prefer natural-derived emollients suitable for tropical climates, driving local ingredient innovation. The National Health Surveillance Agency (ANVISA) oversees cosmetic ingredient safety and efficacy. São Paulo's robust cosmetics sector actively incorporates sustainably sourced natural oils into new product lines.
Global Personal Care Emollients Market Key Industry Players
Global majors compete with regional champions across product portfolio breadth and geographic reach within the personal care emollients market. The industry structure shows consolidation among large chemical companies and fragmentation among specialized ingredient suppliers, reflecting diverse operational scales. Strategic archetypes include diversified chemical giants, sustainable ingredient specialists, and technology-focused innovators. Companies frequently pursue portfolio diversification, geographic expansion, and strategic partnerships to strengthen their market positions and mitigate supply chain risks.
Diversified chemical giants like BASF SE represent broad portfolios spanning synthetic and natural-based emollients, leveraging extensive production networks. Croda International Plc exemplifies a sustainable ingredient specialist, focusing on plant-derived and bio-fermented solutions for 'clean beauty' formulations. Evonik Industries AG occupies a position as a technology-focused innovator, known for specialized silicone technologies for high-performance cosmetic applications. These companies anchor different segments of the emollient supply chain, from raw material sourcing to specialized ingredient development, catering to varied customer needs.
| Leading Market Players |
|---|
| BASF SE |
| Croda International Plc |
| Evonik Industries AG |
| Clariant AG |
| Eastman Chemical Company |
| The Lubrizol Corporation |
| Ashland Global Holdings Inc. |
| Covestro AG |
| Hallstar Innovations Corp. |
Cost & Logistics Intelligence
Palm oil and coconut oil commodity benchmarks heavily influence emollient pricing, cascading through the supply chain into distinct pricing tiers for formulators. This volatility directly impacts the cost of natural oils and esters, forcing strategic adjustments in procurement and product development.
Pricing Analysis
Bundling technical support and formulation guidance differentiates emollient suppliers beyond basic unit pricing. The dominant pricing structure involves contract-based long-term offtake agreements for large-volume buyers, complemented by per-unit transactional models for specialized or smaller orders. Price differentiation stems from ingredient purity, specific certifications like COSMOS, and the volume scale of procurement. Pricing pressure stems from intense competition among suppliers and the rising demand for cost-effective natural alternatives. Cosmetic manufacturers are generally more price-sensitive for bulk ingredients, while dermatology clinics prioritize performance and purity over cost for specialized formulations.
Supply Chain Analysis
Logistics and freight costs represent a significant component of final emollient pricing, particularly for globally sourced natural feedstocks. Supply concentration for key natural oils originates in Southeast Asia for palm oil derivatives and South America for various plant-derived oils. Raw material dependencies center on agricultural commodities like palm, coconut, and castor oil, alongside petrochemical feedstocks for synthetic esters and silicones. Commodity price volatility for natural feedstocks remains a structural supply chain risk. Distribution runs primarily through a network of specialized chemical distributors and direct sales channels from large multinational chemical companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The personal care emollients market presents a cost-of-compliance story, where stringent regulations like ECHA REACH create a significant barrier-to-entry moat for compliant players.
For Market Incumbents:
Cement market leadership by expanding multi-source procurement strategies for key natural feedstocks. This mitigates the threat of raw material price volatility and regional supply disruptions. Invest heavily in safety dossier development for both existing and novel emollients to ensure ongoing compliance with evolving regulatory frameworks. Leverage extensive production networks to offer a broad portfolio, including bio-fermented options, to counter emerging competitive threats from specialized startups.
For New Entrants and Emerging Players:
Capture white-space opportunities by focusing on biotechnology integration to produce novel bio-fermented emollients with unique sensory profiles. Target the underserved male grooming segment with lightweight, non-greasy formulations for products like beard oils. The most penetrable segment remains high-performance 'clean beauty' startups seeking innovative, sustainable ingredients. Obtain verifiable certifications such as COSMOS or NATRUE to provide a clear market advantage and appeal to discerning brands.
For Investors and Strategic Acquirers:
Distressed-cycle entries favor specialized ingredient suppliers in Europe and North America with strong intellectual property in bio-fermentation technology. The long-term viability of the personal care emollients market is underpinned by continuous consumer demand for advanced, sustainable cosmetic products. Target acquisition archetypes include mid-cap companies possessing proprietary green chemistry processes or extensive safety dossiers. A key signal to watch is increased M&A activity within the bio-fermented emollient sector, indicating market validation.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Bio-fermented Emollients | Secures supply for high-growth 'clean beauty' formulations. |
| Multi-source Feedstock Procurement | De-risks supply chains against regional disruptions and price volatility. |
| Investment in Safety Dossier Development | Ensures compliance with stringent regulations like ECHA REACH. |
| Strategic Partnerships for Certification | Accelerates market entry for verifiable natural and organic ingredients. |
| Targeted R&D for Sun Care Emollients | Addresses specific sensory needs for high-SPF formulations. |
Research Approach
Multi-period observation of feedstock price trends and regulatory enforcement actions anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary research involved discussions with R&D directors, procurement leads, brand managers, and regulatory affairs specialists across key geographies. Secondary data sources included ECHA dossiers, NMPA guidelines, industry association reports, and customs trade statistics. This approach facilitated bottom-up and top-down triangulation of market data.
The input-output matrix framing guided the forecast framework, modeling market dynamics across the projection horizon. Segmentation dimensions included product type, application, end-user, and regional demand patterns. Compound annual growth rates were derived from historical data, identified market drivers, and expert consensus. Industry-specific forecast inputs included shifts in consumer preferences for natural ingredients and the approval timeline for novel emollients.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to unforeseen regulatory changes or disruptive biotechnologies. These forecasts reflect assumptions about market evolution and technological advancements. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Oil Control Shampoo Market
Beauty & Personal Care
Nail Care Products Market
Beauty & Personal Care
Vanity Mirror Market
Beauty & Personal Care
Handmade False Eyelash Market
Beauty & Personal Care
Hair Removal Epilator Market
Beauty & Personal Care
Makeup Brushes Market
Beauty & Personal Care
Russia Beauty and Personal Care Market
Beauty & Personal Care
Global Heated Eyelash Curlers Market
Beauty & Personal Care
DIY Face Mask Machine Market
Beauty & Personal Care
Mens Intimate Care Products Market
Beauty & Personal Care
Sustainable Personal Care Market
Beauty & Personal Care
China Electric Face Cleanser Market
Beauty & Personal Care
Hand Care Products Market
Beauty & Personal Care
Wrinkle Release Spray Market
Beauty & Personal Care
Sunless Tanners Market
Beauty & Personal Care
Switzerland Haircare Market