
 Luxury Cosmetics Market | 2026-2036
Luxury Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Cosmetics Market Analysis
Department store beauty halls is tilting toward experiential retail formats that blend diagnostics with personalized service. L'Oréal leverages its dermatological science heritage to anchor premium skin care credibility. The Estée Lauder Companies sustains fragrance dominance through heritage house positioning and controlled distribution. Chanel differentiates via vertical integration from fragrance composition to boutique retail, limiting grey-market exposure.
Luxury cosmetics encompass high-margin personal care formulations distinguished by superior active ingredient concentrations, artisanal manufacturing methods, and brand equity pricing power. These products serve consumers seeking sensorial experience, status signaling, and perceived efficacy beyond mass-market alternatives. Skin care commands the largest value pool among product types, reflecting consumer willingness to invest in visible, long-term results. Fragrance registers the fastest structural expansion, fueled by unisex positioning and niche perfumery growth. Online retail captures disproportionate momentum among distribution channels, though specialty stores retain margin superiority through immersive brand storytelling.
REACH governs ingredient safety and disclosure across European formulations, while FDA oversight in the United States shapes labeling and manufacturing practice standards. China's NMPA registration requirements for imported cosmetics create compliance barriers that favor established multinationals with regulatory infrastructure. Stakeholders must monitor evolving ingredient blacklists and digital traceability mandates that will determine market access and consumer trust architecture.
Market Dynamics
Clean beauty technology and ECHA's REACH disclosure mandates are compressing formulation development cycles while elevating compliance costs, forcing brands to rebuild supply chains around biotech-derived actives and digital ingredient traceability.
Growth Catalysts
- REACH transparency mandates:ECHA's expanded safety data requirements accelerate consumer trust migration toward brands with established regulatory infrastructure and documented supply chain provenance.
- Biotech fermentation processes:Engineered yeast and plant cell cultures now produce rare botanical actives at scale, collapsing dependency on wild-harvested ingredients with volatile availability.
- China's tier-one city concentration:Shanghai, Beijing, and Shenzhen generate disproportionate luxury cosmetics velocity despite national macroeconomic moderation, rewarding localized marketing infrastructure.
Market Restraints
- Raw material concentration risk:Over 70% of global fragrance compound production concentrates in Grasse, France, creating single-point vulnerability to climate disruption and labor action.
- NMPA registration timelines:China's National Medical Products Administration imposes 10-18 month approval windows for imported cosmetics, freezing market entry for brands lacking pre-established regulatory relationships.
- Natural ingredient substitution ceiling:Synthetic alternatives to palm-derived emollients face performance gaps in texture stability and oxidation resistance that limit clean-label migration in premium skin care.
Strategic Opportunities
- India's emerging luxury corridor:Mumbai and Delhi luxury retail expansion outpaces mass-market saturation, creating first-mover advantage for prestige fragrance and color cosmetics positioning.
- AI-driven personalization engines:Machine learning skin analysis tools integrated with e-commerce platforms enable mass-customized serum formulations at premium price points.
- EU Green Deal chemical substitution incentives:Tax advantages and accelerated approval pathways for biodegradable surfactants and renewable packaging polymers reduce compliance burden for early adopters.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in natural preservation systems and emulsion stability commands premium compensation, constraining R&D throughput for mid-tier brands.
- Digital traceability system integration:Blockchain-enabled ingredient provenance platforms require legacy ERP reconstruction and supplier onboarding cycles that delay product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Cosmetics Market |
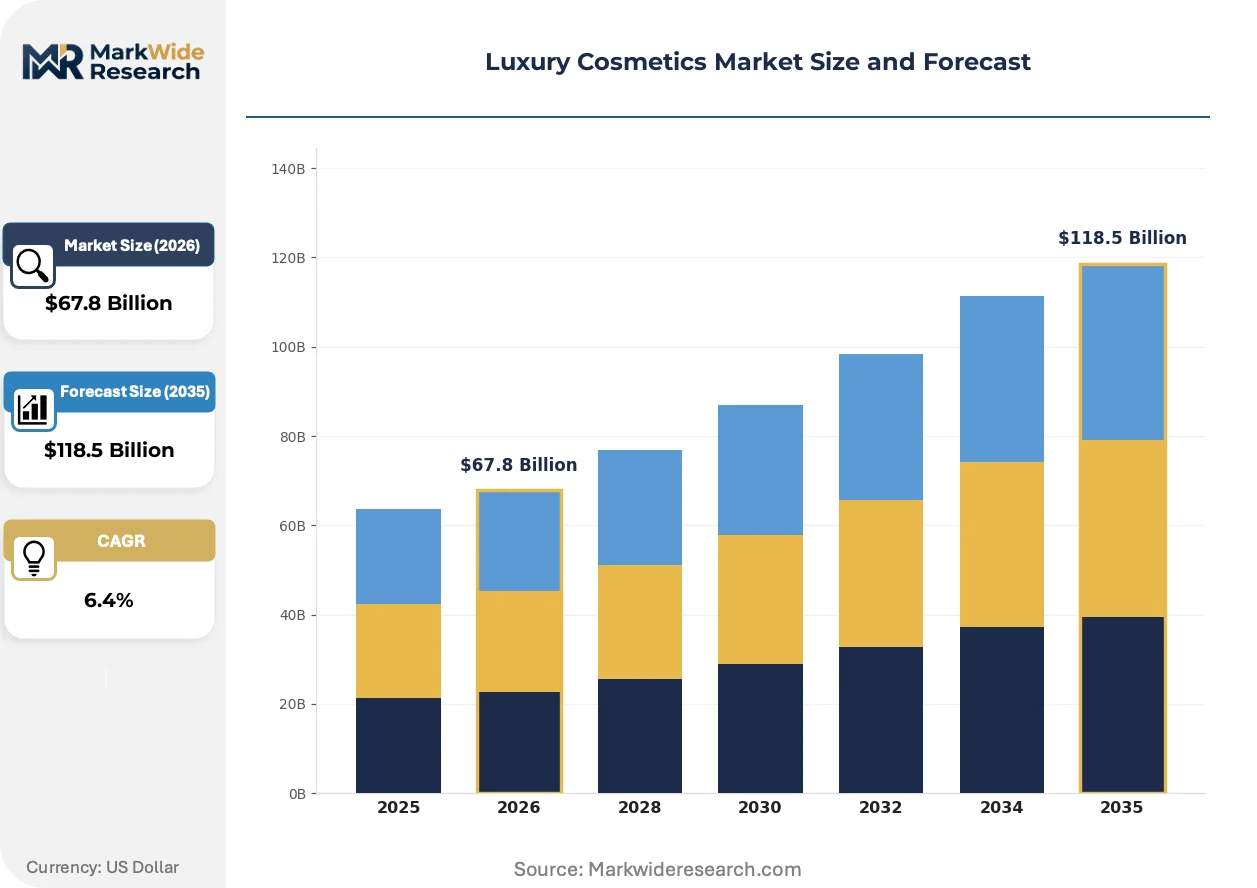
| Market Size in 2026 | $67.8 Billion |
| Market Size in 2035 | $118.5 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skin Care, Make-up, Fragrance, Hair Care End User: Women, Men, Unisex, Teenagers Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales Ingredient Type: Organic, Synthetic, Natural, Others |
| Companies Covered | L'Oréal, The Estée Lauder Companies, LVMH, Chanel, Shiseido Company, Coty, Puig, Kao Corporation, La Mer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Cosmetics Market Emerging Trajectories
Biotechnology and artificial intelligence are converging to transform how luxury cosmetics are formulated, manufactured, and distributed, collapsing traditional boundaries between clinical efficacy claims and sensorial experience design.
Precision fermentation technology is collapsing the cost structure of rare botanical extraction. Engineered microorganisms now produce squalane, resveratrol, and bakuchiol at purity levels exceeding plant-derived equivalents. Prestige skin care brands in South Korea and the United States are accelerating adoption, compressing the premium pricing power previously held by wild-harvested ingredient suppliers.
ECHA's REACH candidate list expansion is forcing reformulation of long-stable product lines. The 2023 addition of several siloxane compounds to restricted substance catalogs requires fragrance houses to rebuild base formulations. European prestige fragrance manufacturers are responding by accelerating investment in biodegradable alternative chemistries and accelerating disclosure documentation for retail partners.
Diagnostic-enabled retail is displacing traditional counter service models. Skin imaging devices and AI-powered recommendation engines now anchor beauty hall experiences in Shanghai, Tokyo, and New York. Department store operators are reallocating square footage from inventory display to consultation pods, capturing higher-margin service revenue while reducing working capital intensity.
Luxury Cosmetics Market Segmentation
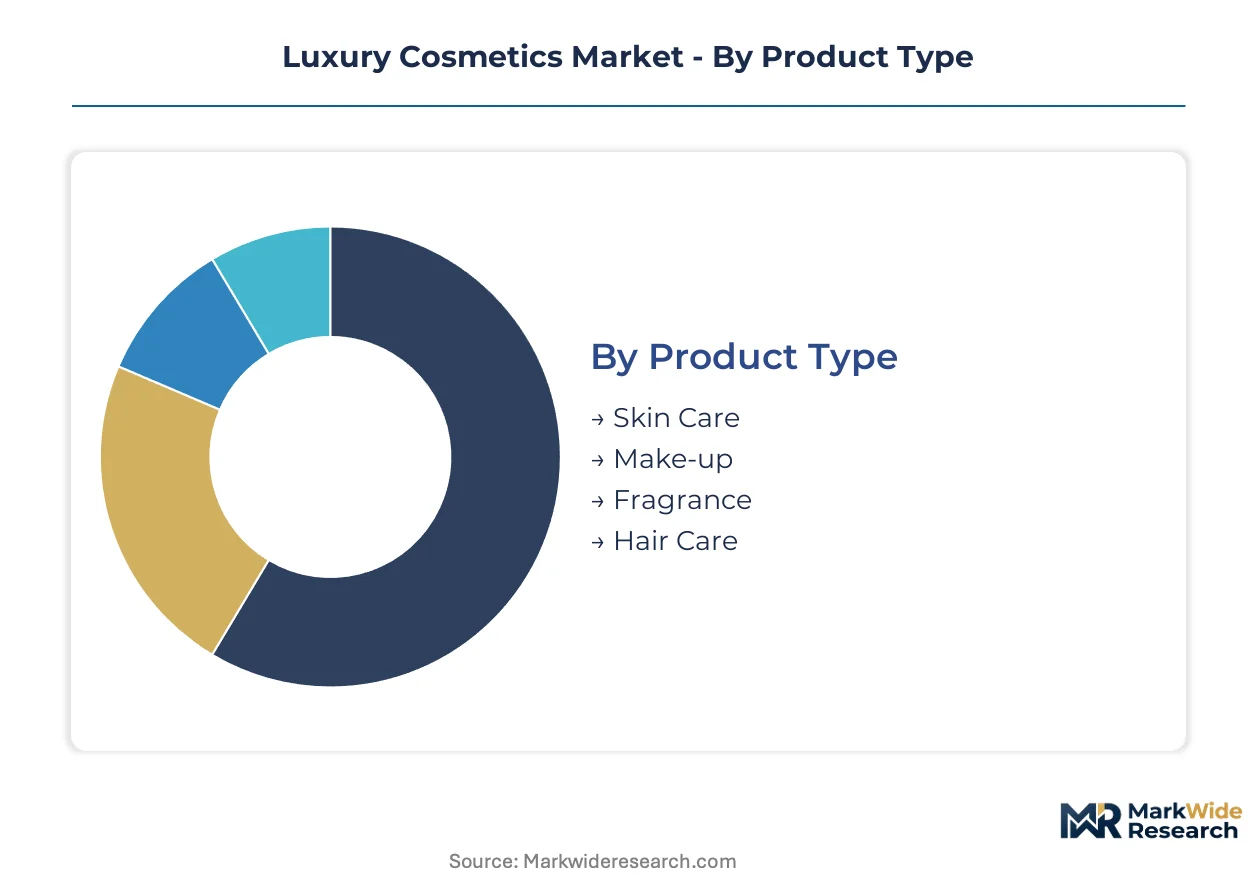
Luxury cosmetics segmentation reveals divergent margin profiles and inventory velocity across product categories. Understanding these structural differences enables targeted resource allocation and channel strategy optimization.
Product Type:
Skin care commands the longest development cycles and highest consumer loyalty, while fragrance turns inventory fastest through impulse purchase dynamics.
- Skin Care:Clinically validated formulations with concentrated active ingredients such as retinoids and peptides command premium price persistence. Affluent consumers in Shanghai and Beijing drive demand for dermatologist-backed regimens despite macroeconomic headwinds.
- Fragrance:Artisanal composition and heritage house positioning create scarcity value through controlled distribution. Unisex positioning and niche perfumery expansion fuel structural growth across European and Asian markets.
- Make-up:Color cosmetics balance seasonal trend velocity with core SKU stability.
- Hair Care:Prestige scalp treatments and styling formulations occupy emerging positioning territory.
Skin care anchors the volume base while fragrance gains share at the steepest rate.
End User:
Customer archetypes stratify sharply by price elasticity and purchase frequency, with gender-targeted marketing requiring distinct channel approaches.
- Women:Established category owners with sustained investment in multi-step regimens and seasonal color updates. Department store beauty halls retain loyalty through personalized consultation services.
- Unisex:Gender-neutral fragrance and skin care lines attract younger demographics seeking inclusive brand positioning. South Korean and United States prestige brands accelerate SKU expansion in this segment.
- Men:Grooming sophistication drives premium migration beyond functional basics.
- Teenagers:Entry-luxury positioning captures early brand relationship formation.
Women sustain the revenue core while unisex positioning climbs the fastest among emerging segments.
Distribution Channel:
Channel economics diverge dramatically between high-touch service models and scalable digital reach, with working capital intensity determining strategic fit.
- Specialty Stores:Immersive brand storytelling environments deliver superior margin capture through controlled experience design. Flagship locations in Tokyo, Paris, and New York anchor global brand perception.
- Online Retail:E-commerce platforms capture disproportionate momentum through AI-driven personalization and subscription mechanics. Digital-native consumers in tier-one Chinese cities favor mobile-first discovery and purchase.
- Department Stores:Experiential retail reinvestment preserves relevance for discovery-oriented shoppers.
- Direct Sales:Consultant networks sustain relationship-based commerce in select demographics.
Specialty stores defend margin leadership while online retail expands most quickly across geographic markets.
Ingredient Type:
Formulation philosophy directly shapes regulatory compliance burden and supply chain resilience, with biotechnology disrupting traditional sourcing models.
- Natural:Wild-harvested botanicals and cold-pressed oils satisfy clean beauty preferences among European and North American consumers. ECHA REACH disclosure mandates elevate documentation requirements for traceability claims.
- Synthetic:Laboratory-engineered molecules deliver batch consistency and performance stability that natural alternatives cannot match. Siloxane compound restrictions under REACH are forcing accelerated reformulation investment.
- Organic:Certified cultivation standards command price premiums in environmentally conscious segments.
- Others:Hybrid and emerging biotech-derived categories occupy definitional boundary zones.
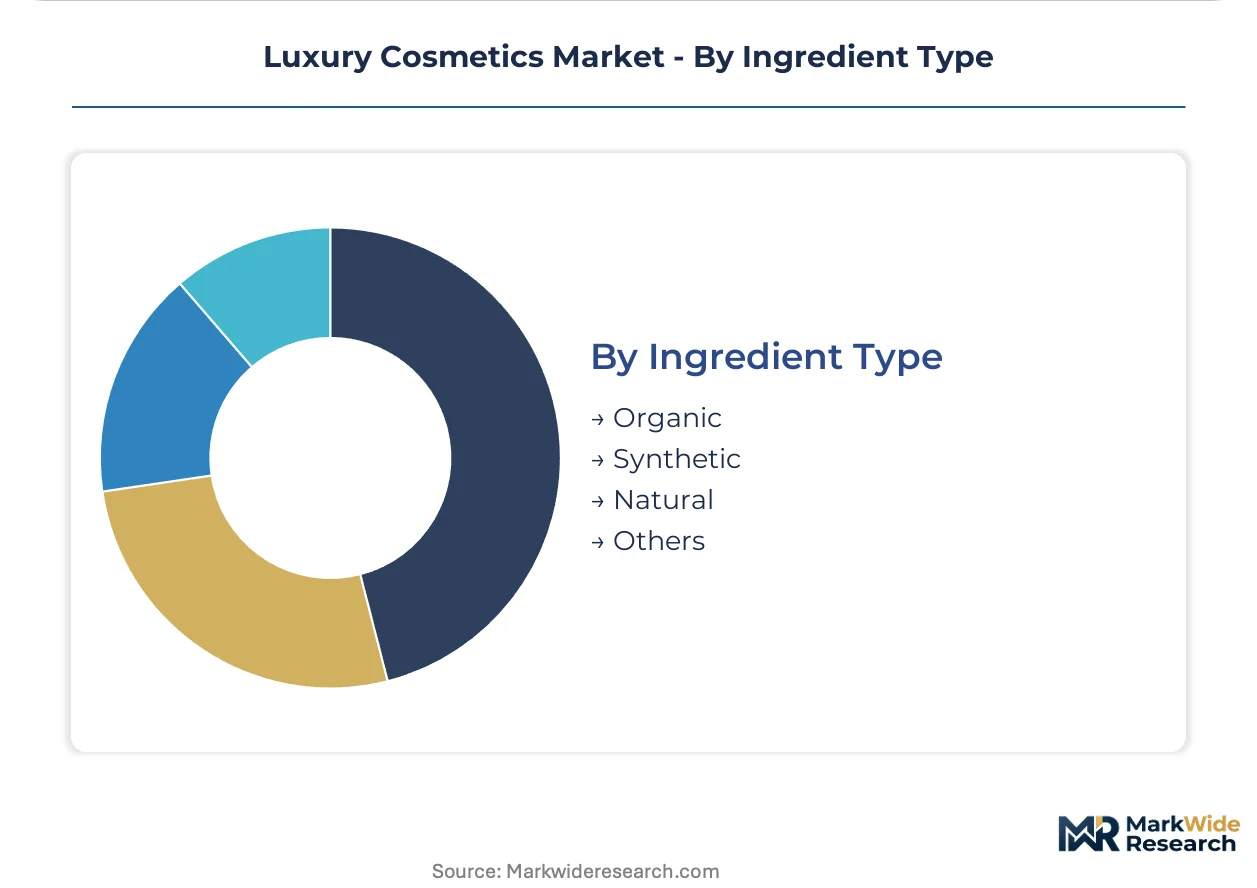
Synthetic formulations anchor manufacturing scale while natural positioning shows the steepest trajectory among premium consumer preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Luxury cosmetics command 40% higher price persistence in Paris and Milan than in Shanghai's tier-one malls, yet Chinese domestic spending velocity now outpaces European heritage market growth. This pricing-power asymmetry is narrowing as biotech-anchored brands from Seoul and San Francisco capture premium positioning.
United States
Affluent millennial and Gen Z consumers in New York and Los Angeles drive prestige skin care velocity through subscription mechanics and AI-powered personalization. FDA labeling standards shape manufacturing practice requirements for clinical efficacy claims. Greater Boston anchors dermatological science partnerships that feed formulation credibility into national distribution.
France
Heritage fragrance houses in Grasse sustain artisanal composition dominance through controlled distribution and scarcity positioning. ECHA REACH disclosure mandates force accelerated investment in biodegradable alternative chemistries. The Provence-Alpes-Côte d'Azur cluster concentrates over 70% of global fragrance compound production, creating climate and labor vulnerability.
China
Shanghai, Beijing, and Shenzhen generate disproportionate luxury cosmetics velocity despite national macroeconomic moderation, with domestic brands capturing share from heritage imports. NMPA registration timelines of 10-18 months for imported cosmetics favor established multinationals with pre-established regulatory infrastructure. The Yangtze River Delta anchors localized marketing infrastructure and biotech fermentation partnerships.
South Korea
Seoul-based prestige brands accelerate SKU expansion in unisex fragrance and skin care, leveraging K-beauty credibility into global premium positioning. MFDS cosmetic safety standards elevate documentation requirements for clinical backing claims. The Seoul Capital Area concentrates diagnostic-enabled retail innovation and precision fermentation technology adoption.
Japan
Tokyo and Osaka sustain loyalty through multi-step regimen investment and sensorial experience design among established female demographics. METI standards on sustainable packaging shape supply chain reconstruction priorities. The Kanto region anchors immersive brand storytelling environments that defend margin leadership against digital-native competitors.
Luxury Cosmetics Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with formulation and manufacturing expertise. The vendor base concentrates among heritage conglomerates with dermatological science credibility and vertically controlled distribution networks. Three archetypes dominate: science-anchored skin care platforms, artisanal fragrance houses with controlled scarcity, and biotech-native challengers collapsing rare ingredient cost structures. Competitive moves center on precision fermentation partnerships and experiential retail reinvestment.
Among heritage conglomerates, L'Oréal and The Estée Lauder Companies exemplify platform integrators with established regulatory infrastructure spanning REACH, FDA, and NMPA compliance. Chanel occupies a position within the artisanal scarcity tier through vertical control from fragrance composition to boutique retail. Shiseido Company anchors the Asia-Pacific science credibility vector with dermatological heritage and diagnostic-enabled retail innovation.
| Leading Market Players |
|---|
| L'Oréal |
| The Estée Lauder Companies |
| LVMH |
| Chanel |
| Shiseido Company |
| Coty |
| Puig |
| Kao Corporation |
| La Mer |
| Others |
Supply Flow & Price Mechanics
Grasse, France concentrates over 70% of global fragrance compound production, tethering margin pools downstream to heritage houses with captive supply relationships and artisanal composition control. REACH disclosure mandates and biotechnology disruption are compressing the premium pricing power previously held by wild-harvested ingredient suppliers while elevating compliance costs across formulation tiers.
Pricing Analysis
Configured-to-order serum formulations command 40-60% premiums over standard SKUs through AI-driven skin analysis and personalized active ingredient dosing. Three-tier pricing structure across premium, standard, and economy levels stratifies by concentration grade and dermatologist endorsement tier. Pricing pressure stems from biotech fermentation collapsing rare botanical scarcity premiums. Mass-market entrants exhibit highest price sensitivity; heritage house loyalists show lowest elasticity.
Supply Chain Analysis
Upstream feedstock for luxury actives draws from France, South Korea, and Switzerland, with precision fermentation capacity expanding fastest in the Seoul Capital Area and Greater Boston. Squalane, resveratrol, and bakuchiol now emerge from engineered yeast cultures rather than wild harvest. Single-source vulnerability concentrates in Grasse fragrance compound production. Distribution runs through controlled boutique networks and AI-enabled e-commerce platforms with subscription mechanics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with clean beauty technology and unisex positioning creating niches between heritage conglomerates and mass-market alternatives. Biotech-native challengers and regional specialists can capture share from incumbents slow to reformulate around REACH-compliant ingredient architectures.
For Market Incumbents: Build regulatory infrastructure moats by accelerating NMPA pre-registration in China and REACH documentation automation in Europe. Deepen precision fermentation partnerships to secure biotech-derived active supply chains before cost structures collapse further. Defend against Korean challengers through dermatological science credibility and diagnostic-enabled retail reinvestment.
For New Entrants and Emerging Players: Establish a beachhead in India's Mumbai-Delhi luxury corridor where prestige fragrance and color cosmetics positioning remains underdeveloped. Target unisex skin care SKUs with K-beauty influenced sensorial design and clean-label biotechnology credentials. Deploy direct-to-consumer subscription models with AI skin analysis to bypass department store gatekeepers.
For Investors and Strategic Acquirers: Capital is best deployed toward biotech-native formulation platforms with precision fermentation capabilities and established regulatory dossiers across FDA, REACH, and NMPA jurisdictions. Long-term viability favors vertical integration from active ingredient production to controlled distribution. Watch for NMPA registration timeline compression as inflection signal for import brand entry feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Engineered yeast production of squalane collapses dependency on wild-harvested shark liver and olive sources. |
| Diagnostic-Enabled Retail Expansion | AI skin imaging pods in Shanghai and Tokyo beauty halls capture higher-margin service revenue. |
| REACH Compliance Automation | Digital ingredient traceability platforms satisfy ECHA disclosure mandates ahead of candidate list expansion. |
| Unisex SKU Line Extension | Gender-neutral fragrance and skin care positioning attracts affluent millennial and Gen Z demographics. |
| NMPA Registration Pre-Investment | Early regulatory infrastructure in China locks in 10-18 month approval timeline advantage. |
Methodological Framework
A spread of perspectives from brand managers at heritage houses, category buyers at department store beauty halls, formulation chemists at fragrance compounds manufacturers, and regulatory affairs leads at multinational cosmetics groups converged on the working assumptions. Primary fieldwork combined with secondary validation against ECHA REACH candidate list updates, NMPA registration databases, MFDS cosmetic safety filings, and customs trade data for active ingredient flows. Bottom-up SKU velocity analysis and top-down market sizing triangulated across the projection horizon.
Demand-supply-balance framing anchored the analytical framework, modeling consumption patterns against biotechnology production capacity expansion and heritage supply chain constraints. Segmentation dimensions included product type, end user archetype, distribution channel economics, and ingredient sourcing philosophy. CAGRs derived from trend extrapolation of tier-one Chinese city velocity, precision fermentation adoption curves, and regulatory approval timeline impacts. Industry-specific inputs incorporated diagnostic-enabled retail penetration rates and clean beauty certification adoption.
Sensitivities concentrate around NMPA regulatory timeline shifts, REACH candidate list expansion scope, and climate disruption impacts on Grasse fragrance harvests. Cross-checking against Nielsen retail audit data and customs import records for premium cosmetics flows is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Online Beauty and Personal Care Products Market
Beauty & Personal Care
United States Beauty and Personal Care Products Market
Beauty & Personal Care
Body Firming Creams Market
Beauty & Personal Care
Advanced Night Repair Serum Market
Beauty & Personal Care
Herbal Shampoo Market
Beauty & Personal Care
Global Organic Personal Care Products Market
Beauty & Personal Care
Anti-Dandruff Shampoo Market
Beauty & Personal Care
Body Care Products Market
Beauty & Personal Care
Anti-Aging Cosmetics Market
Beauty & Personal Care
Nail Buffers Market
Beauty & Personal Care
Loofah Bath Sponge Market
Beauty & Personal Care
In-Wash Scent Booster Market
Beauty & Personal Care
UV Nail Gel Market
Beauty & Personal Care
Natural Deodorant Crystal Market
Beauty & Personal Care
Cosmetics and Toiletries Market
Beauty & Personal Care
Beauty Pillowcases Market