
 Anti-Aging Beauty Device Market | 2026-2036
Anti-Aging Beauty Device Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Aging Beauty Device Market Insights
Certified aesthetician and biomedical engineer talent is bifurcating the competitive landscape, separating brands that can support clinical validation from those confined to unregulated wellness positioning. NuFACE leverages its FDA-cleared microcurrent technology to anchor premium pricing in professional and at-home channels. CurrentBody competes through curated device ecosystems and exclusive distribution partnerships with clinic networks. Alma Lasers dominates the professional-grade segment with multi-technology platforms deployed across dermatology practices worldwide.
Anti-aging beauty devices are electromechanical or photonic instruments engineered to deliver energy doses—typically 1-20 MHz radio frequency, 400-700 nm LED spectra, or sub-sensory microcurrent pulses—to dermal and subdermal tissue for collagen remodeling and epidermal rejuvenation. Their commercial purpose spans wrinkle reduction, skin tightening, and tone improvement for consumers, dermatologists, and spa owners. LED devices occupy the volume base due to lower manufacturing costs and simplified user protocols, while radio frequency devices capture concentrated margin pools where thermal tissue interaction demands precise engineering controls. Microcurrent devices are expanding fastest among at-home technology segments as non-invasive positioning resonates with consumers seeking clinic-equivalent outcomes without procedural downtime.
FDA 510(k) clearances and CE marking under the EU MDR govern device safety and efficacy claims, directly shaping which technologies gain market access and reimbursement-adjacent positioning in clinical settings. ISO 13485 quality management standards and IEC 60601 electrical safety requirements further constrain design and manufacturing processes for brands targeting professional channels. Stakeholders must monitor evolving regulatory interpretations of software-driven personalization features, as algorithmic dose adjustment triggers novel classification debates that could redraw competitive boundaries between consumer wellness and regulated medical device territories.
Market Dynamics
Radio frequency and microcurrent technologies are forcing a bifurcation between clinic-grade efficacy claims and unregulated wellness positioning, as FDA 510(k) clearances tighten safety thresholds while accelerating clearance timelines for compliant manufacturers.
Growth Catalysts
- Medspa channel expansion:Dermatology clinics in the United States are scaling device fleets to capture at-home consumers seeking professional-grade outcomes without procedural downtime.
- EU MDR pathway acceleration:CE marking timelines for LED and microcurrent devices are compressing as notified bodies streamline quality management reviews under ISO 13485 harmonization.
- Dual carbon manufacturing:Chinese producers are integrating renewable energy into semiconductor fab processes for RF chipsets, lowering unit economics for export markets.
Market Restraints
- GaAs wafer supply concentration:Gallium arsenide substrate for RF power amplifiers concentrates among three East Asian foundries, exposing device OEMs to input cost volatility.
- FDA software-as-medical-device ambiguity:Algorithmic dose adjustment features trigger novel classification debates that delay market access for AI-enabled personalization.
- LED efficacy ceiling:400-700 nm spectra penetrate only epidermal layers, limiting collagen remodeling claims against deeper-acting RF alternatives.
Strategic Opportunities
- Brazilian aesthetic medicine infrastructure:ANVISA regulatory harmonization with FDA precedents is opening professional-grade distribution for cleared RF platforms.
- Microcurrent-LED convergence:Hybrid devices combining sub-sensory electrical stimulation with photobiomodulation are capturing premium positioning in South Korean direct-to-consumer channels.
- Subscription hardware models:Device-plus-consumable ecosystems are displacing one-time retail transactions through curated clinic partnerships in Germany.
Industry Challenges
- Biomedical engineer scarcity:Clinical validation teams require electromechanical and photonics expertise that concentrates among certified aesthetician programs in Seoul and Los Angeles.
- IEC 60601 electrical safety recertification:Battery chemistry shifts to solid-state architectures force redesign cycles that compress margin timelines for at-home device portfolios.
- Patent thickets around RF electrode geometries:Licensing complexity in 1-20 MHz thermal delivery systems is elevating legal spend for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Aging Beauty Device Market |
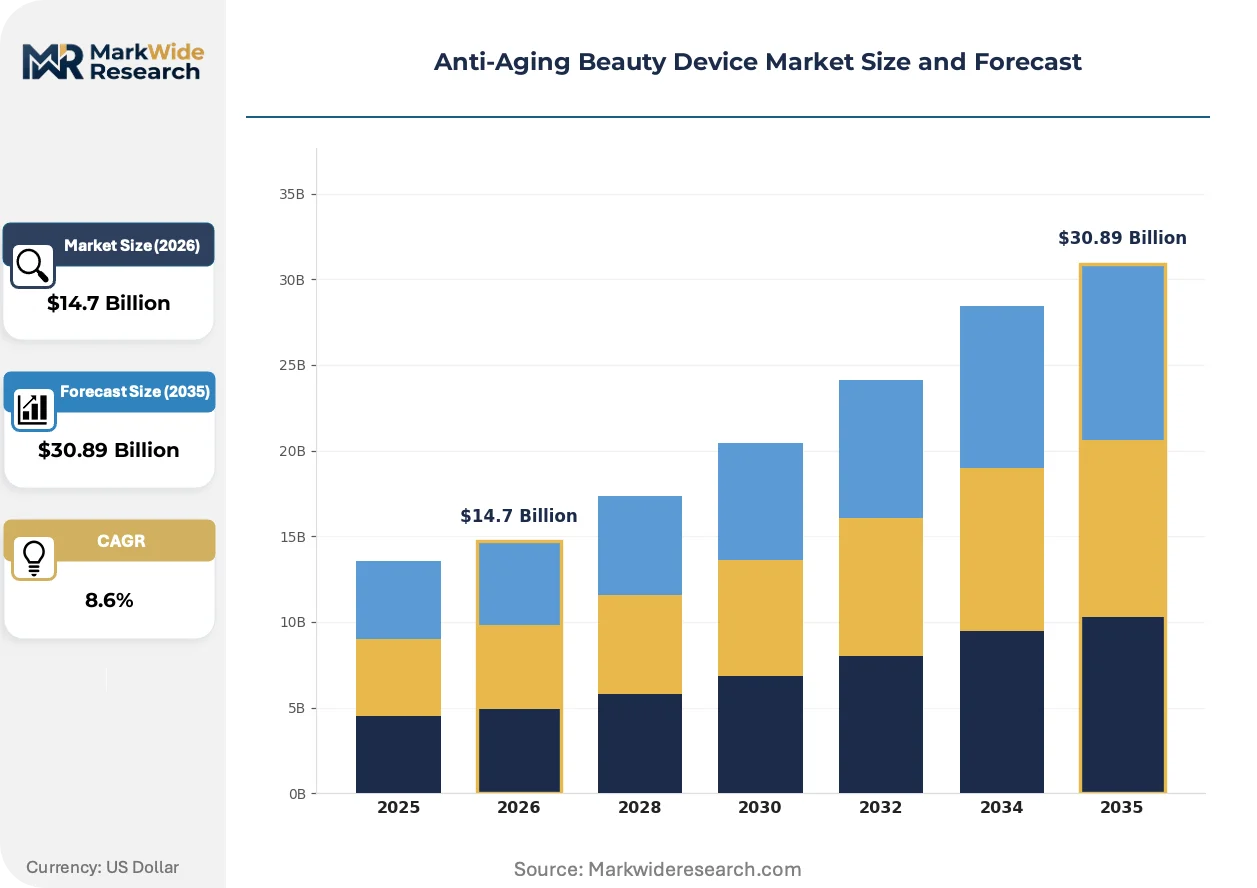
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Devices, Microcurrent Devices, Radio Frequency Devices, Ultrasound Devices End User: Consumers, Dermatologists, Spa Owners, Personal Care Professionals Technology: Non-invasive, At-home, Professional-grade, Therapeutic Application: Wrinkle Reduction, Skin Tightening, Tone Improvement, Acne Treatment |
| Companies Covered | NuFACE, Solawave, CurrentBody, Panasonic Corporation, FOREO, TRIA Beauty, Philips, Alma Lasers, L'Oréal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Aging Beauty Device Market Trends and Innovations
Personalization algorithms and convergent energy modalities are compressing the gap between clinical and at-home efficacy claims, reshaping how device manufacturers validate outcomes and distribute hardware.
Multi-technology platforms are decomposing the traditional separation between professional and consumer device categories. Dermatology practices in South Korea are deploying identical RF hardware across in-clinic and patient-owned units, synchronized through cloud-based treatment protocols. This convergence is collapsing price premiums that historically separated medical-grade from wellness-tier positioning.
Software-driven personalization features are triggering reclassification debates under FDA 510(k) and EU MDR frameworks. Algorithmic dose adjustment that responds to real-time skin impedance readings is shifting from consumer wellness into regulated medical device territory. Manufacturers with existing quality management certifications are accelerating submissions to capture first-mover positioning in this redefined category boundary.
Direct-to-consumer channels are displacing traditional medspa retail for entry-level LED and microcurrent devices. NuFACE and CurrentBody are building exclusive distribution partnerships with clinic networks that drive patient referrals toward at-home maintenance protocols. This hybrid channel structure concentrates in the United States and United Kingdom, where aesthetic medicine infrastructure supports seamless handoffs between professional treatment and consumer-owned hardware.
Anti-Aging Beauty Device Market Segmentation
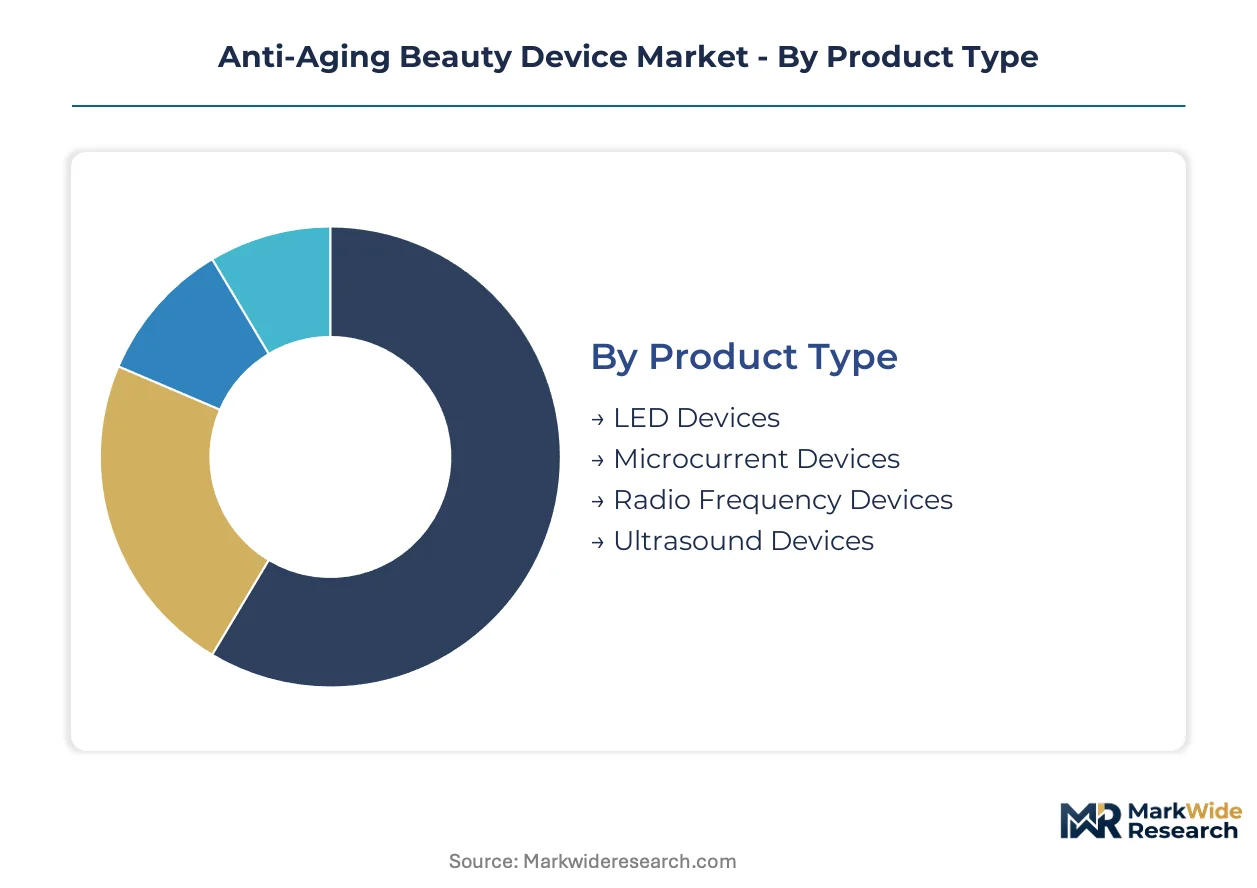
Anti-aging beauty device manufacturers configure product portfolios across four intersecting dimensions that determine regulatory pathway, pricing architecture, and channel strategy. Each segmentation axis carries distinct margin profiles and compliance burdens that reshape competitive positioning.
Product Type:
LED devices concentrate manufacturing in Chinese export zones while RF platforms retain domestic production in Germany and the United States for quality control proximity to clinical validation sites.
- LED Devices:Semiconductor arrays emitting 400-700 nm spectra penetrate epidermal layers for photobiomodulation. Demand clusters in United States direct-to-consumer channels where simplified protocols attract first-time buyers seeking maintenance between professional treatments.
- Radio Frequency Devices:Electromagnetic energy delivery at 1-20 MHz generates controlled thermal injury for collagen remodeling. Dermatology practices in South Korea and Germany deploy these platforms as anchor revenue generators requiring certified operator training.
- Microcurrent Devices:Sub-sensory electrical stimulation mimics cellular bioelectric currents for facial muscle toning.
- Ultrasound Devices:High-frequency acoustic waves target subdermal tissue layers for non-surgical lifting.
LED devices hold the largest share; momentum sits with microcurrent platforms.
End User:
Professional channels command three-to-five times the unit economics of consumer segments, though at-home devices expand addressable market through lower price points and reduced regulatory friction.
- Consumers:Individual purchasers operating devices without clinical supervision. United States and United Kingdom households drive volume through subscription hardware models and influencer-mediated discovery.
- Dermatologists:Board-certified physicians integrating devices into medical practice workflows. FDA 510(k) clearance requirements concentrate demand among manufacturers with ISO 13485 quality management systems.
- Spa Owners:Aesthetic service providers seeking differentiation through technology-enabled treatment menus.
- Personal Care Professionals:Licensed aestheticians performing services under physician oversight or independently per jurisdiction.
Dermatologists generate the highest revenue per account; consumers are climbing the fastest.
Technology:
Classification thresholds under FDA and EU MDR determine whether algorithmic features trigger medical device jurisdiction, creating divergent commercialization timelines.
- Non-invasive:Energy delivery without epidermal breach or recovery protocols. Positioning dominates South Korean and United States marketing as "lunchtime procedure" alternatives.
- At-home:Consumer-operated hardware with simplified safety interlocks and reduced power outputs. Distribution concentrates through Amazon, Sephora, and dedicated e-commerce platforms.
- Professional-grade:Clinic-deployed systems with higher energy densities and operator certification requirements.
- Therapeutic:Medical claims requiring clinical trial substantiation and reimbursement coding.
Non-invasive platforms dominate volume; at-home configurations show steepest expansion trajectory.
Application:
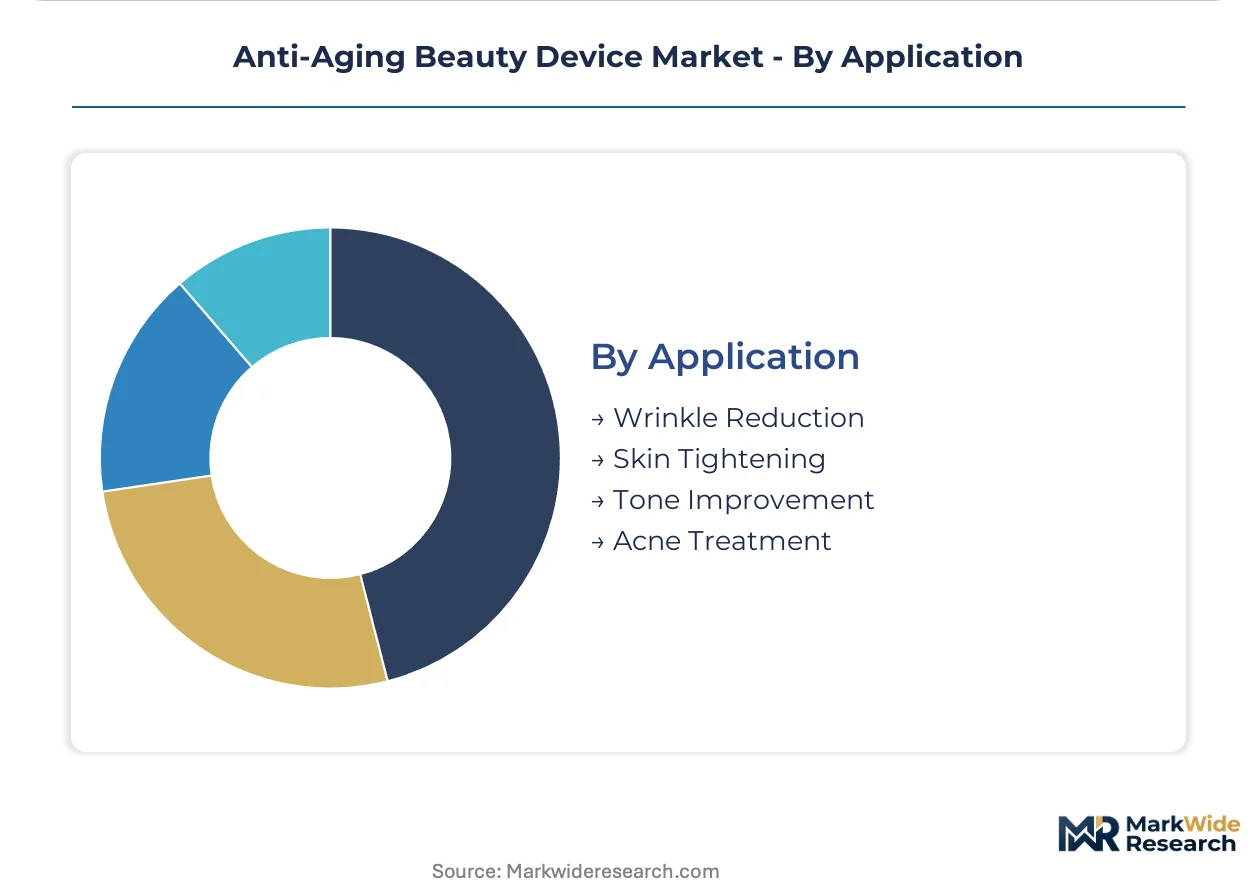
Wrinkle reduction and skin tightening command premium positioning while acne treatment overlaps with adjacent dermatology device categories, expanding addressable market through indication breadth.
- Wrinkle Reduction:Collagen induction and muscle relaxation targeting periorbital and forehead rhytides. United States medspas bundle RF and microcurrent protocols for comprehensive facial rejuvenation.
- Skin Tightening:Dermal heating for laxity correction in jawline, neck, and décolletage zones. Demand concentrates among patients aged 45-65 seeking non-surgical alternatives to rhytidectomy.
- Tone Improvement:Pigmentation and texture refinement through LED photobiomodulation.
- Acne Treatment:Blue light bacterial suppression and sebaceous gland modulation.
Wrinkle reduction holds the largest share; skin tightening gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearances anchor United States demand as dermatology clinics scale device fleets to capture consumers seeking professional-grade outcomes without procedural downtime. Regulatory harmonization across South Korea, Germany, and Brazil is compressing market entry timelines for compliant manufacturers.
United States
Medspa channel expansion and direct-to-consumer subscription models drive demand concentration. FDA 510(k) pathways for radio frequency and microcurrent technologies are tightening safety thresholds while accelerating clearance timelines. Los Angeles and New York Metro anchor aesthetic medicine infrastructure where clinic networks deploy identical hardware across professional and patient-owned units.
South Korea
Hybrid microcurrent-LED convergence and cloud-synchronized treatment protocols reshape premium positioning. MFDS regulatory alignment with FDA precedents streamlines quality management reviews under ISO 13485 harmonization. Seoul Capital Area dermatology practices pioneer identical RF hardware deployment across in-clinic and at-home channels.
Germany
Subscription hardware models through curated clinic partnerships displace one-time retail transactions. EU MDR CE marking timelines compress as notified bodies streamline reviews. Bavaria and North Rhine-Westphalia concentrate professional-grade manufacturing for quality control proximity to clinical validation sites.
China
Dual carbon manufacturing integration into semiconductor fab processes lowers unit economics for RF chipset exports. NMPA regulatory pathways for LED devices accelerate under streamlined quality management frameworks. Yangtze River Delta and Pearl River Delta anchor LED device manufacturing for export markets.
Brazil
ANVISA regulatory harmonization with FDA precedents opens professional-grade distribution for cleared RF platforms. Aesthetic medicine infrastructure expansion in São Paulo and Rio de Janeiro drives clinic network growth. Local spa owners seek technology-enabled differentiation through imported device platforms.
Anti-Aging Beauty Device Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with dermatology-focused conglomerates controlling multi-technology platforms while pure-play device manufacturers capture premium niches through FDA-cleared positioning. The structure rewards clinical validation capabilities and quality management certifications that separate regulated medical device territory from unregulated wellness positioning. Three archetypes dominate: professional-grade platform vendors, at-home consumer specialists, and hybrid channel operators bridging clinic and direct-to-consumer distribution. Competitive moves concentrate on exclusive distribution partnerships with clinic networks and algorithmic personalization features that trigger reclassification debates under FDA and EU MDR frameworks.
Within the professional-grade platform tier, Alma Lasers and NuFACE exemplify divergent strategic positions. Alma Lasers represents the integrated multi-technology vendor archetype deployed across dermatology practices worldwide. NuFACE occupies the FDA-cleared at-home specialist position, anchoring premium pricing through microcurrent technology validation. CurrentBody exemplifies the hybrid channel operator, building curated device ecosystems and exclusive clinic partnerships that drive patient referrals toward at-home maintenance protocols. Panasonic Corporation and Philips represent diversified electronics conglomerates with beauty device portfolios sitting within broader personal care divisions, leveraging manufacturing scale and retail distribution reach without medical-grade regulatory positioning. FOREO and TRIA Beauty occupy the pure-play consumer wellness tier, competing through simplified user protocols and influencer-mediated discovery rather than clinical validation claims.
| Leading Market Players |
|---|
| NuFACE |
| Solawave |
| CurrentBody |
| Panasonic Corporation |
| FOREO |
| TRIA Beauty |
| Philips |
| Alma Lasers |
| L'Oréal |
| Others |
Pricing and Supply Chain Analysis
Chinese LED fab scale economies at Yangtze River Delta facilities compress unit costs for entry-tier devices while German and United States RF manufacturing maintains price floors through ISO 13485 certification overhead and clinical validation proximity. This geographic bifurcation concentrates margin capture among professional-grade OEMs with quality management credentials while commoditizing wellness-tier positioning.
Pricing Analysis
United States dermatology practices command three-to-five times the unit price of equivalent at-home devices sold through Amazon and Sephora channels. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared professional platforms from CE-marked consumer units and unregulated wellness imports. Cost compression in the economy tier stems from Yangtze River Delta manufacturing scale and direct-to-consumer bypass of clinic markups. Spa owners show highest price sensitivity due to capital equipment budget constraints, while hospital purchasing committees demonstrate lowest sensitivity given reimbursement-adjacent positioning.
Supply Chain Analysis
China and South Korea anchor semiconductor fabrication for LED arrays and RF power chipsets, with Taiwan concentrating GaAs wafer supply for RF amplifiers. Device OEMs draw from gallium arsenide substrates, lithium-ion battery cells, and medical-grade aluminum enclosures as critical inputs. Single-source vulnerability in GaAs wafer supply among three East Asian foundries exposes margin timelines to input cost volatility. Distribution runs through dermatology clinic networks for professional-grade platforms and dedicated e-commerce platforms for at-home configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-synchronized treatment protocols between clinic and patient-owned units signal a platform-economics inflection where hardware margins migrate toward subscription software and consumable ecosystems.
For Market Incumbents: Fortify FDA 510(k) clearance portfolios against algorithmic dose adjustment reclassification debates that threaten to redraw category boundaries. Deepen exclusive distribution partnerships with United States medspa networks to lock in patient referral flows toward at-home maintenance protocols. Vertical integration into solid-state battery architectures reduces IEC 60601 recertification exposure from chemistry shifts.
For New Entrants and Emerging Players: Lead with ANVISA-harmonized RF platforms into Brazilian aesthetic medicine infrastructure where clinic network expansion outpaces cleared device supply. Brazilian spa owners present the most penetrable buyer archetype given technology-enabled differentiation demand and limited domestic manufacturing. Direct-to-consumer hybrid models through curated clinic partnerships bypass capital-intensive professional-grade certification requirements.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hybrid channel operators bridging clinic and direct-to-consumer distribution with existing ISO 13485 quality management infrastructure. Long-term viability hinges on regulatory navigation capabilities rather than manufacturing scale alone. Watch FDA software-as-medical-device classification determinations for algorithmic personalization features as the primary inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Acceleration | Compresses market access timelines for microcurrent and RF platforms in United States dermatology channels. |
| EU MDR CE Marking Pathway | Streamlines quality management reviews under ISO 13485 harmonization for German and broader European clinic networks. |
| Clinic Network Partnership | Drives patient referrals toward at-home maintenance protocols through exclusive distribution arrangements. |
| Software Companion Development | Triggers reclassification debates under FDA frameworks while enabling subscription revenue migration. |
| Reimbursement Strategy | Positions therapeutic-grade devices for medical claims coding adjacent to procedural dermatology revenue. |
Research Methodology
A standing panel of dermatology practice administrators, biomedical engineers at device OEMs, FDA regulatory consultants, and medspa procurement managers provided ongoing calibration across the study period. Primary interview findings combined with secondary validation from FDA 510(k) filings, EU MDR notified body databases, MFDS submission records, and customs trade data for LED and RF component flows. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Consistency checks validated volume and value outputs against external benchmarks including hospital procurement database trends and GPO contract disclosures. Segmentation modeling spanned product type, end user archetype, technology classification, and application indication across the projection horizon. CAGRs derived from fitted growth curves applied to technology-specific adoption S-cycles, with RF and microcurrent penetration rates calibrated against LED baseline saturation patterns.
The analysis sits within stated boundaries; outcomes outside sustained FDA clearance timeline acceleration or EU MDR harmonization stability would require recalibration. Forecasts reflect assumptions regarding GaAs wafer supply continuity and algorithmic feature classification determinations. Recalibration cycles align with material shifts in notified body review velocity and software-as-medical-device precedent rulings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Frizz Control Shampoo Market
Beauty & Personal Care
Global Lash Extension Market
Beauty & Personal Care
Global Organic Hair Color Market
Beauty & Personal Care
Anti-Aging Cosmetics Market
Beauty & Personal Care
Global Personal Care Emollients Market
Beauty & Personal Care
Europe Professional Beauty Services Market
Beauty & Personal Care
South Korea Dermocosmetics Market
Beauty & Personal Care
Anti-Dandruff Shampoo Market
Beauty & Personal Care
South America Deodorants Market
Beauty & Personal Care
Hair Wig Market
Beauty & Personal Care
Makeup Setting Spray Market
Beauty & Personal Care
Salon Products Market
Beauty & Personal Care
US Natural Personal Care Market
Beauty & Personal Care
Germany Cosmetics for Pregnancy Market
Beauty & Personal Care
Refillable Deodorants Market
Beauty & Personal Care
India Antibacterial Soap Market