
 Mobile Protective Cases Market | 2026-2036
Mobile Protective Cases Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Protective Cases Market Outlook
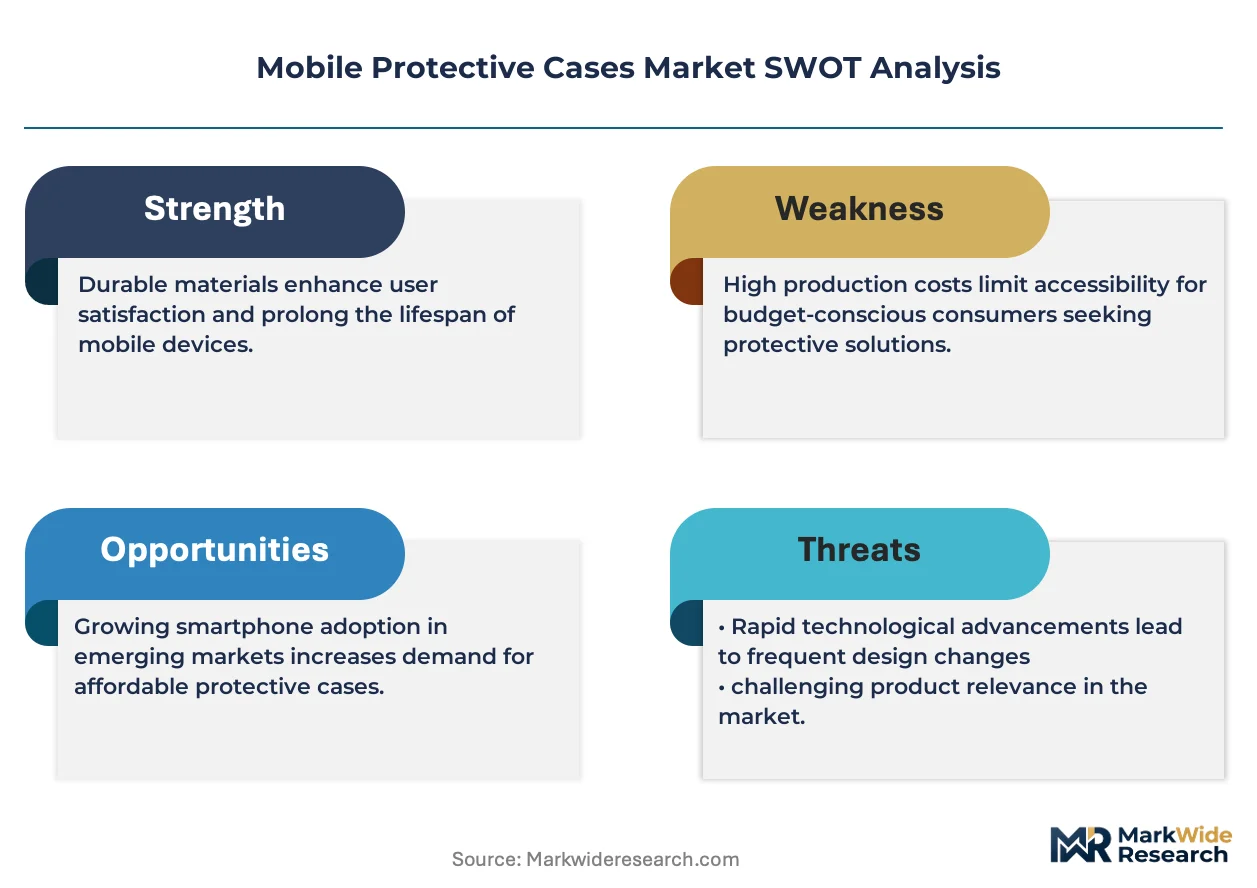
Enterprise procurement is shifting toward ruggedized protective solutions as technology sector employers expand BYOD reimbursement programs. OtterBox dominates military-grade certification channels with in-house drop-test protocols. Spigen competes through design-forward thin-profile cases that sustain premium pricing in direct-to-consumer channels.
Mobile protective cases are engineered enclosures—typically molded from polycarbonate, TPU, or silicone composites—that shield handheld computing devices from mechanical shock, particulate intrusion, and thermal stress while maintaining RF transparency and port accessibility. Hard case configurations occupy the largest volume share due to manufacturing scalability, while waterproof variants command the highest per-unit margins driven by IP68 certification requirements and marine end-use adoption. Battery case integration represents the fastest-expanding feature segment as consumers prioritize untethered power autonomy.
FCC equipment authorization rules govern electromagnetic compatibility for cases incorporating active electronics in the United States, while EU REACH and RoHS frameworks restrict phthalate and halogen content in polymer substrates sold across member states. California's Proposition 65 labeling mandates further shape material selection for brands distributing in North America. Stakeholders must monitor evolving right-to-repair legislation that could mandate case disassembly compatibility with OEM device architectures.
Market Dynamics
Enterprise BYOD reimbursement maturation is restructuring procurement volumes toward ruggedized protective solutions, while REACH and RoHS compliance mandates in the European Union are forcing polymer substrate reformulation across manufacturing footprints.
Growth Catalysts
- Domestic smartphone assembly scaling:India's PLI scheme for electronics manufacturing is accelerating local device production, driving parallel demand for accessorization among first-time buyers entering the smartphone ecosystem.
- Halogen-free TPU transition:ECHA's REACH enforcement and RoHS substance restrictions are compelling manufacturers to certify halogen-free thermoplastic polyurethane formulations for EU market access.
- Battery case integration:Untethered power autonomy requirements from mobile professionals are pulling active electronics enclosures into protective case architectures, expanding functional utility beyond mechanical protection.
Market Restraints
- Petrochemical input volatility:Polycarbonate and TPU feedstock costs fluctuate with crude oil derivatives, compressing margin stability for molded enclosure producers.
- IP68 certification timeline:Waterproof variant development requires extended validation cycles against IEC 60529 standards, delaying premium product launches.
- Thin-profile substitution pressure:Design-forward minimal cases from direct-to-consumer brands are fragmenting price realization for traditional protective configurations.
Strategic Opportunities
- Right-to-repair alignment:Emerging EU and US state-level repairability mandates are creating openings for case architectures designed around OEM device disassembly compatibility.
- Marine end-use expansion:IP68-certified waterproof variants are penetrating recreational boating and commercial fishing segments previously underserved by consumer-grade protection.
- Direct-to-enterprise channels:Technology sector employers are consolidating device protection into BYOD reimbursement bundles, bypassing retail intermediaries.
Industry Challenges
- RF transparency engineering:Active electronics integration demands specialized antenna window design and FCC equipment authorization, stretching in-house electromagnetic compatibility capabilities.
- Multi-jurisdiction labeling compliance:California Proposition 65 warning requirements叠加 EU substance declarations create packaging complexity for brands distributing across North America and Europe.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Protective Cases Market |
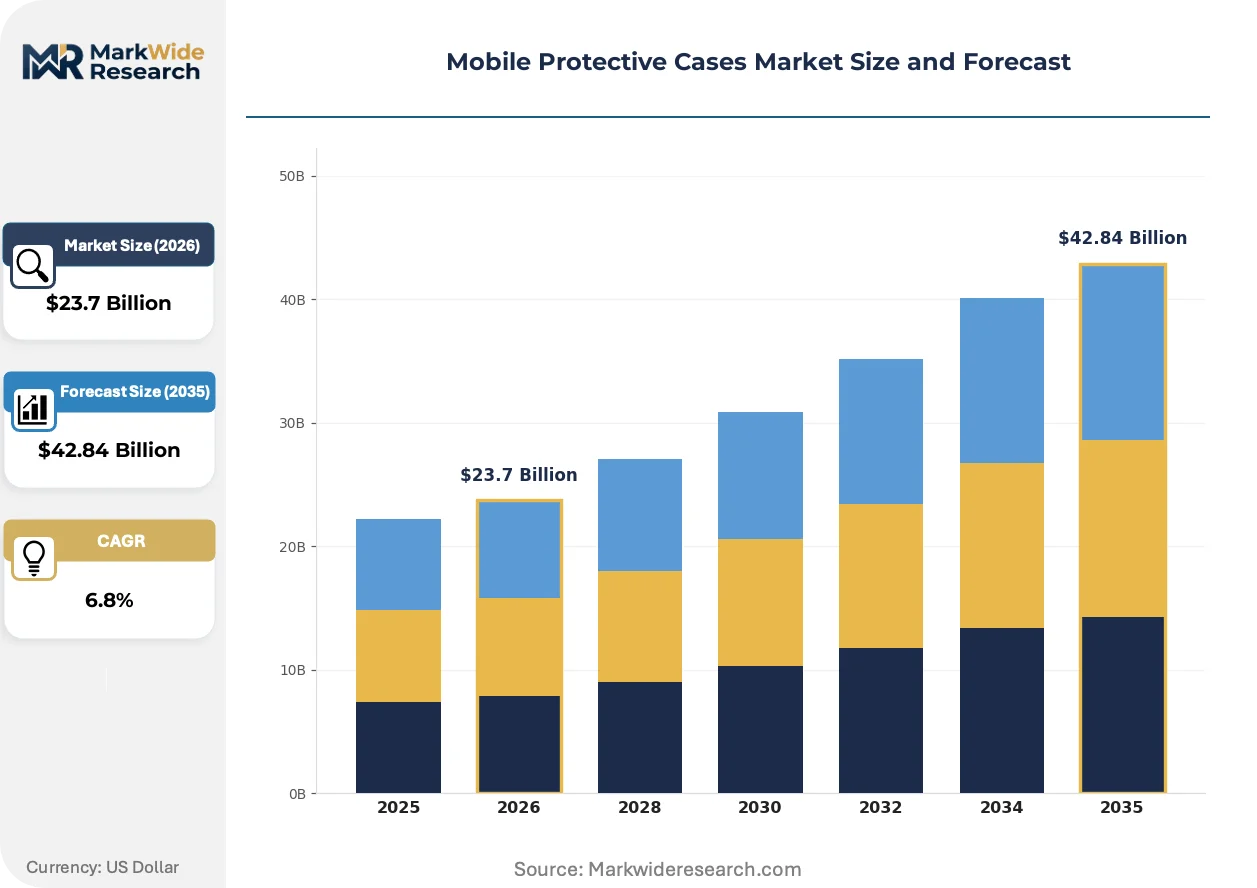
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Case Type: Hard Case, Soft Shell, Wallet Case, Waterproof Case Material: Polycarbonate, Silicone, TPU, Leather Feature: Shockproof, Scratch Resistant, Stand Function, Battery Case End User: Consumers, Corporates, Retailers, Schools |
| Companies Covered | OtterBox, Spigen, ZAGG, Incipio, Belkin International, Tech21, UAG (Urban Armor Gear), Casetify, Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Protective Cases Market Strategic Shifts
Material science advances and regulatory stringency are compressing development cycles while expanding functional boundaries beyond mechanical protection into power management and thermal regulation.
Biodegradable polymer development is converging with consumer sustainability preferences to reshape substrate selection. PLA-TPU composites and mycelium-based alternatives are entering pilot production for eco-conscious direct-to-consumer channels. This material transition is converging with premium pricing acceptance, enabling margin recovery from higher input costs.
EU REACH substance restriction expansion is tightening phthalate and halogen content ceilings for polymer substrates sold across member states. Manufacturers are requalifying supply chains to ECHA-registered alternatives ahead of enforcement windows. Waterproof variants with marine end-use certification face the steepest compliance burden due to adhesive and sealant reformulation requirements.
Enterprise procurement consolidation is bundling device protection into technology sector BYOD reimbursement programs. Direct sales teams are displacing retail distribution for volume accounts above five hundred units. This channel compression is most visible in North American technology clusters where employer-sponsored device policies have achieved critical mass.
Mobile Protective Cases Market Segmentation
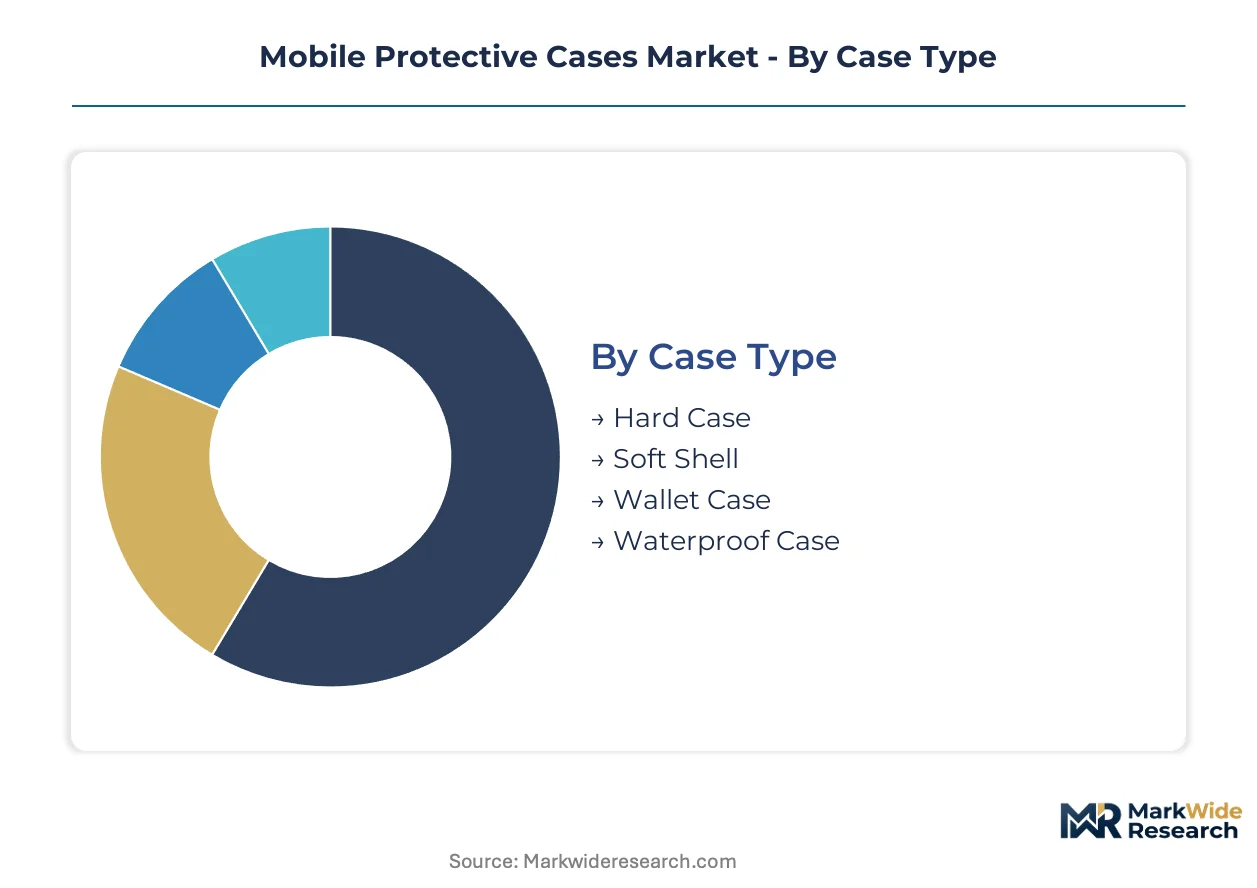
Protective case purchasing decisions hinge on trade-offs between mechanical protection, aesthetic integration, and functional augmentation. Each segmentation dimension captures a distinct axis of buyer prioritization—from material preference to end-use environment.
Case Type:
Buyers select enclosure architecture based on anticipated drop severity and daily handling conditions.
- Hard Case:Molded polycarbonate or composite shells deliver rigid impact distribution and manufacturing scalability at volume. Demand concentrates among first-time smartphone buyers in India where domestic assembly expansion is driving accessorization rates upward.
- Waterproof Case:IP68-certified enclosures with marine-grade seals and pressure-equalization valves command premium positioning. Recreational boating and commercial fishing segments in coastal United States markets are pulling these variants into previously underserved professional end-uses.
- Soft Shell:TPU and silicone wraps provide grip enhancement and corner cushioning with minimal bulk addition.
- Wallet Case:Folio configurations integrate card slots and cash compartments, appealing to consolidation-oriented consumers.
Volume sits with Hard Case configurations; growth tilts toward Waterproof Case as marine and industrial certifications expand addressable use cases.
Material:
Substrate selection balances impact absorption, regulatory compliance, and sustainability positioning.
- TPU:Thermoplastic polyurethane delivers Shore hardness tunability and RF transparency without signal attenuation. ECHA REACH enforcement and RoHS substance restrictions are compelling halogen-free formulation certification for EU market access.
- Polycarbonate:Engineering-grade resin provides rigid structural integrity and thin-wall moldability for precision-fit enclosures. Petrochemical feedstock volatility tied to crude derivatives is compressing margin stability for high-volume producers.
- Silicone:Elastomeric compounds offer tactile grip and thermal insulation with straightforward color customization.
- Leather:Natural and synthetic hide variants target premium direct-to-consumer channels with aging-patina aesthetics.
Polycarbonate dominates unit economics; TPU is climbing fastest on regulatory reformulation and sustainability preference convergence.
Feature:
Functional augmentation beyond mechanical protection is reshaping value capture and replacement cycles.
- Battery Case:Active electronics integration with lithium-polymer cells and FCC equipment authorization extends untethered operation. Mobile professionals across North American technology corridors are pulling power autonomy into protective enclosure specifications.
- Shockproof:Multi-layer dampening architectures with air-pocket corners and honeycomb substructures dissipate kinetic energy from meter-plus drops. Enterprise BYOD reimbursement programs are consolidating ruggedized specifications into procurement bundles.
- Scratch Resistant:Hard-coat surface treatments and tempered glass integration preserve optical clarity and resale value.
- Stand Function:Integrated kickstands and magnetic mounts enable hands-free media consumption and video conferencing.
Shockproof configurations anchor volume; Battery Case integration is gaining share fastest as power anxiety drives functional premiumization.
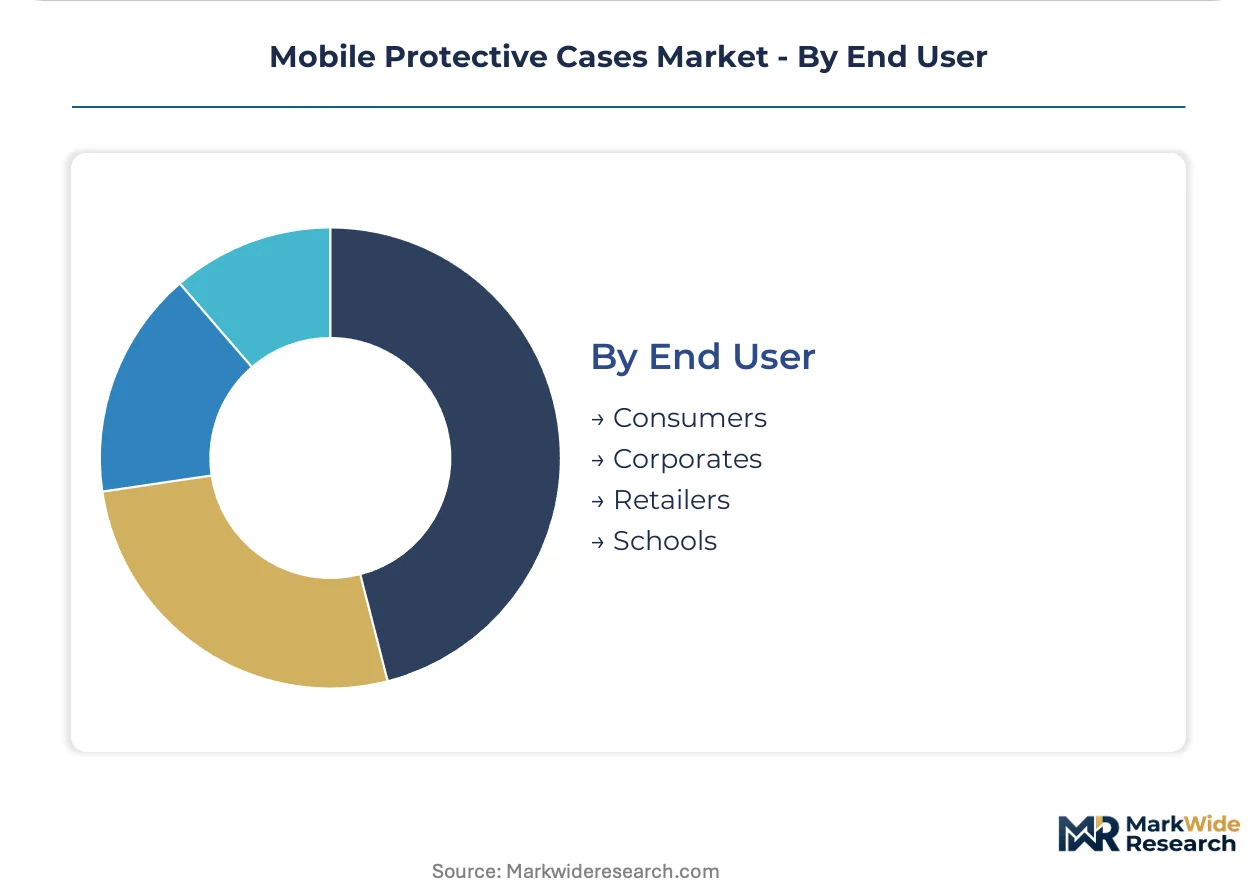
End User:
Procurement channel and volume scale differentiate buyer requirements and pricing realization.
- Corporates:Technology sector employers with mature BYOD policies are consolidating device protection into reimbursement programs. Direct sales teams are displacing retail intermediaries for accounts above five hundred units.
- Consumers:Individual purchasers through direct-to-consumer and retail channels prioritize design-forward thin-profile aesthetics alongside baseline protection.
- Retailers:Accessory bundling at point-of-sale captures impulse purchasing alongside device transactions.
- Schools:Educational institutional procurement emphasizes bulk durability and loss-prevention at cost-constrained budgets.
Consumer channels maintain volume concentration; Corporate procurement is expanding most quickly as employer-sponsored device policies achieve critical mass.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing scale concentrates in Asia while consumption tilts toward North America and Europe, creating divergent regulatory exposure across polymer supply chains and end-use markets.
United States
Enterprise BYOD reimbursement programs and marine recreational activity drive demand for ruggedized and waterproof variants. FCC equipment authorization governs active electronics integration in battery cases. California's Proposition 65 labeling mandates shape material selection for brands distributing through Los Angeles and San Francisco logistics hubs.
Germany
Industrial procurement from automotive and engineering sectors prioritizes precision-fit protective solutions for field-deployed devices. ECHA REACH enforcement and RoHS substance restrictions compel halogen-free TPU formulation certification. Manufacturing clusters in Bavaria and Baden-Württemberg host polymer compounding facilities serving EU-wide distribution.
India
Domestic smartphone assembly scaling under the PLI scheme accelerates accessorization rates among first-time buyers entering the smartphone ecosystem. BIS certification requirements apply to imported protective accessories. Tamil Nadu and Karnataka electronics manufacturing corridors concentrate device assembly capacity, driving parallel case demand.
China
Raw material supply and mold fabrication capacity anchor global polycarbonate and TPU substrate production. MIIT oversees electromagnetic compatibility standards for active electronics enclosures. Pearl River Delta manufacturing clusters in Guangdong Province supply component assemblies to downstream case fabricators worldwide.
Japan
Precision polymer processing and thin-profile design innovation support premium direct-to-consumer channels. METI administers JIS standards for electronic device accessories. Kanto region manufacturing bases around Tokyo and Yokohama specialize in high-tolerance injection molding for export markets.
Mobile Protective Cases Market Competitive Environment
Top-tier vendors anchor military-grade certification and direct-to-enterprise channels, while mid-scale specialists compete through design-forward aesthetics and rapid product cycle turnover. The vendor base stratifies across three functional tiers: ruggedized protection specialists, thin-profile design innovators, and OEM-integrated accessory providers. Capacity expansion and strategic channel compression into BYOD reimbursement bundles represent the dominant competitive moves reshaping procurement relationships.
Within the ruggedized protection tier, OtterBox exemplifies military-grade certification anchoring, while Spigen occupies a position among design-forward thin-profile specialists. ZAGG represents the functional augmentation archetype through active electronics integration. These three vendors collectively illustrate the strategic segmentation between mechanical protection, aesthetic minimalism, and power management extension that defines competitive positioning in protective case markets.
| Leading Market Players |
|---|
| OtterBox |
| Spigen |
| ZAGG |
| Incipio |
| Belkin International |
| Tech21 |
| UAG (Urban Armor Gear) |
| Casetify |
| Samsung Electronics |
| Others |
Value Chain & Pricing Dynamics
Enterprise technology sector employers consolidating BYOD reimbursement bundles command pricing leverage through direct procurement channels, compressing retail intermediaries and favoring contract-based volume offtake over spot-market transactions. This buyer concentration reshapes margin distribution across polycarbonate and TPU substrate tiers.
Pricing Analysis
Margin tightening in standard-grade hard cases reflects polycarbonate feedstock volatility tied to crude oil derivatives. Three-tier pricing structure across military-certified, design-forward, and economy private-label levels segments buyers by certification burden and brand premium. Price differentiation hinges on IP68 validation cycles and FCC equipment authorization for active electronics. Cost-down pressure accelerates in consumer channels as thin-profile imports from direct-to-consumer specialists erode traditional protective case price realization.
Supply Chain Analysis
Polycarbonate resin supply rests on petrochemical complexes in China, South Korea, and Saudi Arabia. TPU compounding draws from specialty chemical producers in Germany and the United States. Mold fabrication capacity concentrates in Guangdong Province and Taiwan. Single-source vulnerability in halogen-free adhesive formulations for waterproof variants creates compliance risk ahead of ECHA REACH enforcement windows. Distribution runs through Los Angeles and Rotterdam logistics hubs for North American and European retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive position in protective case markets hinges on backward integration into polymer compounding and captive mold fabrication capacity. Players securing upstream control over TPU formulation and IP68 sealant chemistry capture margin and compliance speed.
For Market Incumbents: Anchor military-grade certification leadership through in-house drop-test protocol investment and ECHA-registered halogen-free TPU supply chain capture. Deepen direct-to-enterprise channel control as technology sector BYOD reimbursement programs displace retail volume. Defend against design-forward thin-profile substitutes by accelerating battery case integration with FCC pre-certified antenna architectures. For New Entrants and Emerging Players: Capture marine end-use white space in recreational boating and commercial fishing segments underserved by consumer-grade IP68 variants. Target India's PLI-driven smartphone assembly corridors where domestic accessorization rates surge among first-time buyers. Enter through biodegradable PLA-TPU composite positioning for eco-conscious direct-to-consumer channels. For Investors and Strategic Acquirers: The window for entry favors mid-scale specialists with halogen-free formulation certification and marine-grade pressure-equalization valve engineering. Long-term viability centers on repairability-aligned case architectures as EU and US state-level right-to-repair mandates mature. Watch ECHA substance restriction expansion timelines as inflection triggers for supply chain requalification costs.| Strategic Initiative | Industry Significance |
|---|---|
| Halogen-Free TPU Certification | ECHA REACH compliance secures EU market access ahead of enforcement windows. |
| Battery Case Integration | FCC equipment authorization extends functional utility for mobile professionals. |
| Direct-to-Enterprise Channel Buildout | BYOD reimbursement bundling bypasses retail margin compression. |
| Marine IP68 Variant Development | Recreational boating certification opens professional end-use expansion. |
| Biodegradable Polymer Pilot Production | PLA-TPU composites align with sustainability premium pricing acceptance. |
Study Parameters
Multi-period observation of smartphone assembly capacity, accessorization rate trajectories, and polymer substrate pricing anchored the trend analysis, supplemented by interviews with case manufacturing executives, enterprise procurement officers at technology sector employers, polymer compounding specialists, and marine equipment distributors. Secondary validation drew from BIS certification databases, ECHA substance restriction notices, FCC equipment authorization filings, and customs trade records. Bottom-up volume builds across case type, material, and end-user segments triangulated against top-down market sizing.
Input-output matrices modeled polycarbonate and TPU feedstock cost pass-through, certification timeline delays, and channel shift elasticity across the projection horizon. Segmentation dimensions included case architecture, substrate composition, functional feature integration, and procurement channel. CAGRs derived from fitted growth curves applied to smartphone shipment forecasts and accessorization penetration assumptions. Industry-specific inputs encompassed PLI scheme capacity announcements and REACH enforcement phase-in schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to petrochemical price volatility, right-to-repair legislative progression, and marine certification adoption rates. Assumptions reflect documented regulatory trajectories and announced manufacturing capacity. A small set of triggers—ECHA substance list expansion, major employer BYOD policy revisions, and biodegradable polymer cost parity achievement—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Gear
China Pollution Mask Market
Protective Gear
Waterproof Cases Market
Protective Gear
Mobile Handset Protection Market
Protective Gear
Mobile Phone Protective Cover Market
Protective Gear
Military Boots Market
Protective Gear
Global Mobile Phone Protective Cases Market
Protective Gear
Work Boots Market
Protective Gear
Waterproof Boots Market
Protective Gear
Earplug Distributor Market
Protective Gear
Diving Suits Market
Protective Gear
Disposable Hygiene Footwear Market
Protective Gear
Heated Goggles Market
Protective Gear
Food Processing Uniforms Market
Protective Gear
Advanced Protective Gear and Armor Market
Protective Gear
Tactical Boots Market
Protective Gear
Equestrian Helmets Market