
 Europe Vegan Cosmetics Market | 2026-2036
Europe Vegan Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Vegan Cosmetics Market Insights
Leaping Bunny certification is unwinding competitive access across the Europe vegan cosmetics landscape, filtering out suppliers unable to meet cruelty-free audit cycles. Kjaer Weis leverages refillable packaging systems to anchor premium positioning in Scandinavia. MuLondon Organic specializes in small-batch botanical formulations that sustain artisan credibility against mass-market entrants. e.l.f. Cosmetics competes on price-accessible vegan lines that dominate volume channels in the United Kingdom and Ireland.
Europe vegan cosmetics comprise beauty and personal care formulations manufactured without animal-derived ingredients or animal testing, relying instead on plant-based emulsifiers, mineral pigments, and synthetic alternatives validated through in-vitro and reconstructed human epidermis testing protocols. Their commercial purpose centers on satisfying consumer ethical standards while delivering dermatological performance comparable to conventional products. Skin care commands the deepest margin pools as consumers prioritize botanical serums and moisturizers with traceable supply chains. Makeup experiences the fastest volume expansion as color cosmetics brands reformulate legacy SKUs to capture shifting purchase criteria. Hair care remains comparatively mature, with professional salon channels showing slower conversion rates than retail.
EMA ingredient safety assessments, REACH chemical registration requirements, and the EU Green Deal circular economy action plan collectively mandate disclosure of raw material origins and restrict substances linked to environmental harm. These frameworks compel reformulation investments and elevate compliance costs for non-European exporters seeking market access. Stakeholders must monitor pending amendments to the EU Cosmetics Regulation that could broaden mandatory fragrance allergen labeling beyond current thresholds.
Market Dynamics
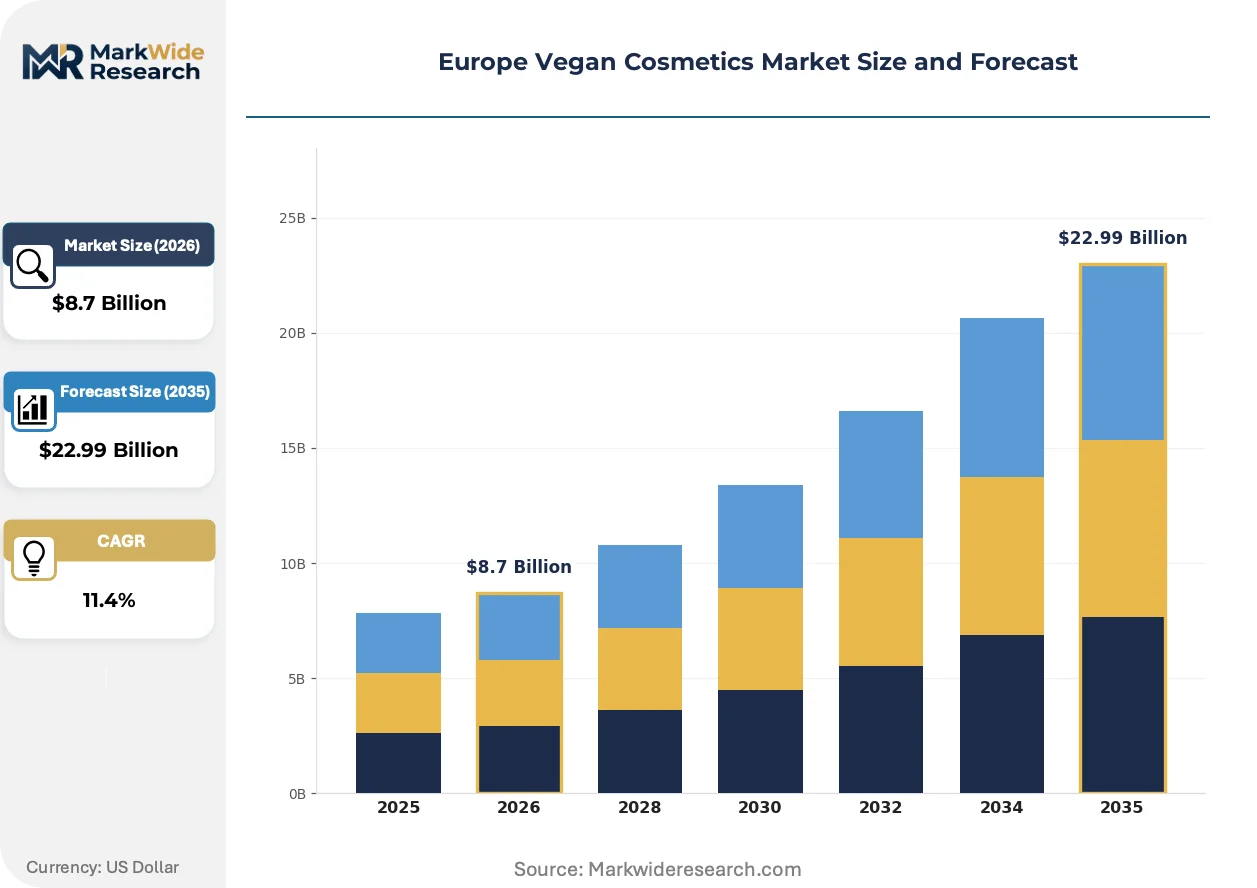
REACH chemical registration requirements and the EU Green Deal circular economy action plan are forcing wholesale reformulation investments across European vegan cosmetics supply chains. These frameworks elevate compliance costs while simultaneously creating competitive moats for domestic manufacturers with transparent botanical sourcing.
Growth Catalysts
- EU Green Deal circular economy mandates:Packaging reuse targets and waste reduction frameworks accelerate refillable system adoption among premium skin care brands seeking regulatory alignment.
- German millennial and Gen-Z demographics:Ethical consumption preferences in personal care categories drive volume expansion for certified cruelty-free color cosmetics through direct-to-consumer channels.
- Plant-based emulsifier innovation:Advanced botanical lipid alternatives validated through reconstructed human epidermis testing protocols reduce dependency on synthetic chemistry while maintaining dermatological performance benchmarks.
Market Restraints
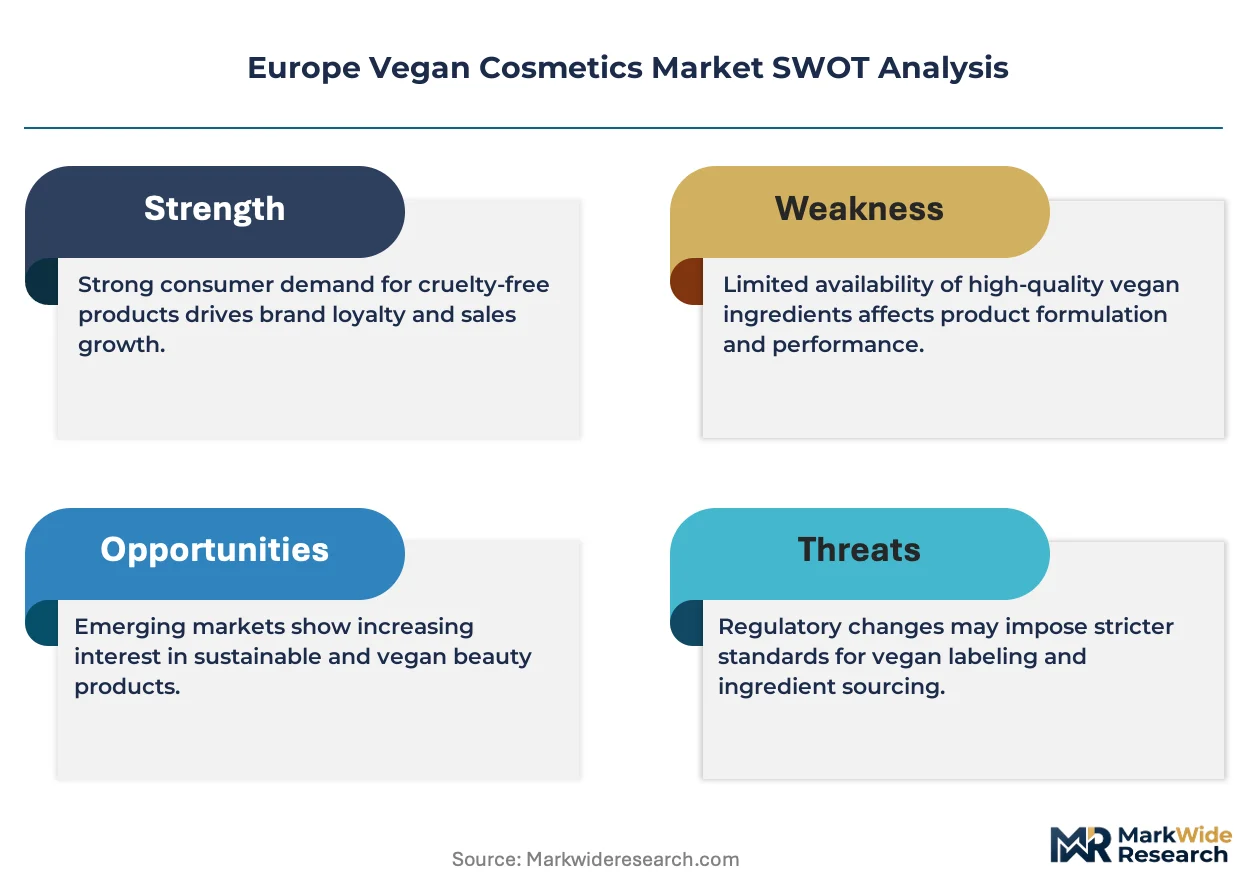
- Specialty botanical input cost volatility:Cold-pressed oils and rare plant extracts face price instability from climate-sensitive cultivation regions, compressing margin pools for small-batch formulators.
- Third-party cruelty-free certification concentration: Leaping Bunny and PETA audit cycles create bottleneck risks as demand for accredited suppliers outpaces qualified auditor availability across Northern Europe.
- Preservative efficacy limitations:Natural antimicrobial alternatives struggle to match synthetic paraben shelf-life extension, constraining water-based product development timelines.
Strategic Opportunities
- Eastern European retail underpenetration:Poland and Czech Republic specialty beauty channels show minimal vegan-certified SKU density relative to Western European saturation levels.
- Professional salon channel conversion:Hair care applications in licensed cosmetology settings represent untapped volume as retail-led skin care and makeup segments mature.
- EMA fragrance allergen labeling expansion:Pending amendments to EU Cosmetics Regulation disclosure thresholds create first-mover positioning for brands with pre-emptive transparent formulation strategies.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise bridging botanical efficacy with regulatory compliance remains concentrated among legacy European manufacturers, constraining new entrant R&D velocity.
- Multi-certification audit timelines:Simultaneous pursuit of vegan, organic, and cruelty-free credentials creates sequential validation bottlenecks extending product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Vegan Cosmetics Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skin Care, Hair Care, Makeup, Fragrance Ingredient Source: Botanical, Mineral, Synthetic, Plant-Based Application: Personal Care, Professional Use, Retail Use, Spa Services Packaging Type: Recyclable, Biodegradable, Glass, Plastic |
| Companies Covered | Byena Beauty, Arganour Cosmetics, Vary Vace, MuLondon Organic, Kjaer Weis, Nui Cosmetics, Pure U, e.l.f. Cosmetics, Und Gretel, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Vegan Cosmetics Market Trends and Innovations
Biotechnology-derived ingredients and circular packaging systems are actively restructuring competitive positioning across European vegan cosmetics. These shifts compress traditional supply chain configurations while elevating transparency requirements as baseline market entry conditions.
Solid waterless formulations utilizing concentrated surfactant bars and anhydrous balms are decomposing conventional emulsion chemistry dependencies. Indie beauty brands in Scandinavia and the Netherlands accelerate adoption, eliminating preservative load requirements while reducing shipping weights. This technology is decomposing established manufacturing infrastructure investments in liquid filling equipment across contract manufacturers.
REACH chemical registration requirements are tightening substance restriction thresholds for environmental persistence and endocrine disruption potential. The European Chemicals Agency enforcement agenda now targets UV filters and silicones prevalent in legacy sun care and primer formulations. Color cosmetics manufacturers face accelerated reformulation cycles as candidate substance lists expand beyond current inventory screening protocols.
Ingredient traceability verification has emerged as a non-negotiable purchase criterion among French and German prestige beauty consumers. Blockchain-enabled supply chain documentation displaces paper-based certification claims in premium retail channels. This behavioral pivot concentrates volume gains among brands with captive agricultural partnerships or vertically controlled extraction operations.
Europe Vegan Cosmetics Market Segmentation
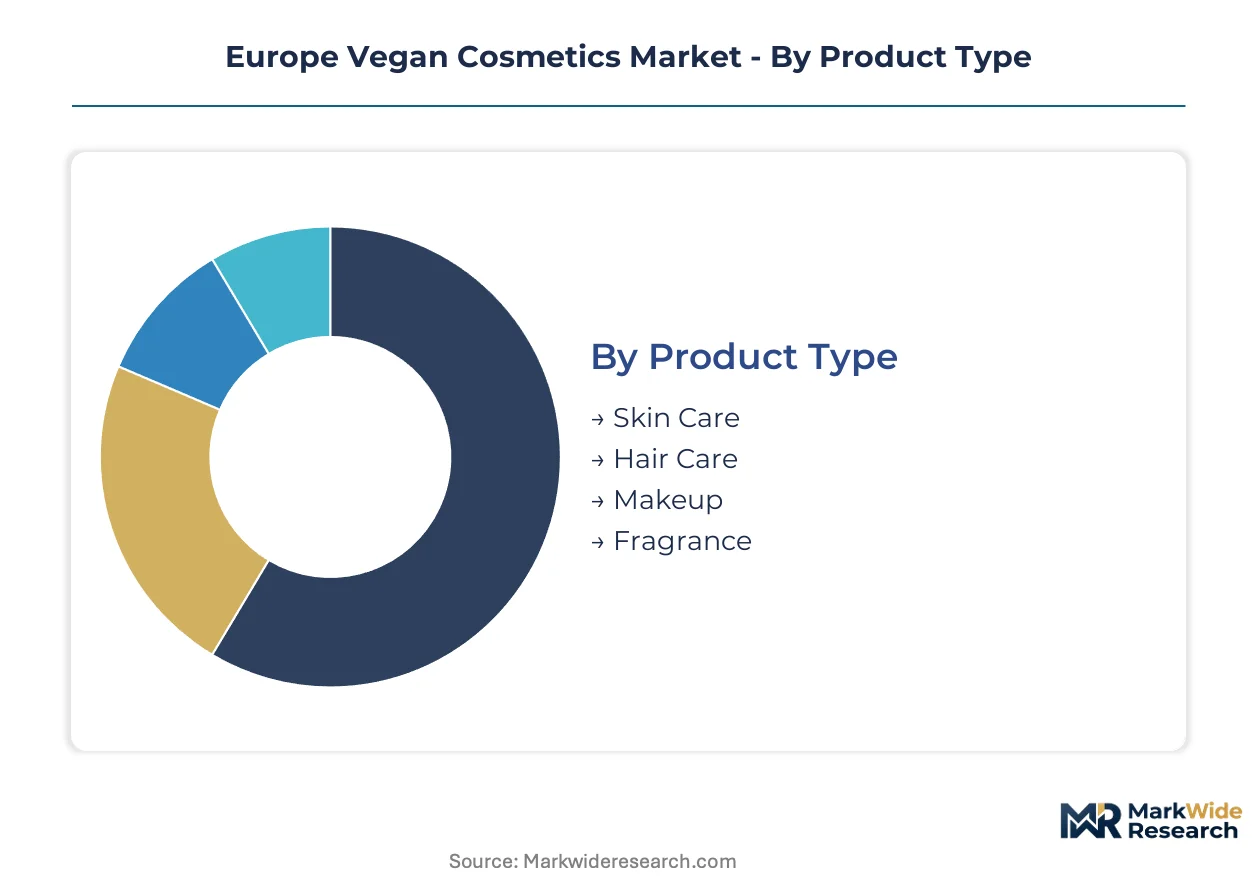
Segmentation in European vegan cosmetics reveals how regulatory frameworks and consumer ethics intersect to reshape purchasing patterns. REACH chemical registration and the EU Green Deal create divergent compliance burdens across product categories, ingredient sourcing strategies, and packaging formats. Understanding these divides allows stakeholders to allocate reformulation investments toward segments with the strongest margin protection.
Product Type:
REACH substance restrictions and EMA safety assessments apply unevenly across cosmetic categories, with leave-on products facing stricter preservative efficacy documentation than rinse-off alternatives. German and French consumers drive divergent demand patterns based on application duration and skin contact intensity.
- Skin Care:Formulations rely on plant-based emulsifiers and botanical lipid complexes validated through reconstructed human epidermis testing protocols. Northern European prestige channels concentrate demand for traceable supply chain serums and moisturizers as French consumers prioritize ingredient transparency documentation. REACH compliance costs elevate entry barriers for water-based creams requiring natural antimicrobial alternatives.
- Makeup:Color cosmetics manufacturers reformulate legacy SKUs with mineral pigments and synthetic alternatives to capture shifting purchase criteria among German millennial demographics. ECHA enforcement targeting UV filters and silicones accelerates reformulation cycles for primers and sun care hybrids. Direct-to-consumer channels in the United Kingdom and Ireland show fastest volume expansion for certified cruelty-free lines.
- Hair Care:Professional salon channels show slower conversion rates than retail, with licensed cosmetology settings retaining conventional formulations longer due to performance consistency requirements.
- Fragrance:Pending EU Cosmetics Regulation amendments on fragrance allergen labeling create compliance preparation urgency for brands with complex botanical essential oil blends.
Skin Care handles the majority of throughput; Makeup is the fastest mover on share.
Ingredient Source:
Cost tiers separate ingredient sourcing strategies, with cold-pressed botanical extracts commanding premium positioning against standardized synthetic alternatives. Supply chain transparency investments correlate directly with pricing power in German and French retail channels.
- Botanical:Cold-pressed oils and rare plant extracts from climate-sensitive cultivation regions face price instability that compresses margins for small-batch formulators. Scandinavian indie brands leverage solid waterless formulations to reduce preservative loads while maintaining artisan credibility. Blockchain-enabled supply chain documentation displaces paper-based certification claims in premium French retail.
- Synthetic:Laboratory-validated alternatives reduce dependency on agricultural supply volatility while satisfying REACH chemical registration requirements for environmental persistence thresholds. ECHA candidate substance list expansion targets legacy silicones prevalent in primer formulations.
- Mineral:Mica and iron oxide pigments require ethical sourcing verification to satisfy Leaping Bunny cruelty-free audit cycles.
- Plant-Based:Advanced botanical lipid alternatives bridge performance benchmarks with regulatory alignment across Northern European markets.
Botanical commands the deepest margin pools; Synthetic is expanding most quickly as manufacturers seek supply stability.
Application:
Volume concentration varies sharply between self-directed personal use and service-dependent professional channels, with divergent certification requirements and purchase decision timelines.
- Personal Care:Direct-to-consumer channels in Germany and the United Kingdom dominate volume for certified cruelty-free color cosmetics as millennial and Gen-Z demographics prioritize ethical consumption. Refillable packaging systems anchor premium positioning in Scandinavian markets aligned with EU Green Deal circular economy mandates.
- Professional Use:Licensed cosmetology settings in France and Germany show slower vegan formulation adoption due to performance consistency requirements and established supplier relationships.
- Retail Use:Specialty beauty channels in Poland and the Czech Republic exhibit minimal vegan-certified SKU density relative to Western European saturation levels.
- Spa Services:High-touch service environments prioritize botanical ingredient narratives to justify treatment premiums in German wellness tourism clusters.
Personal Care handles the majority of throughput; Retail Use is climbing the fastest as Eastern European distribution deepens.
Packaging Type:
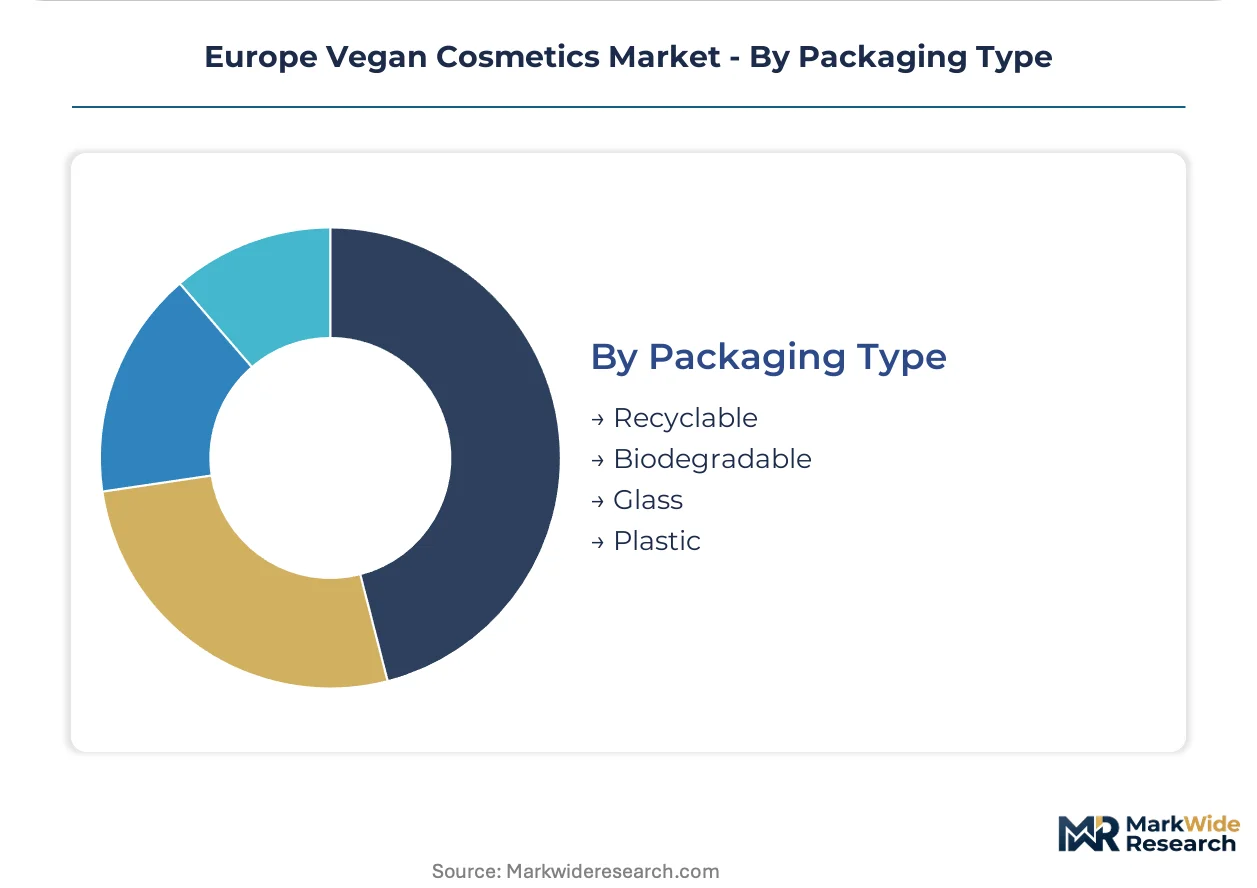
Supply concentration in glass manufacturing and biodegradable material innovation creates divergent cost structures across packaging categories, with circular economy compliance timelines driving strategic positioning.
- Recyclable:Standardized collection infrastructure across Germany and France supports cost-effective compliance with EU Green Deal waste reduction frameworks. Kjaer Weis leverages refillable aluminum systems to capture Scandinavian premium positioning.
- Biodegradable:Material innovation clusters in the Netherlands accelerate adoption of compostable alternatives that eliminate conventional plastic dependencies. Shelf-life limitations constrain water-based product development timelines.
- Glass:Heavy shipping weights increase logistics costs, though inert chemical properties satisfy REACH substance restriction documentation for reactive botanical formulations.
- Plastic:Conventional formats face regulatory pressure as ECHA enforcement agendas expand environmental persistence screening protocols.
Recyclable handles the majority of throughput; Biodegradable is gaining share fastest as circular economy mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal circular economy mandates and REACH chemical registration requirements are redistributing manufacturing capacity across European vegan cosmetics supply chains. Domestic producers with transparent botanical sourcing capture regulatory alignment advantages while non-European exporters face elevated compliance barriers.
Germany
Millennial and Gen-Z demographics in Berlin and Hamburg drive direct-to-consumer volume for certified cruelty-free color cosmetics. BfR consumer safety assessments align with REACH substance restriction protocols for leave-on skin care formulations. The North Rhine-Westphalia chemical manufacturing corridor concentrates contract formulation capacity serving private-label vegan brands.
France
Prestige beauty consumers in Paris and Lyon prioritize blockchain-enabled ingredient traceability documentation for botanical serums. ANSM cosmetic safety surveillance reinforces EMA guidelines on fragrance allergen disclosure thresholds. The Provence-Alpes-Côte d'Azur region anchors lavender and botanical extract cultivation clusters supplying premium formulators.
United Kingdom
Price-accessible vegan lines dominate volume channels in London and Manchester retail environments. The UK Cosmetics Regulation maintains REACH-aligned substance restrictions post-Brexit through retained EU law frameworks. The Southeast England distribution hub channels imported formulations through Dover and Felixstowe port infrastructure.
Scandinavia
Refillable packaging systems capture premium positioning in Copenhagen and Stockholm markets aligned with circular economy waste reduction targets. Swedish Chemicals Agency enforcement extends REACH candidate substance screening to UV filters in sun care hybrids. The Øresund region clusters solid waterless formulation innovation among indie beauty manufacturers.
Netherlands
Biodegradable material innovation accelerates in Amsterdam and Rotterdam specialty packaging channels. RIVM environmental health assessments evaluate endocrine disruption potential in botanical preservative alternatives. The Eindhoven polymer research corridor supplies compostable film technologies eliminating conventional plastic dependencies.
Europe Vegan Cosmetics Market Competitive Landscape
Player mix skews toward indie formulators and mid-scale specialists rather than consolidated multinational beauty conglomerates. Market structure fragments across certification tiers, with Leaping Bunny-accredited suppliers commanding shelf-space premiums in German and French prestige retail. Three archetypes dominate: artisan botanical specialists with captive agricultural partnerships, scale-oriented private-label manufacturers serving mass-market distributors, and biotechnology-integrated formulators leveraging fermentation-derived ingredients. Competitive dynamics center on sequential certification acquisition and circular packaging system deployment.
Among Scandinavian refillable packaging specialists, Kjaer Weis occupies a position exemplifying premium circular economy alignment. Within the price-accessible mass-market tier, e.l.f. Cosmetics represents volume-channel penetration strategies across UK and Ireland retail. MuLondon Organic anchors the artisan botanical archetype through small-batch formulation credibility against industrialized competitors.
| Leading Market Players |
|---|
| Byena Beauty |
| Arganour Cosmetics |
| Vary Vace |
| MuLondon Organic |
| Kjaer Weis |
| Nui Cosmetics |
| Pure U |
| e.l.f. Cosmetics |
| Und Gretel |
| Others |
Pricing and Supply Chain Analysis
Ninety-day inventory cycles for cold-pressed botanical extracts concentrate pricing power among French and German formulators with captive Provence-Alpes-Côte d'Azur agricultural partnerships, while spot-market dependency in synthetic emulsifier sourcing erodes margin stability for smaller Scandinavian competitors.
Pricing Analysis
Certification level creates the primary spread between Leaping Bunny-accredited premium tiers and uncertified mass-market alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by botanical traceability documentation and refillable packaging compliance. Pricing pressure stems from ECHA candidate substance list expansion forcing accelerated reformulation cycles. Price-sensitive volume buyers in UK and Ireland retail channels contrast with transparency-prioritizing prestige consumers in Paris and Lyon.
Supply Chain Analysis
Just-in-time inventory strategies dominate synthetic emulsifier procurement, while strategic stockpiling prevails for climate-sensitive lavender and rare plant extracts from Provence-Alpes-Côte d'Azur cultivation clusters. Supply concentrates in France, Germany, and the Netherlands for botanical inputs, with laboratory-validated alternatives drawing from Belgian and Swiss chemical manufacturing corridors. Single-source vulnerability in cold-pressed oil extraction creates bottleneck risks during adverse weather events. Distribution runs through Rotterdam and Antwerp port infrastructure serving Northern European contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-enabled ingredient traceability platforms are reconfiguring competitive moats around data interoperability standards, with EMA fragrance allergen labeling expansion creating first-mover advantages for brands with pre-emptive transparent formulation architectures.
For Market Incumbents: Secure captive agricultural partnerships in Provence-Alpes-Côte d'Azur and North Rhine-Westphalia to defend margin position against biotechnology-integrated fermentation entrants. Prioritize simultaneous Leaping Bunny and EU Green Deal circular economy certification acquisition to extend shelf-space premiums in German and French prestige retail channels. For New Entrants and Emerging Players: Anchor in Poland and Czech Republic specialty beauty channels where vegan-certified SKU density remains minimal relative to Western European saturation levels. Target professional salon hair care applications in licensed cosmetology settings for untapped volume conversion. Deploy direct-to-consumer subscription models with refillable packaging systems to bypass established distributor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across solid waterless formulation manufacturing as equipment retooling requirements accelerate. Long-term viability favors acquisition targets with vertically controlled extraction operations and blockchain-enabled supply chain documentation. Monitor ECHA enforcement agenda expansion targeting UV filters and silicones as signal for consolidation timing in color cosmetics reformulation services.| Strategic Initiative | Industry Significance |
|---|---|
| Refillable Packaging System Deployment | Kjaer Weis demonstrates circular economy alignment capturing Scandinavian premium positioning under EU Green Deal mandates. |
| Blockchain Traceability Integration | French prestige consumers now demand cryptographic supply chain verification displacing paper-based certification claims. |
| Biotechnology Fermentation Scale-Up | Laboratory-derived ingredients reduce dependency on climate-sensitive agricultural supply volatility. |
| Eastern European Distribution Expansion | Poland and Czech Republic specialty channels exhibit minimal vegan SKU density creating white-space capture opportunity. |
| Professional Salon Channel Conversion | Licensed cosmetology settings in France and Germany retain conventional formulations longer than retail segments. |
Research Methodology
Desk research of ECHA substance restriction databases, EU Cosmetics Regulation amendment filings, and customs import records preceded structured interviews with formulation chemists, cruelty-free certification auditors, and specialty beauty retail buyers across Germany, France, and Scandinavia. Bottom-up SKU-level volume estimates triangulated against top-down category expenditure data from national statistical offices and trade association disclosures.
Variance decomposition across product type, ingredient source, application channel, and packaging format segmentation dimensions anchored the analytical framework throughout the projection horizon. CAGRs derived from regression analysis of historical certification penetration rates and regulatory enforcement intensity indicators, with REACH compliance cost trajectories and EU Green Deal circular economy adoption curves serving as primary forecast inputs.
Material uncertainties — EMA fragrance allergen labeling threshold amendments, biotechnology ingredient safety assessments, and climate-induced botanical harvest volatility — sit outside the modeled envelope. Forecasts reflect assumptions regarding certification audit cycle availability and refillable packaging infrastructure deployment timelines. Revision becomes warranted when ECHA candidate substance list expansion accelerates beyond current screening protocol capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegan Cosmetics
Chile Vegan Cosmetics Market
Vegan Cosmetics
Argentina Vegan Cosmetics Market
Vegan Cosmetics
China Vegan Cosmetics Market
Vegan Cosmetics
Canada Vegan Cosmetics Market
Vegan Cosmetics
South Korea Vegan Cosmetics Market
Vegan Cosmetics
Asia-Pacific Vegan Cosmetics Market
Vegan Cosmetics
Australia Vegan Cosmetics Market
Vegan Cosmetics
US Vegan Cosmetics Market
Vegan Cosmetics
India Vegan Cosmetics Market
Vegan Cosmetics
Vegan Cosmetics Market
Vegan Cosmetics
Functional Cosmetics Market
Vegan Cosmetics
Spain Vegan Cosmetics Market
Vegan Cosmetics
France Vegan Cosmetics Market
Vegan Cosmetics
Vegan Beauty Products Market
Vegan Cosmetics
Organic Cosmetics Market
Vegan Cosmetics
Mexico Vegan Cosmetics Market