
 South Korea Vegan Cosmetics Market | 2026-2036
South Korea Vegan Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Vegan Cosmetics Market Insights
The price-performance gap between prestige vegan lines and mass-market alternatives is hardening as ingredient transparency becomes a non-negotiable purchase criterion. Amorepacific anchors its position through captive botanical sourcing in Jeju Island. COSRX competes on fermentation-derived actives that bypass traditional animal-derived emollients. Kolmar Korea sustains manufacturing scale as the dominant private-label producer for emerging domestic brands.
South Korea vegan cosmetics encompass beauty and personal care products formulated without animal-derived ingredients, animal by-products, or animal testing, typically relying on plant-based emulsifiers, synthetic peptides, and mineral pigments to achieve functional equivalence with conventional formulations. These products serve consumers seeking alignment between ethical consumption standards and the multi-step skincare regimens characteristic of Korean beauty culture. Face Care dominates current value generation through sheet masks and essences that command repeat purchase frequency. Online Retail captures the fastest volume expansion via live commerce platforms and subscription box models that reduce customer acquisition costs for niche entrants. The Plant-Based ingredient category occupies the deepest margin pools as domestic consumers associate botanical provenance with safety and hanbang-inspired efficacy claims.
MFDS cosmetic safety regulations and the Korea Agency for Technology and Standards' vegan certification criteria shape product development timelines and labeling requirements for brands seeking domestic retail placement. The EU-Korea Free Trade Agreement's mutual recognition provisions on cruelty-free standards ease export pathways for compliant manufacturers targeting European distribution channels. Stakeholders must monitor whether emerging synthetic biology-derived alternatives to plant extracts will trigger revised classification debates under existing vegan labeling frameworks.
Market Dynamics
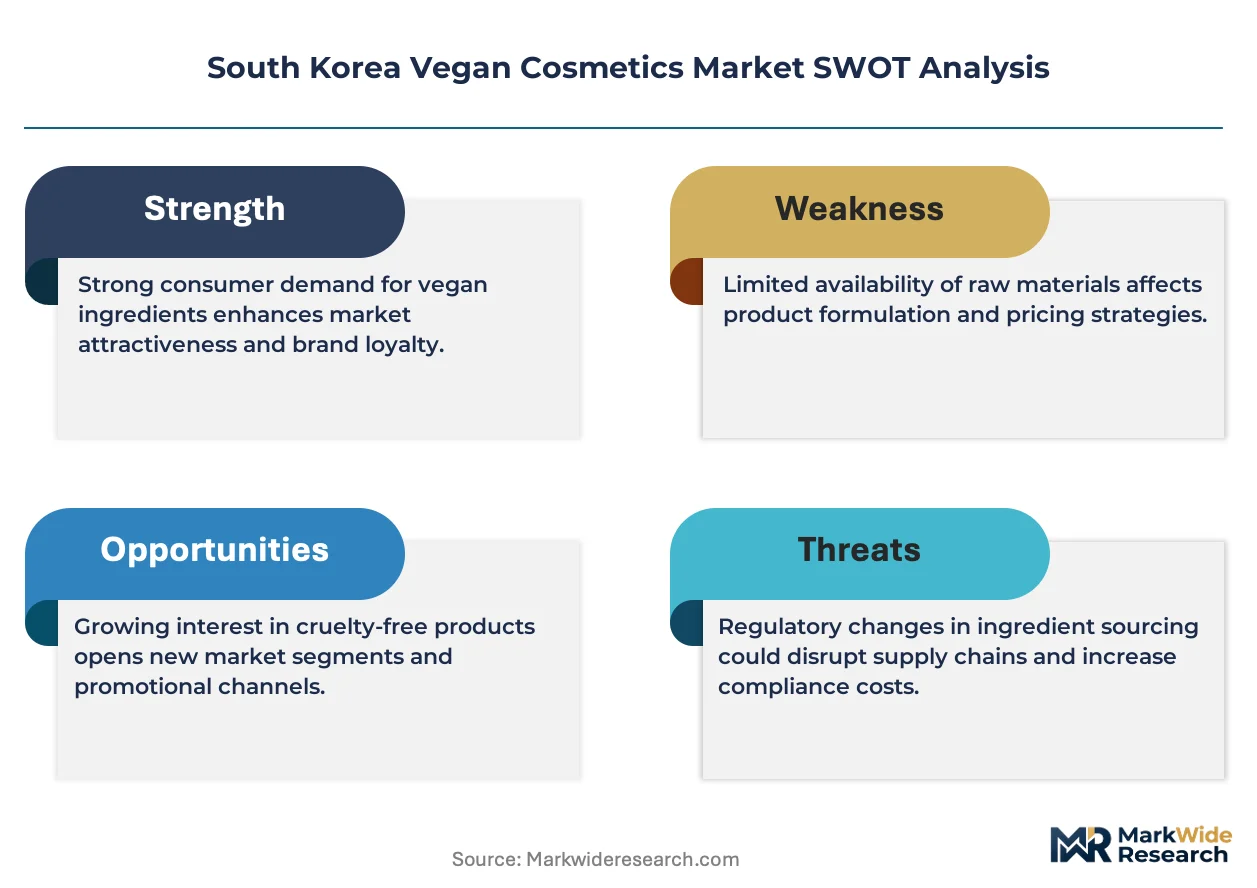
MFDS regulatory tightening on animal-testing exemptions forces accelerated reformulation timelines across domestic manufacturers, compressing product development cycles while elevating compliance costs for brands seeking domestic retail placement.
Growth Catalysts
- Regulatory harmonization:The EU-Korea Free Trade Agreement's mutual recognition provisions on cruelty-free standards streamline export pathways for compliant manufacturers targeting European distribution channels.
- Seoul retail corridor clustering:Clean beauty flagships concentrate in Gangnam and Hongdae districts, creating destination shopping experiences that reduce customer acquisition costs for emerging domestic brands.
- Fermentation biotechnology:Advanced fermentation-derived actives bypass traditional animal-derived emollients while delivering functional equivalence in multi-step skincare regimens.
Market Restraints
- Captive botanical supply constraints:Jeju Island's limited arable land restricts domestic sourcing of key plant-based emulsifiers, forcing reliance on imported raw materials subject to agricultural tariff volatility.
- Private-label manufacturing concentration:Kolmar Korea's dominance in contract manufacturing creates single-source vulnerability for emerging brands lacking in-house production capabilities.
- Synthetic biology classification uncertainty:Laboratory-cultured alternatives to plant extracts face pending reclassification debates under existing MFDS vegan labeling frameworks.
Strategic Opportunities
- Live commerce channel expansion:Subscription box models integrated with live streaming platforms reduce customer acquisition costs for niche entrants targeting young professional women in secondary cities.
- Hanbang-inspired efficacy positioning:Traditional Korean medicine heritage claims create differentiation opportunities in the Plant-Based ingredient category where consumers associate botanical provenance with safety.
- Busan retail corridor development:Underpenetrated premium positioning in South Korea's second-largest metropolitan area offers first-mover advantages for clean beauty flagships.
Industry Challenges
- Reformulation technical talent scarcity:Shortage of cosmetic chemists skilled in plant-based emulsifier substitution slows product pipeline velocity for brands transitioning from conventional formulations.
- MFDS certification timeline compression:Accelerated safety review requirements strain regulatory affairs teams, extending time-to-market for new vegan-designated product launches.
- Sheet mask supply chain reconfiguration:Shifting from animal-derived biocellulose to plant-based alternatives requires capital-intensive manufacturing line modifications at contract facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Vegan Cosmetics Market |
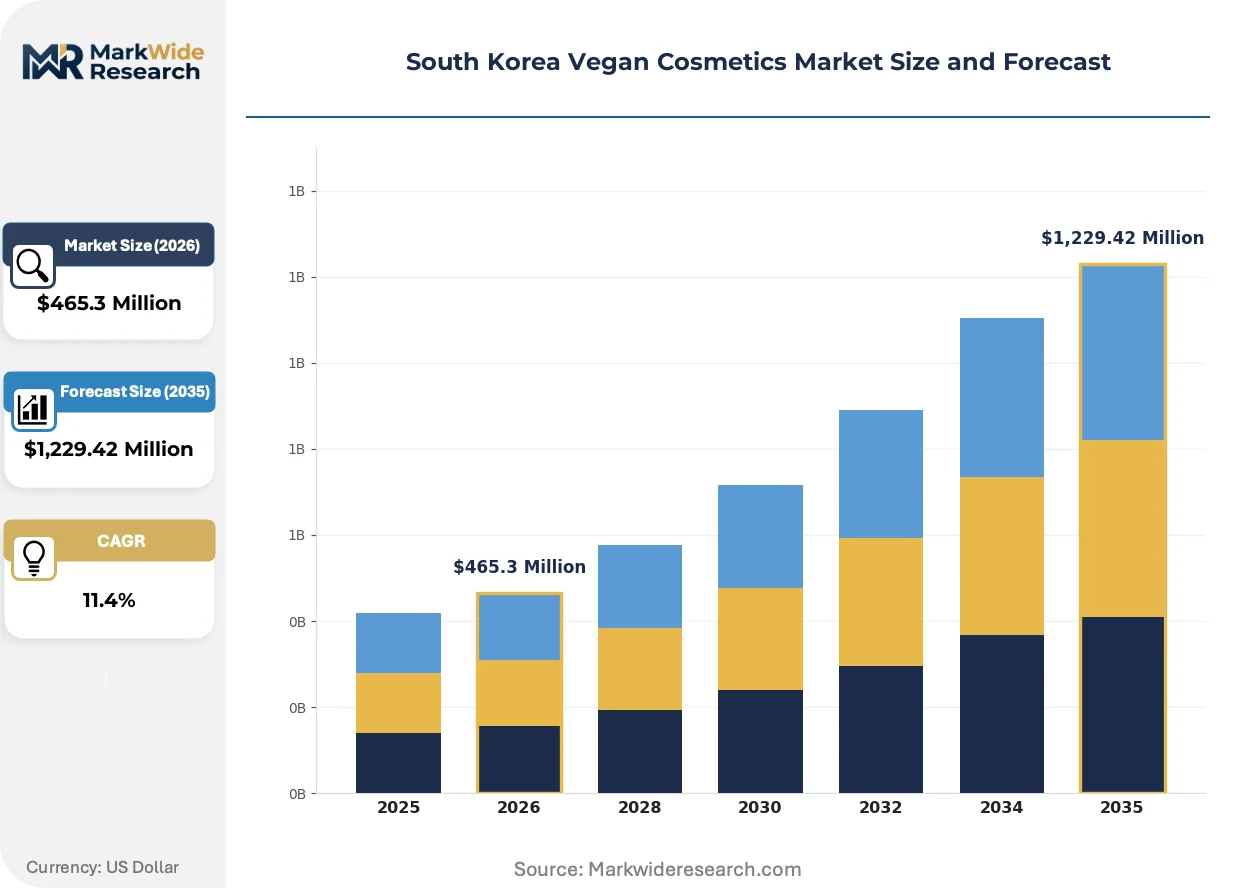
| Market Size in 2026 | $465.3 Million |
| Market Size in 2035 | $1,229.42 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Face Care, Hair Care, Makeup, Body Care Ingredient Category: Plant-Based, Synthetic, Mineral, Organic Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies End User: Women, Men, Teens, Cruelty-Free Consumers |
| Companies Covered | Cosmax, Dear, Amorepacific, COSRX, Klairs, LG Household & Health Care, Kolmar Korea, Olive Young, PNStory, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Vegan Cosmetics Market Trends and Innovations
Biotechnology-derived alternatives are actively reshaping ingredient sourcing strategies, while regulatory convergence and channel fragmentation simultaneously compress traditional go-to-market timelines for domestic brands.
Biotechnology-derived actives is absorbing capital allocation from conventional extraction methods as manufacturers seek alternatives to plant supply constraints. Seoul-based formulators adopt microbial fermentation platforms at accelerating pace to secure consistent input streams. This technology shift is absorbing margin pressure from agricultural commodity volatility while enabling claims of laboratory-controlled purity.
MFDS cosmetic safety regulations now mandate stricter documentation of animal-testing exemption eligibility, forcing brands to maintain comprehensive supply chain audit trails. Domestic manufacturers face compressed compliance timelines as the regulator eliminates grandfathering provisions for existing product registrations. Face Care segments with high repeat purchase frequency absorb disproportionate compliance burden due to extensive SKU portfolios requiring individual certification updates.
Live commerce platforms displace traditional department store counters as the primary discovery channel for vegan skincare purchases among young professional women. Subscription box models replace single-transaction retail by locking in recurring revenue streams and reducing customer acquisition costs for emerging entrants. This channel rotation concentrates in Seoul's digital-native consumer base before diffusing to Busan and other metropolitan areas.
South Korea Vegan Cosmetics Market Segmentation
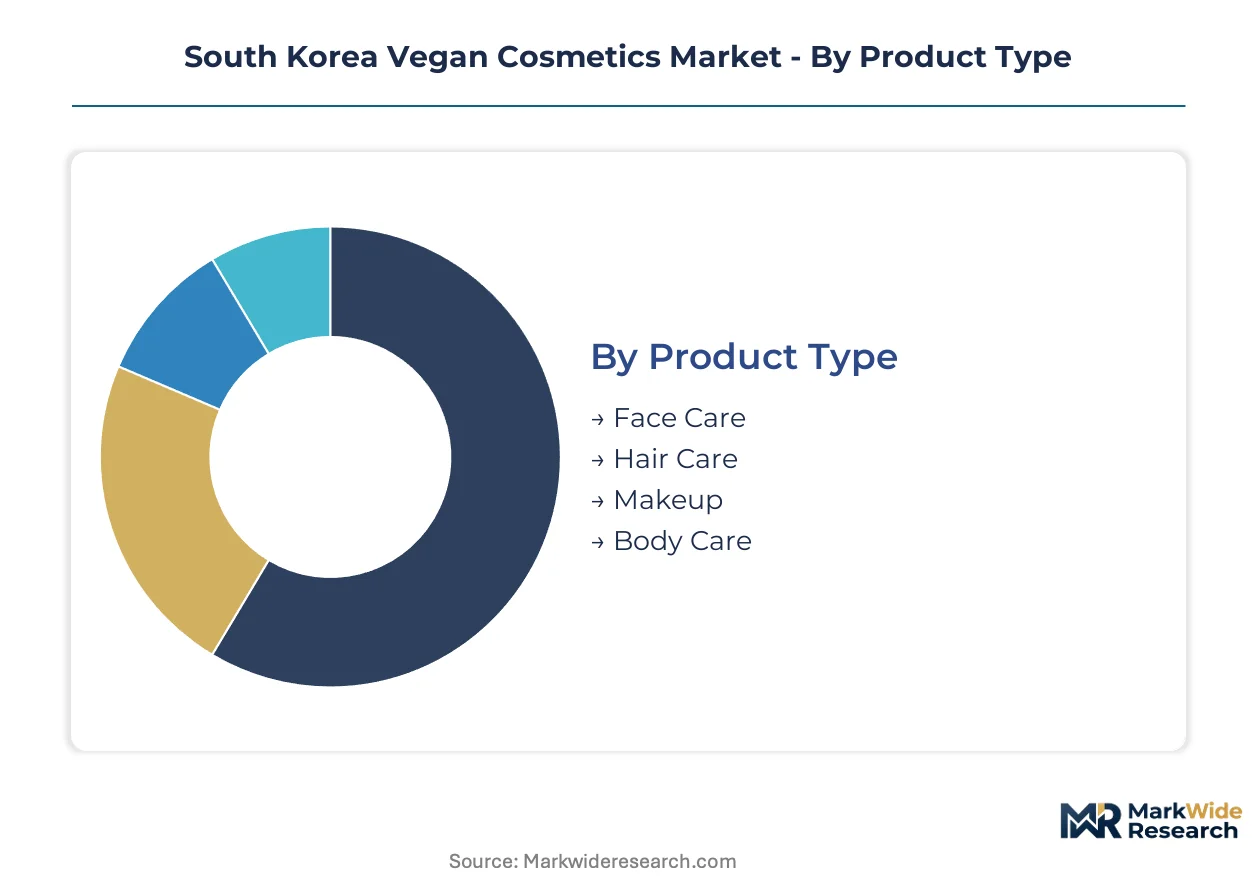
Segmentation in South Korea's vegan cosmetics market reveals how capital allocation, regulatory compliance, and channel economics concentrate value creation across distinct product and customer configurations. Manufacturers prioritize segments where fermentation biotechnology and MFDS certification requirements create defendable margin positions.
Product Type:
Capital intensity varies sharply across formulation complexity, with multi-step skincare regimens demanding substantially higher upfront R&D investment than single-use color cosmetics.
- Face Care:Sheet masks and essences require sophisticated plant-based emulsifier substitution and biocellulose sourcing alternatives. Demand concentrates among young professional women in Seoul's Gangnam district where repeat purchase frequency sustains premium pricing power against rising compliance costs.
- Hair Care:Fermentation-derived actives replace keratin and silk proteins in conditioners and scalp treatments. Adoption spreads through Busan's underpenetrated retail corridors as domestic brands seek geographic diversification beyond Seoul saturation.
- Makeup:Mineral pigments and synthetic waxes achieve color payoff without carmine or beeswax derivatives.
- Body Care:Lower formulation complexity attracts mass-market private-label entrants with limited technical capabilities.
Most installed capacity flows through Face Care. Expansion is steepest in Hair Care.
Ingredient Category:
Margin structures diverge based on input sourcing economics, with captive botanical supply commanding premium positioning against commodity synthetic alternatives.
- Plant-Based:Jeju Island-sourced botanicals anchor hanbang-inspired efficacy claims through controlled cultivation partnerships. Seoul consumers associate domestic botanical provenance with safety credentials, deepening margin pools despite agricultural supply constraints.
- Synthetic:Laboratory-controlled purity enables consistent batch performance without agricultural volatility. MFDS documentation requirements for animal-testing exemption eligibility apply uniformly across synthetic and natural inputs.
- Mineral:Mica and iron oxide sourcing faces emerging scrutiny over mining ethics and heavy metal contamination.
- Organic:Certification premiums struggle to justify price differentials against conventional plant-based alternatives in cost-conscious segments.
Plant-Based captures the deepest margin pools. Synthetic alternatives are climbing the fastest as manufacturers seek supply security.
Distribution Channel:
Customer acquisition economics favor digital-native models that reduce fixed retail overhead while enabling real-time conversion optimization.
- Online Retail:Live commerce platforms and subscription box models lock in recurring revenue streams. Young professional women in secondary cities discover vegan skincare through influencer-driven streaming events that bypass traditional department store counter economics.
- Specialty Stores:Clean beauty flagships in Hongdae create destination shopping experiences with immersive brand storytelling. Capital requirements for flagship fit-outs limit entrants to well-funded domestic players and multinational subsidiaries.
- Supermarkets:Mass-market volume play with compressed margins and limited SKU breadth.
- Pharmacies:MFDS cosmetic safety regulations enable derma-positioning claims that justify premium shelf placement.
Online Retail absorbs the steepest marketing investment. Specialty Stores deliver the highest per-transaction value.
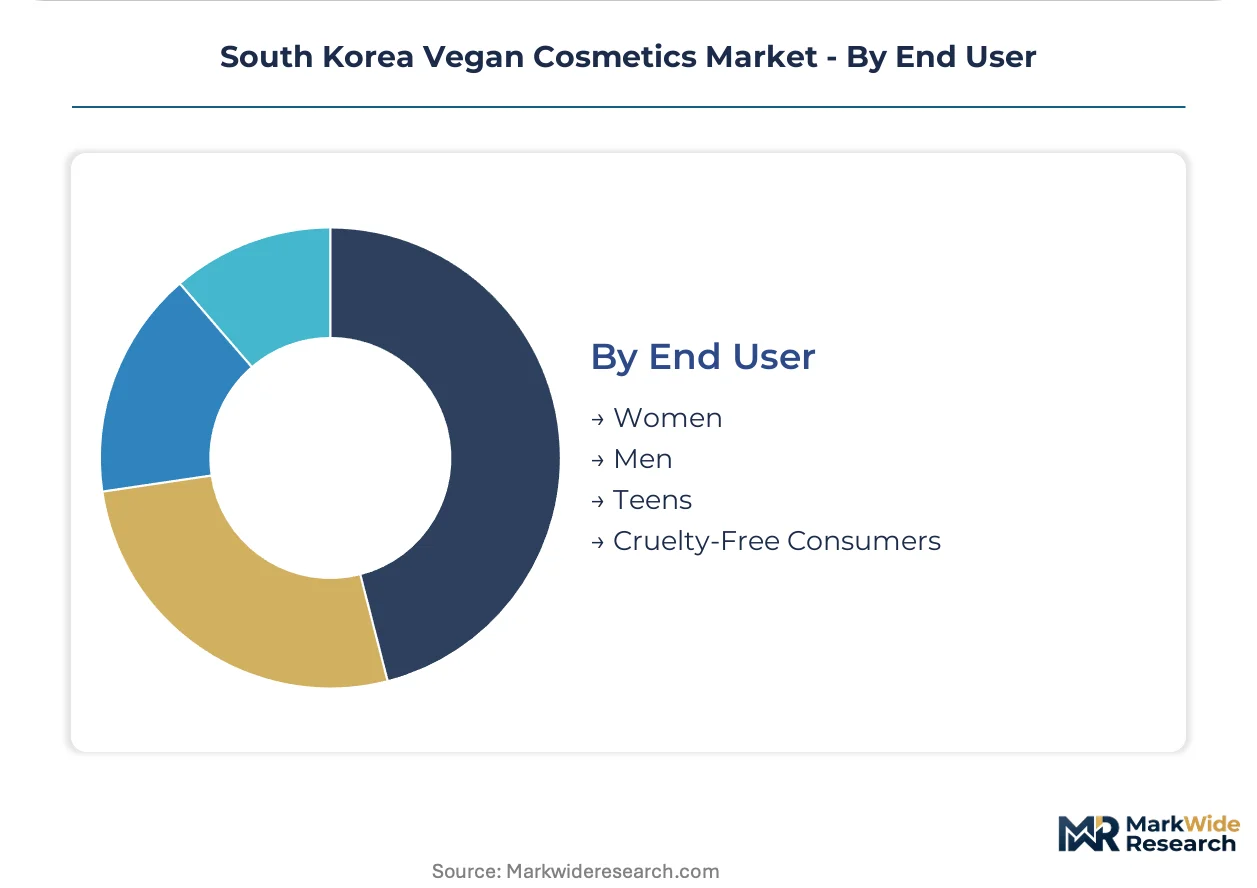
End User:
Purchase behavior segmentation tracks ethical conviction intensity against convenience-seeking pragmatism across demographic cohorts.
- Women:Multi-step skincare regimen adherence creates highest lifetime value through repeat essence and sheet mask purchases. Professional cohorts in Seoul and Busan drive premium segment volume with ingredient transparency as non-negotiable criterion.
- Men:Simplified routines concentrate in basic cleansing and moisturizing with lower SKU penetration per customer.
- Teens:Price sensitivity and social media discovery patterns favor online retail with limited brand loyalty.
- Cruelty-Free Consumers:Ethical conviction extends beyond ingredient sourcing to supply chain audit demands and packaging sustainability.
Women represent the dominant installed demand base. Cruelty-Free Consumers are expanding most quickly as ethical positioning penetrates mainstream purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cosmetic chemists and formulation specialists concentrate in Seoul Capital Area and Busan-Ulsan corridor, anchoring South Korea's vegan cosmetics innovation capacity.
Seoul Capital Area
Gangnam and Hongdae retail corridors host clean beauty flagships where young professional women drive repeat purchases of sheet masks and essences. MFDS cosmetic safety regulations mandate stricter documentation of animal-testing exemption eligibility for all domestic retail placement. Amorepacific maintains captive botanical sourcing partnerships in Jeju Island while operating flagship stores in Gangnam.
Busan-Ulsan
Underpenetrated premium positioning creates first-mover opportunities for clean beauty brands targeting South Korea's second-largest metropolitan area. The EU-Korea Free Trade Agreement's mutual recognition provisions on cruelty-free standards streamline export pathways for compliant manufacturers based in this logistics hub. Fermentation biotechnology specialists cluster in Ulsan's industrial zones to supply plant-based emulsifier alternatives.
Daegu-Gyeongbuk
Traditional hanbang medicine heritage supports botanical ingredient cultivation partnerships for hanbang-inspired efficacy claims. Regional agricultural cooperatives supply Jeju Island-restricted botanical alternatives to domestic formulators. Cosmetic manufacturing subcontractors in Daegu specialize in small-batch vegan certification runs for emerging domestic brands.
Daejeon-Sejong
Korea Agency for Technology and Standards operates vegan certification criteria development programs from Sejong administrative city. Research institutes in Daejeon pilot microbial fermentation platforms for laboratory-cultured alternatives to plant extracts. Regulatory affairs specialists cluster here to navigate MFDS timeline compression for new product registrations.
Gwangju-Honam
Agricultural supply chains for plant-based emulsifiers face tariff volatility due to limited domestic arable land in this southwestern region. Secondary city consumer bases discover vegan skincare through live commerce platforms reducing customer acquisition costs for niche entrants. Regional distributors test subscription box models before scaling to Seoul and Busan metropolitan areas.
South Korea Vegan Cosmetics Market Competitive Landscape
Top-tier vendors anchor premium positioning through captive botanical sourcing and fermentation biotechnology, while mid-tier contract manufacturers and private-label specialists compete on scale and speed-to-market. The vendor base stratifies across three tiers: integrated beauty conglomerates with Jeju Island cultivation partnerships, specialized fermentation technology firms, and private-label producers serving emerging domestic brands. Strategic archetypes include captive supply integrators, biotechnology formulators, and manufacturing-scale enablers. Competitive moves concentrate on backward integration into botanical sourcing and technology licensing for fermentation-derived actives.
Among integrated beauty conglomerates, Amorepacific and LG Household & Health Care occupy positions exemplifying captive supply chain control, while COSRX represents the biotechnology-specialist archetype emphasizing fermentation-derived formulations. Kolmar Korea anchors the manufacturing-scale tier as a dominant private-label producer enabling emerging domestic brands. These three companies collectively illustrate the competitive spectrum from upstream botanical control through formulation innovation to production scale.
| Leading Market Players |
|---|
| Cosmax |
| Dear |
| Amorepacific |
| COSRX |
| Klairs |
| LG Household & Health Care |
| Kolmar Korea |
| Olive Young |
| PNStory |
| Others |
Pricing and Supply Chain Analysis
Young professional women's ingredient transparency demands in Seoul's Gangnam and Hongdae corridors force manufacturers toward Jeju Island captive botanical sourcing and fermentation biotechnology, compressing margins on mass-market alternatives while deepening premium-tier pricing power.
Pricing Analysis
Subscription box models bundled with live commerce platform access separate premium hanbang-inspired lines from economy private-label alternatives. Price differentiation hinges on MFDS vegan certification tier and Jeju botanical provenance claims. Pricing pressure stems from Kolmar Korea's manufacturing concentration forcing emerging brands into volume commitments. Economy-tier entrants face acute price sensitivity as online retail discovery reduces brand loyalty stickiness.
Supply Chain Analysis
Dual-sourcing requirements for plant-based emulsifiers now mandate qualification of both Jeju Island agricultural cooperatives and Ulsan fermentation biotechnology facilities. Domestic supply draws from South Korea's captive botanical partnerships and imported raw materials subject to agricultural tariff exposure. Single-source vulnerability concentrates in Kolmar Korea's contract manufacturing dominance. Distribution runs through live commerce platforms displacing traditional department store counter economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation biotechnology cost curves and MFDS regulatory premium-tier bifurcation position this market for sustained margin expansion as synthetic-derived actives displace volatile agricultural inputs.
For Market Incumbents: Extend captive Jeju Island botanical partnerships into exclusive cultivation agreements that lock out emerging competitors. Deepen fermentation biotechnology R&D investment to accelerate biocellulose alternatives for sheet mask substrates. Kolmar Korea's manufacturing concentration threatens pricing autonomy; backward integration into pilot-scale production preserves formulation secrecy. For New Entrants and Emerging Players: The price-point gap between Amorepacific premium positioning and mass-market private-label creates white-space in Busan's underpenetrated retail corridors. Target secondary city professional women through subscription box models with hanbang-inspired efficacy claims. Live commerce platform partnerships reduce customer acquisition costs versus Hongdae flagship capital requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with fermentation biotechnology specialists possessing microbial platform IP and MFDS pre-certification relationships. Long-term viability favors formulators with laboratory-cultured alternatives to plant extract supply constraints. Watch for MFDS reclassification rulings on synthetic biology-derived ingredients as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Platform Scale-Up | Ulsan biotechnology clusters secure consistent input streams bypassing Jeju agricultural constraints. |
| Captive Jeju Cultivation Partnership | Exclusive botanical sourcing locks in hanbang-inspired efficacy claims for premium positioning. |
| MFDS Pre-Certification Investment | Accelerated safety review timelines compress time-to-market for vegan-designated launches. |
| Live Commerce Channel Integration | Subscription box models reduce customer acquisition costs in secondary city expansion. |
| Synthetic Biology R&D Pipeline | Laboratory-cultured alternatives hedge against plant extract supply volatility and tariff exposure. |
Research Methodology
Coverage spans Seoul Capital Area, Busan-Ulsan corridor, and Daegu-Gyeongbuk region, with primary inputs from each. Cosmetic chemists, regulatory affairs specialists at MFDS, brand managers at domestic conglomerates, and procurement leads at Kolmar Korea provided structured interviews. Secondary validation drew from MFDS cosmetic safety filings, Korea Agency for Technology and Standards certification databases, EU-Korea Free Trade Agreement documentation, and Jeju Island agricultural cooperative export records. Bottom-up SKU-level modeling triangulated against top-down category spend estimates.
Granularity-level modeling operated at product type, ingredient category, distribution channel, and metropolitan retail corridor dimensions across the analysis window. CAGRs derived from segment-level volume trajectories weighted by repeat purchase frequency patterns and compliance cost absorption rates. Fermentation biotechnology adoption curves and live commerce penetration rates served as industry-specific forecast inputs.
Caveats apply where MFDS reclassification of synthetic biology-derived ingredients or EU-Korea Free Trade Agreement cruelty-free standard revisions could materially shift the outlook. Deviation in Jeju Island agricultural output or Kolmar Korea manufacturing capacity allocation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegan Cosmetics
Organic Cosmetics Market
Vegan Cosmetics
Spain Vegan Cosmetics Market
Vegan Cosmetics
Argentina Vegan Cosmetics Market
Vegan Cosmetics
Global Probiotic Cosmetics Market
Vegan Cosmetics
Mexico Vegan Cosmetics Market
Vegan Cosmetics
Functional Cosmetics Market
Vegan Cosmetics
Vegan Face Cream Market
Vegan Cosmetics
Europe Vegan Cosmetics Market
Vegan Cosmetics
US Vegan Cosmetics Market
Vegan Cosmetics
Vegan Cosmetics Market
Vegan Cosmetics
Vegan Beauty Products Market
Vegan Cosmetics
Chile Vegan Cosmetics Market
Vegan Cosmetics
Asia-Pacific Vegan Cosmetics Market
Vegan Cosmetics
Italy Vegan Cosmetics Market
Vegan Cosmetics
China Vegan Cosmetics Market
Vegan Cosmetics
Japan Vegan Cosmetics Market