
 Chile Vegan Cosmetics Market | 2026-2036
Chile Vegan Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Vegan Cosmetics Market Insights
Chile's updated cosmetics labeling regulation under the Ministry of Health is expanding compliance costs for importers while creating advantages for domestic reformulators. L'Oréal Chile leverages its Santiago distribution infrastructure to preempt regulatory bottlenecks. Natura Cosméticos anchors its position through captive sourcing of Amazonian botanicals. The Body Shop differentiates via fixed cruelty-free certifications that satisfy both local and cross-border standards.
Vegan cosmetics exclude animal-derived ingredients and animal testing across formulation, production, and packaging stages, with primary commercial purpose centered on ethical positioning and allergen reduction for sensitive-skin consumers. Skincare leads volume contribution due to higher repurchase frequency and serum concentration premiums. Specialty shops capture disproportionate margin pools through assisted selling and sampling economics. Online channels represent the fastest-growing distribution vector as last-mile logistics improve in Chile's secondary cities.
Chile's Ministry of Health, the National Customs Service, and ISO 16128 standards collectively govern ingredient verification, import clearance, and naturalness claims in this market. Compliance with these frameworks determines shelf access for both domestic manufacturers and foreign entrants. Stakeholders must monitor regulatory alignment between Chilean labeling mandates and evolving Mercosur technical standards to anticipate harmonization costs or competitive displacement.
Market Dynamics
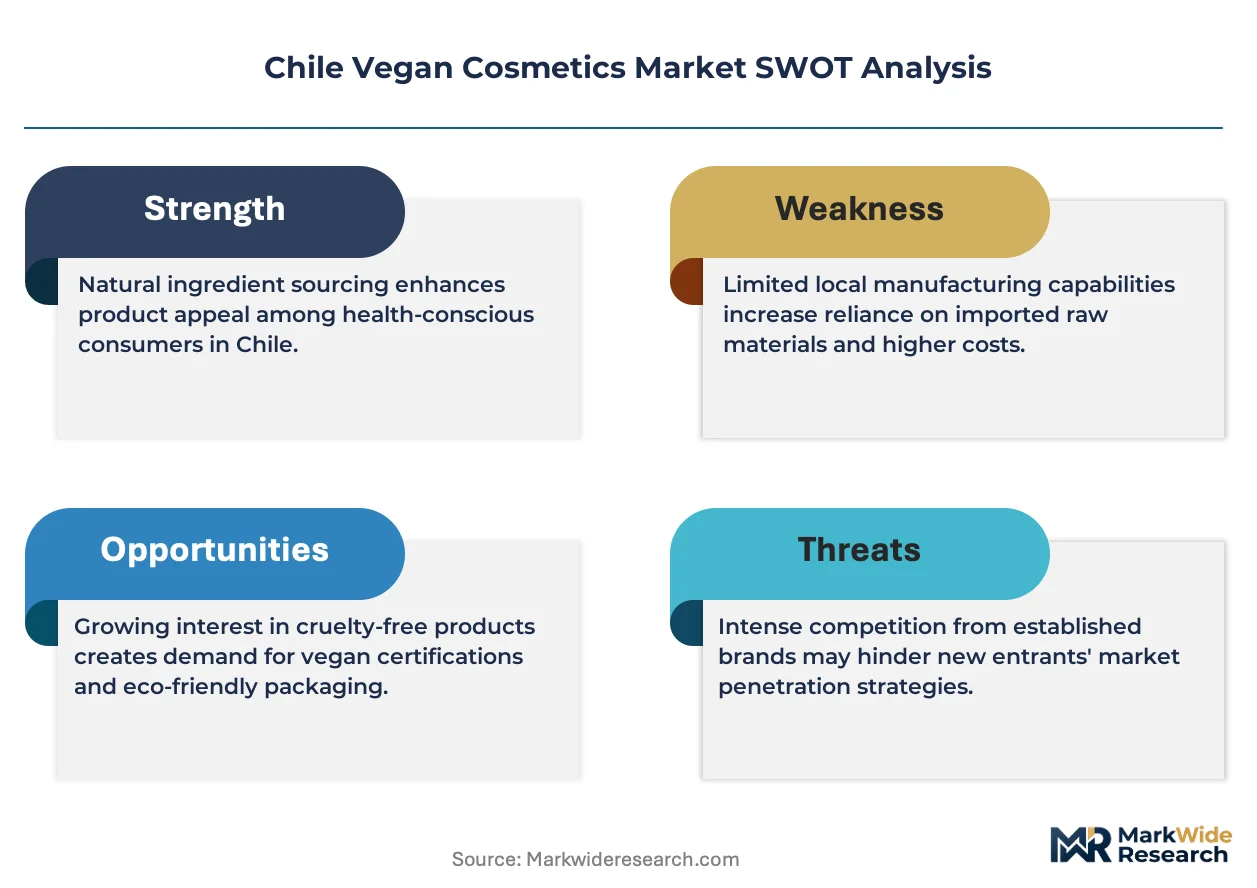
Chile's Ministry of Health labeling mandates are forcing ingredient transparency upgrades across domestic and imported vegan cosmetics, compressing reformulation timelines while elevating compliance costs for smaller distributors.
Growth Catalysts
- ISO 16128 naturalness standards:Chilean regulators align with these international benchmarks, accelerating domestic certification adoption and reducing cross-border friction for Amazonian-sourced botanical suppliers.
- Secondary city logistics expansion:Improved last-mile delivery infrastructure in Concepción and La Serena unlocks online channel penetration for vegan skincare brands previously concentrated in Santiago.
- Serum concentration premiums:High-repurchase-frequency skincare formats command pricing power that subsidizes vegan certification costs across product portfolios.
Market Restraints
- Quillaja saponaria supply concentration:Chile's native soapbark extract dependency creates input volatility for domestic formulators lacking captive Amazonian sourcing agreements.
- Import clearance friction:The National Customs Service extended verification protocols delay European and Asian vegan brand entry, advantaging established Santiago-based distributors.
- Conventional surfactant cost undercutting:Petrochemical-derived cleansing agents maintain price advantages in mass-market shampoo and body wash segments.
Strategic Opportunities
- Valparaíso specialty retail corridor:Assisted-selling beauty boutiques in this port city capture disproportionate margin pools through sampling economics and certified vegan curation.
- Mercosur harmonization alignment:Chilean regulators signal future technical standard convergence with Brazilian ANVISA frameworks, preemptive compliance positioning opens Argentine and Uruguayan export pathways.
- Biotechnology-fermentation convergence:Lab-cultured squalane and collagen alternatives reduce botanical harvest dependency while satisfying ISO 16128 naturalness thresholds.
Industry Challenges
- Reformulation chemist scarcity:Chilean universities produce limited cosmetic formulation specialists trained in plant-based emulsifier substitution and preservative-free stability testing.
- Cruelty-free certification timeline compression:Dual Leaping Bunny and PETA verification requirements extend product launch cycles by eight to fourteen months for import-dependent brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Vegan Cosmetics Market |
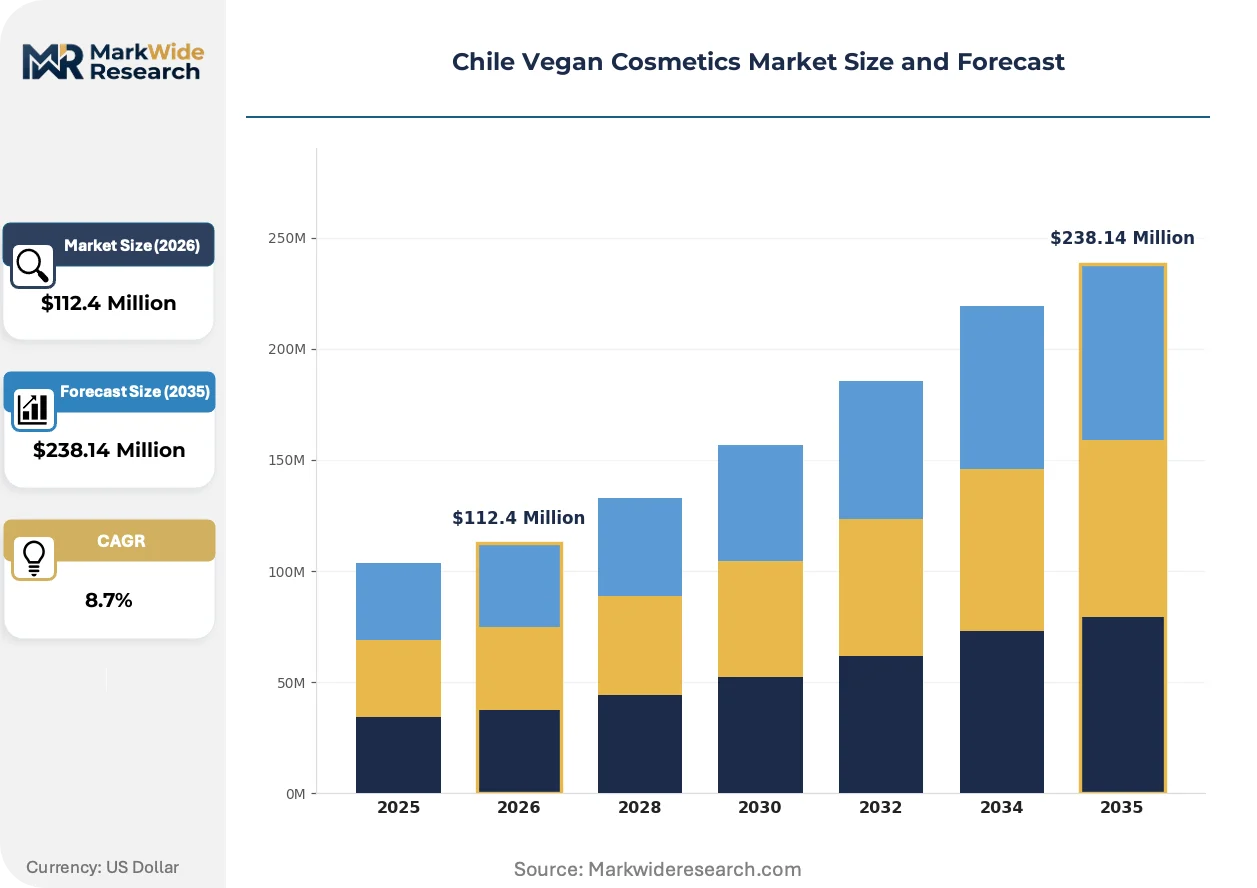
| Market Size in 2026 | $112.4 Million |
| Market Size in 2035 | $238.14 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Makeup, Fragrance Ingredient Source: Plant-Based, Organic, Mineral, Synthetic-Free End User: Women, Men, Unisex, Professionals Distribution Channel: Online, Retail Stores, Specialty Shops, Pharmacies |
| Companies Covered | L'Oréal Chile, Natura Cosméticos, The Body Shop, Unilever Chile, Estée Lauder Companies, Procter & Gamble, Avon Chile, Beiersdorf, Coty, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Vegan Cosmetics Market Trends and Innovations
Biotechnology-derived alternatives are displacing wild-harvested botanicals in Chilean vegan cosmetics, while regulatory transparency mandates and direct-to-consumer channel migration reshape competitive positioning across price tiers.
Plant stem cell cultivation technology is absorbing market share from conventional extraction methods. Domestic formulators in Santiago adopt this bioprocessing approach to stabilize quillaja and aloe vera supply. The technology is absorbing volatility premiums previously embedded in wild-harvested ingredient contracts.
Chile's Ministry of Health expanded ingredient disclosure requirements now mandate quantitative listing of all fragrance allergens above 0.001 percent concentration. This regulatory shift forces reformulation of legacy preservative systems and accelerates domestic lab investment in chromatography verification equipment. Skincare serums face the steepest compliance costs due to complex botanical active matrices.
Specialty shop assisted-selling models are losing traffic to subscription-based sampling programs. Young urban consumers in Santiago and Valparaíso now trial vegan cosmetics through curated monthly boxes before committing to full-size purchases. This behavioral pivot concentrates brand discovery budgets into logistics partnerships rather than in-store education staffing.
Chile Vegan Cosmetics Market Segmentation
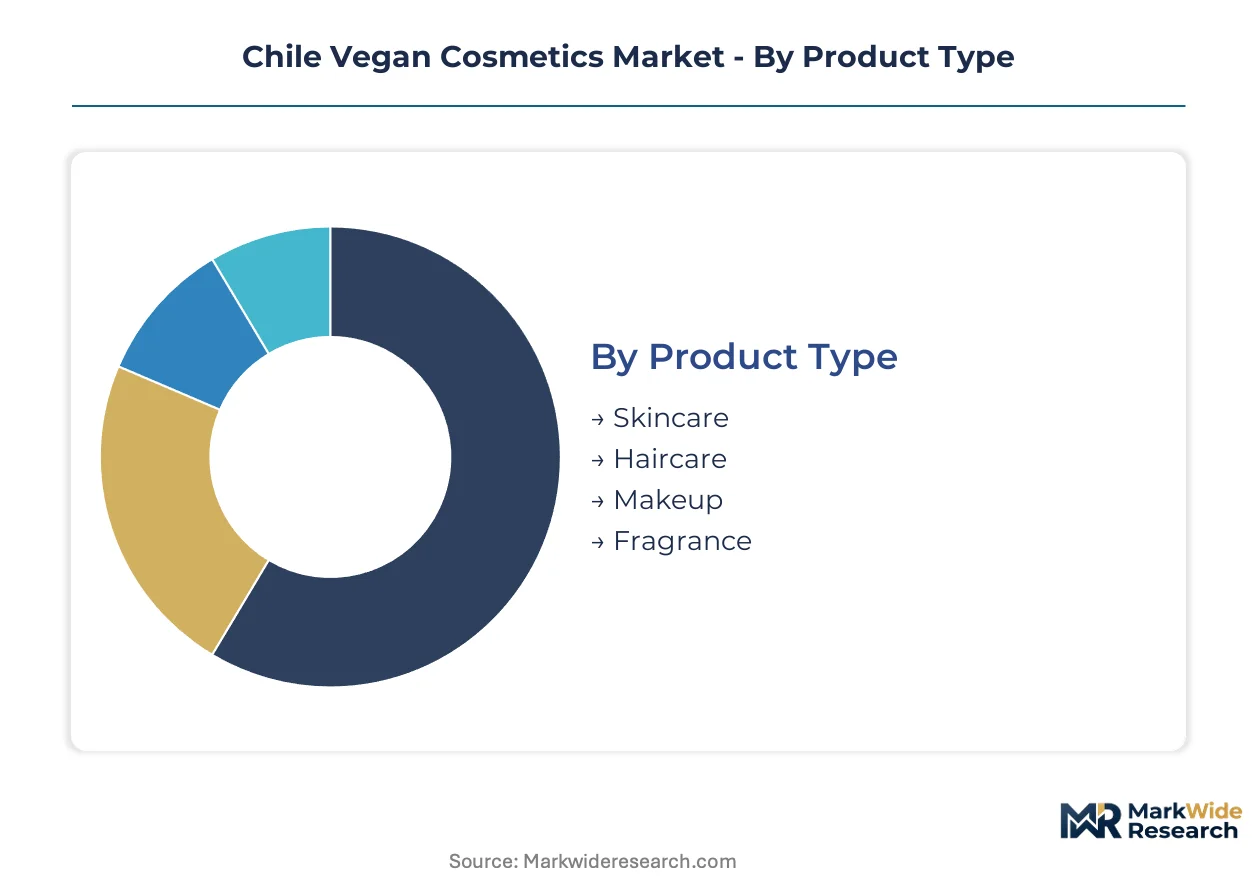
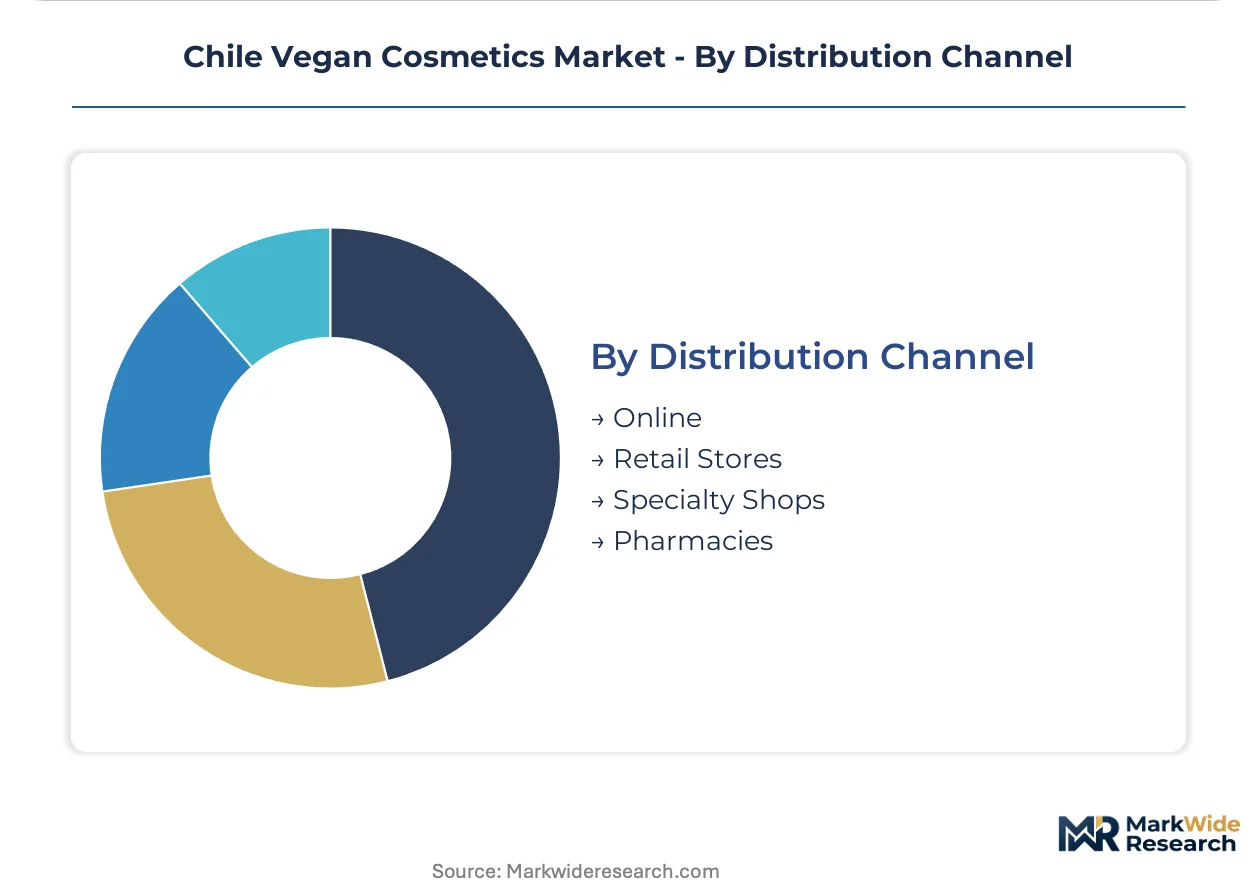
Segmentation in Chile's vegan cosmetics market reveals distinct procurement patterns across buyer demographics and channel preferences. Santiago's urban consumers prioritize ingredient transparency while secondary city adoption follows logistics-enabled online access.
Product Type:
Purchase frequency and margin structure differentiate buyer commitment across cosmetic categories.
- Skincare:High-concentration serums and moisturizers dominate repurchase cycles. Santiago consumers absorb premium pricing for plant-based retinol alternatives and quillaja-stabilized emulsions. Chile's Ministry of Health allergen disclosure mandates impose steeper compliance costs on complex botanical formulations in this segment.
- Makeup:Color cosmetics command trial-heavy purchasing with lower loyalty coefficients. Valparaíso specialty retailers capture margin through assisted shade-matching and vegan certification verification at point of sale.
- Haircare:Shampoo and conditioner formats face petrochemical surfactant price competition in mass-market distribution.
- Fragrance:Alcohol-free botanical extracts attract niche positioning among allergen-sensitive buyers in urban centers.
Volume sits with skincare; growth tilts toward makeup.
Ingredient Source:
Raw material provenance determines certification eligibility and cross-border trade friction.
- Plant-Based:Amazonian botanicals and native Chilean extracts anchor formulation pipelines. Natura Cosméticos leverages captive sourcing agreements to stabilize input costs while domestic competitors face quillaja saponaria harvest volatility.
- Organic:Certified cultivation standards restrict supplier pools and extend lead times for Chilean formulators seeking ISO 16128 alignment.
- Mineral:Mica and zinc oxide derivatives serve color cosmetic and sun protection applications with lower biotechnology processing requirements.
- Synthetic-Free:Preservative-free stability challenges concentrate R&D investment among Santiago-based reformulators.
Plant-based sourcing captures volume concentration; organic certification climbs fastest on export positioning.
End User:
Demographic targeting shapes product architecture and channel selection.
- Women:Core purchasing demographic across all categories with established trial-to-loyalty conversion in specialty retail.
- Men:Grooming category expansion drives simplified formulation demands and masculine-coded packaging requirements.
- Unisex:Fragrance and skincare formats gain traction among younger Santiago consumers prioritizing sustainability signaling over gendered positioning.
- Professionals:Salon and spa channels require bulk procurement terms and wholesale pricing structures distinct from direct-to-consumer models.
Women retain volume dominance; unisex positioning gains share fastest on generational turnover.
Distribution Channel:
Last-mile infrastructure maturity determines geographic reach and margin capture.
- Online:Subscription sampling programs and direct-to-consumer logistics unlock Concepción and La Serena penetration previously blocked by retail concentration in Santiago.
- Retail Stores:Supermarket and department store distribution requires mass-market pricing tolerance that compresses vegan certification cost recovery.
- Specialty Shops:Assisted-selling boutiques in Valparaíso and Santiago's Providencia district sustain margin premiums through education-intensive customer acquisition.
- Pharmacies:Dermocosmetic positioning leverages healthcare credibility for sensitive-skin vegan formulations.
Retail stores hold volume concentration; online channels expand most quickly on logistics investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration in Chile's vegan cosmetics market clusters around Santiago's affluent urban districts and Valparaíso's port-connected consumer corridors. Secondary cities now accelerate adoption as logistics infrastructure matures. Regulatory alignment with Mercosur standards is reshaping cross-border trade dynamics.
Santiago Metropolitan Region
High-income households in Providencia and Las Condes drive serum and moisturizer repurchase cycles at premium price points. Chile's Ministry of Health allergen disclosure mandates impose steepest compliance costs on complex botanical formulations sold through specialty retail here. Biotechnology fermentation labs in Quilicura industrial parks now cultivate lab-grown squalane alternatives to stabilize supply chains.
Valparaíso Region
Port city consumers exhibit trial-heavy purchasing patterns across color cosmetics and fragrance categories. The National Customs Service clearance protocols for imported vegan brands create friction that advantages established distributors with bonded warehouse infrastructure. Assisted-selling boutiques in Viña del Mar capture margin premiums through certified vegan curation and shade-matching services.
Biobío Region
Concepción's emerging middle class accesses vegan skincare through subscription sampling programs as last-mile logistics improve. Domestic formulators face quillaja saponaria harvest volatility without captive Amazonian sourcing agreements. Local pharmacy chains now stock dermocosmetic vegan lines targeting sensitive-skin demographics.
Coquimbo Region
La Serena's tourism economy supports niche demand for alcohol-free botanical fragrances among allergen-sensitive visitors. ISO 16128 naturalness certification adoption accelerates among regional distributors seeking export positioning toward Argentine markets. Coastal retail corridors experiment with unisex product positioning among younger consumers.
Chile Vegan Cosmetics Market Competitive Landscape
Brazilian and European producers anchor the premium formulation tier; Chilean domestic specialists hold mid-market positioning through native botanical extraction. Market structure tilts toward consolidated distribution with fragmented brand portfolios. Three archetypes dominate: multinational beauty conglomerates with captive sourcing networks, Amazonian botanical specialists with vertical supply control, and direct-to-consumer challengers leveraging subscription logistics. Competitive moves concentrate on regulatory preemption through early compliance investment and secondary city logistics partnerships.
Within the multinational tier, L'Oréal Chile and Natura Cosméticos occupy positions defined by infrastructure scale and captive sourcing respectively. The Body Shop exemplifies certification-driven differentiation through fixed cruelty-free standards. These three anchors represent divergent responses to Chile's tightening Ministry of Health labeling mandates: preemptive compliance investment, upstream botanical supply control, and cross-border certification portability.
| Leading Market Players |
|---|
| L'Oréal Chile |
| Natura Cosméticos |
| The Body Shop |
| Unilever Chile |
| Estée Lauder Companies |
| Procter & Gamble |
| Avon Chile |
| Beiersdorf |
| Coty |
| Others |
Pricing and Supply Chain Analysis
Reformulation chemist scarcity in Santiago's metropolitan universities widens labor-cost differentials between premium certified formulations and mass-market alternatives, compressing margins for mid-tier players unable to absorb ISO 16128 compliance premiums.
Pricing Analysis
Volume concentrates in mass-market haircare where petrochemical surfactant undercutting limits vegan certification cost recovery, while margin pools accumulate in high-concentration skincare serums sold through specialty retail. Price differentiation separates Leaping Bunny-certified premium tiers from PETA-verified standard positioning, with economy segments facing acute pressure from conventional cleansing agents. Pricing softness in mass-market distribution reflects supermarket buyers' resistance to absorbing transparency-mandate compliance costs. Professional salon channels exhibit lowest price sensitivity due to wholesale procurement structures and bulk volume commitments.
Supply Chain Analysis
Single-source vulnerability sits with wild-harvested quillaja saponaria extract from Chile's central valley, exposing domestic formulators to harvest volatility without captive Amazonian sourcing agreements. Geographic supply concentration centers on Brazil for Natura Cosméticos' botanical networks, Peru for aloe vera cultivation, and domestic Chilean extraction facilities for native soapbark processing. Raw material dependencies include plant-based emulsifiers, fermentation-derived squalane alternatives, and chromatography-verified preservative systems. Tariff exposure from Mercosur alignment discussions threatens cross-border botanical trade flows. Distribution runs through Santiago-based bonded warehouses serving specialty retail corridors in Valparaíso and emerging subscription logistics for secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chile's Ministry of Health labeling mandates operate as a cost-of-compliance moat, advantaging incumbents with pre-invested chromatography verification infrastructure while extending product launch timelines for import-dependent challengers.
For Market Incumbents: Anchor market position through preemptive certification investment in dual Leaping Bunny and PETA verification pipelines, defending against direct-to-consumer challengers exploiting subscription logistics penetration in Concepción and La Serena. Deepen captive sourcing agreements with Amazonian botanical suppliers to neutralize quillaja harvest volatility. Prioritize R&D allocation toward biotechnology-fermentation alternatives that reduce wild-harvest dependency while maintaining ISO 16128 naturalness thresholds. For New Entrants and Emerging Players: The premium-to-economy price-point gap in dermocosmetic vegan skincare offers white-space targeting through pharmacy channel partnerships in Santiago's Providencia district and unisex fragrance positioning in La Serena's coastal retail corridors. Subscription-based sampling programs represent the most penetrable go-to-market angle, concentrating brand discovery budgets into logistics partnerships rather than competing for in-store education staffing against established specialty boutiques. For Investors and Strategic Acquirers: Re-rating potential sits with domestic reformulators possessing captive Amazonian sourcing networks given Mercosur harmonization alignment signaling future Argentine and Uruguayan export pathway expansion. Long-term viability over a five-to-ten year horizon favors acquisition targets with pre-invested Ministry of Health compliance infrastructure and established secondary city logistics partnerships. Monitor biotechnology-fermentation convergence adoption rates as the critical inflection indicator for supply chain stability premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology Fermentation Investment | Lab-cultured squalane alternatives reduce quillaja dependency while satisfying ISO 16128 thresholds. |
| Dual Certification Preemption | Early Leaping Bunny and PETA compliance investment shortens launch cycles versus import-dependent competitors. |
| Secondary City Logistics Partnership | Subscription sampling penetration in Concepción unlocks previously blocked online channel growth. |
| Captive Amazonian Sourcing Agreement | Vertical supply control stabilizes input costs against domestic soapbark harvest volatility. |
| Mercosur Alignment Positioning | Preemptive ANVISA framework compliance opens Argentine and Uruguayan export corridors. |
Research Methodology
Multi-period observation of Ministry of Health regulatory filings, ISO 16128 certification adoption rates, and specialty retail channel expansion anchored the trend analysis, supplemented by interviews with cosmetic brand managers, pharmacy chain procurement leads, regulatory affairs specialists at import distributors, and biotechnology fermentation R&D directors. Secondary validation drew from customs clearance records, Chilean university formulation program enrollment data, and Mercosur technical standard harmonization documents. Bottom-up channel volume estimates triangulated against top-down market sizing from ingredient supplier shipment disclosures.
Segment-weighting across product type, ingredient source, and distribution channel dimensions structured the analytical framework, with CAGRs derived from trend extrapolation adjusted for regulatory implementation timelines and logistics infrastructure investment cycles. Modeled inputs included serum concentration premium persistence, subscription sampling program adoption curves, and cruelty-free certification timeline compression effects. The projection horizon incorporates biotechnology-fermentation cost reduction trajectories and Mercosur trade agreement negotiation status.
Inputs from regulatory filing databases and channel partner interviews were available through the study window; gaps in real-time customs clearance duration metrics and proprietary biotechnology yield data introduce uncertainty bands around import-dependent brand penetration forecasts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegan Cosmetics
Canada Vegan Cosmetics Market
Vegan Cosmetics
Vegan Beauty Products Market
Vegan Cosmetics
India Vegan Cosmetics Market
Vegan Cosmetics
Japan Vegan Cosmetics Market
Vegan Cosmetics
Global Probiotic Cosmetics Market
Vegan Cosmetics
Functional Cosmetics Market
Vegan Cosmetics
Europe Vegan Cosmetics Market
Vegan Cosmetics
France Vegan Cosmetics Market
Vegan Cosmetics
Argentina Vegan Cosmetics Market
Vegan Cosmetics
China Vegan Cosmetics Market
Vegan Cosmetics
Germany Vegan Cosmetics Market
Vegan Cosmetics
US Vegan Cosmetics Market
Vegan Cosmetics
Vegan Face Cream Market
Vegan Cosmetics
Vegan Cosmetics Market
Vegan Cosmetics
Brazil Vegan Cosmetics Market
Vegan Cosmetics
Mexico Vegan Cosmetics Market