
 India Vegan Cosmetics Market | 2026-2036
India Vegan Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
India Vegan Cosmetics Market Insights
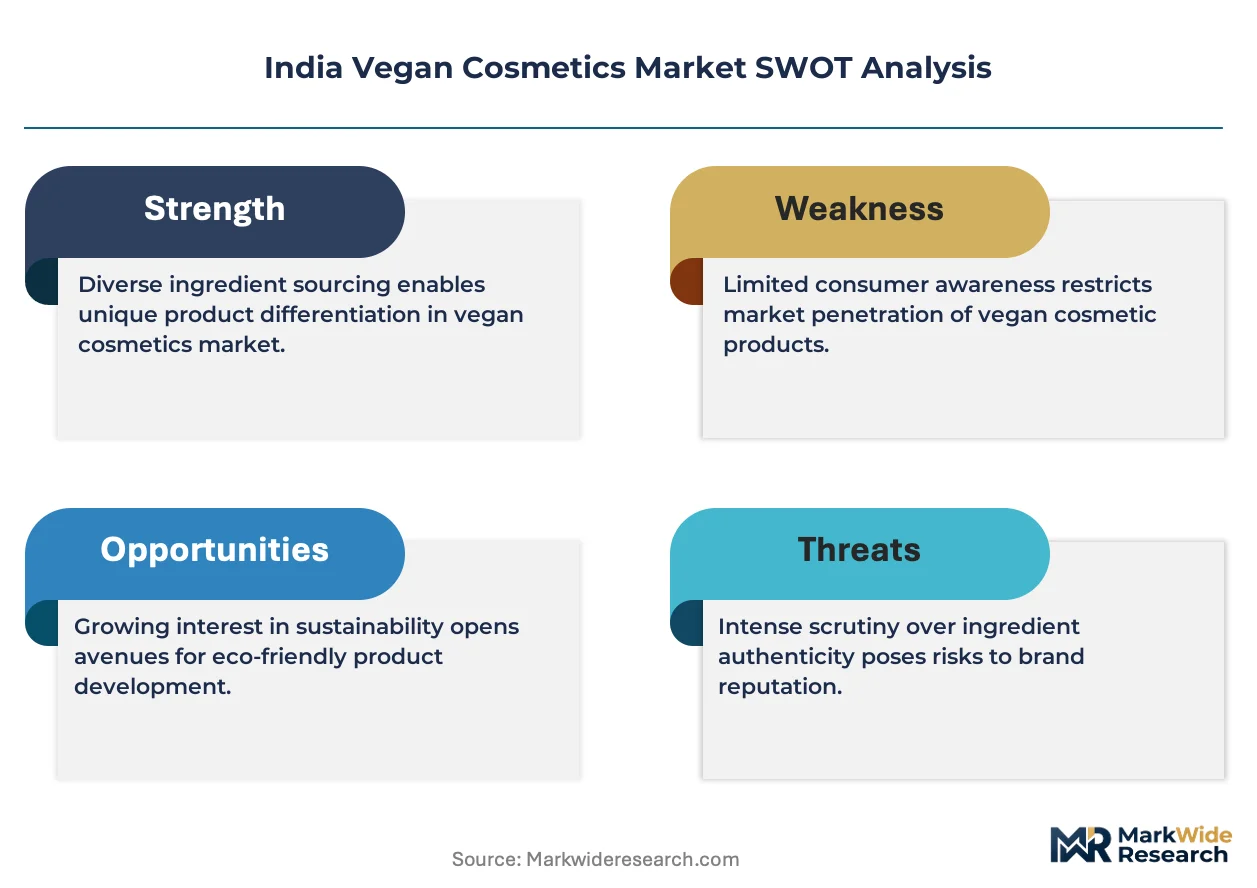
Prestige skincare and professional salon channels is repositioning toward vegan-certified stock, pulling procurement decisions upstream. Plum Goodness sustains direct-to-consumer dominance through its digital-native platform and toxin-free positioning. Daughter Earth anchors premium botanical R&D with cold-pressed extraction protocols and Himalayan sourcing claims. Juicy Chemistry specializes in oil-based anhydrous formulations with zero synthetic emulsifiers, occupying a defensible craft segment.
India vegan cosmetics comprise beauty and personal care products formulated without animal-derived ingredients, animal testing, or by-products such as beeswax, lanolin, or carmine, typically substituting plant oils, mineral pigments, and biotech-derived actives to deliver equivalent functional performance. These formulations serve consumers seeking ethical alignment, allergy reduction, and clean-label transparency in daily grooming rituals. Skincare leads absolute volume given higher per-capita usage frequency and repurchase rates across facial serums and moisturizers. Online channels represent the fastest-growing distribution vector, though specialty stores retain margin concentration through experiential trials and consultant-assisted conversion. The herbal formulation cluster shows particular momentum as Ayurvedic heritage intersects with vegan certification protocols.
BIS cosmetic safety standards, CDSCO ingredient disclosure mandates, and FSSAI overlapping scrutiny on cosmeceutical claims collectively elevate compliance costs while filtering out unverified entrants. The PLI scheme for domestic manufacturing indirectly supports local vegan formulators scaling captive production. Stakeholders must monitor regulatory convergence between chemical safety and ethical certification standards to anticipate which compliance investments will determine market access.
Market Dynamics
CDSCO ingredient disclosure mandates and BIS cosmetic safety standards are compressing formulation timelines while forcing domestic manufacturers to rebuild supply chains around certified vegan inputs.
Growth Catalysts
- Metro Millennial Demand:Tier-I urban consumers repurchase facial serums at higher frequencies than color cosmetics, concentrating volume in skincare SKUs with clean-label positioning.
- PLI Manufacturing Incentive:India's production-linked incentive scheme for domestic manufacturing subsidizes captive extraction facilities and cold-press equipment for plant-based actives.
- Ayurvedic-Vegan Convergence:Herbal formulation clusters leverage existing R&D infrastructure to achieve vegan certification without reformulation costs, accelerating SKU expansion.
Market Restraints
- Input Cost Volatility:Cold-pressed Himalayan botanicals and specialty plant oils face harvest-dependent pricing swings that compress gross margins on premium SKUs.
- Supply Concentration Risk:Anhydrous oil-based formulations rely on a narrow supplier base for zero-synthetic emulsifiers, creating vulnerability during monsoon logistics disruptions.
- Regulatory Friction:FSSAI overlapping scrutiny on cosmeceutical claims forces dual compliance spending alongside CDSCO mandates, elevating barriers for new entrants.
Strategic Opportunities
- Tier-II City Penetration:Mini-metro clusters show rising trial rates for vegan-certified skincare, with specialty retail expanding beyond Delhi-Mumbai-Bangalore corridors.
- Salon Channel Professionalization:Prestige skincare lines are repositioning toward vegan-certified stock, pulling procurement decisions upstream into institutional buyers.
- Biotech-Derived Actives:Fermentation-based alternatives to animal-derived collagen and squalane enable performance parity claims without agricultural input constraints.
Industry Challenges
- Certification Timeline Compression:Vegan certification protocols require 12-18 month validation cycles that delay product launches against faster conventional competitors.
- Formulation Skill Scarcity:Cosmetic chemists with dual expertise in Ayurvedic extraction and vegan compliance command premium salaries that strain mid-cap R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Vegan Cosmetics Market |
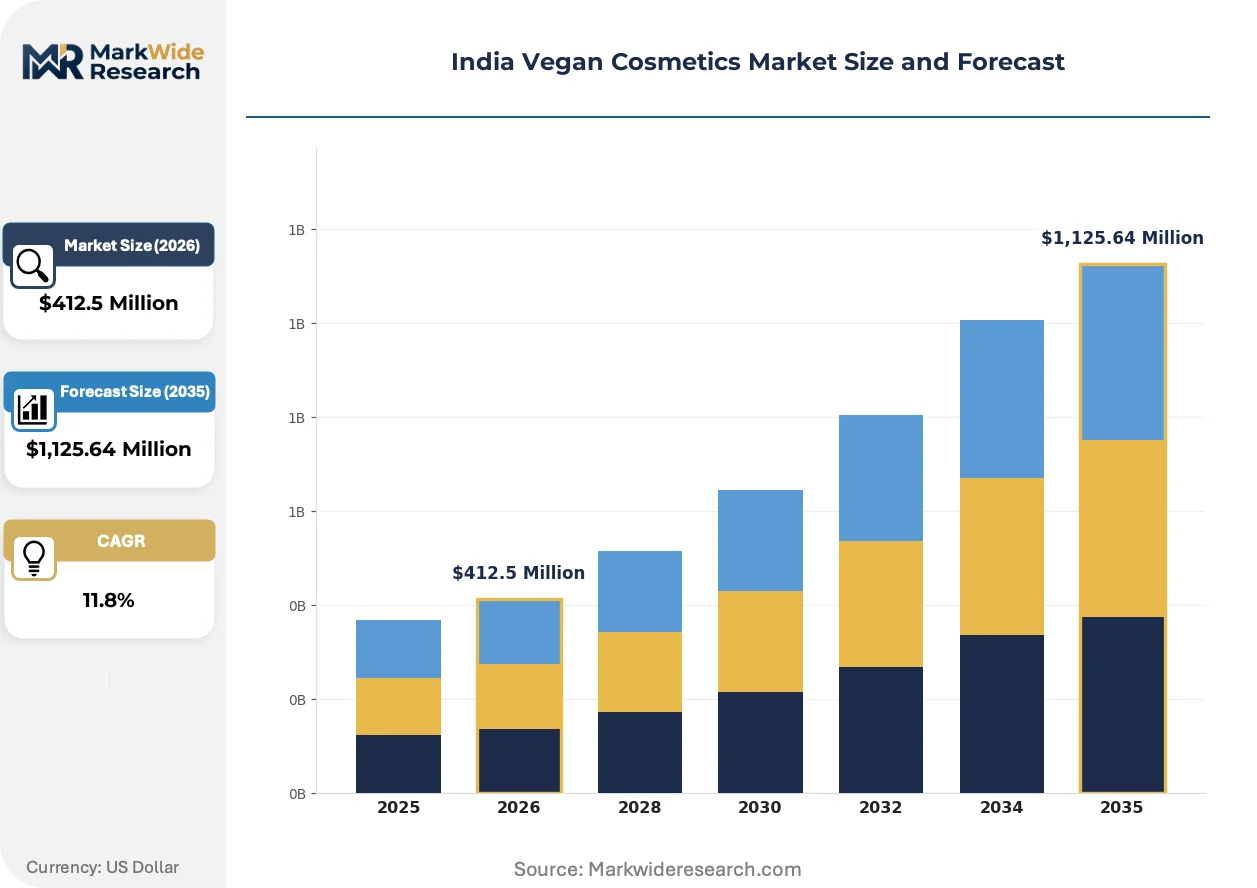
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,125.64 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Makeup, Skincare, Haircare, Fragrance Formulation: Natural, Organic, Herbal, Synthetic-Free End User: Women, Men, Teens, Children Distribution Channel: Online, Specialty Stores, Supermarkets, Pharmacies |
| Companies Covered | Svah Cosmetics Private Limited (Kiro Beauty), Eternite Elements Private Limited (Daughter Earth), Pureplay Skin Sciences (India) Private Limited (Plum Goodness), FAE Beauty Pvt Ltd, AFFOREST Green Beauty LLP, Delashi Care Private Limited (Disguise Cosmetics), Asa Beauty Private Limited, Typsy Beauty, Juicy Chemistry Private Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Vegan Cosmetics Market Trends and Innovations
Digital-native distribution models and biotech ingredient platforms are restructuring how vegan formulations reach Indian consumers, compressing traditional wholesale hierarchies.
Supercritical CO2 extraction technology is automating the recovery of heat-sensitive actives from Himalayan botanicals. Premium formulators in Uttarakhand and Himachal Pradesh are adopting these systems to replace solvent-based methods. This automation is compressing batch-to-batch variability while enabling traceability documentation required for export certification.
BIS cosmetic safety standards now mandate ingredient disclosure down to 0.01% concentration for preservatives and fragrances. Domestic manufacturers must retest legacy formulations and rebuild documentation systems. Skincare exporters targeting EU markets face parallel REACH compliance, forcing harmonized testing protocols that favor larger R&D budgets.
Direct-to-consumer subscription models are displacing traditional distributor networks for facial serum and moisturizer categories. Metro millennials prefer automated replenishment with ingredient transparency portals over retail trial. This shift concentrates customer data ownership with digital-native brands and compresses working capital cycles for inventory-light operators.
India Vegan Cosmetics Market Segmentation
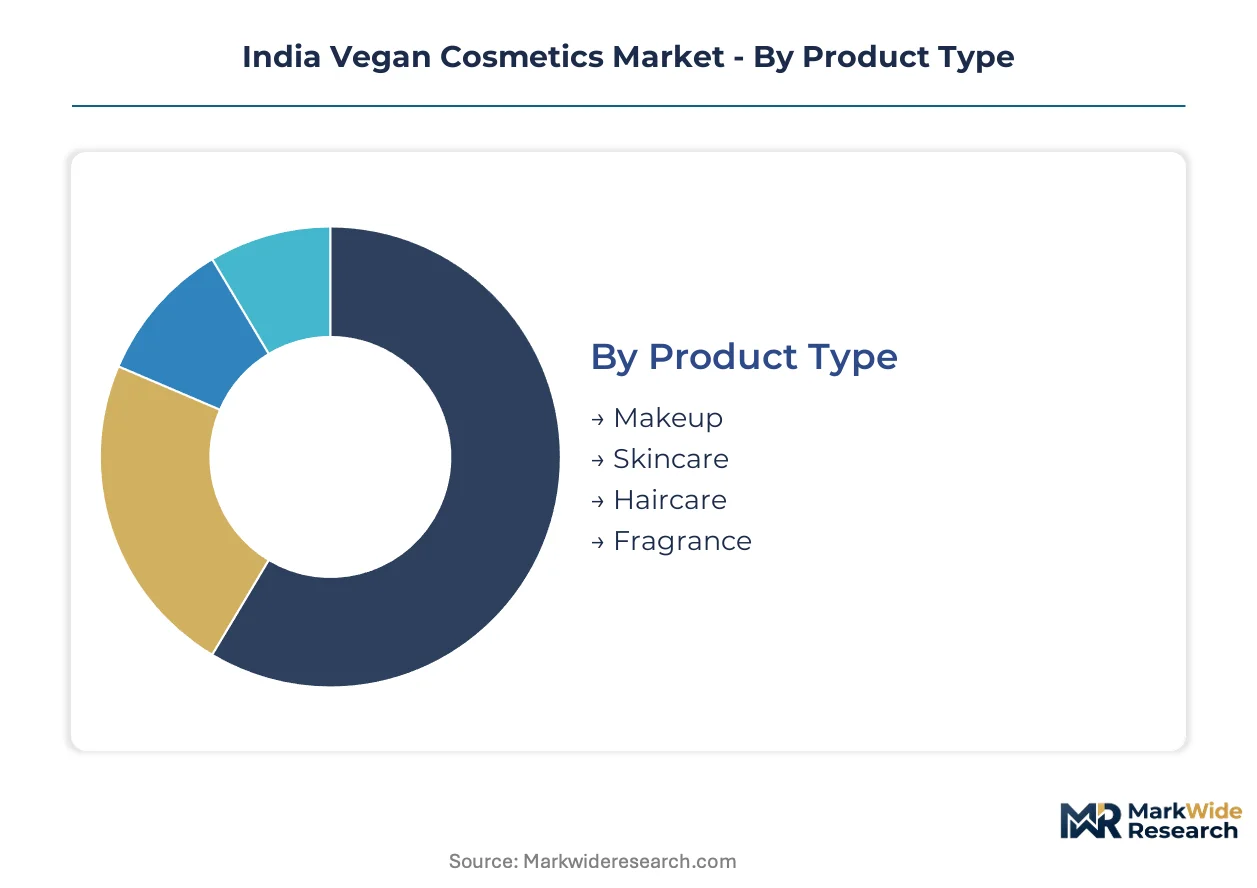
Segmentation in the India vegan cosmetics market reveals how ethical positioning, ingredient transparency, and channel accessibility interact to determine purchase outcomes. Buyers prioritize certification credibility over price in skincare, while fragrance and color cosmetics respond more acutely to trial accessibility and sensory validation.
Product Type:
Repurchase frequency and per-capita consumption intensity drive buyer allocation decisions across facial, body, and decorative categories.
- Skincare:Facial serums and moisturizers dominate absolute volume through daily application rituals. Metro millennials in Delhi and Mumbai concentrate demand for clean-label formulations with CDSCO-mandated ingredient disclosure down to 0.01% concentration.
- Makeup:Color cosmetics face higher trial barriers due to shade-matching requirements and sensory preference variation. Specialty stores in Bangalore and Hyderabad sustain conversion through consultant-assisted sampling that offsets online purchase hesitation.
- Haircare:Shampoo and conditioner segments leverage Ayurvedic heritage claims with vegan certification overlays. Himachal Pradesh extraction facilities supply cold-pressed actives to domestic formulators.
- Fragrance:Alcohol-free and botanical perfume formats occupy a niche premium tier. Niche buyers seek synthetic-free positioning with BIS-compliant safety documentation.
Skincare leads on scale; makeup trails on conversion efficiency despite equivalent consumer awareness levels.
Formulation:
Certification depth and supply chain traceability determine margin stratification across ingredient sourcing tiers.
- Herbal:Ayurvedic extraction protocols achieve vegan compliance without reformulation costs. Uttarakhand and Himachal Pradesh clusters supply Himalayan botanicals through supercritical CO2 systems that automate heat-sensitive active recovery.
- Natural:Plant-oil and mineral-pigment bases substitute animal-derived emollients and colorants. Input cost volatility on cold-pressed specialty oils compresses gross margins during monsoon harvest disruptions.
- Organic:Certified organic sourcing requires 12-18 month validation cycles that delay launches against conventional competitors. FSSAI overlapping scrutiny on cosmeceutical claims elevates dual compliance spending.
- Synthetic-Free:Zero-synthetic emulsifier formulations rely on narrow supplier bases for anhydrous oil systems. Juicy Chemistry occupies this craft segment with defensible technical positioning.
Herbal formulations capture volume leadership through infrastructure reuse; synthetic-free claims gain share fastest among premium digital-native entrants.
End User:
Demographic targeting intensity correlates with grooming ritual frequency and ethical purchasing sophistication.
- Women:Facial serum and moisturizer categories sustain the highest repurchase rates. Direct-to-consumer subscription models concentrate customer data ownership with brands like Plum Goodness through automated replenishment portals.
- Men:Beard care and minimalist skincare routines show rising trial rates in Tier-II mini-metro clusters. Specialty retail expansion beyond Delhi-Mumbai-Bangalore corridors captures emerging demand.
- Teens:Acne-targeted clean formulations respond to parental allergy-reduction preferences. Online channels dominate discovery and initial purchase.
- Children:Gentle formulation requirements intersect with safety-certification priorities. BIS cosmetic safety standards filter unverified entrants from this sensitive segment.
Women's segments anchor revenue scale; men's grooming exhibits the steepest expansion trajectory as professional salon channels professionalize vegan-certified stock.
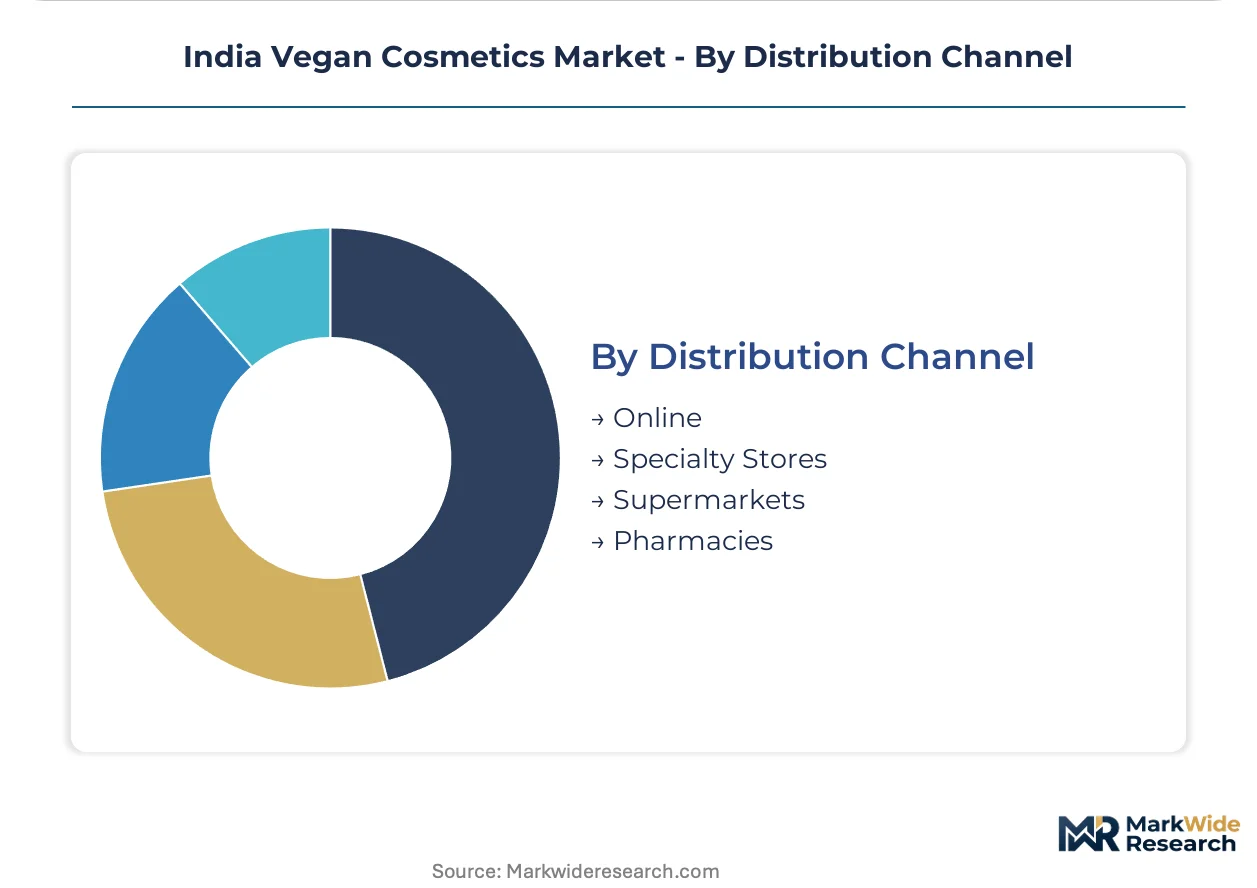
Distribution Channel:
Customer acquisition economics and working capital efficiency separate inventory-light digital operators from experiential retail.
- Online:Automated replenishment with ingredient transparency portals displaces traditional distributor networks. Metro millennials prefer data ownership and subscription pricing over retail trial friction.
- Specialty Stores:Consultant-assisted conversion and sensory trial sustain margin concentration. Daughter Earth anchors premium positioning through botanical R&D storytelling in physical environments.
- Supermarkets:Mass-market accessibility demands price compression that conflicts with certification cost recovery. PLI scheme subsidies for domestic manufacturing partially offset margin pressure.
- Pharmacies:Cosmeceutical claims face FSSAI scrutiny alongside CDSCO mandates. Dual compliance requirements elevate barriers for pharmacy channel entrants.
Online channels expand most quickly; specialty stores retain profitability leadership through experiential differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production gravity shifts toward sub-regions where PLI scheme subsidies offset CDSCO compliance costs, creating arbitrage opportunities for domestic formulators scaling captive extraction facilities.
Maharashtra
Mumbai and Pune anchor demand concentration for prestige skincare through professional salon channel procurement. CDSCO ingredient disclosure mandates force legacy formulators to rebuild documentation systems. The Mumbai specialty retail corridor sustains experiential trial conversion for vegan-certified color cosmetics.
Karnataka
Bangalore's digital-native consumer base drives direct-to-consumer subscription penetration for facial serum categories. BIS cosmetic safety standards filter unverified entrants from the children's gentle formulation segment. Whitefield and Koramangala clusters host cold-press equipment operators supplying plant-based actives upstream.
Delhi-NCR
Tier-I urban millennials in Gurugram and Noida concentrate repurchase frequency for clean-label moisturizers. FSSAI overlapping scrutiny on cosmeceutical claims elevates dual compliance spending for pharmacy channel entrants. The Okhla industrial area houses supercritical CO2 extraction facilities automating heat-sensitive botanical recovery.
Tamil Nadu
Chennai's specialty retail expansion captures rising trial rates for men's beard care formulations. PLI scheme subsidies for domestic manufacturing partially offset margin pressure on mass-market SKUs. The Ambattur industrial belt supports fermentation-based biotech active production for collagen alternatives.
Himachal Pradesh
Himalayan sourcing claims drive premium positioning for Uttarakhand-adjacent extraction clusters. Harvest-dependent pricing volatility on cold-pressed botanicals compresses gross margins during monsoon disruptions. Solan and Baddi pharmaceutical zones repurpose R&D infrastructure for vegan-certified herbal formulation compliance.
India Vegan Cosmetics Market Competitive Landscape
Strategic partnerships dominate the current landscape as digital-native brands secure captive supply agreements with Himalayan extraction clusters. The vendor base stratifies across three tiers: heritage Ayurvedic houses with certification overlays, venture-backed direct-to-consumer operators, and craft-scale anhydrous specialists. Two archetypes define competitive positioning: inventory-light subscription platforms concentrating customer data ownership, and experiential retail anchors sustaining margin through consultant-assisted conversion. Portfolio diversification and geographic expansion toward Tier-II mini-metros represent the dominant competitive moves.
Within the direct-to-consumer archetype, Plum Goodness anchors digital-native platform strategy through toxin-free positioning and automated replenishment portals. Daughter Earth exemplifies the premium botanical R&D tier with Himalayan sourcing claims and cold-pressed extraction protocols. Juicy Chemistry occupies the defensible craft segment specializing in oil-based anhydrous formulations with zero synthetic emulsifiers. These three entities collectively represent how certification depth, supply chain traceability, and channel accessibility interact to determine purchase outcomes across metro and emerging mini-metro clusters.
| Leading Market Players |
|---|
| Svah Cosmetics Private Limited (Kiro Beauty) |
| Eternite Elements Private Limited (Daughter Earth) |
| Pureplay Skin Sciences (India) Private Limited (Plum Goodness) |
| FAE Beauty Pvt Ltd |
| AFFOREST Green Beauty LLP |
| Delashi Care Private Limited (Disguise Cosmetics) |
| Asa Beauty Private Limited |
| Typsy Beauty |
| Juicy Chemistry Private Limited |
| Others |
Pricing and Supply Chain Analysis
Venture-backed direct-to-consumer operators concentrate pricing power through subscription lock-in, while family-owned Ayurvedic houses defend margin through captive Himalayan sourcing agreements that insulate against raw material volatility.
Pricing Analysis
Distributor margin compression in supermarket channels forces mass-market SKUs toward PLI-subsidized domestic manufacturing to recover certification cost outlays. Pricing stratifies across premium Himalayan-sourced tiers, mid-market herbal formulations, and economy private-label alternatives. Cost compression in premium cold-pressed actives is intensifying because monsoon harvest disruptions tighten supply. Pharmacy channel buyers exhibit highest price sensitivity due to FSSAI dual compliance burdens, while direct-to-consumer subscribers accept premium positioning for automated replenishment convenience.
Supply Chain Analysis
Single-source vulnerability sits with Himachal Pradesh and Uttarakhand extraction clusters for supercritical CO2-processed Himalayan botanicals. Domestic supply draws from Uttarakhand cold-press facilities, Solan pharmaceutical zone repurposed infrastructure, and Ambattur fermentation-based biotech active production. Supply chain risk centers on monsoon logistics disruptions that delay harvest-dependent ingredient flows. Distribution runs through direct-to-consumer subscription platforms displacing traditional wholesale hierarchies, with specialty stores retaining margin concentration through experiential trial conversion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India vegan cosmetics market functions as a stable compounder, with metro millennial repurchase frequency in facial serums generating predictable revenue basins that attract long-term capital allocation.
For Market Incumbents: Anchor market position through backward integration into captive supercritical CO2 extraction facilities in Uttarakhand and Himachal Pradesh, eliminating supplier concentration risk for heat-sensitive actives. Deepen certification moats by accelerating BIS cosmetic safety documentation ahead of CDSCO disclosure mandate expansion, filtering out unverified competitors. Control salon channel procurement decisions through professional-grade SKU development that pulls institutional buyers upstream. For New Entrants and Emerging Players: The gap between premium Daughter Earth positioning and mass-market supermarket accessibility offers white-space capture opportunity for mid-tier digital-native brands. Target Tier-II mini-metro clusters in Chennai and Hyderabad where specialty retail expansion outpaces brand saturation. Penetrate men's beard care segments through professional salon channel partnerships that leverage rising trial rates. Deploy biotech-derived active platforms to bypass agricultural input constraints that compress legacy formulator margins. For Investors and Strategic Acquirers: Valuations sit cheapest among craft-scale anhydrous specialists with defensible zero-synthetic emulsifier technical positioning and narrow but loyal customer bases. Long-term viability favors entities with dual Ayurvedic heritage and vegan certification infrastructure that accelerates SKU expansion without reformulation costs. Monitor CDSCO-BIS regulatory convergence timelines as inflection indicator for which compliance investments will determine market access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Extraction Facility Buildout | Uttarakhand supercritical CO2 systems automate heat-sensitive botanical recovery for export certification. |
| Direct-to-Consumer Subscription Launch | Plum Goodness demonstrates automated replenishment portals concentrate customer data ownership. |
| Professional Salon Channel Certification | Prestige skincare repositioning pulls procurement decisions upstream into institutional buyers. |
| Biotech-Derived Active Platform | Fermentation-based collagen alternatives enable performance parity without Himalayan harvest constraints. |
| Tier-II City Specialty Retail Expansion | Chennai and Hyderabad clusters show rising trial rates for vegan-certified men's grooming. |
Research Methodology
Coverage spans Maharashtra, Karnataka, Delhi-NCR, Tamil Nadu, and Himachal Pradesh, with primary inputs from each sub-region's extraction clusters and metro demand centers. The analysis combines primary interviews with cosmetic formulators, specialty retail buyers, CDSCO regulatory affairs consultants, and PLI scheme administrators with secondary validation from BIS cosmetic safety standards, CDSCO ingredient disclosure mandates, FSSAI cosmeceutical guidance documents, and customs records on plant-oil imports. Bottom-up SKU-level demand modeling triangulates against top-down category spend estimates.
Granularity-level framing applies product type, formulation certification tier, end-user demographic, and distribution channel dimensions at the state-cluster level across the projection horizon. CAGRs derive from repurchase frequency curves in facial serum and moisturizer categories, layered against channel shift assumptions for digital-native subscription penetration. Industry-specific forecast inputs include PLI scheme subsidy uptake rates and CDSCO compliance cost trajectories for domestic manufacturers.
Caveats apply where CDSCO-BIS regulatory convergence timelines or monsoon severity deviations could materially shift the outlook for input cost volatility and certification delay cycles. Forecasts reflect documented assumptions on metro millennial adoption curves and Tier-II specialty retail expansion rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegan Cosmetics
Organic Cosmetics Market
Vegan Cosmetics
France Vegan Cosmetics Market
Vegan Cosmetics
US Vegan Cosmetics Market
Vegan Cosmetics
Asia-Pacific Vegan Cosmetics Market
Vegan Cosmetics
Vegan Cosmetics Market
Vegan Cosmetics
Spain Vegan Cosmetics Market
Vegan Cosmetics
Functional Cosmetics Market
Vegan Cosmetics
Canada Vegan Cosmetics Market
Vegan Cosmetics
Brazil Vegan Cosmetics Market
Vegan Cosmetics
Vegan Beauty Products Market
Vegan Cosmetics
Europe Vegan Cosmetics Market
Vegan Cosmetics
South Korea Vegan Cosmetics Market
Vegan Cosmetics
China Vegan Cosmetics Market
Vegan Cosmetics
Global Probiotic Cosmetics Market
Vegan Cosmetics
Japan Vegan Cosmetics Market
Vegan Cosmetics
Italy Vegan Cosmetics Market