
 Brazil Vegan Cosmetics Market | 2026-2036
Brazil Vegan Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Vegan Cosmetics Market Insights
Biotechnology-derived alternatives to animal-derived ingredients is fragmenting traditional formulation pipelines across Brazil's cosmetics laboratories. Sallve leverages its direct-to-consumer platform to control pricing and customer data in ways legacy brands cannot replicate. Natura anchors its competitive position through backward integration into Amazonian botanical supply chains. Skala competes aggressively on unit economics in mass-market haircare through high-volume manufacturing scale.
Brazil vegan cosmetics encompass beauty and personal care products formulated without animal-derived substances, certified cruelty-free, and typically incorporating plant-based or synthetic biomimetic actives such as squalane from olive fermentation or hyaluronic acid produced via bacterial fermentation. These formulations serve consumers seeking ethical alignment between purchasing decisions and animal welfare standards. Skincare dominates current value contribution as Brazilian consumers prioritize facial routines with clean-label claims. Haircare represents the fastest-expanding category as curl-specific and bond-repair vegan lines gain traction among demographics historically underserved by multinational portfolios. The cream formulation segment occupies the largest share of manufacturing output, though serum formats command superior per-unit margins through concentrated active delivery.
ANVISA governs cosmetic ingredient safety and labeling requirements, while the Lei Federal nº 14.064 mandates cruelty-free certification for products marketed with vegan claims in Brazil. These frameworks compel brands to maintain dual documentation trails: one for formulation integrity, another for supply chain provenance. The EU Green Deal's extraterritorial influence on ingredient sourcing standards is reshaping how Brazilian exporters qualify for European market access. Stakeholders must monitor whether ANVISA will harmonize its definition of vegan cosmetics with emerging Mercosur technical standards, as divergence would fragment compliance costs for cross-border brands.
Market Dynamics
ANVISA's updated ingredient transparency requirements are compressing reformulation cycles across Brazil's domestic cosmetics laboratories, forcing brands to rebuild documentation trails for both formulation integrity and supply chain provenance.
Growth Catalysts
- Lei Federal nº 14.064:Brazil's cruelty-free certification mandate for vegan claims creates standardized compliance pathways that reduce consumer skepticism and accelerate retailer acceptance of certified products.
- Bacterial fermentation:Synthetic biomimetic production of squalane and hyaluronic acid is eliminating supply constraints from olive and animal-derived sources while improving batch consistency for formulators.
- Southeast regional concentration:São Paulo and Rio de Janeiro's urban professional cohorts generate disproportionate demand pull through specialty retail channels that reward premium positioning.
Market Restraints
- Amazonian botanical supply concentration:Dependence on wild-harvested and cultivated Amazonian inputs exposes formulators to climate volatility and indigenous land-use disputes that disrupt raw material flows.
- Dual documentation burden:ANVISA's parallel requirements for formulation safety and supply chain provenance inflate compliance costs disproportionately for mid-scale domestic brands lacking dedicated regulatory teams.
- Conventional synthetic substitutes:Petroleum-derived emollients and silicones retain cost advantages in mass-market haircare, constraining vegan penetration in price-sensitive consumer segments.
Strategic Opportunities
- Northeast urban corridors:Recife and Salvador's emerging professional class remains underserved by specialty vegan retail, presenting first-mover advantages for direct-to-consumer platform expansion.
- Curl-specific haircare:Bond-repair and texture-specific formulations for Afro-Brazilian hair types represent whitespace historically neglected by multinational vegan portfolios.
- Mercosur technical harmonization:Potential alignment between ANVISA and regional standards would streamline cross-border certification for Brazilian exporters targeting Argentine and Uruguayan markets.
Industry Challenges
- Green chemistry talent scarcity:Formulation chemists with expertise in plant-derived surfactants and biomimetic actives command premium compensation that strains R&D budgets outside Natura-scale enterprises.
- EU Green Deal extraterritorial compliance:Brazilian exporters must maintain parallel ingredient qualification systems to satisfy divergent European sourcing standards without guaranteed ANVISA reciprocity.
- Legacy ERP integration:Batch-level traceability requirements for vegan certification conflict with decades-old manufacturing software architectures still prevalent among established domestic producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Vegan Cosmetics Market |
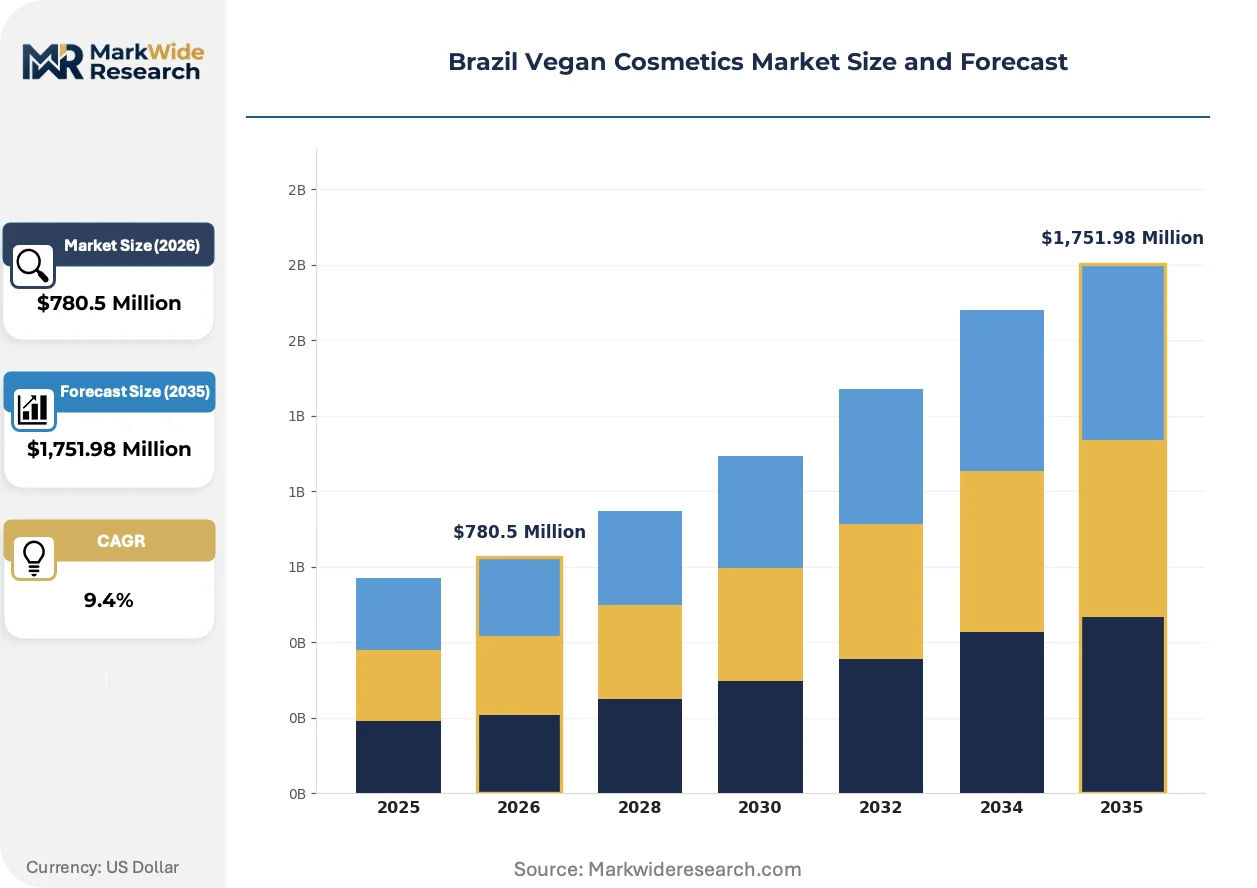
| Market Size in 2026 | $780.5 Million |
| Market Size in 2035 | $1,751.98 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Makeup, Fragrance Formulation: Cream, Serum, Gel, Balm Target Segment: Eco-Conscious Consumers, Millennials, Cruelty-Free Supporters, Health Enthusiasts Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies |
| Companies Covered | Sallve, Mink Cosméticos, Skala, Adversa, The Lilly Beauty, Lola From Rio, Essencial Amazônia, GrowinCo, Natura, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Vegan Cosmetics Market Trends and Innovations
Biotechnology is displacing conventional extraction methods while regulatory fragmentation and channel specialization reshape competitive positioning across Brazil's vegan cosmetics landscape.
Fermentation-derived squalane from engineered yeast strains is digitizing supply chain transparency through blockchain-tracked batch records. Premium skincare brands in São Paulo adopt these inputs fastest, compressing documentation timelines from months to weeks while satisfying ANVISA's provenance requirements without manual audit trails.
Lei Federal nº 14.064's cruelty-free mandate is forcing laboratory retooling across domestic manufacturers. Brands must maintain dual certification systems—one for ANVISA safety compliance, another for vegan claim integrity—disproportionately burdening mid-tier producers lacking dedicated regulatory infrastructure.
Direct-to-consumer platforms are capturing customer data that specialty retail channels cannot replicate. Young urban professionals in Rio de Janeiro increasingly purchase through Instagram-integrated storefronts, bypassing traditional beauty advisors while demanding personalized curl-care recommendations that algorithmic matching enables.
Brazil Vegan Cosmetics Market Segmentation
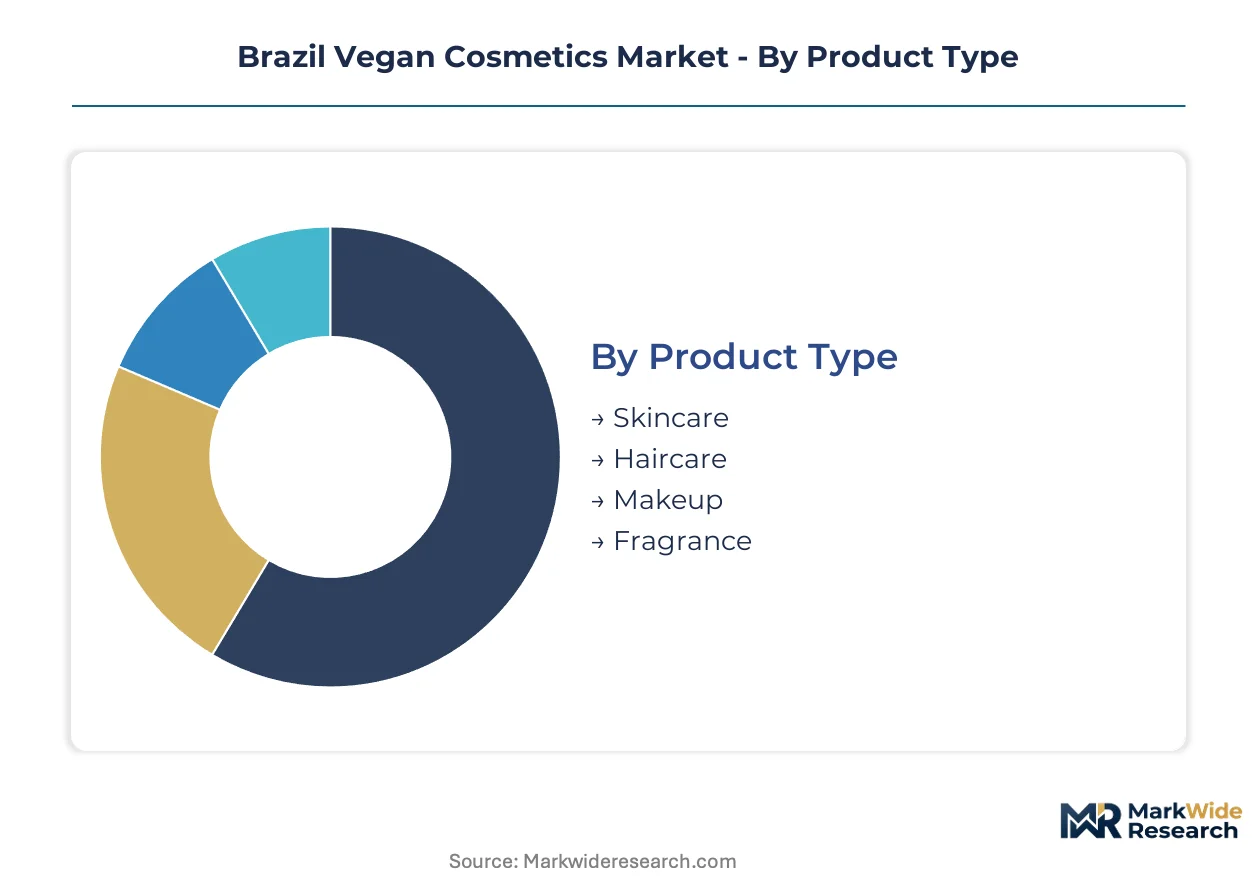
Vegan cosmetics segmentation in Brazil reflects divergent consumer priorities across formulation science, ethical positioning, and channel access. Understanding these partitions reveals where ANVISA compliance costs concentrate and where direct-to-consumer platforms can bypass traditional retail gatekeepers.
Product Type:
After-sales service intensity varies sharply across product categories, with skincare demanding educational support for regimen adherence while haircare requires texture-specific troubleshooting that strains conventional retail staffing models.
- Skincare:Facial formulations incorporate bacterial fermentation-derived hyaluronic acid and olive-based squalane as biomimetic hydrators. São Paulo's urban professional cohort drives premium demand through specialty channels seeking clean-label transparency under ANVISA's ingredient disclosure mandates.
- Haircare:Curl-specific and bond-repair vegan lines address historically underserved Afro-Brazilian demographics. Recife and Salvador's emerging professional class pulls these products through Instagram-integrated storefronts that algorithmically match texture concerns to formulation chemistry.
- Makeup:Pigment sourcing from mineral and synthetic alternatives avoids carmine and guanine, satisfying Lei Federal nº 14.064 certification requirements for cruelty-free claims.
- Fragrance:Plant-derived and biotechnology-produced aroma molecules replace animalic bases such as ambergris and civet, though batch consistency challenges persist for domestic laboratories.
Skincare holds the largest share; momentum sits with haircare.
Formulation:
Cost tier stratification separates concentrated actives from base moisturizers, with per-unit manufacturing economics determining which formats sustain specialty retail margins versus mass-market penetration.
- Cream:Emulsion-based vehicles dominate manufacturing output through established cold-process infrastructure. Petroleum-derived emollient substitutes retain cost advantages that constrain vegan penetration in price-sensitive segments.
- Serum:Concentrated active delivery commands superior margins via biomimetic ingredients from engineered yeast fermentation. Southeast region specialty retailers capture this value through personalized consultation services.
- Gel:Water-based matrices suit humid coastal climates in Rio de Janeiro, though plant-derived thickeners require reformulation expertise that green chemistry talent scarcity makes expensive.
- Balm:Occlusive formulations for barrier repair leverage Amazonian botanical waxes, exposing supply chains to climate volatility and indigenous land-use disputes.
Cream occupies the volume base; serum captures the steepest expansion trajectory.
Target Segment:
Customer type differentiation maps directly to channel preference, with digitally native demographics bypassing traditional beauty advisors while ethically motivated purchasers reward certification transparency.
- Eco-Conscious Consumers:Purchasing decisions integrate carbon footprint and packaging sustainability alongside vegan claims, concentrating demand in brands with blockchain-tracked supply chain documentation.
- Millennials:São Paulo and Rio de Janeiro's young urban professionals generate disproportionate demand pull through social commerce platforms that legacy brands struggle to replicate.
- Cruelty-Free Supporters:Lei Federal nº 14.064's standardized certification reduces skepticism, accelerating retailer acceptance of dual-compliant products across pharmacy and specialty channels.
- Health Enthusiasts:Clean-label seekers prioritize ANVISA's expanded ingredient disclosure as a screening mechanism, rewarding brands with transparent formulation architecture.
Eco-Conscious Consumers anchor current value; Millennials are gaining share fastest.
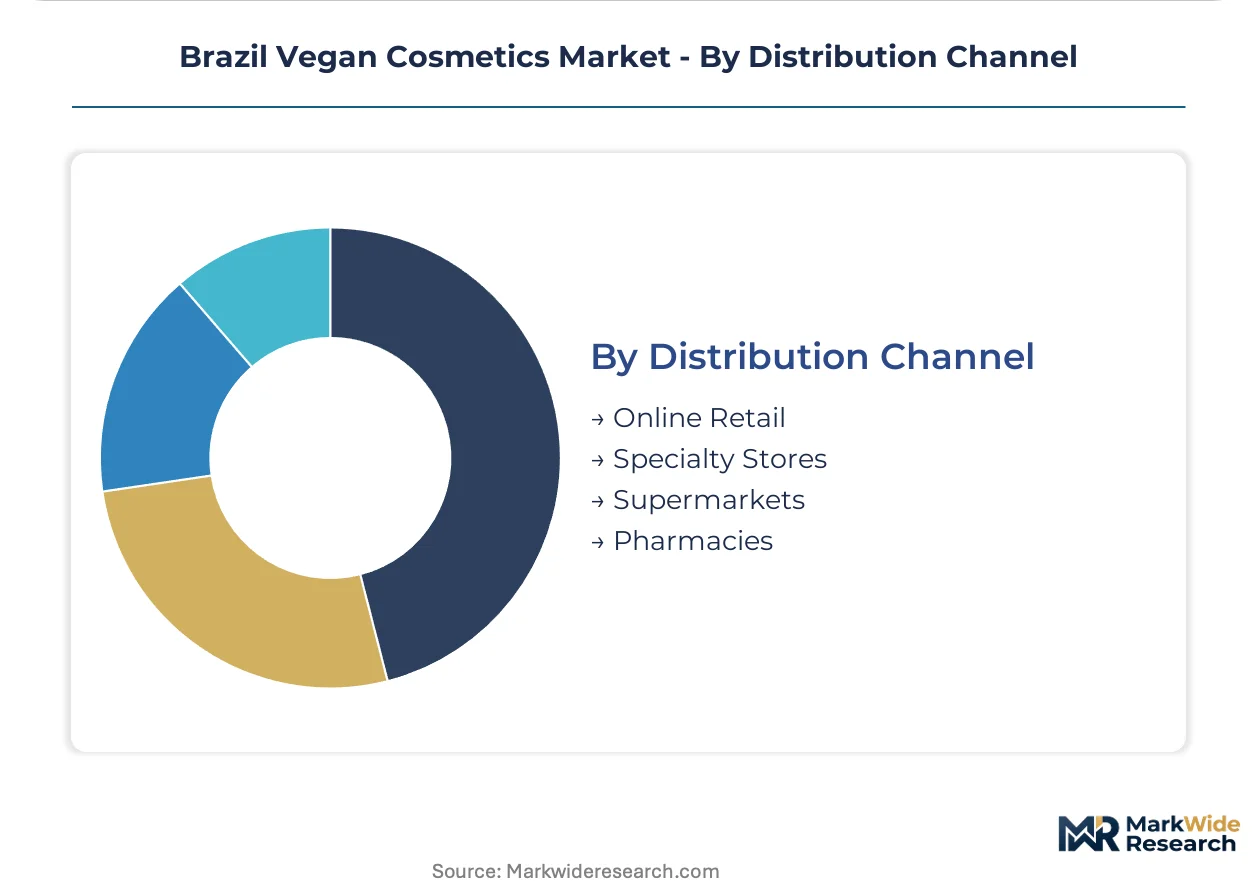
Distribution Channel:
Geography determines channel viability, with Northeast urban corridors underserved by specialty vegan retail while Southeast concentration supports premium positioning through experienced beauty advisors.
- Online Retail:Direct-to-consumer platforms capture customer data and enable algorithmic personalization for curl-care recommendations. Inventory-light models help mid-scale domestic brands avoid legacy ERP integration burdens for batch-level traceability.
- Specialty Stores:Concentrated in São Paulo and Rio de Janeiro, these channels reward premium positioning through trained staff capable of explaining fermentation-derived ingredient advantages.
- Supermarkets:Mass-market penetration faces headwinds from petroleum-derived synthetic cost advantages in conventional haircare, limiting vegan shelf space allocation.
- Pharmacies:ANVISA's safety compliance reputation lends credibility to certified products, though dual documentation requirements for vegan claim integrity strain smaller brand regulatory capacity.
Specialty Stores command the margin premium; Online Retail climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian vegan cosmetics manufacturers export primarily to Mercosur neighbors Argentina and Uruguay, where harmonized technical standards reduce certification friction. Domestic demand concentrates in Southeast urban corridors while Northeast metros emerge as expansion targets.
São Paulo
São Paulo's urban professional cohort drives premium skincare demand through specialty retail channels staffed by trained beauty advisors. ANVISA's ingredient disclosure mandates accelerate retailer acceptance of certified vegan products in pharmacy and department store networks. The city's Pinheiros and Jardins districts host concentration of direct-to-consumer brand headquarters leveraging social commerce platforms.
Rio de Janeiro
Rio de Janeiro's humid coastal climate pulls demand for gel-based formulations requiring plant-derived thickener expertise. Lei Federal nº 14.064's cruelty-free certification reduces consumer skepticism among digitally native millennials purchasing through Instagram-integrated storefronts. Copacabana and Ipanema neighborhoods concentrate specialty vegan retail serving tourists and affluent residents.
Minas Gerais
Minas Gerais anchors biotechnology fermentation capacity supplying biomimetic squalane and hyaluronic acid to Southeast formulators. The state's pharmaceutical manufacturing heritage creates talent pools for green chemistry specialization. Belo Horizonte's industrial parks house contract manufacturers serving mid-scale domestic brands lacking captive R&D infrastructure.
Bahia
Bahia's Salvador metro represents underserved whitespace for curl-specific vegan haircare targeting Afro-Brazilian demographics. Emerging professional class purchasing power supports direct-to-consumer platform expansion bypassing traditional retail gatekeepers. The state's African heritage influences texture-specific formulation demand patterns distinct from Southeast preferences.
Rio Grande do Sul
Rio Grande do Sul's Porto Alegre industrial base supports mass-market manufacturing scale competing on unit economics against petroleum-derived conventional substitutes. The state's European immigrant heritage shapes consumer expectations for premium positioning that vegan claims struggle to satisfy at mass price points. Local distributors test pharmacy channel penetration for dual-certified products.
Brazil Vegan Cosmetics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions defined by scale and certification depth. The structure fragments between mass-market manufacturers with legacy retail relationships and digital-native brands capturing customer data through direct platforms. Three archetypes dominate: Amazonian botanical-integrated incumbents, fermentation-technology specialists, and algorithmic personalization platforms. Competitive moves concentrate on backward integration into supply chains and social commerce infrastructure buildout.
Within the botanical-integrated tier, Natura anchors through upstream control over Amazonian raw material networks. Sallve occupies a position exemplifying direct-to-consumer platform architecture with pricing autonomy and data capture capabilities. Skala represents scale-driven manufacturing archetype competing on unit economics in high-volume haircare segments.
| Leading Market Players |
|---|
| Sallve |
| Mink Cosméticos |
| Skala |
| Adversa |
| The Lilly Beauty |
| Lola From Rio |
| Essencial Amazônia |
| GrowinCo |
| Natura |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in bacterial fermentation facilities across Minas Gerais is compressing supplier margins while simultaneously elevating pricing power for biotechnology-derived squalane and hyaluronic acid producers serving Southeast formulators. ANVISA's dual documentation requirements for formulation safety and supply chain provenance inflate compliance costs that concentrate in mid-tier domestic brands, forcing pricing stratification between certification-capable and legacy manufacturers.
Pricing Analysis
The fermentation-technology pricing gap separates engineered-yeast-derived biomimetics commanding premium positioning from conventional olive-extraction alternatives and petroleum-derived synthetic substitutes competing on unit economics. Three-tier pricing structure across premium serum formats, standard cream vehicles, and economy haircare lines reflects certification depth and active concentration. Cost compression in mass-market segments intensifies as Skala-scale manufacturers exploit high-volume scale against petroleum-derived emollient substitutes. Price-sensitive consumers in Rio Grande do Sul's mass-market channels resist vegan premiums, while São Paulo's specialty retail shoppers absorb fermentation-derived ingredient markups through trained beauty advisor justification.
Supply Chain Analysis
EU Green Deal extraterritorial controls on ingredient sourcing standards restrict Brazilian exporter access unless parallel qualification systems satisfy divergent European requirements without ANVISA reciprocity guarantees. Geographic supply concentration centers on Minas Gerais biotechnology fermentation capacity, Amazonian wild-harvested botanical networks, and imported synthetic biomimetic precursors from Chinese and Indian specialty chemical producers. Raw material dependencies include engineered yeast strains, Amazonian waxes and oils, and bacterial fermentation feedstocks. Single-source vulnerability pervades wild-harvested Amazonian inputs exposed to climate volatility and indigenous land-use disputes. Distribution runs through specialty retail channels in Southeast urban corridors, direct-to-consumer platforms capturing customer data, and pharmacy networks leveraging ANVISA credibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among direct-to-consumer platforms and specialty retail chains capable of algorithmic personalization and certification transparency, fragmenting traditional wholesale relationships that legacy brands depended upon for shelf access.
For Market Incumbents: Insulate formulation pipelines by deepening backward integration into Amazonian botanical supply chains and captive fermentation capacity in Minas Gerais industrial parks. Invest in blockchain-tracked batch documentation systems that compress ANVISA compliance timelines from months to weeks, defending against digital-native entrants with superior data capture. Prioritize green chemistry talent acquisition to offset scarcity-driven R&D cost inflation.
For New Entrants and Emerging Players: Pursue curl-specific vegan haircare whitespace in Salvador and Recife's underserved Northeast urban corridors, where Afro-Brazilian texture-specific demand outpaces multinational portfolio coverage. Deploy Instagram-integrated storefronts with algorithmic matching capabilities that bypass legacy retail gatekeepers and capture customer data incumbent brands cannot replicate. Anchor go-to-market positioning through Lei Federal nº 14.064 dual certification credibility.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer platforms with subscription skincare regimens and algorithmic personalization infrastructure. Long-term viability over the next decade hinges on supply chain traceability technology and biotechnology fermentation capabilities that decouple from Amazonian climate exposure. Target acquisition archetypes include mid-scale domestic brands with compliant documentation systems but lacking captive R&D. The signal to watch is ANVISA-Mercosur technical harmonization progress, which would streamline cross-border certification and reshape export-competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amazonian Botanical Supply | Natura's upstream control over wild-harvested networks secures raw material priority access against climate disruption. |
| Direct-to-Consumer Platform Launch | Sallve's pricing autonomy and customer data capture bypass specialty retail margin extraction. |
| Fermentation Technology Scale-Up | Minas Gerais biotechnology capacity expansion eliminates supply constraints for biomimetic squalane and hyaluronic acid. |
| Curl-Specific Product Line Extension | Bond-repair and texture-specific formulations address historically underserved Afro-Brazilian demographics in Northeast metros. |
| Blockchain Traceability Implementation | Batch-level documentation digitization compresses ANVISA compliance timelines while satisfying EU Green Deal sourcing standards. |
Research Methodology
Cross-validation between primary interviews with formulation chemists, regulatory affairs specialists at ANVISA, specialty retail buyers, and direct-to-consumer brand operators and secondary validation through ANVISA ingredient disclosure databases, Lei Federal nº 14.064 certification registries, and customs trade records anchors the qualitative findings. Bottom-up triangulation from product-level volume estimates and top-down reconciliation against aggregate market sizing ensures methodological consistency. Stakeholder perspectives from Natura-scale integrated incumbents, Sallve-type digital-native platforms, and Skala-scale mass-market manufacturers provide competitive archetype coverage.
Calibration against historical growth trajectories in adjacent clean-label personal care categories and fermentation-technology adoption curves in pharmaceutical applications informs the projection framework. Segmentation dimensions modeled include product type, formulation vehicle, target consumer archetype, and distribution channel across the analysis window. CAGRs derive from regression-weighted consensus across demand-side pull factors and supply-side capacity constraints. Industry-specific inputs incorporate ANVISA regulatory timeline assumptions and biotechnology fermentation yield improvement curves.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates, consumer discretionary spending indices, and EU Green Deal enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory harmonization progress and fermentation technology cost reduction. Material shifts in ANVISA-Mercosur technical standard alignment or Amazonian supply disruption severity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegan Cosmetics
Organic Cosmetics Market
Vegan Cosmetics
Vegan Face Cream Market
Vegan Cosmetics
Functional Cosmetics Market
Vegan Cosmetics
China Vegan Cosmetics Market
Vegan Cosmetics
India Vegan Cosmetics Market
Vegan Cosmetics
Vegan Beauty Products Market
Vegan Cosmetics
Asia-Pacific Vegan Cosmetics Market
Vegan Cosmetics
Mexico Vegan Cosmetics Market
Vegan Cosmetics
Vegan Cosmetics Market
Vegan Cosmetics
South Korea Vegan Cosmetics Market
Vegan Cosmetics
US Vegan Cosmetics Market
Vegan Cosmetics
Canada Vegan Cosmetics Market
Vegan Cosmetics
Japan Vegan Cosmetics Market
Vegan Cosmetics
Chile Vegan Cosmetics Market
Vegan Cosmetics
Global Probiotic Cosmetics Market
Vegan Cosmetics
Germany Vegan Cosmetics Market