
 Canada Vegan Cosmetics Market | 2026-2036
Canada Vegan Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Vegan Cosmetics Market Insights
Millennial buyers are bifurcating from traditional prestige purchasers as the dominant growth archetype in Canadian vegan cosmetics. L'Oréal Group leverages its dermatological R&D infrastructure to anchor plant-based skincare lines across Quebec and Ontario retail networks. Pacifica Beauty competes through its entirely vegan product architecture, while e.l.f. Beauty extends aggressive e-commerce pricing that captures price-sensitive ethical consumers nationwide.
Canada vegan cosmetics encompass beauty and personal care formulations that exclude animal-derived ingredients, animal testing, and commonly incorporate plant-based emulsifiers such as cetyl alcohol from coconut or squalane from olive sources, serving consumers who prioritize ethical sourcing and ingredient transparency alongside dermatological efficacy. Skincare dominates current revenue pools due to higher per-unit pricing and repeat purchase frequency, while haircare registers the fastest trajectory as sulfate-free and botanical formulations displace conventional salon products. E-commerce channels now capture the dominant share of new customer acquisition, though specialty stores retain margin superiority through experiential retail and personalized consultation services.
Health Canada and PMRA enforce cosmetic ingredient labeling under the Food and Drugs Act, while the Competition Act polices misleading cruelty-free claims, collectively elevating compliance costs for new entrants but rewarding established certifiers. The Canadian Environmental Protection Act further restricts certain synthetic preservatives, pushing reformulation toward mineral-based stabilizers. Stakeholders must monitor evolving federal definitions of natural versus synthetic-free claims to anticipate which certification frameworks will govern shelf placement decisions.
Market Dynamics
Health Canada's PMRA enforcement of synthetic-free labeling under the Food and Drugs Act is compressing formulation timelines and forcing brands toward mineral-based stabilizers, restructuring competitive advantage around certification speed rather than marketing spend.
Growth Catalysts
- Clean-label mandates:Health Canada and the Canadian Food Inspection Agency maintain ingredient disclosure standards that push brands toward plant-based emulsifiers.
- Urban retail corridor density:Toronto and Vancouver concentrate health-conscious millennial buyers with elevated willingness-to-pay for ethical sourcing verification.
- Sulfate-free formulation science:Botanical haircare chemistry advances enable salon-grade performance without animal-derived proteins.
Market Restraints
- Input cost volatility:Olive-derived squalane and coconut-based cetyl alcohol face agricultural supply fluctuations that compress margins.
- Regulatory friction:The Competition Act's policing of cruelty-free claims creates legal exposure for brands using third-party certification.
- Technical limitation:Mineral-based preservatives deliver shorter shelf stability than synthetic alternatives, constraining distribution reach.
Strategic Opportunities
- Underpenetrated geography:Quebec's francophone consumer base shows lagging vegan cosmetic penetration relative to Ontario and British Columbia.
- Regulatory tailwind:The Canadian Environmental Protection Act's restrictions on synthetic preservatives accelerate reformulation demand.
- Channel innovation:Subscription-based replenishment models bypass specialty retail margin extraction while locking repeat purchase frequency.
Industry Challenges
- Certification timeline compression:Health Canada approval cycles for novel plant-based actives extend product launch windows.
- Supply chain reconfiguration friction:Transitioning from petrochemical to botanical emulsifier suppliers requires reformulation validation.
- Talent scarcity:Cosmetic chemists with dual expertise in dermatological efficacy and plant-based formulation command premium compensation.
Report Scope
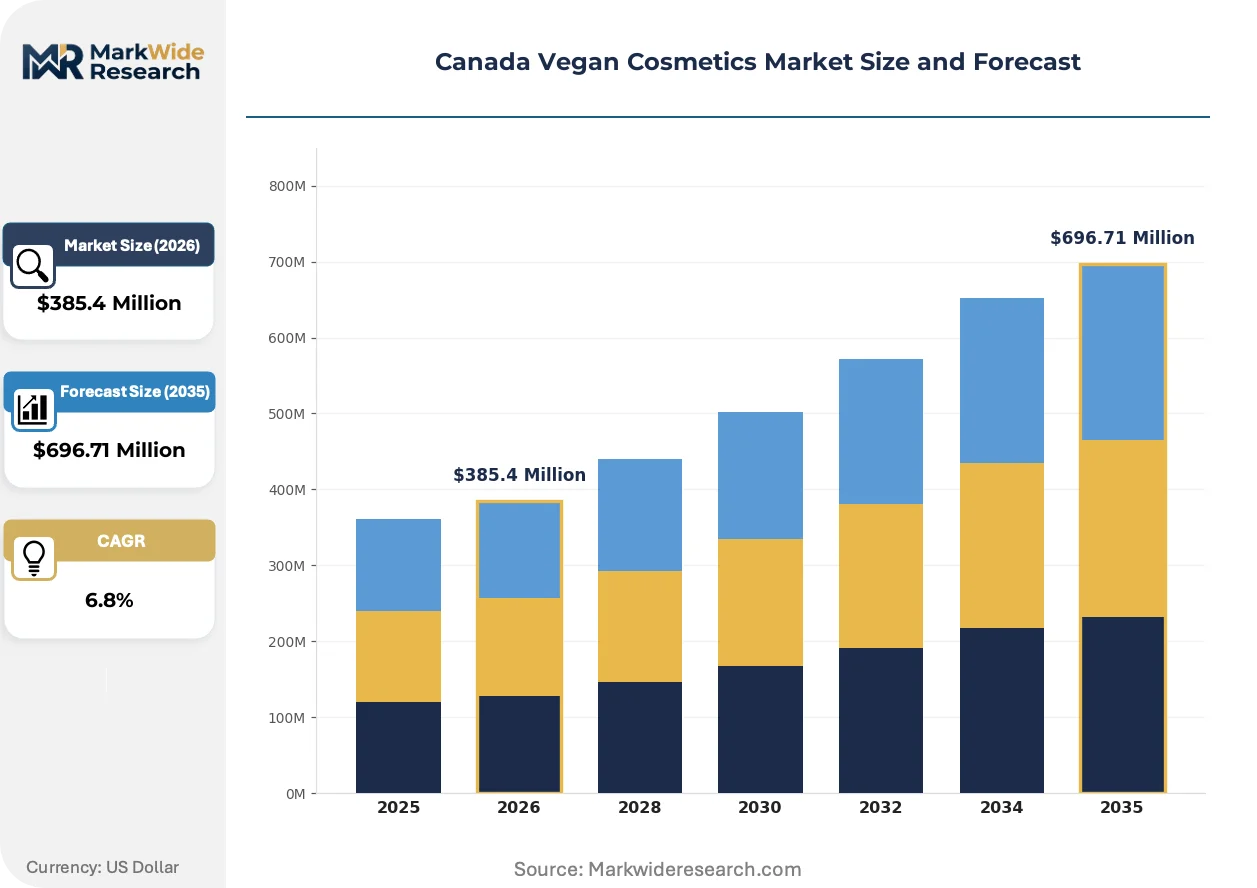
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Vegan Cosmetics Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Makeup, Skincare, Haircare, Fragrance Ingredient Source: Plant-Based, Mineral-Based, Synthetic-Free, Natural Consumer Type: Ethical Consumers, Millennials, Health-Conscious Shoppers, Beauty Enthusiasts Distribution Channel: E-commerce, Specialty Stores, Drugstores, Department Stores |
| Companies Covered | L'Oréal Group, Unilever, Coty Inc., Estée Lauder Companies, Pacifica Beauty, Lush Cosmetics, e.l.f. Beauty, Cover FX, Onoxa, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Vegan Cosmetics Market Trends and Innovations
Biotechnology-derived alternatives to traditional animal ingredients are compressing cost premiums and expanding addressable segments beyond core ethical consumers.
Fermentation-based collagen alternatives replicate structural proteins without animal sourcing. Mid-market skincare brands adopt these inputs at accelerating pace. The technology is miniaturizing production scale requirements, enabling regional batch manufacturing that reduces import dependency.
Health Canada's PMRA maintains escalating scrutiny of natural versus synthetic-free claim definitions. This elevates compliance investment for new entrants while rewarding established certifiers with shelf placement advantages. Skincare lines targeting sensitive-skin segments face the steepest reformulation pressure.
Clean-beauty boutique clusters in Vancouver and Toronto now drive discovery for ethical brands. E-commerce platforms capture subsequent replenishment purchases through subscription mechanics. British Columbia's urban corridors exhibit the sharpest channel bifurcation between experiential retail and digital retention.
Canada Vegan Cosmetics Market Segmentation
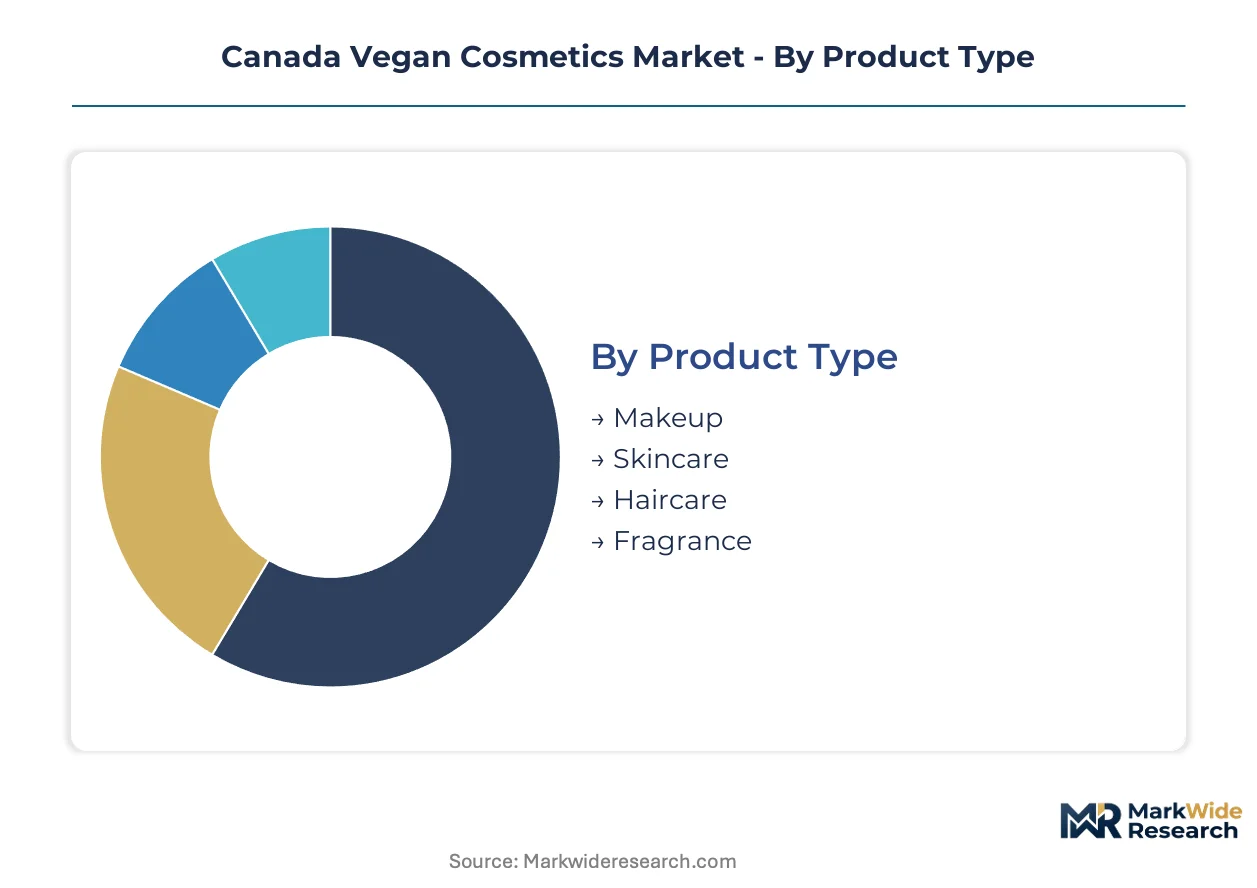
Health Canada's PMRA labeling mandates create divergent compliance burdens across product formulations, reshaping how brands prioritize segment investment. Ingredient transparency requirements concentrate R&D spending toward certifiable categories while compressing margins in legacy synthetic-dependent lines.
Product Type:
Health Canada enforces distinct disclosure standards for leave-on versus rinse-off formulations, elevating compliance complexity for skincare relative to color cosmetics.
- Skincare:Leave-on formulations face the steepest PMRA documentation requirements for plant-based actives. Toronto's urban retail corridors concentrate demand for dermatologically validated vegan moisturizers and serums, with repeat purchase frequency driving subscription model adoption.
- Haircare:Sulfate-free botanical chemistry enables salon-grade performance without animal-derived keratins. Vancouver's clean-beauty boutique clusters show the sharpest channel bifurcation between experiential discovery and digital replenishment for vegan shampoos and conditioners.
- Makeup:Color stability challenges with mineral pigments constrain formulation breadth.
- Fragrance:Alcohol-free botanical extraction methods command premium positioning.
Skincare handles the majority of throughput; haircare is expanding most quickly on share.
Ingredient Source:
Cost tier differentiation separates mass-market accessibility from prestige positioning, with mineral-based stabilizers commanding mid-tier price points.
- Plant-Based:Coconut-derived cetyl alcohol and olive-sourced squalane dominate emulsifier demand. Agricultural supply volatility in Mediterranean and Southeast Asian growing regions compresses margin predictability for brands dependent on these inputs.
- Synthetic-Free:Certification under Health Canada's evolving definitions requires third-party validation investment. Ontario and British Columbia consumers demonstrate elevated willingness-to-pay for verified synthetic-free claims relative to Quebec's francophone base.
- Mineral-Based:Shorter shelf stability constrains national distribution reach.
- Natural:Regulatory ambiguity around claim definitions elevates legal exposure.
Plant-based formulations anchor volume; synthetic-free certification is gaining share fastest.
Consumer Type:
Application intensity varies sharply across demographic cohorts, with ethical sourcing verification driving divergent channel preferences.
- Millennials:Digital-native purchasing patterns concentrate on e-commerce platforms with subscription mechanics. Health-conscious urban populations in Toronto and Vancouver show bifurcation from traditional prestige purchasers toward direct-to-consumer vegan brands.
- Ethical Consumers:Certification scrutiny extends to supply chain transparency beyond ingredient lists. British Columbia's clean-beauty boutique clusters serve as discovery engines for this segment before digital retention captures replenishment.
- Health-Conscious Shoppers:Ingredient label literacy drives pharmacy channel preference.
- Beauty Enthusiasts:Experiential retail consultation demands concentrate in specialty stores.
Millennials handle the majority of throughput; ethical consumers are climbing the fastest.
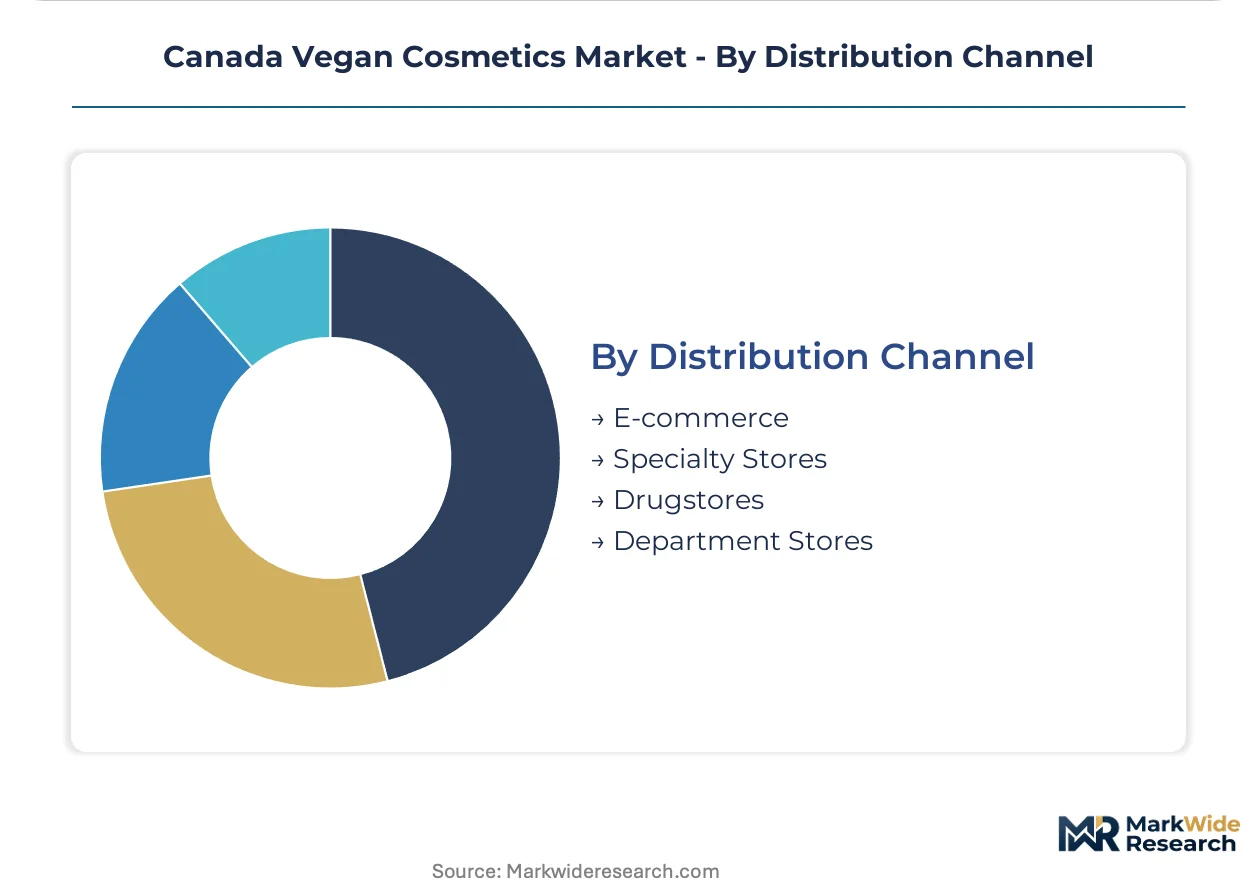
Distribution Channel:
Margin structure separates high-touch consultation formats from scaled digital acquisition, with specialty stores retaining profitability despite volume concentration online.
- E-commerce:Subscription-based replenishment models bypass specialty retail margin extraction while locking repeat purchase frequency. National reach enables Quebec penetration where vegan cosmetic adoption lags Ontario and British Columbia.
- Specialty Stores:Personalized consultation services justify premium pricing for complex skincare regimens. Vancouver and Toronto boutique clusters concentrate experiential discovery before digital channels capture subsequent purchases.
- Drugstores:Mass-market accessibility constraints limit premium formulation distribution.
- Department Stores:Legacy prestige positioning faces compression from direct-to-consumer competition.
E-commerce handles the majority of throughput; specialty stores show the steepest expansion trajectory in margin contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Trans-Canada Highway and CP Rail corridors knit together provincial supply chains, enabling Toronto and Vancouver to function as distribution anchors for plant-based cosmetic formulations moving east-west across the country.
Ontario
Toronto's urban retail corridors concentrate millennial demand for dermatologically validated vegan skincare, with Queen Street West and Yorkville hosting clean-beauty flagship locations. Health Canada's PMRA maintains its Ottawa headquarters, streamlining regulatory consultation for Ontario-based formulators seeking synthetic-free certification. The Golden Horseshoe manufacturing belt around Mississauga houses contract manufacturers serving direct-to-consumer vegan brands.
British Columbia
Vancouver's Kitsilano and Mount Pleasant neighborhoods cluster experiential clean-beauty boutiques where discovery drives initial purchase before digital channels capture replenishment. The province's zero-waste policy frameworks accelerate packaging innovation for solid-format vegan cosmetics. Port Metro Vancouver handles inbound botanical raw materials from Asia-Pacific growing regions, reducing lead times for coconut-derived emulsifiers.
Quebec
Montreal's Plateau-Mile End district shows emerging vegan cosmetic traction among francophone millennials, though penetration lags Ontario and British Columbia benchmarks. The province's distinct civil law tradition creates slightly divergent interpretation of Competition Act cruelty-free claim standards. L'Oréal Group leverages its dermatological R&D infrastructure across Quebec retail networks to anchor plant-based skincare distribution.
Alberta
Calgary's urban core registers growing demand for sulfate-free haircare as botanical formulations displace conventional salon products in professional channels. The province's agricultural sector supplies canola-derived alternatives to olive-sourced squalane, reducing import dependency for regional formulators. Edmonton boutique clusters replicate Vancouver's clean-beauty discovery model at smaller scale.
Canada Vegan Cosmetics Market Competitive Landscape
Listed leaders compete with private specialists across certification speed and formulation transparency, creating a tiered structure where scale advantages clash with agility. L'Oréal Group and Unilever leverage dermatological R&D infrastructure and global supply chains to anchor mass-market plant-based lines. Coty Inc. and Estée Lauder Companies occupy prestige positioning through heritage brand equity. Pacifica Beauty and Lush Cosmetics exemplify entirely vegan architecture specialists. Dominant competitive moves include portfolio diversification into synthetic-free certification and geographic expansion through e-commerce subscription mechanics.
Within the listed multinational tier, L'Oréal Group and Unilever represent scale-driven archetypes with cross-category resources, while Pacifica Beauty and e.l.f. Beauty occupy challenger positions through pricing accessibility and digital-native distribution. Lush Cosmetics exemplifies the private specialist model with experiential retail integration. Cover FX and Onoxa represent mid-tier independents navigating certification investment requirements against compressed margin structures.
| Leading Market Players |
|---|
| L'Oréal Group |
| Unilever |
| Coty Inc. |
| Estée Lauder Companies |
| Pacifica Beauty |
| Lush Cosmetics |
| e.l.f. Beauty |
| Cover FX |
| Onoxa |
| Others |
Pricing and Supply Chain Analysis
Olive-derived squalane displacing petrochemical emollients simultaneously redraws raw material sourcing geography toward Mediterranean suppliers and compresses mid-tier pricing flexibility as agricultural volatility transmits directly into formulation costs.
Pricing Analysis
Volume-discount tiering structures stratify across certification-grade levels rather than conventional premium-mid-economy tiers. Health Canada's PMRA synthetic-free validation commands substantial price premiums in Ontario and British Columbia, while unverified plant-based formulations compete on aggressive e-commerce pricing that captures price-sensitive ethical consumers in Quebec. Cost compression in mass-market tiers intensifies as coconut-derived cetyl alcohol faces Southeast Asian supply fluctuations. Subscription-based replenishment models exhibit lowest price sensitivity; specialty store consultation services justify highest premiums.
Supply Chain Analysis
Strategic stockpiling of botanical emulsifiers dominates inventory strategy given Mediterranean olive harvest volatility and Southeast Asian coconut processing disruptions. Canada draws concentrated supply from Spain, Italy, and Indonesia for squalane and cetyl alcohol inputs. Single-source vulnerability concentrates in olive-derived actives where Spanish drought cycles create intermittent scarcity. Distribution runs through Toronto and Vancouver as east-west anchors, with Port Metro Vancouver reducing Asia-Pacific inbound lead times.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where Health Canada certification entrenchment creates switching costs that lock retail shelf placement and consumer trust.
For Market Incumbents: Secure PMRA synthetic-free certification speed as primary defensive perimeter against emerging direct-to-consumer challengers. Deepen backward integration into botanical emulsifier sourcing through Alberta canola-derived squalane alternatives that reduce Mediterranean import dependency. Channel control through experiential retail consultation in Vancouver and Toronto boutique clusters reinforces margin extraction against e-commerce price erosion.
For New Entrants and Emerging Players: Differentiate on Quebec francophone market penetration where vegan cosmetic adoption trails Ontario and British Columbia benchmarks by double-digit share points. Target sulfate-free haircare as fastest-expanding segment with salon-grade botanical performance claims. Deploy subscription-based replenishment mechanics to bypass specialty retail margin extraction while capturing repeat purchase frequency.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed direct-to-consumer brands possessing Health Canada certification infrastructure but constrained geographic reach. Long-term viability hinges on regulatory compliance scalability across provincial interpretation variations of Competition Act cruelty-free standards. Watch Health Canada's evolving natural versus synthetic-free definitional thresholds as inflection signal for certification framework winners.
| Strategic Initiative | Industry Significance |
|---|---|
| PMRA Synthetic-Free Certification Investment | Health Canada validation secures shelf placement advantage in Ontario and British Columbia retail corridors. |
| Backward Integration into Botanical Sourcing | Alberta canola-derived squalane alternatives reduce Mediterranean olive supply volatility exposure. |
| Subscription-Based Replenishment Launch | Direct-to-consumer mechanics bypass specialty store margin extraction while locking repeat purchase frequency. |
| Quebec Francophone Market Expansion | Montreal and provincial penetration captures underexploited demand relative to Ontario benchmarks. |
| Sulfate-Free Haircare Formulation Scale-Up | Salon-grade botanical chemistry displaces conventional keratin-dependent products in professional channels. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cosmetic formulators, Health Canada regulatory affairs specialists, Toronto and Vancouver specialty retail buyers, and subscription platform operators. Secondary validation drew from Health Canada PMRA disclosure databases, Canadian Food Inspection Agency ingredient standards, Competition Act enforcement records, and provincial retail audit data. Bottom-up volume estimates triangulated against top-down category spending analyses.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, ingredient source certification tier, consumer archetype, and distribution channel with provincial geographic disaggregation. CAGRs were derived from trend extrapolation of historical adoption curves adjusted for regulatory acceleration effects. Forecast inputs incorporated PMRA approval cycle timelines for novel plant-based actives and e-commerce penetration trajectories for subscription mechanics.
The analysis sits within stated boundaries; outcomes outside sustained Health Canada enforcement intensity or abrupt botanical supply disruptions would require recalibration. Forecasts reflect documented assumptions regarding certification timeline compression and consumer willingness-to-pay evolution. Revision becomes warranted when Health Canada definitional thresholds for natural versus synthetic-free claims cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegan Cosmetics
Global Probiotic Cosmetics Market
Vegan Cosmetics
Asia-Pacific Vegan Cosmetics Market
Vegan Cosmetics
Vegan Beauty Products Market
Vegan Cosmetics
Vegan Face Cream Market
Vegan Cosmetics
Organic Cosmetics Market
Vegan Cosmetics
Vegan Cosmetics Market
Vegan Cosmetics
South Korea Vegan Cosmetics Market
Vegan Cosmetics
US Vegan Cosmetics Market
Vegan Cosmetics
Brazil Vegan Cosmetics Market
Vegan Cosmetics
India Vegan Cosmetics Market
Vegan Cosmetics
Australia Vegan Cosmetics Market
Vegan Cosmetics
Functional Cosmetics Market
Vegan Cosmetics
Spain Vegan Cosmetics Market
Vegan Cosmetics
Chile Vegan Cosmetics Market
Vegan Cosmetics
Italy Vegan Cosmetics Market
Vegan Cosmetics
Argentina Vegan Cosmetics Market