
 Italy Vegan Cosmetics Market | 2026-2036
Italy Vegan Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Vegan Cosmetics Market Insights
Multi-source ingredient procurement is restructuring supply relationships across Italy's vegan cosmetics sector. L'Oréal S.A. leverages its Lombardy-based R&D hub to anchor plant-based formulation capabilities. Clarins Group SA specializes in essential oil integration for premium face care lines. Weleda AG sustains its position through controlled botanical sourcing from Alpine cooperatives.
Vegan cosmetics comprise beauty and personal care products formulated without animal-derived ingredients, animal testing, or animal by-products, relying instead on plant-based actives, mineral pigments, and biotechnologically produced alternatives such as squalane from fermented sugar cane. These products serve consumers seeking cruelty-free assurance alongside dermatological efficacy and environmental accountability. Face care and makeup segments lead current revenue generation, with hair care representing the fastest-expanding category as salon professionals convert to vegan protocols. Online retail channels capture disproportionate growth among Gen Z purchasers, while pharmacies retain margin density through clinically positioned dermocosmetic vegan lines.
Italy's Ministry of Health enforces EU Cosmetics Regulation 1223/2009 compliance, while ECHA's REACH framework governs novel plant-derived substance safety assessments. The EU Green Deal's chemical sustainability targets pressure reformulation timelines, accelerating demand for biodegradable emulsifiers and solvent-free extraction methods. Stakeholders must monitor pending revisions to EU-wide microplastic restrictions and Italy's national organic certification harmonization, which will determine which ingredient suppliers retain market access.
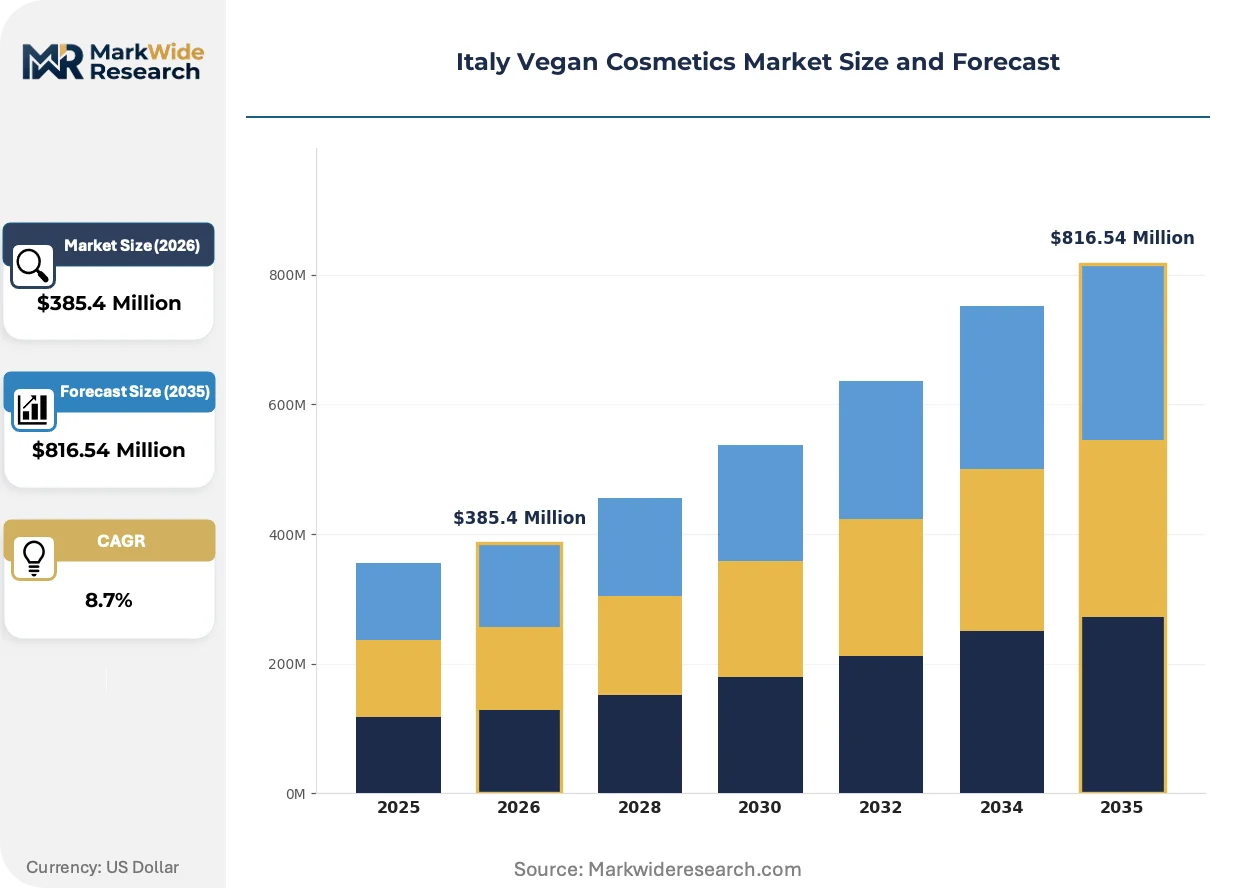
Market Dynamics
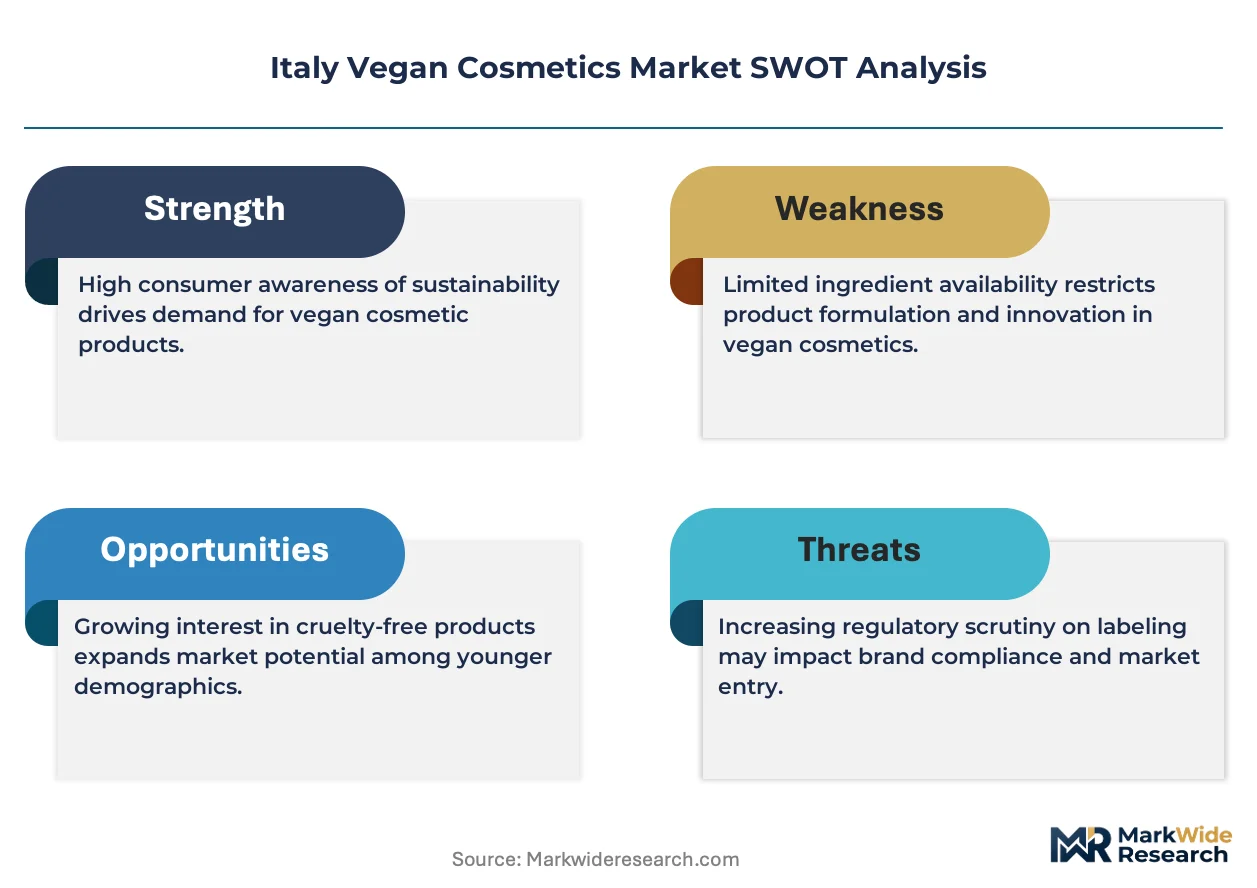
Italy's vegan cosmetics sector is restructuring around biotechnological ingredient substitution as EU Green Deal chemical sustainability targets force reformulation timelines across Lombardy and Veneto manufacturing clusters.
Growth Catalysts
- EU Green Deal chemical sustainability targets:The framework mandates biodegradable emulsifier adoption, accelerating plant-derived surfactant R&D investment across northern Italian formulators.
- Milan beauty innovation cluster:Concentrated R&D infrastructure draws specialty ingredient suppliers and accelerates clinical validation protocols for dermocosmetic vegan lines.
- Fermented sugar cane squalane:This biotechnology-derived emollient resolves supply constraints from shark liver and olive oil sources while meeting performance benchmarks for premium face care.
Market Restraints
- Botanical raw material price volatility:Alpine cooperative supply agreements for essential oils expose formulators to climate-driven harvest fluctuations and contracted volume uncertainty.
- Single-source biotechnology dependency:Fermentation-derived active production concentrates among German and Dutch contract manufacturers, creating supply bottleneck risk for Italian brands.
- REACH novel substance assessment timelines:ECHA's extended safety evaluation protocols delay market entry for innovative plant extracts by 18-24 months versus conventional synthetics.
Strategic Opportunities
- Southern Italy pharmacy channel expansion:Underpenetrated regions including Sicily and Apulia present whitespace for clinically positioned vegan dermocosmetic distribution partnerships.
- Salon professional hair care conversion:Venetian and Emilian hairdressing professionals are adopting vegan color and treatment protocols, opening B2B formulation contracts.
- Italy's national organic certification harmonization:Pending regulatory alignment between Ministry of Health standards and EU organic cosmetics frameworks will create first-mover advantage for certified domestic suppliers.
Industry Challenges
- Green chemistry formulation expertise scarcity:Italian universities produce insufficient cosmetic chemists trained in solvent-free extraction and enzymatic synthesis methods.
- Legacy ERP integration with batch-level traceability:Mid-tier manufacturers face capital intensity upgrading systems to document plant-origin chain of custody for EU compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Vegan Cosmetics Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Face Care, Hair Care, Makeup, Body Care Ingredient Type: Plant-Based, Natural Extracts, Essential Oils, Minerals Sales Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies Customer Type: Millennials, Gen Z, Eco-Conscious Consumers, Professionals |
| Companies Covered | L'Oréal S.A., Beiersdorf AG, LVMH SE, Clarins Group SA, Unilever PLC, The Estée Lauder Companies Inc., Weleda AG, NAOS, Pacifica Beauty LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Vegan Cosmetics Market Trends and Innovations
Biotechnology-derived actives and circular extraction methods are displacing conventional botanical sourcing, while regulatory pressure on microplastic content forces packaging and formulation redesign across Italian manufacturing.
Precision fermentation for cosmetic actives is decentralizing supply relationships previously anchored to agricultural harvest cycles. Specialty manufacturers in Veneto and Emilia-Romagna are adopting microbial squalane and ceramide production to reduce dependency on Mediterranean olive oil and marine sourcing. This biotechnology shift is compressing ingredient lead times from seasonal to continuous production models.
REACH microplastic restriction amendments are forcing reformulation of rinse-off vegan cosmetics containing synthetic glitter and exfoliating beads. Italian formulators are accelerating adoption of cellulose and mineral-derived alternatives ahead of enforcement timelines. Hair care and body scrub segments face the steepest compliance costs as existing inventory cycles through retail channels.
Gen Z purchasers are consolidating spending through direct-to-brand digital channels, disintermediating traditional pharmacy and department store distribution. Milan-based indie vegan brands report disproportionate customer acquisition through TikTok and Instagram commerce versus legacy retail partnerships. This channel rotation is most pronounced among consumers under 25 in northern Italian urban centers.
Italy Vegan Cosmetics Market Segmentation
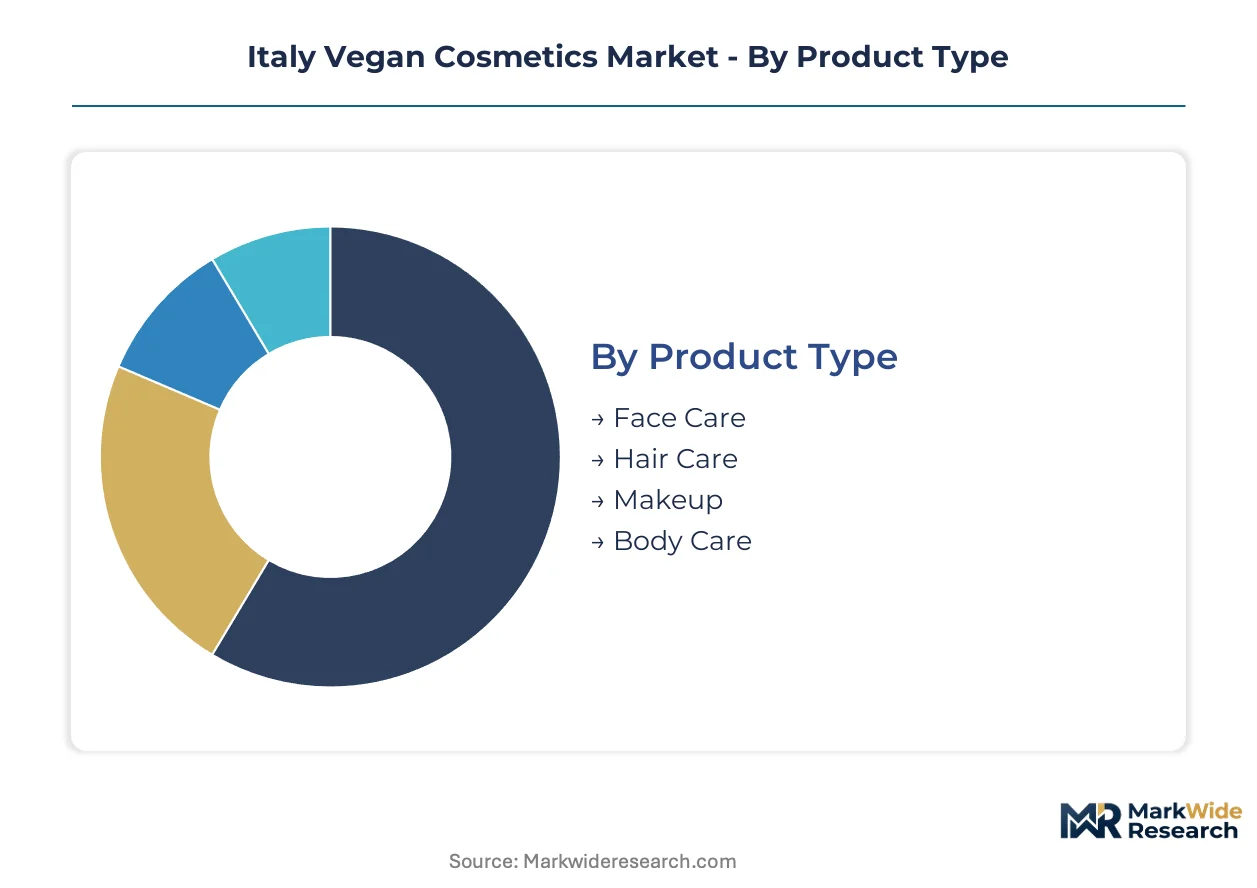
Italy's vegan cosmetics market segments around formulation complexity, procurement depth, and channel access. Understanding these divisions reveals where margin concentrates and which customer cohorts drive technology adoption.
Product Type:
Standalone product categories dominate revenue, while embedded treatment protocols gain traction in professional channels.
- Face Care:Serums, moisturizers, and cleansers formulated with fermented sugar cane squalane and Alpine botanical extracts command premium positioning. Milan's beauty innovation cluster anchors R&D concentration for dermocosmetic vegan lines targeting clinically validated efficacy claims.
- Hair Care:Vegan color systems and treatment protocols are expanding fastest as Venetian and Emilian salon professionals convert from conventional formulations. B2B supply contracts with regional hairdressing chains accelerate category momentum.
- Makeup:Mineral pigments and plant-derived binders replace carmine and lanolin in color cosmetics. REACH microplastic restrictions are forcing reformulation of glitter and exfoliating components ahead of enforcement timelines.
- Body Care:Lotions, scrubs, and washes utilizing biodegradable emulsifiers respond to EU Green Deal chemical sustainability mandates. Cellulose-based alternatives displace synthetic beads in rinse-off applications.
Face Care leads volumes today; Hair Care is gaining share fastest.
Ingredient Type:
Procurement patterns stratify between agricultural harvest cycles and continuous biotechnology production models.
- Plant-Based:Fermented sugar cane squalane and microbial ceramides from Veneto manufacturers reduce dependency on seasonal Mediterranean olive oil sourcing. Continuous production compresses lead times and stabilizes input costs for premium formulators.
- Natural Extracts:Alpine cooperative agreements for botanical actives expose Lombardy formulators to climate-driven harvest volatility. Contracted volume uncertainty complicates long-term production planning.
- Essential Oils:Clarins Group SA and Weleda AG maintain controlled sourcing relationships with Piedmont and Trentino-Alto Adige growers for premium fragrance and therapeutic applications.
- Minerals:Iron oxides, zinc oxides, and mica substitutes from verified conflict-free supply chains support clean-label makeup claims. ECHA REACH safety assessments govern novel mineral-derived substance approvals.
Plant-Based inputs anchor current formulation volumes; biotechnology-derived actives are climbing the fastest.
Sales Channel:
Channel concentration shifts from legacy retail toward direct digital access and clinically positioned pharmacy distribution.
- Online Retail:Milan-based indie vegan brands acquire Gen Z customers disproportionately through TikTok and Instagram commerce. Direct-to-brand digital channels disintermediate traditional department store relationships for consumers under 25.
- Pharmacies:Dermocosmetic vegan lines retain margin density through clinically positioned distribution in northern Italy. Southern regions including Sicily and Apulia present underpenetrated whitespace for expansion partnerships.
- Specialty Stores:Sephora and Douglas flagship locations in Rome, Milan, and Turin curate premium vegan assortments with in-store sampling infrastructure.
- Supermarkets:Mass-market vegan personal care gains shelf space through Esselunga and Coop retail networks, competing on price-accessible clean-label positioning.
Pharmacies dominate value capture today; Online Retail shows the steepest expansion trajectory.
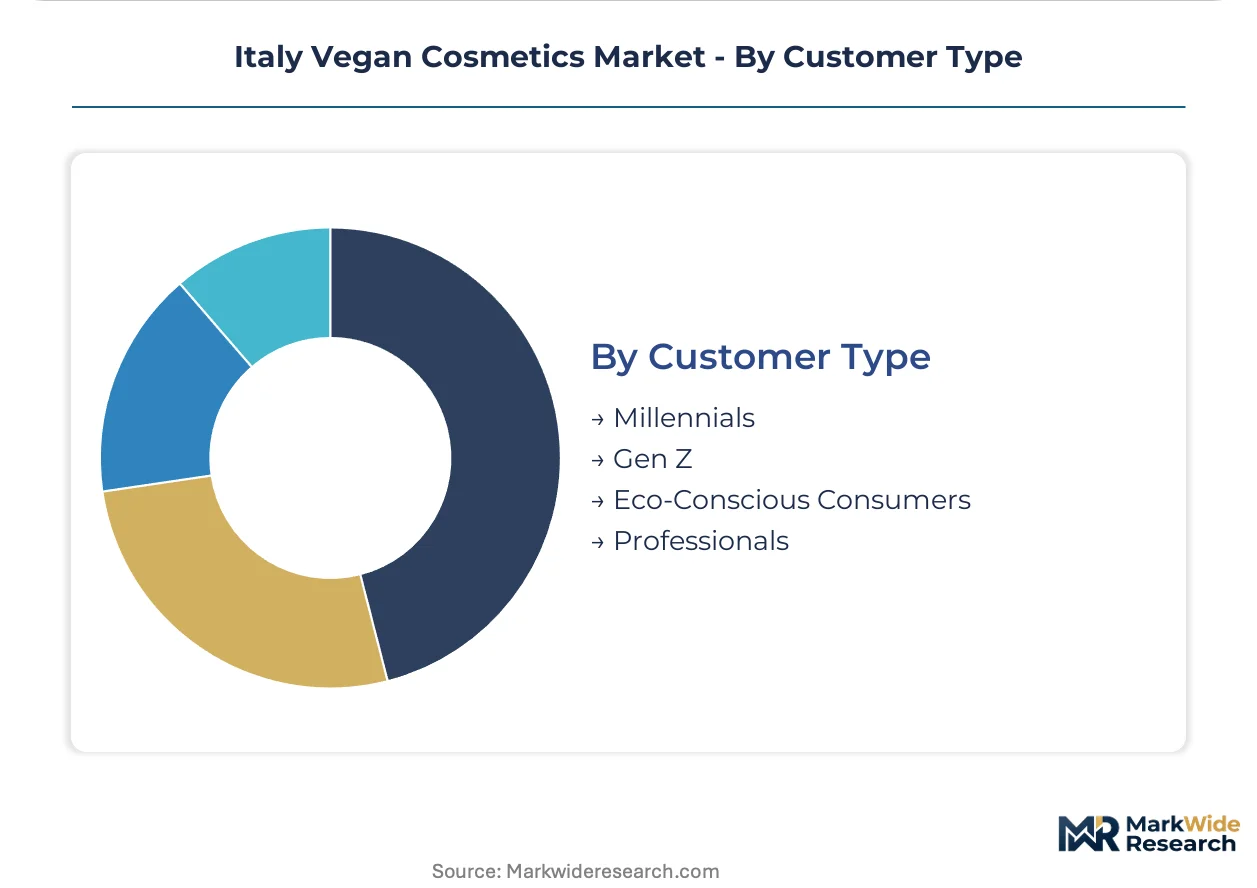
Customer Type:
Generational cohorts and professional segments split between efficacy-seeking and values-driven purchase motivations.
- Gen Z:Digital-native purchasers consolidate spending through brand-owned channels, prioritizing cruelty-free assurance and environmental accountability over legacy heritage positioning.
- Millennials:Northern Italian urban consumers drive specialty retail adoption, balancing dermatological efficacy with sustainability credentials in face care and makeup categories.
- Eco-Conscious Consumers:Certification-focused buyers monitor Italy's pending national organic cosmetics harmonization with EU frameworks, creating first-mover advantage sensitivity.
- Professionals:Venetian and Emilian hairdressing professionals adopt vegan color and treatment protocols, generating B2B formulation demand distinct from retail consumer patterns.
Millennials anchor current spending volumes; Gen Z is expanding most quickly as purchasing power matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Milan's beauty innovation cluster anchors northern Italy's manufacturing concentration, with R&D infrastructure drawing specialty ingredient suppliers and accelerating clinical validation protocols for dermocosmetic vegan lines across Lombardy and Veneto.
Lombardy
Milan-based formulators drive premium face care development through fermented sugar cane squalane integration. ECHA REACH frameworks govern novel plant-derived substance safety assessments for products manufactured here. The region's R&D concentration supports L'Oréal S.A.'s Lombardy-based hub for plant-based formulation capabilities.
Piedmont
Alpine cooperative agreements supply essential oils to premium fragrance and therapeutic applications. The EU Green Deal's chemical sustainability targets pressure local formulators toward biodegradable emulsifier adoption. Turin's proximity to botanical sourcing networks anchors controlled supply relationships for heritage vegan brands.
Veneto
Venetian salon professionals accelerate vegan hair care conversion through B2B formulation contracts for color and treatment protocols. Italy's Ministry of Health enforces EU Cosmetics Regulation 1223/2009 compliance across regional manufacturing. Specialty manufacturers here adopt microbial ceramide production to reduce dependency on seasonal Mediterranean olive oil sourcing.
Emilia-Romagna
Emilian hairdressing professionals expand vegan protocol adoption, generating demand distinct from retail consumer patterns. Pending revisions to EU-wide microplastic restrictions force reformulation of rinse-off cosmetics containing synthetic glitter. Bologna's manufacturing belt concentrates batch-level traceability system upgrades for EU compliance documentation.
Lazio
Rome's pharmacy channel retains margin density through clinically positioned dermocosmetic vegan lines distribution. Southern expansion whitespace includes underpenetrated regions where certification-focused buyers monitor Italy's pending national organic cosmetics harmonization. The capital's retail infrastructure supports Sephora and Douglas flagship locations curating premium vegan assortments.
Italy Vegan Cosmetics Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer digital channels and biotechnology-derived ingredient positioning. The vendor base stratifies across multinational formulators with Lombardy R&D infrastructure, Alpine heritage brands with controlled botanical sourcing, and indie labels leveraging Milan's innovation cluster for rapid product iteration. Three archetypes dominate: scale-driven multinationals with integrated supply chains, specialist houses with geographic ingredient lock-ins, and digital-native challengers with social commerce customer acquisition. Competitive moves concentrate on strategic partnerships with fermentation-derived active suppliers and portfolio diversification into salon professional hair care protocols.
Among multinational formulators, L'Oréal S.A. and Beiersdorf AG occupy positions anchored by Lombardy-based R&D capabilities and scale advantages in plant-based formulation development. Clarins Group SA exemplifies the specialist archetype through essential oil integration for premium face care lines, while Weleda AG represents heritage positioning sustained through controlled botanical sourcing relationships with Alpine cooperatives. These three companies illustrate the competitive tension between biotechnology-driven reformulation capabilities and traditional geographic ingredient advantages shaping procurement strategies across northern Italian manufacturing clusters.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Beiersdorf AG |
| LVMH SE |
| Clarins Group SA |
| Unilever PLC |
| The Estée Lauder Companies Inc. |
| Weleda AG |
| NAOS |
| Pacifica Beauty LLC |
| Others |
Pricing and Supply Chain Analysis
Cosmetic chemists trained in green extraction methods concentrate in Milan and Bologna, and this workforce scarcity widens spreads between premium biotechnology-derived formulations and commodity plant-based alternatives.
Pricing Analysis
Input-cost pass-through from Alpine botanical volatility and fermentation-derived active premiums shapes tiered pricing across Italian vegan cosmetics. Three-tier pricing structure across premium, standard, and economy levels separates dermocosmetic pharmacy lines from mass-market supermarket offerings and indie direct-to-consumer brands. Cost compression in standard tiers intensifies because German and Dutch contract manufacturers command pricing power for microbial squalane. Gen Z purchasers through digital channels show highest price sensitivity, while pharmacy-positioned dermocosmetic buyers accept premium positioning for clinically validated efficacy claims.
Supply Chain Analysis
Single-source vulnerability sits with Dutch and German fermentation facilities supplying microbial ceramides to Veneto formulators. Geographic supply concentration spans Italy for Alpine botanical extraction, Germany for biotechnology contract manufacturing, and France for essential oil distillation infrastructure. Raw material dependencies center on Mediterranean olive oil harvests, fermented sugar cane feedstock, and Piedmont-grown aromatic botanicals. Supply chain risk from REACH novel substance assessment timelines delays ingredient qualification by 18-24 months versus conventional synthetics. Distribution runs through pharmacy wholesale networks in northern Italy, direct-to-brand digital channels for Gen Z acquisition, and Sephora flagship locations in Milan and Rome.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's vegan cosmetics sector represents a late-cycle quality story as consumer demand shifts decisively toward biotechnology-derived actives with verified chain-of-custody documentation.
For Market Incumbents: Lock in controlled sourcing relationships with Alpine cooperatives before national organic certification harmonization creates supplier scarcity. Backward integration into microbial fermentation capabilities in Veneto manufacturing clusters counters dependency on German and Dutch contract manufacturers. Prioritize R&D investment in solvent-free extraction methods to defend margin position against indie brands leveraging Milan's innovation cluster for rapid formulation iteration.
For New Entrants and Emerging Players: Begin with underpenetrated pharmacy distribution partnerships in Sicily and Apulia where clinically positioned dermocosmetic vegan lines retain whitespace. Target salon professional hair care conversion in Venetian and Emilian hairdressing chains through B2B formulation contracts distinct from saturated retail consumer channels. Deploy TikTok and Instagram commerce as primary go-to-market angle to acquire Gen Z purchasers disintermediating legacy department store relationships.
For Investors and Strategic Acquirers: Specialty chemical multinationals with existing biotechnology infrastructure are the most active acquirer in this space, seeking Italian brands with validated plant-based formulation capabilities. Over the medium-term horizon, acquisition targets with integrated Alpine sourcing relationships and REACH-compliant novel substance portfolios command scarcity premium. Monitor pending EU-wide microplastic restriction enforcement timelines as inflection indicator for reformulation cost exposure across rinse-off product inventories.
| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology Partnership | Fermentation-derived active supply agreements with German and Dutch manufacturers reduce harvest dependency for Veneto formulators. |
| Alpine Sourcing Lock-in | Controlled botanical agreements with Piedmont and Trentino-Alto Adige cooperatives secure essential oil supply for premium fragrance lines. |
| Pharmacy Channel Expansion | Southern Italy distribution partnerships in Sicily and Apulia capture whitespace for clinically positioned dermocosmetic vegan assortments. |
| Direct-to-Consumer Launch | TikTok and Instagram commerce infrastructure enables Gen Z customer acquisition disintermediating legacy retail relationships. |
| Regulatory Pre-Positioning | REACH novel substance dossier preparation ahead of microplastic restriction amendments accelerates compliant reformulation timelines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cosmetic formulators, pharmacy category managers, salon professional distributors, and Alpine cooperative supply coordinators alongside secondary validation through ECHA REACH substance registrations, EU Cosmetics Regulation compliance databases, Italian Ministry of Health certification records, and northern Italian regional trade flow data. Bottom-up segmentation modeling and top-down market sizing triangulated volume and value estimates.
Historical reference periods anchored the projection horizon across product type, ingredient sourcing model, sales channel, and generational customer cohort dimensions. CAGRs derived from segmented growth trajectory analysis incorporating biotechnology adoption curves, pharmacy channel expansion rates, and digital commerce penetration patterns specific to Italian Gen Z purchasing behavior.
Caveats apply where EU Green Deal chemical sustainability target revisions, REACH novel substance assessment timeline extensions, or Alpine harvest volatility from climate-driven weather patterns could materially shift the outlook. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegan Cosmetics
South Korea Vegan Cosmetics Market
Vegan Cosmetics
Europe Vegan Cosmetics Market
Vegan Cosmetics
Organic Cosmetics Market
Vegan Cosmetics
Spain Vegan Cosmetics Market
Vegan Cosmetics
Functional Cosmetics Market
Vegan Cosmetics
India Vegan Cosmetics Market
Vegan Cosmetics
Vegan Beauty Products Market
Vegan Cosmetics
China Vegan Cosmetics Market
Vegan Cosmetics
US Vegan Cosmetics Market
Vegan Cosmetics
Mexico Vegan Cosmetics Market
Vegan Cosmetics
Argentina Vegan Cosmetics Market
Vegan Cosmetics
France Vegan Cosmetics Market
Vegan Cosmetics
Chile Vegan Cosmetics Market
Vegan Cosmetics
Japan Vegan Cosmetics Market
Vegan Cosmetics
Canada Vegan Cosmetics Market
Vegan Cosmetics
Vegan Face Cream Market