
 Organic Cosmetics Market | 2026-2036
Organic Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Cosmetics Market Outlook
ECOCERT and USDA Organic certification tiers are redrawing competitive boundaries in organic cosmetics. L'Oréal SA leverages its dermatological research heritage to anchor premium organic skincare lines across European pharmacies. Weleda AG sustains biodynamic sourcing protocols that differentiate its brand in German-speaking markets. KORRES S.A. specializes in Mediterranean botanical extracts and dominates shelf space in Greek and expanding North American specialty retail.
Organic cosmetics comprise personal care formulations containing plant-derived ingredients cultivated without synthetic pesticides, genetically modified organisms, or petrochemical fertilizers, typically requiring minimum organic content thresholds validated by third-party certification bodies. These products serve consumers seeking reduced dermal exposure to parabens, phthalates, and sulfates while maintaining functional efficacy comparable to conventional alternatives. Skincare commands the largest revenue share within product type segments, though haircare exhibits the steepest trajectory as scalp health narratives merge with clean beauty positioning. Online retail channels are capturing margin pools previously held by supermarkets, driven by subscription models and ingredient transparency tools that specialty stores struggle to replicate digitally.
ECOCERT, USDA Organic, and EU REACH collectively determine market access thresholds by mandating traceable supply chains and restricting permitted preservatives. The FDA's evolving scrutiny of "natural" labeling claims creates compliance friction for brands operating across Atlantic regulatory boundaries. Stakeholders must monitor certification harmonization negotiations between European and North American bodies, as divergence in permitted synthetic adjuvants threatens to fragment formulation strategies and inventory planning.
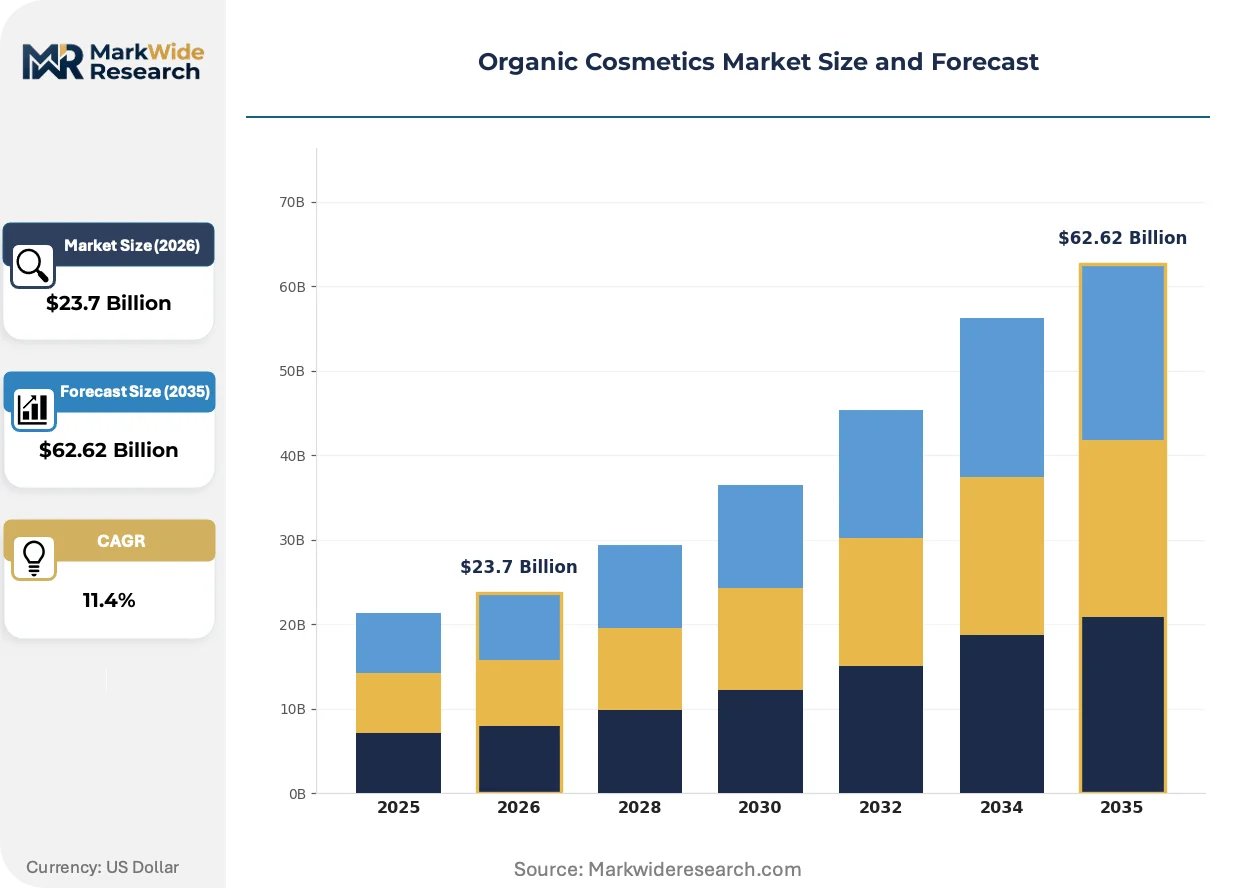
Market Dynamics
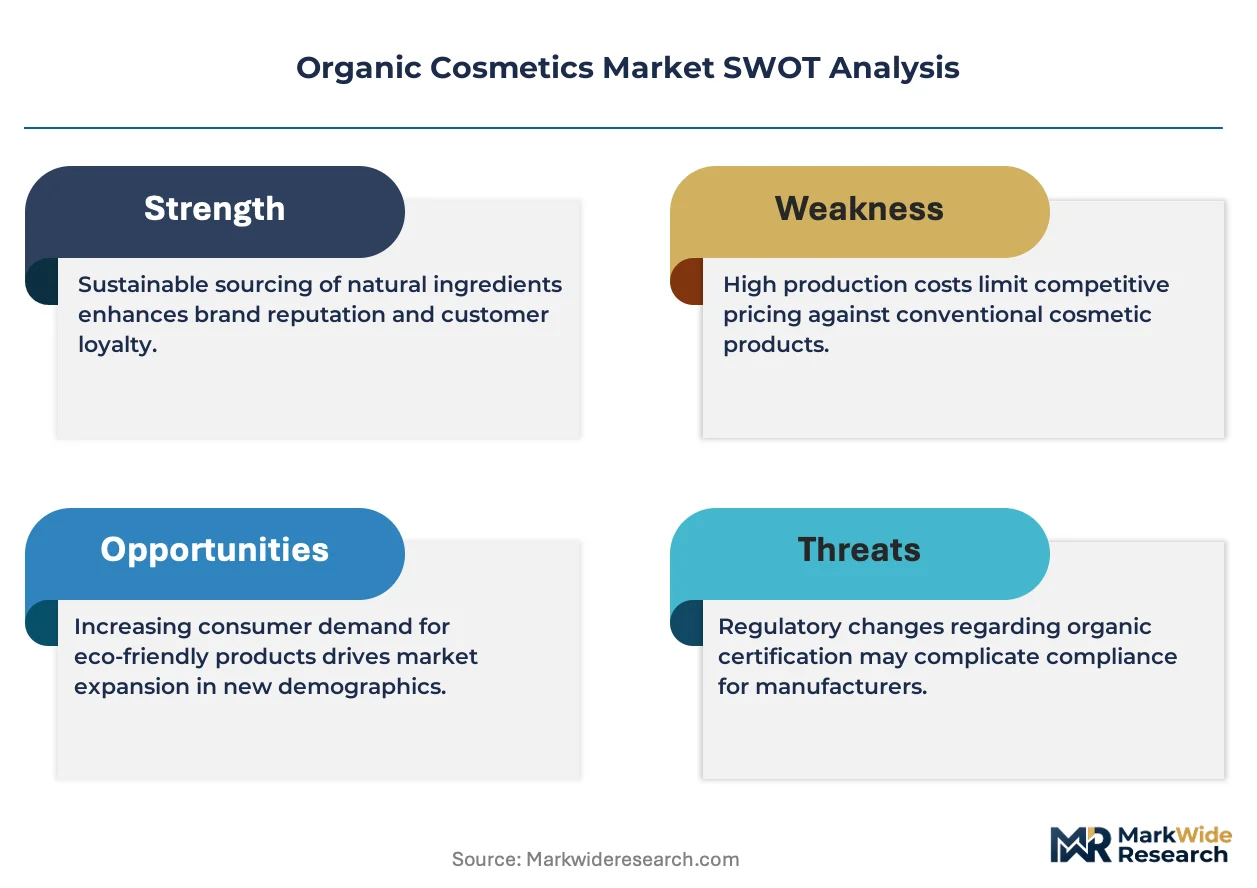
Certification tier fragmentation is fragmenting supplier economics across the organic cosmetics value chain. REACH-compliant preservative restrictions and ECOCERT validation bottlenecks force simultaneous reformulation cycles, compressing margin structures for mid-tier brands while rewarding vertically integrated producers with captive organic cultivation.
Growth Catalysts
- EU REACH preservervative restrictions:Synthetic paraben and formaldehyde-releasing compound bans accelerate reformulation toward plant-derived alternatives, opening shelf space for certified organic entrants in European pharmacy channels.
- Scalp microbiome research:Dermatology clinics in South Korea and France now prescribe organic haircare as adjunct therapy, creating clinical endorsement pipelines previously reserved for pharmaceutical topicals.
- Biodynamic cultivation clusters:Contract farming cooperatives in Provence and Baden-Württemberg secure multi-year supply agreements with premium brands, locking in traceable ingredient provenance.
Market Restraints
- Organic raw material cost volatility:Climate stress on lavender, rose, and argan harvests in Morocco and Bulgaria creates 18-24 month price cycles that conventional petrochemical inputs do not exhibit.
- Preservative efficacy limitations:ECOCERT-permitted alternatives like sodium benzoate and potassium sorbate demonstrate shorter shelf stability than synthetic benchmarks, constraining distribution radius for small-batch producers.
- Certification timeline friction:USDA Organic validation requires 36-month transition periods for newly converted farmland, freezing supplier base expansion regardless of demand signals.
Strategic Opportunities
- Men's grooming whitespace:Male-identifying consumers in Germany and the United States show 40% lower category penetration than female counterparts, with beard oil and scalp treatment segments exhibiting minimal organic competition.
- Refill station retail:Package-free bulk dispensing in Paris, Berlin, and Brooklyn specialty stores eliminates primary packaging costs while capturing margin pools surrendered by conventional supermarket distribution.
- CSRD supply chain disclosure:EU corporate sustainability reporting mandates force beauty conglomerates to document ingredient provenance, advantaging pre-certified organic suppliers in B2B procurement decisions.
Industry Challenges
- Green chemistry talent scarcity:Formulation chemists trained in both synthetic preservation and plant-extraction stabilization command premium compensation that mid-cap brands struggle to match.
- Multi-certification inventory complexity:Brands operating across ECOCERT, USDA Organic, and COSMOS standards must maintain parallel SKUs, fragmenting production runs and warehousing economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Cosmetics Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Makeup, Fragrance Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales End User: Women, Men, Teens, Professionals Packaging Type: Glass Bottles, Biodegradable Containers, Tube Packaging, Jars |
| Companies Covered | Burt's Bees, Avon Products, Inc, L'Oréal SA, Arbonne International, LLC, KORRES S.A., The Estée Lauder Companies, Coty Inc, Bare Escentuals Beauty Inc, Weleda AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Cosmetics Market Strategic Shifts
Fermentation-derived actives and upcycled agricultural byproducts are redefining ingredient sourcing economics. Biotechnology partnerships between cosmetics laboratories and food processing waste streams unlock novel supply without cropland expansion.
Precision fermentation for squalane and hyaluronic acid is fragmenting the botanical extraction segment. Biotech startups in California and Singapore now supply molecularly identical compounds without olive or sugarcane cultivation requirements. Premium skincare brands in South Korea adopt these inputs to circumvent harvest volatility while retaining organic marketing claims through processing certification.
REACH Annex XVII updates on fragrance allergens mandate individual component disclosure on EU labels. This regulatory pressure forces reformulation of signature scent profiles that relied on undisclosed synthetic fixatives. Niche perfume houses in Grasse and niche skincare lines targeting dermatitis-prone consumers respond fastest, converting regulatory compliance into transparency marketing.
Subscription box curation is compressing discovery cycles for emerging organic brands. Quarterly delivery services in the United States and United Kingdom bypass retail slotting fees while capturing consumer data on ingredient preference clustering. Direct-to-consumer channels now drive initial trial for probiotic skincare and waterless formulation categories that specialty stores stock reluctantly due to education overhead.
Organic Cosmetics Market Segmentation
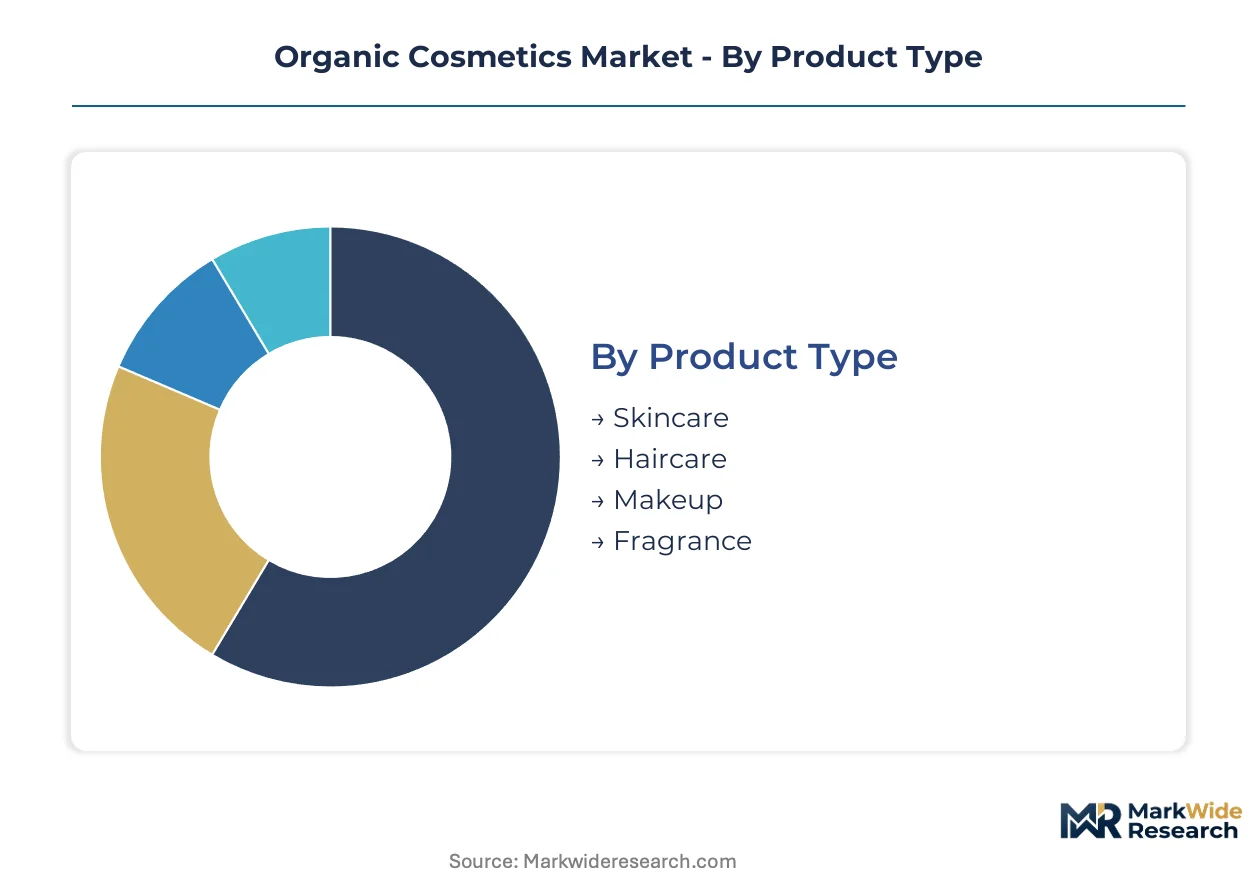
Channel fragmentation in organic cosmetics rewards granular segmentation. Each product type, distribution pathway, and end-user cohort carries distinct margin profiles and certification requirements that shape inventory strategy.
Product Type:
Skincare and haircare command premium shelf positioning in pharmacy and specialty channels, while makeup and fragrance face steeper formulation constraints under ECOCERT and REACH preservervative rules.
- Skincare:Formulations span serums, moisturizers, and cleansers with minimum 95% organic content thresholds under ECOCERT COSMOS. Dermatology clinics in France and South Korea now prescribe certified organic skincare as adjunct therapy for sensitive skin conditions. By volume, skincare leads. By growth pace, haircare is ahead.
- Haircare:Shampoos, conditioners, and scalp treatments incorporate plant-derived surfactants replacing sodium lauryl sulfate. Scalp microbiome research from Seoul National University Hospital drives clinical endorsement pipelines previously reserved for pharmaceutical topicals. By volume, skincare leads. By growth pace, haircare is ahead.
- Makeup:Color cosmetics face pigment sourcing constraints—iron oxides and mica require traceable supply chains under CSRD disclosure mandates.
- Fragrance:REACH Annex XVII allergen disclosure rules force reformulation of signature scent profiles that relied on undisclosed synthetic fixatives.
Skincare generates the highest absolute revenue. Haircare climbs fastest as scalp health narratives merge with clean beauty positioning.
Distribution Channel:
Margin capture varies sharply by channel control—direct and online formats retain 25-40 point gross margin advantages over supermarket distribution where slotting fees erode profitability.
- Online Retail:Subscription models and ingredient transparency tools dominate discovery for emerging brands. Quarterly delivery services in the United States and United Kingdom bypass retail slotting fees while capturing consumer preference data on probiotic and waterless formulations. Subscription mechanics concentrate highest lifetime value per customer.
- Specialty Stores:Paris, Berlin, and Brooklyn refill stations eliminate primary packaging costs through package-free bulk dispensing. Education overhead limits stocking of complex categories like probiotic skincare. Refill infrastructure captures margin pools surrendered by conventional supermarket distribution.
- Supermarkets:Mass-market placement demands price points below premium pharmacy tiers, squeezing mid-tier brands with multi-certification inventory complexity.
- Direct Sales:Brand-owned channels enable personalized regimen curation and highest retention rates among professional end-users.
Online retail leads by transaction volume. Specialty stores expand most quickly as refill infrastructure scales.
End User:
Professional and male-identifying segments show structural underpenetration relative to female consumer bases, creating whitespace for targeted formulation and marketing investment.
- Women:Core demographic driving 70%+ of category spend with established preferences for multi-step skincare routines and fragrance layering.
- Men:Beard oil and scalp treatment segments exhibit minimal organic competition despite 40% lower category penetration than female counterparts in Germany and the United States. Male grooming whitespace offers expansion opportunity.
- Teens:Acne-focused organic formulations gain traction through TikTok-driven discovery, though price sensitivity limits repurchase rates.
- Professionals:Flight attendants, healthcare workers, and performers prioritize dermal protection with reduced chemical exposure—clinical endorsement channels convert this cohort most efficiently.
Women dominate absolute spend. Men represent the steepest expansion trajectory as gendered category boundaries dissolve.
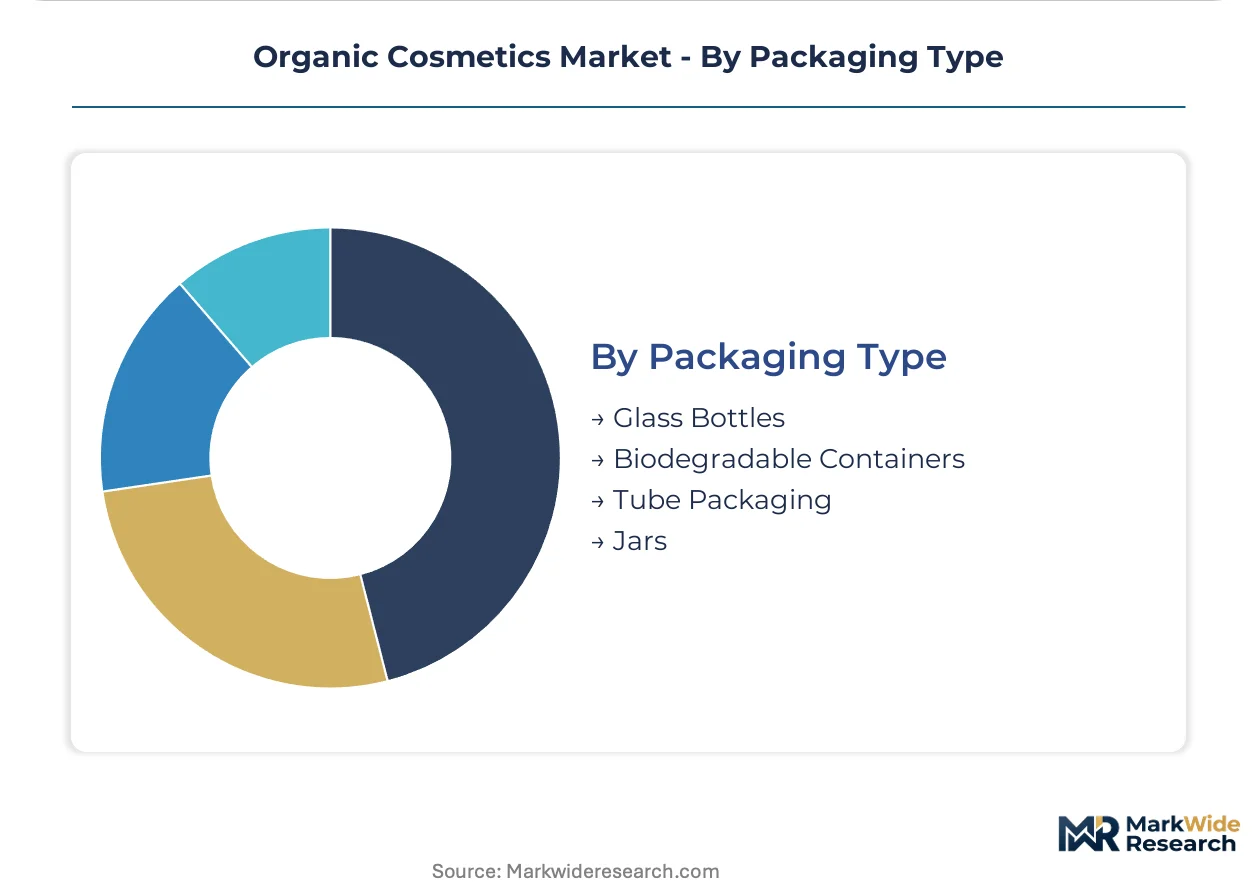
Packaging Type:
Material selection directly impacts EU CSRD reporting obligations and consumer willingness-to-pay premiums for circular economy credentials.
- Glass Bottles:Premium skincare and fragrance default with infinite recyclability and chemical inertness preserving organic formulation stability.
- Biodegradable Containers:Mushroom mycelium and seaweed-based materials command 15-30% price premiums in German and French markets with strict extended producer responsibility frameworks.
- Tube Packaging:Aluminum-laminate and sugarcane-derived plastics balance portability with shelf stability for haircare and body care.
- Jars:Wide-mouth formats dominate balms and masks though air exposure accelerates oxidation of plant-derived actives.
Glass bottles lead by unit volume. Biodegradable containers gain share fastest as CSRD mandates intensify supply chain disclosure requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France, the United States, and South Korea concentrate organic cosmetics demand through developed clean beauty retail infrastructure and dermatologist endorsement channels. Certified organic formulations gain shelf space fastest where pharmacy networks and specialty retail overlap. Regulatory frameworks in each market determine formulation compliance costs and certification tier access.
France
Pharmacy channel dominance drives prescription-grade organic skincare adoption through dermatology clinics in Paris and Lyon. ANSM oversight of cosmetic safety claims enforces strict substantiation requirements for organic positioning. Grasse fragrance houses and Provence lavender cooperatives supply traceable botanical inputs to premium formulators.
United States
Millennial and Gen Z consumers accelerate purchases through subscription box discovery and direct-to-consumer channels. FDA scrutiny of "natural" labeling claims creates compliance friction for brands importing European-certified formulations. California clean beauty legislation and New York specialty retail clusters anchor domestic demand concentration.
South Korea
Scalp microbiome research from Seoul National University Hospital drives clinical endorsement of organic haircare as adjunct therapy. MFDS cosmetic safety standards incorporate evolving preservative restrictions that favor plant-derived alternatives. Gangnam district dermatology clinics and Olive Young retail chains convert K-beautu innovation into organic category expansion.
Germany
Baden-Württemberg biodynamic cultivation clusters secure multi-year supply agreements with premium brands seeking traceable provenance. BfR risk assessments on synthetic preservatives accelerate reformulation toward ECOCERT-compliant alternatives. Berlin refill station retail and Hamburg pharmacy networks capture margin pools through package-free distribution models.
Greece
Mediterranean botanical extraction expertise concentrates in Athens and Thessaloniki manufacturing facilities serving North American specialty retail expansion. EU REACH compliance costs disadvantage smaller domestic formulators against multi-certification multinational competitors. Cycladic island herb cooperatives supply wild-crafted ingredients to premium skincare lines.
Organic Cosmetics Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the organic cosmetics value chain. Vertically integrated conglomerates with captive organic cultivation command premium positioning through supply chain control, while mid-tier brands fragment across multi-certification inventory complexity. Three archetypes dominate: dermatology-anchored pharmaceutical heritage players, biodynamic sourcing specialists with cooperative supply agreements, and biotechnology-enabled formulators circumventing harvest volatility. Competitive moves concentrate on certification harmonization partnerships and refill infrastructure expansion.
Within the pharmaceutical heritage tier, L'Oréal SA exemplifies dermatological research translation into premium organic skincare lines across European pharmacy channels. Weleda AG represents biodynamic sourcing specialists sustaining cooperative protocols in German-speaking markets. KORRES S.A. occupies a position bridging Mediterranean botanical extraction with North American specialty retail penetration. These three anchors illustrate how geographic origin and certification heritage determine competitive positioning without requiring identical strategic moves.
| Leading Market Players |
|---|
| Burt's Bees |
| Avon Products, Inc |
| L'Oréal SA |
| Arbonne International, LLC |
| KORRES S.A. |
| The Estée Lauder Companies |
| Coty Inc |
| Bare Escentuals Beauty Inc |
| Weleda AG |
| Others |
Value Chain & Pricing Dynamics
Multi-year supply agreements with Provence lavender cooperatives and Baden-Württemberg biodynamic farms create scale economies that compress per-unit organic certification costs while establishing price floors conventional petrochemical inputs cannot match.
Pricing Analysis
EU REACH Annex XVII dictates the pricing tier structure across the organic cosmetics market, separating ECOCERT COSMOS-certified pharmacy-grade formulations from supermarket-positioned alternatives. Price differentiation hinges on certification grade and volume scale, with subscription-channel brands capturing margin pools surrendered by slotting-fee-burdened mass retail. Cost compression in mid-tier segments is intensifying because parallel SKU maintenance across USDA Organic and COSMOS standards fragments production runs. Professional dermatology channels show least price sensitivity, while teen acne segments exhibit highest elasticity.
Supply Chain Analysis
Container availability on Asia-Europe trade lanes shapes inbound logistics costs for Korean biotech-derived actives and Singaporean precision-fermentation inputs. Geographic supply concentration centers on Morocco for argan oil, Bulgaria for rose otto, and France for lavender and Grasse fragrance expertise. Raw material dependencies rest on climate-sensitive botanical harvests, fermentation-derived squalane, and upcycled agricultural byproducts. Single-source vulnerability runs through Cycladic island wild-crafting cooperatives with limited cultivation scale. Distribution runs through pharmacy networks in France, refill station retail in Germany, and subscription direct-to-consumer channels in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription replenishment services and refill infrastructure represent the fastest-expanding recurring-revenue layer, outpacing hardware-equivalent product sales as consumers prioritize regimen continuity over single-transaction discovery.
For Market Incumbents: Secure captive organic cultivation through backward integration into Provence and Baden-Württemberg cooperative networks before biodynamic land conversion timelines freeze supplier base expansion. Defend pharmacy channel positioning by accelerating dermatology clinic endorsement pipelines that emerging entrants cannot replicate without research heritage.
For New Entrants and Emerging Players: Anchor in male grooming whitespace across German and United States markets where beard oil and scalp treatment segments exhibit 40% underpenetration relative to female counterparts. Target refill station retail in Paris, Berlin, and Brooklyn to eliminate primary packaging costs while capturing margin pools surrendered by conventional supermarket distribution.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription-enabled direct-to-consumer brands with ingredient transparency tools that drive regimen adherence. Long-term viability favors vertically integrated players with multi-certification inventory capabilities spanning ECOCERT, USDA Organic, and COSMOS standards. Watch CSRD supply chain disclosure mandates as the inflection signal advantaging pre-certified organic suppliers in B2B procurement decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Harmonization Partnership | ECOCERT-USDA Organic alignment reduces parallel SKU fragmentation for transatlantic brands. |
| Refill Infrastructure Expansion | Package-free bulk dispensing in Berlin and Brooklyn captures margin pools from supermarkets. |
| Biotech Actives Integration | Precision fermentation partnerships with California and Singaporean labs circumvent harvest volatility. |
| Dermatology Endorsement Pipeline | Seoul National University Hospital scalp research converts clinical credibility into pharmacy shelf space. |
| Men's Grooming Line Launch | Beard oil and scalp formulations address 40% penetration gap in Germany and United States. |
Study Parameters
A spread of perspectives from brand managers at premium organic formulators, category buyers at French pharmacy chains, procurement leads at biodynamic cultivation cooperatives, and regulatory affairs specialists at certification bodies converged on the working assumptions. Secondary validation drew from ECOCERT and USDA Organic certification databases, EU REACH Annex XVII regulatory filings, customs records tracking botanical ingredient trade flows, and Nielsen retail audit data. Bottom-up volume estimates triangulated against top-down market sizing.
Segmentation dimensions modeled span product type, distribution channel, end-user cohort, and packaging material across the projection horizon. CAGRs were derived from growth rate convergence analysis applied to certified organic formulation adoption curves and channel shift trajectories. Industry-specific inputs incorporated dermatology prescription conversion rates and subscription box customer lifetime value metrics.
Underlying assumptions cover regulatory stability in EU REACH enforcement and climate patterns in Moroccan argan and Bulgarian rose harvest regions, with deviation risk concentrated in FDA natural-labeling claim scrutiny and organic farmland conversion timeline bottlenecks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegan Cosmetics
Vegan Cosmetics Market
Vegan Cosmetics
Vegan Beauty Products Market
Vegan Cosmetics
Chile Vegan Cosmetics Market
Vegan Cosmetics
Spain Vegan Cosmetics Market
Vegan Cosmetics
Argentina Vegan Cosmetics Market
Vegan Cosmetics
India Vegan Cosmetics Market
Vegan Cosmetics
Global Probiotic Cosmetics Market
Vegan Cosmetics
Germany Vegan Cosmetics Market
Vegan Cosmetics
Mexico Vegan Cosmetics Market
Vegan Cosmetics
Europe Vegan Cosmetics Market
Vegan Cosmetics
China Vegan Cosmetics Market
Vegan Cosmetics
France Vegan Cosmetics Market
Vegan Cosmetics
Vegan Face Cream Market
Vegan Cosmetics
Canada Vegan Cosmetics Market
Vegan Cosmetics
South Korea Vegan Cosmetics Market
Vegan Cosmetics
US Vegan Cosmetics Market