
 Table Sauce Market | 2026-2036
Table Sauce Market Size, Share, and Industry Trends Forecast 2026-2036
Table Sauce Market Intelligence
A growing scarcity of experienced flavor scientists capable of developing low-sodium and clean-label formulations is reorganizing product development cycles. McCormick & Company leverages its global R&D network to address regional flavor preferences. Kikkoman Corporation sustains its market position through specialization in soy-based sauces and proprietary fermentation expertise. Meanwhile, Unilever competes on brand recognition and extensive distribution across both retail and food service channels.
Table sauce refers to a prepared liquid, paste, or cream condiment added to food to enhance flavor, moisture, and texture. These products are typically shelf-stable, often achieved through pH control using vinegar or citric acid, water activity reduction via sugar or salt, and sometimes thermal processing. While ketchup and mayonnaise remain high-volume categories, the hot sauce segment shows significant growth driven by flavor experimentation. Packaging in bottles dominates retail, but flexible pouches are gaining share in the food service application due to portion control and operational efficiency.
Food safety and labeling regulations from agencies like the U.S. FDA and the European Food Safety Authority (EFSA) govern allergen declarations and nutritional information. In markets like India, standards set by the FSSAI impact ingredient sourcing and permitted additives, influencing market access for manufacturers. Navigating the divergence between regional consumer taste profiles and increasingly harmonized international food safety standards will define future competitive success.
Market Dynamics
The central tension shaping the table sauce market is the conflict between consumer demand for authentic, diverse global flavors and the industrial necessity for shelf-stable, cost-effective formulations. This dynamic is intensified by regulatory pressure, particularly from agencies like the FDA, to reduce sodium content without compromising taste.
Growth Catalysts
- Quick-Service Restaurant Expansion:The proliferation of quick-service and fast-casual restaurant chains in Southeast Asian urban centers, including Bangkok and Ho Chi Minh City, drives significant volume demand for portioned and bulk sauces.
- Sodium Reduction Mandates:Guidelines from health authorities such as the U.S. FDA, which encourage voluntary sodium reduction targets, are compelling manufacturers to innovate with new formulations, creating a market for low-sodium alternatives.
- Proprietary Process Technology:Expertise in specialized techniques like fermentation for soy-based sauces allows producers to create high-value, differentiated products with unique flavor profiles that are difficult for competitors to replicate.
Market Restraints
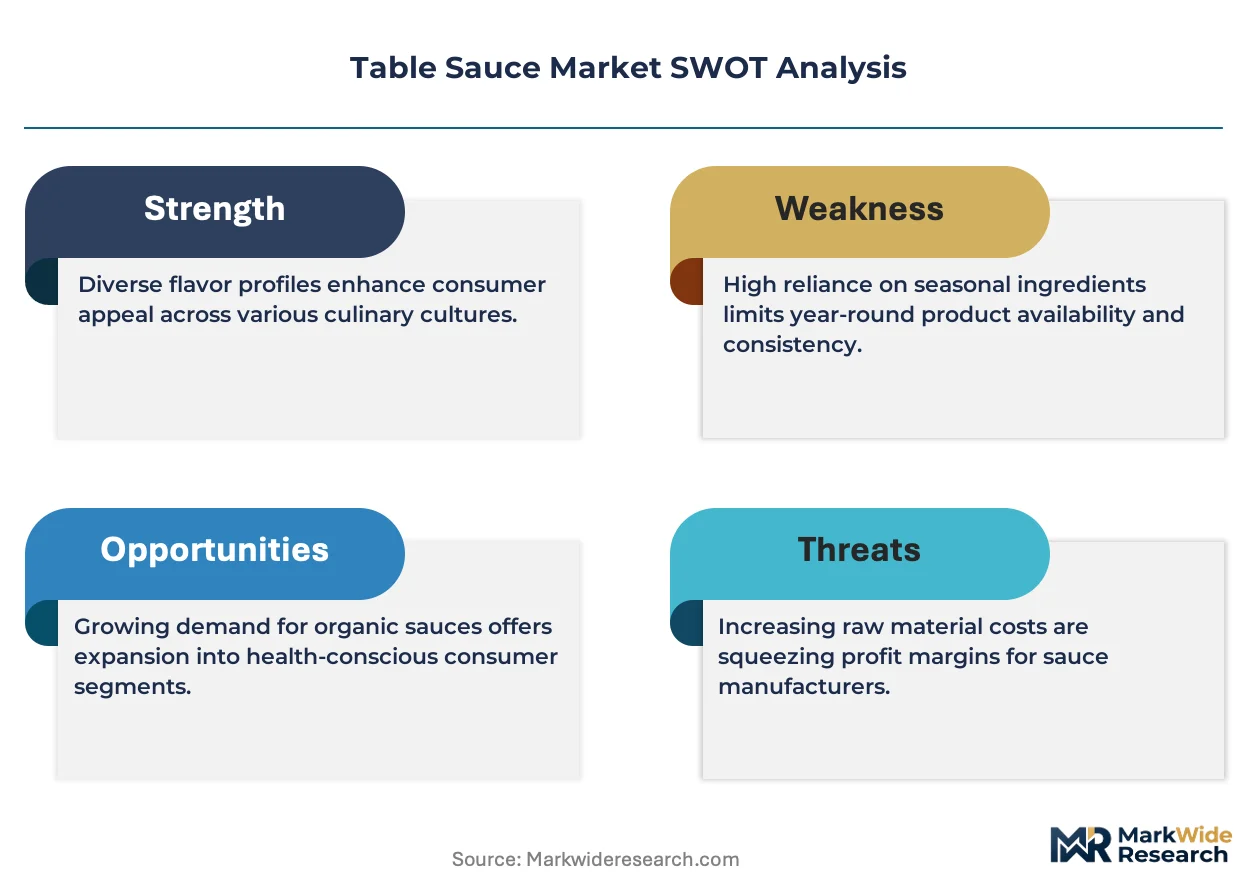
- Input Cost Volatility:Fluctuations in the price and quality of key agricultural commodities, including tomatoes, chili peppers, and soybeans, directly impact production costs and create margin pressure for manufacturers.
- Regulatory Divergence:Navigating disparate international food safety standards, such as differing rules on permitted additives between the European Food Safety Authority (EFSA) and India's FSSAI, complicates global product launches.
- Formulation Expertise Scarcity:A growing shortage of experienced flavor scientists capable of developing clean-label and low-sodium sauces that meet consumer taste expectations acts as a bottleneck for product development.
Strategic Opportunities
- Plant-Based Food Pairings:Developing and marketing sauces specifically formulated to enhance the flavor, moisture, and texture of plant-based meat alternatives addresses a specific need in a high-growth adjacent category.
- Direct-to-Consumer Channels:The rise of e-commerce platforms enables artisanal and specialty hot sauce makers to bypass traditional retail gatekeepers and build direct relationships with consumers, fostering brand loyalty.
- Geographic White Space:Untapped demand in certain Eastern European markets, where consumer palates are diversifying but local production of Western-style condiments like barbecue sauce and specialty mayonnaises remains limited.
Industry Challenges
- Clean-Label Supply Chains:Reconfiguring procurement to source traceable, non-GMO, and organic-certified ingredients at scale without compromising cost or performance presents a significant logistical and financial challenge.
- Allergen Labeling Complexity:Adhering to evolving and inconsistent allergen declaration regulations across major markets, such as the EU and the US, requires constant vigilance and investment in compliance systems.
- Sensory Science Talent Gap:A shortage of food technologists who possess dual expertise in sensory panel management and the regulatory frameworks of multiple countries hinders the efficient global rollout of new products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Table Sauce Market |
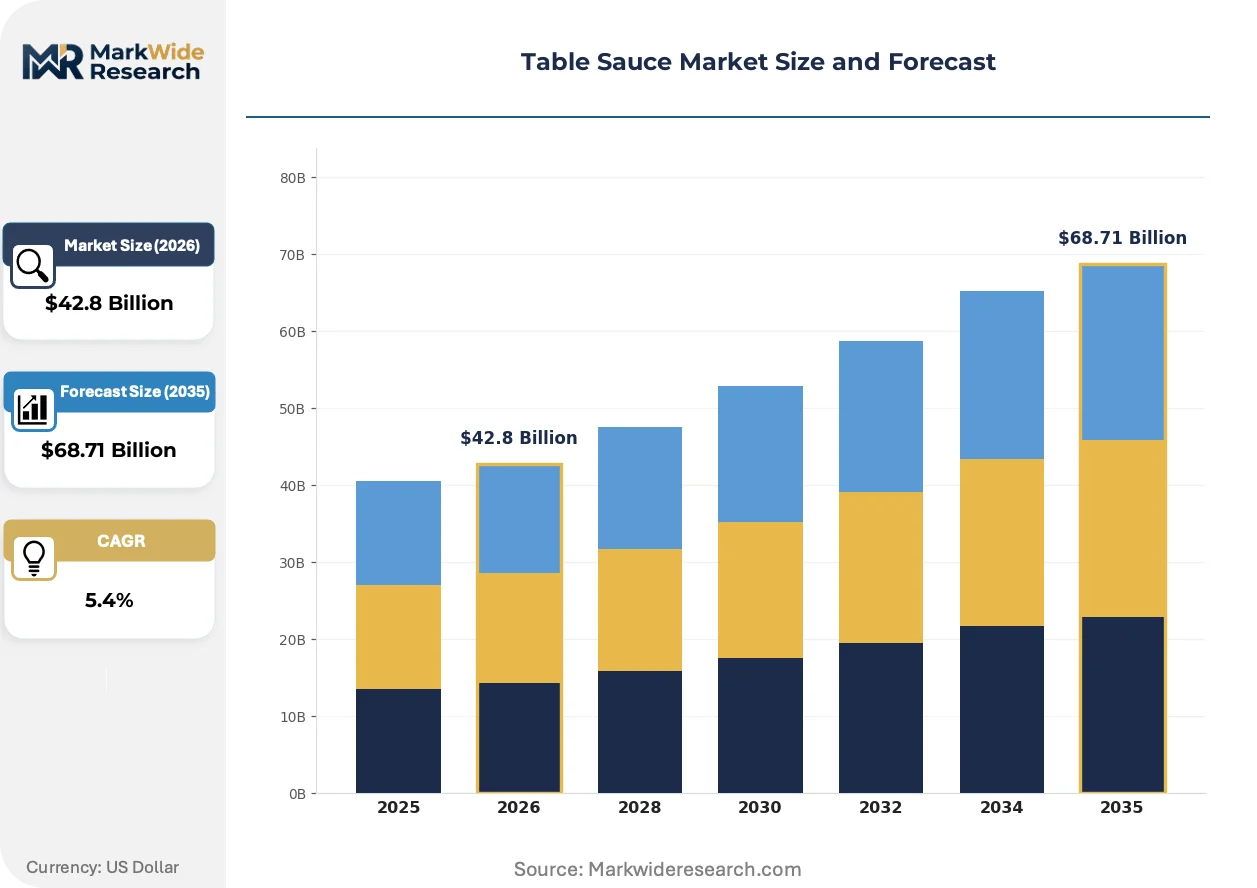
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $68.71 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ketchup, Mayonnaise, Mustard, Barbecue, Soy Sauce, Hot Sauce Form: Liquid, Paste, Cream, Powder, Gel Application: Home Use, Food Service, Institutional, Catering Packaging Type: Bottle, Sachet, Jar, Pouch, Dispenser |
| Companies Covered | McCormick & Company, Kikkoman Corporation, Unilever, Dr. Oetker, Del Monte Foods, The Kraft Heinz Company, Conagra Brands, Lee Kum Kee, Nestle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Table Sauce Market Strategic Shifts & Innovations
Product development is shifting from optimizing mass-market staples like ketchup to creating specialized, health-conscious, and regionally authentic flavor profiles. This evolution is driven by consumer exploration and tightening food safety and labeling standards. The market's future will be defined by formulation agility and transparent sourcing.
Technology-Driven Flavor Customization
Precision fermentation allows for the creation of specific flavor compounds and functional ingredients without relying on variable agricultural inputs. Niche and clean-label sauce producers are adopting this to achieve unique and consistent taste profiles. This technological capability is fragmenting the traditional flavor market, enabling smaller brands to compete on taste innovation.
Regulatory Push for Cleaner Labels
The European Food Safety Authority (EFSA) continues to tighten regulations on food additives, colorants, and preservatives as part of a broader clean-label movement. This forces manufacturers to reformulate products, often replacing synthetic stabilizers with natural alternatives like citrus fiber or cultured sugar. The creamy dressings segment is particularly affected, requiring significant R&D to maintain texture and shelf life.
Shift in At-Home Consumption Patterns
A notable behavioral change is the premiumization of at-home dining, with consumers seeking to replicate restaurant-quality meals. This trend disrupts traditional retail channels, where basic private-label condiments face competition from both co-branded restaurant sauces and artisanal, small-batch offerings. This dynamic is most visible in North American and Western European markets, fueled by digital food media.
Table Sauce Market Segmentation
Understanding the distinct segments within the table sauce market is crucial for manufacturers to tailor product offerings and distribution strategies effectively. Consumer preferences for flavor, texture, and convenience vary significantly across different product types and usage occasions. This granular analysis illuminates where competitive pressures are most acute and where innovation can yield the highest returns.
Product Type:
The table sauce market experiences significant substitution pressure, particularly for traditional product types facing newer, more experimental flavor profiles.
- Ketchup:A viscous, sweet-sour condiment primarily made from tomatoes, vinegar, sugar, and spices. Demand concentrates in quick-service restaurants across North America, driven by its universal appeal as a dipping sauce.
- Mayonnaise:A thick, creamy emulsion of oil, egg yolk, vinegar or lemon juice, and seasonings. Its versatility makes it a staple in both home kitchens and food service applications.
- Mustard:A pungent condiment prepared from mustard seeds, vinegar, water, and spices. Demand for specialty and artisanal varieties is expanding in deli and gourmet food sectors.
- Barbecue:A rich, smoky, and often sweet or tangy sauce used for grilling, marinating, and dipping. Its popularity is tied to outdoor cooking trends and casual dining experiences.
- Soy Sauce:A fermented condiment made from soybeans, wheat, salt, and water, offering umami flavor. Kikkoman Corporation maintains a strong position through proprietary fermentation techniques.
- Hot Sauce:A fiery condiment typically made from chili peppers, vinegar, and salt, often featuring fermented ingredients. Consumer experimentation drives growth in Western European retail channels, seeking diverse heat levels and flavor complexities.
Ketchup anchors the volume base while Hot Sauce gains share at the steepest rate.
Form:
The form factor of table sauces directly impacts production costs and consumer convenience across various usage scenarios.
- Liquid:Free-flowing, pourable sauces typically packaged in bottles or pouches, offering ease of dispensing. Food service operations in Southeast Asia drive significant volume for bulk liquid condiments.
- Paste:Concentrated sauce forms, often requiring dilution or used as a base for other preparations. Asian cuisines frequently utilize paste forms for flavor intensity.
- Cream:Thick, emulsified sauces like mayonnaise or creamy dressings, requiring careful formulation for stability and texture. Regulatory pushes for cleaner labels are forcing reformulation efforts in this segment.
- Powder:Dehydrated sauce ingredients that are rehydrated before use, offering extended shelf life and reduced shipping weight. This form is common in institutional catering and dry mix applications.
- Gel:Semi-solid, viscous preparations that maintain shape, often used for decorative plating or specific textural experiences. Specialty culinary applications sometimes feature gel-based condiments.
Liquid forms offer the broadest application diversity, while cream forms demand specialized R&D for consistent quality.
Application:
Volume demand for table sauces varies dramatically across different end-use applications, influencing packaging and formulation priorities.
- Home Use:Retail-packaged sauces purchased by individual consumers for at-home meal preparation and dining. Premiumization of at-home dining in North America drives sales of artisanal and co-branded offerings.
- Food Service:Bulk and portion-controlled sauces supplied to restaurants, cafes, and quick-service establishments. Quick-service restaurant expansion in urban centers like Bangkok generates substantial demand.
- Institutional:Large-volume sauce formats supplied to facilities such as hospitals, schools, and corporate cafeterias. Cost-effectiveness and shelf-stability are critical factors in this segment.
- Catering:Sauces provided for events and large gatherings, often requiring convenient dispensing and diverse flavor options. Flexible pouches are gaining traction for operational efficiency in catering services.
Food Service represents a strategically important channel for volume, while Home Use offers opportunities for brand differentiation.
Packaging Type:
Supply chain configurations for table sauces are heavily influenced by the chosen packaging types, from bulk containers to individual sachets.
- Bottle:Rigid containers, typically glass or plastic, widely used for retail sales due to consumer familiarity and reusability. Ketchup and mayonnaise sales predominantly run through bottled formats in supermarkets.
- Sachet:Small, single-serving packets commonly found in quick-service restaurants and travel kits. These provide convenience and hygiene for on-the-go consumption.
- Jar:Glass containers, often used for specialty sauces, relishes, and preserves, conveying a premium or artisanal image. Gourmet condiment brands frequently choose jars for their shelf appeal.
- Pouch:Flexible, lightweight packaging offering benefits in portion control, reduced waste, and shipping efficiency. Food service operations increasingly adopt pouches for bulk sauces in high-volume settings.
- Dispenser:Bulk systems designed for high-volume self-service or back-of-house use in commercial kitchens. These minimize waste and streamline operations in large establishments.
Bottles cater to established consumer preferences, while pouches offer significant operational efficiencies for commercial users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. FDA's guidelines on sodium reduction influence product development across the table sauce market. This regulatory environment pushes manufacturers to innovate formulations while meeting diverse consumer preferences. Regional demand patterns reflect a mix of established categories and emerging flavor trends.
United States
Consumer demand in the United States prioritizes both convenience and health-conscious options for table sauces. The U.S. FDA's voluntary sodium reduction targets compel manufacturers to reformulate products. Major food processing hubs like Chicago and Los Angeles see significant R&D investment in low-sodium and clean-label sauce development.
India
India's table sauce market experiences strong demand for both traditional local condiments and Western-style offerings. The FSSAI's standards on ingredient sourcing and permitted additives significantly impact market access. Urban centers such as Mumbai and Delhi are driving consumption, with a rising preference for globally inspired flavors.
Germany
German consumers show a steady demand for classic table sauces, alongside a growing interest in organic and specialty variants. The European Food Safety Authority (EFSA) regulations on food additives and labeling necessitate continuous product reformulation. Food innovation clusters in cities like Hamburg and Munich focus on sustainable and clean-label sauce production.
Thailand
Thailand's market is propelled by a robust food service sector and evolving culinary tastes in urban areas. Local health authorities are increasingly emphasizing nutritional transparency for packaged foods. Bangkok, a major urban center, exhibits high volume demand for portioned sauces in quick-service restaurants and a growing interest in diverse international flavors.
Japan
Japanese consumers value high-quality, authentic, and umami-rich table sauces, with soy-based products holding a strong position. The country's food safety standards are rigorous, influencing ingredient selection and processing techniques. Cities like Tokyo and Osaka are key consumption centers, where specialized fermentation techniques drive product differentiation and premiumization.
Table Sauce Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the competitive structure of the table sauce market. This tiered landscape includes large multinational food conglomerates and niche artisanal producers, each vying for consumer attention. Archetypes include global brand custodians, regional flavor specialists, and ingredient-focused innovators seeking differentiation. Dominant competitive moves involve extensive distribution network expansion and strategic portfolio diversification to capture varied consumer segments and usage occasions.
Global brand custodians, such as Unilever, leverage extensive distribution and brand recognition across multiple product categories, serving both retail and food service channels. McCormick & Company exemplifies a strategic focus on regional flavor preferences and R&D-driven innovation, particularly in integrating spices and seasonings into new sauce formulations. Kikkoman Corporation maintains its market position through deep specialization in soy-based sauces, capitalizing on proprietary fermentation expertise and a strong global presence within that specific condiment segment. These companies represent different strategies for market penetration and sustained leadership.
| Leading Market Players |
|---|
| McCormick & Company |
| Kikkoman Corporation |
| Unilever |
| Dr. Oetker |
| Del Monte Foods |
| The Kraft Heinz Company |
| Conagra Brands |
| Lee Kum Kee |
| Nestle |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements for key agricultural inputs like tomatoes and chili peppers lock in supply access and provide price visibility for major table sauce manufacturers. This contract-based approach mitigates volatility in commodity markets.
Pricing Analysis
Contract-based long-term offtake agreements for key ingredients such as soybeans and spices underpin pricing for large-scale table sauce production. Price differentiation stems from quality grade, including organic certifications, and brand premium for established names like Kikkoman. Pricing pressure intensifies due to input cost volatility for agricultural commodities and compliance costs associated with sodium reduction mandates. Quick-service restaurants exhibit the highest price sensitivity for bulk sauces, while consumers of specialty hot sauces demonstrate lower elasticity.
Supply Chain Analysis
Inventory management for table sauces balances shelf-stability with fresh ingredient sourcing, impacting lead times for new product launches. Geographic supply concentration for raw materials centers on India for chili peppers, China for soybeans, and the United States for tomatoes. The supply chain relies on consistent access to these agricultural commodities and packaging components like glass bottles. Commodity price volatility for these inputs represents a significant structural risk for manufacturers. Distribution runs through extensive retail networks and specialized food service channels globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The table sauce market presents a high-growth disruption, driven by precision fermentation technology enabling novel flavor compounds and cleaner formulations. This innovation reshapes product development cycles for both established and emerging brands.
For Market Incumbents: Secure experienced flavor scientists and invest heavily in R&D to address the sensory science talent gap. Expand global R&D networks, as McCormick & Company does, to develop low-sodium and clean-label formulations that meet diverse regional preferences. Leverage existing distribution channel control to counter emerging direct-to-consumer brands. Strategic acquisitions of specialty hot sauce makers can also mitigate the threat from flavor experimentation trends.
For New Entrants and Emerging Players: Organic certification fast-tracks enable smaller brands to establish credibility in health-conscious segments. Target white space in plant-based food pairings by developing sauces specifically for meat alternatives, addressing a high-growth adjacent category. Focus on Eastern European markets where Western-style condiments are underpenetrated. Utilize direct-to-consumer e-commerce platforms to build brand loyalty and bypass traditional retail gatekeepers, as seen with specialty hot sauce makers.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized flavor innovators with proprietary fermentation expertise and robust clean-label formulation capabilities. These assets offer long-term viability within the table sauce market over a five-to-ten year window, given sustained consumer demand for authentic and healthy options. Acquisition targets should prioritize companies demonstrating agility in meeting evolving regulatory standards from agencies like the FDA and EFSA. The signal to watch is the increasing adoption rates of precision fermentation technology for flavor customization.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D Investment in Low-Sodium Formulations | Addresses FDA sodium reduction targets and consumer health preferences, enhancing product appeal for quick-service restaurants. |
| Expansion of Direct-to-Consumer Channels | Bypasses traditional retail, fostering brand loyalty for artisanal sauce makers and reaching specific consumer niches. |
| Strategic Acquisition of Specialty Brands | Integrates niche flavor expertise and unique product lines, strengthening market position against emerging competitors. |
| Development for Plant-Based Food Pairings | Captures growth in the adjacent plant-based food category, serving consumers seeking enhanced flavor and texture. |
| Global Sourcing for Traceable Ingredients | Ensures compliance with clean-label regulations from EFSA and FSSAI, supporting market access and consumer trust. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to build a robust market perspective. Primary interviews with flavor scientists, R&D directors, procurement managers, and quick-service restaurant operators provided qualitative insights. Secondary validation drew from FDA filings, EFSA reports, FSSAI standards, and relevant trade association publications. This approach employed both bottom-up and top-down triangulation to ensure data accuracy.
The analysis window for this study spans nine years, employing a rigorous analytical framework to project market trajectories. Segmentation dimensions modeled include product type, form, application, and packaging type, alongside regional consumer preferences. Compound annual growth rates were derived through a multi-variable regression model, integrating historical market performance. Commodity price trends and evolving regulatory compliance costs served as critical forecast inputs.
Decision-makers should treat outputs as directional under current consumer behavior and regulatory enforcement assumptions; material deviation would warrant model refresh. Forecasts reflect these base assumptions, but unforeseen geopolitical events or new foodborne illness outbreaks could significantly alter market dynamics. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Global Hot Pot Condiment Market
Condiments & Sauces
Soy-Based Sauce Market
Condiments & Sauces
Hot Sauce Powder Market
Condiments & Sauces
Oriental Sauce Market
Condiments & Sauces
Barbeque Sauce Market
Condiments & Sauces
Europe Hot Sauce Market
Condiments & Sauces
Vinegar and Vinaigrette Market
Condiments & Sauces
Sauce Market
Condiments & Sauces
Prepared Mustard Market
Condiments & Sauces
Dipping Sauces Market
Condiments & Sauces
Vegan Fish Sauce Market
Condiments & Sauces
North America Mayonnaise Market
Condiments & Sauces
Sweet and Savory Spread Market
Condiments & Sauces
Salad Dressings Market
Condiments & Sauces
Sour Dressings Market
Condiments & Sauces
UK Prepared Mustard Market