
 Vegan Fish Sauce Market | 2026-2036
Vegan Fish Sauce Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Fish Sauce Market Analytics
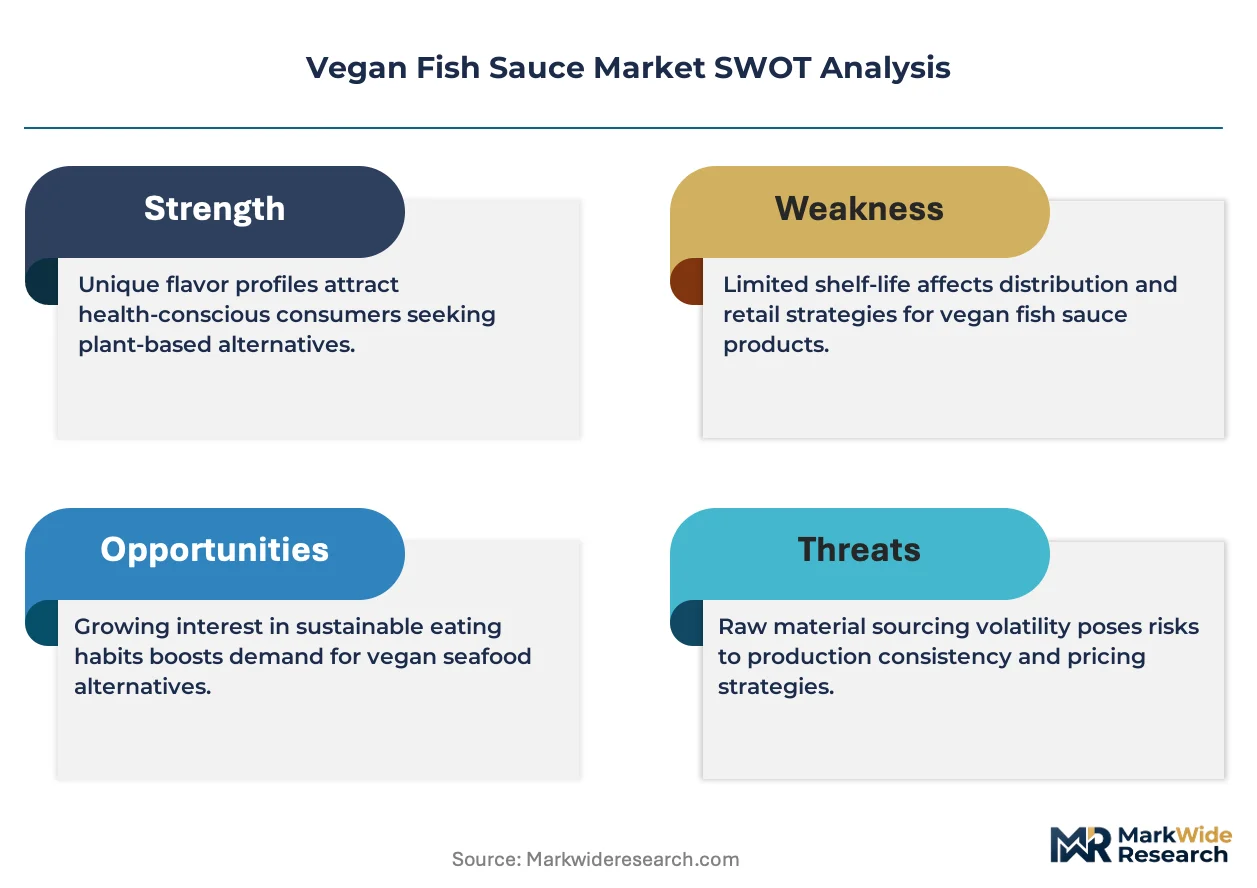
Southeast Asian coconut aminos producers is restructuring supply chains to secure fermented base material volumes amid raw ingredient competition. 24Vegan Fish Sauce leverages direct plantation partnerships in Vietnam to sustain batch consistency. Tofuna Fysh anchors its position through R&D intensity in cold-brewed seaweed extraction. Ocean's Halo competes via broad retail distribution across North American natural grocery channels.
Vegan fish sauce denotes a plant-derived liquid condiment replicating the savory-umami profile of traditional fermented anchovy sauce, typically manufactured through controlled enzymatic hydrolysis of coconut sap, soy protein, or kombu kelp at salinities between 15% and 25%. The product serves commercial kitchens and packaged food manufacturers requiring allergen-free, shellfish-free alternatives for Southeast Asian, Korean, and Japanese recipe formulations. Liquid formulations dominate current volume owing to established pouring formats and recipe interchangeability, while powder and concentrate variants capture faster growth as food manufacturers seek reduced-weight inputs for instant noodle and snack seasoning sachets. Seaweed extract and mushroom extract ingredient types command premium positioning due to longer fermentation cycles and cleaner label credentials.
EU REACH and EFSA frameworks govern additive thresholds and novel food status for fermented plant proteins entering European commerce, while FDA GRAS self-affirmation shapes US market entry pathways for coconut amino acid bases. Thailand's FDA-equivalent national food regulator enforces fish sauce identity standards that plant-based alternatives must navigate through distinct labeling protocols. Stakeholders must monitor evolving codex alignment between ASEAN member states on fermented condiment nomenclature to anticipate harmonized trade barriers or accelerated regional clearance.
Market Dynamics
Thailand's metropolitan foodservice corridors are accelerating adoption of plant-based umami condiments as consumer dietary preferences shift toward allergen-free alternatives, forcing fermentation facilities to restructure supply chains for raw ingredient security.
Growth Catalysts
- EU REACH compliance:Tightening ingredient disclosure requirements for fermented alternatives is pushing manufacturers toward cleaner label credentials and premium positioning in European retail channels.
- Instant noodle manufacturers:Powder and concentrate variants capture faster growth as food manufacturers seek reduced-weight inputs for seasoning sachets across Southeast Asian packaged food production.
- Seaweed extract fermentation:Longer fermentation cycles and cleaner label credentials command premium positioning in Korean and Japanese recipe formulations requiring shellfish-free alternatives.
Market Restraints
- Coconut sap supply volatility:Raw ingredient competition from coconut sugar and beverage producers creates batch consistency challenges for enzymatic hydrolysis operations.
- Thailand FDA-equivalent standards:National fish sauce identity standards force plant-based alternatives into distinct labeling protocols that complicate shelf placement.
- Soy protein substitution threat:Lower-cost conventional soy sauce alternatives limit price elasticity in mass-market foodservice segments.
Strategic Opportunities
- North American natural grocery channels:Broad retail distribution networks remain underpenetrated for liquid format premium positioning.
- Cold-brewed extraction technology:Convergence with controlled enzymatic hydrolysis enables shorter production cycles without sacrificing umami depth.
- ASEAN codex harmonization:Evolving alignment between member states on fermented condiment nomenclature could accelerate regional clearance pathways.
Industry Challenges
- Fermentation microbiology expertise:Talent scarcity in controlled enzymatic hydrolysis at 15-25% salinity creates quality control bottlenecks.
- Novel food status timelines:EFSA framework compliance for fermented plant proteins extends European market entry durations.
- Legacy recipe reformulation:Commercial kitchens require technical support for 1:1 substitution ratios in established Southeast Asian formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Fish Sauce Market |
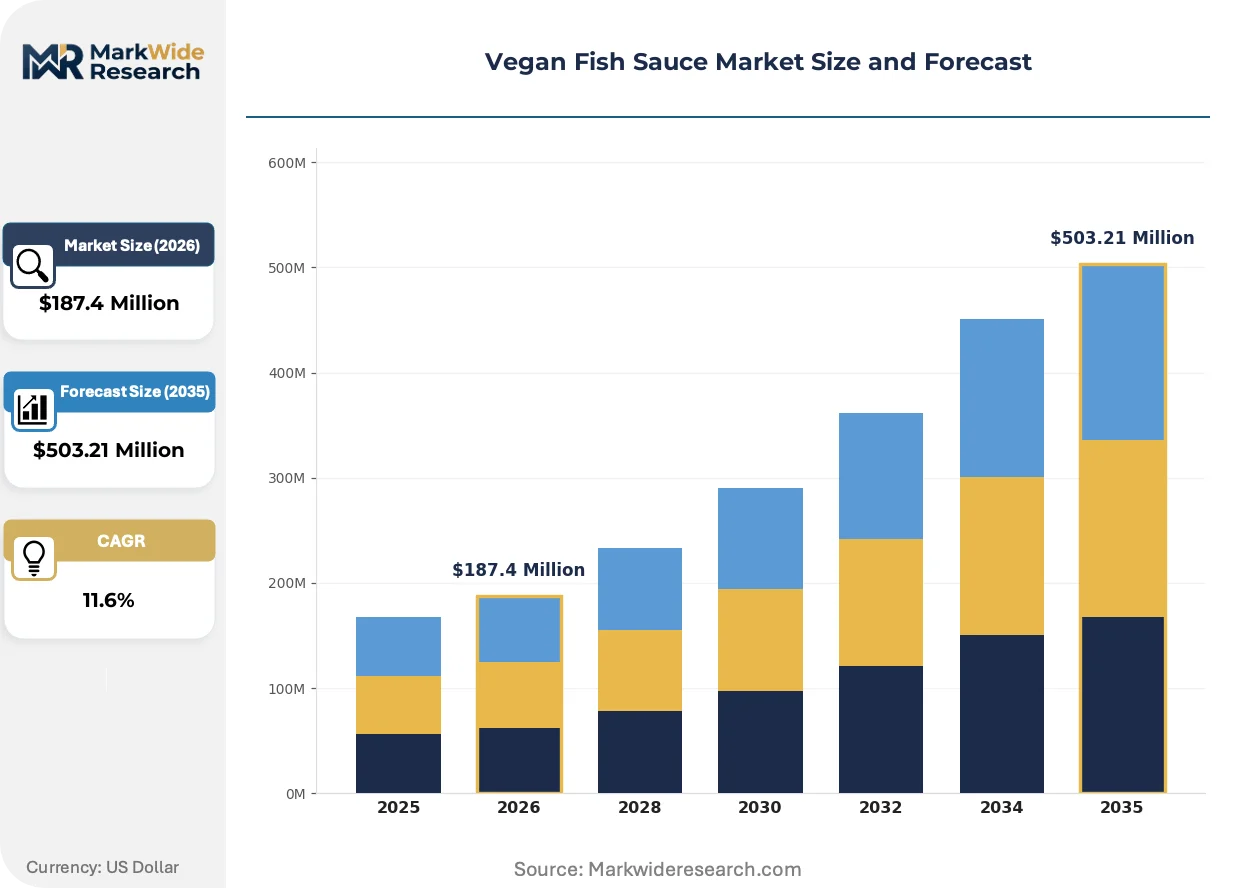
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Paste, Concentrate Ingredient Type: Coconut Aminos, Soy Sauce, Seaweed Extract, Mushroom Extract Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops End User: Households, Restaurants, Food Manufacturers, Catering Services |
| Companies Covered | 24Vegan Fish Sauce, Tofuna Fysh, Ocean's Halo, Top Kitchen, Au Lac, Thai Kitchen, Tân Tân, The Korean Vegan, Coconut Secret, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Fish Sauce Market Evolving Landscape
Fermentation technology advances and regulatory disclosure mandates are compressing production timelines while expanding addressable end-use segments beyond traditional foodservice.
Cold-brewed seaweed extraction is converging with precision enzymatic hydrolysis to reduce fermentation cycle duration from months to weeks. Korean instant noodle manufacturers are adopting these accelerated processes at pilot scale. The technology is converging with traditional umami chemistry to enable cost parity with conventional anchovy-based alternatives.
REACH authorization requirements for novel fermented protein additives are tightening contaminant threshold documentation across EU member states. Manufacturers must now submit full toxicological profiles for coconut amino acid bases prior to commercial distribution. German and French retail channels are responding by consolidating supplier bases toward pre-certified fermentation partners.
Direct plantation partnerships are replacing spot-market procurement for coconut sap and kombu kelp inputs. Vietnamese agricultural cooperatives are signing multi-year offtake agreements with processing facilities. This consolidation is most visible in Thailand's metropolitan foodservice corridors, where batch traceability has become a non-negotiable procurement criterion for restaurant chains.
Vegan Fish Sauce Market Segmentation
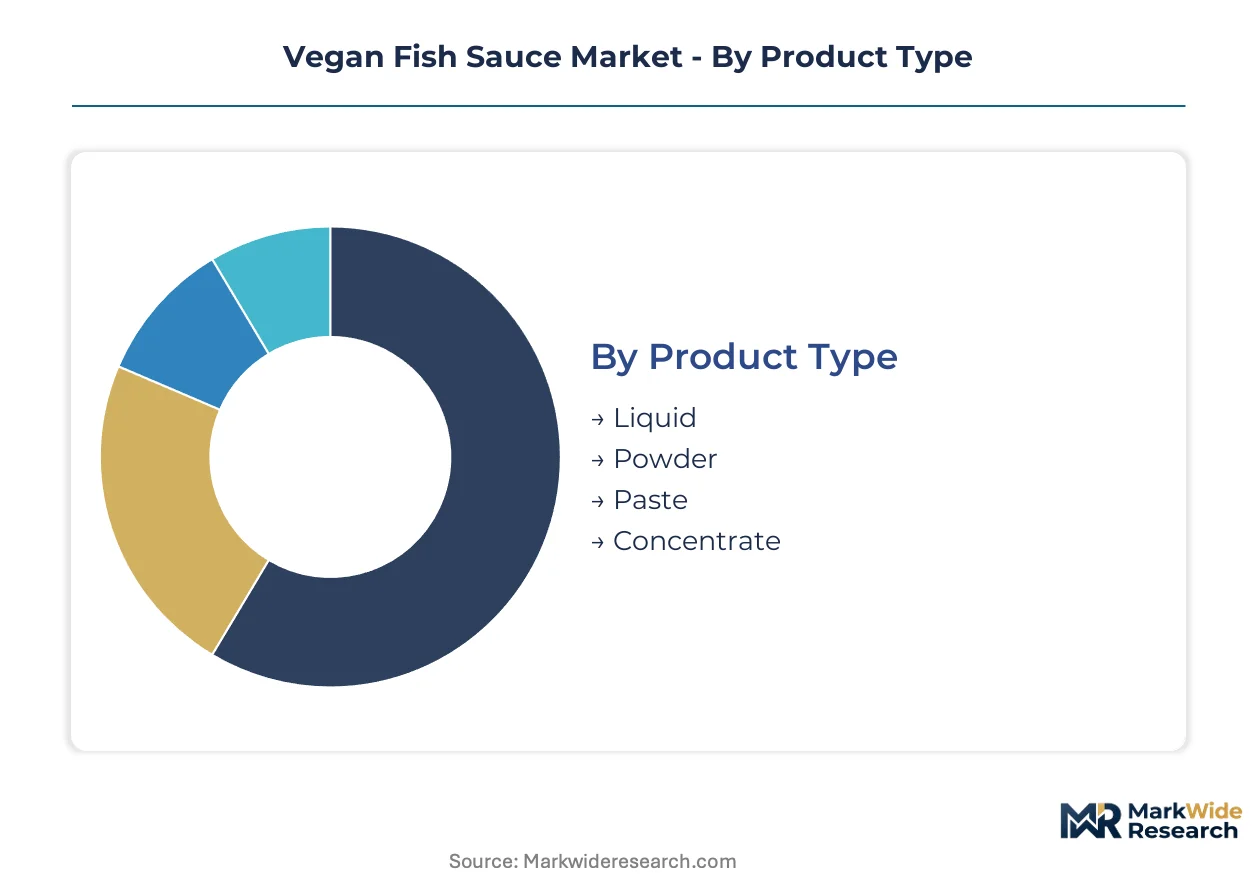
Vegan fish sauce manufacturers navigate divergent regulatory pathways depending on segment classification. Fermented liquid formats face stricter EFSA novel food scrutiny than dried concentrates, while seaweed-derived ingredients trigger distinct REACH authorization thresholds compared to soy protein bases.
Product Type:
Liquid formats carry the heaviest certification burden under FDA GRAS self-affirmation and EFSA novel food frameworks, while powders and concentrates benefit from simplified additive thresholds in ASEAN markets.
- Liquid:Dominant format manufactured through controlled enzymatic hydrolysis at 15-25% salinity. Restaurant chains across Thailand's metropolitan foodservice corridors specify liquid for 1:1 substitution in legacy recipes, though batch consistency challenges persist from coconut sap supply volatility.
- Powder:Reduced-weight input capturing food manufacturer demand for instant noodle seasoning sachets. Korean manufacturers pilot accelerated cold-brewed extraction to compress production timelines from months to weeks without sacrificing umami depth.
- Paste:Thickened variant serving niche catering applications requiring controlled portioning.
- Concentrate:Dilutable format targeting industrial food production with freight cost advantages over liquid equivalents.
Liquid sits at the top of the volume ranking, with Powder climbing the fastest.
Ingredient Type:
Cost tiers separate commodity soy bases from premium-positioned seaweed and mushroom extracts, with fermentation cycle duration driving margin differentiation.
- Coconut Aminos:Fermented coconut sap base competing directly with coconut sugar and beverage producers for raw material access. Vietnamese agricultural cooperatives are signing multi-year offtake agreements to secure supply.
- Soy Sauce:Lower-cost conventional alternative limiting price elasticity in mass-market foodservice segments.
- Seaweed Extract:Longer fermentation cycles and cleaner label credentials command premium positioning in Korean and Japanese recipe formulations requiring shellfish-free alternatives. German and French retail channels consolidate supplier bases toward pre-certified fermentation partners.
- Mushroom Extract:Shiitake-derived umami base gaining traction among allergen-free positioning strategies.
Coconut Aminos dominates current volume, with Seaweed Extract expanding most quickly.
Distribution Channel:
Customer type determines channel priority, with food manufacturers bypassing retail entirely while households fragment across digital and physical touchpoints.
- Online Retail:Direct-to-consumer growth vector for specialty formats with extended shelf stability.
- Supermarkets:Mass-market penetration point for liquid formats in North American natural grocery channels.
- Health Food Stores:Premium positioning venue for certified organic and non-GMO variants.
- Specialty Shops:Asian grocery and gourmet retailers serving recipe-authenticity demand.
Supermarkets hold the volume lead, with Online Retail gaining share fastest.
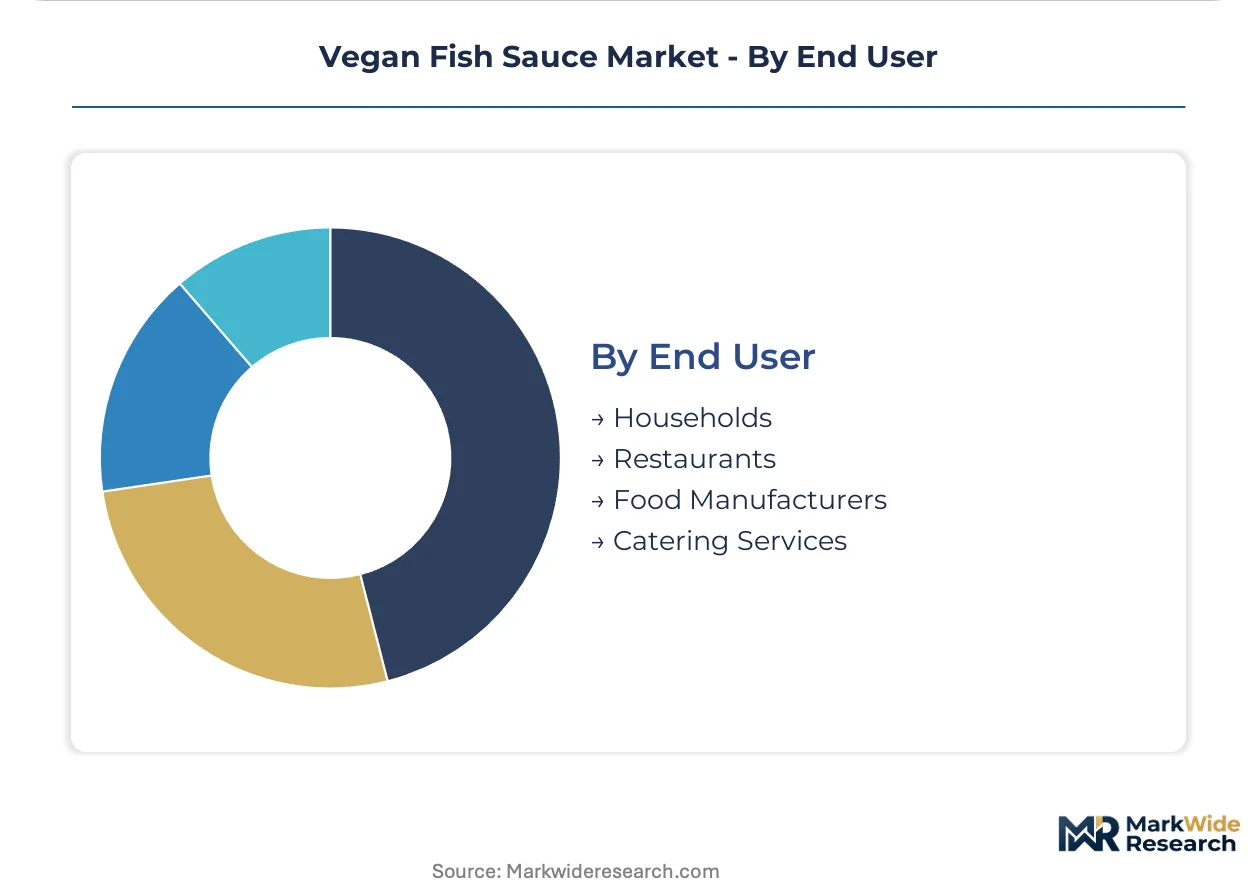
End User:
Application maturity varies sharply, with commercial kitchens requiring technical substitution support while packaged food manufacturers prioritize input standardization.
- Households:Recipe experimentation segment sensitive to price positioning against conventional fish sauce.
- Restaurants:Thailand's metropolitan foodservice corridors accelerate adoption as batch traceability becomes non-negotiable procurement criteria.
- Food Manufacturers:Instant noodle and snack seasoning producers drive concentrate and powder demand for reduced-weight inputs.
- Catering Services:Bulk procurement segment favoring paste and concentrate formats for portion control.
Restaurants anchor current volume, with Food Manufacturers on the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production capacity toward jurisdictions with streamlined novel-food approval pathways, as EFSA timelines stretch European entry while ASEAN markets accelerate clearance. Manufacturers now site fermentation facilities based on cost-of-compliance differentials rather than raw material proximity alone.
United States
Natural grocery channel expansion drives demand for certified organic variants. FDA GRAS self-affirmation enables faster market entry than European equivalents, attracting coconut amino processors seeking retail shelf placement. California's Bay Area food-tech cluster hosts multiple pilot facilities testing cold-brewed extraction scale-up.
Thailand
Metropolitan foodservice corridors in Bangkok and Chiang Mai accelerate plant-based umami adoption as restaurant chains enforce batch-traceability procurement rules. The national food regulator maintains strict fish-sauce identity standards forcing distinct labeling for fermented alternatives. Fermentation facilities concentrate in the Central Plains agricultural zone near coconut sap plantations.
Germany
REACH authorization requirements for novel fermented proteins tighten contaminant documentation, consolidating retail channels toward pre-certified suppliers. EFSA novel food scrutiny extends approval timelines beyond eighteen months for enzymatic hydrolysis products. Hamburg and Berlin serve as import hubs for Southeast Asian liquid formats seeking EU market testing.
Vietnam
Direct plantation partnerships secure coconut sap supply chains against competition from sugar and beverage producers. Agricultural cooperatives in the Mekong Delta sign multi-year offtake agreements with processing facilities. Ho Chi Minh City's food manufacturing zone anchors regional export capacity for powder and concentrate variants.
South Korea
Instant noodle manufacturers pilot accelerated fermentation cycles for seasoning sachet inputs. MFDS novel food frameworks govern additive thresholds for kombu kelp-derived bases. Busan's port infrastructure handles bulk concentrate imports for redistribution to Gyeonggi-do packaged food production clusters.
Vegan Fish Sauce Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue certified-organic and cold-extraction premium positioning. The vendor base stratifies across three tiers: plantation-integrated fermenters with captive raw material supply, technology-licensed specialists leveraging accelerated enzymatic processes, and retail-brand distributors without production assets. Dominant competitive moves include backward integration into coconut sap cultivation and strategic partnerships with instant noodle manufacturers for powder-format offtake agreements.
Within the plantation-integrated tier, 24Vegan Fish Sauce exemplifies direct agricultural partnership models, while Tofuna Fysh occupies a position emphasizing R&D intensity in extraction methodology. Ocean's Halo anchors the retail-distribution archetype through natural grocery channel breadth. These three represent the strategic positioning spectrum: upstream supply control, process technology differentiation, and downstream market access.
| Leading Market Players |
|---|
| 24Vegan Fish Sauce |
| Tofuna Fysh |
| Ocean's Halo |
| Top Kitchen |
| Au Lac |
| Thai Kitchen |
| Tân Tân |
| The Korean Vegan |
| Coconut Secret |
| Others |
Value Network & Pricing Analysis
Coconut sap spot-market volatility cascades through enzymatic hydrolysis operations into three distinct pricing tiers: plantation-integrated fermenters command premium positioning through captive supply, technology-licensed specialists occupy mid-market bands via accelerated extraction efficiencies, and retail-brand distributors compete on volume at compressed margins.
Pricing Analysis
Distributor margin layers absorb the steepest compression as coconut sap competition intensifies from beverage and sugar producers. Three-tier pricing structure across premium, standard, and economy levels separates seaweed-extract fermentation with EFSA pre-certification from soy-protein commodity bases and private-label alternatives. Pricing pressure stems from raw material spot-market instability rather than demand contraction. Food manufacturers exhibit highest price sensitivity due to input-cost pass-through constraints, while certified-organic retail channels maintain lowest elasticity through brand-loyalty premiums.
Supply Chain Analysis
Dual-sourcing requirements now dominate procurement protocols as restaurant chains in Thailand's metropolitan corridors mandate batch-traceability documentation from multiple fermentation partners. Supply concentrates in Vietnam, Thailand, and Indonesia for coconut sap and kombu kelp feedstocks. Controlled enzymatic hydrolysis operations rest on coconut sap, soy protein isolate, and seaweed extract inputs. Single-source vulnerability persists in cold-brewed extraction enzyme suppliers. Distribution runs through plantation-integrated fermenters direct to food manufacturers, bypassing traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vegan fish sauce has entered late-cycle quality phase as Thailand's metropolitan foodservice corridors shift procurement criteria toward batch-traceability certification and fermented-base transparency.
For Market Incumbents: Deploy backward integration into Mekong Delta coconut plantations to neutralize raw material competition from sugar and beverage producers. Anchor market position through multi-year offtake agreements with instant noodle manufacturers seeking powder-format standardization. Counter soy-sauce substitution threats by accelerating EFSA pre-certification timelines for European retail channel consolidation.
For New Entrants and Emerging Players: Natural grocery channel buyers in North American markets present the most penetrable entry vector given underdeveloped certified-organic shelf presence. Target cold-brewed extraction technology licensing as differentiation lever against incumbent fermentation-cycle advantages. Pursue direct-to-foodservice distribution in South Korea's instant noodle manufacturing clusters where accelerated production timelines command premium positioning.
For Investors and Strategic Acquirers: Asymmetric upside sits with plantation-integrated mid-cap specialists possessing captive Vietnamese agricultural cooperative partnerships. Five-to-ten year viability hinges on codex harmonization acceleration across ASEAN member states. Watch EFSA novel-food approval velocity as inflection indicator for European market entry cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coconut Plantations | Vietnamese agricultural cooperatives secure multi-year sap offtake against beverage-producer competition. |
| Cold-Brewed Extraction Scale-Up | California Bay Area pilot facilities compress fermentation cycles from months to weeks. |
| EFSA Pre-Certification Investment | German and French retail channels consolidate supplier bases toward documented toxicological profiles. |
| Powder-Format Manufacturing Expansion | Korean instant noodle manufacturers adopt reduced-weight inputs for seasoning sachet standardization. |
| Direct Plantation Partnership Structuring | Thailand's metropolitan restaurant chains enforce batch-traceability as non-negotiable procurement criterion. |
Research Methodology
Coverage spans Southeast Asia, North America, and Western Europe, with primary inputs from each region combining fermentation facility operators, food manufacturer procurement leads, natural grocery channel buyers, and regulatory affairs specialists with secondary validation through FDA GRAS filings, EFSA novel-food submissions, ASEAN customs trade data, and coconut commodity price indices. Bottom-up volume triangulation against top-down value estimates ensures cross-verification integrity.
Rate-of-change decomposition separates volume expansion from value premium capture across the projection horizon. Segmentation dimensions modeled include product format, ingredient base, distribution channel, and end-user application maturity. CAGRs derive from historical trajectory analysis adjusted for regulatory pathway acceleration and raw material supply elasticity. Forecast inputs incorporate REACH authorization timeline distributions and cold-brewed extraction adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA novel-food approval velocity and ASEAN codex harmonization timing. Deviation in coconut sap commodity pricing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Sauces and Condiments Market
Condiments & Sauces
Tomato Ketchup Market
Condiments & Sauces
Dipping Sauces Market
Condiments & Sauces
Oyster Sauce Market
Condiments & Sauces
Low Fat Pasta Sauce Market
Condiments & Sauces
Sour Dressings Market
Condiments & Sauces
Acciughe Pasta Sauce Market
Condiments & Sauces
Ketchup Concentrates Market
Condiments & Sauces
Sun-Dried Tomato Umami Concentrate Systems Market
Condiments & Sauces
Fat Free Salad Dressings Market
Condiments & Sauces
Asia Pacific Fish Sauce Market
Condiments & Sauces
Salad Dressings Market
Condiments & Sauces
Low Fat Mayo Market
Condiments & Sauces
Curry Cube Market
Condiments & Sauces
Australia and New Zealand Tomato Sauce Market
Condiments & Sauces
Culinary Sauces Market