
 Vegan Sashimi Market | 2026-2036
Vegan Sashimi Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Sashimi Market Analytics
Premium-grade texture fidelity is bifurcating the competitive landscape into artisan-positioned and mass-market tiers. Kuleana leverages advanced extrusion technologies to replicate tuna mouthfeel, while Boldly sustains R&D intensity through dedicated mycelium fermentation labs. Vegan ZeaStar anchors European distribution through controlled retail partnerships with specialty grocers.
Vegan sashimi comprises plant-derived protein matrices, typically konjac root, pea isolate, or cultured fungal mycelium, formulated with algae-derived omega oils and color-stabilized with beet or spirulina extracts to mimic raw fish appearance and nutritional profiles. The product type segment reveals seaweed-based formulations dominating current volume, though jackfruit variants are capturing fastest-growing positioning in Southeast Asian markets. Food service channels command the deepest margin pools, while online retailers experience the steepest volume acceleration among distribution channels.
FDA GRAS self-affirmation and EFSA novel food consultations shape ingredient approval timelines and cross-border market access for mycelium and fermented protein inputs. Japan's Consumer Affairs Agency and South Korea's MFDS enforce strict allergen labeling and additive thresholds that determine formulation viability in high-potential East Asian markets. Stakeholders must monitor evolving precision-fermentation regulatory classifications, as these rulings will determine which production technologies achieve scalable commercial clearance.
Market Dynamics
Precision fermentation infrastructure is concentrating production capability among capitalized operators, while novel food approval pathways at FDA and EFSA determine which ingredient technologies achieve cross-border commercial clearance.
Growth Catalysts
- FDA GRAS Self-Affirmation:Accelerated ingredient approvals reduce time-to-market for mycelium-based protein matrices, enabling faster product iteration cycles.
- Flexitarian Demographics:Expanding consumer bases in Japan and South Korea seek plant-based alternatives that preserve traditional sashimi ritual and presentation.
- Algae Omega Cultivation:Controlled-environment lipid production secures supply chains for nutritional profile matching without wild fisheries dependency.
Market Restraints
- Konjac Root Price Volatility:Weather-sensitive harvests in Southeast Asian growing regions create input cost instability for texture-formulation suppliers.
- East Asian Regulatory Friction:Japan's Consumer Affairs Agency and South Korea's MFDS enforce additive thresholds that disqualify several Western-approved color stabilizers.
- Animal Protein Substitution:Lab-cultured seafood from precision aquaculture presents a competing alternative with identical sensory profiles.
Strategic Opportunities
- German Retail Partnerships:Controlled distribution through specialty grocers anchors European market penetration before mass-channel expansion.
- Extrusion-Convergence:Advanced shear-cell technology combined with mycelium fermentation enables texture fidelity previously requiring artisan production.
- EU Green Deal Procurement:Public sector foodservice mandates for sustainable sourcing create institutional demand pools in Nordic countries.
Industry Challenges
- Cross-Jurisdictional Labeling:Divergent allergen disclosure requirements between FDA, EFSA, and Japan's Consumer Affairs Agency complicate unified packaging strategies.
- Fermentation Scale-Up Capex:Commercial bioreactor capacity requires eight-figure capital deployment before unit economics reach competitive parity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Sashimi Market |
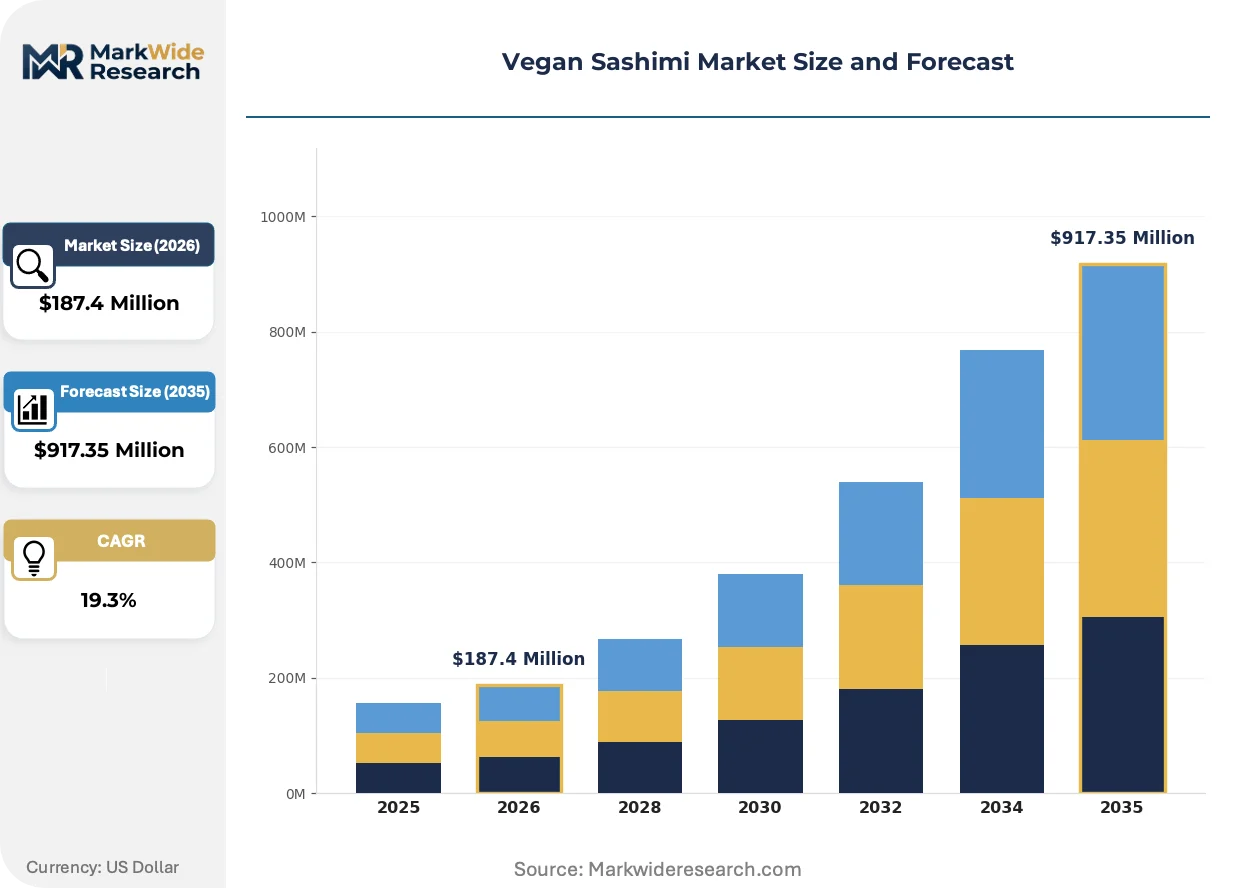
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $917.35 Million |
| CAGR (2026 – 2036) | 19.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seaweed, Tofu, Jackfruit, Mushroom Preparation Method: Raw, Smoked, Marinated, Grilled Distribution Channel: Supermarkets, Online Retailers, Food Service, Specialty Stores Customer Type: Restaurants, Retail Consumers, Catering Services, Meal Kit Providers |
| Companies Covered | GTFO It's Vegan, Vegan ZeaStar, Boldly, GreatFoods, Veggie Yatra, GreenSaffron, Kuleana, Ocean Hugger Foods, IMA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Sashimi Market Evolving Landscape
Texture replication technologies are bifurcating competitive tiers between artisan-positioned and mass-market offerings, while regulatory clarity on novel proteins determines which production methods achieve scalable clearance.
Shear-cell extrusion is fragmenting the texture-formation landscape by enabling industrial-scale mouthfeel replication previously confined to small-batch production. Premium restaurant chains in North America adopt these formulations for core menu placement, compressing the capability gap between artisan and commodity suppliers.
EFSA novel food consultations are compressing approval timelines for fermented protein inputs, creating regulatory momentum for mycelium-based alternatives. European operators respond by prioritizing formulation strategies that preemptively address EFSA safety documentation requirements.
Foodservice procurement is rotating toward specification-driven contracts that bind suppliers to texture consistency benchmarks and algae-oil provenance documentation. Japanese premium dining establishments lead this shift, unbundling traditional supply relationships in favor of certified ingredient traceability.
Vegan Sashimi Market Segmentation
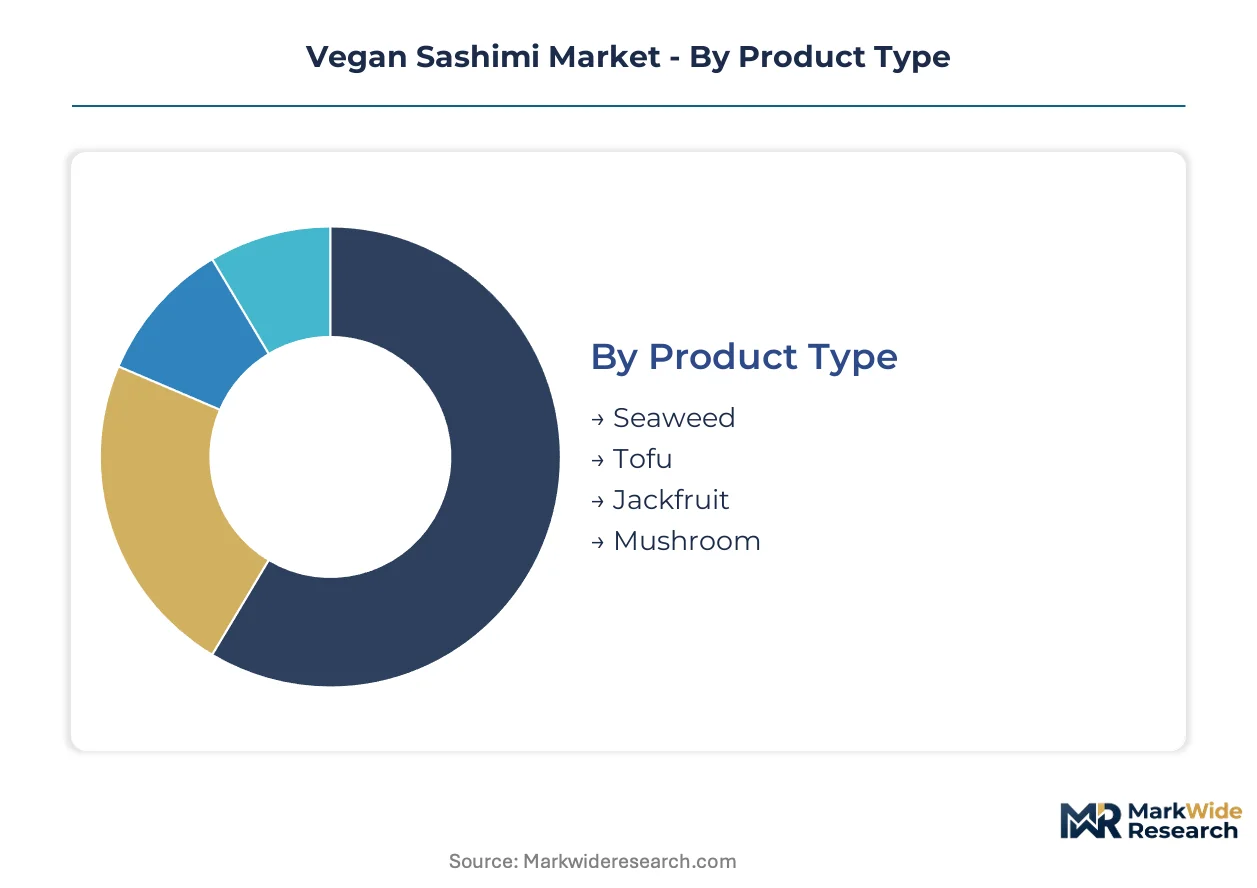
Segmentation in vegan sashimi reveals how texture technology and distribution infrastructure determine commercial viability across price tiers. Each category exposes distinct supply chain requirements and regulatory exposure that shape supplier positioning.
Product Type:
Seaweed-based formulations anchor domestic production in Japan and South Korea, while jackfruit variants drive export-led growth into Southeast Asian markets.
- Seaweed:Konjac and carrageenan matrices deliver translucent, gelatinous mouthfeel with algae-derived omega oils integrated for nutritional parity. Japanese premium dining establishments specify this format for traditional presentation rituals, though EFSA novel food consultations delay European rollout for certain red algae extracts.
- Jackfruit:Neutral-flavored fibrous flesh accepts marine flavoring and color stabilization more readily than protein-dense alternatives. Demand concentrates in Bangkok, Singapore, and Jakarta foodservice channels where tropical ingredient familiarity reduces consumer education costs.
- Tofu:Soy protein isolates provide cost-efficient base material for mass-market retail SKUs in North American supermarkets.
- Mushroom:Mycelium fermentation yields dense, umami-rich textures currently limited to artisan-positioned restaurant supply.
Seaweed commands the established base. The steepest expansion runs through jackfruit.
Preparation Method:
Raw preparations concentrate margin capture in high-end foodservice, while smoked and marinated variants extend shelf life for retail channel economics.
- Raw:Unprocessed plant matrices require precise temperature control and rapid turnover to maintain texture integrity. Tokyo and Osaka omakase restaurants specify raw-format products with documented algae-oil provenance, binding suppliers to 48-hour delivery windows.
- Smoked:Cold-smoking with applewood or hickory masks base ingredient off-notes while extending refrigerated shelf life to 21 days. German and Dutch retail chains prioritize smoked variants for deli counter placement.
- Marinated:Soy-citrus or miso-based marinades penetrate konjac matrices for flavor depth suited to bento and grab-and-go applications.
- Grilled:Brief high-heat exposure creates surface char that replicates tataki preparation styles in casual dining formats.
Raw formats retain the premium price position. Marinated products are climbing the fastest as meal kit providers scale procurement.
Distribution Channel:
Food service channels demand specification-driven contracts with texture benchmarks, while online retailers prioritize shelf-stable formats that tolerate ambient shipping.
- Food Service:Direct supplier relationships with premium restaurant chains and institutional caterers specify shear-cell extrusion consistency and lot-level traceability. South Korean hotel and corporate dining procurement teams now require third-party texture analysis certificates.
- Online Retailers:Frozen and modified-atmosphere packaging enables nationwide reach without cold-chain density requirements. Japanese e-commerce platforms report strongest velocity for multi-format variety packs targeting home sushi preparation.
- Supermarkets:Refrigerated case placement in North American and European chains depends on slotting fee negotiations and weekly promotional support.
- Specialty Stores:Asian grocery formats in Los Angeles, Vancouver, and London provide targeted access to culturally primed consumer bases.
Food service commands the established base. Online retailers show the steepest volume acceleration trajectory.
Customer Type:
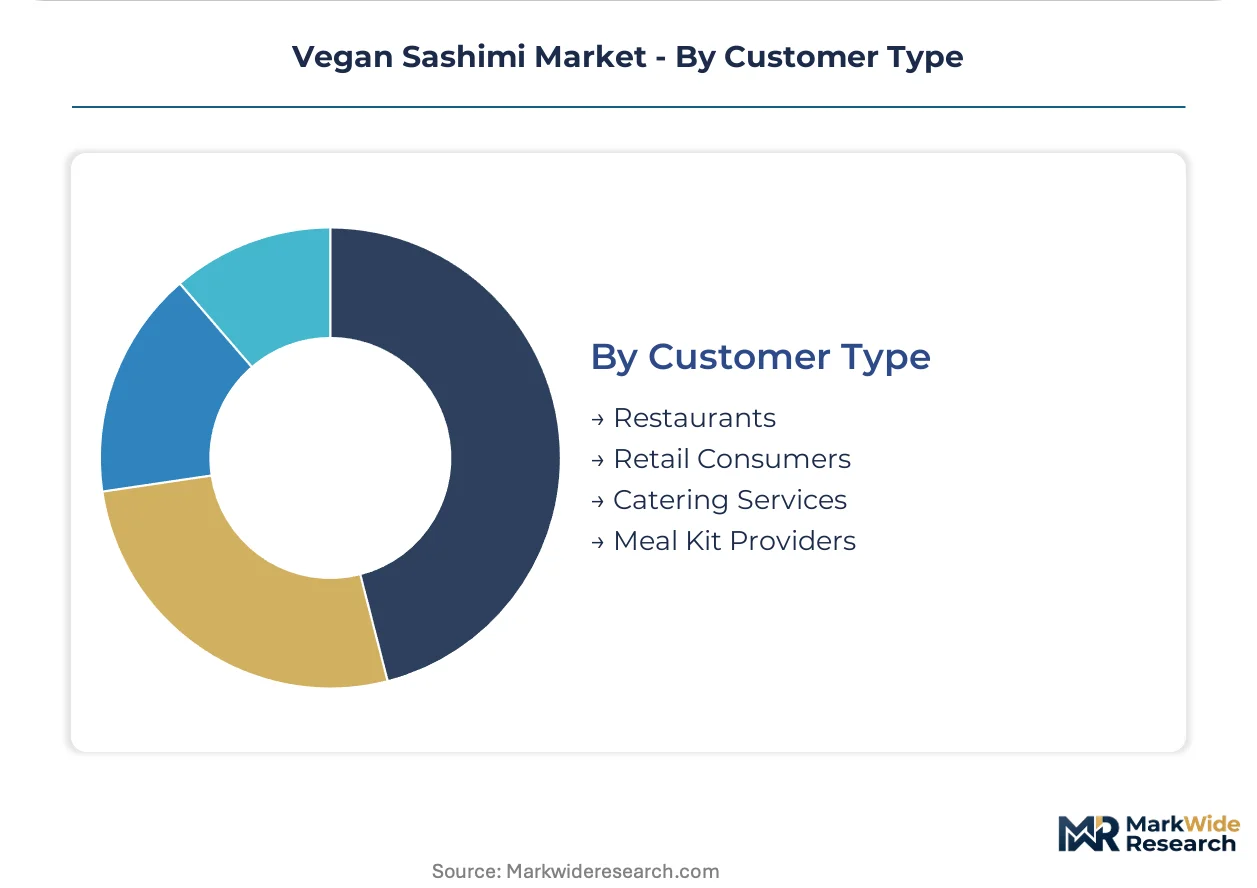
Restaurant procurement emphasizes presentation-grade appearance and portion consistency, while meal kit providers prioritize format flexibility and extended freshness windows.
- Restaurants:Fine-dining and fast-casual operators specify color-stabilized products that maintain visual appeal under display case lighting. New York and San Francisco restaurant groups now require mycelium-based alternatives for sustainability narrative alignment.
- Meal Kit Providers:Pre-portioned, sauce-paired formats reduce home preparation complexity. European subscription services drive formulation requests for 7-day refrigerated shelf life.
- Retail Consumers:Direct purchase behavior favors recognizable ingredient declarations and allergen-free positioning.
- Catering Services:Volume-scale events demand cost-optimized formats with ambient holding tolerance.
Restaurants command the established base. Meal kit providers represent the fastest-expanding demand pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in vegan sashimi tilt toward import dependence in Western markets against export-led manufacturing clusters in East Asia. Japan and South Korea maintain production surpluses while Germany and the United States absorb inbound shipments of precision-fermented proteins and konjac-based formulations.
Japan
Tokyo and Osaka omakase restaurants drive premium-grade demand for algae-oil-infused konjac matrices that replicate traditional tuna mouthfeel. The Consumer Affairs Agency enforces strict additive thresholds that disqualify several Western-approved color stabilizers, forcing reformulation for market entry. Kanto and Kansai industrial corridors host specialized extrusion facilities serving domestic foodservice channels.
South Korea
Seoul Capital Area hotel and corporate dining procurement teams now require third-party texture analysis certificates for plant-based raw fish alternatives. The MFDS mandates comprehensive allergen labeling that exceeds FDA disclosure requirements, creating compliance friction for imported products. Busan-Ulsan manufacturing zones concentrate mycelium fermentation capacity for regional export.
Germany
Berlin and Hamburg specialty grocers anchor European distribution through controlled retail partnerships that prioritize smoked variants for deli counter placement. EFSA novel food consultations compress approval timelines for fermented protein inputs, accelerating product registration. Bavaria and North Rhine-Westphalia host precision-fermentation infrastructure investments from capitalized operators.
United States
New York and San Francisco restaurant groups require mycelium-based alternatives for sustainability narrative alignment in fine-dining procurement. FDA GRAS self-affirmation pathways reduce time-to-market for novel protein matrices, enabling faster product iteration cycles. California and Pacific Northwest clusters concentrate shear-cell extrusion R&D facilities.
United Kingdom
London and Southeast Asian grocery formats in Greater London provide targeted access to culturally primed consumer bases familiar with sashimi preparation rituals. EFSA regulatory alignment post-Brexit maintains streamlined novel food consultation procedures for mycelium-based ingredients. Midlands distribution hubs handle refrigerated case placement negotiations for supermarket chains.
Vegan Sashimi Market Competitive Landscape
Listed leaders compete with private specialists across fermentation technology and extrusion capability. The vendor base stratifies between capitalized precision-fermentation operators and artisan-positioned texture specialists. Three archetypes dominate: mycelium fermentation labs, advanced extrusion technologists, and controlled-distribution retail partners. Competitive moves concentrate on capacity expansion in bioreactor infrastructure and strategic partnerships with premium restaurant chains.
Within the fermentation-specialist tier, Boldly and Kuleana exemplify divergent technology bets, while Vegan ZeaStar anchors European market penetration through retail channel control. GTFO It's Vegan occupies a position in direct-to-consumer distribution archetypes. Ocean Hugger Foods and IMA sit within the texture-replication specialist category. GreatFoods, Veggie Yatra, and GreenSaffron represent regional formulation players with geographic concentration in specific national markets.
| Leading Market Players |
|---|
| GTFO It's Vegan |
| Vegan ZeaStar |
| Boldly |
| GreatFoods |
| Veggie Yatra |
| GreenSaffron |
| Kuleana |
| Ocean Hugger Foods |
| IMA |
| Others |
Value Network & Pricing Analysis
Algae-derived omega oil substitution for wild-caught fish lipids simultaneously reshapes supply geography toward controlled-environment cultivation facilities and compresses pricing economics by decoupling finished product costs from volatile fisheries commodity cycles. This input transition concentrates margin pressure on legacy konjac-root suppliers while rewarding vertically integrated operators with captive lipid production.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in vegan sashimi procurement. Price differentiation hinges on texture fidelity certification and algae-oil provenance documentation, with Japanese omakase restaurants showing least sensitivity and North American retail consumers most responsive to shelf-price positioning. Pricing pressure stems from konjac root harvest volatility in Southeast Asian growing regions. Foodservice channels absorb premium positioning while supermarket SKUs face margin compression from slotting fee structures.
Supply Chain Analysis
Japan and South Korea anchor precision-fermentation infrastructure for mycelium-based protein matrices, while Indonesia and Thailand concentrate konjac root cultivation and jackfruit processing. Raw material dependencies include algae-derived lipids, pea protein isolates, and fungal fermentation substrates. Supply chain risk centers on single-source vulnerability for red algae extracts subject to EFSA novel food consultation delays. Distribution runs through specification-driven foodservice contracts in East Asia and controlled retail partnerships in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists in vegan sashimi as texture technology bifurcation creates distinct artisan and mass-market niches. Flexitarian demand expansion across East Asian markets rewards specialized positioning over broad commodity plays.
For Market Incumbents: Fortify bioreactor capacity in Busan-Ulsan and Kanto-Kansai corridors to preempt fermentation scale-up bottlenecks. Secure backward integration into algae cultivation to defend margin position against lipid supply volatility. Prioritize EFSA pre-submission documentation for mycelium inputs ahead of regulatory clarity windows. For New Entrants and Emerging Players: Differentiate on jackfruit-based formulations for Southeast Asian foodservice channels where tropical ingredient familiarity reduces consumer education costs. Target German specialty grocer partnerships as the most penetrable European entry point. Pursue direct-to-online retail distribution to bypass slotting fee barriers in North American supermarket channels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision-fermentation operators holding commercial bioreactor capacity but lacking brand distribution. Five-to-ten year viability favors mycelium-technology platforms over commodity extrusion plays. Monitor EFSA novel food consultation outcomes as the critical inflection signal for scalable commercial clearance.| Strategic Initiative | Industry Significance |
|---|---|
| Precision-Fermentation Scale-Up | Commercial bioreactor deployment in South Korea and Japan secures mycelium supply for texture-fidelity applications. |
| Algae Cultivation Integration | Controlled-environment lipid production decouples omega oil supply from wild fisheries commodity volatility. |
| EFSA Pre-Submission Investment | Novel food documentation preparation accelerates European market entry timelines for fermented protein inputs. |
| Shear-Cell Extrusion Licensing | Technology transfer agreements enable industrial-scale mouthfeel replication previously confined to artisan production. |
| Retail Partnership Structuring | Controlled distribution through German specialty grocers anchors European market penetration before mass-channel expansion. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with foodservice procurement directors, precision-fermentation R&D leads, specialty grocer category managers, and regulatory affairs specialists at novel food ingredient firms. Secondary validation drew from FDA GRAS notifications, EFSA novel food consultation registers, Japanese Consumer Affairs Agency additive thresholds, South Korean MFDS allergen labeling directives, and customs trade flow data. Bottom-up volume modeling and top-down value triangulation were cross-referenced across these sources.
Across the analysis window, forecasts applied a segmented analytical framework incorporating product type matrices, preparation method economics, distribution channel velocity, and customer procurement specifications. CAGRs were derived from regression analysis against historical adoption curves and regulatory approval timelines. Industry-specific inputs included precision-fermentation capacity buildout schedules and East Asian flexitarian demographic expansion rates.
Material uncertainties — regulatory reclassification of precision-fermentation outputs, konjac root harvest disruption, and lab-cultured seafood competitive entry — sit outside the modeled envelope. Forecasts reflect assumptions about EFSA consultation timelines and East Asian consumer acceptance trajectories. Recalibration cycles align with material shifts in novel protein regulatory classifications and precision-fermentation infrastructure deployment milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Vegan Casing Market
Alternative Food Sources
Fish Meal Alternative Market
Alternative Food Sources
Vegetable Waste Products Market
Alternative Food Sources
Global Konjac Glucomannan Market
Alternative Food Sources
Global Algae Protein Market
Alternative Food Sources
Europe Algae Protein Market
Alternative Food Sources
Konjac Market
Alternative Food Sources
Meat Alternative Market
Alternative Food Sources
Europe Duckweed Protein Market
Alternative Food Sources
North America Edible Insects Market
Alternative Food Sources
Mycoprotein Products Market
Alternative Food Sources
United States Hemp Protein Market
Alternative Food Sources
Europe Emergency Food Market
Alternative Food Sources
Flaxseed Based Egg Replacement Market
Alternative Food Sources
Microalgae Based Products Market
Alternative Food Sources
Edible Packaging Market