
 Single Cell Oil Market | 2026-2036
Single Cell Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Single Cell Oil Market Analytics
EU Novel Food regulations is recalibrating the cost-of-entry calculus for new microbial oil entrants, forcing extensive safety dossiers and toxicity studies before market authorization. DSM Nutritional Products leverages its decades-long strain development pipeline to sustain leadership in high-purity omega-3 algal oils. Corbion NV anchors European supply through proprietary fermentation platforms optimized for docosahexaenoic acid output. Cellana Inc. competes on photosynthetic cultivation economics, differentiating its Hawaii-based open-pond systems from conventional heterotrophic fermentation.
Single cell oil comprises lipid biomass harvested from unicellular organisms—algae, fungi, bacteria, and yeast—typically containing triglyceride profiles exceeding 20% dry cell weight, with fatty acid chain lengths ranging from C14 to C22 including omega-3 polyunsaturates. These oils serve as drop-in replacements for fish-derived lipids in dietary supplements, infant formula, and aquaculture feed, eliminating marine contaminant accumulation and supply volatility. Microbial oil dominates current production volumes due to established heterotrophic fermentation infrastructure and substrate flexibility, while algal oil captures premium positioning in cosmetics and clean-label nutraceuticals where phototrophic provenance commands price premiums. Yeast oil remains the fastest-expanding category as strain engineering advances boost lipid titers toward commercial parity with established alternatives.
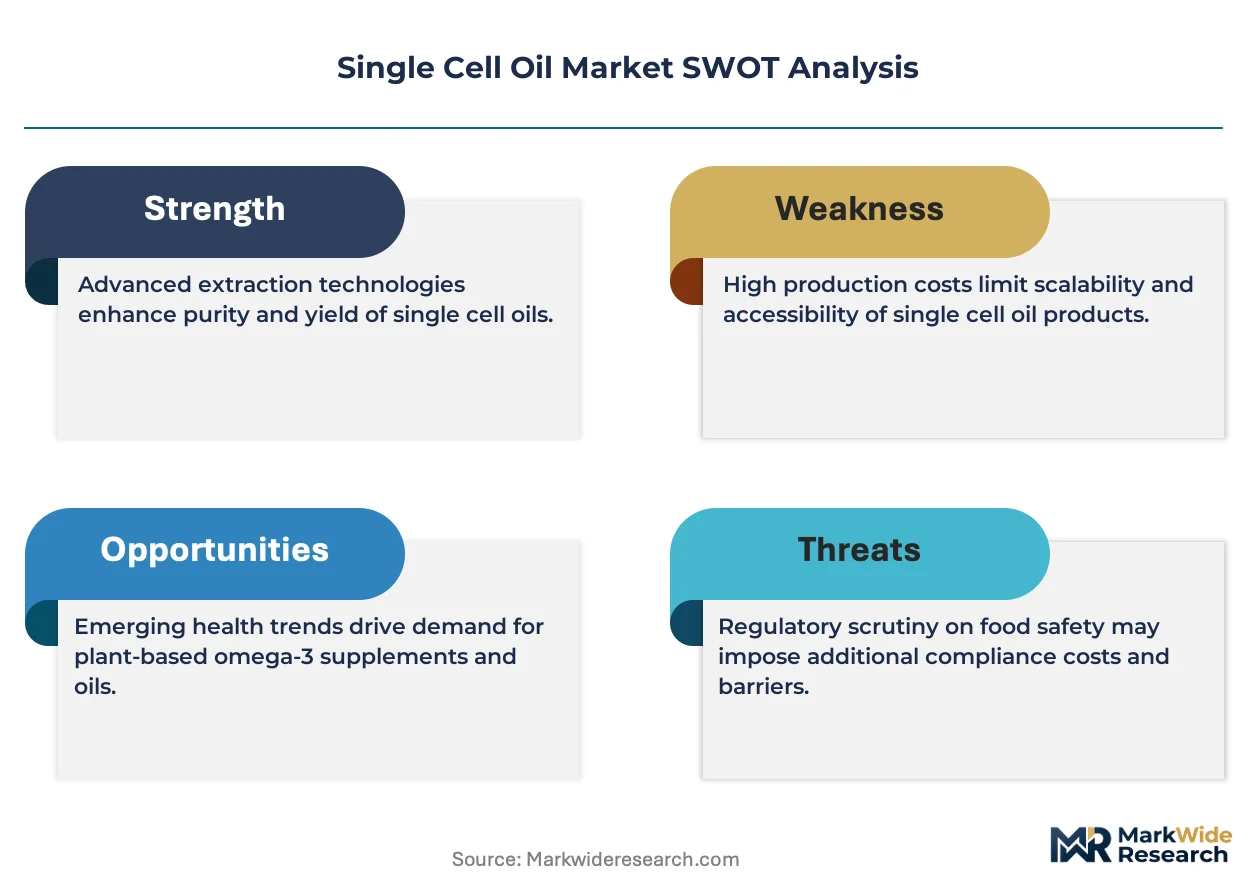
The European Food Safety Authority mandates novel food pre-market authorization under Regulation 2015/2283, creating compliance barriers that favor incumbents with established dossiers and toxicological data. The FDA's GRAS self-affirmation pathway offers faster US market access but demands rigorous expert panel reviews for new microbial strains, while China's National Health Commission maintains separate new food raw material registration requirements. Stakeholders must monitor regulatory divergence between jurisdictions, as asynchronous approval timelines for genetically optimized strains threaten to fragment global product rollouts and strand R&D investments in non-harmonized frameworks.
Market Dynamics
Heterotrophic fermentation infrastructure concentration in Germany and the Netherlands is locking in supply-side advantages for established microbial oil producers while phototrophic challengers struggle to achieve comparable unit economics at commercial scale.
Growth Catalysts
- REACH-compliant substrate sourcing:EU chemical safety frameworks are accelerating investment in closed-loop fermentation systems that eliminate palm oil and other contested feedstocks from supply chains.
- Aquaculture feed formulation:Salmon and shrimp producers in Norway and Scotland are substituting fishmeal with algal DHA to reduce marine contaminant exposure and secure supply continuity.
- Infant formula fortification:Premium nutrition brands are mandating vegetarian-certified omega-3 sources to capture clean-label positioning in German and French retail channels.
Market Restraints
- Glucose feedstock volatility:Corn-derived sugar prices fluctuate with US agricultural commodity cycles, compressing margins for yeast oil fermenters without long-term supply contracts.
- Fermentation capacity concentration:Commercial-scale bioreactor availability clusters around Rotterdam-Antwerp and Hamburg port corridors, creating bottleneck risks for new entrants.
- Phototrophic yield ceilings:Open-pond algae systems face fundamental biological productivity limits that heterotrophic platforms have already transcended through strain engineering.
Strategic Opportunities
- Polish biotech corridor development:Lower-cost fermentation infrastructure in Wrocław and Poznań offers expansion capacity for producers seeking alternatives to saturated Benelux hubs.
- Cosmeceutical squalane applications:Yeast-derived squalane is penetrating premium skincare formulations as shark liver oil substitutes face sustainability scrutiny.
- EU Green Deal bioeconomy funding:Horizon Europe and national recovery programs are channeling capital into microbial lipid platforms that demonstrate carbon-negative production pathways.
Industry Challenges
- Novel food dossier compilation:EFSA pre-market authorization requires 12-18 month toxicological study timelines that strain R&D budgets for strain-optimized products.
- Downstream processing capex:Cell disruption and lipid extraction equipment represents 40-50% of facility investment, favoring producers with existing chemical engineering capabilities.
- Cross-jurisdiction regulatory fragmentation:Asynchronous approval timelines between EFSA, FDA, and China's NHC threaten to strand products in non-harmonized compliance frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Cell Oil Market |
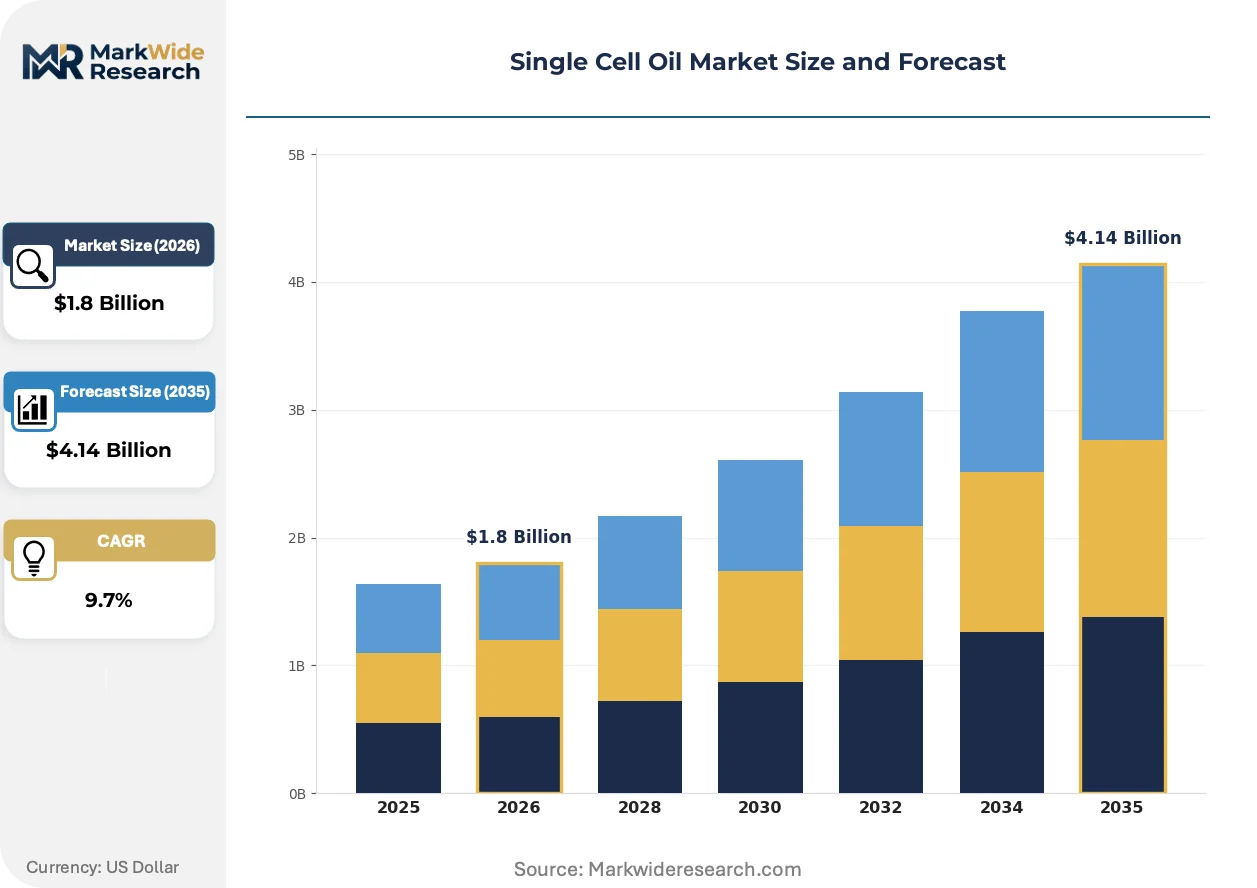
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Algal Oil, Fungal Oil, Microbial Oil, Yeast Oil Application: Cosmetics, Nutraceuticals, Food Industry, Biofuels End User: Food Manufacturers, Personal Care Brands, Pharmaceutical Companies, Bioenergy Firms Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | DSM Nutritional Products, BASF SE, Corbion NV, Cargill Incorporated, Royal DSM NV, Cellana Inc., Goerlich Pharma GmbH, DIC Corporation, Alltech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Cell Oil Market Evolving Landscape
Strain engineering breakthroughs and regulatory pressure on marine sourcing are compressing technology adoption cycles across microbial lipid platforms, with heterotrophic systems consolidating production advantages.
Continuous fermentation technology is overtaking batch processing as the dominant production paradigm for high-titer yeast oil. Industrial biotechnology firms in Bavaria and North Rhine-Westphalia are retrofitting existing pharmaceutical fermentation assets for lipid production, achieving 30-40% throughput improvements. This operational shift is compressing capital recovery timelines and enabling price parity with refined fish oil in bulk feed applications.
EFSA's tightened novel food evaluation protocols under Regulation 2015/2283 are extending authorization timelines for genetically optimized strains. The industrial consequence is a competitive moat widening around incumbents with established dossiers and toxicological datasets. Algal oil producers with phototrophic heritage strains are responding by emphasizing non-GMO positioning to bypass regulatory scrutiny entirely.
Formulation houses are consolidating supplier relationships around vertically integrated fermentation partners who control strain IP, substrate sourcing, and extraction capabilities. Long-term offtake agreements are displacing spot market purchasing in infant formula and aquaculture feed channels. This consolidation pattern is most visible in the Netherlands, where DSM and Corbion have captured multi-year contracts with major European nutrition brands.
Single Cell Oil Market Segmentation
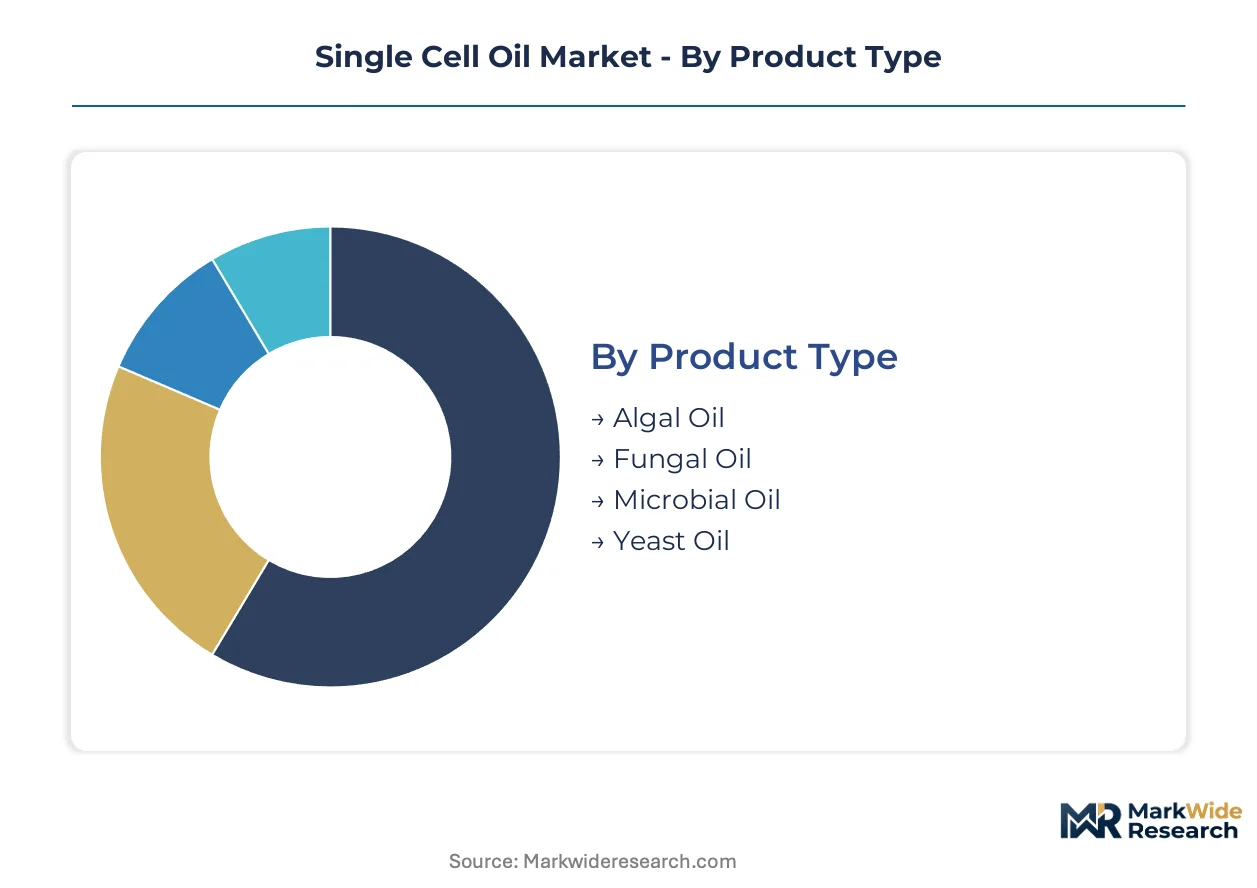
Segmentation in single cell oil markets maps directly to regulatory burden intensity and substrate sourcing complexity. Each product type carries distinct EFSA novel food dossier requirements, while application channels determine REACH compliance depth and customer certification standards.
Product Type:
EFSA novel food authorization timelines vary sharply across microbial platforms, with phototrophic strains facing shorter toxicology pathways than genetically optimized heterotrophic alternatives.
- Algal Oil:Phototrophic cultivation yields DHA and EPA profiles exceeding 35% lipid content in open-pond or closed photobioreactor systems. Infant formula manufacturers in Germany and France prioritize algal oil for vegetarian-certified omega-3 positioning, though batch-to-batch consistency constraints limit aquaculture feed penetration.
- Yeast Oil:Heterotrophic fermentation of engineered Saccharomyces cerevisiae strains achieves lipid titers above 80 grams per liter in continuous bioreactor operations. Norwegian salmon feed compounders are switching to yeast-derived DHA to eliminate marine contaminant accumulation and secure supply continuity against fishery volatility.
- Fungal Oil:Mortierella alpina fermentation produces arachidonic acid for infant nutrition applications with established GRAS status in US markets.
- Microbial Oil:Bacterial lipid platforms utilizing engineered E. coli or cyanobacteria remain pre-commercial for bulk applications.
Microbial oil sits at the top of the volume ranking, with yeast oil climbing the fastest.
Application:
Cost tier differentiation separates premium-positioned channels from commodity bulk applications, with certification depth determining margin capture.
- Nutraceuticals:Dietary supplement brands demand third-party tested algal DHA with contaminant-free certifications. German pharmacy chains and US direct-to-consumer subscription models concentrate demand for high-purity omega-3 capsules.
- Food Industry:Infant formula fortification requires vegetarian-certified lipid sources with full supply chain traceability. Major European nutrition brands now mandate microbial oil exclusively for clean-label positioning in retail channels.
- Cosmetics:Yeast-derived squalane penetrates premium skincare as shark liver oil substitutes face sustainability scrutiny.
- Biofuels:Microbial lipid feedstocks for renewable diesel remain cost-constrained against agricultural oil alternatives.
Nutraceuticals command the highest price realization, with cosmetics expanding most quickly.
End User:
Customer type determines contract structure, with pharmaceutical and food manufacturers locking in multi-year offtake agreements while bioenergy procurement remains spot-market driven.
- Food Manufacturers:Infant formula and functional food producers integrate microbial oil into vegetarian-certified product lines. DSM and Corbion have captured long-term supply contracts with major European nutrition brands through integrated strain-to-extraction capabilities.
- Pharmaceutical Companies:Prescription omega-3 drug applications demand pharmaceutical-grade DHA with full GMP compliance and batch documentation.
- Personal Care Brands:Premium skincare formulators specify yeast-derived squalane for sustainability marketing claims.
- Bioenergy Firms:Renewable fuel producers evaluate microbial lipids against waste oil feedstocks on carbon intensity metrics.
Food manufacturers anchor current volume, with personal care brands gaining share fastest.
Distribution Channel:
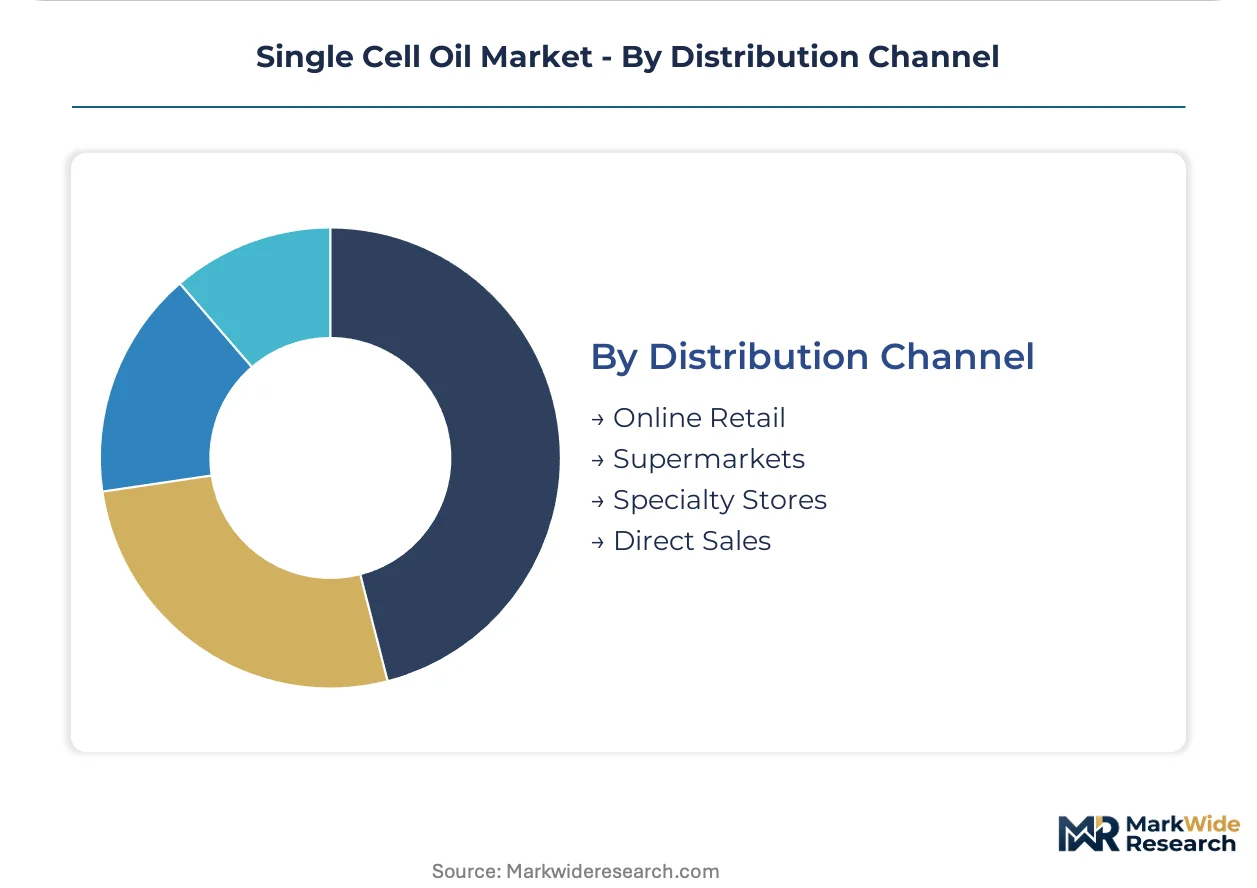
Channel selection reflects customer scale and technical service requirements, with direct sales dominating bulk industrial procurement.
- Direct Sales:Fermentation producers negotiate long-term offtake agreements directly with infant formula and aquaculture feed compounders. Technical service integration including formulation support and regulatory documentation locks in supplier relationships.
- Specialty Stores:Premium nutraceutical brands distribute algal omega-3 through health food retailers with trained staff consultation.
- Online Retail:Direct-to-consumer subscription models capture repeat purchase loyalty for high-margin supplement products.
- Supermarkets:Mass-market penetration remains limited due to price positioning against fish oil alternatives.
Direct sales generate the largest transaction values, with online retail showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Single cell oil production scaled through German fermentation engineering in the 1990s, with heterotrophic platforms establishing the technical foundation that now anchors European supply. Today, manufacturing concentrates in port-adjacent biotech clusters where substrate logistics and regulatory expertise co-locate.
Germany
Infant formula manufacturers in Frankfurt and Munich drive algal DHA procurement for vegetarian-certified product lines. EFSA novel food dossiers under Regulation 2015/2283 require 12-18 month toxicology timelines that favor established players with historical data. The Hamburg-Rotterdam corridor hosts concentrated fermentation capacity serving DSM and Corbion production platforms.
Netherlands
Aquaculture feed compounders in Rotterdam substitute fishmeal with microbial DHA to eliminate marine contaminant accumulation. REACH compliance frameworks mandate closed-loop substrate sourcing that eliminates palm oil from supply chains. The Rotterdam-Antwerp port biotech cluster anchors heterotrophic fermentation infrastructure for European omega-3 output.
United States
Dietary supplement brands in California and New York deploy direct-to-consumer subscription models for algal omega-3 capsules. FDA GRAS self-affirmation offers faster market access than EFSA pathways but demands rigorous expert panel reviews. Hawaii-based open-pond systems compete on photosynthetic cultivation economics against mainland fermentation platforms.
Norway
Salmon producers in Bergen and Trondheim mandate algal DHA inclusion to reduce marine contaminant exposure and secure supply continuity. The country's national food safety regulator enforces strict contaminant thresholds that microbial oils satisfy more reliably than fish-derived alternatives. Stavanger biotech partnerships link aquaculture demand to German fermentation supply.
China
Domestic infant formula brands accelerate vegetarian-certified omega-3 sourcing as clean-label positioning penetrates tier-one retail. The National Health Commission maintains separate new food raw material registration requirements that fragment approval timelines from Western jurisdictions. Qingdao and Shanghai fermentation facilities expand heterotrophic capacity for regional nutraceutical supply.
Single Cell Oil Market Competitive Landscape
The competitive structure tilts toward integrated fermentation specialists with strain IP and extraction capabilities under one roof. Market concentration is moderate, with a tiered hierarchy separating global nutrition conglomerates from regional biotech operators and specialized algae cultivators. Three archetypes dominate: vertically integrated fermentation platforms controlling substrate-to-extraction workflows, phototrophic specialists competing on non-GMO positioning, and contract manufacturers serving private-label nutraceutical brands. Capacity expansion and long-term offtake agreements constitute the primary competitive moves, as formulation houses consolidate supplier relationships around partners who guarantee regulatory documentation and supply continuity.
Among integrated nutrition platforms, DSM Nutritional Products and BASF SE exemplify the strain-to-extraction archetype with decades-long development pipelines. Corbion NV occupies a position within the European fermentation tier, leveraging proprietary platforms for docosahexaenoic acid output. Cellana Inc. represents the phototrophic challenger model, differentiating through open-pond cultivation economics against conventional heterotrophic systems.
| Leading Market Players |
|---|
| DSM Nutritional Products |
| BASF SE |
| Corbion NV |
| Cargill Incorporated |
| Royal DSM NV |
| Cellana Inc. |
| Goerlich Pharma GmbH |
| DIC Corporation |
| Alltech |
| Others |
Value Network & Pricing Analysis
Corn-derived glucose price indices cascade through heterotrophic fermentation economics, compressing margins for yeast oil producers without long-term supply contracts while concentrating pricing power among incumbents with captive substrate sourcing. This commodity linkage stratifies the market into contract-secured volume tiers and spot-market exposed entrants.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, food-certified, and feed-grade levels separates infant formula manufacturers from aquaculture compounders and bulk biofuel buyers. Price differentiation hinges on EFSA novel food dossier completeness and REACH-compliant substrate traceability, with pharmaceutical-grade DHA commanding substantial premia over feed applications. Cost compression in the feed-grade tier is intensifying because glucose feedstock volatility transfers directly from agricultural commodity cycles. Aquaculture feed compounders in Norway exhibit the highest price sensitivity due to fish oil benchmark competition, while infant formula brands absorb premia for vegetarian-certified positioning.
Supply Chain Analysis
Freight costs for substrate delivery to Rotterdam-Antwerp and Hamburg port corridors anchor unit economics, with glucose rail shipments from Benelux agricultural processing hubs representing 15-20% of landed fermentation input costs. Supply concentrates in Germany, the Netherlands, and Norway, with heterotrophic bioreactor capacity clustering around North Sea logistics nodes. The supply chain draws from corn-derived glucose, proprietary engineered yeast strains, and extraction solvent chemicals, creating single-source vulnerability around strain IP holders. Distribution runs through direct long-term offtake agreements for industrial buyers, with specialty nutraceutical channels serving smaller formulation houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Single Cell Oil Market represents a late-cycle quality story where EFSA novel food authorization barriers and REACH compliance depth favor incumbents with established toxicological dossiers. Demand is concentrating toward pharmaceutical-grade and vegetarian-certified specifications that command durable margin premia over commodity feed applications.
For Market Incumbents: Anchor defensible positioning through backward integration into glucose substrate sourcing and expansion of closed-loop fermentation systems that eliminate palm oil dependencies. DSM Nutritional Products and Corbion NV should deepen strain IP moats via continuous fermentation technology deployment in Bavaria and North Rhine-Westphalia, while monitoring phototrophic challengers exploiting non-GMO regulatory bypass strategies. For New Entrants and Emerging Players: Capture white-space opportunity in Polish biotech corridor development around Wrocław and Poznań, where lower-cost fermentation infrastructure offers escape from saturated Benelux capacity constraints. Yeast-derived squalane for premium cosmeceutical applications presents the most penetrable segment given sustainability-driven substitution away from shark liver oil. A go-to-market angle emphasizing carbon-negative production pathways aligns with EU Green Deal bioeconomy funding access. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated fermentation platforms controlling strain development, substrate sourcing, and extraction capabilities under unified ownership. Long-term viability over a multi-year horizon favors producers with established EFSA dossiers and multi-year offtake agreements with European nutrition brands. The signal to watch is regulatory approval timeline convergence between EFSA, FDA, and China's NHC for genetically optimized strains, which would unlock global product rollouts and validate R&D investments currently stranded in non-harmonized frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Fermentation Technology Deployment | Bavarian retrofitting of pharmaceutical assets achieves 30-40% throughput improvements for yeast oil titers. |
| Backward Integration into Substrate Sourcing | Corn-derived glucose supply contracts with US agricultural processors insulate margins from commodity volatility. |
| EFSA Novel Food Dossier Investment | 12-18 month toxicology timelines create competitive moats around established microbial oil incumbents. |
| Polish Biotech Corridor Expansion | Wrocław and Poznań fermentation capacity offers cost-advantaged alternative to Rotterdam-Antwerp bottlenecks. |
| Yeast-Derived Squalane Platform Development | Premium skincare penetration accelerates as shark liver oil substitutes face intensifying sustainability scrutiny. |
Research Methodology
Coverage spans Germany, the Netherlands, Norway, the United States, and China, with primary inputs from each market cluster combined with secondary validation. Fermentation technology directors, infant formula procurement leads, aquaculture feed compounders, EFSA regulatory affairs specialists, and REACH compliance officers provided structured interviews. Secondary sources include EFSA novel food authorization databases, FDA GRAS notification filings, customs trade data for microbial oil shipments, SEC filings from listed nutrition conglomerates, and EU Green Deal bioeconomy funding disclosures. Bottom-up capacity modeling triangulates against top-down demand aggregation from end-use applications.
Granularity-level modeling operates at the intersection of microbial platform type, certification grade tier, and end-use application channel, with geographic production hub as an orthogonal dimension. Volume and value outputs across the projection horizon reflect segment-specific CAGRs derived from capacity expansion announcements, offtake agreement tenors, and regulatory approval pipeline status. Industry-specific forecast inputs include heterotrophic fermentation titer improvement curves and phototrophic algae productivity ceilings from peer-reviewed biotechnology literature.
Underlying measurement precision varies by segment; pharmaceutical-grade and infant formula applications carry tighter precision than emerging biofuel feedstock evaluations due to established demand quantification. Forecasts reflect assumptions regarding regulatory timeline harmonization, substrate cost trajectories, and strain engineering breakthrough rates that could materially revise projections. Stakeholders should weight assumptions against their own operating context and risk tolerance for asynchronous approval frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Africa Fat Replacers Market
Alternative Food Sources
Flaxseed Based Egg Replacement Market
Alternative Food Sources
Flaxseed Based Egg Market
Alternative Food Sources
Global Meal Replacement Shakes Market
Alternative Food Sources
Algal Protein Market
Alternative Food Sources
Mock Meat Market
Alternative Food Sources
Vegan Egg Substitute Market
Alternative Food Sources
Asia-Pacific Meat Substitutes Market
Alternative Food Sources
Monoprotein Market
Alternative Food Sources
Vegan Casing Market
Alternative Food Sources
Hemp-Based Products Market
Alternative Food Sources
Edible Insects Market
Alternative Food Sources
Vegetable Waste Products Market
Alternative Food Sources
North America Insect Protein Market
Alternative Food Sources
Black Soldier Fly (BSF) Market
Alternative Food Sources
Plant-Based Squalene Market