
 Dairy-Free Chocolate Market | 2026-2036
Dairy-Free Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy-Free Chocolate Market Analytics
EU F-Gas Regulation is repositioning refrigeration standards across European chocolate manufacturing, raising capital requirements for temperature-controlled processing. Mondelez International leverages its cocoa sourcing infrastructure to secure supply continuity under tighter environmental rules. Barry Callebaut anchors its competitive stance through specialized dairy-free couverture formulations for industrial bakers. Nestle competes by extending its plant-based R&D pipeline from beverages into confectionery applications.
Dairy-free chocolate denotes confectionery products formulated without milk solids, butterfat, or lactose derivatives, typically employing cocoa mass, cocoa butter, and plant-based milk alternatives such as oat or almond emulsions processed below 50°C to preserve volatile flavor compounds. The primary commercial purpose centers on serving consumers with lactose intolerance, milk protein allergies, or vegan dietary preferences while maintaining mouthfeel parity with conventional chocolate. Dark chocolate occupies the largest volume position due to its naturally minimal dairy content and established consumer familiarity, while oat milk formulations represent the fastest-expanding ingredient source segment as manufacturers resolve viscosity and fat-bloom stability challenges. Health food stores command premium margin pools through curated assortments and educated staff, though supermarkets dominate absolute throughput as shelf space allocation shifts.
The FDA enforces allergen labeling under FALCPA, compelling manufacturers to declare milk protein cross-contact risks even in dairy-free production lines. EFSA evaluates novel food applications for emerging plant proteins, shaping which ingredient sources gain rapid EU market access. REACH compliance adds chemical safety documentation burdens for imported flavoring compounds. Stakeholders must monitor how evolving clean-label standards redefine permissible processing aids and emulsifier classifications.
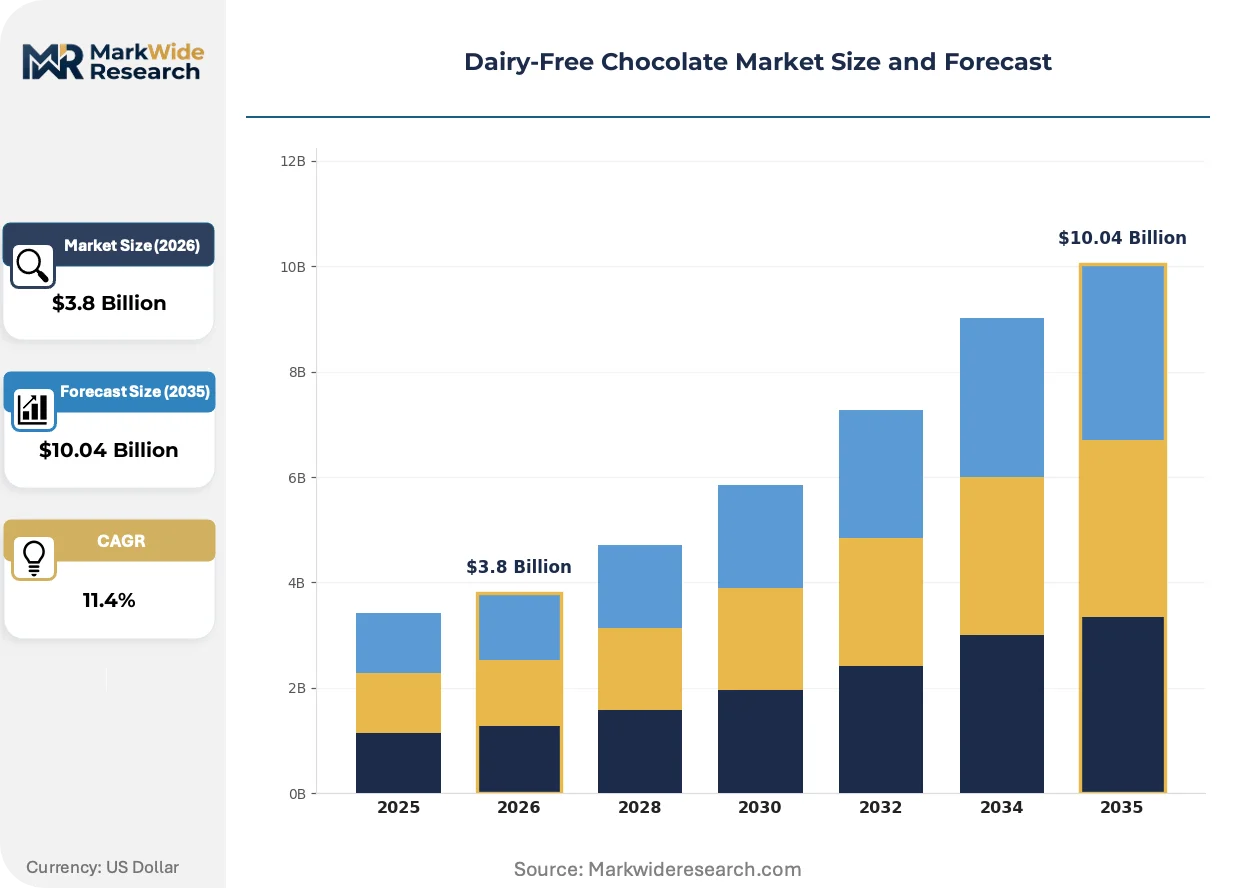
Market Dynamics
Oat milk emulsion technology is compressing formulation timelines while EU F-Gas Regulation forces capital reinvestment in temperature-controlled processing infrastructure across European manufacturing facilities.
Growth Catalysts
- Lactose intolerance prevalence:Germany's dense retail networks for plant-based confectionery demonstrate how concentrated demand clusters accelerate shelf-space allocation in specialty and mainstream channels simultaneously.
- REACH compliance frameworks:Chemical safety documentation requirements for imported flavoring compounds are filtering out undercapitalized suppliers and consolidating import channels toward established compounders with dedicated regulatory affairs functions.
- Clean-label processing aids:Evolving emulsifier classifications under FDA and EFSA evaluations are redirecting R&D expenditure toward lecithin alternatives and enzymatically modified plant proteins with superior declaration profiles.
Market Restraints
- Cocoa butter price volatility:Confectionery margins compress when cocoa futures spike, forcing reformulation toward lower cocoa-butter ratios that compromise snap and mouthfeel parity with conventional chocolate.
- West African supply concentration:Bean sourcing from Côte d'Ivoire and Ghana creates single-origin risk exposure that EUDR deforestation due diligence requirements now amplify through traceability cost burdens.
- Fat-bloom stability limitations:Oat lipid profiles lack the polymorphic crystallization control of milk fat, requiring extended tempering protocols that reduce line throughput and elevate energy costs.
Strategic Opportunities
- Industrial baker channel expansion:Specialized dairy-free couverture formulations for artisan and commercial bakeries represent underpenetrated volume pools outside traditional confectionery retail.
- Health food store premium positioning:Curated assortments with educated staff command margin multiples above supermarket throughput, particularly in urban clusters with high vegan household density.
- Novel protein fast-track approvals:EFSA novel food application pathways for emerging plant proteins offer first-mover advantages to manufacturers submitting comprehensive toxicology dossiers ahead of competitor filings.
Industry Challenges
- Flavor chemist talent scarcity:Formulation expertise in volatile compound preservation below 50°C processing thresholds concentrates among specialists with dairy-alternative experience, constraining scale-up velocity.
- Cross-contact certification timelines:Third-party allergen-free verification for production lines previously handling milk solids requires extended validation periods that delay product launches and tie up working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy-Free Chocolate Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Compound Chocolate Ingredient Source: Coconut Milk, Almond Milk, Soy Milk, Oat Milk Form: Bars, Chips, Baking Drops, Gummy Candies Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Health Food Stores |
| Companies Covered | Mondelez International, The Hershey Company, Nestle, Barry Callebaut, Lindt & Sprüngli, Mars, No Whey Chocolate, Alter Eco, Endangered Species Chocolate, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy-Free Chocolate Market Evolving Landscape
Precision fermentation-derived cocoa butter equivalents are entering commercial scale, while regulatory pressure on carbon-intensive refrigeration accelerates process reengineering across European manufacturing footprints.
Cell-cultured cocoa butter is converging with traditional conching equipment as specialty confectioners in Switzerland and Belgium pilot enzymatic interesterification to achieve lipid profiles indistinguishable from conventional chocolate. Industrial bakers with stringent cost targets represent the fastest-adopting buyer segment, accepting slight viscosity adjustments in exchange for supply security and price stability. This convergence is compressing the premium gap between artisan dairy-free positioning and mass-market accessibility.
EU F-Gas Regulation is mandating phase-down of hydrofluorocarbon refrigerants across chocolate tempering and storage infrastructure, raising capital requirements for temperature-controlled processing lines. Manufacturers with legacy equipment face retrofit-or-replace decisions that favor greenfield facilities with integrated heat recovery systems. German and Belgian production clusters are responding fastest, leveraging existing sustainability investment cycles to absorb compliance costs without margin erosion.
Direct-to-consumer subscription models are displacing traditional wholesale relationships for premium dairy-free chocolate assortments, particularly among urban millennials with established vegan dietary commitments. Specialty retailers with curated discovery formats are capturing loyalty through limited-batch releases unavailable in supermarket channels. This channel rotation is most visible in Berlin, London, and Amsterdam, where plant-based household penetration supports viable subscriber density for recurring revenue models.
Dairy-Free Chocolate Market Segmentation
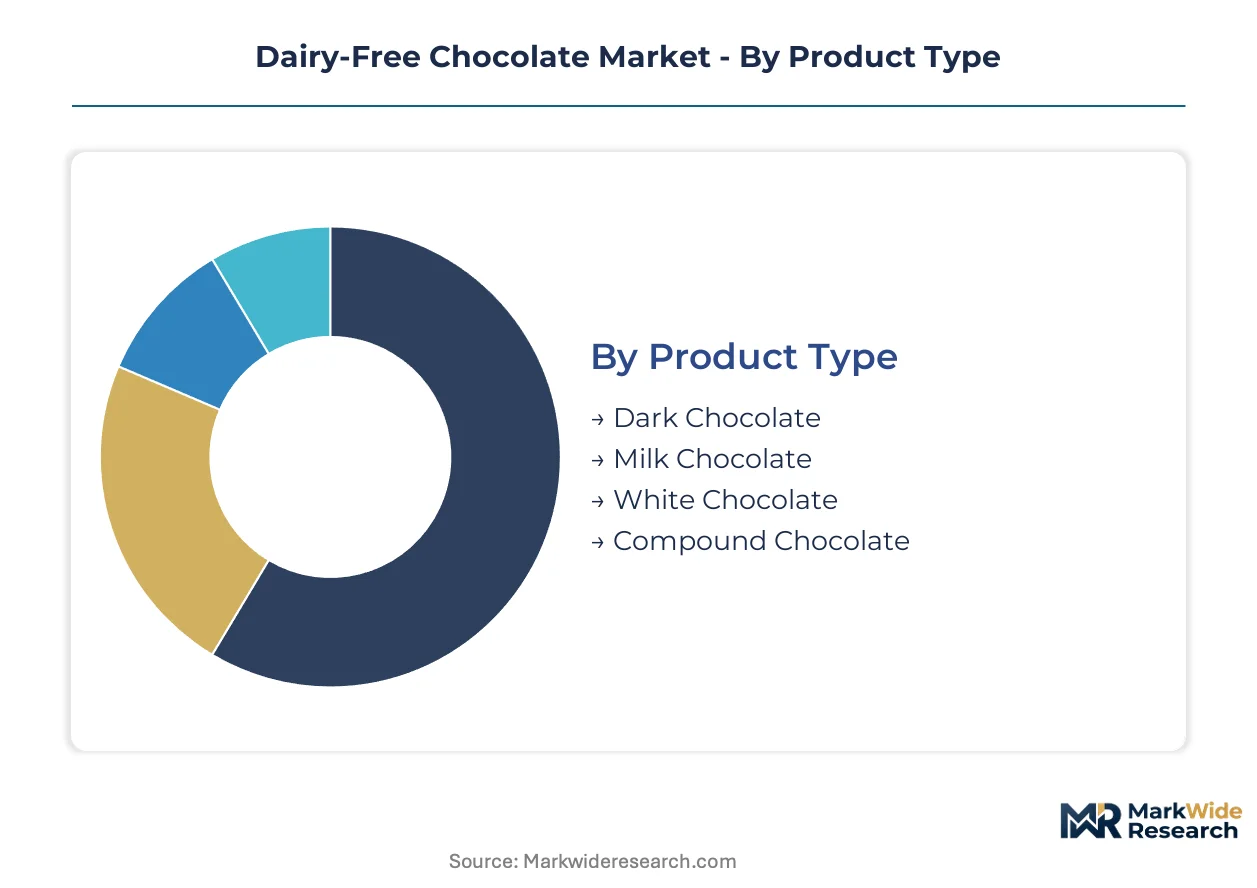
Segmentation in dairy-free chocolate reveals how formulation chemistry and channel access determine margin capture. Manufacturers must align product architecture with the distinct purchasing behaviors of vegan households, allergen-avoidant consumers, and industrial bakeries.
Product Type:
Supply concentration in cocoa butter sourcing favors segments with established processing infrastructure and tempering expertise.
- Dark Chocolate:Cocoa mass and cocoa butter formulations with minimal emulsifier requirements dominate current production volumes. Germany's dense retail networks for plant-based confectionery absorb the majority of dark chocolate throughput, driven by vegan household concentration in Berlin and Munich.
- Milk Chocolate:Plant-based milk emulsions replace dairy solids to achieve creamy mouthfeel parity with conventional chocolate. Oat milk formulations are climbing the fastest as manufacturers resolve viscosity stability challenges in European tempering facilities.
- White Chocolate:Cocoa butter-heavy recipes with elevated fat-bloom sensitivity require specialized tempering protocols.
- Compound Chocolate:Vegetable fat substitutions reduce cocoa butter dependency for cost-sensitive industrial applications.
Dark chocolate absorbs the bulk of installed capacity; oat milk-based milk chocolate is expanding most quickly.
Ingredient Source:
Cost tier differentiation separates premium-positioned nut milks from commodity-scale grain and legume alternatives.
- Oat Milk:Enzymatically treated oat emulsions deliver neutral flavor profiles and superior fat-bloom stability in tempering applications. Belgian and Swiss specialty confectioners are piloting oat-based formulations for industrial baker channels seeking supply security.
- Almond Milk:Protein-rich emulsions contribute textural body but carry tree nut allergen labeling burdens under FDA FALCPA and EFSA frameworks.
- Coconut Milk:High-lauric fat content provides crystallization control but limits clean-label positioning in EU markets.
- Soy Milk:Established supply chains and isoflavone content appeal to legacy vegan consumers, though allergen prevalence constrains school and institutional channels.
Oat milk commands the steepest expansion trajectory; almond milk maintains premium positioning in health food store channels.
Form:
Application-driven demand separates at-home consumption formats from industrial ingredient specifications.
- Bars:Molded tablet formats with snap and gloss requirements dominate retail shelf space allocation. Direct-to-consumer subscription models in London, Amsterdam, and Berlin prioritize limited-batch bar releases for loyalty capture.
- Chips:Calibrated particle size for cookie and muffin industrial production lines. Barry Callebaut's specialized dairy-free couverture formulations target this segment for artisan and commercial bakeries.
- Baking Drops:Heat-stable shapes engineered to retain form through oven cycles.
- Gummy Candies:Pectin or starch-based confections with cocoa butter coating represent adjacent category expansion.
Bars absorb dominant retail throughput; chips are gaining share fastest in industrial procurement.
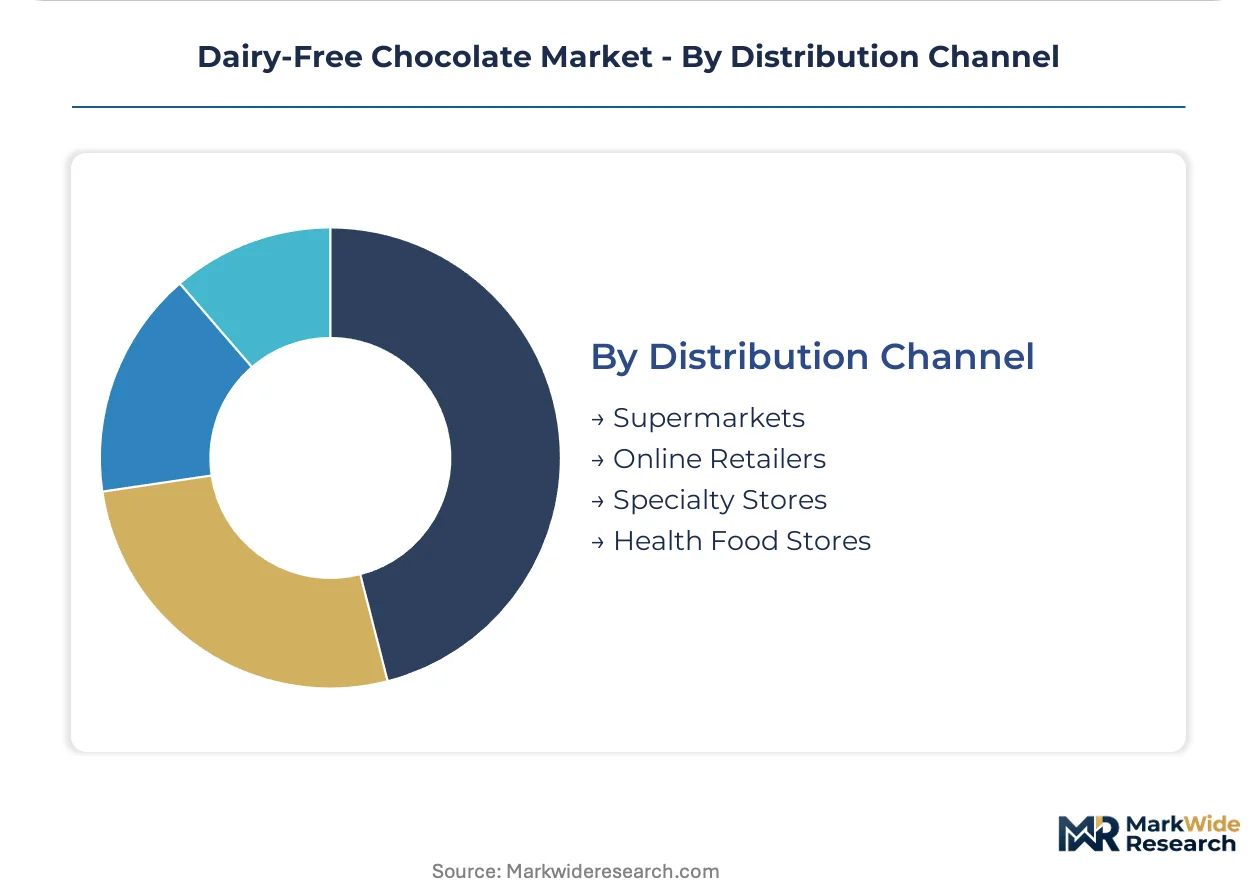
Distribution Channel:
Margin structure varies sharply between curated discovery environments and high-velocity supermarket throughput.
- Supermarkets:Expanded shelf space in US and German mainstream retail channels is displacing specialty store dominance. Oat milk-based bars now sit alongside conventional offerings in specialty confectionery aisles.
- Health Food Stores:Educated staff and curated assortments command premium multiples above supermarket pricing. Urban clusters with high vegan household density in Berlin, London, and Amsterdam sustain viable subscriber density for recurring revenue models.
- Specialty Stores:Limited-batch releases and discovery formats build loyalty unavailable in mass retail.
- Online Retailers:Direct-to-consumer subscriptions displace traditional wholesale relationships for premium assortments among established vegan dietary commitments.
Supermarkets capture absolute volume; health food stores and online channels are expanding margin contribution fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates the densest retail networks for plant-based confectionery, with Berlin and Munich driving shelf-space allocation decisions that ripple across European procurement patterns.
United States
FDA's evolving allergen labeling requirements under FALCPA tighten ingredient disclosure standards for cross-contact risks. Specialty confectionery aisles in US supermarkets now carry oat milk-based bars alongside traditional offerings, expanding mainstream accessibility. California and New York Metro anchor the highest vegan household densities, driving direct-to-consumer subscription growth.
Germany
Berlin and Munich host concentrated demand clusters that accelerate shelf-space allocation in specialty and mainstream channels simultaneously. EU F-Gas Regulation mandates phase-down of hydrofluorocarbon refrigerants across chocolate tempering infrastructure, raising capital requirements for manufacturers. German production clusters leverage existing sustainability investment cycles to absorb compliance costs without margin erosion.
Switzerland
Specialty confectioners pilot enzymatic interesterification to achieve lipid profiles indistinguishable from conventional chocolate. Swissmedic maintains strict novel food evaluation frameworks that shape which precision fermentation-derived ingredients gain rapid market access. Zurich and Geneva anchor premium positioning for artisan dairy-free chocolate with limited-batch discovery formats.
United Kingdom
London sustains viable subscriber density for recurring revenue models through curated discovery formats unavailable in supermarket channels. EFSA novel food application pathways filter emerging plant proteins toward established compounders with dedicated regulatory affairs functions. Birmingham and Manchester industrial bakeries represent underpenetrated volume pools for specialized dairy-free couverture formulations.
Belgium
Belgian specialty confectioners pilot oat-based formulations for industrial baker channels seeking supply security and price stability. REACH compliance adds chemical safety documentation burdens for imported flavoring compounds, consolidating import channels toward established suppliers. Brussels and Antwerp production facilities respond fastest to EU F-Gas retrofit-or-replace decisions favoring greenfield facilities with integrated heat recovery systems.
Dairy-Free Chocolate Market Competitive Landscape
European producers anchor the premium artisan tier; North American specialists hold the mass-market innovation vector. The vendor base stratifies across three tiers: multinational confectionery conglomerates with cocoa sourcing infrastructure, mid-scale plant-based specialists with dedicated dairy-free lines, and artisan craft producers with limited-batch positioning. Two dominant competitive moves are reshaping positioning: portfolio diversification into industrial baker channels and backward integration into precision fermentation-derived lipid sourcing.
Within the multinational tier, Mondelez International, Nestle, and Barry Callebaut occupy positions defined by supply chain scale and regulatory compliance bandwidth. Mondelez leverages established cocoa sourcing infrastructure to secure continuity under tightening environmental rules. Nestle extends plant-based R&D pipelines from beverages into confectionery applications. Barry Callebaut anchors competitive stance through specialized formulations for industrial bakers, exemplifying how ingredient suppliers capture volume outside traditional retail channels.
| Leading Market Players |
|---|
| Mondelez International |
| The Hershey Company |
| Nestle |
| Barry Callebaut |
| Lindt & Sprüngli |
| Mars |
| No Whey Chocolate |
| Alter Eco |
| Endangered Species Chocolate |
| Others |
Value Network & Pricing Analysis
Precision fermentation-derived cocoa butter equivalents are compressing cost economics while simultaneously redistributing supply concentration toward biotechnology hubs with fermentation capacity. This production-method transition simultaneously elevates capital requirements for traditional tempering facilities and creates new margin pools for lipid innovators.
Pricing Analysis
Volume throughput concentrates in supermarket channels with thin margins, while health food stores and direct-to-consumer subscriptions capture premium multiples. Three-tier pricing structure across premium artisan, standard retail, and economy industrial levels reflects certification grade and tempering protocol sophistication. Pricing pressure stems from cocoa butter price volatility forcing reformulation toward lower-fat ratios. Industrial bakeries exhibit highest price sensitivity, accepting viscosity trade-offs for supply security, while vegan household subscribers show lowest elasticity for limited-batch positioning.
Supply Chain Analysis
Flavor chemist talent scarcity in Belgium, Switzerland, and Germany constrains formulation scale-up velocity across European manufacturing clusters. Cocoa butter sourcing draws from Côte d'Ivoire and Ghana, while oat milk emulsion supply anchors in Nordic and German processing facilities. Single-source vulnerability in West African bean origination amplifies EUDR traceability cost burdens. Distribution runs through importer-compounder networks with dedicated regulatory affairs functions serving industrial baker and retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dairy-free chocolate sector is transitioning from plant-based emulsion formulations toward precision fermentation-derived lipid systems, with cell-cultured cocoa butter replacing conventional tempering inputs.
For Market Incumbents: Anchor supply continuity through backward integration into cocoa sourcing infrastructure under tightening EUDR environmental rules. Defend margin position by extending specialized dairy-free couverture formulations for industrial baker channels, insulating against oat milk commodity price swings. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms represent the most penetrable white-space target, particularly in urban clusters with established vegan household density. Industrial bakery supply contracts offer volume scale with lower brand investment requirements than retail shelf-space competition. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational confectionery conglomerates seeking plant-based R&D pipelines. Mid-scale specialists with dedicated dairy-free lines and novel food regulatory dossiers present viable targets. Watch EFSA approval velocity for precision fermentation-derived ingredients as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Cell-cultured cocoa butter reduces dependency on West African supply concentration. |
| Industrial Baker Channel Expansion | Specialized couverture formulations capture volume outside traditional confectionery retail. |
| EU F-Gas Compliance Retrofit | Greenfield facilities with heat recovery absorb regulatory costs without margin erosion. |
| Novel Food Regulatory Dossier Investment | EFSA fast-track approvals secure first-mover positioning for emerging plant proteins. |
| Direct-to-Consumer Subscription Launch | Recurring revenue models in Berlin and London displace wholesale dependency. |
Research Methodology
Independent corroboration across regulatory filings, customs trade records, and retail audit databases underwrites the qualitative findings. Primary interviews with flavor chemists, industrial bakery procurement leads, and health food store category buyers combined with secondary validation from FDA FALCPA guidance documents, EFSA novel food registers, and EU F-Gas implementation reports. Bottom-up volume triangulation across ingredient source segments and top-down value reconciliation anchored the market sizing.
Rate-of-change decomposition across the projection horizon separated volume growth from price-mix effects. Segmentation dimensions modeled include product type, ingredient source, form factor, and distribution channel, with regional regulatory clusters as a cross-cutting overlay. CAGRs derived from historical trajectory analysis adjusted for technology adoption S-curves in precision fermentation and oat milk emulsion processing.
Caveats apply where EFSA novel food approval delays or cocoa butter price spikes could materially shift the outlook. Forecasts reflect assumptions on tempering protocol standardization and vegan household penetration velocity. A small set of named triggers—regulatory approval timelines, fermentation scale-up economics, and West African supply disruptions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Europe Dairy Alternatives Market
Dairy Alternatives
Dairy Alternatives Market
Dairy Alternatives
Milk Alternatives Market
Dairy Alternatives
Coconut Milk Market
Dairy Alternatives
Buttermilk Market
Dairy Alternatives
Global Vegan Sour Cream Market
Dairy Alternatives
Plant Milk Market
Dairy Alternatives
Pet Milk Market
Dairy Alternatives
Dairy-Free Ice Creams Market
Dairy Alternatives
Asia-Pacific Coconut Milk Market
Dairy Alternatives
Cheese Alternative Market
Dairy Alternatives
Vegan Yogurts Market
Dairy Alternatives
Germany Non-Dairy Milk Market
Dairy Alternatives
Soy Milk Market
Dairy Alternatives
Vegan Ice Cream Market
Dairy Alternatives
US Lactose-Free Dairy Market