
 Germany Non-Dairy Milk Market | 2026-2036
Germany Non-Dairy Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Non-Dairy Milk Market Insights
Enzymatic processing of oat fibers is fragmenting traditional extraction methods across the German non-dairy milk supply chain. Oatly Group AB leverages proprietary enzymatic technology to sustain premium positioning in foodservice channels. Danone SA anchors its German portfolio through specialized fermentation capabilities for almond and soy bases. Alpro dominates retail shelf space with extensive cold-chain logistics that control supermarket distribution networks.
Germany non-dairy milk comprises plant-based liquid beverages formulated from aqueous extracts of oilseeds, cereals, or nuts, standardized to protein contents between 0.5% and 3.5% and fortified with calcium, vitamin D, and vitamin B12 to match dairy nutritional profiles. Oat milk leads product type segments due to superior foaming stability and neutral flavor compatibility with coffee applications. Online retail channels represent the fastest-growing distribution pathway as direct-to-consumer subscriptions bypass traditional wholesale markups. Tetra packs occupy the dominant packaging format owing to extended ambient shelf life and lower carbon footprint relative to refrigerated plastic bottles.
German regulators enforce strict labeling under EU Regulation 1169/2011, requiring clear differentiation between "milk" (dairy-only) and plant-based descriptors, while BfR (Federal Institute for Risk Assessment) monitors maximum residue levels for mycotoxins in nut-based beverages. The EU F-Gas Regulation indirectly shapes processing economics by restricting hydrofluorocarbon use in cold storage infrastructure. Stakeholders must monitor pending revisions to the EU Plant Protein Strategy and Germany's national protein transition roadmap, as these frameworks will determine subsidy eligibility and public procurement criteria for domestic oat processing facilities.
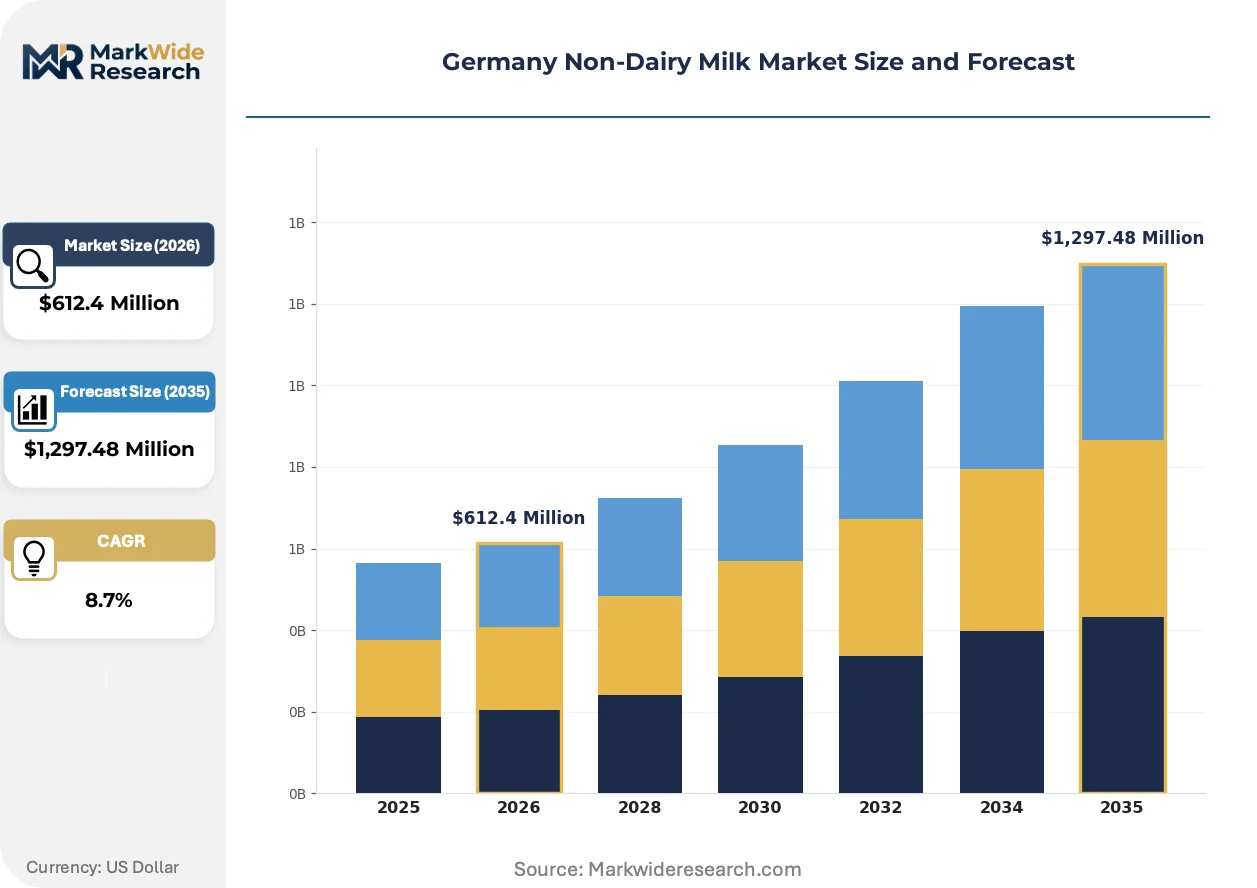
Market Dynamics
Enzymatic oat fiber processing is compressing extraction costs and enabling foodservice-grade foaming stability that conventional milling cannot replicate. This technological inflection is redrawing procurement relationships between German roasteries and ingredient suppliers.
Growth Catalysts
- EU Plant Protein Strategy:Pending subsidy frameworks for domestic oat processing facilities will reduce import dependency on Nordic suppliers. German agricultural cooperatives are positioning for grant eligibility.
- Specialty coffee channel expansion:Berlin and Munich café chains now specify barista-grade oat milk in equipment procurement tenders. This specification locks in volume commitments.
- BfR mycotoxin monitoring protocols:Stringent residue testing for nut-based beverages is accelerating quality investments that favor established oat processors with laboratory infrastructure.
Market Restraints
- Oat raw material concentration:Swedish and Finnish suppliers control premium milling-grade oat supply. German processors face currency exposure and Baltic shipping bottlenecks.
- Cold-chain infrastructure costs:Refrigerated distribution for fresh plant-based beverages requires hydrofluorocarbon-compliant equipment under EU F-Gas Regulation. Retrofit capex strains mid-tier brands.
- Dairy lobby litigation:German dairy associations challenge plant-based labeling under EU Regulation 1169/2011. Legal defense costs divert R&D budgets.
Strategic Opportunities
- Direct-to-consumer subscriptions:Online retail bypasses supermarket slotting fees. Tetra pack ambient formats enable pantry delivery models without cold-chain investment.
- Public procurement criteria:Germany's national protein transition roadmap will mandate plant-based options in federal catering contracts. Municipal canteen tenders represent volume anchors.
- Enzyme-catalyzed protein fortification:Convergence of fermentation science and precision enzymology enables 3.5% protein oat milks matching dairy nutritional equivalence.
Industry Challenges
- Food technologist scarcity:Formulation expertise for enzyme-stabilized emulsions concentrates in Copenhagen and Amsterdam. German universities lag in applied plant protein curricula.
- Organic certification timelines:EU organic conversion periods for oat sourcing extend 24-36 months. Brands cannot pivot quickly to capture premium shelf positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Non-Dairy Milk Market |
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,297.48 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond Milk, Soy Milk, Oat Milk, Coconut Milk Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Convenience Stores Consumer Type: Health Conscious, Vegan, Lactose Intolerant, Organic Enthusiasts Packaging Type: Plastic Bottles, Tetra Packs, Glass Bottles, Cans |
| Companies Covered | AlnaturA Produktions- und Handels GmbH, Oatly Group AB, Danone SA, Nestlé SA, The Hain Celestial Group Inc., Blue Diamond Growers, Veganz Group, Simply V, Alpro, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Non-Dairy Milk Market Trends and Innovations
Processing technology and distribution infrastructure are diverging from legacy dairy paradigms. German manufacturers are building purpose-built capabilities rather than retrofitting milk plants.
High-shear enzymatic hydrolysis of oat beta-glucans is rendering obsolete traditional roller milling for beverage-grade extraction. Bavarian foodservice distributors now specify hydrolyzed oat base in quarterly procurement agreements. The technology is compressing ingredient costs while extending ambient shelf stability beyond twelve months.
EU F-Gas Regulation restrictions on hydrofluorocarbon refrigerants are forcing cold storage infrastructure decisions. German processors face accelerated depreciation of existing chilling equipment. Ambient-stable UHT formats are gaining share as refrigerated plastic bottle economics deteriorate.
Subscription-based replenishment models are displacing supermarket impulse purchases among urban vegan households. Direct-to-consumer platforms in Hamburg and Cologne offer flavor-customized variety packs. North Rhine-Westphalia demonstrates the highest trial-to-retention conversion for auto-ship plant-based beverages.
Germany Non-Dairy Milk Market Segmentation
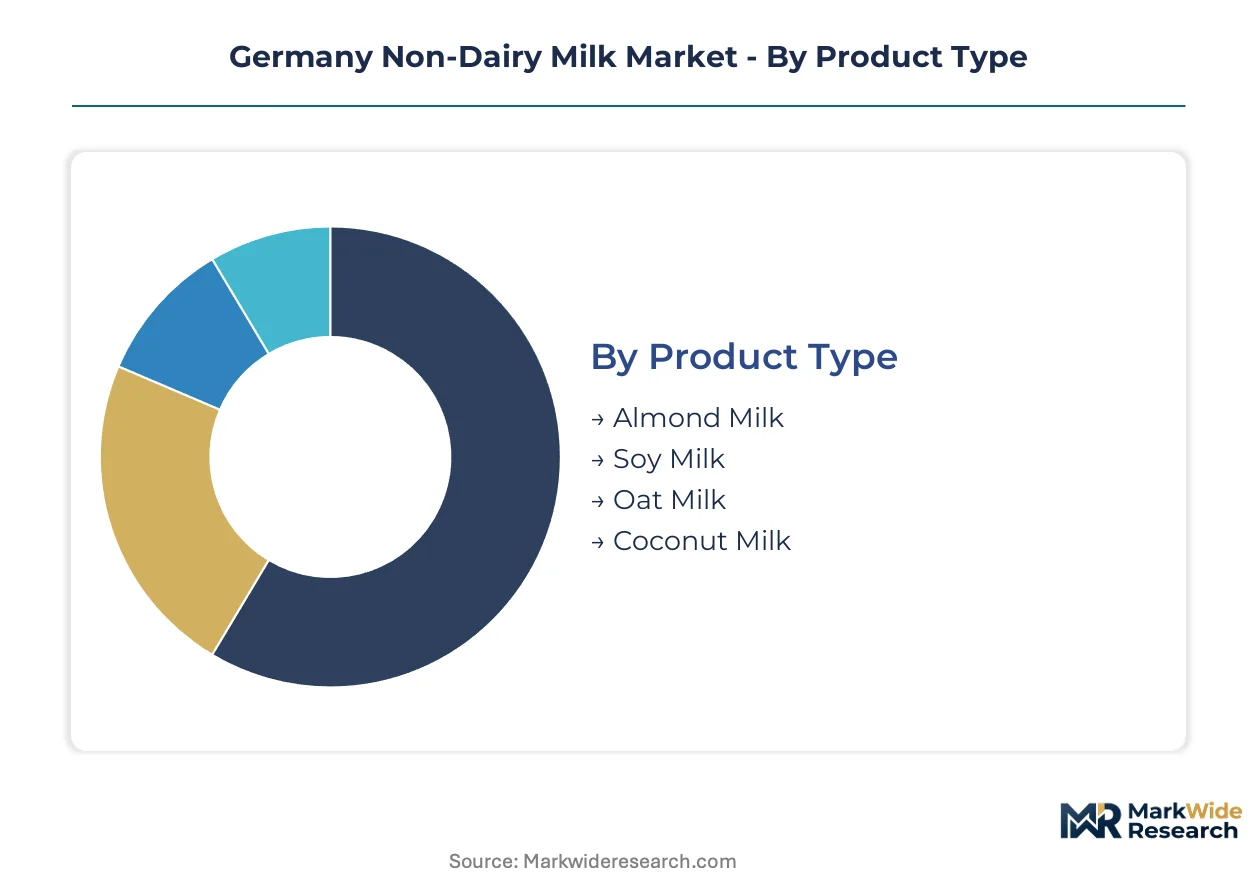
German non-dairy milk segmentation reveals divergent growth mechanics across product formulations and channel economics. Each dimension carries distinct margin profiles, regulatory exposure, and supply chain requirements that reshape competitive positioning.
Product Type:
Maturity varies sharply across plant bases, with cereal-derived formats commanding foodservice premiums while legacy oilseed varieties defend retail volume.
- Oat Milk:Enzymatically hydrolyzed beta-glucan bases deliver superior foaming stability for barista applications. Bavarian specialty coffee chains in Munich and Berlin now specify hydrolyzed oat in procurement tenders, locking in volume commitments through multi-year supply agreements.
- Almond Milk:Lower protein content and water-intensive cultivation constrain German sourcing. BfR mycotoxin monitoring protocols for imported nut bases accelerate quality investments that favor established processors with laboratory infrastructure.
- Soy Milk:Fermentation-optimized formulations from Danone anchor retail shelf presence through specialized cold-chain logistics.
- Coconut Milk:Tropical sourcing exposes processors to currency volatility and extended shipping routes from Southeast Asian suppliers.
Oat milk handles the majority of throughput; coconut milk is gaining share fastest through ethnic cuisine channel expansion.
Distribution Channel:
Channel economics split between high-frequency retail replenishment and subscription-driven direct fulfillment, each demanding distinct packaging and margin structures.
- Supermarkets:Alpro dominates through extensive cold-chain networks controlling refrigerated shelf space. Slotting fees and promotional calendars compress margins for mid-tier entrants.
- Online Retail:Direct-to-consumer subscriptions bypass wholesale markups. Hamburg and Cologne platforms offer flavor-customized variety packs with auto-ship retention models.
- Health Food Stores:Organic certification premiums attract dedicated vegan demographics in urban centers.
- Convenience Stores:Ambient Tetra pack formats enable grab-and-go positioning without refrigeration investment.
Supermarkets handle the majority of throughput; online retail is climbing the fastest on share as subscription models displace impulse purchasing.
Consumer Type:
Customer archetypes align with distinct price sensitivities and certification requirements that reshape formulation priorities.
- Vegan:Strict ethical positioning demands B12 fortification and transparent supply chain auditing. North Rhine-Westphalia demonstrates the highest concentration of dedicated plant-based households.
- Health Conscious:Protein equivalence drives interest in enzyme-catalyzed fortification reaching 3.5% content. German Nutrition Society guidelines validate plant-based alternatives in dietary planning.
- Lactose Intolerant:Functional substitution needs prioritize taste parity over nutritional matching.
- Organic Enthusiasts:EU organic conversion timelines of 24-36 months for oat sourcing prevent rapid pivoting to capture premium positioning.
Vegan consumers handle the majority of throughput; organic enthusiasts are expanding most quickly as certification infrastructure matures.
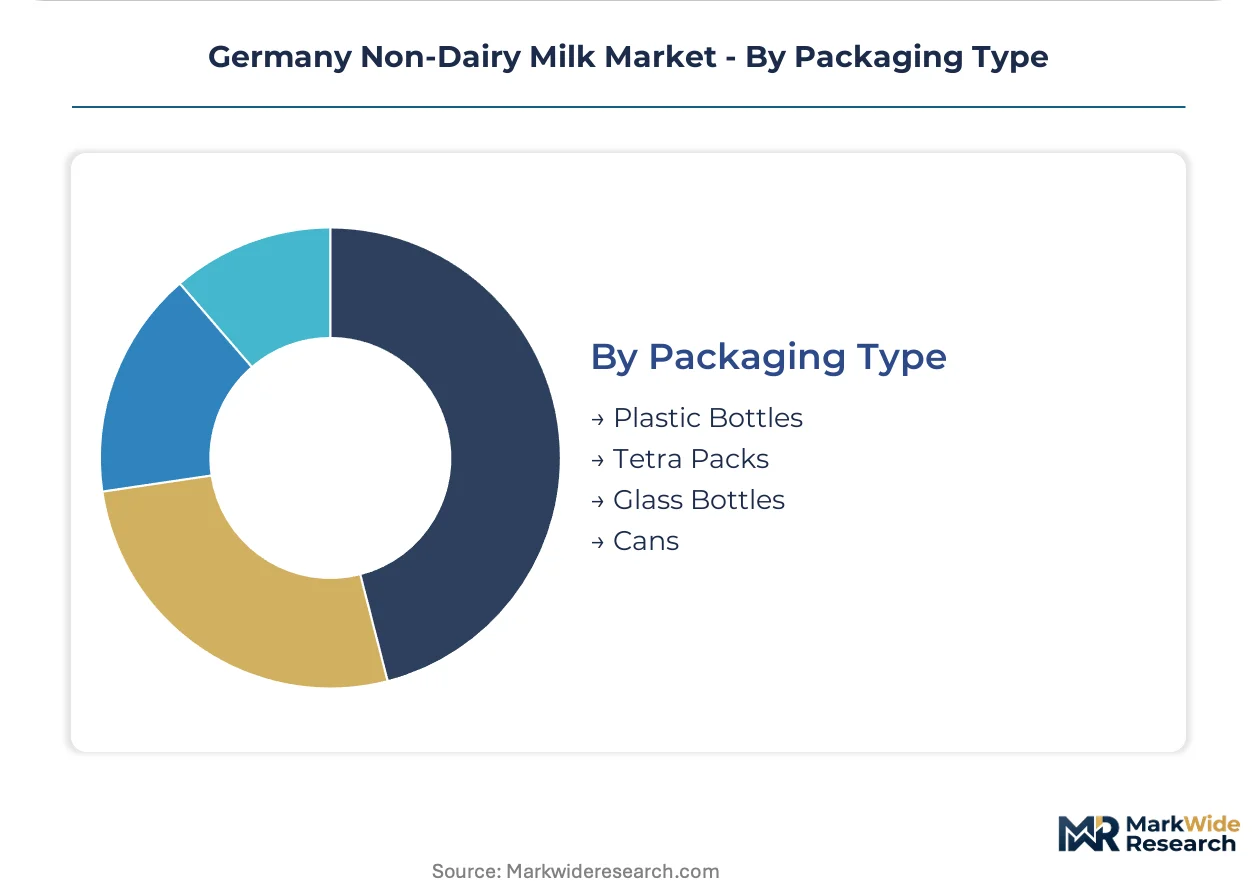
Packaging Type:
Format selection determines cold-chain investment, shelf-life economics, and carbon footprint positioning under EU sustainability frameworks.
- Tetra Packs:Aseptic carton technology enables twelve-month ambient stability with lower carbon footprint than refrigerated alternatives. UHT processing avoids EU F-Gas Regulation compliance costs for hydrofluorocarbon refrigeration.
- Plastic Bottles:Chilled distribution requirements strain mid-tier brands facing accelerated depreciation of existing cooling equipment.
- Glass Bottles:Premium positioning in organic channels carries weight penalties and breakage risk in logistics.
- Cans:Metallic formats serve foodservice bulk dispensing with extended durability.
Tetra packs handle the majority of throughput; plastic bottles are losing share fastest as refrigerated economics deteriorate under regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's non-dairy milk sector operates as a net importer of premium oat milling stock, with domestic processing capacity concentrated in Bavaria and North Rhine-Westphalia absorbing Nordic supply while re-exporting finished Tetra pack formats to neighboring EU markets.
North Rhine-Westphalia
Urban vegan household density in Cologne and Düsseldorf drives subscription platform proliferation for direct-to-consumer oat milk delivery. The EU F-Gas Regulation shapes cold storage investment decisions for processors serving this corridor. Dortmund logistics clusters host ambient UHT packaging facilities that bypass refrigeration infrastructure costs entirely.
Bavaria
Munich specialty coffee chains specify barista-grade enzymatically hydrolyzed oat bases in multi-year procurement tenders. The German Nutrition Society guidelines validate plant-based alternatives in federal dietary planning documents. Nuremberg foodservice distributors now require hydrolyzed oat specifications in quarterly supply agreements.
Baden-Württemberg
Stuttgart metropolitan health-conscious consumers prioritize protein-fortified formulations matching dairy nutritional equivalence. BfR mycotoxin monitoring protocols for nut-based imports accelerate laboratory infrastructure investments. Freiburg organic certification demand strains EU conversion timelines of 24-36 months for regional oat sourcing.
Berlin-Brandenburg
Berlin café culture anchors foodservice-grade oat milk volume commitments through equipment procurement specifications. EU Regulation 1169/2011 labeling disputes consume legal defense budgets among plant-based entrants. Potsdam municipal canteen tenders anticipate Germany's national protein transition roadmap mandates for federal catering contracts.
Hamburg
Port logistics infrastructure enables Baltic oat import reception from Swedish and Finnish milling-grade suppliers. Currency exposure and shipping bottlenecks concentrate procurement risk for German processors. Hamburg direct-to-consumer platforms demonstrate the highest trial-to-retention conversion for auto-ship plant-based beverage subscriptions nationwide.
Germany Non-Dairy Milk Market Competitive Landscape
On the supply side, the industry is consolidating around enzymatic processing capabilities and cold-chain logistics networks that favor scale-driven operators over artisan entrants. Three archetypes dominate: Nordic-origin oat specialists with proprietary hydrolysis technology, diversified dairy conglomerates leveraging fermentation science for plant-based extensions, and regional organic pure-play brands capturing health food store premiums. Competitive moves concentrate on backward integration into Nordic oat sourcing and strategic partnerships with specialty coffee equipment manufacturers.
Within the diversified food conglomerate tier, Danone SA and Nestlé SA occupy positions anchored by specialized fermentation capabilities and global distribution infrastructure. Among oat-native specialists, Oatly Group AB exemplifies the premium foodservice positioning archetype through proprietary enzymatic technology. Alpro represents the retail shelf dominance model controlling supermarket refrigerated networks across German metropolitan corridors.
| Leading Market Players |
|---|
| AlnaturA Produktions- und Handels GmbH |
| Oatly Group AB |
| Danone SA |
| Nestlé SA |
| The Hain Celestial Group Inc. |
| Blue Diamond Growers |
| Veganz Group |
| Simply V |
| Alpro |
| Others |
Pricing and Supply Chain Analysis
Baltic Sea shipping corridors from Swedish and Finnish milling-grade suppliers concentrate procurement risk for German processors, with freight cost volatility transmitting directly into downstream price stratification across foodservice and retail tiers.
Pricing Analysis
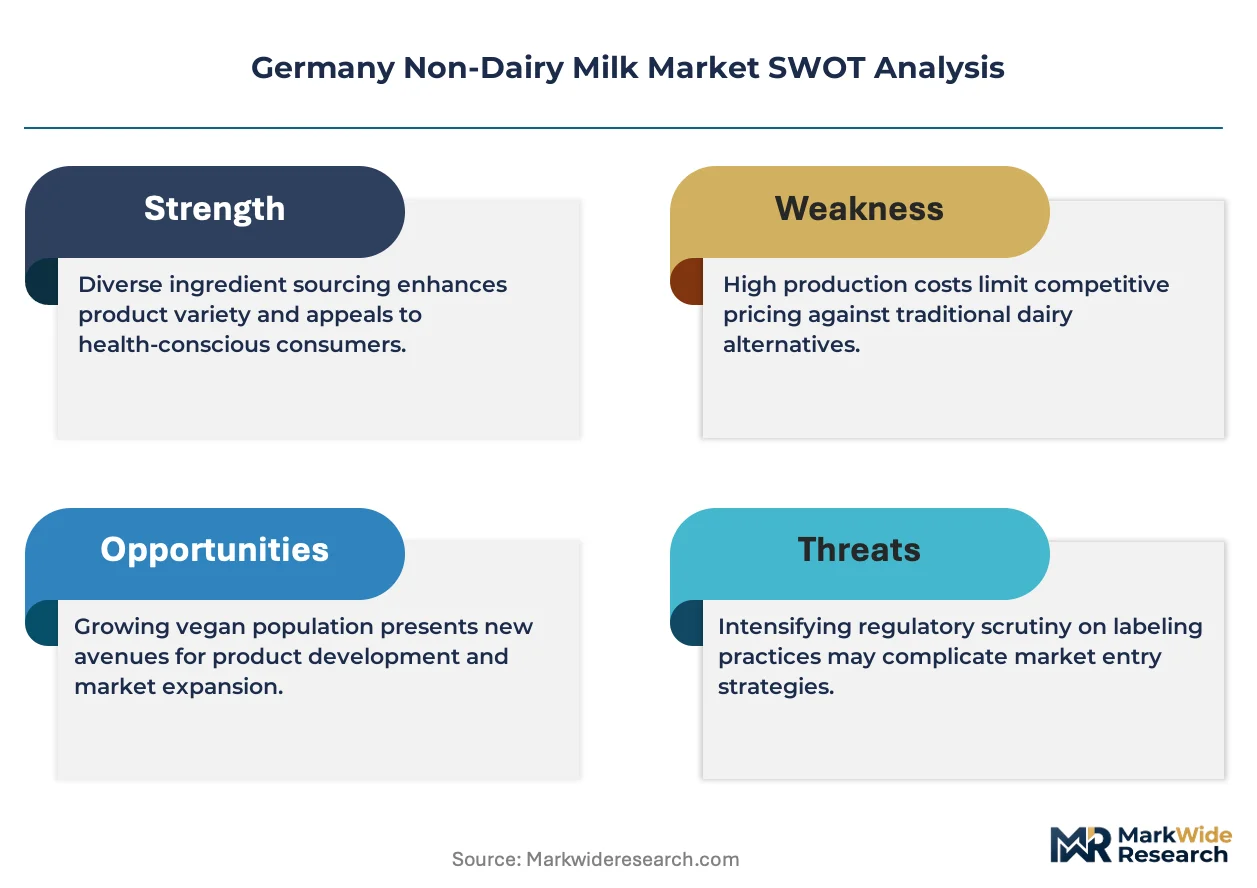
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with enzymatic hydrolysis certification and cold-chain logistics capability serving as the primary differentiation drivers. Cost compression in the standard tier is intensifying because mid-tier brands face accelerated depreciation of hydrofluorocarbon-compliant refrigeration equipment. Foodservice chains demonstrate the lowest price sensitivity due to locked multi-year volume commitments, while convenience store channels exhibit highest elasticity.
Supply Chain Analysis
Premium milling-grade oat feedstock draws from Swedish and Finnish agricultural cooperatives, with German processors dependent on enzymatic processing inputs and aseptic packaging materials. Single-source vulnerability concentrates in Baltic shipping routes exposed to seasonal bottlenecks. Distribution runs through Bavarian and North Rhine-Westphalia logistics clusters serving retail and foodservice channels respectively.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's non-dairy milk sector represents high-growth disruption catalyzed by enzymatic hydrolysis technology compressing extraction costs while extending ambient shelf stability beyond legacy dairy paradigms.
For Market Incumbents: Pre-empt Nordic supplier consolidation by securing captive oat sourcing through backward integration into German agricultural cooperative networks. Invest in laboratory infrastructure to meet BfR mycotoxin monitoring protocols before quality requirements tighten. Channel control through specialized fermentation capabilities anchors retail shelf presence against oat-native specialists. For New Entrants and Emerging Players: Establish a beachhead in direct-to-consumer subscription platforms bypassing supermarket slotting fees. Target North Rhine-Westphalia's urban vegan household density where trial-to-retention conversion rates peak nationally. Flavor-customized variety packs with auto-ship retention models offer the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified dairy conglomerates seeking to divest non-core plant-based extensions amid margin pressure. Long-term viability hinges on enzymatic processing IP and cold-chain logistics scale rather than brand equity alone. Watch pending EU Plant Protein Strategy subsidy frameworks as the decisive inflection for domestic oat processing facility valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oat Sourcing | Reduces currency exposure to Swedish and Finnish milling-grade suppliers. |
| Enzymatic Hydrolysis Capacity Expansion | Enables barista-grade foaming stability specifications from Munich café chains. |
| Ambient UHT Format Transition | Bypasses EU F-Gas Regulation compliance costs for hydrofluorocarbon refrigeration. |
| Direct-to-Consumer Platform Launch | Captures Hamburg and Cologne subscription retention without supermarket slotting fees. |
| BfR Laboratory Infrastructure Investment | Accelerates quality certification for nut-based beverage import protocols. |
Research Methodology
The analysis maps oat milk, almond milk, soy milk, and coconut milk sub-sectors, each validated through plant protein formulation scientists, foodservice procurement directors, retail category buyers, and cold-chain logistics operators. Primary interviews combined with secondary validation from EU Regulation 1169/2011 filings, BfR residue monitoring protocols, and German Nutrition Society guideline documents. Bottom-up volume triangulation against top-down protein transition roadmap projections anchored forecast reliability.
Assumptions held fixed include EU F-Gas Regulation enforcement timelines and organic certification conversion periods, while oat raw material pricing and enzymatic processing adoption rates varied across scenarios. Segmentation dimensions modeled encompass product type, distribution channel, consumer archetype, and packaging format through the projection horizon. CAGRs derived from volume trajectory analysis incorporating specialty coffee channel expansion rates and subscription platform penetration curves.
Stress conditions across Baltic shipping bottlenecks, currency volatility, and BfR protocol stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these bounded assumptions with acknowledged sensitivity to pending EU Plant Protein Strategy subsidy revisions. Cross-checking against German agricultural cooperative grant allocation data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
A2 Ice Cream Market
Dairy Alternatives
Saudi Arabia Dairy Alternatives Market
Dairy Alternatives
China Dairy Alternatives Market
Dairy Alternatives
Almond Milk Market
Dairy Alternatives
Vegan Condensed Milk Market
Dairy Alternatives
Milk Alternatives Market
Dairy Alternatives
Middle East Dairy Alternatives Market
Dairy Alternatives
Sesame Milk Market
Dairy Alternatives
Global Milk Replacers Market
Dairy Alternatives
Coconut Milk and Cream Market
Dairy Alternatives
Coconut Milk Powder Market
Dairy Alternatives
Coconut Milk Products Market
Dairy Alternatives
Vegan Coffee Creamer Market
Dairy Alternatives
Coconut Milk Derivatives Market
Dairy Alternatives
Non-Dairy Yogurt Market
Dairy Alternatives
United States Oat Milk Market