
 Vapor Blasting Equipment Market | 2026-2036
Vapor Blasting Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Vapor Blasting Equipment Market Analytics
Market Context
Single-source procurement for precision blast media is decoupling from traditional abrasive supply chains as buyers diversify vendor relationships. Rösler Oberflächentechnik GmbH leverages its German engineering base to dominate high-tolerance cabinet systems for aerospace. Vapormatt Ltd. competes through specialized wet-blast automation for turbine blade restoration. Graco Inc. anchors North American distribution with broad portable and stationary equipment portfolios.
Technical Definition and Segment Structure
Vapor blasting equipment suspends abrasive media in a water slurry, typically operating at pressures between 30 and 150 psi to produce satin surface finishes without dimensional distortion. The technology serves critical restoration and preparation functions across aerospace, automotive, and marine maintenance workflows. Stationary systems command the deepest margin pools due to capital intensity and integration with factory automation, while portable units address expanding on-site service provider demand. Wet blast technology leads installed base share, though dual-action systems are gaining traction where facilities must switch between delicate finishing and aggressive stripping.
Regulatory Environment
EPA NESHAP standards for abrasive blasting emissions and OSHA silica exposure limits directly shape equipment specification and dust-collection requirements in the United States. REACH registration obligations and CE machinery directives in Europe restrict certain abrasive chemistries and mandate operator safety interlocks. Stakeholders must monitor evolving state-level silica rules and EU Green Deal industrial emissions protocols to anticipate compliance-driven replacement cycles.
Market Dynamics
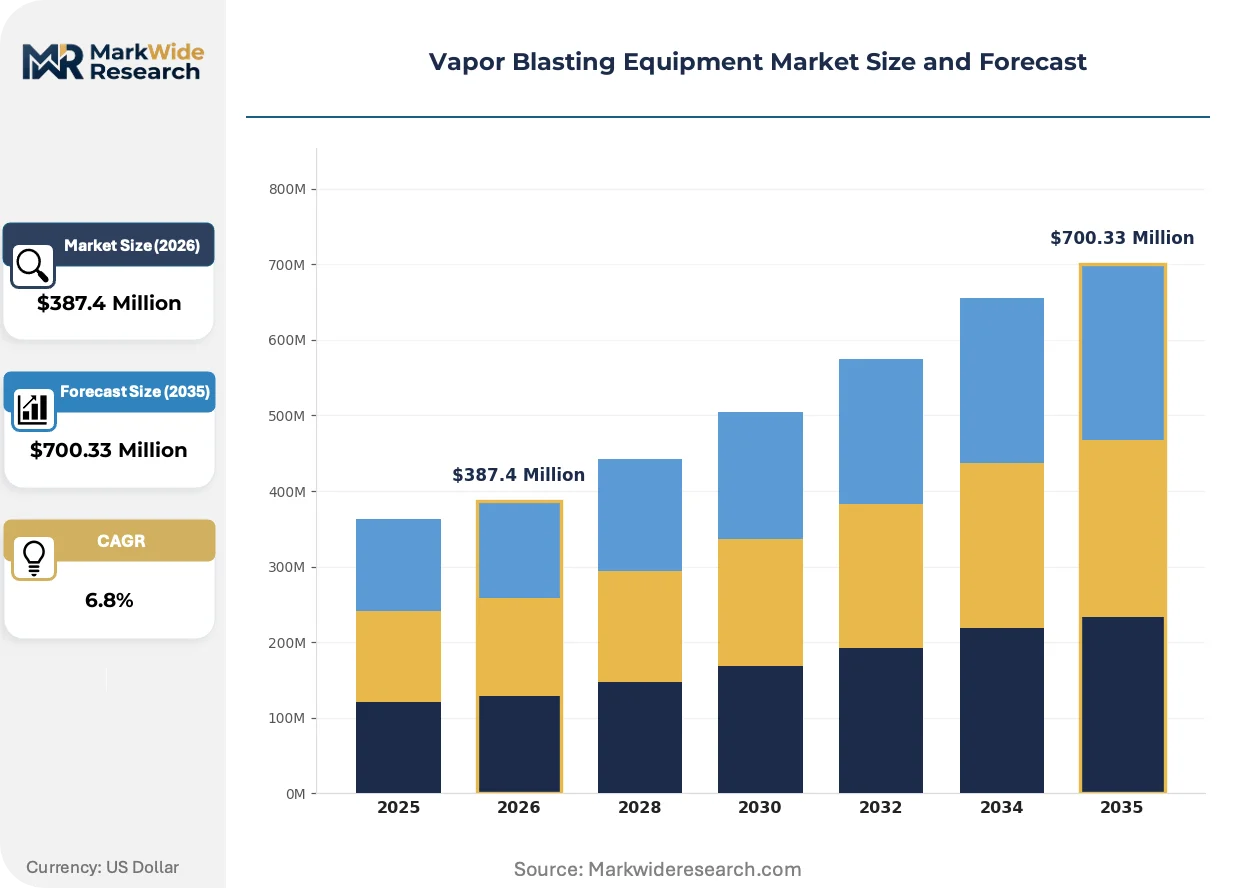
The vapor blasting equipment market is experiencing a structural pivot as wet-blast technology captures share from dry abrasive systems, driven by tightening silica exposure regulations and aerospace precision requirements that favor water-slurry finishing.
Growth Catalysts
- REACH Phase-Down of Hazardous Abrasives:ECHA restrictions on crystalline silica and heavy-metal slags are forcing European facilities toward closed-loop wet systems that eliminate airborne particulate.
- Turbine Blade Restoration Demand:Aerospace MRO facilities are expanding wet-blast capacity to handle thermal barrier coating removal without substrate damage to nickel superalloy components.
- German Automotive Supply Chain:Precision surface-finishing clusters around Stuttgart and Munich are standardizing vapor blast protocols for powertrain component preparation.
Market Restraints
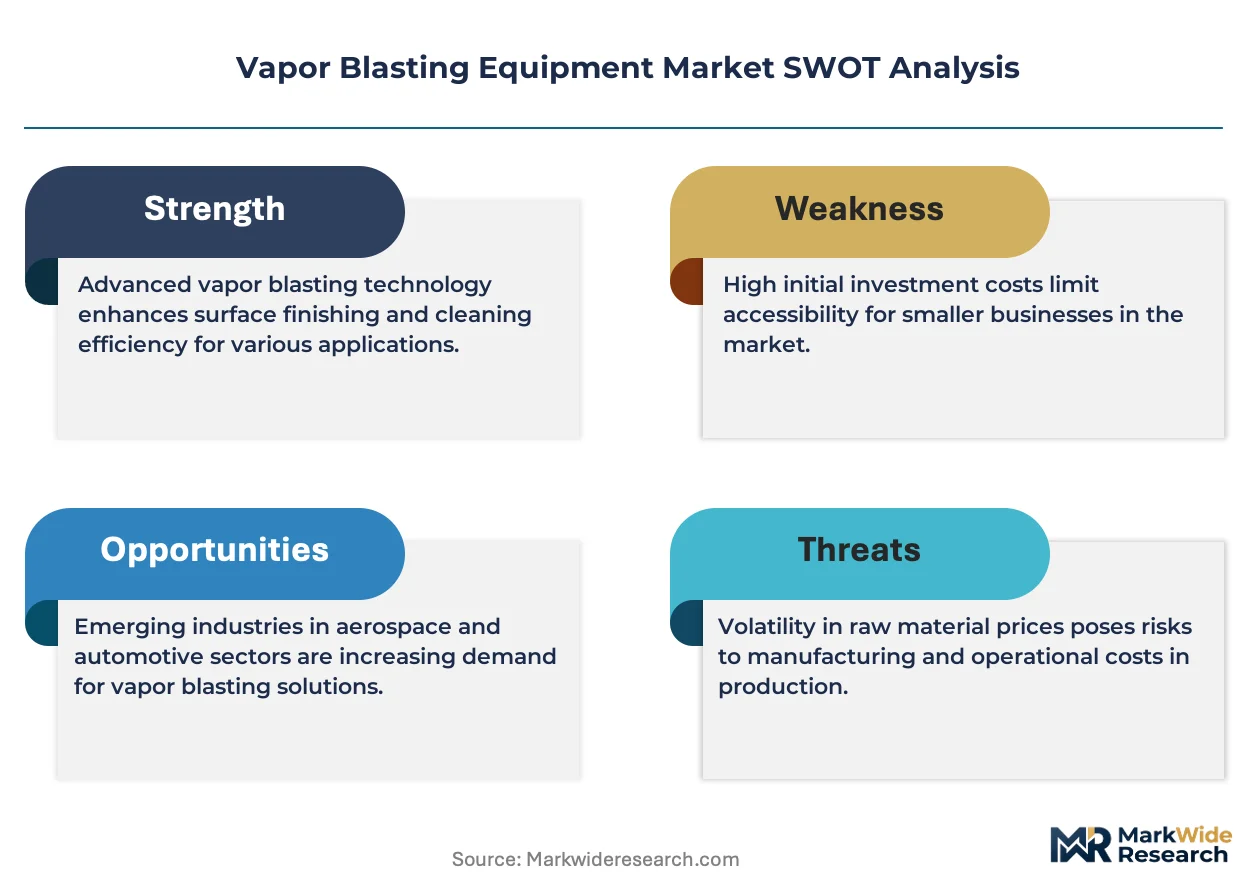
- Alumina Price Volatility:Fused aluminum oxide, the dominant abrasive media, faces supply squeezes from Chinese export curbs and energy-cost spikes at European smelters.
- Capital Equipment Intensity:Stationary vapor blast cabinets with automated indexing and closed-loop filtration require substantial upfront investment that limits small-shop adoption.
- Dry Blast Substitution in Heavy Stripping:Shipyards and structural steel contractors continue favoring high-pressure dry blasting for thick coating removal where surface finish tolerance is loose.
Strategic Opportunities
- India Defense Aerospace:Hindustan Aeronautics and private MRO providers are building turbine restoration capabilities that lack indigenous wet-blast equipment supply.
- EU Green Deal Industrial Emissions Protocol:Upcoming tightening of particulate matter thresholds will mandate wet-system retrofits at metal-finishing facilities across member states.
- Robotics Convergence:Collaborative robot integration with vapor blast cabinets is enabling consistent surface preparation for additive manufacturing post-processing workflows.
Industry Challenges
- Wet-Media Process Engineering Talent:Facilities struggle to hire technicians who understand slurry rheology, nozzle wear patterns, and water chemistry balancing for consistent finish quality.
- CE Machinery Directive Compliance Timelines:Manufacturers face extended certification cycles for safety interlocks and operator exposure monitoring systems required for European market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vapor Blasting Equipment Market |
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $700.33 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Units, Stationary Systems, Automated Machines, Cabinet Systems Application: Aerospace Components, Automotive Parts, Industrial Equipment, Marine Applications End User: Manufacturers, Service Providers, Workshops, OEMs Technology: Wet Blast, Dry Blast, Propellant-Free, Dual-Action |
| Companies Covered | Rösler Oberflächentechnik GmbH, Graco Inc., Vapormatt Ltd., Vapor Honing Technologies, Greener Blast Technology, Guyson Corporation, Clemco Industries Corp., Sinto America, Vixen Surface Treatments Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vapor Blasting Equipment Market Evolving Landscape
Wet-blast technology is advancing through three interconnected vectors: equipment automation, regulatory-driven media reformulation, and shifting procurement relationships between OEMs and finishing service providers.
Closed-loop slurry recovery systems are unifying water treatment, abrasive recycling, and waste minimization into single-platform designs. Aerospace tier-one suppliers are adopting these integrated systems to meet internal sustainability targets. The technology is unifying what were previously separate capital purchases—blast cabinet, water clarifier, and media classifier—into turnkey installations that compress vendor management overhead.
EPA NESHAP standards for abrasive blasting emissions are tightening permissible particulate discharge thresholds at metal fabrication facilities. Equipment buyers now specify HEPA filtration and negative-pressure cabinet designs as baseline requirements. Wet-blast system manufacturers serving the US market are engineering lower-pressure, higher-volume slurry delivery to maintain finish quality while reducing mist generation.
Contract manufacturers are consolidating precision finishing relationships with fewer, larger equipment vendors who provide predictive maintenance and media logistics. Tier-two automotive suppliers are shifting from equipment ownership to throughput-based service agreements with regional job shops. This concentration is most visible in southern Germany, where BMW and Porsche supply chains have reduced approved vapor blast vendors from dozens to single-digit panels.
Vapor Blasting Equipment Market Segmentation
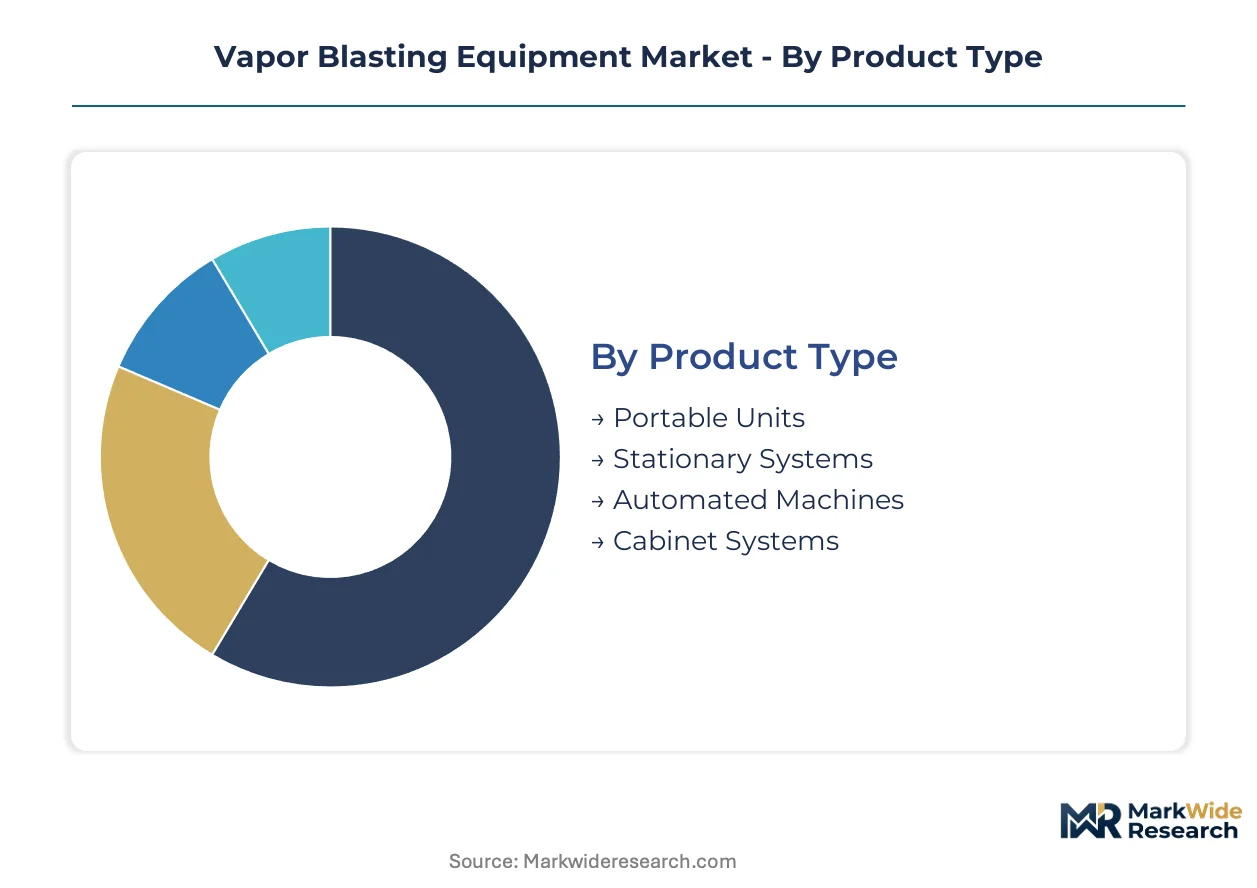
Vapor blasting equipment segments diverge sharply by capital intensity and integration depth. Standalone portable units serve mobile contractors, while embedded automated systems tie directly into aerospace and automotive production lines. Procurement decisions hinge on whether surface finishing operates as a discrete service or an integrated manufacturing step.
Product Type:
Portable units operate as standalone service assets deployed to customer sites, while stationary systems embed permanently within factory automation architectures. Cabinet systems occupy a middle tier—semi-fixed installations that workshops reconfigure for batch changes.
- Stationary Systems:Fixed installations integrate with robotic indexing and closed-loop filtration for continuous production environments. Aerospace tier-one suppliers in Germany specify these for turbine blade restoration workflows where thermal barrier coating removal demands precise pressure control. Capital intensity limits adoption to high-volume facilities with dedicated maintenance budgets.
- Portable Units:Mobile equipment addresses on-site service demand from marine repair contractors and field-based MRO providers. Shipyards in Hamburg and Bremen deploy these for hull preparation where transport to fixed facilities proves uneconomical. Lower upfront cost expands access to small workshops, though throughput constraints cap revenue per deployment.
- Automated Machines:Robotic integration enables consistent surface preparation for additive manufacturing post-processing.
- Cabinet Systems:Semi-fixed enclosures serve job shops with batch variability across automotive and industrial equipment applications.
Stationary systems lead volumes today; automated machines are gaining share fastest.
Application:
Cost tiers separate aerospace precision requirements from heavy industrial stripping where tolerance bands widen and equipment specifications relax.
- Aerospace Components:Thermal barrier coating removal from nickel superalloy turbine blades demands water-slurry finishing at controlled pressures to prevent substrate damage. MRO facilities at Lufthansa Technik and MTU Maintenance expand wet-blast capacity to handle engine overhaul volumes. REACH compliance on crystalline silica accelerates closed-loop system adoption.
- Automotive Parts:Powertrain component preparation requires satin finishes for bearing surfaces and transmission housings. Stuttgart-area suppliers standardize vapor blast protocols for BMW and Porsche supply chain integration. Process consistency requirements favor automated cabinet configurations over manual operations.
- Industrial Equipment:General machinery restoration accepts broader surface finish tolerances.
- Marine Applications:Hull maintenance and propeller refurbishment balance corrosion removal against substrate preservation.
Aerospace components command premium pricing; automotive parts show the steepest expansion trajectory.
End User:
Customer type determines whether equipment purchases center on throughput ownership or service-based revenue models.
- Service Providers:Independent job shops purchase portable and cabinet systems to offer outsourced finishing. Southern Germany has seen vendor panels consolidate from dozens to single-digit approved suppliers as BMW and Porsche tighten supply chain oversight. Throughput-based contracts now replace equipment ownership for tier-two automotive suppliers.
- Manufacturers:Captive finishing operations integrate stationary systems directly into production lines.
- Workshops:Small-batch operators prioritize flexible equipment reconfiguration.
- OEMs:Original equipment manufacturers specify vendor equipment for warranty-compliant restoration protocols.
Service providers dominate unit shipments; manufacturers capture the highest revenue per installation.
Technology:
Technology maturity separates established wet-blast dominance from emerging dual-action flexibility.
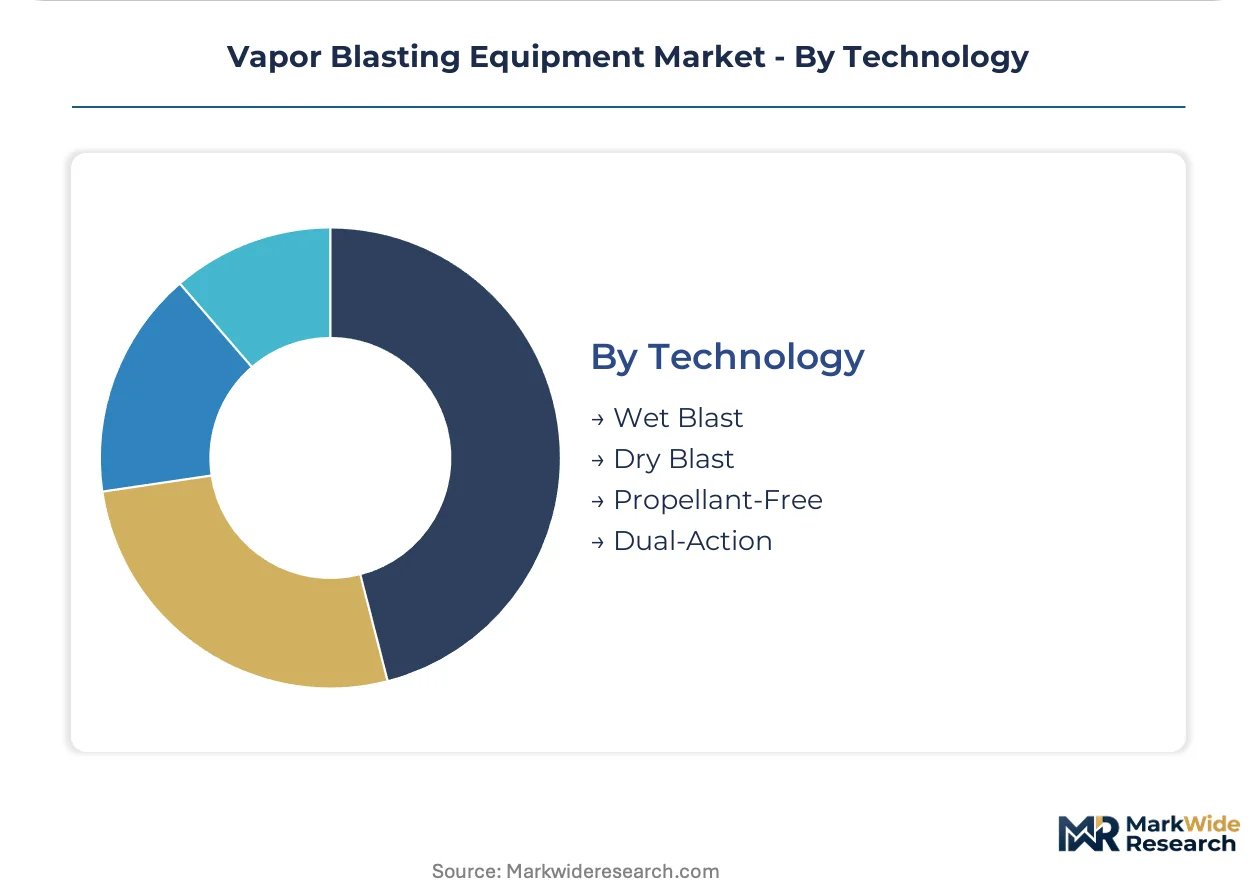
- Wet Blast:Water-slurry suspension at 30-150 psi produces satin finishes without dimensional distortion. EPA NESHAP tightening on particulate emissions and OSHA silica exposure limits accelerate displacement of dry systems in US metal fabrication. Closed-loop slurry recovery unifies water treatment and abrasive recycling into single-platform designs.
- Dual-Action:Switchable wet-dry operation addresses facilities needing both delicate finishing and aggressive stripping. Shipyards and structural steel contractors value this flexibility where coating thickness varies dramatically. Higher mechanical complexity elevates maintenance requirements and operator training demands.
- Dry Blast:High-pressure abrasive delivery persists in heavy stripping applications.
- Propellant-Free:Centrifugal and mechanical acceleration methods eliminate compressed air dependency.
Wet blast leads installed base share; dual-action configurations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart's precision surface-finishing cluster anchors worldwide vapor blasting equipment demand, driven by automotive OEM supply chain integration and REACH-mandated wet-system adoption across European metal fabrication.
United States
EPA NESHAP emission standards and OSHA silica exposure limits force metal fabrication facilities toward closed-loop wet blast retrofits. Aerospace MRO providers at Dallas-Fort Worth and Atlanta expand turbine restoration capacity. California's South Bay manufacturing corridor adopts HEPA-integrated cabinet systems for precision component finishing.
Germany
REACH phase-down of crystalline silica abrasives accelerates displacement of dry blasting in automotive powertrain preparation. Bavarian suppliers around Munich standardize vapor blast protocols for BMW and Porsche supply chain integration. MTU Maintenance in Hannover expands wet-blast capacity for engine overhaul workflows.
China
Domestic aerospace MRO buildout at COMAC service centers creates demand for precision wet-blast systems. MIIT industrial emissions guidelines tighten particulate discharge thresholds at metalworking facilities. Yangtze River Delta manufacturing clusters adopt automated slurry recovery platforms for bearing surface preparation.
India
Hindustan Aeronautics and private defense MRO providers build turbine restoration capabilities lacking indigenous wet-blast equipment supply. BIS certification requirements for imported machinery extend procurement timelines. Bengaluru's aerospace manufacturing corridor attracts regional equipment vendors establishing service partnerships.
Japan
PMDA-aligned medical device manufacturers specify vapor blast finishing for implant surface preparation. METI industrial decarbonization programs incentivize closed-loop water treatment integration. Nagoya's automotive component cluster adopts satin-finish protocols for transmission housing production.
Vapor Blasting Equipment Market Competitive Landscape
Global majors compete with regional champions across precision engineering specialization and regulatory compliance integration. Market structure tiers between German-engineered stationary systems, North American portable equipment portfolios, and specialized wet-blast automation providers. Three archetypes dominate: capital-intensive cabinet system integrators, mobile service equipment fabricators, and robotics-convergence specialists. Competitive moves center on predictive maintenance service bundling and throughput-based contracting models that displace traditional equipment ownership.
Within the precision-engineering tier, Rösler Oberflächentechnik GmbH exemplifies German-engineered stationary system dominance for high-tolerance aerospace applications. Graco Inc. anchors North American distribution breadth across portable and stationary equipment categories. Vapormatt Ltd. occupies a specialized position in wet-blast automation for turbine blade restoration workflows. These three represent contrasting geographic and technical positioning strategies without overlapping core competency claims.
| Leading Market Players |
|---|
| Rösler Oberflächentechnik GmbH |
| Graco Inc. |
| Vapormatt Ltd. |
| Vapor Honing Technologies |
| Greener Blast Technology |
| Guyson Corporation |
| Clemco Industries Corp. |
| Sinto America |
| Vixen Surface Treatments Ltd. |
| Others |
Value Network & Pricing Analysis
Slurry process engineering talent concentration in southern Germany widens pricing-tier spreads between premium automated systems and economy-grade portable units, as labor-cost differentials compound with CE certification overhead to stratify vendor margins.
Pricing Analysis
Input-cost pass-through from fused aluminum oxide and energy-intensive smelting operations intensifies pricing pressure across equipment tiers. Three-tier pricing structure across premium, standard, and economy levels differentiates by automation depth and CE machinery directive compliance grade. Aerospace MRO buyers exhibit lowest price sensitivity due to thermal barrier coating restoration criticality, while mobile marine contractors face acute cost compression. Price differentiation hinges on closed-loop filtration integration and predictive maintenance bundling.
Supply Chain Analysis
CE machinery directive compliance and EPA NESHAP certification gating restrict vendor participation to qualified system integrators with proven safety interlock engineering. Manufacturing concentrates in Germany, the United States, and China, with Bavarian engineering clusters supplying high-tolerance aerospace cabinets. Critical inputs draw from fused aluminum oxide smelters, precision pump assemblies, and HEPA filtration media. Single-source vulnerability in abrasive media supply from Chinese export-curtailed alumina elevates procurement risk. Distribution runs through OEM-direct specification and regional job-shop equipment financing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as REACH phase-down of crystalline silica abrasives redirects demand toward premium closed-loop wet systems with certified emissions control.
For Market Incumbents: Deploy predictive maintenance service bundling to deepen account control against emerging robotics-convergence specialists. Integrate backward control over abrasive media logistics to offset alumina price volatility. Fortify Stuttgart and Munich service density before EU Green Deal industrial emissions protocols trigger replacement cycles at tier-two automotive suppliers. For New Entrants and Emerging Players: EPA NESHAP tightening in the United States opens a window for HEPA-integrated cabinet system penetration at metal fabrication facilities lacking wet-blast retrofit capacity. Target California South Bay and Dallas-Fort Worth aerospace corridors with throughput-based contracting models that displace capital equipment ownership. Pursue strategic equipment-leasing partnerships with regional job shops to bypass incumbent distribution lock-in. For Investors and Strategic Acquirers: Aerospace tier-one suppliers are the most active acquirer in this space, seeking captive finishing capabilities for additive manufacturing post-processing workflows. Five-to-ten year viability favors automated system integrators with robotics convergence competence over pure portable equipment fabricators. Monitor India defense aerospace MRO buildout as inflection indicator for geographic expansion returns.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Slurry Recovery Integration | Unifies water treatment and abrasive recycling for REACH compliance at German automotive suppliers. |
| Robotics Convergence Development | Enables consistent surface preparation for additive manufacturing post-processing at aerospace OEMs. |
| Regional Service Partnership Expansion | Establishes maintenance density in Bengaluru and COMAC service centers for defense aerospace buildout. |
| CE Machinery Directive Certification Investment | Accelerates European market entry through safety interlock and operator exposure monitoring compliance. |
| Throughput-Based Contracting Model | Displaces equipment ownership for tier-two automotive suppliers in BMW and Porsche supply chains. |
Research Methodology
Bottom-up aerospace and automotive end-use modeling reconciled against top-down equipment manufacturer supply-side tracking forms the analytical core. Primary interviews with maintenance directors at MRO facilities, plant engineers at powertrain suppliers, aftermarket service heads at job shops, and OEM procurement teams at tier-one aerospace integrators combined with secondary validation from EPA NESHAP filings, ECHA REACH registrations, SEC equipment manufacturer disclosures, and customs trade data on abrasive media flows.
Historical trendline analysis across installed base expansion and replacement cycle timing informs projection mechanics. Segmentation dimensions span product type, application criticality, end-user ownership model, and technology maturity across the analysis window. CAGRs derive from slope analysis of equipment shipment trajectories adjusted for regulatory compliance-driven acceleration in European metal fabrication and US aerospace MRO.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt alumina supply disruption or accelerated EU Green Deal implementation timelines. A model refresh is warranted upon material change in REACH enforcement intensity or MIIT emissions guideline tightening in China.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Global Loaders Market
Material Handling Equipment
Asia-Pacific Forklift Rental Market
Material Handling Equipment
Apron Feeder Market
Material Handling Equipment
Asia-Pacific Forklift Truck Market
Material Handling Equipment
Pug Mill Mixers Market
Material Handling Equipment
Tube Rotator Market
Material Handling Equipment
Conveyor Sprocket Market
Material Handling Equipment
Log Stackers Market
Material Handling Equipment
Dewatering Screen Market
Material Handling Equipment
Cable Conduit Systems Market
Material Handling Equipment
Hot-Rolling Mill and Cold-Rolling Mill Market
Material Handling Equipment
Gravity Conveyor Market
Material Handling Equipment
Global Loading Dock Lifts Market
Material Handling Equipment
Portable Conveyor Belt Market
Material Handling Equipment
Asia-Pacific Conveyors Market
Material Handling Equipment
Electric Hoist Market