
 Pug Mill Mixers Market | 2026-2036
Pug Mill Mixers Market Size, Share, and Industry Trends Forecast 2026-2036
Pug Mill Mixers Market Analytics
Steel-reinforced wear liners is shifting toward ceramic-composite alternatives in high-abrasion pug mill applications, cutting replacement frequency by half in limestone processing environments. McLanahan leverages its century-long mining equipment heritage to dominate the heavy-duty mixer segment for aggregate producers. FEECO International sustains engineering leadership through custom thermal processing integration with its pug mill platforms. DustMASTER Enviro Systems specializes in dust-controlled pug mill configurations that anchor its position in environmental remediation contracts.
A pug mill mixer is a twin-shaft, counter-rotating industrial blending device that kneads, homogenizes, and densifies materials through mechanical shear and compression, typically operating at throughput rates from 50 to 1,500 tons per hour depending on rotor diameter and paddle configuration. Its primary purpose is to produce uniformly blended, moisture-conditioned outputs for road base stabilization, fly ash conditioning, and chemical waste solidification. Continuous mixers lead volume demand in highway construction where uninterrupted material flow matches paver placement rates, while batch mixers command premium positioning in food processing and specialty chemical applications requiring formulation traceability. Heavy-duty mixers concentrate margin pools in mining and aggregate sectors where abrasion-resistant construction extends equipment life cycles.
EPA NESHAP standards for mineral processing facilities mandate enclosed material handling and dust suppression, directly shaping pug mill enclosure designs and ventilation integration requirements. OSHA silica exposure limits drive demand for sealed mixing chambers in construction material production, particularly for manufactured sand and recycled concrete aggregate operations. ASTM C979 and AASHTO specifications for soil-cement and lime-stabilized base materials define performance thresholds that equipment must consistently achieve. Stakeholders must weigh capital allocation between electric drive adoption for energy efficiency and hydraulic systems for torque density in the heaviest abrasion applications.
Market Dynamics
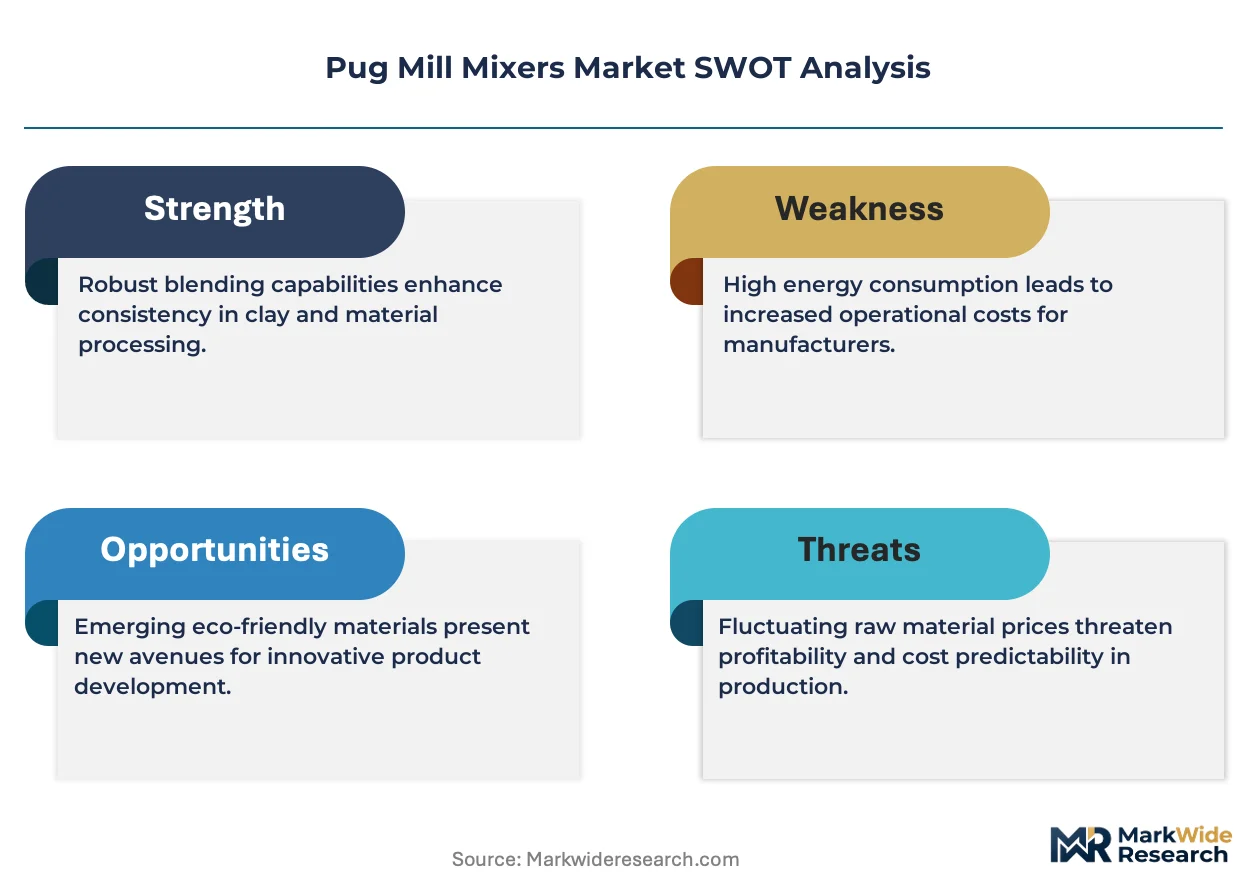
EPA NESHAP standards for mineral processing facilities are forcing aggregate producers toward enclosed pug mill configurations with integrated dust collection, compressing equipment replacement cycles and reshaping vendor procurement criteria toward compliance-first specifications.
Growth Catalysts
- India's Bharatmala Highway Initiative:This national road development program generates sustained demand for continuous soil-cement mixing equipment across state-level contracting consortia.
- Silica Exposure Limits:OSHA's tightened permissible exposure levels for respirable crystalline silica mandate sealed mixing chambers in manufactured sand operations, accelerating equipment upgrades.
- Ceramic-Composite Liners:Advanced wear materials are extending service intervals in limestone processing environments, reducing total cost of ownership for high-abrasion applications.
Market Restraints
- Steel Price Volatility:Fluctuations in alloy steel costs for rotor shafts and paddle assemblies compress margin predictability for equipment fabricators.
- Specialized Fabrication Concentration:Heavy-duty pug mill production clusters among a limited supplier base in the US Upper Midwest and Germany's Ruhr industrial region.
- Thermal Processing Integration Complexity:Custom heat-treatment add-ons extend engineering lead times and require specialized commissioning expertise that constrains deployment velocity.
Strategic Opportunities
- Environmental Remediation Contracts:Chemical waste solidification applications for contaminated site cleanup represent an underpenetrated vertical with specialized dust-control requirements.
- China's Dual Carbon Goals:National emissions reduction targets are creating procurement preferences for electrically driven mixers in infrastructure corridor projects.
- Digital Condition Monitoring:Convergence of vibration sensors with cloud-based analytics enables predictive maintenance offerings that differentiate aftermarket service portfolios.
Industry Challenges
- Commissioning Engineer Scarcity:Qualified technicians for twin-shaft alignment and paddle clearance calibration remain concentrated among legacy equipment specialists.
- ASTM C979 Certification Timelines:Third-party validation for soil-cement performance consistency extends product launch cycles for new rotor configurations.
- Legacy Control System Integration:Retrofitting enclosed pug mills with modern PLC architectures requires custom interface development for existing batching plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pug Mill Mixers Market |
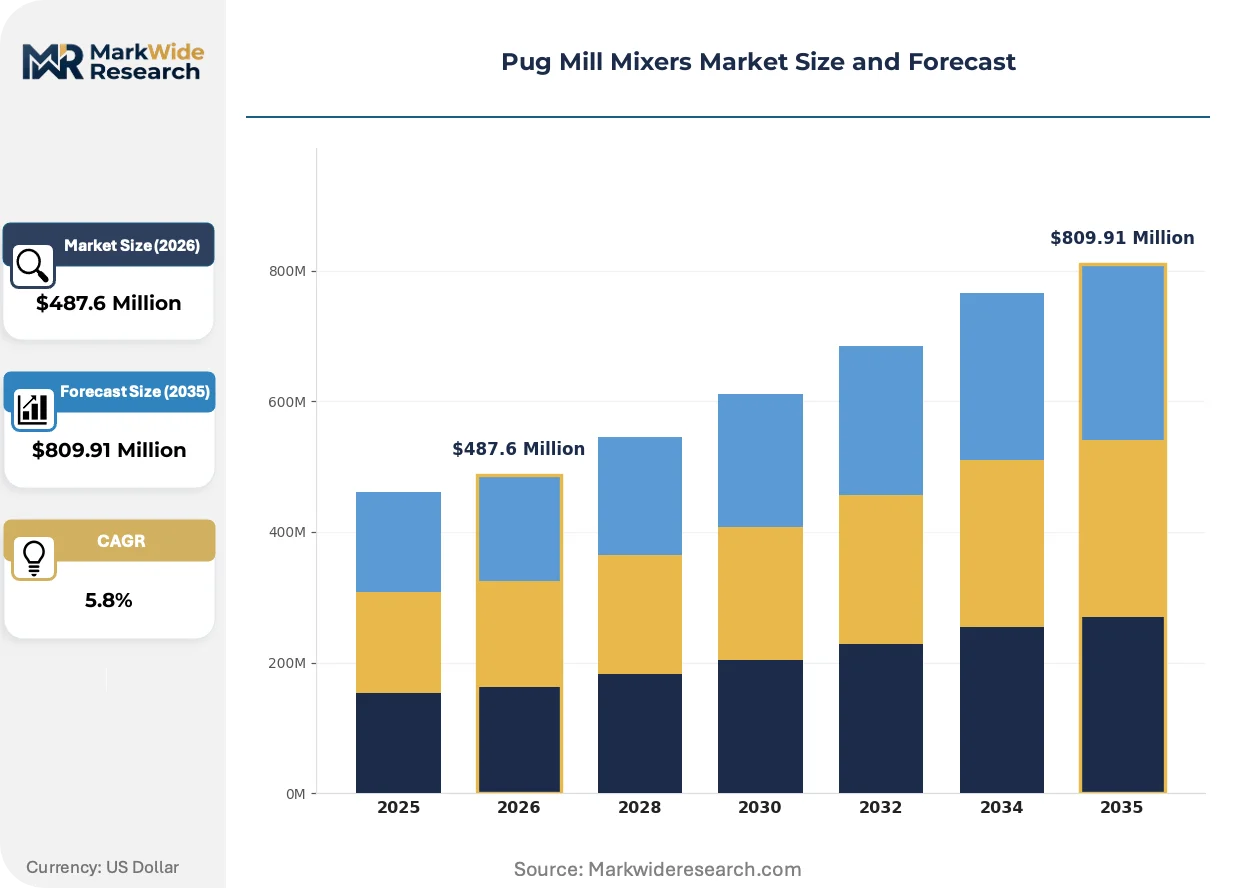
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Mixers, Batch Mixers, Heavy-duty Mixers, Inline Mixers Application: Construction, Food Processing, Chemical Manufacturing, Environmental Management End User: Manufacturers, Contractors, Distributors, Suppliers Technology: Electric, Hydraulic, Pneumatic, Mechanic |
| Companies Covered | McLanahan, FEECO International, DustMASTER Enviro Systems, Pugmill Systems, The Bonnot Company, Rock Systems, Nidec-Shimpo America Corporation, Superior Industries, Scott Equipment Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pug Mill Mixers Market Evolving Landscape
Equipment architecture is converging around modular thermal processing platforms, while regulatory pressure on particulate emissions accelerates enclosure design evolution and buyer procurement criteria sharpen on lifecycle cost rather than capital expenditure alone.
Integrated dust collection is unifying ventilation and mixing functions within single-source equipment packages. Aggregate producers in the US Southwest and Australia's quarrying belt are specifying these configurations to preempt regulatory enforcement actions. This unification is compressing the traditional separation between material handling and air quality control capital budgets, forcing single-vendor accountability for compliance outcomes.
REACH regulations on persistent organic pollutants are extending to construction material processing equipment sold into EU member states. Manufacturers must now document substance restrictions across lubricants, seals, and coating systems in technical files. German and French aggregate producers are prioritizing CE-marked equipment with full material disclosure to accelerate site permitting.
Buyer evaluation criteria are pivoting toward total cost of ownership metrics that weight energy consumption and liner replacement intervals above initial capital outlay. Large highway contractors in China and India are embedding these requirements into tender specifications, displacing price-only procurement models. This shift is most pronounced in state-backed infrastructure consortia where equipment performance guarantees extend across multi-year project horizons.
Pug Mill Mixers Market Segmentation
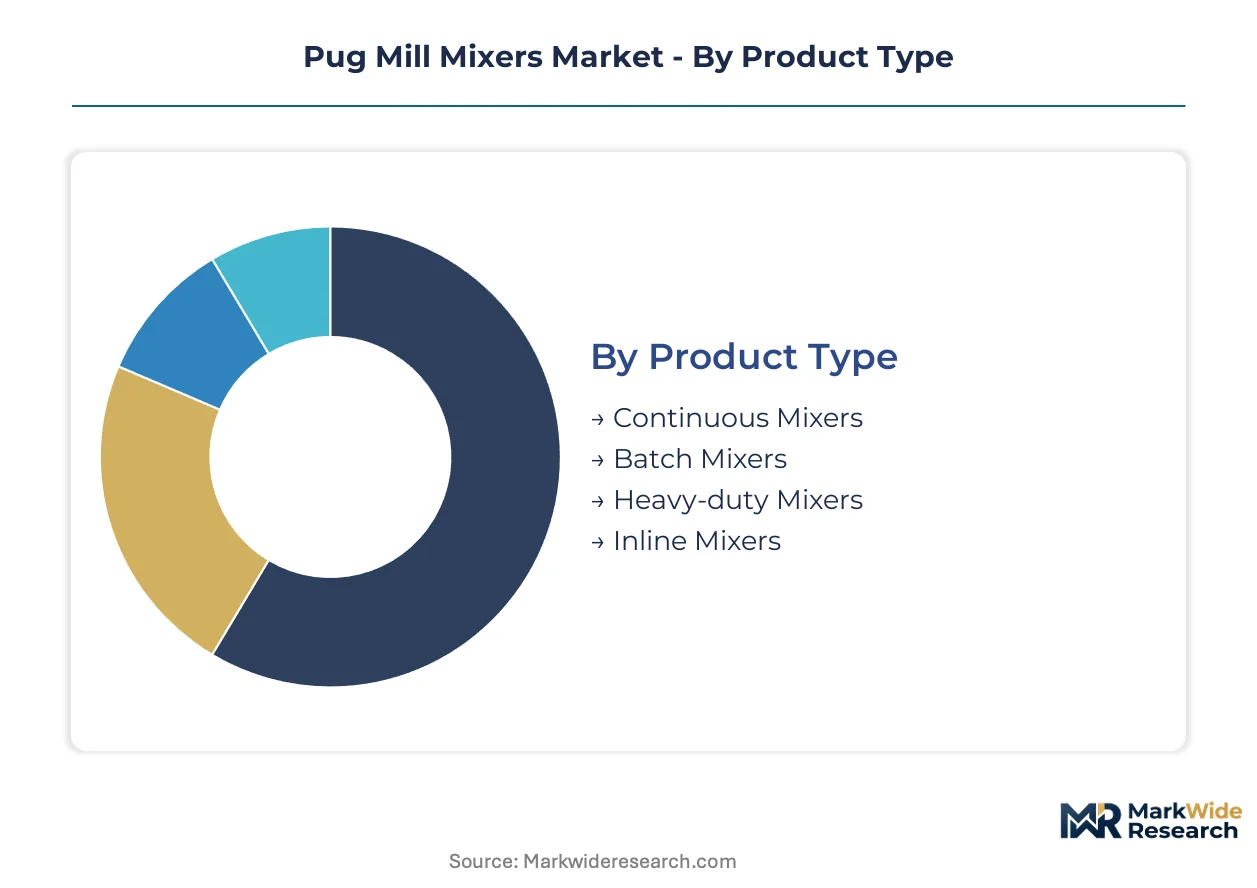
Pug mill mixer procurement patterns diverge sharply between high-volume infrastructure contractors seeking throughput reliability and specialty processors demanding formulation precision. Equipment specification cascades through four interconnected dimensions—product architecture, application environment, procurement channel, and power transmission technology.
Product Type:
Volume-driven continuous units dominate highway construction tenders, while batch configurations command premium positioning in traceability-sensitive sectors.
- Continuous Mixers:Twin-shaft counter-rotating systems operate at 50-1,500 tons per hour with uninterrupted material flow synchronized to paver placement rates. India's Bharatmala Highway Initiative and China's infrastructure corridor projects concentrate demand for these configurations where downtime costs exceed capital expenditure differentials.
- Batch Mixers:Sealed chamber designs with precise moisture and additive control serve food processing and specialty chemical applications requiring lot traceability. OSHA silica exposure limits and FDA food safety mandates drive specification toward stainless-steel construction and integrated clean-in-place systems.
- Heavy-duty Mixers:Abrasion-resistant rotor assemblies with ceramic-composite liners extend service intervals in limestone and mining aggregate operations.
- Inline Mixers:Compact footprint configurations integrate directly into existing material handling lines for retrofit installations at constrained sites.
Today's leader: Continuous Mixers. Tomorrow's challenger: Heavy-duty Mixers.
Application:
Construction sector procurement concentrates in state-backed infrastructure consortia, while environmental remediation contracts represent an underpenetrated vertical with specialized dust-control requirements.
- Construction:Road base stabilization and soil-cement mixing for highway projects generate the largest equipment volumes. EPA NESHAP standards for mineral processing facilities mandate enclosed configurations with integrated dust collection, compressing replacement cycles toward compliance-first specifications.
- Environmental Management:Chemical waste solidification for contaminated site cleanup demands sealed mixing chambers with negative-pressure ventilation. REACH regulations on persistent organic pollutants extend documentation requirements to lubricants and sealing systems in EU-sourced equipment.
- Food Processing:Sanitary-grade stainless construction with FDA-compliant surface finishes serves ingredient blending and dough conditioning applications.
- Chemical Manufacturing:Corrosion-resistant alloys and explosion-proof electrical enclosures address reactive material handling and hazardous location requirements.
Construction maintains volume dominance; Environmental Management offers the steepest expansion trajectory as remediation liabilities mount.
End User:
Procurement authority fragments between integrated manufacturers with captive maintenance capabilities and project-based contractors prioritizing rental flexibility.
- Contractors:Highway construction consortia in India and Southeast Asia drive demand for mobile continuous mixing plants with rapid site relocation features. Equipment performance guarantees extending across multi-year project horizons are displacing price-only tender evaluation.
- Manufacturers:Integrated aggregate and cement producers specify heavy-duty configurations with predictive maintenance integration, leveraging vibration sensors and cloud-based analytics to optimize liner replacement scheduling.
- Distributors:Regional equipment dealers stock mid-duty configurations for rental fleets serving seasonal construction demand.
- Suppliers:Component and aftermarket parts vendors concentrate in the US Upper Midwest and Germany's Ruhr industrial region.
Contractors set the pace for standardization; Manufacturers define the frontier for digital integration.
Technology:
Power transmission selection hinges on the torque density versus energy efficiency trade-off, with regulatory pressure accelerating electric adoption in emissions-sensitive jurisdictions.
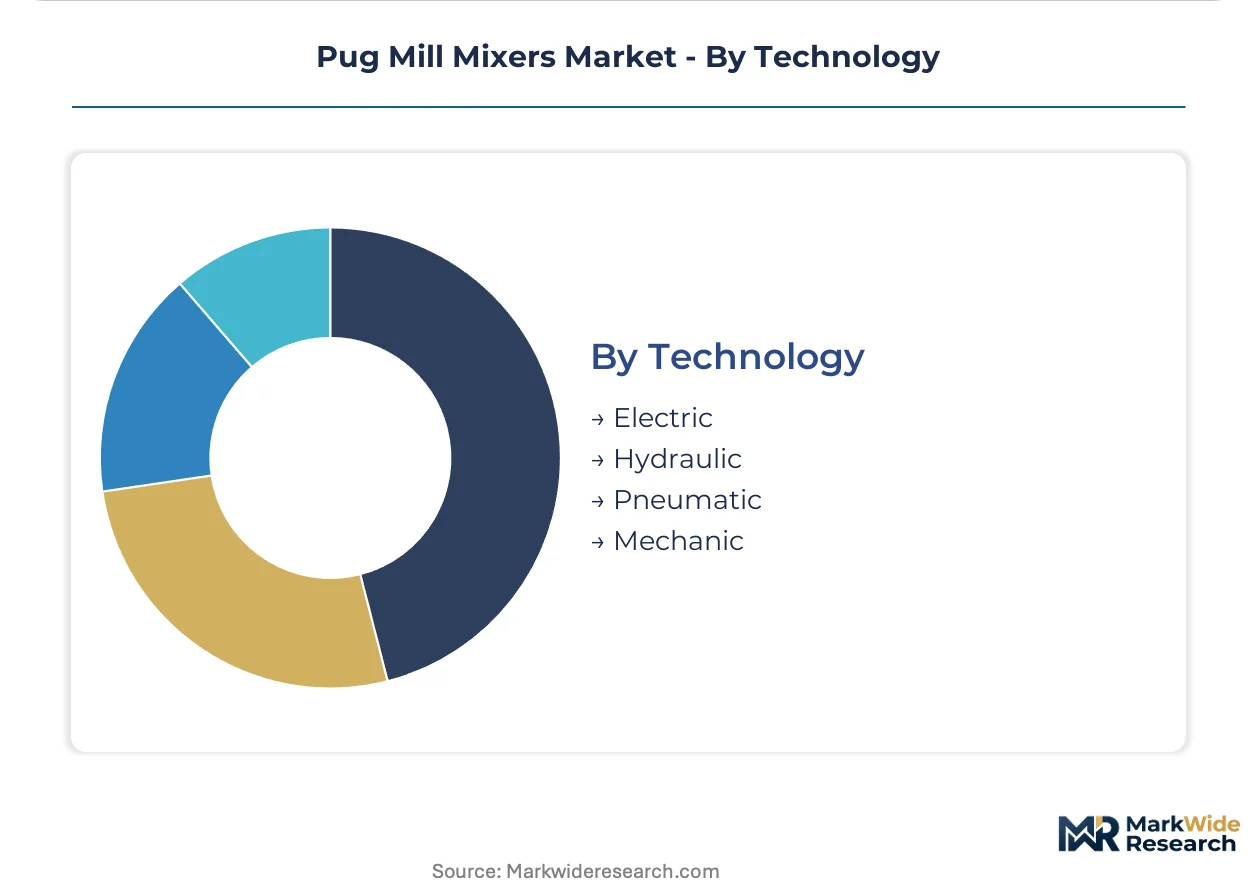
- Electric:Variable frequency drive systems deliver precise speed control and reduced energy consumption, aligning with China's dual carbon goals and EU Green Deal procurement preferences. Grid connectivity constraints limit deployment at remote quarry sites.
- Hydraulic:High-torque density configurations maintain dominance in the heaviest abrasion applications where rotor stall resistance outweighs efficiency metrics. Mining operations in Australia's quarrying belt specify these for limestone and granite processing.
- Pneumatic:Compressed air actuation serves explosion-risk environments and food-grade applications requiring oil-free operation.
- Mechanic:Direct mechanical drive systems persist in legacy installations and cost-constrained developing markets.
Electric systems gain regulatory tailwinds; Hydraulic retains the abrasion-intensive core.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr industrial region anchors heavy-duty pug mill fabrication, with specialized suppliers clustered around Dortmund and Essen serving European aggregate and mining sectors.
United States
EPA NESHAP standards for mineral processing facilities drive enclosure upgrades across Southwest quarrying operations. OSHA silica exposure limits mandate sealed mixing chambers in manufactured sand plants. Equipment fabricators in the Upper Midwest concentrate production of abrasion-resistant rotor assemblies for limestone processing.
China
Infrastructure corridor projects generate sustained procurement of continuous mixing equipment synchronized to paver placement rates. Dual carbon goals create procurement preferences for electrically driven mixers in state-backed highway construction. Yangtze River Delta manufacturers supply ceramic-composite liner systems to domestic aggregate producers.
India
The Bharatmala Highway Initiative generates multi-year equipment demand across state-level contracting consortia. Central Pollution Control Board emissions guidelines push road contractors toward dust-controlled pug mill configurations. Equipment deployment concentrates in Maharashtra and Gujarat where highway density expansion accelerates.
Australia
Quarrying belt operations in Western Australia and Queensland specify hydraulic drive systems for granite and limestone processing. State environmental protection authorities enforce particulate matter limits at aggregate sites. Perth and Brisbane equipment distributors stock mobile continuous mixing plants for remote site deployment.
Germany
REACH regulations on persistent organic pollutants extend documentation requirements to lubricants and sealing systems in EU-sourced equipment. CE marking with full material disclosure accelerates site permitting for aggregate producers. Ruhr region fabricators dominate heavy-duty mixer exports to Middle Eastern and African mining operations.
Pug Mill Mixers Market Competitive Landscape
Global majors compete with regional champions across fabrication specialization and aftermarket service density. The supplier base organizes around three tiers: century-established mining equipment heritage firms, custom thermal processing integrators, and environmental remediation specialists. Strategic moves concentrate on ceramic-composite liner technology licensing and predictive maintenance platform partnerships.
Among heritage mining equipment fabricators, McLanahan exemplifies the heavy-duty abrasion-resistant segment. FEECO International occupies a position within custom thermal processing integration archetypes. DustMASTER Enviro Systems represents the environmental compliance specialization tier, anchoring dust-controlled configuration demand. These three firms illustrate how vendor positioning fragments across application-specific engineering capabilities rather than converging on undifferentiated volume production.
| Leading Market Players |
|---|
| McLanahan |
| FEECO International |
| DustMASTER Enviro Systems |
| Pugmill Systems |
| The Bonnot Company |
| Rock Systems |
| Nidec-Shimpo America Corporation |
| Superior Industries |
| Scott Equipment Company |
| Others |
Value Network & Pricing Analysis
Ceramic-composite liner adoption is compressing lifecycle cost economics while redistributing fabrication margins toward specialized coating suppliers in Germany and Japan. This materials transition simultaneously elevates upfront equipment pricing and concentrates supply relationships among a narrower tier of qualified vendors.
Pricing Analysis
Alloy steel cost pass-through dominates equipment pricing dynamics, with rotor shaft and paddle assembly materials accounting for substantial build-cost sensitivity. Price differentiation hinges on abrasion-resistance certification tier and integrated dust-collection bundling, with highway contractors in India and China exhibiting highest price sensitivity due to tender-based procurement, while mining operators in Australia prioritize lifecycle cost over capital outlay. Pricing pressure stems from steel volatility compressing fabricator margins, forcing tiered pricing structures that separate premium ceramic-lined configurations from standard steel-reinforced units.
Supply Chain Analysis
Abrasion-resistant alloy supply rests on German Ruhr region foundries and US Upper Midwest steel producers, with ceramic-composite liner systems drawing from Japanese specialty coating manufacturers and Yangtze River Delta powder metallurgy specialists. Critical dependencies include nickel-chromium alloy feedstock, tungsten carbide overlay materials, and precision-machined rotor bearings. Single-source vulnerability concentrates in specialized twin-shaft gearbox assemblies fabricated by a limited supplier base. Distribution runs through regional equipment dealers stocking mid-duty rental fleets and direct OEM relationships for heavy-duty custom configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where India's Bharatmala infrastructure spending contrasts with EU REACH compliance costs, creating divergent margin pools for regionally configured product lines.
For Market Incumbents: Anticipate margin compression from Chinese electric-drive competitors by deepening captive supply of ceramic-composite liner systems through backward integration into coating technology. Anchor defensive positioning around EPA NESHAP compliance bundling, where integrated dust-collection expertise creates switching costs for US aggregate producers facing enforcement escalation.
For New Entrants and Emerging Players: Regional equipment dealers represent the most accessible channel partner type for penetrating India's state-level highway contracting consortia without direct OEM competition. Environmental remediation contracts for chemical waste solidification offer white-space expansion with specialized negative-pressure ventilation requirements that heritage mining fabricators underserve. Target mobile continuous mixing configurations with rapid site relocation features for Southeast Asian road contractors.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier thermal processing integrators lacking predictive maintenance platforms but holding custom engineering relationships with cement producers. Long-term viability favors vendors bridging heavy-duty abrasion resistance with digital condition monitoring capabilities. Watch commissioning engineer scarcity as an inflection signal—concentration of qualified twin-shaft alignment technicians indicates consolidation pressure among legacy specialists.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic-Composite Liner Licensing | Technology partnerships with Japanese coating specialists extend service intervals for limestone processors. |
| Predictive Maintenance Platform Integration | Vibration sensor convergence with cloud analytics differentiates aftermarket service portfolios for mining operators. |
| Electric Drive Configuration Expansion | Variable frequency systems align with China's dual carbon procurement preferences in infrastructure corridors. |
| Environmental Remediation Vertical Entry | Sealed chamber designs with negative-pressure ventilation capture chemical waste solidification contracts. |
| Regional Fabrication Footprint Addition | India-based assembly reduces delivery costs for Bharatmala highway equipment tenders. |
Research Methodology
Multiple input streams — equipment procurement managers at highway construction consortia, maintenance directors at aggregate processing facilities, aftermarket service heads at regional dealers, and regulatory compliance officers — were reconciled against customs trade records, SEC filings from disclosed equipment suppliers, EPA enforcement databases, and AASHTO specification documentation. Bottom-up triangulation across primary stakeholder interviews and secondary validation sources anchored volume estimates. Top-down cross-checks against infrastructure spending disclosures from India's NHAI and China's Ministry of Transport confirmed demand-side calibration.
Data-stream reconciliation fed analytical frameworks modeling continuous versus batch mixer deployment, electric versus hydraulic drive adoption, and construction versus environmental management application splits across the projection horizon. CAGRs derived from equipment replacement cycle analysis, regulatory compliance deadline clustering, and liner technology substitution curves. Industry-specific forecast inputs included EPA NESHAP enforcement trajectory assumptions and silica exposure limit implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to steel price volatility, commissioning engineer availability, and REACH substance restriction expansion. Assumptions reflect documented regulatory schedules and disclosed infrastructure spending commitments. A small set of triggers — alloy supply disruption, accelerated electric-drive subsidies, or silica enforcement escalation — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Vertical Platform Lift Market
Material Handling Equipment
Scraper Conveyor Market
Material Handling Equipment
Heavy Equipment Movers Market
Material Handling Equipment
Pick and Carry (PNC) Crane Market
Material Handling Equipment
Circular Stacker and Reclaimer Market
Material Handling Equipment
Global Large Conveyor Chain Market
Material Handling Equipment
Crawler Crane Market
Material Handling Equipment
Asia-Pacific Forklift Truck Market
Material Handling Equipment
Firewood Processors Market
Material Handling Equipment
Portable Forklift Ramps Market
Material Handling Equipment
Wagon Tipplers Market
Material Handling Equipment
Air Hose Market
Material Handling Equipment
Slow Speed Shredding Machines Market
Material Handling Equipment
Apron Feeder Market
Material Handling Equipment
Roller Crusher Market
Material Handling Equipment
North America Conveyor Belt Market