
 Log Stackers Market | 2026-2036
Log Stackers Market Size, Share, and Industry Trends Forecast 2026-2036
Log Stackers Market Analytics
Modular attachment configurations for log stackers is pivoting procurement patterns as buyers prioritize swap-ready grapple systems over fixed-specification machines. Komatsu leverages its integrated forestry electronics architecture to sustain premium positioning in automated boom-control segments. John Deere anchors North American distribution through dealer networks that dominate regional parts availability. Volvo Construction Equipment differentiates via telematics-enabled fleet management platforms that extend service-contract attach rates.
A log stacker is a heavy-material-handling machine engineered with telescopic booms reaching 25–35 feet, rated load capacities of 12–25 metric tons, and purpose-built grapple heads for sorting, loading, and stacking cut timber in sawmill yards and forest landings. Hydraulic log stackers command the dominant installed base due to power density requirements in high-throughput pulp and paper operations, though electric variants are gaining traction in European yard operations where emission zones restrict diesel equipment. Pulp and paper represents the most concentrated margin pool among industry verticals because downtime costs at integrated mills justify premium pricing for reliability-certified units. Mobile deployment configurations lead unit shipments as contractors prioritize equipment transfer flexibility across seasonal harvesting sites.
EPA Tier 4 Final and Stage V emission frameworks from the US and Europe have forced engine redesigns that add cost but create compliance-based differentiation for manufacturers with certified powertrain portfolios. OSHA yard-safety directives and ISO 19014 functional-safety standards shape operator-guard specifications and access-platform geometries that influence R&D allocation. Stakeholders must monitor battery-electric range and charging infrastructure maturation in Nordic forestry clusters to time capital commitments between diesel replacement cycles and electrification tipping points.
Market Dynamics
EU Green Deal emission benchmarks are compressing replacement cycles for hydraulic log stackers as Nordic forestry operators accelerate fleet renewals to meet tightening yard-equipment specifications.
Growth Catalysts
- EU Green Deal benchmarks:Forestry operators in Sweden and Finland face mandatory emission reductions that drive replacement demand for certified equipment.
- Mechanized harvesting expansion:High-throughput pulp and paper operations require power-dense hydraulic units with extended reach capabilities.
- Telematics-enabled fleet management:Contractors prioritize equipment with real-time monitoring to optimize utilization across seasonal harvesting sites.
Market Restraints
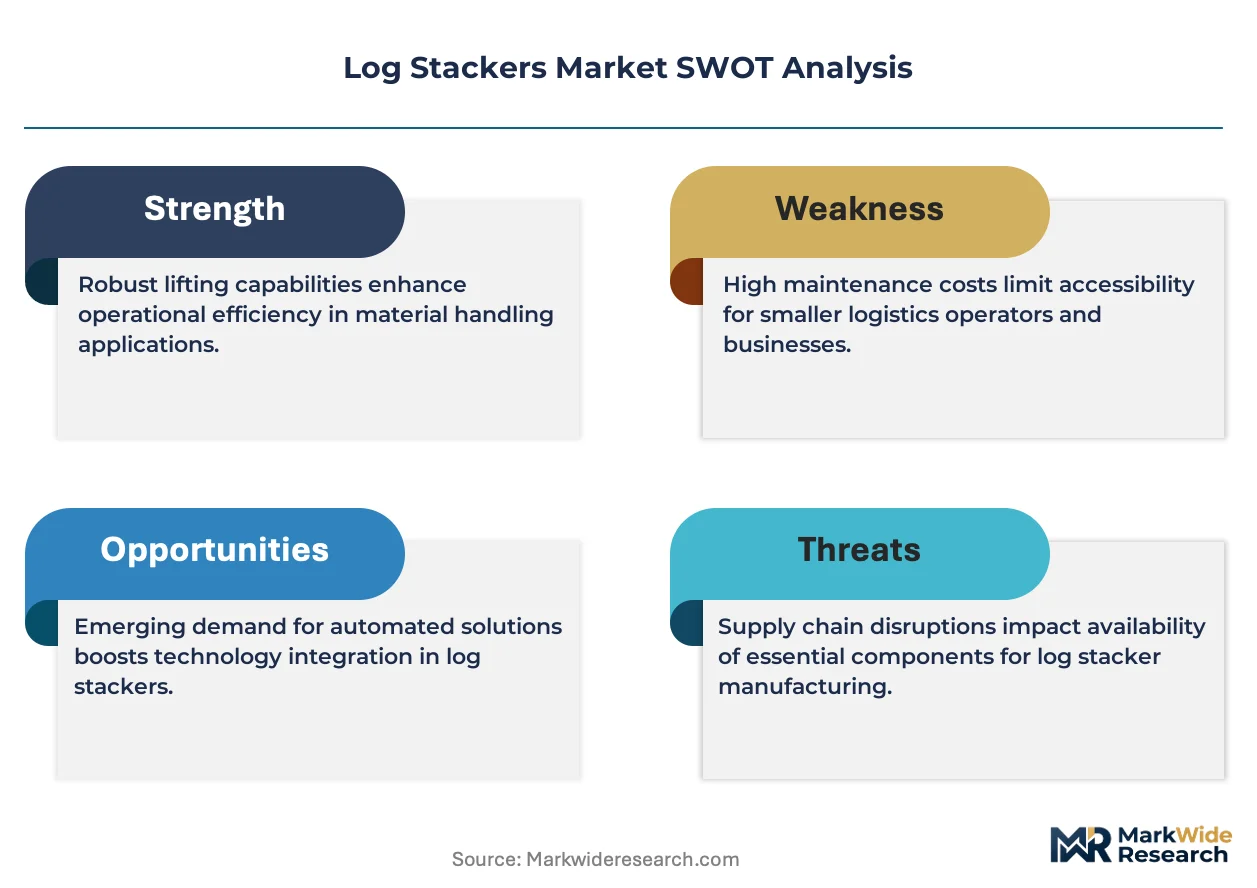
- Engine redesign costs:EPA Tier 4 Final and Stage V compliance requirements add capital burden to powertrain development.
- Battery-electric range limitations:Current energy density constraints restrict electric variant deployment to short-cycle yard operations.
- Specialized grapple system concentration:Modular attachment standardization remains incomplete across manufacturer ecosystems.
Strategic Opportunities
- Swedish charging infrastructure maturation:Public-private forestry cluster investments enable electric equipment pilot programs.
- ISO 19014 functional-safety certification:First-mover advantage accrues to manufacturers with validated operator-guard platforms.
- Service-contract unbundling:Independent maintenance providers capture aftermarket revenue from telematics-integrated diagnostics.
Industry Challenges
- Hydraulic technician scarcity:Specialized boom-control calibration expertise concentrates with OEM dealer networks.
- Dual powertrain inventory complexity:Dealers must stock diesel and electric parts simultaneously during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Log Stackers Market |
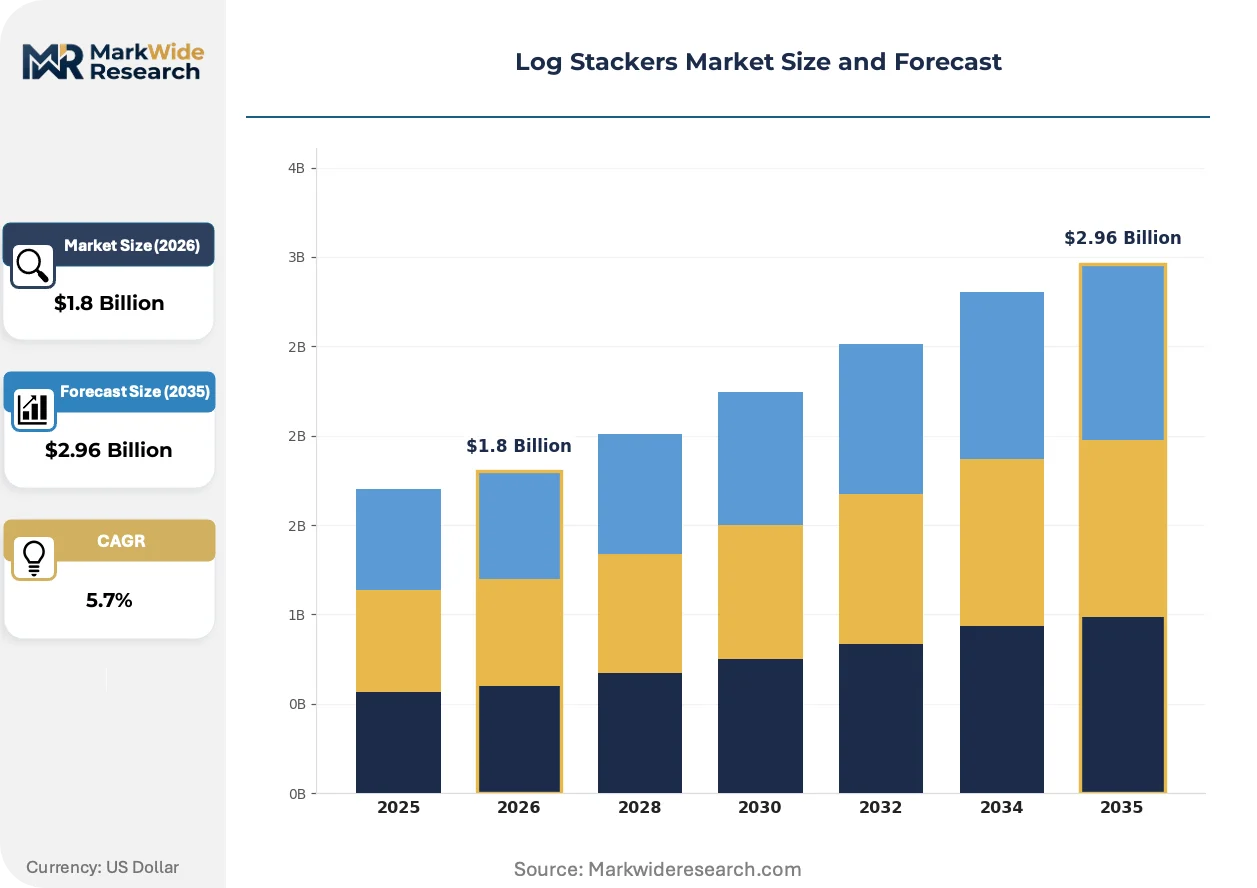
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Log Stackers, Electric Log Stackers, Manual Log Stackers, Pneumatic Log Stackers Industry Vertical: Forestry, Construction, Pulp & Paper, Wood Processing End User: Loggers, Lumber Mills, Wood Manufacturers, Contractors Deployment: On-site, Off-site, Mobile, Fixed |
| Companies Covered | John Deere, Komatsu, Caterpillar, Liebherr, Konecranes, Doosan Corporation, Volvo Construction Equipment, Hyundai Construction Equipment, SANY Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Log Stackers Market Evolving Landscape
Automation architectures and emission-compliant powertrains are reconfiguring equipment specifications as buyers prioritize data-integrated machines over conventional hydraulic platforms.
Electrified drivetrain technology is integrating battery-electric propulsion with regenerative boom hydraulics to extend operating range in intermittent-duty cycles. Pulp and paper mills with captive yard operations pilot these configurations during scheduled maintenance windows. The technology is integrating emission-zone compliance with total cost of ownership compression for high-utilization sites.
Stage V emission frameworks from European regulators mandate particulate matter and nitrogen oxide reductions that force engine architecture changes. Manufacturers with certified powertrain portfolios capture specification-driven procurement in EU member states. Integrated mills in Finland and Sweden now require compliance documentation as a gate criterion for fleet approval.
Modular grapple attachment systems are displacing fixed-specification purchases as contractors demand swap-ready configurations for multi-product handling. Dealer networks in Nordic forestry clusters stock standardized quick-coupler inventories to support this flexibility. Sawmill yards in Sweden demonstrate the highest penetration of reconfigurable boom systems.
Log Stackers Market Segmentation
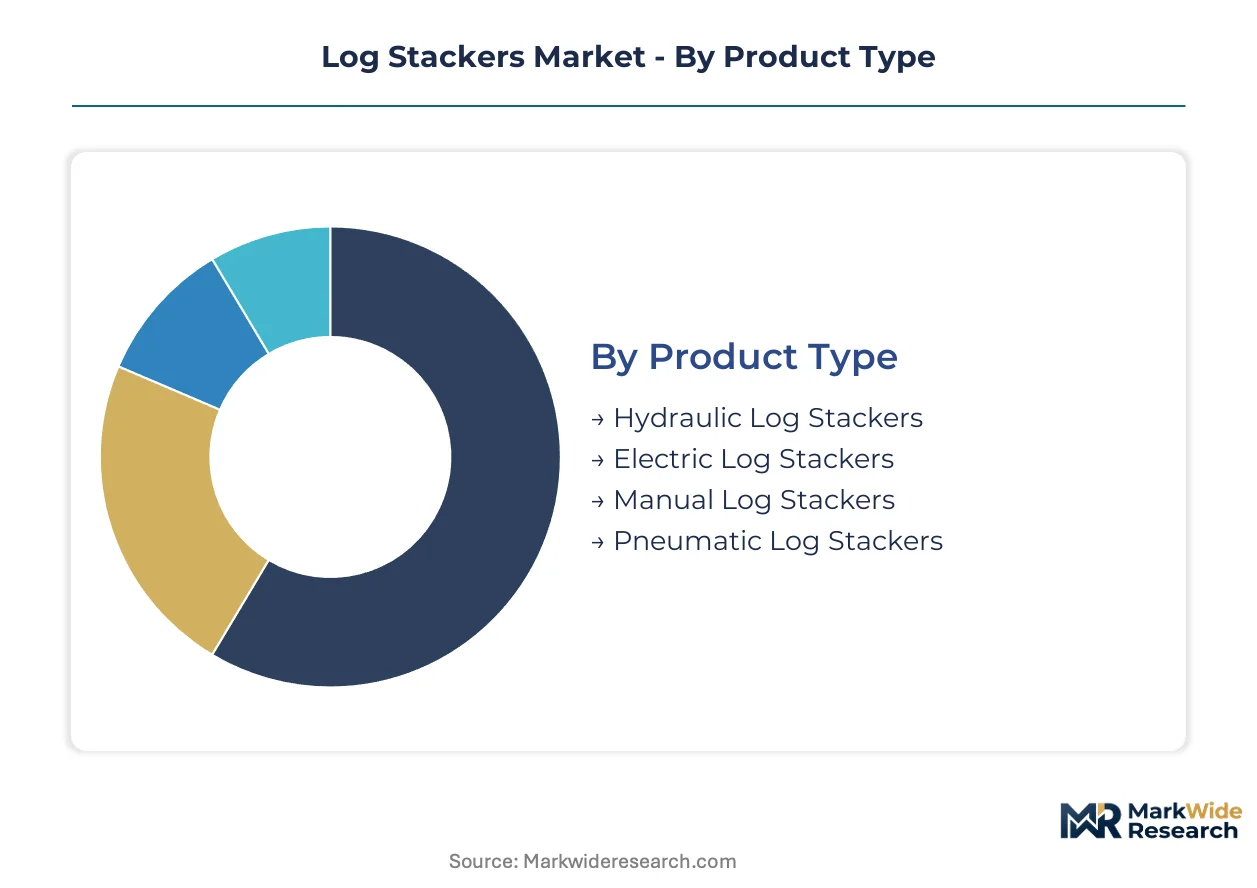
Equipment specification choices in log stacker procurement directly determine compliance eligibility and operational uptime in regulated forestry environments. Buyers segment purchases across powertrain technology, industry application, and deployment flexibility to align capital cycles with emission mandates and yard logistics requirements.
Product Type:
Fleet renewal decisions in Nordic forestry clusters are compressing replacement intervals as emission benchmarks disqualify legacy hydraulic units from tender eligibility.
- Hydraulic Log Stackers:These units deploy high-pressure fluid power systems delivering 12–25 metric ton lift capacities with telescopic boom reach extending 25–35 feet. Demand concentrates in Finnish and Swedish pulp and paper mills where high-throughput operations require power density for continuous duty cycles; EU Green Deal compliance documentation now gates fleet approval for new procurements.
- Electric Log Stackers:Battery-electric propulsion integrates with regenerative boom hydraulics to extend operating range in intermittent-duty yard cycles. Swedish sawmill operators pilot these configurations during scheduled maintenance windows as public-private charging infrastructure investments mature in forestry clusters; emission-zone restrictions in European yards accelerate specification shifts.
- Manual Log Stackers:Human-powered lifting mechanisms serve small-scale woodlot operations with sub-metric-ton capacity requirements.
- Pneumatic Log Stackers:Compressed-air systems address niche applications in explosion-sensitive processing environments.
Volume placements concentrate in hydraulic configurations; the faster expansion belongs to electric variants.
Industry Vertical:
Margin capture potential varies sharply across verticals based on downtime cost sensitivity and certification premium willingness.
- Forestry:Mechanized harvesting operations in Sweden and Finland drive replacement demand for high-reach units with automated boom control; seasonal site transfer requirements prioritize mobile deployment specifications.
- Pulp & Paper:Integrated mills with captive yard operations justify premium pricing for reliability-certified units where unplanned downtime costs cascade through continuous-process production lines.
- Construction:General material handling applications absorb standardized units without grapple specialization.
- Wood Processing:Sawmill yards demonstrate highest penetration of modular grapple systems for multi-product handling flexibility.
Revenue concentration sits with pulp and paper; forestry applications are climbing the fastest.
End User:
Procurement authority and maintenance capability distribution shape channel strategy and service contract attach rates.
- Loggers:Independent contractors prioritize equipment transfer flexibility across seasonal harvesting sites; telematics-enabled fleet management platforms optimize utilization rates in dispersed operations.
- Lumber Mills:Permanent yard operations favor fixed installations with quick-coupler grapple inventories for product mix reconfiguration.
- Wood Manufacturers:Secondary processing facilities require standardized handling equipment without forestry-specific boom extensions.
- Contractors:Multi-site operators demand mobile deployment configurations with dealer network parts availability guarantees.
Contractor segment dominates unit shipments; lumber mills show steepest expansion trajectory for automated systems.
Deployment:
Capital allocation efficiency depends on matching mobility specifications to operational site stability and transfer frequency.
- Mobile:Self-propelled configurations with highway-transport compatibility lead unit shipments as Swedish and Finnish contractors prioritize fleet redeployment across dispersed harvesting concessions; telematics integration enables real-time positioning for logistics coordination.
- Fixed:Permanent foundation installations serve high-volume pulp and paper yards with dedicated material flows; ISO 19014 functional-safety certification requirements concentrate R&D investment in operator-guard platforms for these high-utilization sites.
- On-site:Restricted-radius operations within single facility boundaries.
- Off-site:Remote landing operations requiring autonomous power and maintenance capability.
Mobile configurations capture volume leadership; fixed installations gain share fastest in integrated mill expansions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finnish special economic zones for sustainable forestry equipment accelerate capital deployment toward emission-compliant machinery clusters in Nordic timber processing corridors.
Sweden
Mechanized harvesting operations in Västerbotten and Norrbotten drive fleet renewal demand for high-reach hydraulic units with automated boom control. EU Green Deal emission benchmarks compress replacement cycles as tender documentation now mandates Stage V compliance certification. The Södra Cell cluster in Värmland pilots electric log stacker configurations alongside public-private charging infrastructure investments.
Finland
Integrated pulp and paper mills in Kymenlaakso and Central Finland justify premium procurement for reliability-certified equipment where unplanned downtime cascades through continuous-process lines. The national energy authority promotes battery-electric yard equipment through targeted capital allowance programs. Metsä Group operations in Äänekoski demonstrate highest penetration of modular grapple systems for multi-product handling flexibility.
Germany
Sawmill yards in Bavaria and Baden-Württemberg absorb standardized handling equipment with quick-coupler inventories for product mix reconfiguration. KBA emission certification requirements for non-road mobile machinery shape procurement gate criteria. The Stuttgart industrial corridor concentrates dealer network parts availability for contractor fleet maintenance.
United States
Pacific Northwest timber operators in Oregon and Washington prioritize mobile deployment configurations with highway-transport compatibility across dispersed harvesting concessions. EPA Tier 4 Final frameworks force engine architecture redesigns that add capital burden to powertrain development. The Puget Sound cluster anchors North American distribution networks for regional parts availability guarantees.
Canada
British Columbia forestry contractors demand telematics-enabled fleet management platforms to optimize utilization rates across seasonal harvesting sites. Health Canada and PMRA coordinate emission standards alignment with US EPA benchmarks to preserve cross-border equipment certification reciprocity. The Vancouver Island sawmill corridor demonstrates concentrated demand for extended-reach hydraulic units in high-throughput yard operations.
Log Stackers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered equipment specification bands. The vendor base organizes around three strategic archetypes: integrated construction-equipment conglomerates with forestry divisions, dedicated material-handling specialists, and regional fabrication houses serving price-sensitive contractor segments. Consolidation pressure concentrates among mid-scale operators seeking scale economies in emission-compliant powertrain development. Geographic expansion and strategic partnerships constitute the dominant competitive moves as manufacturers establish localized service networks.
Among construction-equipment conglomerates, Komatsu and Volvo Construction Equipment exemplify integrated technology platforms with telematics-enabled fleet management capabilities. John Deere anchors the North American market through established dealer network density. These three entities occupy positions across premium and mid-tier specification bands, representing divergent approaches to emission compliance architecture and aftermarket service contract attach rates.
| Leading Market Players |
|---|
| John Deere |
| Komatsu |
| Caterpillar |
| Liebherr |
| Konecranes |
| Doosan Corporation |
| Volvo Construction Equipment |
| Hyundai Construction Equipment |
| SANY Group |
| Others |
Value Network & Pricing Analysis
Steel and hydraulic component costs cascade through three-tier pricing structures across premium, standard, and economy levels as emission-compliant powertrain investments concentrate procurement decisions among certified manufacturers. Swedish and Finnish forestry operators absorb tier premiums for Stage V documentation while dealer networks manage dual inventory complexity during diesel-to-electric transitions.
Pricing Analysis
Margin tightening in mid-tier configurations reflects engine redesign cost absorption from EPA Tier 4 Final and Stage V compliance mandates. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and telematics integration depth, with automated boom-control units commanding premium positioning. Pricing pressure intensifies in economy tiers as regional fabrication houses compete on stripped specifications. Independent contractors in dispersed harvesting operations exhibit highest price sensitivity; integrated pulp and paper mills accept reliability-certified premiums where downtime costs cascade through continuous-process lines.
Supply Chain Analysis
Regional distribution centers in Germany, Sweden, and Finland anchor hub-and-spoke patterns serving Nordic forestry clusters with quick-coupler grapple inventories. High-pressure hydraulic systems draw from specialized foundries in Germany and Italy, while battery-electric powertrains rest on South Korean and Chinese cell suppliers. Single-source vulnerability concentrates in certified engine architectures compliant with EU Green Deal benchmarks. Distribution runs through OEM-captive dealer networks dominating parts availability for hydraulic technician expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-electric propulsion with regenerative boom hydraulics is displacing conventional diesel platforms in yard operations, compressing replacement cycles as emission zones mature charging infrastructure.
For Market Incumbents: Anticipate margin compression from dual powertrain inventory obligations by consolidating service-contract attach rates through telematics-enabled diagnostics platforms. Backward integration into battery-electric powertrain development secures specification control as EU Green Deal benchmarks tighten tender eligibility. Channel control through hydraulic technician certification programs defends against independent maintenance providers capturing aftermarket revenue. For New Entrants and Emerging Players: Begin with modular grapple attachment standardization gaps in wood processing verticals where quick-coupler interoperability remains incomplete across manufacturer ecosystems. Swedish sawmill yards present most penetrable entry points given public-private charging infrastructure investments enabling electric equipment pilot programs. Telematics-integrated fleet management platforms offer differentiation against established dealer network density. For Investors and Strategic Acquirers: Finnish special economic zone designation for sustainable forestry equipment is the leading indicator that capital deployment timing favors emission-compliant machinery clusters over legacy hydraulic exposure. Mid-scale operators seeking scale economies in certified powertrain development represent acquisition target archetypes with technology-transition optionality. Monitor battery-electric range maturation in intermittent-duty cycles as inflection signal for capital commitment timing between diesel replacement and electrification tipping points.| Strategic Initiative | Industry Significance |
|---|---|
| Emission-Compliant Powertrain Certification | Stage V documentation gates fleet approval for Swedish and Finnish tender eligibility. |
| Telematics Platform Integration | Real-time monitoring optimizes contractor utilization across seasonal harvesting concessions. |
| Modular Grapple System Standardization | Quick-coupler interoperability captures wood processing demand for multi-product flexibility. |
| Charging Infrastructure Partnership | Public-private forestry cluster investments enable electric equipment pilot programs in Sweden. |
| Service Contract Unbundling | Independent diagnostics providers capture aftermarket revenue from integrated telematics. |
Research Methodology
Independent corroboration across maintenance directors at pulp and paper mills, OEM procurement teams at construction-equipment manufacturers, aftermarket service heads at dealer networks, and hydraulic technician training programs underwrites the qualitative findings. Secondary validation draws from EPA emission certification databases, EU Green Deal implementation tracking, Stage V compliance registries, and forestry equipment trade flow records. Bottom-up unit shipment analysis triangulates with top-down market sizing across powertrain technology and deployment configuration segments.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include powertrain architecture, industry vertical application, deployment mobility specification, and regional regulatory cluster alignment. CAGRs derive from replacement cycle compression analysis and electrification penetration scenarios. Forecast inputs incorporate EU Green Deal benchmark implementation schedules and Nordic charging infrastructure deployment trajectories.
Underlying measurement precision varies by segment; electric log stacker projections carry tighter precision than hydraulic legacy estimates given pilot program visibility. Forecasts reflect assumptions on emission zone expansion and battery energy density improvement curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Fork Lift Attachments Market
Material Handling Equipment
Sweep Depalletizers Market
Material Handling Equipment
High-Precision Gear Reducer Market
Material Handling Equipment
Telehandler Market
Material Handling Equipment
Global Mechanical Seals Market
Material Handling Equipment
Hydraulic Hoist Market
Material Handling Equipment
Roller Crusher Market
Material Handling Equipment
Dock Levelers Market
Material Handling Equipment
Electric Hoist Market
Material Handling Equipment
Material Handling Automation Market
Material Handling Equipment
Industrial Static Equipment Market
Material Handling Equipment
Apron Feeder Market
Material Handling Equipment
Europe Forklift Truck Market
Material Handling Equipment
North America Industrial Duct for Dust Collection Market
Material Handling Equipment
Light Duty Telehandler Market
Material Handling Equipment
Construction Lifts Market