
 Asia-Pacific Conveyors Market | 2026-2036
Asia-Pacific Conveyors Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Conveyors Market Outlook
The divergence between premium automated systems and commodity manual conveyors is realigning procurement patterns across Asia-Pacific manufacturing hubs. Daifuku Co. Ltd. leverages its vertical integration in airport baggage and factory automation to command premium positioning in Japan and Southeast Asia. Murata Machinery Ltd. competes through specialized clean-room conveyor solutions for semiconductor and pharmaceutical clients. Interroll Holding AG anchors its regional presence with modular roller platforms that scale from mid-tier warehouses to large distribution centers.
Asia-Pacific conveyors are mechanical handling devices engineered to transport bulk materials or discrete items along predetermined paths, typically specified by load capacity per meter, belt speed in meters per second, and drive power ratings. These systems serve as the circulatory infrastructure of modern manufacturing, warehousing, and logistics operations, enabling continuous flow from raw material intake through finished goods dispatch. Belt conveyors dominate bulk handling applications in mining and food processing across Australia and Indonesia, while roller conveyors capture margin pools in e-commerce sortation hubs where modularity and throughput velocity determine total cost of ownership. Automated technology segments are gaining fastest in automotive final assembly and pharmaceutical packaging, though manual and hybrid systems still occupy substantial share in cost-sensitive Southeast Asian markets.
China's MIIT enforces GB standards on industrial equipment efficiency that directly shape conveyor motor specifications and drive system certifications for domestic and export-bound manufacturers. Japan's METI promotes JIS-compliant smart factory integrations that require conveyor systems with embedded sensors and IoT connectivity protocols. India's BIS mandates mechanical safety standards for material handling equipment that influence design choices for steel-framed heavy-duty installations. Stakeholders must weigh regulatory compliance timelines against automation upgrade cycles when allocating capital across multi-country production networks.
Market Dynamics
China's dual carbon goals under MEE directives are compressing upgrade cycles for industrial conveyors across Asia-Pacific manufacturing networks. Energy-efficiency mandates now override depreciation schedules, forcing capital redeployment toward regenerative drive systems and low-friction belt materials before standard replacement timelines.
Growth Catalysts
- E-commerce fulfillment density:Southeast Asian parcel hubs in Indonesia, Vietnam, and Thailand are deploying modular roller systems to handle cross-border shipment volumes. Automated sortation infrastructure is expanding faster than warehouse stock.
- MIIT efficiency mandates:China's GB standards on motor efficiency are disqualifying legacy conveyor drives from domestic production lines. Export-oriented manufacturers must certify compliance to maintain market access.
- Pharmaceutical corridor automation:India's CDSCO-aligned manufacturing clusters around Hyderabad and Mumbai are retrofitting clean-room conveyor lines to meet EU MDR and US FDA inspection protocols for active pharmaceutical ingredient exports.
Market Restraints
- Steel input volatility:Conveyor frame and roller fabrication depends on regional hot-rolled coil pricing, which fluctuates with Chinese export quotas and Indonesian nickel supply disruptions.
- Drive component concentration:Precision gearmotors and variable frequency drives for heavy-duty systems concentrate in Japanese and German supplier bases, exposing buyers to extended lead times and currency risk.
- Substitution by autonomous mobile robots:Flexible AMR fleets are capturing intralogistics tasks previously assigned to fixed conveyor arrays in high-mix, low-volume distribution operations.
Strategic Opportunities
- Vietnam electronics manufacturing:Underpenetrated conveyor automation in northern industrial zones around Bac Ninh and Hai Phong offers first-mover positioning as Samsung and Apple suppliers localize supply chains.
- Food-grade modular belting:Convergence of antimicrobial polymer formulations and quick-release tensioning systems is opening hygienic design applications in Australian dairy and Southeast Asian aquaculture processing.
- India PLI scheme tailwinds:Production-linked incentives for pharmaceutical and electronics manufacturing are accelerating capital expenditure timelines for automated material handling in greenfield facilities.
Industry Challenges
- Mechatronics skill scarcity:Conveyor commissioning and predictive maintenance require technicians fluent in PLC programming, vibration analysis, and IoT sensor calibration. Training pipelines lag deployment schedules across Indonesia and the Philippines.
- Legacy system integration friction:Brownfield automotive and textile plants in India and Thailand operate mechanical lines from the 1990s. Retrofitting sensor arrays and networked drives without production stoppage demands phased implementation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Conveyors Market |
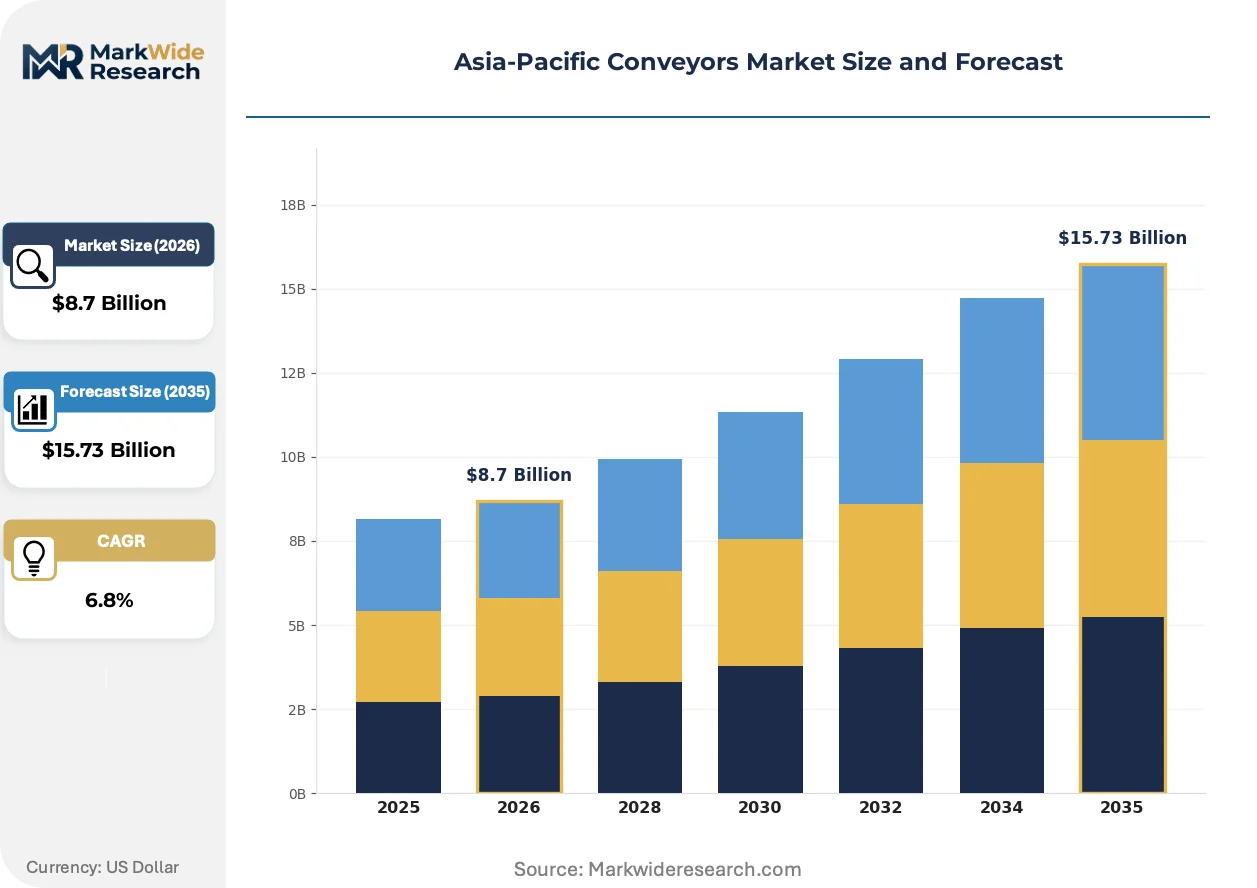
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roller Conveyors, Belt Conveyors, Chain Conveyors, Screw Conveyors End User: Automotive, Food & Beverage, Retail, Pharmaceuticals Technology: Automated, Manual, Hybrid, Smart Material: Steel, Aluminum, Plastic, Rubber |
| Companies Covered | Daifuku Co. Ltd., Murata Machinery Ltd., SSI Schaefer AG, Swisslog Holding AG, BEUMER Group, Interroll Holding AG, Dematic, Vanderlande, KUKA AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Conveyors Market Strategic Shifts
Digital thread technologies are threading sensor networks through mechanical conveyor infrastructure, collapsing the distinction between material handling equipment and data acquisition platforms. This convergence is redrawing supplier capability requirements and buyer evaluation criteria across Asia-Pacific procurement offices.
Edge-computing conveyor controllers are unifying motor control, condition monitoring, and predictive analytics within single hardware enclosures. Semiconductor fabs in South Korea and pharmaceutical packagers in Singapore are adopting these integrated units to reduce panel footprint and wiring complexity. The technology is compressing vendor lists by eliminating separate PLC and sensor suppliers from system architecture.
Japan's METI is enforcing JIS-compliant smart factory integration standards that mandate OPC-UA connectivity and MTConnect protocol support in material handling equipment. Conveyor manufacturers serving Toyota and Honda supplier networks must embed these communication stacks to qualify for procurement. The policy is segmenting the supplier base between connected-systems specialists and commodity mechanical fabricators.
Asset-as-a-service contracting is displacing outright purchase models in Australian mining and Indonesian palm oil processing. Buyers now pay per ton-meter moved rather than capitalizing equipment, transferring uptime risk to OEMs or third-party fleet operators. This shift is most visible in Western Australia iron ore operations and Sumatra bulk commodity terminals where output volatility makes fixed-cost structures untenable.
Asia-Pacific Conveyors Market Segmentation
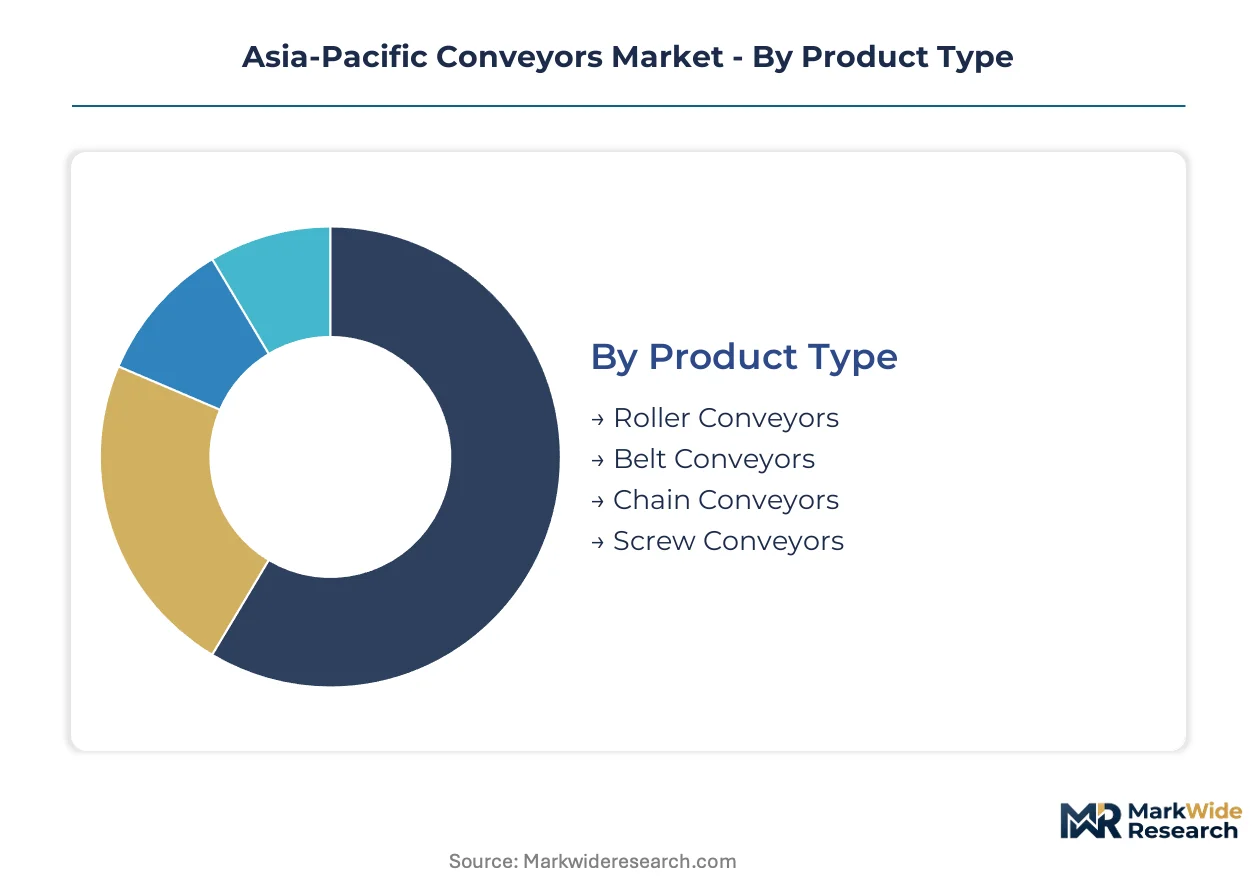
Segmentation in Asia-Pacific conveyors reveals divergent upgrade cycles across mechanical, electromechanical, and digital system tiers. Procurement committees weight total cost of ownership differently depending on whether they operate brownfield automotive plants or greenfield e-commerce hubs.
Product Type:
Replacement cycles vary dramatically by load-bearing architecture and friction mechanics across Asia-Pacific industrial corridors.
- Roller Conveyors:Gravity and powered roller configurations handle discrete packages and palletized loads through modular frame assemblies. E-commerce sortation hubs in Indonesia and Vietnam prioritize these systems for cross-border parcel velocity where reconfigurability trumps initial capital outlay.
- Belt Conveyors:Continuous flat or troughed belts transport bulk solids and unit loads along fixed paths, specified by tensile rating and cover thickness. Australian mining operations and Indonesian coal terminals specify heavy-duty fabric or steel-cord constructions for abrasive material streams.
- Chain Conveyors:Engineered for hot, heavy, or irregular loads through roller chain or drag mechanisms.
- Screw Conveyors:Helical flighting within troughs moves powders and granules at controlled rates for food and chemical processing.
Volume placements concentrate in Belt Conveyors; the faster expansion belongs to Roller Conveyors.
End User:
Capital allocation patterns split between regulatory-driven pharmaceutical upgrades and throughput-driven logistics automation.
- Automotive:Final assembly and powertrain plants deploy precision pallet conveyors with synchronous indexing for just-in-sequence component delivery. Thailand's Eastern Economic Corridor facilities are retrofitting lines for electric vehicle platform flexibility.
- Pharmaceuticals:Clean-room compatible systems with stainless steel construction and washdown capability serve active ingredient manufacturing and finished dose packaging. CDSCO-aligned clusters around Hyderabad and Mumbai mandate EU MDR and US FDA inspection readiness.
- Food & Beverage:Hygienic designs with quick-release belting and antimicrobial coatings for dairy, meat, and aquaculture processing.
- Retail:Modular sortation and accumulation systems for omnichannel fulfillment centers.
Capital deployment is heaviest in Pharmaceuticals; Automotive is gaining share fastest on EV transition timelines.
Technology:
Control architecture choices determine integration depth with factory IoT networks and predictive maintenance platforms.
- Automated:PLC-controlled systems with variable frequency drives, photo-eye arrays, and centralized SCADA integration. South Korean semiconductor fabs and Singapore pharmaceutical packagers specify these for traceability and OEE optimization.
- Smart:Edge-computing controllers embedding vibration sensors, motor current signature analysis, and OPC-UA connectivity for autonomous condition monitoring.
- Manual:Unpowered gravity sections and hand-crank adjustments for cost-sensitive Southeast Asian SMEs.
- Hybrid:Segmented zones combining powered and gravity sections with manual divert stations.
Installed base concentrates in Automated; Smart systems are climbing the fastest on METI JIS compliance deadlines.
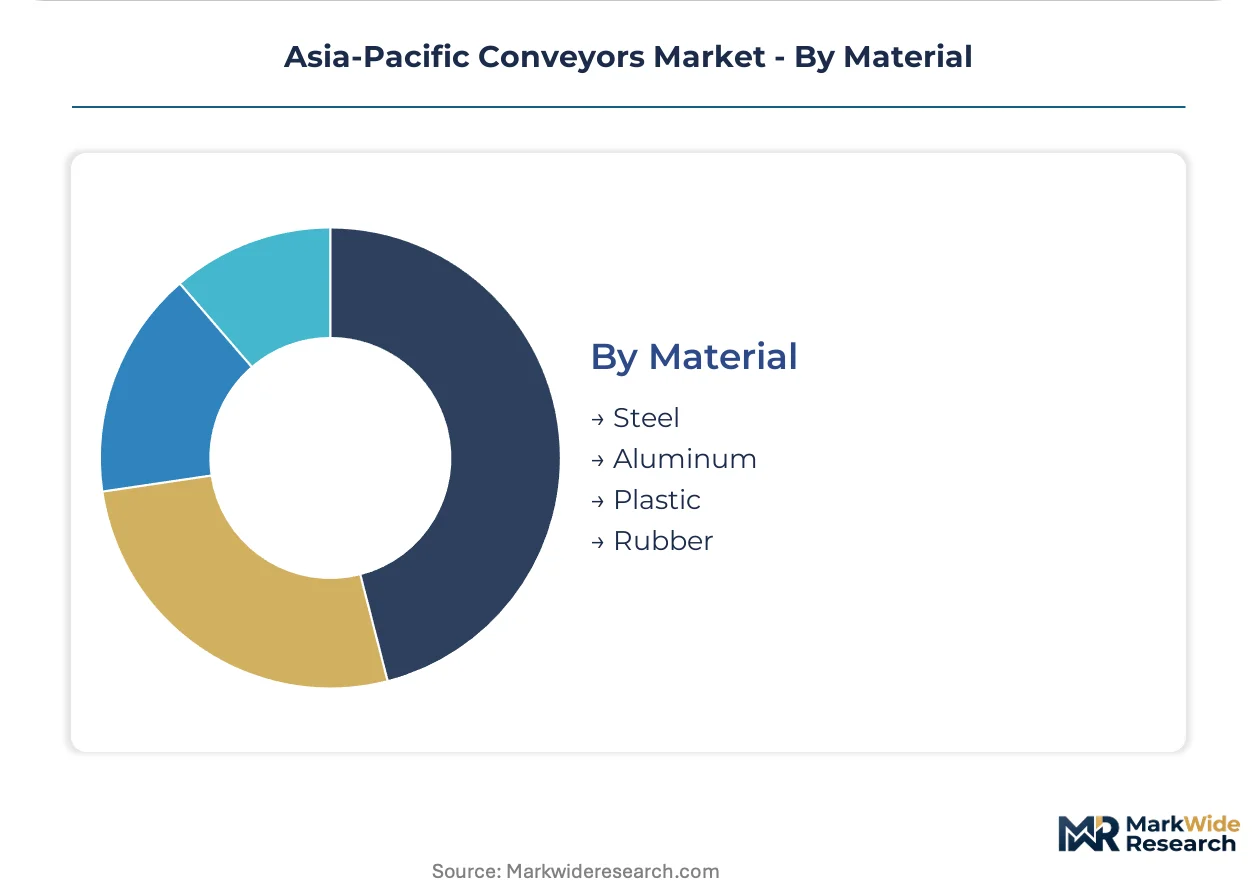
Material:
Frame and component material selection balances corrosion resistance, weight reduction, and magnetic properties against regional steel pricing volatility.
- Steel:Hot-rolled and stainless grades dominate heavy-duty mining and bulk handling for structural rigidity and impact resistance. Chinese GB standards on structural steel grades shape procurement specifications for domestic and export-bound equipment.
- Aluminum:Extruded frame sections reduce weight for overhead and mobile conveyor applications in electronics manufacturing clean rooms.
- Plastic:Polymer rollers and modular belting for corrosion resistance and noise reduction in food processing.
- Rubber:Cover compounds and skirting materials specified for abrasion resistance and oil resistance.
Steel captures the largest tonnage; Aluminum is expanding most quickly on clean-room and lightweighting priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyderabad's pharmaceutical manufacturing corridors are accelerating automated material handling upgrades faster than any other Asia-Pacific industrial cluster, with Mumbai's chemical processing belt and China's Yangtze River Delta electronics zones following distinct regulatory and demand trajectories.
China
MIIT's GB motor efficiency standards are disqualifying legacy conveyor drives from domestic production lines and export-oriented manufacturing. The Yangtze River Delta electronics assembly hubs around Shanghai and Suzhou are retrofitting clean-room conveyor systems to maintain semiconductor supply chain access. MEE dual carbon directives are compressing industrial upgrade cycles toward regenerative drive adoption.
India
CDSCO-aligned pharmaceutical clusters in Hyderabad and Mumbai are retrofitting clean-room conveyor lines to meet EU MDR and US FDA inspection protocols for active pharmaceutical ingredient exports. The PLI scheme for electronics manufacturing is accelerating capital expenditure timelines for automated material handling in greenfield facilities around Bengaluru and Chennai. BIS mechanical safety standards are shaping steel-framed heavy-duty installation specifications.
Japan
METI's JIS-compliant smart factory integration standards mandate OPC-UA connectivity and MTConnect protocol support in material handling equipment serving Toyota and Honda supplier networks. The Kanto region's precision manufacturing belt around Tokyo and Yokohama is deploying edge-computing conveyor controllers to reduce panel footprint. Semiconductor fabs in Kyushu are adopting integrated motor control and condition monitoring units.
Australia
Asset-as-a-service contracting is displacing outright purchase models in Western Australia iron ore operations and Queensland bulk commodity terminals. Buyers now pay per ton-meter moved rather than capitalizing equipment, transferring uptime risk to OEMs or third-party fleet operators. TGA-aligned food safety protocols are driving antimicrobial polymer belting adoption in dairy processing corridors around Victoria.
Vietnam
Underpenetrated conveyor automation in northern industrial zones around Bac Ninh and Hai Phong offers first-mover positioning as Samsung and Apple suppliers localize supply chains. Cross-border e-commerce fulfillment hubs in Ho Chi Minh City are deploying modular roller systems to manage surging parcel volumes from China-directed manufacturing. The government's electronics manufacturing incentives are accelerating warehouse automation capital deployment.
Asia-Pacific Conveyors Market Competitive Environment
Premium-margin players sit above commodity-margin players across technology integration depth, with JIS-compliant smart systems commanding pricing power over standard mechanical fabrications. The vendor base organizes into three tiers: vertically integrated factory automation specialists, modular component platform providers, and regional steel fabrication houses serving cost-sensitive Southeast Asian markets. Dominant competitive moves include backward integration into drive system manufacturing and strategic technology licensing for IoT connectivity stacks.
Among Japanese factory automation specialists, Daifuku Co. Ltd. and Murata Machinery Ltd. exemplify the premium-tier archetype through their positioning in airport baggage handling and clean-room pharmaceutical applications. Interroll Holding AG occupies a distinct modular platform position, anchoring regional presence with scalable roller systems that span mid-tier warehouses to large distribution centers. These three companies represent the strategic segmentation between integrated system providers and component platform specialists.
| Leading Market Players |
|---|
| Daifuku Co. Ltd. |
| Murata Machinery Ltd. |
| SSI Schaefer AG |
| Swisslog Holding AG |
| BEUMER Group |
| Interroll Holding AG |
| Dematic |
| Vanderlande |
| KUKA AG |
| Others |
Value Chain & Pricing Dynamics
Hot-rolled coil pricing volatility cascades from Chinese export quotas through steel-framed conveyor fabrication costs, stratifying end-user tiers between premium automated systems and commodity manual configurations across Asia-Pacific procurement networks.
Pricing Analysis
Throughput-based contracting anchors pricing for heavy-duty mining and bulk commodity applications in Western Australia and Sumatra, where buyers pay per ton-meter moved rather than capitalizing equipment. Pricing stratifies across premium smart-system tiers with METI JIS compliance, standard automated lines with PLC integration, and economy gravity-roller configurations for Southeast Asian SMEs. Cost compression in standard automated tiers intensifies because Chinese MIIT efficiency mandates are disqualifying legacy motor drives before depreciation schedules. Pharmaceutical manufacturers in Hyderabad and Mumbai exhibit lowest price sensitivity due to EU MDR and US FDA compliance requirements, while Indonesian e-commerce fulfillment hubs remain most sensitive to initial capital outlay.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and German precision gearmotor suppliers for heavy-duty variable frequency drive systems, exposing buyers to extended lead times and currency risk. Component manufacturing concentrates in China for structural steel frames, Japan for precision drive systems, and South Korea for edge-computing controllers. Raw material dependencies include regional hot-rolled coil from Chinese mills, nickel-bearing stainless steels from Indonesian supply chains, and specialized polymer formulations for food-grade belting. Tariff exposure on steel inputs threatens margin stability for regional fabrication houses. Distribution runs through OEM direct sales for large mining contracts, systems integrators for factory automation projects, and regional distributors for replacement components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific conveyor manufacturing is consolidating around smart-systems capability as METI JIS compliance deadlines and MIIT efficiency mandates force mechanical fabricators toward technology licensing or exit.
For Market Incumbents: Deploy backward integration into regenerative drive system manufacturing to capture margin pools dislocated from Japanese and German component suppliers. Secure OPC-UA connectivity licensing from semiconductor controller specialists before METI compliance deadlines harden qualification requirements. Autonomous mobile robot substitution in high-mix distribution operations threatens fixed conveyor arrays in Southeast Asian logistics hubs. For New Entrants and Emerging Players: Launch via modular roller platform partnerships with Vietnamese electronics manufacturing zones around Bac Ninh and Hai Phong, where Samsung and Apple supplier localization is accelerating warehouse automation capital deployment. Target underpenetrated clean-room conveyor retrofit opportunities in India's CDSCO-aligned pharmaceutical corridors. Position around quick-release antimicrobial belting systems for Australian dairy and Southeast Asian aquaculture processing. For Investors and Strategic Acquirers: CDSCO-aligned facility certifications crossing fifty percent penetration in Hyderabad pharmaceutical clusters is the leading indicator that automated material handling upgrade cycles are entering sustained expansion. Five-to-ten year viability favors vertically integrated factory automation specialists with captive drive system production and JIS-compliant smart factory integration capability. Watch for MIIT GB standard enforcement intensity as the signal for Chinese domestic upgrade cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Drive Systems | Captures margin dislocated from Japanese and German component suppliers. |
| OPC-UA Connectivity Licensing | Qualifies equipment for METI JIS-compliant Toyota and Honda supplier networks. |
| Clean-Room Retrofit Specialization | Addresses EU MDR and US FDA inspection requirements in Hyderabad pharmaceutical corridors. |
| Asset-as-a-Service Contracting | Transfers uptime risk to OEMs in Western Australia iron ore and Sumatra bulk terminals. |
| Antimicrobial Belting Formulation | Opens hygienic design applications in Australian dairy and Southeast Asian aquaculture. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across maintenance directors at Australian mining operations, plant engineers in India's pharmaceutical manufacturing corridors, OEM procurement teams at Japanese automotive suppliers, and aftermarket service heads at Southeast Asian distribution hubs. Bottom-up equipment shipment data triangulated against top-down capital expenditure disclosures from listed conveyor manufacturers and systems integrators.
Granularity-level modeling operated at product type, end user, technology tier, and material composition dimensions, with additional disaggregation by regulatory compliance cluster across MIIT GB standards, METI JIS requirements, and CDSCO-aligned pharmaceutical protocols. CAGRs were derived from equipment replacement cycle compression analysis and greenfield facility automation intensity curves. Forecast inputs included motor efficiency mandate enforcement timelines and cross-border e-commerce parcel volume trajectories.
Steel input price volatility, regulatory enforcement intensity shifts, and autonomous mobile robot substitution velocity are the dominant revision risks to projection assumptions. Deviation in MIIT GB standard disqualification timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Pneumatic Caster Market
Material Handling Equipment
Heavy Duty Loading Ramps Market
Material Handling Equipment
Industrial Belt Drives Market
Material Handling Equipment
Industrial Carts Market
Material Handling Equipment
Material Handling Automation Market
Material Handling Equipment
Global Mechanical Seals Market
Material Handling Equipment
Roll Handling Machine Market
Material Handling Equipment
Outdoor Power Equipment (OPE) Market
Material Handling Equipment
North America Conveyor Belt Market
Material Handling Equipment
Linear Slides Market
Material Handling Equipment
Pug Mill Mixers Market
Material Handling Equipment
United States Conveyor Belt Market
Material Handling Equipment
GCC Conveyor Belt Market
Material Handling Equipment
Cherry Picker Crane Market
Material Handling Equipment
Crane Mats Market
Material Handling Equipment
Global Conveyors Market