
 Global Valves in Oil and Gas Industry Market | 2026-2036
Global Valves in Oil and Gas Industry Market Size, Share, and Industry Trends Forecast 2026-2036
Global Valves in Oil and Gas Industry Market Foresight
Specialized welding and metallurgical engineering talent is rotating toward unconventional reservoir projects, tightening supply for conventional valve fabrication. Emerson Electric leverages its distributed control systems footprint to anchor integrated valve-automation packages in North American shale plays. Baker Hughes competes through in-house production of superalloy trim components for sour service conditions. Flowserve Corporation dominates aftermarket service contracts across legacy offshore installations in the North Sea and Gulf of Mexico.
Valves in the oil and gas industry are mechanical flow control devices engineered to withstand pressure ratings exceeding 15,000 psi, temperature extremes from cryogenic LNG service to superheated steam, and corrosive media containing hydrogen sulfide or carbon dioxide. Their primary purpose is to isolate, regulate, or throttle hydrocarbon streams across drilling, gathering, transport, refining, and petrochemical conversion processes. Ball valves capture substantial share in transmission pipeline isolation duty due to their bidirectional sealing reliability and low torque operation. Electric actuated technology leads upstream automation retrofits where remote monitoring reduces platform manning requirements. Downstream refining applications maintain mature replacement demand driven by turnaround schedules and evolving fluid specifications.
The American Petroleum Institute governs valve design, materials, and testing through API 6D and API 598 standards that govern pipeline and refinery procurement specifications across North American projects. ISO 14313 and IEC 61508 shape international interoperability and functional safety requirements for automated valve packages in integrated production systems. The EPA's methane emissions rules and the EU's F-Gas Regulation are forcing material and packing upgrades to limit fugitive releases from valve stem seals. Stakeholders must monitor how carbon border adjustment mechanisms and evolving Scope 3 accounting standards redirect procurement criteria toward traceable, low-emission manufacturing credentials.
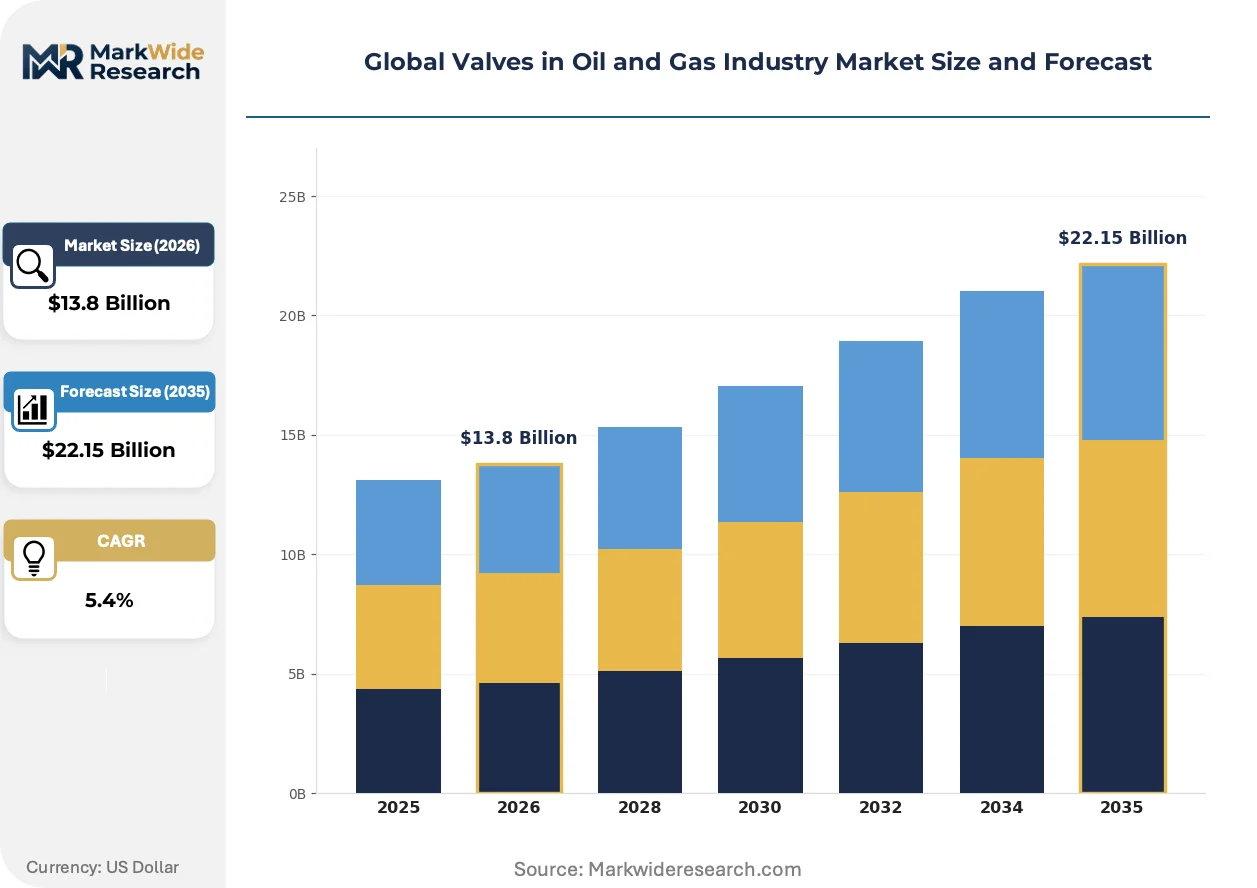
Market Dynamics
Subsea field redevelopment and LNG export terminal construction are compressing replacement cycles while tightening certification requirements reshape supplier qualification criteria across major procurement bases.
Growth Catalysts
- API 6D Certification Mandates:Pipeline operators in the United States Gulf Coast corridor now require updated material testing protocols for high-pressure isolation valves, accelerating upgrade spending across gathering systems.
- Electric Actuation Retrofits:Platform operators deploy remote monitoring packages to reduce offshore manning requirements, driving automation hardware demand in mature North Sea and Gulf of Mexico installations.
- Sour Service Alloy Demand:Hydrogen sulfide-bearing reservoirs in Middle Eastern and Caspian basins specify superalloy trim components that withstand corrosive media above 15,000 psi operating pressure.
Market Restraints
- Specialized Welding Talent Scarcity:Metallurgical engineers are rotating toward unconventional reservoir projects, leaving conventional valve fabrication yards in Houston and Aberdeen understaffed for qualified overlay welding.
- Nickel and Chromium Price Volatility:Superalloy feedstock cost swings compress margin visibility for trim component suppliers serving sour service specifications.
- Extended ISO 14313 Testing Cycles:International interoperability certification now requires additional fire-safe and fugitive emission validation sequences that extend factory acceptance timelines.
Strategic Opportunities
- Carbon Border Adjustment Preparedness:European LNG importers are screening valve suppliers for traceable low-emission manufacturing credentials ahead of phased carbon tariff implementation.
- Aftermarket Service Unbundling:Legacy offshore installation operators in the United Kingdom and Norway are separating maintenance contracts from original equipment procurement, opening independent service entry points.
- Cryogenic LNG Valve Specialization:Qatar and Australian liquefaction train expansions specify cryogenic ball valve configurations for minus 162 degree Celsius service that few fabrication yards can consistently deliver.
Industry Challenges
- Functional Safety Integration Complexity:IEC 61508 compliance for automated valve packages requires embedded diagnostics that conflict with legacy distributed control system architectures in brownfield refineries.
- Dual Certification Timeline Pressure:Suppliers pursuing simultaneous API 6D and ISO 14313 qualification face divergent documentation requirements that strain engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Valves in Oil and Gas Industry Market |
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $22.15 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Valves, Gate Valves, Globe Valves, Butterfly Valves, Check Valves, Needle Valves Technology: Electric Actuated, Pneumatic Actuated, Hydraulic Actuated, Manual, Solenoid Operated, Electro-Hydraulic Application: Upstream Exploration, Midstream Transportation, Downstream Refining, Petrochemical Processing, Gas Processing End User Segment: Exploration & Production Firms, Pipeline Operators, Refinery Plants, Petrochemical Manufacturers, Gas Processing Companies |
| Companies Covered | Schlumberger, Emerson Electric, Flowserve Corporation, Parker Hannifin, CIRCOR International, IMI, Baker Hughes, Crane Company, National Oilwell Varco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Valves in Oil and Gas Industry Market Shifts & Advancements
Digital valve positioners and predictive maintenance algorithms are restructuring how operators manage rotating equipment reliability across remote production facilities.
Additive manufacturing of superalloy valve components is fragmenting traditional forging and casting supply chains. Supermajor operators in Norwegian and Brazilian deepwater projects are qualifying laser powder bed fusion parts for subsea manifold applications. This distributed production capability is compressing lead times for complex trim geometries while challenging incumbent foundries in Pittsburgh and Sheffield.
The EPA's methane emissions rules are forcing material upgrades across North American valve stem seal configurations. Packing manufacturers must now qualify graphite-based or PTFE-impregnated designs that withstand higher cycle counts without fugitive release. Gathering system operators in the Permian and Bakken basins are replacing legacy packing sets during scheduled turnarounds to preempt enforcement exposure.
Integrated valve-automation packages are displacing discrete component procurement in shale field development programs. Exploration companies in the United States and Argentina now specify pre-configured electric actuator and positioner assemblies from single-source vendors rather than engineering separate specifications. This bundling concentrates specification authority with automation specialists and compresses margin for standalone valve manufacturers.
Global Valves in Oil and Gas Industry Market Segmentation
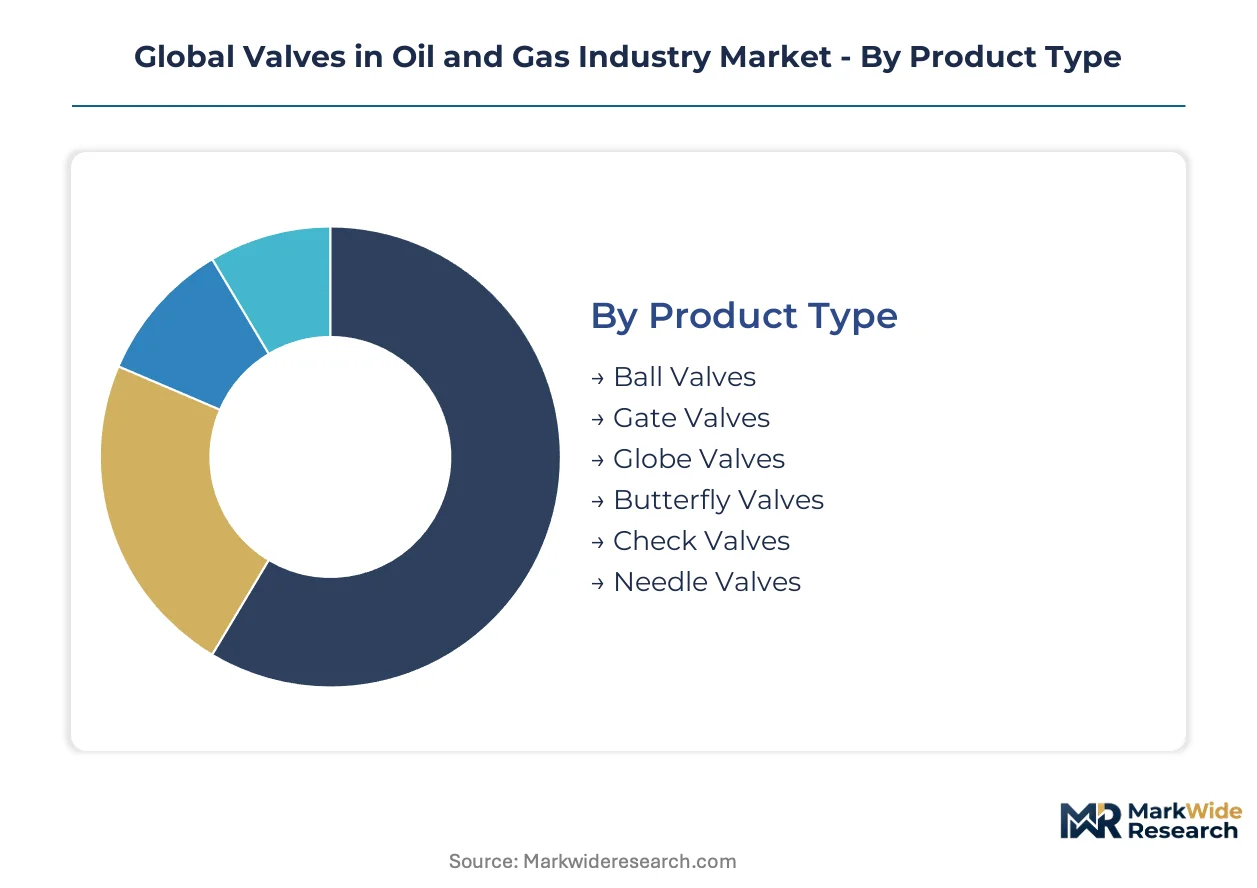
Valve specification patterns diverge sharply across operating environments, with pressure ratings, actuation methods, and metallurgical requirements creating distinct procurement lanes that resist standardization. Understanding these segment boundaries clarifies where margin concentrates and which technical specifications command premium positioning.
Product Type:
API 6D and ISO 14313 impose divergent testing protocols on each valve family, with pipeline versus refinery applications triggering different certification burdens.
- Ball Valves:Quarter-turn isolation devices with bidirectional sealing capability dominate transmission pipeline duty. United States Gulf Coast LNG export terminals specify trunnion-mounted configurations rated above 15,000 psi for cryogenic and high-pressure service.
- Gate Valves:Linear-motion designs provide full-bore flow paths ideal for on-off isolation in gathering systems. Middle Eastern sour service fields require Inconel 625 overlay welding on gate and seat surfaces to withstand hydrogen sulfide corrosion above 10,000 psi.
- Globe Valves:Throttling applications in steam and process lines utilize their superior flow modulation characteristics.
- Butterfly Valves:Compact wafer and lug designs serve low-pressure utility and cooling water systems across refinery complexes.
- Check Valves:Swing and piston configurations prevent backflow in compressor stations and pump discharge lines.
- Needle Valves:Precision flow control for instrumentation and sampling points in analytical skids.
Ball valves handle the majority of throughput; needle valves are expanding most quickly in subsea instrumentation packages.
Technology:
Actuation selection hinges on power availability, response time requirements, and functional safety integration complexity in brownfield versus greenfield installations.
- Electric Actuated:Motor-driven packages with embedded positioners and diagnostic capability anchor upstream automation retrofits. North Sea platform operators deploy these systems to reduce offshore manning requirements and satisfy IEC 61508 safety integrity levels.
- Pneumatic Actuated:Compressed air systems deliver fast stroke speeds and fail-safe positioning for emergency shutdown duty. Caspian basin projects specify these for their reliability in extreme temperature swings and compatibility with existing instrument air infrastructure.
- Hydraulic Actuated:High-force output for subsea wellhead and manifold isolation where electric power distribution is impractical.
- Manual:Handwheel or gear-operated designs persist in low-cycle isolation points and maintenance bypass lines.
- Solenoid Operated:Rapid response for pneumatic pilot circuits and emergency venting applications.
- Electro-Hydraulic:Hybrid systems combining electric control with hydraulic force multiplication for deepwater blowout preventer stacks.
Pneumatic actuation retains the largest installed base; electric systems are climbing the fastest on share in new upstream developments.
Application:
Operating pressure, temperature, and corrosivity profiles create non-overlapping specification envelopes that fragment supplier qualification across the value chain.
- Upstream Exploration:Subsea and high-pressure onshore environments demand metallurgical excellence and rapid actuation response. Norwegian deepwater projects specify superduplex stainless steel bodies with titanium trim for seawater injection systems.
- Midstream Transportation:Long-distance pipeline isolation requires fire-safe certification and low-torque operation for remote valve automation. FERC-regulated interstate lines in the United States mandate API 6D compliance with full-bore pigging compatibility.
- Downstream Refining:Turnaround-driven replacement cycles and evolving fluid specifications maintain mature demand for corrosion-resistant alloys in catalytic cracking and hydrotreating units.
- Petrochemical Processing:Ethylene and propylene polymerization trains require cryogenic and high-temperature valve configurations with tight emission control.
- Gas Processing:Acid gas removal and dehydration facilities specify sour service trim for hydrogen sulfide and carbon dioxide handling.
Midstream transportation commands the greatest valve count per facility; upstream exploration shows the steepest expansion trajectory on capital intensity.
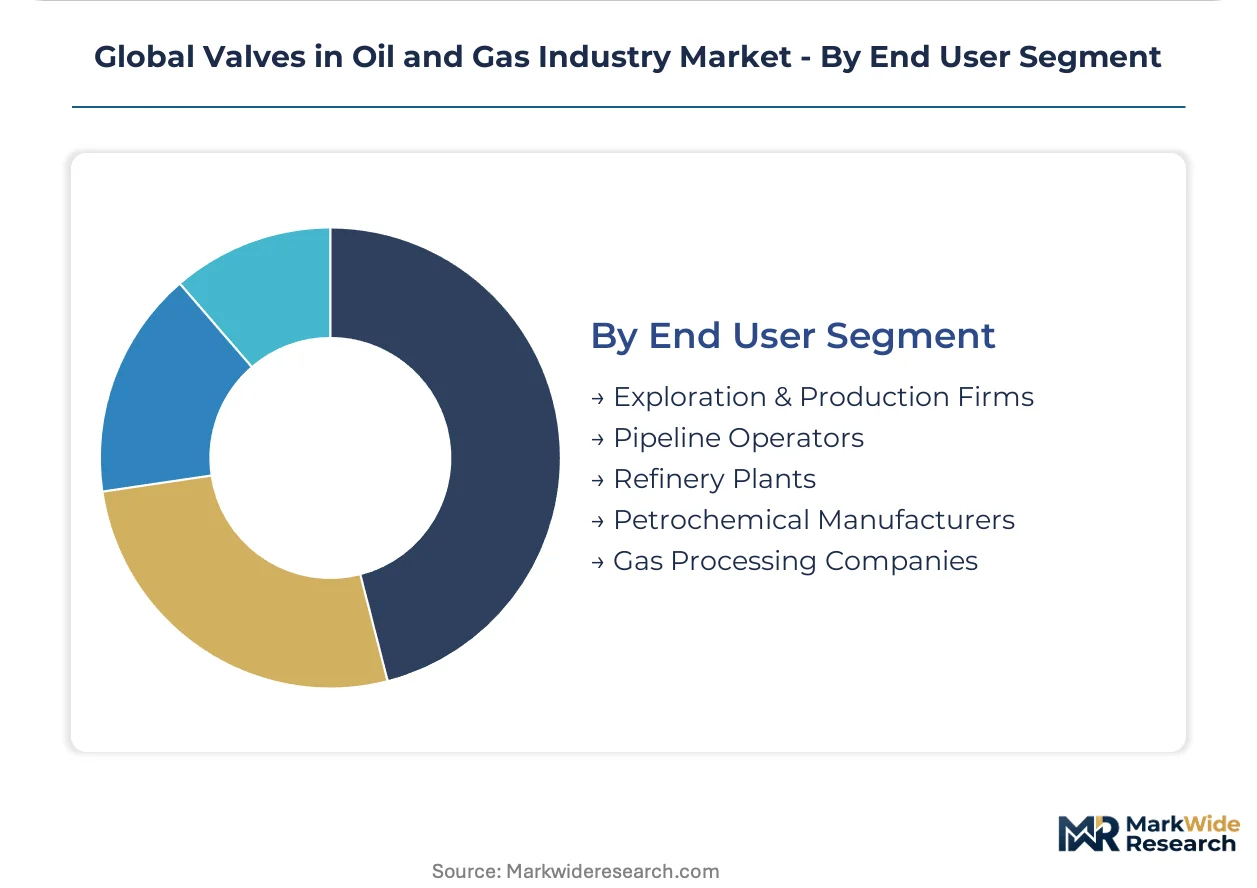
End User Segment:
Procurement authority and lifecycle cost modeling differ fundamentally between asset owners with captive engineering resources and outsourced operators.
- Exploration & Production Firms:Integrated supermajors and independents specify valves as part of subsea production system packages. Brazilian pre-salt developments qualify suppliers through extended factory acceptance testing protocols that span 18-24 months.
- Pipeline Operators:Interstate and intrastate transmission companies prioritize total cost of ownership and interoperability in multi-vendor environments. United States-based operators emphasize API 6D monogrammed products with traceable material certifications.
- Refinery Plants:Maintenance departments drive replacement demand through turnaround schedules and reliability-centered maintenance programs.
- Petrochemical Manufacturers:Ethylene crackers and aromatics complexes specify valves for severe thermal cycling and polymer fouling resistance.
- Gas Processing Companies:Cryogenic fractionation and liquefaction facilities demand leak-tight performance across extreme temperature ranges.
Pipeline operators generate the highest unit volume; exploration and production firms are gaining share fastest on subsea capital deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Norwegian deepwater fabrication yards while United States Gulf Coast suppliers absorb margin compression from accelerated replacement cycles. This asymmetry reflects divergent certification burdens and labor scarcity patterns across the Atlantic basin.
United States
LNG export terminal construction along the Texas and Louisiana coastlines drives procurement of cryogenic ball valves rated for 15,000 psi service. EPA methane emissions rules mandate graphite-based packing upgrades across Permian and Bakken gathering systems. Houston fabrication yards face qualified overlay welding shortages as metallurgical engineers rotate toward unconventional reservoir projects.
Norway
Subsea field redevelopment in the North Sea and Norwegian Sea sustains premium pricing for superduplex stainless steel valve configurations. The country's national petroleum regulator enforces extended factory acceptance testing protocols spanning 18-24 months for pre-qualified suppliers. Stavanger and Bergen clusters anchor deepwater manifold fabrication where laser powder bed fusion additive manufacturing is gaining qualification traction.
Germany
Industrial valve automation integration serves chemical processing complexes along the Rhine-Ruhr corridor and Bavarian petrochemical sites. EU F-Gas Regulation and forthcoming carbon border adjustment mechanisms screen suppliers for traceable low-emission manufacturing credentials. Düsseldorf-based engineering groups concentrate on IEC 61508 functional safety compliance for brownfield refinery retrofits.
China
Domestic LNG liquefaction train expansions and shale gas development in Sichuan-Chongqing basin compress lead times for cryogenic service valves. The Ministry of Ecology and Environment enforces dual carbon goals that redirect procurement toward domestic fabrication with emissions traceability. Shanghai and Dalian shipyards integrate valve packages into subsea production system exports for Brazilian and West African markets.
Saudi Arabia
Hydrogen sulfide-bearing reservoirs in the Ghawar and Safaniya fields specify superalloy trim components above 10,000 psi operating pressure. The national oil company mandates API 6D and ISO 14313 dual certification for pipeline isolation valve suppliers. Eastern Province fabrication clusters near Jubail Industrial City concentrate sour service overlay welding capacity for Middle Eastern and Caspian basin export programs.
Global Valves in Oil and Gas Industry Market Competitive Landscape
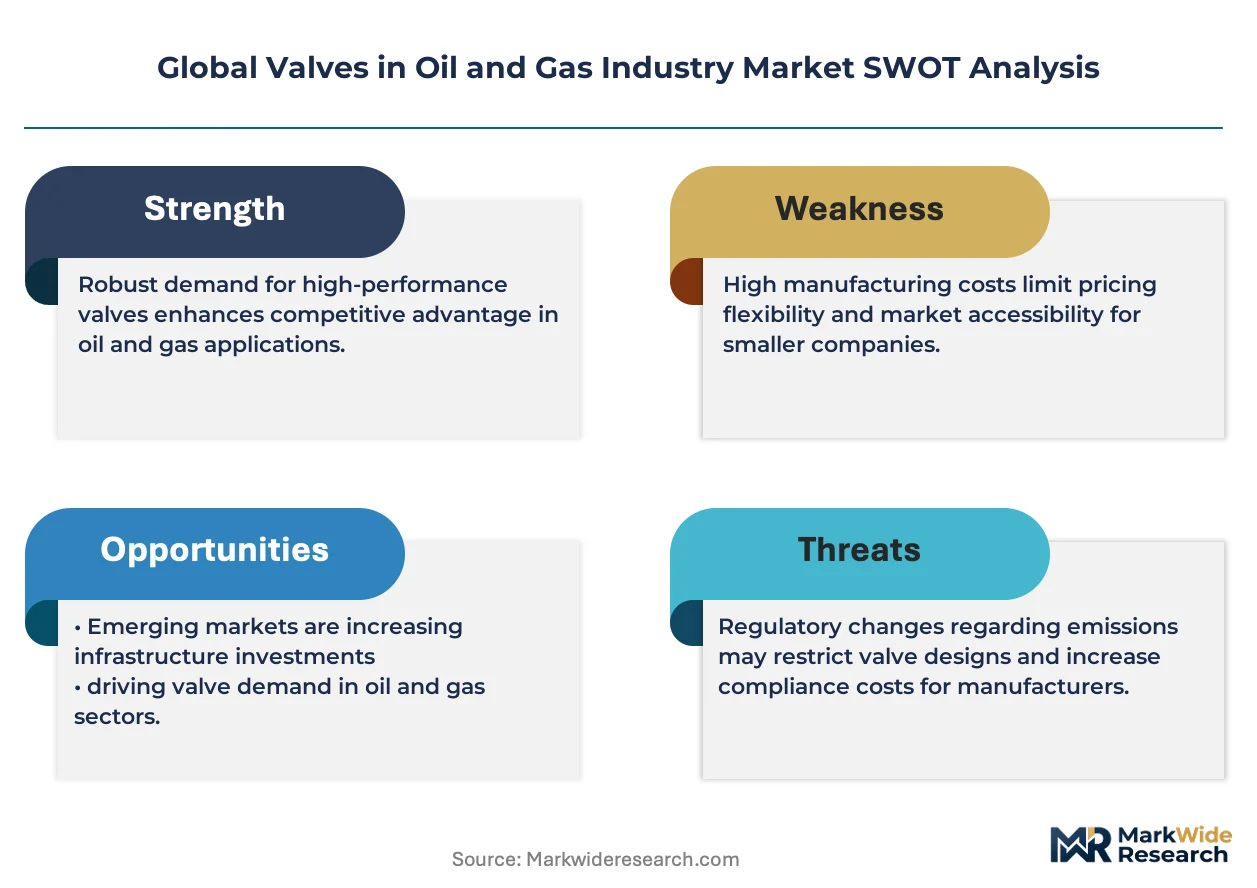
Technology leadership and cost leadership are held by different player archetypes across the valve supply base. Integrated automation conglomerates anchor specification authority through distributed control system footprints, while specialized metallurgical fabricators compete on superalloy trim qualification for corrosive service. The market structure tiers into three archetypes: full-system integrators bundling valve-automation packages, component specialists dominating aftermarket service contracts, and emerging additive manufacturing qualifiers disrupting traditional forging supply chains. Competitive moves concentrate on strategic partnerships for certification co-qualification and geographic expansion into carbon-adjustment-prepared supply bases.
Among United States-based industrial conglomerates, Emerson Electric and Baker Hughes exemplify divergent strategic positioning within the integrated tier. Emerson leverages automation platform dominance to anchor pre-configured electric actuator and positioner assemblies in North American shale plays. Baker Hughes occupies a position centered on in-house superalloy production for sour service conditions. Flowserve Corporation, a standalone valve and pump specialist, anchors aftermarket service concentration across legacy offshore installations in the North Sea and Gulf of Mexico.
| Leading Market Players |
|---|
| Schlumberger |
| Emerson Electric |
| Flowserve Corporation |
| Parker Hannifin |
| CIRCOR International |
| IMI |
| Baker Hughes |
| Crane Company |
| National Oilwell Varco |
| Others |
Supply & Pricing Matrix
Twenty-four to thirty-six month factory acceptance testing cycles for Norwegian subsea qualification concentrate pricing power in Stavanger-Bergen fabrication clusters while compressing margins for Gulf Coast suppliers facing accelerated replacement demands. This lead-time asymmetry between premium-tier and standard-tier supply bases directly shapes how procurement managers allocate capital across certification grades.
Pricing Analysis
United States Gulf Coast cryogenic ball valves trade at a discount to Norwegian superduplex configurations despite equivalent pressure ratings, reflecting divergent labor scarcity and certification burden. Three-tier pricing structure across premium, standard, and economy levels separates API 6D monogrammed products with full material traceability from non-monogrammed alternatives. Pricing pressure stems from nickel and chromium feedstock volatility eroding trim component margins. Pipeline operators exhibit highest price sensitivity through total cost of ownership modeling, while exploration firms prioritize qualification speed over unit economics.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for superalloy feedstock destined to Houston and Aberdeen fabrication yards. Supply concentrates in the United States, Norway, and Saudi Arabia for high-pressure isolation valve production. Manufacturing draws from nickel-chromium superalloy castings, forged carbon steel bodies, and electric actuator subassemblies. Single-source vulnerability concentrates in Pittsburgh and Sheffield foundries facing additive manufacturing disruption. Distribution runs through original equipment manufacturer direct sales for greenfield projects and independent service networks for aftermarket maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market approaches a platform-economics inflection as integrated valve-automation bundles displace discrete component procurement, with Emerson Electric's distributed control system ecosystem demonstrating how specification authority migrates toward automation-native vendors.
For Market Incumbents: Consolidate overlay welding capacity in Houston and Aberdeen through targeted acquisition of distressed fabrication assets facing metallurgical engineer shortages. Defend specification authority by embedding diagnostic capability deeper into electric actuator platforms before IEC 61508 compliance becomes mandatory across brownfield retrofits. Prioritize dual API 6D and ISO 14313 certification investment to capture European LNG importer procurement ahead of carbon border adjustment implementation. For New Entrants and Emerging Players: Aftermarket service unbundling in United Kingdom and Norwegian offshore installations represents the most penetrable white-space target, as legacy operators separate maintenance contracts from original equipment procurement. Cryogenic LNG valve specialization for Qatar and Australian liquefaction train expansions offers qualification-fast entry where incumbent capacity is constrained. Pursue laser powder bed fusion qualification partnerships with Brazilian or Norwegian deepwater operators to bypass traditional foundry lead times. For Investors and Strategic Acquirers: Long-term, this sits as a certification-moat play because dual API 6D and ISO 14313 qualification timelines create structural barriers that compound over successive replacement cycles. Target mid-tier fabrication specialists with existing sour service overlay welding capability but lacking automation integration. Watch for inflection when carbon border adjustment mechanisms trigger procurement preference shifts toward traceable low-emission manufacturing credentials.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | API 6D and ISO 14313 co-qualification opens European LNG importer procurement channels ahead of carbon tariff phase-in. |
| Additive Manufacturing Qualification | Laser powder bed fusion adoption compresses lead times for complex trim geometries while challenging incumbent Pittsburgh and Sheffield foundries. |
| Aftermarket Service Unbundling | Separating maintenance contracts from original equipment procurement creates independent entry points in United Kingdom and Norwegian offshore markets. |
| Electric Actuator Platform Integration | Pre-configured valve-automation bundles concentrate specification authority with automation specialists in North American shale plays. |
| Low-Emission Manufacturing Credentialing | Traceable emissions documentation satisfies EU carbon border adjustment screening requirements for valve suppliers. |
Research Methodology
Cross-validation between primary interviews with subsea project engineers, procurement managers at pipeline operators, metallurgical welding specialists, and aftermarket service directors anchors the qualitative findings against secondary validation from API certification databases, SEC 10-K filings, and FERC interstate pipeline construction records. Bottom-up segmentation modeling triangulates with top-down energy infrastructure capex tracking across the analysis window.
Sensitivity analysis around nickel price volatility, certification timeline extensions, and carbon border adjustment implementation pace shapes the forecast framework. Segmentation dimensions include valve product family, actuation technology, pressure-temperature service class, and regional regulatory cluster. CAGRs derive from replacement cycle compression observations and LNG terminal construction pipeline tracking. Industry-specific inputs incorporate EPA methane emissions rule compliance cost curves and IEC 61508 safety integrity level adoption rates.
Underlying assumptions cover stable API 6D and ISO 14313 standard continuity, with deviation risk concentrated in accelerated carbon border adjustment timelines or sudden nickel supply disruption. Forecasts reflect these boundary conditions; outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Battery Pack Cooling Valve Actuator Systems Market
Valves
Global Thermostatic Radiator Valve Market
Valves
Europe Valves Market
Valves
Insulation Flanges Market
Valves
Global Marine Actuators and Valves Market
Valves
Dense Phase Vessels Market
Valves
Aerospace Valves Market
Valves
Global Plastic Valves Market
Valves
Carbon Seal Rings Market
Valves
Global Pressure Relief Valves Market
Valves
Leak Detection Market
Valves
Naval Actuators and Valves Market
Valves
Expansion Valves Market
Valves
Air Jet Ejectors Market
Valves
Global Solenoid Valves Market
Valves
Pipeline Pigging System Market