
 Off-Highway Hydraulic Valve Actuator Systems Market | 2026-2036
Off-Highway Hydraulic Valve Actuator Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Off-Highway Hydraulic Valve Actuator Systems Market Insights
ISO 4406 cleanliness certification is rotating supplier qualification cycles toward particle-count-controlled manufacturing environments. Bosch Rexroth leverages captive foundry and machining capacity to dominate electro-hydraulic actuator supply for European construction OEMs. Danfoss Power Solutions sustains R&D intensity in load-sensing architectures across its Nordborg engineering campus. Parker Hannifin anchors North American aftermarket channels through its independent distribution network for replacement valve actuator cartridges.
Off-highway hydraulic valve actuator systems integrate spool valves, solenoid coils, and position feedback sensors to modulate fluid power delivery in mobile equipment operating above 350 bar. These assemblies translate electrical or mechanical command signals into precise hydraulic flow routing, enabling boom articulation, bucket curl, and drivetrain shift functions under cyclic load conditions. Electro-hydraulic valve actuators command premium positioning as construction machinery electrifies pilot controls and eliminates mechanical linkages. Load sensing control technology captures expanding margin pools where multi-function demand requires simultaneous actuator coordination without flow saturation. Mechanical valve actuators retain cost-driven volume in emerging-market agricultural equipment with simpler hydraulic architectures.
EPA Tier 4 Final and EU Stage V emissions frameworks compel engine-aftertreatment packaging that crowds hydraulic component space, driving demand for compact integrated actuator-manifold assemblies. EMA and REACH compliance further shapes material selection for seals and coatings in European-sourced systems. China's GB standards for non-road mobile machinery impose parallel technical requirements that filter market access for imported actuator platforms. Stakeholders must monitor how dual carbon goals in Beijing and Brussels redirect R&D budgets toward energy-efficient hydraulic architectures without sacrificing actuator response bandwidth.
Market Dynamics
Electro-hydraulic valve actuator architectures are compressing mechanical linkage supply chains while expanding precision control requirements across construction and agricultural equipment platforms.
Growth Catalysts
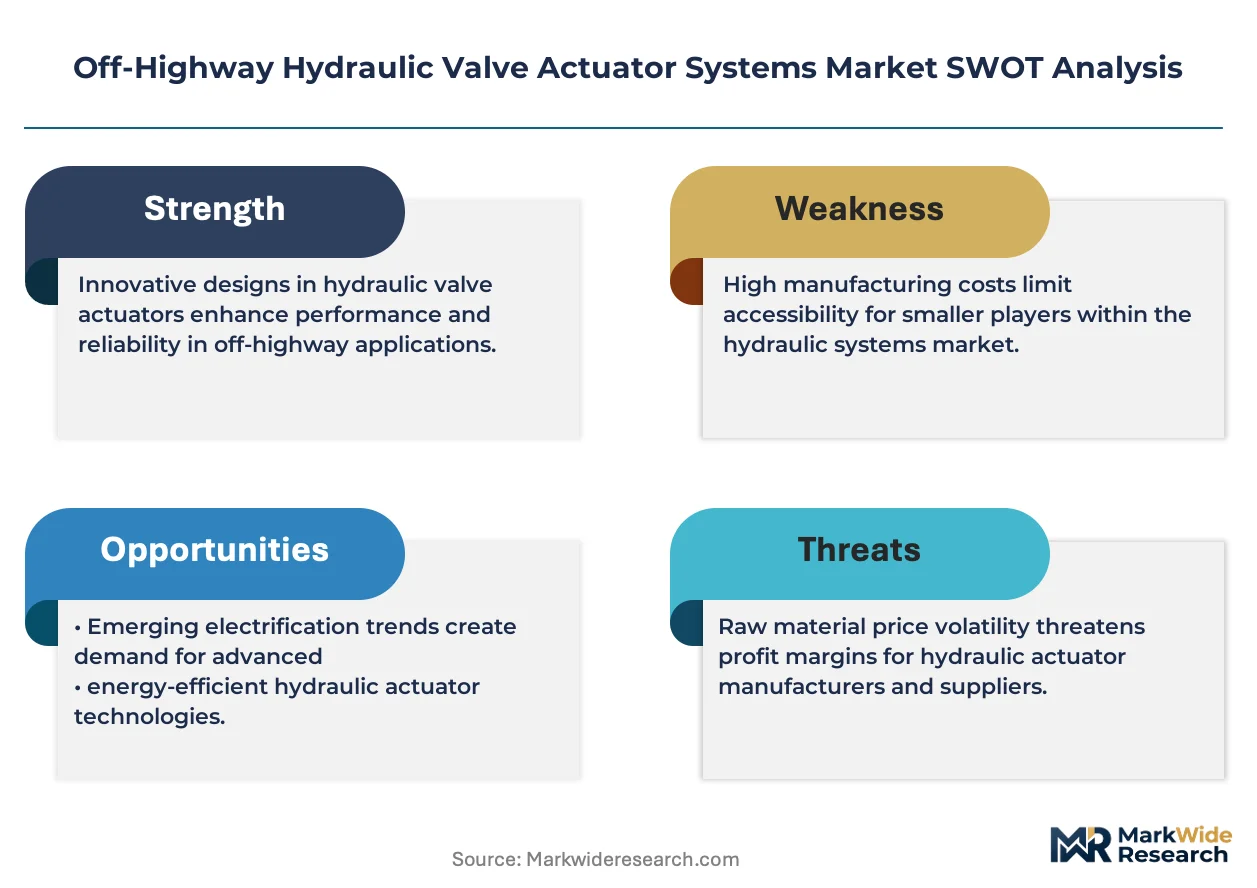
- Stage V emissions mandates:EU engine packaging constraints force compact integrated actuator-manifold designs that eliminate discrete component mounting.
- Construction machinery electrification:OEM pilot control elimination drives demand for position-feedback-enabled electro-hydraulic actuators in earthmoving equipment.
- ISO 4406 cleanliness protocols:Particle-count certification requirements rotate supplier qualification toward controlled manufacturing environments.
Market Restraints
- Specialized seal material costs:REACH-compliant fluorocarbon and hydrogenated nitrile compounds face price volatility from European chemical feedstock constraints.
- Foundry capacity concentration:Ductile iron casting for valve bodies clusters in German and Chinese manufacturing basins, creating single-source exposure.
- Mechanical actuator substitution limits:Cost-driven agricultural equipment in emerging markets retains cable and linkage architectures that block electro-hydraulic upgrade paths.
Strategic Opportunities
- Indian agricultural mechanization:Tractor hydraulic system upgrades create demand for load-sensing valve actuators as BIS standards tighten.
- Autonomous construction platforms:Machine-to-machine coordination protocols require simultaneous multi-actuator response without pilot intervention.
- Remanufacturing channel development:Independent distributors capture aftermarket cartridge replacement volume through position sensor refurbishment capabilities.
Industry Challenges
- Electro-hydraulic calibration expertise:Solenoid coil impedance matching and spool position sensor alignment require specialized technician training absent in traditional hydraulic service networks.
- Legacy mechanical system integration:Retrofit compatibility with existing pilot line architectures complicates electro-hydraulic upgrade deployments in mid-life equipment fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Off-Highway Hydraulic Valve Actuator Systems Market |
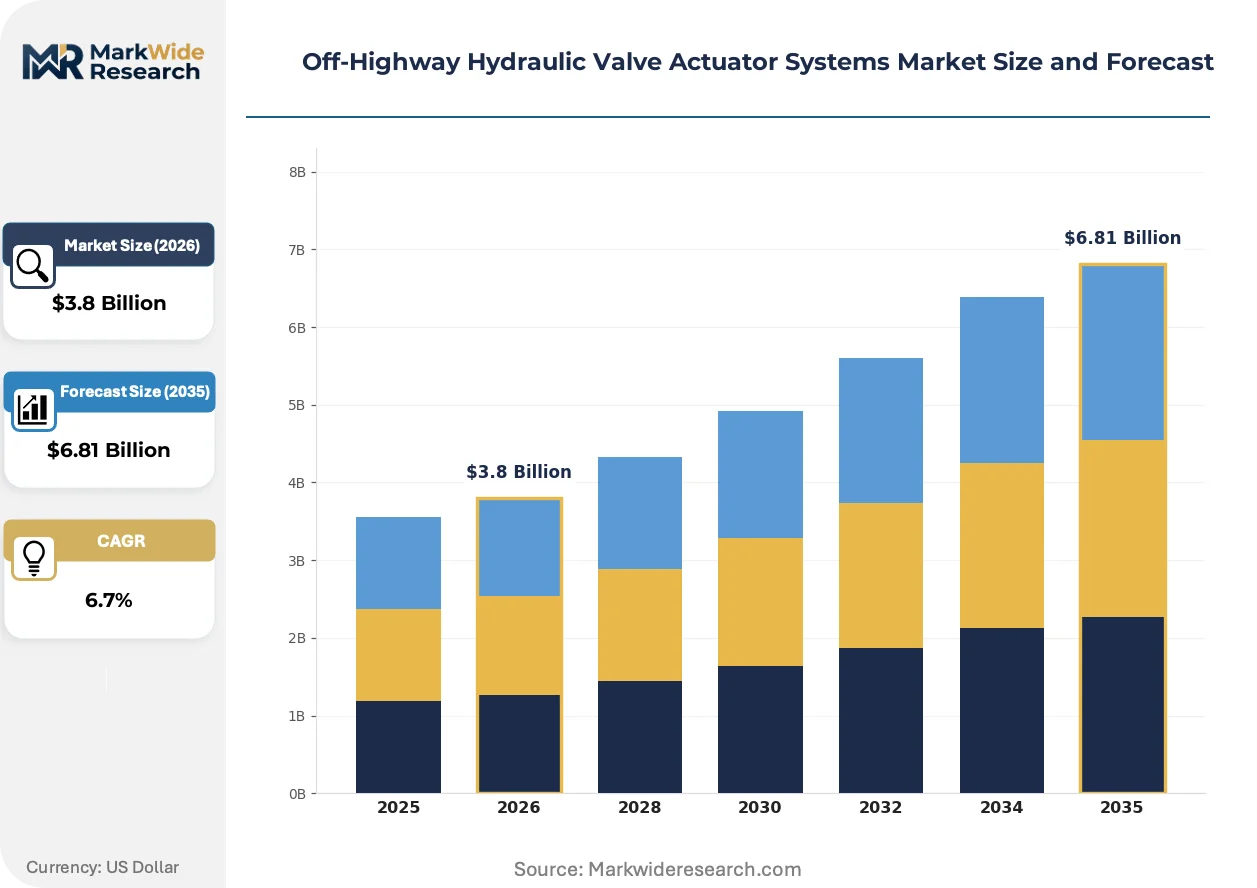
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electro-Hydraulic Valve Actuators, Mechanical Valve Actuators, Pneumatic Valve Actuators, Direct-Drive Valve Actuators Technology: Proportional Control, ON/OFF Control, Servo Control, Load Sensing Control Application: Construction Machinery, Agricultural Equipment, Mining Machines, Forestry Tools End User: OEMs, Aftermarket Suppliers, Maintenance Service Providers, Hydraulic Equipment Manufacturers |
| Companies Covered | Bosch Rexroth, Danfoss Power Solutions, Parker Hannifin, Eaton, Bucher Hydraulics, HAWE Hydraulik, HydraForce, Sun Hydraulics, Moog, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Off-Highway Hydraulic Valve Actuator Systems Market Trends and Innovations
Valve actuator system architectures are pivoting from discrete component supply toward integrated electro-hydraulic modules that compress assembly time and eliminate leakage points.
Proportional solenoid technology with integrated electronics is supplanting conventional on-off solenoid architectures in construction equipment boom and bucket circuits. OEMs in Germany and Japan are specifying closed-loop spool position feedback for functions requiring sub-millimeter articulation precision. This transition compresses the addressable market for purely mechanical pilot-stage actuators while expanding margin pools for sensor-integrated electro-hydraulic cartridges.
EPA Tier 4 Final and EU Stage V frameworks are crowding engine compartments with aftertreatment hardware that consumes hydraulic component mounting space. Compact integrated actuator-manifold assemblies that consolidate multiple valve functions into single castings capture expanding specification share. North American and European construction OEMs are qualifying these integrated designs for earthmoving platforms where packaging density determines competitive positioning.
Construction equipment fleet operators are compressing replacement cycles for valve actuator cartridges based on ISO 4406 cleanliness monitoring rather than fixed hour intervals. Predictive maintenance contracts that bundle fluid analysis with scheduled cartridge replacement are displacing traditional break-fix aftermarket relationships. This pattern concentrates procurement authority with fleet management companies in Germany and the United States that negotiate multi-year actuator supply agreements.
Off-Highway Hydraulic Valve Actuator Systems Market Segmentation
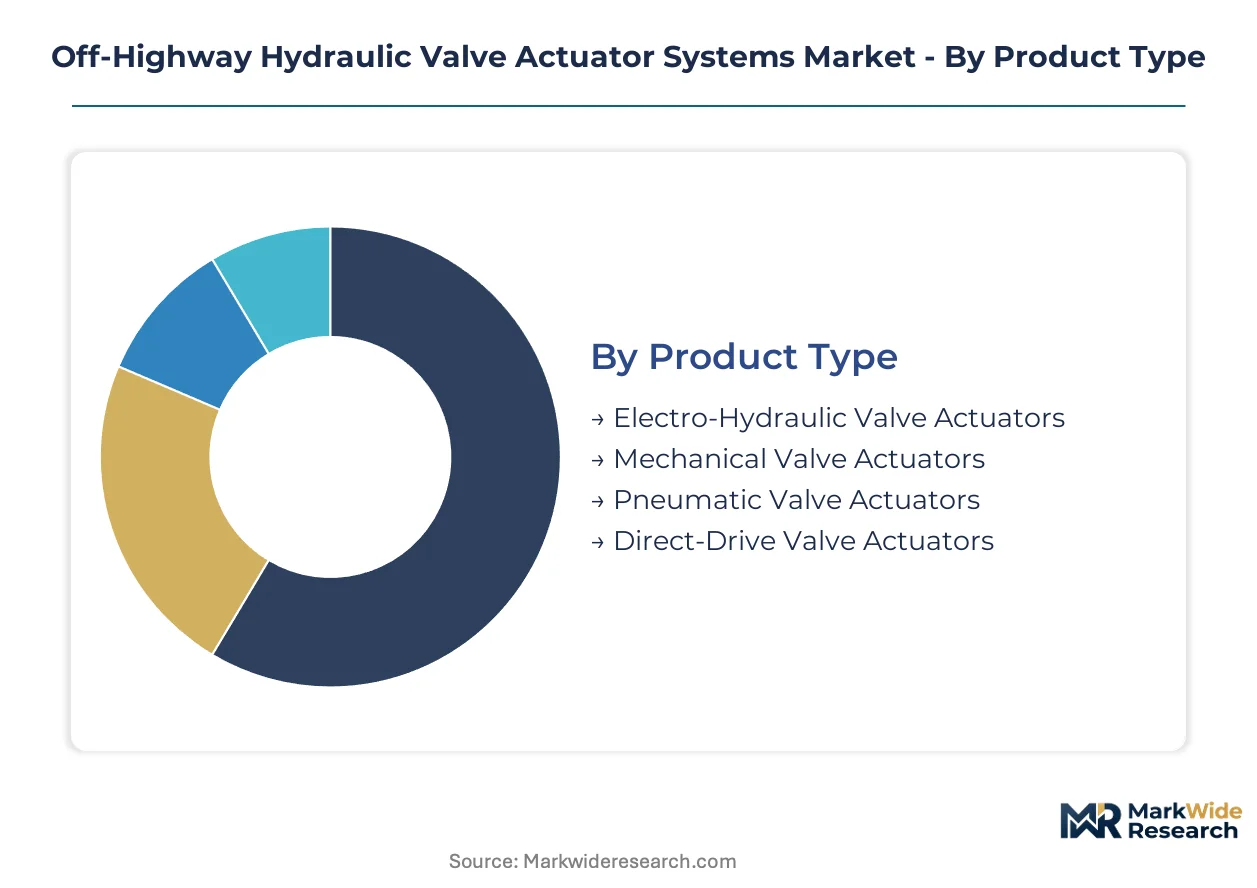
Segmentation in off-highway hydraulic valve actuators reveals how technology tiers and procurement channels fragment across equipment lifecycles. Product architecture choices cascade through calibration requirements, aftermarket service models, and regional manufacturing footprints.
Product Type:
Electro-hydraulic actuators dominate export flows to European and North American construction OEMs, while mechanical variants serve price-sensitive domestic agricultural markets in India and Brazil.
- Electro-Hydraulic Valve Actuators:These assemblies integrate proportional solenoids with closed-loop position feedback, enabling sub-millimeter articulation precision for boom and bucket functions. Demand concentrates in German and Japanese construction machinery OEMs where pilot control elimination drives specification upgrades. EPA Tier 4 Final packaging constraints favor compact integrated designs that compress discrete component mounting.
- Mechanical Valve Actuators:Cable and linkage architectures translate operator input into spool displacement without electrical intermediaries. Procurement clusters in Indian tractor manufacturing and Brazilian agricultural equipment where cost thresholds block electro-hydraulic conversion. BIS standards tightening on hydraulic system efficiency create gradual upgrade pressure.
- Pneumatic Valve Actuators:Compressed air-driven spool positioning serves auxiliary functions in mining ventilation and forestry equipment where explosion-proofing requirements apply.
- Direct-Drive Valve Actuators:Linear motor architectures eliminate intermediate mechanical stages for ultra-high-response applications in autonomous construction platforms.
Electro-hydraulic valve actuators hold the largest share; momentum sits with direct-drive architectures for autonomous equipment.
Technology:
Control methodology stratifies by precision requirements and cost structure, with proportional and load-sensing architectures commanding premium positioning against simpler ON/OFF alternatives.
- Proportional Control:Variable solenoid current modulates spool position across intermediate states, enabling smooth velocity profiling for earthmoving equipment boom circuits. Japanese OEMs specify these architectures for excavator multi-function coordination where simultaneous actuator demand risks flow saturation.
- Load Sensing Control:Pressure-compensated flow matching adjusts pump output to actual actuator demand, eliminating energy waste in agricultural equipment with intermittent hydraulic cycles. German engineering campuses anchor R&D concentration for these architectures.
- ON/OFF Control:Binary solenoid actuation provides directional switching for simple implement circuits in cost-driven emerging-market equipment.
- Servo Control:Closed-loop electronic feedback achieves positioning accuracy for precision forestry harvesting heads and automated grading attachments.
Load sensing control captures expanding margin pools in agricultural applications; proportional architectures gain share fastest in construction electrification.
Application:
Equipment category determines pressure ratings, duty cycles, and environmental sealing specifications that reshape actuator material selection.
- Construction Machinery:Earthmoving platforms operate above 350 bar with cyclic load conditions demanding high-cycle seal durability. OEM procurement in Germany and the United States specifies integrated actuator-manifold assemblies to resolve Tier 4 Final packaging constraints.
- Agricultural Equipment:Tractor hydraulic systems face seasonal utilization patterns with extended idle periods that accelerate seal degradation. Indian mechanization trends drive specification upgrades as BIS standards tighten on system efficiency.
- Mining Machines:Underground equipment requires explosion-proof actuator housings and corrosion-resistant coatings for high-particulate environments.
- Forestry Tools:Harvesting heads and forwarders demand precision positioning for delicate timber handling alongside impact resistance for felling operations.
Construction machinery holds the largest share; agricultural equipment presents the steepest expansion trajectory in Indian and Southeast Asian markets.
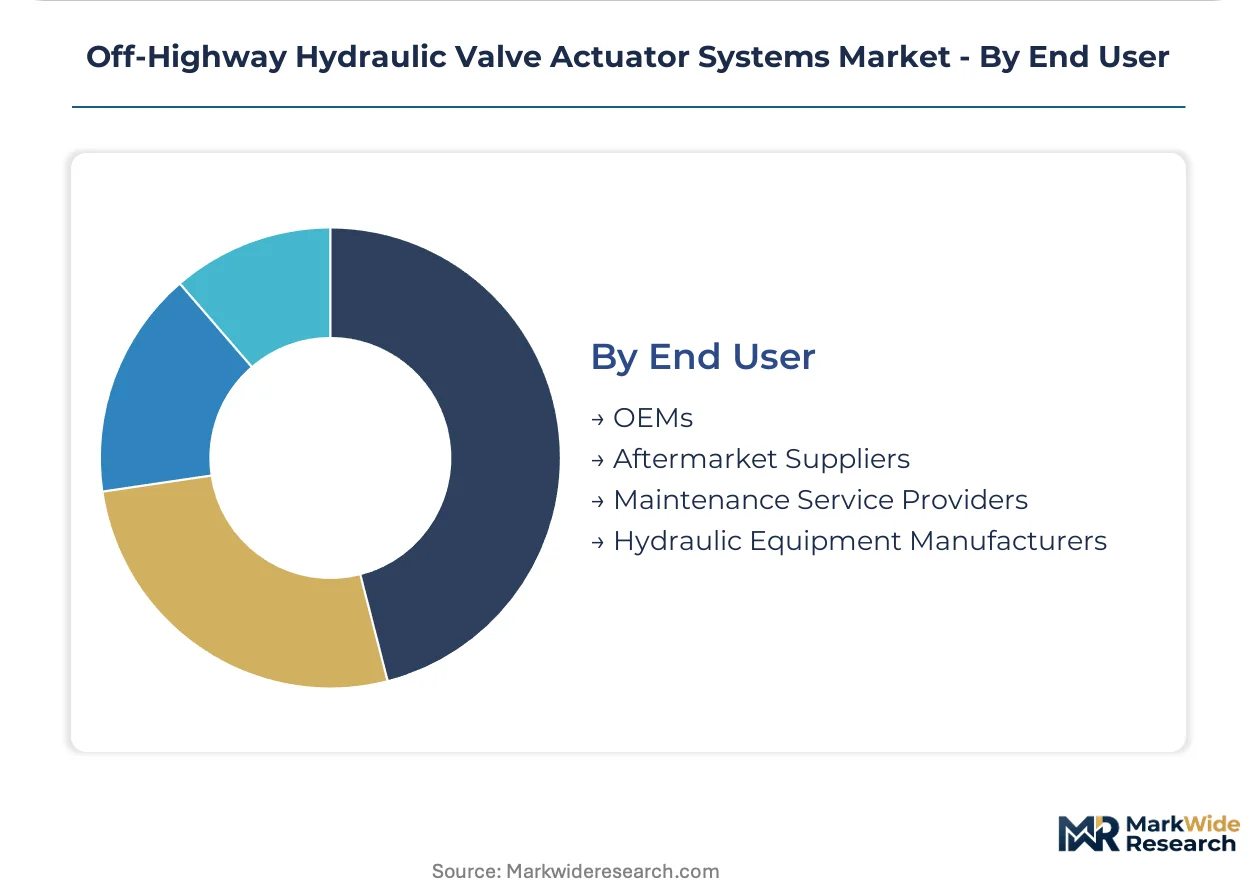
End User:
Procurement authority fragments between factory-installed specifications and aftermarket replacement channels with diverging technical service requirements.
- OEMs:Original equipment manufacturers specify actuator architectures during platform design, locking in multi-year supply agreements with electro-hydraulic specialists. German construction machinery producers dominate procurement volume for integrated valve-manifold assemblies.
- Aftermarket Suppliers:Independent distributors capture cartridge replacement volume through ISO 4406 cleanliness monitoring contracts that displace fixed-hour maintenance schedules. North American fleet management companies consolidate procurement authority for scheduled replacement programs.
- Maintenance Service Providers:Field technicians require specialized calibration equipment for solenoid impedance matching and position sensor alignment that traditional hydraulic service networks lack.
- Hydraulic Equipment Manufacturers:Component suppliers integrate purchased actuators into custom manifold assemblies for regional equipment builders serving niche applications.
OEMs hold the largest share; aftermarket suppliers are expanding most quickly through predictive maintenance contract models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German construction machinery OEMs concentrate procurement authority for integrated actuator-manifold assemblies. Japanese excavator manufacturers drive specification upgrades for closed-loop position feedback systems. Indian tractor producers anchor emerging-market volume for load-sensing architectures.
United States
Construction fleet operators consolidate procurement through predictive maintenance contracts bundling ISO 4406 fluid analysis with scheduled cartridge replacement. EPA Tier 4 Final compliance crowds engine compartments with aftertreatment hardware that consumes hydraulic mounting space. Illinois-based distributors capture aftermarket volume through position sensor refurbishment capabilities.
Germany
Bosch Rexroth and Bucher Hydraulics anchor advanced manufacturing clusters for mobile hydraulic components serving European construction OEMs. EU Stage V emissions mandates force compact integrated designs that eliminate discrete component mounting. Bavarian engineering campuses concentrate R&D intensity for load-sensing control architectures.
China
GB standards for non-road mobile machinery impose technical requirements that filter market access for imported actuator platforms. Beijing's dual carbon goals redirect R&D budgets toward energy-efficient hydraulic architectures. Yangtze River Delta foundries cluster ductile iron casting capacity for valve bodies.
Japan
Excavator OEMs specify proportional control architectures for multi-function coordination where simultaneous actuator demand risks flow saturation. METI industrial policy supports precision manufacturing capabilities for sub-millimeter articulation requirements. Nagoya-based producers dominate closed-loop spool position feedback specifications.
India
Tractor hydraulic system upgrades create demand for load-sensing valve actuators as BIS standards tighten on system efficiency. Agricultural mechanization trends drive specification upgrades beyond cost-driven mechanical architectures. Maharashtra and Gujarat manufacturing corridors concentrate domestic assembly capacity.
Off-Highway Hydraulic Valve Actuator Systems Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with captive hydraulics divisions alongside specialized fluid power component houses. Market structure concentrates specification authority among German and US-based OEM-facing suppliers with integrated manufacturing footprints. Two archetypes dominate: full-system integrators controlling foundry-to-assembly verticality, and focused cartridge specialists capturing aftermarket replacement cycles. Competitive moves center on capacity consolidation in German manufacturing basins and technology licensing arrangements for Indian market entry.
Among European-headquartered industrial groups, Bosch Rexroth and Danfoss Power Solutions occupy positions as specification anchors for construction machinery electrification. Bucher Hydraulics sits within the specialized tier serving premium OEM integration requirements. These three entities exemplify the geographic clustering that shapes competitive access to Tier 4 Final and Stage V compliance-driven procurement cycles.
| Leading Market Players |
|---|
| Bosch Rexroth |
| Danfoss Power Solutions |
| Parker Hannifin |
| Eaton |
| Bucher Hydraulics |
| HAWE Hydraulik |
| HydraForce |
| Sun Hydraulics |
| Moog |
| Others |
Pricing and Supply Chain Analysis
ISO 4406 cleanliness certification gates supplier qualification and price differentiation simultaneously, as particle-count-controlled manufacturing environments command premium positioning while excluding cost-driven mechanical actuator producers from European and North American construction OEM procurement cycles.
Pricing Analysis
Cost-plus contracts with steel and rare-earth magnet indexation dominate electro-hydraulic actuator procurement between German construction OEMs and their tier-one suppliers. Price differentiation rests on certification grade and volume scale, with ISO 4406-compliant manufacturers capturing standard-tier premiums over uncertified competitors. Pricing pressure stems from REACH-compliant fluorocarbon seal material volatility compressing margins in the economy tier. Emerging-market agricultural equipment buyers exhibit highest price sensitivity, while German construction machinery OEMs prioritize performance over unit cost.
Supply Chain Analysis
Inbound logistics costs from Yangtze River Delta ports to European assembly plants fluctuate with container availability on the Asia-North Europe trade lane, compressing just-in-time delivery windows for ductile iron valve body castings. Supply concentrates in Germany, China, and Japan, with Yangtze River Delta foundries and Bavarian machining clusters anchoring upstream capacity. Raw material dependencies span ductile iron feedstock, copper winding wire for solenoid coils, and neodymium rare-earth magnets. Single-source vulnerability runs through Chinese rare-earth processing. Distribution runs through captive OEM supply agreements and independent aftermarket distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electro-hydraulic calibration expertise scarcity constrains market expansion, as solenoid coil impedance matching and spool position sensor alignment require technician capabilities absent from traditional hydraulic service networks.
For Market Incumbents: Fortify backward integration into captive foundry capacity to secure ductile iron supply against Yangtze River Delta concentration risk. Expand ISO 4406-certified manufacturing footprints in India to capture agricultural mechanization demand before BIS standards fully tighten. Prioritize R&D investment in direct-drive architectures for autonomous construction platforms. For New Entrants and Emerging Players: Anchor in Indian tractor hydraulic system upgrades as the most penetrable white-space target, where load-sensing actuator demand outpaces domestic supply capability. Target aftermarket sensor refurbishment services through predictive maintenance contract models displacing fixed-hour replacement schedules. Pursue technology licensing arrangements with established German engineering campuses to bypass certification barriers. For Investors and Strategic Acquirers: EU Stage V emissions compliance deadlines reshape the acquisition landscape toward integrated actuator-manifold specialists with proven Tier 4 Final qualification records. Long-term viability favors targets with captive machining capacity and established OEM specification authority. Monitor Chinese dual carbon policy implementation as the signal indicating accelerated R&D budget redirection toward energy-efficient architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Capacity | Secures ductile iron supply against Yangtze River Delta single-source exposure for German OEM suppliers. |
| ISO 4406 Certification Investment | Unlocks European construction machinery procurement cycles previously gated to particle-count-controlled manufacturers. |
| Direct-Drive Architecture Development | Positions suppliers for autonomous construction platform specifications requiring ultra-high-response actuator coordination. |
| Indian Manufacturing Footprint Expansion | Captures agricultural mechanization volume as BIS standards tighten on tractor hydraulic system efficiency. |
| Predictive Maintenance Contract Launch | Displaces break-fix aftermarket relationships through ISO 4406 fluid analysis bundling with scheduled cartridge replacement. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with hydraulic system engineers, OEM procurement directors, aftermarket service technicians, and fleet maintenance managers; and secondary validation through customs trade data, SEC filings from diversified industrial conglomerates, association reports from fluid power industry bodies, and technical documentation from regulatory filings with EPA and EU Stage V compliance databases. Bottom-up equipment production forecasts triangulated against top-down hydraulic component consumption estimates.
Across the analysis window, the forecasting framework modeled demand by product architecture, control technology tier, equipment application category, and procurement channel. CAGRs derived from equipment production trajectories, technology substitution curves for electro-hydraulic versus mechanical architectures, and emissions compliance-driven redesign cycles. Industry-specific inputs incorporated foundry capacity utilization rates and rare-earth magnet price index movements.
Material uncertainties — commodity price volatility, regulatory enforcement timing variations, and autonomous equipment adoption acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding technology substitution rates and OEM specification inertia. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Valve Remote Control System Market
Valves
Float Traps Market
Valves
Large Bore Vacuum Insulated Pipe Market
Valves
Valve Manifold Box (VMB) Market
Valves
Sanitary Valves Market
Valves
Europe Butterfly Valve Market
Valves
Pinch Valve Market
Valves
Global Solenoid Valves Market
Valves
Actuators and Valves Market
Valves
Global Valves in Oil and Gas Industry Market
Valves
Electrohydraulic Servo Valves (Ehsvs) Market
Valves
Global Plastic Valves Market
Valves
Mobile Hydraulic Valves Market
Valves
Subsea Control System Market
Valves
Middle East and Africa Industrial Valves Market
Valves
Three Way Ball Valve Market