
 Steel Cylinder Market | 2026-2036
Steel Cylinder Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Cylinder Market Insights
The capital-intensity divergence between integrated steel producers and specialized fabricators is redrawing competitive boundaries in steel cylinder manufacturing. Worthington Enterprises leverages its backward integration into steel processing to control input costs across North American operations. Everest Kanto Cylinder anchors its position through dominant share in India's compressed natural gas vehicle segment. Hexagon Composites differentiates by competing with lightweight composite-wrapped alternatives that challenge conventional steel in weight-sensitive applications.
Steel cylinders are seamless or welded pressure vessels fabricated from carbon steel, alloy steel, or specialty grades, typically designed to withstand internal pressures from 150 bar to over 700 bar depending on application and wall thickness. Hot working and automated welding remain dominant fabrication routes for industrial-grade units, while cold working and ultrasonic testing define premium medical and high-purity gas segments. Seamless cylinders command premium positioning in hydrogen and medical gas storage where defect tolerance approaches zero. Welded constructions occupy volume-driven industrial gas and fire protection segments where cost efficiency outweighs absolute performance margins.
ISO 9809 governs design, manufacture, and testing of refillable steel gas cylinders worldwide, while DOT specifications enforced by PHMSA regulate US transportable pressure equipment and EPA oversight affects cylinder coatings and surface treatments. The EU Pressure Equipment Directive and F-Gas Regulation collectively tighten material traceability and leak-tightness standards across European supply chains. Stakeholders must monitor hydrogen embrittlement research and evolving certification protocols for 700-bar containment as clean energy infrastructure scales.
Market Dynamics
The hydrogen economy buildout is compressing certification timelines and forcing fabricators to choose between seamless premium positioning and welded volume strategies. Capital allocation now hinges on 700-bar containment readiness rather than traditional industrial gas cycles.
Growth Catalysts
- Hydrogen pipeline investments:Germany's SoutH2 and similar corridor projects across the Netherlands and Spain are pulling demand for ISO 9809-1 certified seamless cylinders capable of 700-bar service.
- EU F-Gas Regulation phase-down:The refrigerant containment mandate is accelerating cylinder replacement cycles for HVAC service fleets and industrial gas distributors.
- CrMo alloy advances:Chromium-molybdenum steel grades with enhanced hydrogen compatibility are extending service life in high-cycle refueling applications.
Market Restraints
- Scrap steel volatility:Electric arc furnace feedstock costs swing with construction demolition cycles, compressing margin predictability for welded cylinder producers.
- Seamless billet concentration:Five integrated mills control premium rotary forging feedstock, creating bottleneck risk for medical and hydrogen-grade cylinder supply.
- Composite substitution pressure:Type IV carbon-fiber wrapped vessels from Hexagon and NPROXX are capturing weight-sensitive mobility applications above 350 bar.
Strategic Opportunities
- Saudi Arabia hydrogen exports:NEOM and Red Sea Project offtake agreements are creating demand for high-pressure containment systems in a market with limited local fabrication.
- Medical oxygen homecare expansion:India's Ayushman Bharat rural health infrastructure is pulling lightweight aluminum-lined steel cylinders for portable therapeutic gas delivery.
- Remanufacturing services:Cylinder requalification and neck ring replacement programs offer recurring revenue streams as installed base ages across European industrial gas networks.
Industry Challenges
- ASME BPVC Section VIII certification backlog:Third-party inspector capacity constraints are extending time-to-market for novel high-pressure designs.
- Hydrogen embrittlement testing protocols:Evolving ISO 11114-4 material compatibility standards require destructive testing investments that strain mid-cap fabricator R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Cylinder Market |
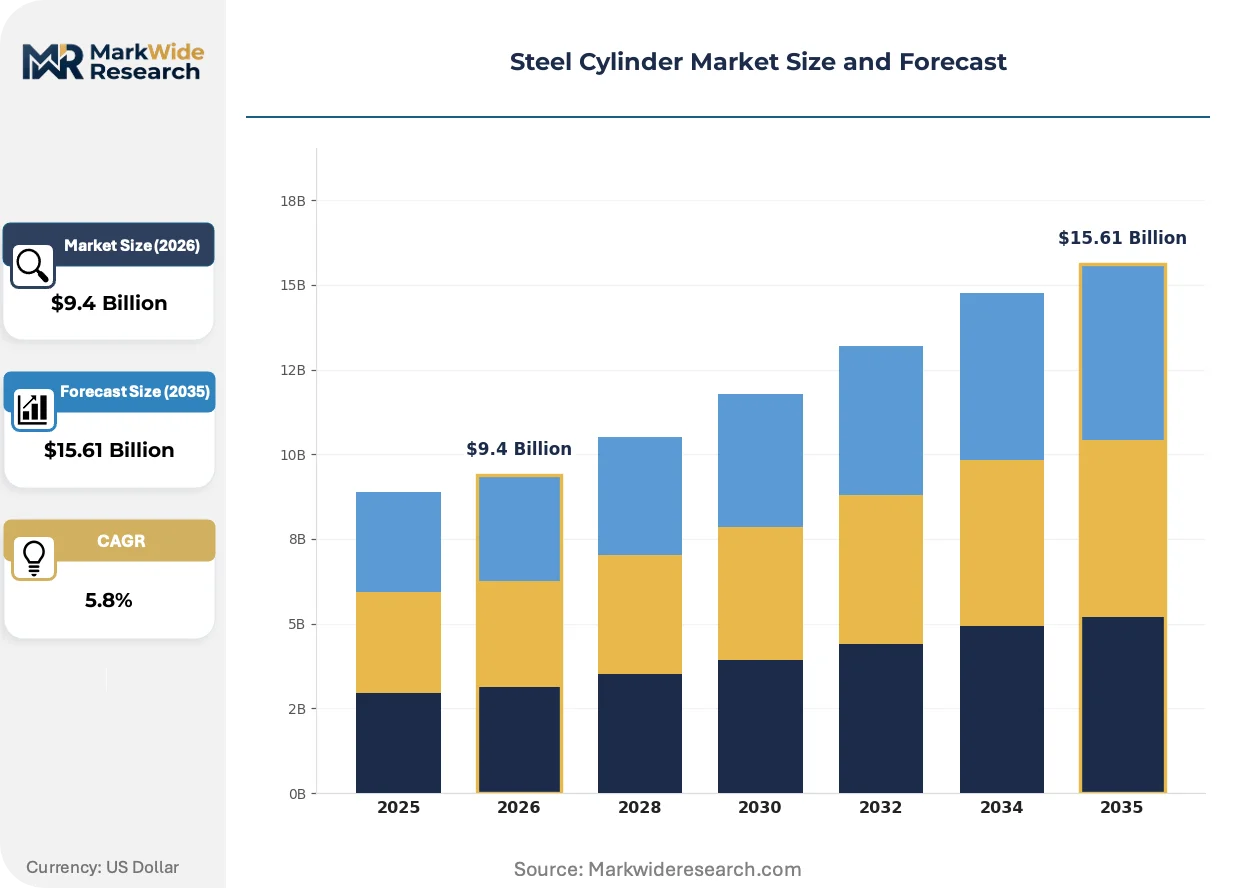
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $15.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seamless, Welded, High-Pressure, Low-Pressure, Composite, Specialty Alloy Application: Industrial Gases, Medical Gas Storage, Fire Protection, Food & Beverage, Diving & Scuba, Chemical Processing End User: Manufacturers, Research Laboratories, Fire Departments, Beverage Bottlers, Diving Schools, Chemical Plants Technology: Cold Working, Hot Working, Surface Coating, Heat Treatment, Ultrasonic Testing, Automated Welding |
| Companies Covered | Worthington Enterprises Inc., Hexagon Composites ASA, Tenaris S.A., Everest Kanto Cylinder Ltd., Luxfer Holdings PLC, Chart Industries Inc., TriMas Corporation, Norris Cylinder Company, CIMC Enric Holdings Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Cylinder Market Trends and Innovations
Digital traceability and automated non-destructive testing are redefining quality assurance economics. Fabricators now compete on data transparency rather than unit cost alone.
Ultrasonic phased array inspection is bifurcating the quality tier structure. Seamless cylinder producers deploy full-body scanning to eliminate manual magnetic particle testing. Medical gas and hydrogen storage buyers now mandate digital defect archives. The technology is compressing price premiums for conventional radiographic certification.
EU F-Gas Regulation tightening is forcing coating chemistry pivots. Epoxy-phenolic internal linings face substitution by powder-based alternatives to meet ECHA substance restrictions. Cylinder requalification intervals are shortening in refrigeration service. German and French distributors are consolidating supplier lists to suppliers with verified REACH compliance documentation.
Leasing models are displacing outright cylinder purchases in industrial gas supply. Air Liquide and Linde are expanding asset-light arrangements where fabricators retain ownership and handle maintenance. This compresses upfront revenue but extends contract durations. The shift is most visible in Benelux and Nordic markets where capital efficiency metrics dominate procurement scoring.
Steel Cylinder Market Segmentation
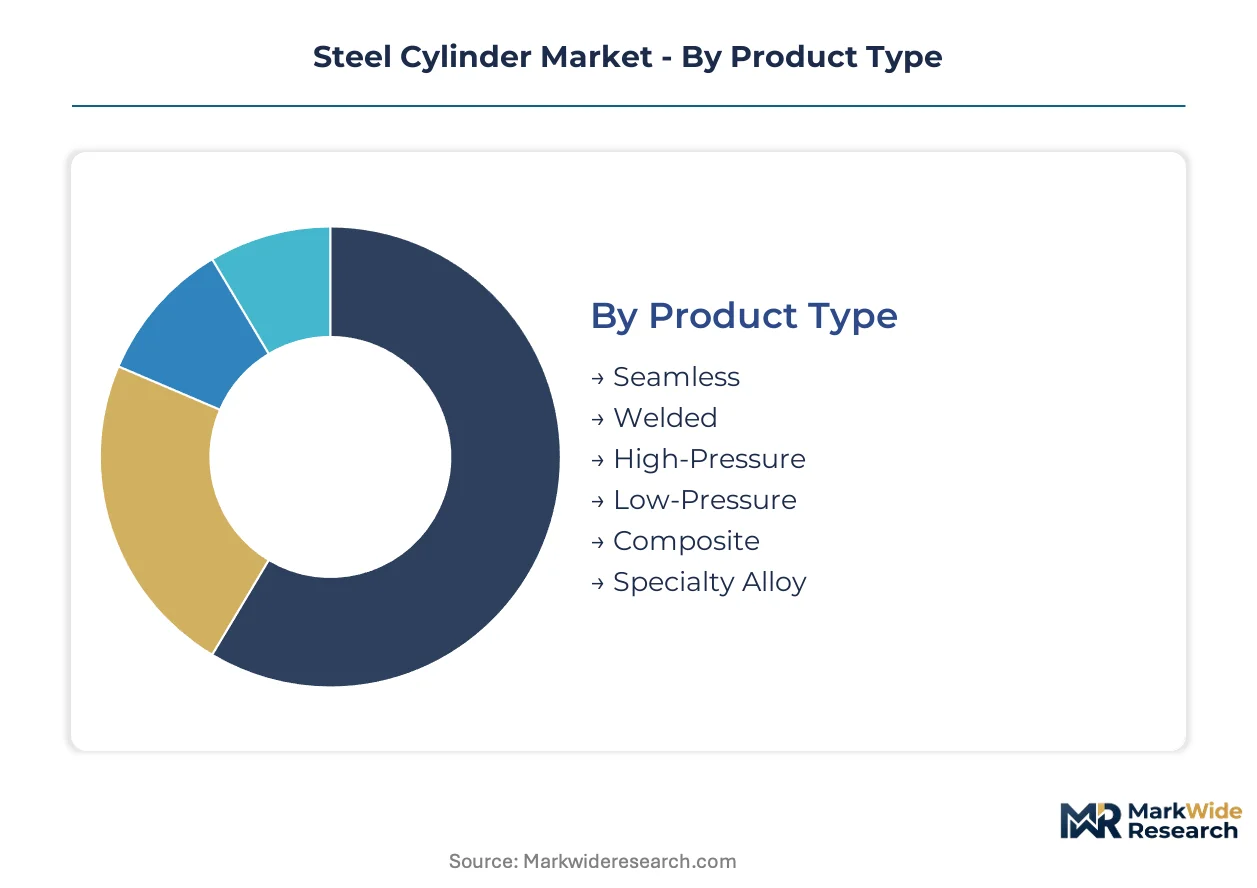
Steel cylinder segmentation reveals how fabrication methods and pressure ratings map to diverging margin structures. Product type and application categories show the clearest fault lines between premium positioning and volume-driven commoditization.
Product Type:
Composite-wrapped alternatives are compressing addressable market for conventional steel across weight-sensitive segments, forcing steel fabricators to defend position through pressure rating specialization and alloy innovation.
- Seamless:Rotary-forged from solid billets with zero weld seams, these cylinders achieve defect tolerance approaching zero for hydrogen and medical gas service. Demand concentrates in Germany's industrial gas corridor where 700-bar containment specifications for hydrogen pipeline injection are tightening certification requirements.
- Welded:Longitudinal or circumferential seam construction from rolled plate enables cost-efficient production of larger-diameter vessels. India's compressed natural gas vehicle fleet and industrial gas distribution networks absorb the highest volumes, though margin pressure from scrap steel volatility constrains producer profitability.
- High-Pressure:Designed for service above 350 bar with enhanced wall thickness and CrMo alloy compositions. Hydrogen refueling infrastructure in the Netherlands and Spain is pulling demand for ISO 9809-1 certified units.
- Low-Pressure:Standard industrial gas storage below 200 bar for welding gases and fire suppression systems. Food and beverage carbonation represents the most stable demand pool.
- Composite:Steel-lined Type III or all-composite Type IV vessels from Hexagon and NPROXX are capturing mobility applications above 350 bar where weight reduction justifies premium pricing.
- Specialty Alloy:Nickel-chromium-molybdenum grades for corrosive chemical service and extreme temperature cycling. Chemical processing clusters in Texas and Louisiana specify these for chlorine and hydrogen fluoride containment.
Welded cylinders anchor the volume base while seamless construction gains share at the steepest rate as hydrogen infrastructure scales.
Application:
End-use concentration patterns diverge sharply between regulated medical environments and price-sensitive industrial procurement.
- Industrial Gases:Oxygen, nitrogen, argon, and acetylene distribution for manufacturing and metal fabrication. Leasing models from Air Liquide and Linde are displacing outright purchases in Benelux and Nordic markets.
- Medical Gas Storage:Ultra-high purity oxygen and nitrous oxide for hospital and homecare delivery. India's Ayushman Bharat rural health infrastructure is pulling lightweight aluminum-lined steel cylinders for portable therapeutic applications.
- Fire Protection:Carbon dioxide and clean agent suppression systems for commercial buildings. US fire code adoption cycles drive replacement demand.
- Food & Beverage:Carbon dioxide for beverage carbonation and modified atmosphere packaging. Brewery consolidation is concentrating procurement among fewer bottlers.
- Diving & Scuba:Breathing air cylinders for recreational and commercial underwater operations. Recreational diving schools in Florida and Queensland represent fragmented demand.
- Chemical Processing:Chlorine, ammonia, and hydrogen containment for petrochemical and fertilizer production. Gulf Coast chemical corridor specifications favor specialty alloy constructions.
Industrial gases commands the largest revenue pool while medical gas storage expands most quickly on homecare infrastructure buildout.
End User:
Customer sophistication tiers separate specification-driven procurement from commodity purchasing.
- Manufacturers:Integrated steel producers and automotive fabricators with captive gas consumption. German automotive OEMs specify seamless cylinders for hydrogen fuel cell testing.
- Research Laboratories:Universities and national research facilities requiring ultra-high purity gas handling. CERN and Max Planck Institutes mandate digital traceability archives.
- Fire Departments:Municipal and industrial fire services with standardized equipment replacement cycles. US municipal budget cycles create lumpy demand patterns.
- Beverage Bottlers:Soft drink and beer producers with high-volume carbon dioxide consumption. Consolidation among Coca-Cola and Pepsi bottlers is reducing supplier counts.
- Diving Schools:Commercial and recreational training facilities with seasonal demand fluctuations. Caribbean and Southeast Asian tourism corridors show strongest concentration.
- Chemical Plants:Petrochemical and specialty chemical producers with hazardous material handling requirements. REACH compliance documentation is mandatory for European chemical majors.
Manufacturers represent the deepest customer relationships while research laboratories pay the steepest specification premiums.
Technology:
Quality assurance automation is bifurcating competitive tiers between digital-capable and manual-dependent fabricators.
- Cold Working:Room-temperature forming of annealed steel for precision dimensional control. Medical and high-purity gas segments specify cold-worked seamless construction exclusively.
- Hot Working:Elevated-temperature forging and rolling for industrial-grade cylinder bodies. Volume production of welded cylinders depends on hot working economics.
- Surface Coating:Epoxy-phenolic internal linings and external powder coating for corrosion resistance. EU F-Gas Regulation is forcing coating chemistry pivots to meet ECHA substance restrictions.
- Heat Treatment:Quenching and tempering protocols to achieve specified mechanical properties. Hydrogen-compatible CrMo grades require precise thermal processing windows.
- Ultrasonic Testing:Phased array inspection replacing manual magnetic particle testing. Full-body scanning is becoming mandatory for hydrogen service certification.
- Automated Welding:Robotic longitudinal and circumferential seam joining for welded cylinder production. Turkish and Indian fabricators have invested most aggressively in automation.
Hot working underpins cost-competitive production while ultrasonic testing is climbing the fastest as digital defect archives become standard.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. German buyers absorb seamless cylinder premiums for hydrogen infrastructure while Indian fleet operators drive welded cylinder volumes on thin margins. The United States sits between these poles with specification-driven medical demand and price-sensitive industrial procurement.
Germany
SoutH2 and other hydrogen corridor projects pull ISO 9809-1 certified seamless cylinders for 700-bar pipeline injection service. The EU F-Gas Regulation accelerates replacement cycles for HVAC service fleets. The Ruhr industrial gas cluster concentrates procurement among distributors requiring REACH-compliant coating documentation.
India
Ayushman Bharat rural health infrastructure creates demand for lightweight aluminum-lined steel cylinders in portable medical oxygen delivery. The country's national pharmaceutical regulator tightens traceability requirements for therapeutic gas containment. Gujarat and Maharashtra host compressed natural gas vehicle conversion hubs that absorb welded cylinder volumes.
United States
PHMSA DOT specifications govern transportable pressure equipment across state lines while EPA oversight affects cylinder coating chemistries. The Gulf Coast chemical corridor specifies specialty alloy constructions for chlorine and hydrogen fluoride service. Texas and Louisiana petrochemical clusters drive premium-grade demand.
Netherlands
Port of Rotterdam hydrogen import terminal investments require high-pressure containment systems for buffer storage. The EU Pressure Equipment Directive tightens material traceability standards across supply chains. Eindhoven-region industrial gas distributors consolidate supplier lists to asset-light leasing model partners.
Saudi Arabia
NEOM and Red Sea Project offtake agreements create demand for high-pressure containment in a market with limited local fabrication capacity. The country's national standards body aligns certification protocols with ISO frameworks for hydrogen export infrastructure. Jeddah and Jubail industrial zones concentrate procurement for downstream chemical applications.
Steel Cylinder Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the steel cylinder market. The vendor base splits between integrated steel processors controlling input costs and specialized fabricators focusing on alloy innovation and certification depth. Three archetypes dominate: backward-integrated metal processors, regional volume specialists, and composite-alternative challengers. Competitive moves center on 700-bar hydrogen certification readiness and automated non-destructive testing deployment.
Among publicly traded industrial conglomerates, Worthington Enterprises Inc. exemplifies the backward-integrated archetype through captive steel processing. Everest Kanto Cylinder Ltd. represents regional volume specialization with dominant positioning in compressed natural gas vehicle markets. Hexagon Composites ASA occupies the alternative-materials vector, challenging conventional steel with composite-wrapped constructions in weight-sensitive applications above 350 bar.
| Leading Market Players |
|---|
| Worthington Enterprises Inc. |
| Hexagon Composites ASA |
| Tenaris S.A. |
| Everest Kanto Cylinder Ltd. |
| Luxfer Holdings PLC |
| Chart Industries Inc. |
| TriMas Corporation |
| Norris Cylinder Company |
| CIMC Enric Holdings Limited |
| Others |
Pricing and Supply Chain Analysis
Ninety-day order-to-delivery cycles for seamless hydrogen-grade cylinders concentrate pricing power among rotary forging specialists in Germany and Japan, while welded cylinder producers absorb scrap steel volatility through shorter contract structures. This lead-time asymmetry separates premium containment markets from commoditized industrial gas supply.
Pricing Analysis
After-sales revenue from cylinder requalification and neck ring replacement programs now drives lifetime value for established fabricators. Three-tier pricing structure across premium seamless, standard welded, and economy refurbished units reflects ISO 9809-1 certification depth and ultrasonic testing coverage. Cost compression in welded segments is intensifying because Indian and Turkish producers automate longitudinal seam joining. Fleet operators in compressed natural gas vehicle markets exhibit highest price sensitivity, while German hydrogen corridor developers accept steep premiums for 700-bar containment readiness.
Supply Chain Analysis
China and India anchor welded cylinder fabrication through hot-rolled plate processing and automated circumferential welding investments. Germany and Japan control seamless billet supply through integrated rotary forging capacity. Raw material flows draw from electric arc furnace scrap cycles, chromium-molybdenum alloy imports, and epoxy-phenolic coating chemistries facing REACH substitution pressure. Single-source vulnerability concentrates in premium seamless feedstock where five integrated mills govern medical and hydrogen-grade supply. Distribution runs through industrial gas distributor networks, asset-light leasing arrangements in Benelux, and direct procurement by automotive OEMs for fuel cell testing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hydrogen economy buildout constitutes a high-growth disruption. The EU F-Gas Regulation phase-down and 700-bar certification mandates compress competitive timelines for conventional fabricators.
For Market Incumbents: Compound defensive positioning through backward integration into steel processing and captive ultrasonic testing capacity. Threats from Hexagon Composites and NPROXX in weight-sensitive mobility above 350 bar demand alloy innovation in CrMo hydrogen-compatible grades. Priority levers include ASME BPVC Section VIII certification pre-positioning and automated phased array inspection deployment. For New Entrants and Emerging Players: Differentiate on digital traceability archives and rapid 700-bar qualification pathways for hydrogen refueling infrastructure. Saudi Arabia's NEOM and Red Sea Project offtake agreements represent the most penetrable geography given limited local fabrication capacity. Go-to-market angle should target EPC contractors with bundled containment and requalification service contracts. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized seamless cylinder divisions and stranded ASME certification assets. Five-to-ten-year viability hinges on hydrogen pipeline investment trajectories in Germany, Spain, and the Netherlands. Signal to monitor: ISO 11114-4 material compatibility standard finalization and destructive testing protocol adoption rates among mid-cap fabricators.| Strategic Initiative | Industry Significance |
|---|---|
| 700-bar Certification Pre-Positioning | ASME BPVC Section VIII readiness unlocks German SoutH2 corridor procurement. |
| Backward Integration into Steel Processing | Captive feedstock control insulates margin from scrap volatility swings. |
| Automated Phased Array Inspection Deployment | Full-body scanning replaces manual testing for hydrogen service mandates. |
| Asset-Light Leasing Model Expansion | Air Liquide and Linde partnerships extend contract duration in Nordic markets. |
| CrMo Alloy Hydrogen Compatibility Investment | Extended service life in high-cycle refueling differentiates premium positioning. |
Research Methodology
A standing panel of cylinder fabrication plant managers, industrial gas procurement leads at Linde and Air Liquide, EPC contractors for hydrogen infrastructure, and aftermarket requalification service heads provided ongoing calibration across the study period. Primary interview findings were cross-validated against secondary sources including ISO 9809 certification databases, PHMSA incident reports, EU Pressure Equipment Directive guidance documents, and customs trade data for seamless and welded cylinder imports. Bottom-up unit economics modeling was triangulated with top-down market sizing from hydrogen pipeline investment disclosures.
Consistency checks validated volume and value outputs against external benchmarks including industrial gas distributor fleet expansion plans and automotive OEM fuel cell testing facility buildouts. The analytical framework modeled segmentation across fabrication method, pressure rating tier, application category, and regional regulatory cluster throughout the forecast period. CAGRs were derived from hydrogen infrastructure deployment curves, F-Gas Regulation replacement cycle assumptions, and medical oxygen homecare penetration trajectories in rural India.
Forecasts assume regulatory continuity in EU F-Gas phase-down schedules and PHMSA DOT specification enforcement; material policy shifts would require re-modeling. Specific risks include hydrogen embrittlement testing protocol changes, seamless billet supply disruptions, and composite substitution acceleration in mobility applications. Recalibration cycles align with material shifts in ISO certification standards and hydrogen corridor project sanctioning decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Explosion Proof Solenoid Valves Market
Valves
Global Marine Actuators and Valves Market
Valves
Deluge Valve Market
Valves
Degassing Valves Market
Valves
Butterfly Valves Market
Valves
Subsea Control System Market
Valves
HVAC Valves Market
Valves
Gate Impellers Market
Valves
Wind Energy Fasteners Market
Valves
Pulsation Dampeners Market
Valves
North America Butterfly Valve Market
Valves
North America Industrial Valves Market
Valves
Choke Valves Market
Valves
Christmas Tree Valves Market
Valves
China Explosion-Proof Equipment Market
Valves
Pipeline and Process Services Market