
 Battery Pack Cooling Valve Actuator Systems Market | 2026-2036
Battery Pack Cooling Valve Actuator Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Pack Cooling Valve Actuator Systems Market Insights
German Tier-1 thermal suppliers is shifting toward integrated valve-actuator modules for next-generation battery platforms. Robert Bosch leverages its mechatronics heritage to anchor high-volume contracts with European EV programs. Denso Corporation sustains manufacturing scale across Japanese and North American plants for hybrid cooling architectures. MAHLE specializes in compact actuator designs that navigate tight pack geometries in premium electric SUVs.
Battery pack cooling valve actuator systems modulate coolant flow through precision electromechanical or pneumatic mechanisms, typically achieving response times under 100 milliseconds to maintain cell temperatures within 2°C of target setpoints across distributed thermal zones. These assemblies prevent thermal runaway propagation while optimizing charging efficiency in lithium-ion and solid-state configurations. Electric actuators dominate OEM specifications for their programmable flow profiles and integration with battery management systems, whereas brushless DC motor technology leads in high-cycle applications requiring maintenance-free operation beyond 10 million actuations. The application split favors electric vehicles where pack energy density demands intensify cooling circuit complexity, while renewable energy storage represents an emerging margin pool as grid-scale batteries adopt automotive-derived thermal architectures.
FDA oversight of battery-powered medical transport vehicles, EPA emissions credits tied to battery durability, and NHTSA thermal runaway testing protocols collectively elevate actuator reliability standards for US market access. Europe's REACH chemical restrictions and CE marking requirements for electromagnetic compatibility shape material selection and validation protocols for valve components. Stakeholders must monitor how solid-state battery thermal profiles alter coolant flow dynamics and whether actuator suppliers can adapt stroke ranges and sealing materials without platform redesigns.
Market Dynamics
Electric vehicle OEMs are consolidating thermal management procurement around integrated valve-actuator modules, compressing supplier tiers and eliminating standalone component vendors from next-generation battery platform contracts.
Growth Catalysts
- China's NMPA battery safety mandates:Mandatory thermal runaway propagation testing is forcing automakers to install redundant cooling circuits with precision actuators.
- Pack energy density escalation:Lithium-ion and emerging solid-state configurations demand tighter temperature uniformity across cell arrays.
- Germany's supplier corridor concentration:Stuttgart and Munich clusters accelerate co-development cycles between actuator specialists and EV thermal system architects.
Market Restraints
- Permanent magnet supply vulnerability:Brushless DC motors depend on rare-earth materials concentrated in Chinese processing facilities.
- REACH chemical restrictions:European sealing material bans limit elastomer options for high-temperature coolant compatibility.
- Pneumatic actuator legacy infrastructure:Existing stamping plant compressed air systems create switching friction for electromechanical upgrades.
Strategic Opportunities
- Grid-scale energy storage:Renewable battery installations are adopting automotive-derived thermal architectures for flow modulation.
- US IRA domestic content credits:Battery component manufacturing incentives attract actuator production to North American facilities.
- Solid-state battery thermal profiles:Altered heat rejection curves require redesigned stroke ranges and flow coefficients.
Industry Challenges
- Mechatronics talent scarcity:Electromechanical actuator design requires rare combinations of motor control firmware and fluid dynamics expertise.
- ECE R100 revision compliance timelines:European validation protocols for electromagnetic compatibility extend product development cycles.
- Legacy CAN bus integration:New smart actuators must interoperate with established battery management system communication stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Pack Cooling Valve Actuator Systems Market |
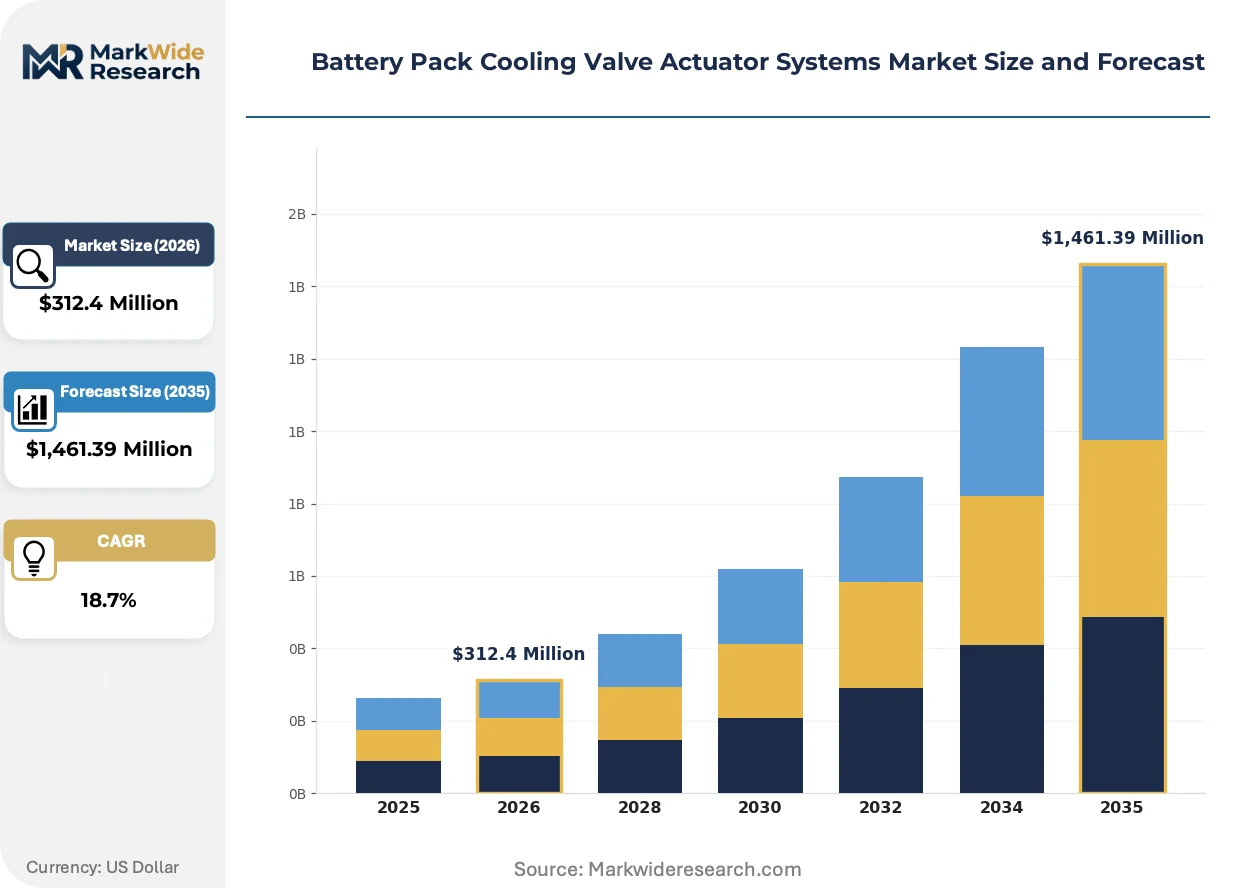
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,461.39 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Actuators, Pneumatic Actuators, Hydraulic Actuators, Manual Actuators Technology: Brushless DC Motor, Stepper Motor, Linear Actuator, Rotary Actuator Application: Electric Vehicles, Hybrid Electric Vehicles, Industrial Equipment, Renewable Energy Storage End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | Robert Bosch, Denso Corporation, MAHLE, Valeo, Hanon Systems, Continental, Johnson Electric, ZF Friedrichshafen, Nidec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Pack Cooling Valve Actuator Systems Market Trends and Innovations
Valve-actuator integration is compressing the thermal management supply chain, eliminating discrete component procurement in favor of subsystem sourcing from consolidated Tier-1 suppliers.
Brushless DC motor technology with integrated position sensing is unifying motion control and feedback functions within single sealed housings. European premium SUV programs are specifying these modules for under-hood packaging constraints. This convergence is unifying what were three separate supplier relationships into single-source contracts.
ECE R100 electromagnetic compatibility revisions are mandating shielding and filtering specifications that add validation cost but prevent interference-induced valve malfunction. Test houses in Germany report expanded booking queues for automotive thermal component certification. Korean and Japanese battery OEMs exporting to Europe are redesigning actuator harness routing to comply.
Fleet operators are compressing supplier qualification cycles, demanding 10-million-cycle durability guarantees before platform sourcing decisions. Commercial vehicle and energy storage buyers are displacing traditional automotive procurement timelines with accelerated technical audits. This pattern is most visible in California and Texas, where logistics electrification and grid storage deployment timelines outpace standard automotive development cadences.
Battery Pack Cooling Valve Actuator Systems Market Segmentation
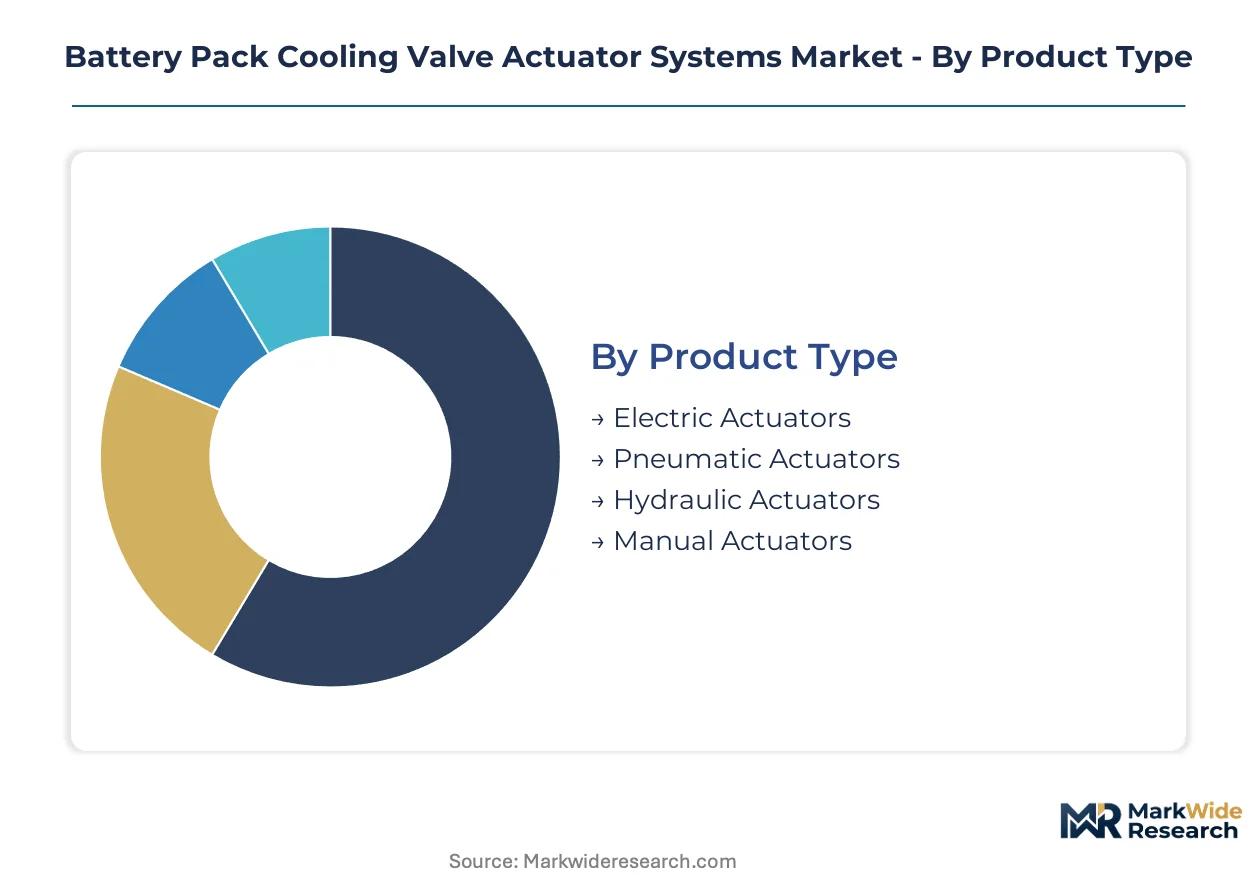
Battery pack cooling valve actuator systems fragment across four critical dimensions that determine procurement patterns, certification pathways, and margin structures. Product type and technology choices lock in electromagnetic compatibility requirements under ECE R100 and NMPA mandates, while application and end-user splits dictate volume concentration and aftermarket serviceability.
Product Type:
Certification burden falls heaviest on electric actuators, which must satisfy electromagnetic compatibility testing under ECE R100 and NMPA battery safety protocols, while pneumatic variants face fewer regulatory hurdles but struggle with compressed air infrastructure dependencies.
- Electric Actuators:Electromechanical assemblies with programmable flow profiles and integrated position sensing achieve response times under 100 milliseconds. OEM specifications in Germany's Stuttgart-Munich corridor dominate procurement, driven by NMPA thermal runaway propagation mandates requiring redundant cooling circuit precision.
- Pneumatic Actuators:Compressed air-driven mechanisms leverage existing stamping plant infrastructure but face switching friction from electromechanical upgrades. Demand concentrates in legacy hybrid architectures where electromagnetic interference concerns limit electric alternatives.
- Hydraulic Actuators:Fluid-power systems deliver high force density for grid-scale energy storage coolant circuits. REACH chemical restrictions constrain sealing material selection for European installations.
- Manual Actuators:Hand-operated valves serve aftermarket service and diagnostic applications where electronic integration is unnecessary. Limited to repair scenarios and prototyping environments.
Electric actuators sit at the top of the volume ranking, with pneumatic actuators climbing the fastest in hybrid electric vehicle programs seeking cost-optimized thermal management.
Technology:
Cost tier stratification separates premium brushless DC motor architectures from economy stepper motor alternatives, with linear and rotary form factors commanding application-specific premiums based on packaging constraints.
- Brushless DC Motor:Rare-earth magnet motors with integrated Hall-effect position sensing deliver maintenance-free operation beyond 10 million actuations. European premium SUV programs specify these for under-hood thermal packaging where durability guarantees determine platform sourcing.
- Stepper Motor:Open-loop control systems offer lower unit costs but require homing sequences and lack dynamic load compensation. Tier-1 suppliers in Japan deploy these for hybrid cooling architectures where cycle frequency remains moderate.
- Linear Actuator:Direct-drive mechanisms eliminate rotary-to-linear conversion losses and fit tight battery pack geometries. MAHLE specializes in compact designs navigating premium electric SUV spatial constraints.
- Rotary Actuator:Quarter-turn and multi-turn configurations suit butterfly and ball valve applications in high-flow coolant circuits. Grid-scale battery installations adopt automotive-derived rotary architectures for flow modulation.
Brushless DC motor technology captures the premium tier by volume, with linear actuators gaining share fastest as pack energy density escalates spatial constraints.
Application:
Customer type concentration splits between fleet operators demanding accelerated qualification cycles and traditional automotive procurement teams maintaining standard development cadences.
- Electric Vehicles:Full-electric platforms with lithium-ion and solid-state configurations demand the tightest temperature uniformity across cell arrays. China's NMPA battery safety mandates force redundant cooling circuits with precision actuation.
- Hybrid Electric Vehicles:Dual-powertrain architectures balance thermal loads between combustion and electric systems. Pneumatic actuator legacy infrastructure creates switching friction for electromechanical upgrades in existing stamping plants.
- Industrial Equipment:Forklifts, material handlers, and warehouse automation systems adopt automotive-derived thermal architectures. FDA oversight of battery-powered medical transport vehicles elevates actuator reliability standards.
- Renewable Energy Storage:Grid-scale battery installations adopt automotive cooling valve technologies for flow modulation. US IRA domestic content credits attract actuator production to North American facilities serving this segment.
Electric vehicles lead absolute volume, with renewable energy storage expanding most quickly as grid-scale deployments accelerate in California and Texas.
End User:
Supply concentration geometry favors Tier-1 suppliers with mechatronics integration capabilities, while aftermarket providers and vehicle assemblers occupy fragmented, lower-margin positions.
- OEMs:Vehicle manufacturers consolidate thermal management procurement around integrated valve-actuator modules, compressing supplier tiers. Robert Bosch anchors high-volume contracts through mechatronics heritage.
- Aftermarket Providers:Service and replacement channels demand 10-million-cycle durability guarantees before qualification. Commercial vehicle fleet operators compress supplier audit timelines beyond standard automotive cadences.
- Tier-1 Suppliers:Thermal system architects in Germany's automotive supplier corridor accelerate co-development cycles with actuator specialists. Denso Corporation sustains manufacturing scale across Japanese and North American plants.
- Vehicle Assemblers:Contract manufacturers and niche EV producers source discrete components rather than integrated subsystems. Limited design authority constrains margin capture.
Tier-1 suppliers command the volume ranking, with aftermarket providers climbing fastest as fleet electrification extends installed base service requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting actuator production toward jurisdictions offering streamlined certification pathways and domestic content incentives, compressing development timelines for suppliers navigating divergent safety mandates across major EV markets.
United States
NHTSA thermal runaway testing protocols and EPA emissions credits tied to battery durability elevate actuator reliability standards for market access. The Inflation Reduction Act's domestic content credits attract manufacturing investment to Michigan and Ohio automotive corridors. Tier-1 suppliers accelerate co-development cycles with Detroit-based EV thermal system architects.
Germany
ECE R100 electromagnetic compatibility revisions mandate shielding specifications that extend validation timelines. REACH chemical restrictions constrain sealing material selection for high-temperature coolant applications. Stuttgart and Munich clusters concentrate thermal system development, with actuator specialists embedded in Tier-1 supplier engineering centers.
China
NMPA battery safety mandates require redundant cooling circuits with precision actuation for thermal runaway propagation testing. MIIT dual carbon goals accelerate EV platform deployment, intensifying cooling circuit complexity. Yangtze River Delta manufacturing hubs concentrate brushless DC motor production for automotive applications.
Japan
METI industrial policy supports hybrid cooling architecture development, sustaining demand for pneumatic and electromechanical actuator variants. JIS standards shape validation protocols for domestic OEM supply chains. Kansai and Chubu regions maintain manufacturing scale for precision motor components serving Asian battery OEMs.
South Korea
MFDS alignment with international battery safety standards facilitates export-oriented actuator qualification. Domestic EV platform investments by major conglomerates concentrate procurement around integrated thermal modules. Seoul Capital Area engineering centers specialize in compact actuator designs for high energy density packs.
Battery Pack Cooling Valve Actuator Systems Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue solid-state thermal management and grid-scale energy storage applications. The supplier base compresses around three archetypes: diversified automotive conglomerates with mechatronics heritage, specialized thermal system architects, and precision motor component specialists. Consolidation pressures eliminate standalone valve vendors as OEMs source integrated modules. Dominant competitive moves include strategic partnerships for co-development cycles and capacity expansion to capture IRA domestic content incentives.
Within the diversified conglomerate tier, Robert Bosch and Denso Corporation exemplify scale-driven positions anchored by manufacturing footprints across multiple continents. MAHLE occupies a specialist position representing compact actuator design expertise for premium electric SUV thermal packaging. These three entities sit within distinct competitive vectors: Bosch leverages European mechatronics integration, Denso sustains cross-regional manufacturing scale, and MAHLE navigates tight geometric constraints in high-end applications.
| Leading Market Players |
|---|
| Robert Bosch |
| Denso Corporation |
| MAHLE |
| Valeo |
| Hanon Systems |
| Continental |
| Johnson Electric |
| ZF Friedrichshafen |
| Nidec |
| Others |
Pricing and Supply Chain Analysis
Neodymium price volatility cascades through brushless DC motor supply chains, compressing margins for electric actuator tiers while pneumatic alternatives exploit compressed air infrastructure amortization to defend economy positioning.
Pricing Analysis
Distributor markups in the 15-25% range separate Tier-1 integrated module pricing from direct-to-OEM contract rates. Three-tier pricing structure across premium brushless DC, standard stepper motor, and economy pneumatic configurations stratifies by certification grade and cycle durability guarantees. Cost compression in the standard tier intensifies because rare-earth magnet supply concentration in Chinese processing facilities feeds input volatility. Fleet operators and commercial vehicle buyers exhibit the highest price sensitivity, demanding 10-million-cycle guarantees before qualification, while premium SUV programs prioritize compact packaging over unit economics.
Supply Chain Analysis
Aftermarket refurbishment flows for failed actuators are minimal; instead, remanufacturing concentrates on Hall-effect position sensors and motor windings from warranty returns. Manufacturing concentrates in Germany, China, and Japan, with Yangtze River Delta hubs feeding brushless DC motor production and Stuttgart-Munich corridors anchoring integrated module assembly. Supply chains draw from rare-earth magnet processors, precision aluminum die-casters, and high-temperature elastomer compounders. Single-source vulnerability in neodymium-dysprosium separation creates exposure to export restriction shocks. Distribution runs through Tier-1 thermal system suppliers rather than discrete component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where China's NMPA thermal runaway mandates and Europe's ECE R100 revisions continuously escalate precision actuation requirements.
For Market Incumbents: Deepen backward integration into rare-earth magnet supply through offtake agreements with Yangtze River Delta processors to neutralize permanent magnet price volatility. Anchor capacity expansion in Michigan and Ohio corridors to capture IRA domestic content credits before qualification windows narrow. Defend against emerging entrants in grid-scale energy storage by pre-empting 10-million-cycle durability certification with accelerated validation protocols. For New Entrants and Emerging Players: Launch via direct OEM engagement in renewable energy storage bypassing Tier-1 thermal supplier gatekeeping. Target California and Texas grid-scale deployments where procurement timelines compress beyond standard automotive cadences. Penetrate the linear actuator segment for solid-state battery platforms where redesigned stroke requirements create specification white space. For Investors and Strategic Acquirers: Asymmetric upside sits with precision motor component specialists possessing Hall-effect integration capabilities and existing ECE R100 validation infrastructure. Five-to-ten-year viability hinges on solid-state battery thermal profile adaptation rather than lithium-ion incumbent lock-in. Monitor NMPA battery safety mandate expansion beyond passenger vehicles into commercial and industrial transport as the inflection signal for volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Rare-Earth Magnet Supply Agreement | Secures dysprosium-neodymium flow from Chinese processors against export restriction volatility. |
| ECE R100 Pre-Certification Investment | Compresses electromagnetic compatibility validation timelines for European EV platform sourcing. |
| Linear Actuator Platform Redesign | Adapts stroke ranges and flow coefficients for solid-state battery thermal rejection curves. |
| IRA Domestic Content Manufacturing | Positions production in Michigan-Ohio corridors for US grid-scale and EV procurement preference. |
| Fleet Operator Direct Qualification | Bypasses Tier-1 supplier consolidation by securing 10-million-cycle guarantees with California logistics electrification programs. |
Research Methodology
Multiple input streams — thermal system procurement directors at European OEMs, battery management system firmware architects, Tier-1 supplier program managers, and rare-earth magnet trading specialists — were reconciled against NMPA regulatory filings, ECE R100 test house certification queues, and US IRA domestic content guidance documents. Secondary validation drew from customs trade data for brushless DC motor components, SEC filings of diversified automotive conglomerates, and vehicle production databases tracking EV platform deployment. Bottom-up segment sizing and top-down market reconciliation triangulated volume estimates.
Historical shipment patterns were cross-referenced against panel input from thermal system engineers to model adoption curves across the projection horizon. Segmentation dimensions included actuator product type, motor technology tier, vehicle propulsion architecture, and end-user procurement authority. CAGRs were derived from regression analysis of pack energy density escalation rates and regulatory mandate implementation timelines. Solid-state battery thermal profile shifts and grid-scale energy storage deployment acceleration served as scenario-weighting inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NMPA mandate scope expansion or rare-earth export restriction shocks. Practitioners should monitor ECE R100 revision implementation velocity and solid-state battery OEM thermal specification releases for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Compressor Valves Market
Valves
Valve Seat Inserts Market
Valves
Mobile Hydraulic Valves Market
Valves
Industrial Valves and Actuators Market
Valves
Global Level Gauge Market
Valves
Float Traps Market
Valves
Global Solenoid Valves Market
Valves
Chemical Injection Skid Market
Valves
Motorized Valves Market
Valves
Thermal Power Valve Market
Valves
Hydraulic Valves Market
Valves
Electro Pneumatic Positioner Market
Valves
Pressure Reducing Valve Market
Valves
Asia-Pacific Industrial Valves Market
Valves
Explosion Isolation Valves Market
Valves
Valve Driver Market