
 Vagal Nerve Stimulation (VNS) Market | 2026-2036
Vagal Nerve Stimulation (VNS) Market Size, Share, and Industry Trends Forecast 2026-2036
Vagal Nerve Stimulation (VNS) Market Analytics
Subscription-based remote programming services is repositioning how VNS manufacturers capture recurring revenue beyond initial device sales. LivaNova PLC leverages its integrated service infrastructure to sustain long-term patient engagement across implantable portfolios. electroCore differentiates through non-invasive delivery platforms that reduce surgical dependency for chronic migraine populations. SetPoint Medical Corporation specializes in bioelectronic medicine approaches that anchor its development pipeline in inflammatory disease applications.
Vagal Nerve Stimulation denotes electrical modulation of the vagus nerve through implantable pulse generators or external transcutaneous devices, typically operating at frequencies between 20-30 Hz with current outputs up to 3.5 mA to modulate autonomic pathways. Its primary purpose spans seizure suppression in drug-resistant epilepsy, mood regulation in treatment-resistant depression, and autonomic modulation for emerging inflammatory conditions. Implantable Devices occupy the dominant margin pool given surgical placement requirements and long-term battery replacement cycles, while External Devices represent the fastest-expanding category as patients seek non-surgical alternatives for migraine and anxiety protocols. Hospitals remain the primary delivery setting, though Home Care configurations are gaining traction with simplified external stimulator designs.
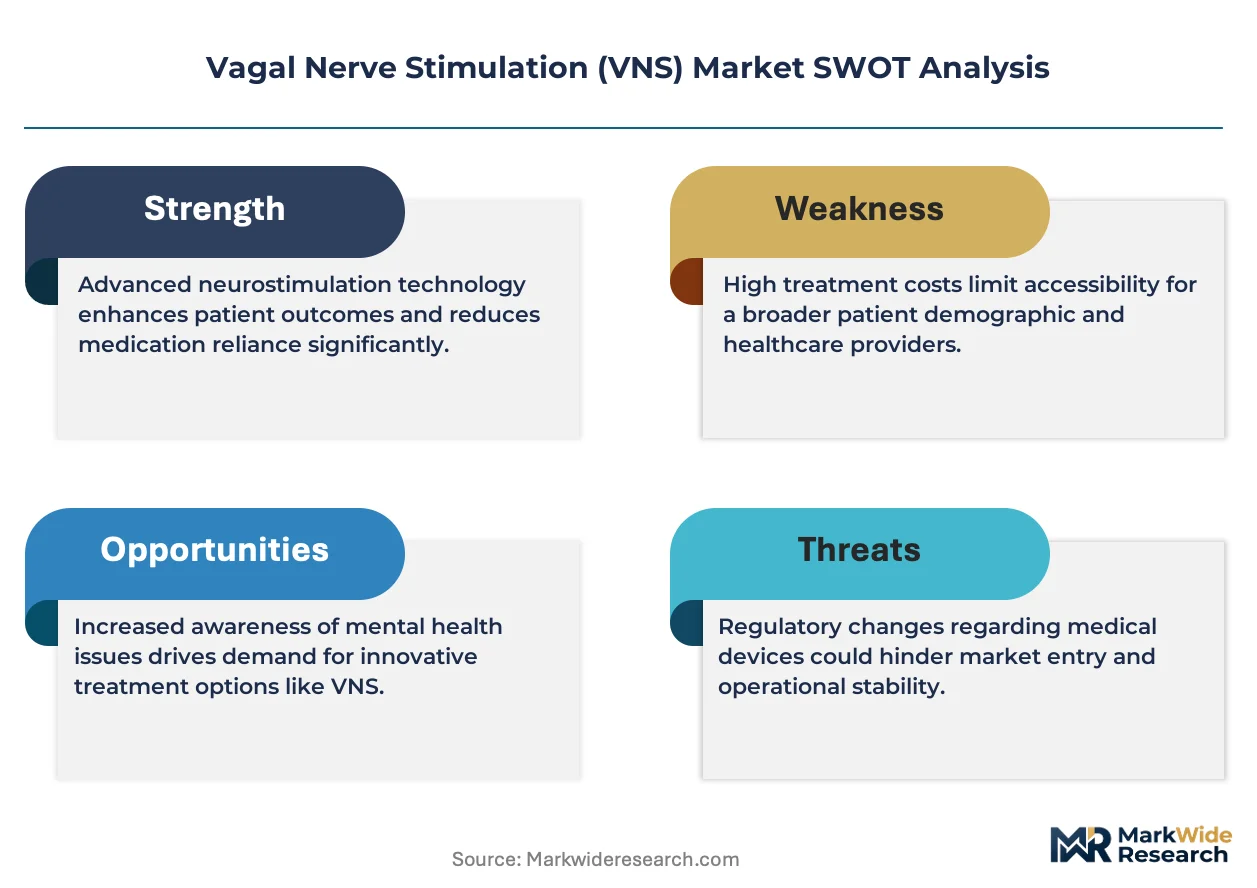
FDA breakthrough device designations and EMA medical device regulation frameworks shape product development timelines and clinical evidence requirements for neuromodulation entrants. The EU AI Act and GDPR provisions increasingly govern connected VNS platforms that transmit patient response data to cloud-based programming systems. Stakeholders must monitor reimbursement parity between invasive and non-invasive delivery modes as health technology assessment bodies recalibrate value metrics for bioelectronic therapies.
Market Dynamics
The VNS market pivots on reimbursement parity negotiations between invasive implantable systems and emerging non-invasive alternatives, with health technology assessment bodies recalibrating value metrics for bioelectronic therapies.
Growth Catalysts
- FDA Breakthrough Device Pathway:The FDA's accelerated review mechanism compresses clinical evidence timelines for novel VNS systems targeting drug-resistant epilepsy and treatment-resistant depression.
- Neurology Clinic Expansion:Specialized neuromodulation service lines at academic medical centers generate rising patient referrals for implantable pulse generator placement and long-term management.
- Cloud-Based Programming Infrastructure:Remote titration capabilities enable real-time parameter adjustment without clinic visits, expanding addressable patient populations in rural and underserved regions.
Market Restraints
- Lithium-Ion Battery Supply Concentration:Pulse generator manufacturers depend on concentrated Asian battery cell suppliers, exposing production schedules to raw material allocation constraints.
- Surgical Implant Cost Structure:Operating room utilization, anesthesia services, and neurosurgical specialist fees compound total procedure costs beyond device procurement alone.
- Reimbursement Fragmentation:Medicare coverage determination variability across US local contractors creates access disparities for depression indications relative to established epilepsy protocols.
Strategic Opportunities
- Inflammatory Disease Applications:Bioelectronic medicine protocols for rheumatoid arthritis and Crohn's disease represent unaddressed therapeutic categories beyond neurological indications.
- Home Care Channel Development:Simplified external stimulator designs enable direct-to-patient distribution models for chronic migraine populations seeking alternatives to pharmaceutical prophylaxis.
- EU AI Act Compliance Positioning:Early alignment with algorithmic transparency requirements for connected VNS platforms creates competitive moats in European markets ahead of enforcement deadlines.
Industry Challenges
- Interdisciplinary Training Deficits:Clinical specialists capable of integrating device programming with pharmacological management remain scarce across neurology and psychiatry departments.
- Legacy EHR Integration Complexity:Proprietary data formats from implantable devices resist seamless incorporation into hospital electronic health record workflows, fragmenting longitudinal patient monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vagal Nerve Stimulation (VNS) Market |
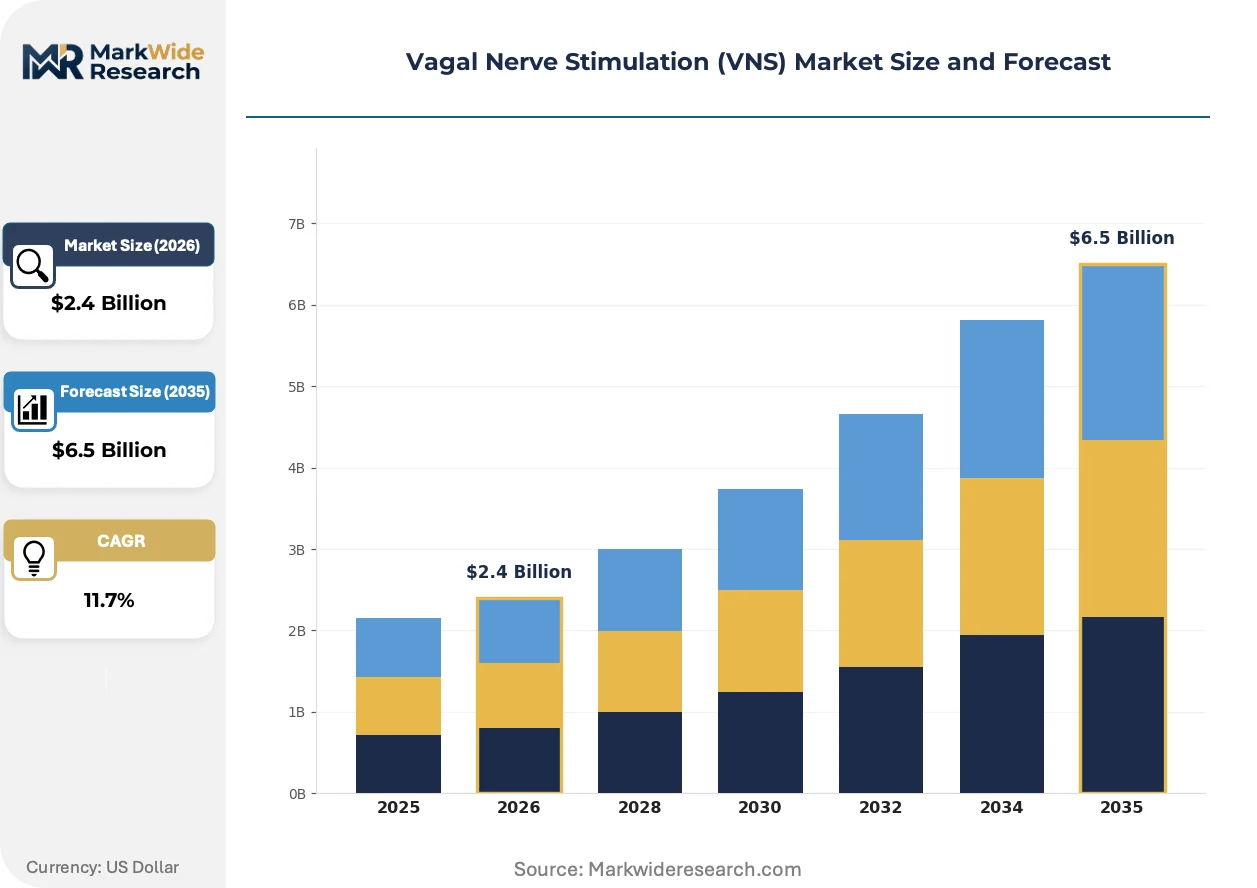
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.5 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implantable Devices, External Devices, Accessories, Neural Interfaces End User: Clinics, Hospitals, Home Care, Research Institutions Application: Epilepsy Treatment, Depression Therapy, Migraines, Chronic Pain Management Delivery Mode: Invasive Procedures, Non-invasive Techniques, Remote Programming, Standard Programming |
| Companies Covered | LivaNova PLC, electroCore, MicroTransponder, Inc., Parasym Ltd, Boston Scientific Corporation, SetPoint Medical Corporation, NeuroMetrix, Inc., tVNS Technologies GmbH, NeuroPace, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vagal Nerve Stimulation (VNS) Market Evolving Landscape
Closed-loop adaptive stimulation architectures are displacing fixed-parameter paradigms, with physiological biomarker detection triggering real-time therapeutic adjustment rather than scheduled clinical reprogramming.
Transcutaneous vagus nerve stimulation is electrifying chronic migraine management by eliminating surgical eligibility requirements and reducing total cost of care. Primary care networks and headache specialty clinics are adopting external neck-worn devices at accelerating rates. This modality is compressing the addressable market for implantable systems among patients with episodic rather than refractory conditions.
The EU Medical Device Regulation (MDR) is extending clinical evidence requirements for legacy VNS products previously certified under the Medical Device Directive. Manufacturers face renewed notified body scrutiny of post-market surveillance data and periodic safety update reports. Implantable pulse generator portfolios with limited long-term follow-up datasets encounter the most significant conformity assessment delays.
Subscription-based remote monitoring contracts are displacing transactional device sales in hospital procurement negotiations. Health systems in Germany and the United States increasingly bundle hardware acquisition with multi-year algorithm update and telemedicine support services. This shift concentrates vendor selection criteria on cloud infrastructure reliability and cybersecurity posture rather than hardware specifications alone.
Vagal Nerve Stimulation (VNS) Market Segmentation
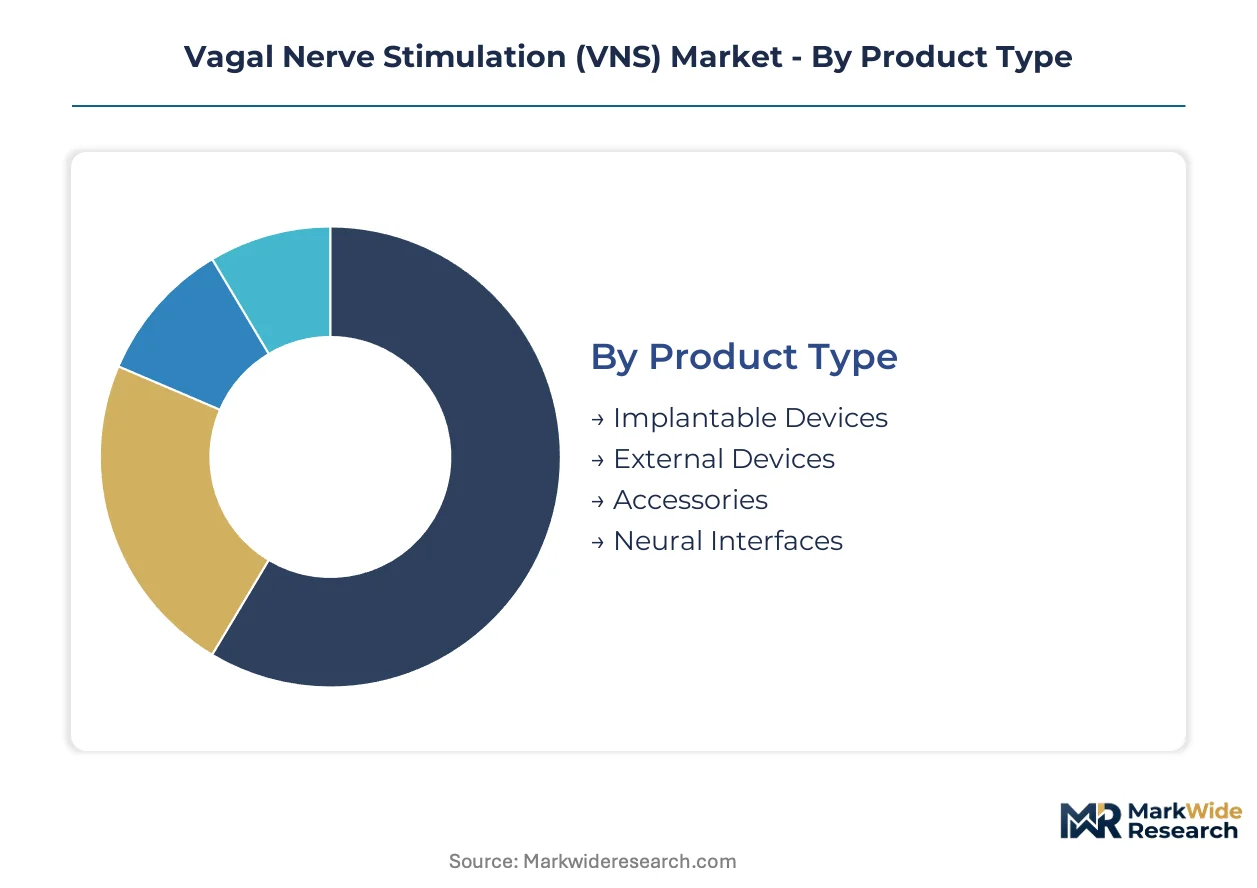
VNS market segmentation reveals divergent margin structures across surgical and non-surgical delivery paradigms. Product architecture and care setting configurations determine reimbursement pathways, patient access timelines, and vendor competitive positioning.
Product Type:
Device selection hinges on surgical risk tolerance, battery longevity requirements, and total cost of ownership across the therapy lifecycle.
- Implantable Devices:Pulse generators with lithium-ion power cells deliver 20-30 Hz stimulation at 1.0-3.5 mA outputs through bipolar leads. Demand concentrates at academic medical centers in the United States where Medicare reimbursement covers generator replacement cycles. Surgical placement requirements and neurosurgical specialist fees elevate total procedure economics.
- External Devices:Transcutaneous stimulators apply cervical vagus nerve modulation through skin-contact electrodes without operative intervention. Home care adoption in Germany and United Kingdom accelerates as patients seek alternatives to implantable systems for episodic migraine management. Non-surgical eligibility expands addressable populations beyond refractory cases.
- Accessories:Lead extensions, programming wands, and patient magnets enable parameter adjustment and emergency device suspension.
- Neural Interfaces:Closed-loop adaptive architectures with biomarker detection capabilities enable real-time therapeutic adjustment.
Implantable Devices lead volumes today; External Devices are gaining share fastest.
End User:
Care setting determines regulatory oversight intensity, capital equipment requirements, and patient throughput economics.
- Hospitals:Operating room infrastructure and anesthesia services support implantable pulse generator placement with intraoperative impedance testing. Academic medical centers in the United States generate highest procedure volumes for drug-resistant epilepsy protocols. Medicare coverage determination variability creates access disparities for depression indications.
- Home Care:Simplified external stimulator designs enable direct-to-patient distribution without clinical facility dependency. Chronic migraine populations in Germany adopt neck-worn devices for prophylactic management outside institutional settings. Remote titration capabilities reduce specialist visit burden.
- Clinics:Specialized neuromodulation service lines at outpatient facilities manage long-term parameter programming and battery monitoring.
- Research Institutions:Clinical trial infrastructure supports investigational device exemption studies for inflammatory disease applications.
Hospitals dominate revenue capture currently; Home Care configurations show steepest expansion trajectory.
Application:
Therapeutic indication shapes clinical evidence requirements, regulatory review pathways, and payer coverage policies.
- Epilepsy Treatment:Drug-resistant seizure suppression represents the original FDA-approved indication with established reimbursement codes. United States Medicare contractors maintain consistent coverage for vagus nerve stimulation in refractory epilepsy populations. Long-term efficacy datasets support prior authorization requirements.
- Migraines:External transcutaneous protocols target chronic migraine prophylaxis without surgical eligibility constraints. Primary care networks in the United Kingdom accelerate adoption of non-invasive alternatives to pharmaceutical prophylaxis. Total cost of care compression drives payer preference.
- Depression Therapy:Treatment-resistant depression indications encounter Medicare coverage variability across local contractors.
- Chronic Pain Management:Emerging applications in fibromyalgia and neuropathic pain await definitive clinical trial outcomes.
Epilepsy Treatment anchors installed base; Migraines demonstrate most rapid indication expansion.
Delivery Mode:
Programming architecture determines patient convenience, rural access equity, and vendor recurring revenue potential.
- Remote Programming:Cloud-based parameter adjustment enables real-time titration without clinic visits. Rural and underserved regions in the United States gain therapeutic access through telemedicine-integrated platforms. Subscription-based service contracts displace transactional device sales in procurement negotiations.
- Non-invasive Techniques:Transcutaneous delivery eliminates surgical risk and reduces total procedure cost burden. External neck-worn devices in Germany and United Kingdom serve chronic migraine populations seeking alternatives to implantable systems. Patient self-administration expands treatment autonomy.
- Invasive Procedures:Surgical lead placement and generator implantation require operating room infrastructure with neurosurgical specialist involvement.
- Standard Programming:Scheduled in-clinic parameter adjustment maintains traditional reimbursement workflows.
Invasive Procedures retain majority revenue share; Remote Programming climbs fastest as health systems bundle hardware with multi-year service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States reimbursement frameworks sustain higher procedure volumes than Germany's statutory health insurance system, while Japan's aging demographics accelerate neuromodulation demand for chronic conditions.
United States
Medicare coverage determinations for drug-resistant epilepsy and treatment-resistant depression drive implantable pulse generator placements. The FDA breakthrough device designation pathway compresses review timelines for novel VNS systems targeting inflammatory conditions. Academic medical centers in Boston and Houston generate concentrated procedure volumes for neuromodulation service lines.
Germany
Statutory health insurance reimbursement for external transcutaneous devices expands home care adoption among chronic migraine populations. The EU Medical Device Regulation extends clinical evidence requirements for legacy VNS products seeking renewed conformity assessment. Medical technology clusters in Baden-Württemberg and Bavaria host specialized neuromodulation programming infrastructure.
United Kingdom
National Health Service technology appraisals prioritize non-invasive alternatives that reduce total cost of care for headache disorders. The Medicines and Healthcare products Regulatory Agency oversees post-market surveillance for connected VNS platforms transmitting patient data. Headache specialty clinics in London and Manchester accelerate adoption of external neck-worn devices.
Japan
Aging demographics and rising prevalence of treatment-resistant depression expand addressable populations for autonomic modulation therapies. The Pharmaceuticals and Medical Devices Agency evaluates clinical evidence requirements for bioelectronic medicine applications beyond neurological indications. Medical device manufacturers in the Tokyo-Osaka corridor develop closed-loop adaptive stimulation architectures.
China
Growing private hospital networks invest in neuromodulation service lines for drug-resistant epilepsy management. The National Medical Products Administration strengthens clinical trial oversight for implantable pulse generators seeking market authorization. Medical technology industrial parks in Suzhou and Shenzhen attract foreign VNS manufacturers seeking localized production capabilities.
Vagal Nerve Stimulation (VNS) Market Competitive Landscape
Top-tier vendors anchor implantable pulse generator portfolios, while specialized entrants occupy non-invasive delivery segments. The competitive structure stratifies across surgical implant manufacturers, external device specialists, and bioelectronic medicine developers. Strategic archetypes include integrated service infrastructure providers, transcutaneous technology innovators, and inflammatory disease application pioneers. Competitive moves concentrate on cloud-based programming infrastructure investments and subscription-based remote monitoring contract negotiations.
Within the integrated service infrastructure tier, LivaNova PLC and Boston Scientific Corporation exemplify vendors bundling hardware acquisition with long-term patient engagement protocols. Among non-invasive delivery specialists, electroCore occupies a position representing transcutaneous vagus nerve stimulation platforms that eliminate surgical dependency. These company archetypes reflect broader market segmentation between implantable systems requiring operating room infrastructure and external devices enabling direct-to-patient distribution models.
| Leading Market Players |
|---|
| LivaNova PLC |
| electroCore |
| MicroTransponder, Inc. |
| Parasym Ltd |
| Boston Scientific Corporation |
| SetPoint Medical Corporation |
| NeuroMetrix, Inc. |
| tVNS Technologies GmbH |
| NeuroPace, Inc. |
| Others |
Value Network & Pricing Analysis
Closed-loop adaptive stimulation architectures are compressing manufacturing cost structures while concentrating component sourcing among Asian battery cell suppliers. This dual shift simultaneously reduces per-unit production expenses and elevates supply-side vulnerability for pulse generator manufacturers dependent on lithium-ion power cells.
Pricing Analysis
Capacity additions in South Korea and Japan are reshaping price floors for implantable pulse generators as battery cell manufacturers expand cylindrical cell output. Subscription-based remote programming services now dominate pricing models, with three-tier pricing structure across premium algorithm bundles, standard telemetry packages, and economy hardware-only tiers. Price differentiation hinges on FDA breakthrough device certification status and cloud infrastructure reliability grades. Pricing pressure stems from Medicare coverage variability for depression indications relative to established epilepsy protocols. Academic medical centers exhibit lowest price sensitivity given bundled reimbursement frameworks, while primary care networks in Germany demonstrate highest sensitivity to total cost of care metrics.
Supply Chain Analysis
Freight cost volatility from Asian manufacturing hubs to United States distribution centers is elevating landed cost uncertainty for implantable device manufacturers. Lithium-ion battery cell production concentrates in China, South Korea, and Japan, with bipolar lead assemblies drawing from specialized wire drawing facilities in Germany and Switzerland. Raw material dependencies span cobalt cathode chemistries, platinum-iridium electrode alloys, and medical-grade silicone insulation sheaths. Single-source vulnerability permeates the battery cell tier where three suppliers control cylindrical cell output for implantable medical devices. Distribution runs through hospital procurement consortia and specialized neuromodulation distributors serving academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The VNS market functions as a stable compounder anchored by recurring revenue from battery replacement cycles and subscription-based remote programming contracts. Reimbursement parity negotiations between invasive and non-invasive delivery modes sustain predictable demand visibility across economic cycles.
For Market Incumbents: Anticipate transcutaneous device encroachment into episodic migraine populations by accelerating closed-loop adaptive architecture development for implantable portfolios. Defensive consolidation moves center on acquiring cloud-based programming infrastructure specialists and securing long-term lithium-ion cell offtake agreements with South Korean suppliers. Priority levers include backward integration into electrode alloy processing and exclusive hospital system partnerships for neuromodulation service line management.
For New Entrants and Emerging Players: Rural primary care networks in the United States represent the most penetrable buyer archetype given telemedicine-integrated remote titration capabilities that eliminate specialist visit requirements. White-space targets span inflammatory disease applications for rheumatoid arthritis and Crohn's disease protocols beyond established neurological indications. Home care channels in Germany offer direct-to-patient distribution angles for simplified external stimulator designs. Go-to-market positioning should emphasize total cost of care compression relative to pharmaceutical prophylaxis.
For Investors and Strategic Acquirers: Valuations sit cheapest among external device specialists with limited reimbursement code coverage relative to implantable incumbents with established Medicare pathways. Long-term viability across the projection horizon rests on regulatory moat durability and cloud infrastructure ownership. Acquisition target archetypes include bioelectronic medicine developers with inflammatory disease pipelines and EU AI Act compliance positioning. The signal to watch is FDA breakthrough device designation velocity for novel therapeutic indications.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerates review timelines for novel VNS systems targeting drug-resistant epilepsy. |
| CE Marking Pathway | Enables European market access under MDR extended clinical evidence requirements. |
| Hospital System Partnership | Secures neuromodulation service line exclusivity at academic medical centers. |
| Software Companion Development | Enables cloud-based parameter adjustment and remote patient monitoring capabilities. |
| Reimbursement Strategy | Addresses Medicare coverage variability for depression indications across local contractors. |
Research Methodology
Direct dialogue with neurosurgeons, biomedical engineers, hospital purchasing committee members, and GPO contracts managers grounded qualitative insights in clinical workflow realities. Secondary validation drew from FDA 510(k) filings, CMS Medicare coverage determinations, ClinicalTrials.gov neuromodulation protocol registrations, and hospital procurement database extracts. Bottom-up triangulation across implantable pulse generator shipment estimates and top-down reconciliation against statutory health insurance reimbursement data ensured methodological robustness.
Segment-level projections across product type, end user, application, and delivery mode dimensions fed into consolidated market estimates across the analysis window. CAGRs were derived from logistic adoption curve modeling calibrated to historical penetration rates for neuromodulation therapies. Industry-specific forecast inputs included Medicare coverage determination timelines, EU MDR conformity assessment durations, and lithium-ion battery replacement cycle frequencies.
Underlying measurement precision varies by segment; implantable device volumes carry tighter precision than emerging inflammatory disease applications pending clinical trial readouts. Forecasts reflect assumptions regarding reimbursement parity evolution and battery cell supply continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Catheter Coatings Market
Medical Devices
Global Hydrogel Based Drug Delivery System Market
Medical Devices
Radial Head Resection Implant Market
Medical Devices
Global Angioplasty Balloons Market
Medical Devices
Pacemaker/Defibrillator Lead Extraction Kits Market
Medical Devices
Australia Drug Delivery Devices Market
Medical Devices
Global Intraoperative Neuromonitoring (IONM) Market
Medical Devices
Intermittent Catheters Market
Medical Devices
Global Skin Grafting Device Market
Medical Devices
Japan Electric Wheelchair Market
Medical Devices
Saudi Arabia Respiratory Devices Market
Medical Devices
Deaver Retractor Market
Medical Devices
Cardioscope Market
Medical Devices
Global Medical Tricorder Device Market
Medical Devices
North America Advanced Drug Delivery Systems Market
Medical Devices
Global PC-Based Audiometer Market