
 Middle East and Africa Semiconductor Manufacturing Equipment Market | 2026-2036
Middle East and Africa Semiconductor Manufacturing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Semiconductor Manufacturing Equipment Market Foresight
The divergence between premium lithography systems and commodity back-end equipment is hardening across Middle East and Africa procurement channels. ASML sustains its grip on extreme ultraviolet lithography through technology leadership in sub-7nm patterning. Applied Materials, Inc. anchors the deposition and etching segments with broad process coverage. KLA Corporation dominates metrology and inspection, leveraging its installed base to control upgrade cycles and service revenue streams.
Middle East and Africa semiconductor manufacturing equipment comprises precision systems for fabricating, testing, and packaging integrated circuits on silicon wafers, operating within cleanroom environments maintaining particulate levels below ISO Class 3 standards and temperature tolerances of ±0.1°C. Photolithography systems command the steepest capital allocations due to their deterministic role in transistor scaling and yield economics. Etching equipment registers the fastest trajectory as three-dimensional gate architectures proliferate across foundry roadmaps. Wafer fabrication absorbs the dominant share of equipment spending, while packaging systems attract renewed attention as chiplet-based designs reshape assembly requirements.
Saudi Arabia's national industrial regulator and South Africa's competition authority shape local procurement frameworks, while CE marking requirements from European trade partners influence import compliance for equipment destined for re-export hubs. The UAE's technology free zone authorities administer specialized permitting for cleanroom infrastructure, directly conditioning project timelines. Stakeholders must monitor how sovereign wealth deployment patterns and local content rules recalibrate vendor selection criteria across the region's emerging fabrication clusters.
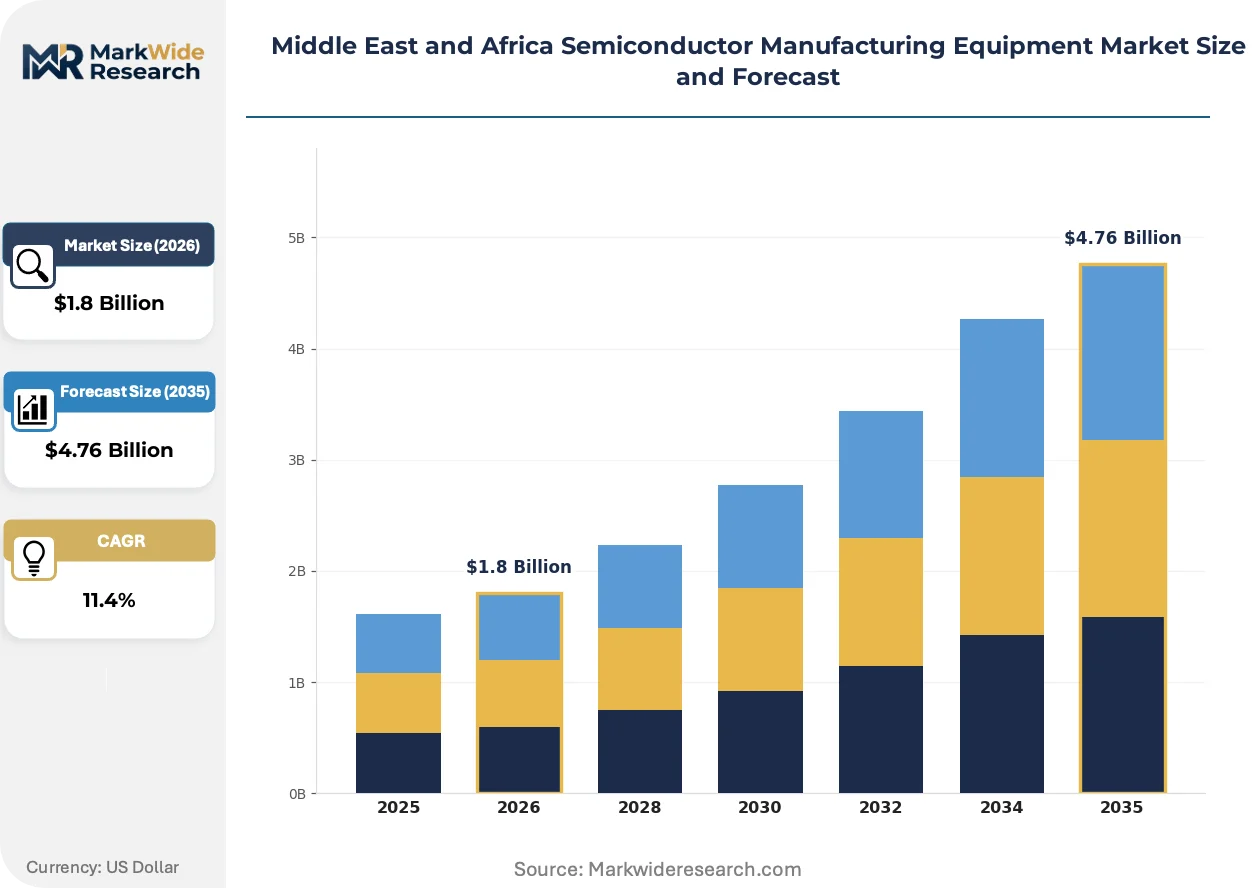
Market Dynamics
Extreme ultraviolet lithography adoption is concentrating capital deployment among Gulf state sovereign funds, while three-dimensional gate architectures force equipment refresh cycles across the region's emerging foundry clusters.
Growth Catalysts
- UAE Technology Free Zone Permitting:Abu Dhabi's specialized cleanroom infrastructure approvals accelerate project timelines for advanced fabrication facilities, drawing lithography system deployments ahead of regional peers.
- Automotive Electronics Demand:Gulf state electric vehicle mandates and advanced driver-assistance system rollouts pull 200mm and 300mm wafer processing equipment into domestic assembly plants.
- Sovereign Wealth Capital Reallocation:Technology-focused investment vehicles redirect petrodollar reserves toward semiconductor fabrication capabilities, underwriting equipment procurement without conventional debt constraints.
Market Restraints
- Extreme Ultraviolet Lithography Supply Concentration:Single-source dependency on Dutch lithography systems creates procurement bottlenecks and extended lead times for sub-7nm capacity.
- Specialized Technician Scarcity:Vacuum technology and plasma physics expertise pools remain shallow across Middle East and Africa labor markets, constraining operational scaling.
- CE Marking Compliance Burden:European re-export requirements impose additional certification layers on equipment destined for UAE-based redistribution hubs.
Strategic Opportunities
- Saudi Arabia Industrial City Development:King Abdullah Economic City and NEOM technology zones offer greenfield sites for integrated device manufacturer facilities with captive equipment supply chains.
- Chiplet-Based Assembly Requirements:Heterogeneous integration architectures create demand for advanced packaging systems previously absent from regional procurement portfolios.
- South Africa Competition Authority Framework:Local content rules and preferential procurement policies open channels for equipment vendors establishing regional service operations.
Industry Challenges
- Cleanroom Construction Expertise Gap:ISO Class 3 particulate control and ±0.1°C temperature tolerance specifications exceed regional contractor capabilities, extending facility commissioning timelines.
- Legacy Equipment Integration Complexity:Brownfield expansions in South Africa and Egypt require protocol bridging between 200mm toolsets and modern 300mm automation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Semiconductor Manufacturing Equipment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Wafer Fabrication, Assembly, Test, Packaging Technology: Photolithography, Etching, Deposition, Ion Implantation Application: Consumer Electronics, Automotive Electronics, Telecommunications, Medical Devices End User: Foundries, Integrated Device Manufacturers, Outsourced Semiconductor Assembly, Test Houses |
| Companies Covered | ASML, KLA Corporation, LAM RESEARCH CORPORATION, Applied Materials, Inc., Tokyo Electron Limited, Plasma-Therm, Veeco Instruments Inc., SCREEN Holdings Co., Ltd., Teradyne Inc., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Semiconductor Manufacturing Equipment Market Shifts & Advancements
Atomic layer deposition systems are penetrating Middle East and Africa procurement channels as gate-all-around transistor architectures redefine process requirements. Equipment specifications now emphasize precision at atomic-scale thickness control.
Gate-all-around transistor manufacturing is expanding into UAE and Saudi Arabian foundry roadmaps as successor technology to finFET architectures. Abu Dhabi's advanced fabrication complex has initiated qualification protocols for these systems. The technology is expanding into regional capital allocation priorities, compressing equipment replacement cycles from seven to five years.
CE marking requirements from European trade partners are tightening documentation standards for equipment re-export through UAE free zones. Compliance verification now extends to supply chain provenance declarations. Deposition and etching system vendors face the steepest administrative burden under these protocols.
Foundry customers across the Gulf states are consolidating procurement authority into centralized technical committees with direct sovereign fund representation. Traditional distributor networks face disintermediation as these committees negotiate directly with original equipment manufacturers. This pattern is most visible in Abu Dhabi, where single-source negotiations now dominate lithography system acquisition.
Middle East and Africa Semiconductor Manufacturing Equipment Market Segmentation
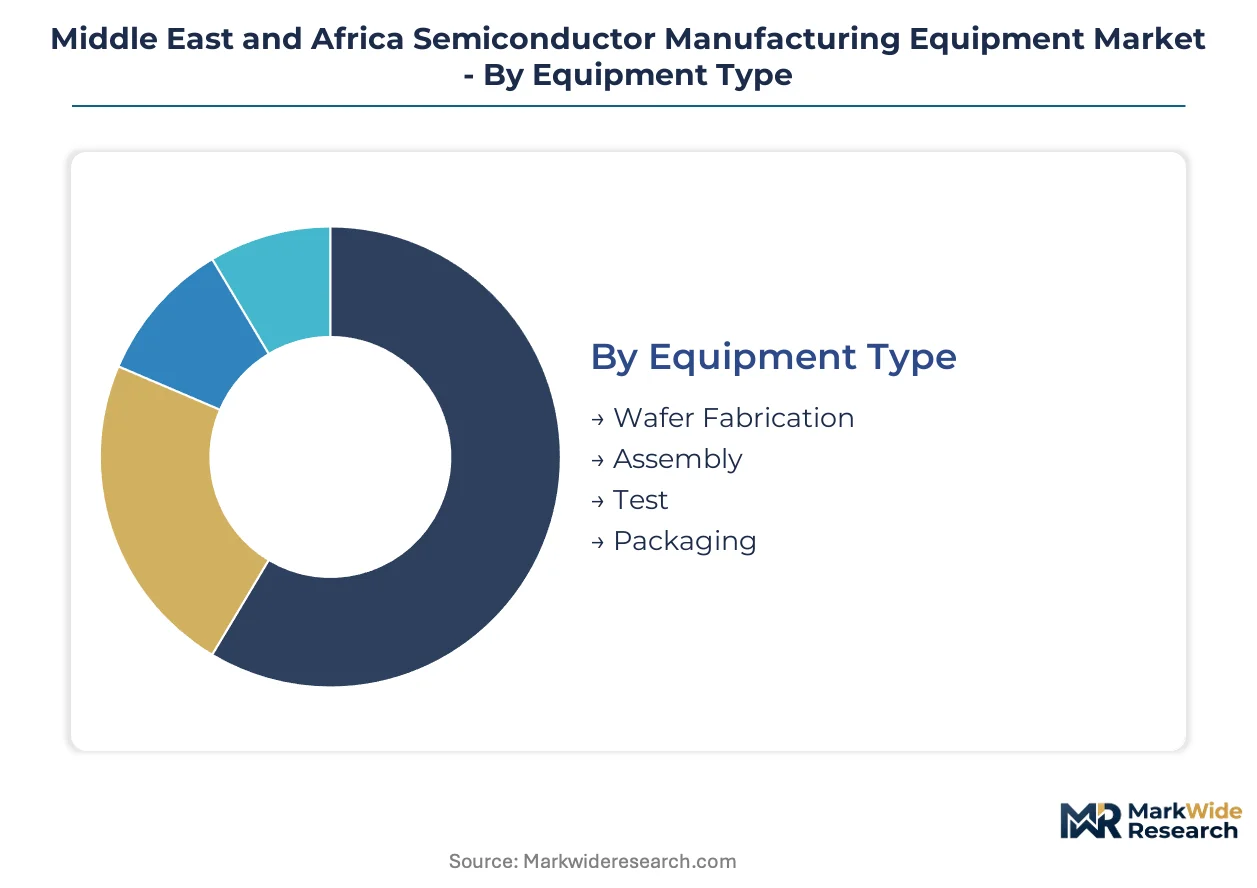
Equipment segmentation in Middle East and Africa semiconductor manufacturing reveals how capital allocation priorities diverge between sovereign-funded greenfield projects and industrial upgrading initiatives. Procurement patterns cluster around specific technology tiers that match regional capability development timelines.
Equipment Type:
Supply concentration in lithography and deposition systems concentrates procurement authority within Abu Dhabi-based technical committees, while assembly and test equipment flows through broader distributor networks.
- Wafer Fabrication:Photolithography, etching, and deposition systems operating within ISO Class 3 cleanroom environments. Demand concentrates in Abu Dhabi's advanced foundry complex where extreme ultraviolet systems anchor sub-7nm capacity expansion, constrained by single-source dependency on Dutch suppliers.
- Assembly:Die attach, wire bonding, and flip-chip placement systems for interconnect fabrication. Procurement is accelerating across Saudi Arabia's industrial cities as electric vehicle mandates pull automotive-grade packaging capacity into domestic facilities.
- Test:Parametric and functional verification systems for wafer and final package validation. UAE free zone permitting streamlines import protocols for high-speed digital test platforms.
- Packaging:Encapsulation, singulation, and thermal management systems for device protection. Chiplet-based heterogeneous integration architectures are expanding regional procurement portfolios beyond traditional commodity assembly.
Today's leader: Wafer Fabrication. Tomorrow's challenger: Packaging.
Technology:
Cost tier stratification separates atomic-scale precision systems from established process platforms, with capital deployment patterns tracking foundry node migration roadmaps.
- Photolithography:Pattern transfer systems using deep ultraviolet and extreme ultraviolet wavelengths. Abu Dhabi's technical committees negotiate directly with original equipment manufacturers, bypassing traditional distributor networks for these highest-value assets.
- Etching:Plasma and wet chemical material removal systems for three-dimensional gate architectures. The steepest expansion trajectory across Gulf state procurement channels as gate-all-around transistors displace finFET designs.
- Deposition:Chemical vapor and atomic layer deposition for thin-film material stacking. CE marking compliance burdens weigh heaviest on European re-export documentation for these systems through UAE hubs.
- Ion Implantation:Dopant acceleration systems for electrical property modification. South African brownfield expansions require protocol bridging between legacy 200mm toolsets and modern automation standards.
Photolithography commands premium capital allocation. Etching equipment gains share fastest.
Application:
Customer type differentiation separates sovereign-funded foundry buildouts from industrial diversification mandates, with procurement specifications tracking end-use reliability requirements.
- Consumer Electronics:Mobile and computing device semiconductor processing equipment. Demand concentrates in UAE-based redistribution hubs serving African consumer markets.
- Automotive Electronics:Power management and sensor fabrication systems for electric vehicles and advanced driver-assistance platforms. Saudi Arabia's national industrial regulator shapes procurement frameworks through domestic content requirements.
- Telecommunications:Radio frequency and baseband processor manufacturing equipment. 5G infrastructure deployment across Gulf states pulls 300mm wafer processing capacity into regional facilities.
- Medical Devices:Biocompatible and high-reliability semiconductor packaging systems. South Africa's competition authority applies preferential procurement policies to equipment vendors establishing regional service operations.
Automotive Electronics anchors current procurement volume. Telecommunications emerges as the next capacity allocation priority.
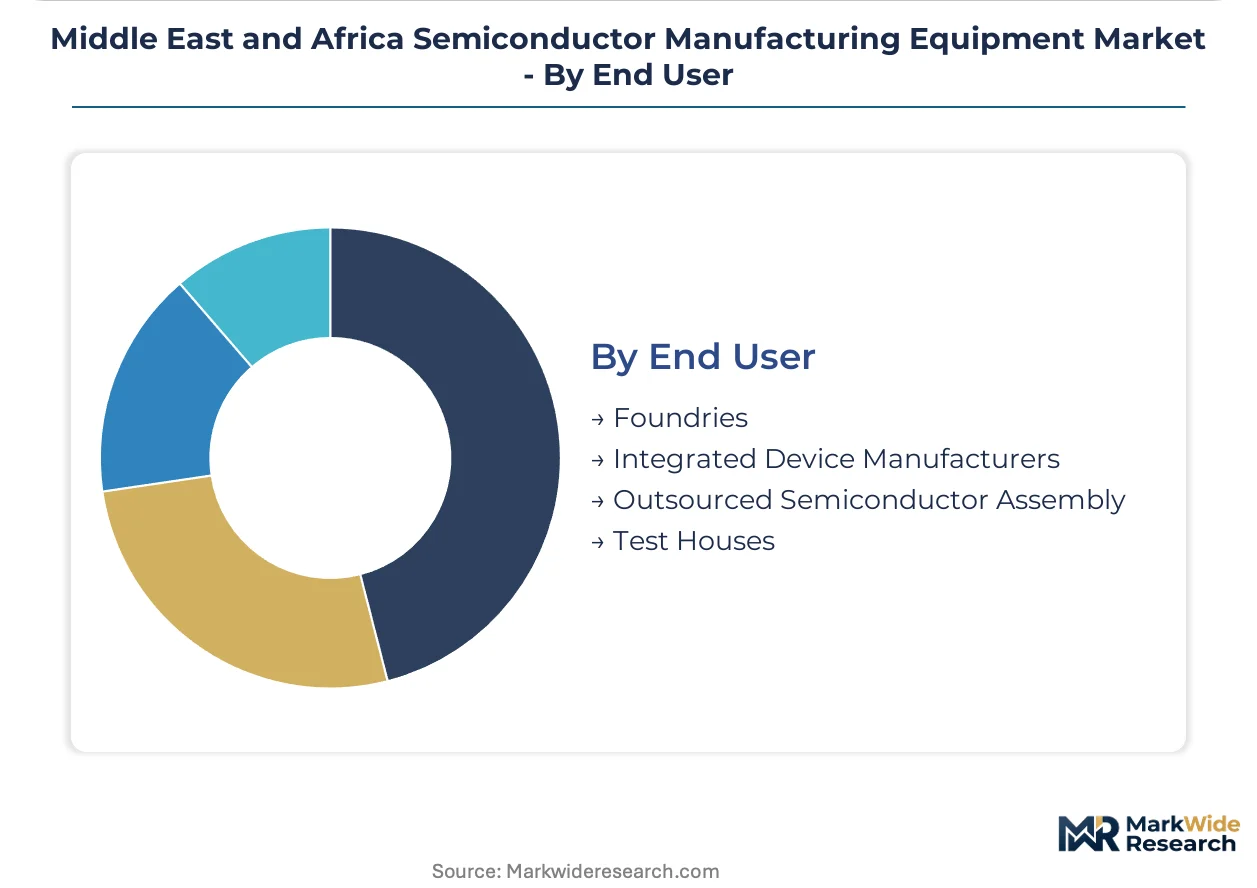
End User:
Volume concentration among foundry operators with sovereign wealth backing creates procurement asymmetries versus smaller outsourced service providers.
- Foundries:Pure-play contract manufacturing facilities serving fabless semiconductor designers. Abu Dhabi's technology free zone authorities administer specialized permitting that accelerates project timelines ahead of regional peers.
- Integrated Device Manufacturers:Captive fabrication facilities within vertically integrated electronics conglomerates. King Abdullah Economic City and NEOM zones in Saudi Arabia target these operators with greenfield site offerings.
- Outsourced Semiconductor Assembly:Third-party packaging and test service providers. Egypt's industrial zones attract these operators with proximity to European re-export markets.
- Test Houses:Independent verification and quality assurance facilities. Specialized technician scarcity across Middle East and Africa labor markets constrains operational scaling for these service providers.
Foundries dominate capital deployment. Integrated Device Manufacturers represent the emerging customer expansion vector.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized technician pools for vacuum technology and plasma physics remain shallow across Middle East and Africa labor markets, constraining operational scaling for advanced fabrication facilities from Abu Dhabi to Johannesburg.
United Arab Emirates
Abu Dhabi's advanced foundry complex anchors regional demand for extreme ultraviolet lithography systems, drawing sovereign wealth capital into single-source negotiations with Dutch equipment suppliers. MOHAP administers specialized permitting protocols for cleanroom infrastructure within technology free zones. Dubai-based redistribution hubs handle CE marking compliance for European re-export markets, conditioning import timelines for deposition and etching systems.
Saudi Arabia
King Abdullah Economic City and NEOM technology zones attract integrated device manufacturer facilities with greenfield site offerings and captive equipment supply chain potential. The national industrial regulator shapes procurement frameworks through domestic content requirements tied to automotive electronics mandates. Riyadh-based technical committees consolidate authority over lithography system acquisition, bypassing traditional distributor networks.
South Africa
Brownfield expansions in Gauteng and Western Cape industrial zones require protocol bridging between legacy 200mm toolsets and modern 300mm automation standards. The country's competition authority applies preferential procurement policies and local content rules to equipment vendors establishing regional service operations. Cape Town attracts medical device packaging system deployments through biocompatibility certification requirements.
Israel
Defense and telecommunications semiconductor demand concentrates in Tel Aviv and Haifa metropolitan corridors, pulling specialized test and inspection equipment into domestic facilities. The national technology investment office coordinates capital deployment toward heterogeneous integration capabilities. Jerusalem-based research institutes qualify atomic layer deposition systems for gate-all-around transistor roadmaps.
Egypt
Proximity to European re-export markets positions Suez Canal Economic Zone facilities for outsourced semiconductor assembly operations serving Mediterranean trade routes. The industrial development authority streamlines import protocols for wire bonding and flip-chip placement systems. Cairo-Alexandria corridor infrastructure supports die attach equipment distribution into North African consumer electronics supply chains.
Middle East and Africa Semiconductor Manufacturing Equipment Market Competitive Landscape
Top-tier vendors anchor lithography and metrology segments, while mid-tier specialists occupy deposition, etching, and assembly equipment niches. Market structure concentrates around precision patterning systems where technology leadership creates single-source dependencies, alongside fragmented competition in back-end packaging and test platforms. Strategic archetypes include full-stack process equipment integrators, sub-specialist technology licensors, and regional service-focused distributors. Competitive moves center on direct sovereign fund negotiations disintermediating traditional channels, alongside qualification partnerships for gate-all-around transistor architectures.
Within the precision lithography tier, ASML represents the archetype of technology-locked market position through extreme ultraviolet system supply concentration. Among metrology and inspection specialists, KLA Corporation exemplifies installed-base leverage controlling upgrade cycles and service revenue streams. Applied Materials, Inc. occupies a position spanning deposition and etching segments with broad process coverage across multiple technology nodes. These three entities anchor the competitive structure through which Gulf state procurement committees negotiate directly, compressing distributor margins and reshaping regional market access patterns.
| Leading Market Players |
|---|
| ASML |
| KLA Corporation |
| LAM RESEARCH CORPORATION |
| Applied Materials, Inc. |
| Tokyo Electron Limited |
| Plasma-Therm |
| Veeco Instruments Inc. |
| SCREEN Holdings Co., Ltd. |
| Teradyne Inc. |
| Others |
Supply & Pricing Matrix
Direct sovereign fund negotiations in Abu Dhabi and Riyadh are compressing distributor margins and forcing equipment vendors to restructure service bundling, which in turn concentrates pricing power among lithography specialists while commoditizing back-end assembly systems.
Pricing Analysis
Bundled service contracts covering installation, qualification, and multi-year maintenance dominate lithography system transactions, while unbundled equipment-only pricing prevails in wire bonding and test handler segments. Price differentiation separates extreme ultraviolet systems with full foundry integration packages from deposition tools sold through distributor networks. Pricing pressure stems from Gulf state technical committees consolidating procurement authority and demanding extended warranty terms. Outsourced semiconductor assembly providers exhibit highest price sensitivity due to thin operating margins, whereas sovereign-backed foundries prioritize technology access over unit cost.
Supply Chain Analysis
Photoresist supply rests on Japanese specialty chemical producers, while extreme ultraviolet light source components draw from Dutch and German precision optics manufacturers. Vacuum pumps and ion source subsystems hinge on American and Swiss suppliers. Single-source vulnerability concentrates in sub-7nm lithography modules where ASML maintains exclusive production capacity. Distribution runs through Dubai-based free zone hubs for CE marking compliance before final delivery to Abu Dhabi cleanroom facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
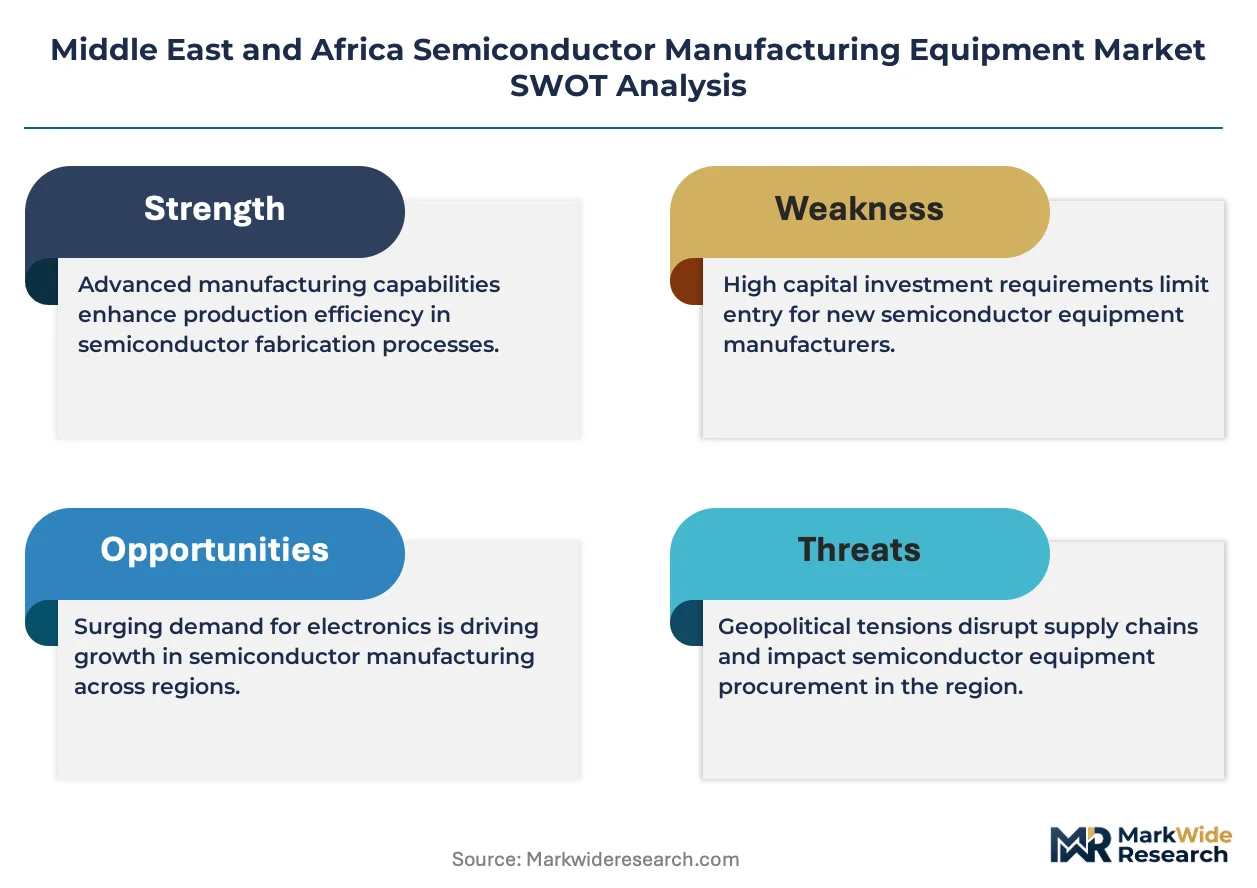
The Middle East and Africa semiconductor manufacturing equipment market functions as a geographic-arbitrage play where Abu Dhabi's accelerated permitting timelines and zero-tax free zones offset European and Asian supply chain costs by eliminating customs duties and compressing project commissioning schedules.
For Market Incumbents: Anticipate disintermediation threats from sovereign fund technical committees negotiating directly with original equipment manufacturers in The Netherlands and USA. Defend position by establishing captive service operations in King Abdullah Economic City and securing MOHAP pre-qualification for cleanroom infrastructure partnerships. Channel control through exclusive distributor agreements loses effectiveness as procurement authority centralizes. For New Entrants and Emerging Players: Regional service partners with vacuum technology and plasma physics expertise represent the most viable entry channel. White-space targets concentrate in Egypt's Suez Canal Economic Zone for outsourced semiconductor assembly and South Africa's Western Cape for medical device packaging systems. The most penetrable segment is legacy 200mm equipment refurbishment and protocol bridging for brownfield expansions. Go-to-market execution should lead with technician training programs bundled with equipment leases. For Investors and Strategic Acquirers: Asymmetric upside sits with deposition and etching specialists qualified for gate-all-around transistor roadmaps in Abu Dhabi and Jerusalem research corridors. Long-term viability favors vendors with installed base leverage controlling upgrade cycles and consumables revenue streams. Acquisition target archetype: mid-tier atomic layer deposition specialists with existing CE marking documentation. The signal to watch is qualification protocol announcements from Abu Dhabi's advanced foundry complex for sub-3nm process nodes.| Strategic Initiative | Industry Significance |
|---|---|
| Gate-All-Around Qualification Partnership | Abu Dhabi's foundry complex accelerates equipment replacement cycles from seven to five years. |
| CE Marking Pre-Certification Program | Dubai free zone hubs reduce import delays for deposition systems bound for European re-export. |
| Regional Service Center Establishment | South Africa's competition authority applies preferential procurement to vendors with local operations. |
| Technician Training Academy Launch | Saudi Arabia's industrial cities address specialized labor scarcity constraining operational scaling. |
| Sovereign Fund Direct Negotiation Protocol | Riyadh-based technical committees disintermediate traditional distributor networks for lithography. |
Research Methodology
Direct dialogue with foundry operations directors, cleanroom infrastructure contractors, sovereign wealth technology investment officers, and European equipment vendor regional sales heads grounded the qualitative assessment. Secondary validation drew from SEC 10-K filings of precision lithography suppliers, UAE technology free zone permitting databases, Saudi Industrial Development Fund capital deployment disclosures, and South African competition authority procurement bulletins. Bottom-up equipment shipment tracking and top-down sovereign fund allocation analysis were triangulated against foundry capacity buildout announcements.
Market size outputs reflect segmentation across wafer fabrication, assembly, test, and packaging equipment types; photolithography, etching, deposition, and ion implantation technologies; and foundry, integrated device manufacturer, and outsourced assembly end-user categories. CAGR derivation incorporated foundry node migration roadmaps, automotive electronics mandate timelines, and gate-all-around transistor adoption curves. Forecast inputs included cleanroom construction permit issuance rates and technician training program graduation volumes.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to extreme ultraviolet lithography supply bottlenecks and Gulf state labor market development. Forecasts reflect documented assumptions regarding sovereign wealth capital continuity and CE marking regulatory stability. A small set of triggers warrants ongoing watch: Dutch export control adjustments, Saudi local content rule revisions, and South African preferential procurement policy updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
DUV Lithography Systems Market
Semiconductor Equipment
Semiconductor LPCVD Furnaces Market
Semiconductor Equipment
Semiconductor Bonding Equipment Market
Semiconductor Equipment
FOUP Cleaning System Market
Semiconductor Equipment
Global Soldering Equipment Market
Semiconductor Equipment
Slide Processing System Market
Semiconductor Equipment
Reticle Pod Cleaning System Market
Semiconductor Equipment
Pulse Tube and Gifford-Mcmahon Cryocoolers Market
Semiconductor Equipment
Wafer Chucks Market
Semiconductor Equipment
Photoresist for Semiconductor Market
Semiconductor Equipment
Vacuum Spin Coaters Market
Semiconductor Equipment
Plasma Etching Equipment Market
Semiconductor Equipment
SMT Reflow Soldering Equipment Market
Semiconductor Equipment
Die Attach Equipment Market
Semiconductor Equipment
UV-Based Nanoimprint Lithography (UV-NIL) System Market
Semiconductor Equipment
Consumable Parts for Semiconductor Equipment Market