
 Booster Compressor Market | 2026-2036
Booster Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Booster Compressor Market Intelligence
China's rapid expansion of its natural gas pipeline network is fragmenting the competitive landscape for booster compressor suppliers. Atlas Copco leverages its extensive service network and energy-efficient technology to serve diverse industrial applications. Ingersoll Rand competes on the proven reliability of its portfolio for midstream operations. Baker Hughes dominates the high-specification segment for large-scale pipeline transmission projects.
A booster compressor is a machine engineered to increase the pressure of air or gas that has already been compressed by a primary unit. These systems typically handle inlet pressures from 2 to 20 bar, elevating them to final pressures required for specific industrial processes. Reciprocating compressors command a significant share due to their efficiency in high-pressure, low-flow applications. The natural gas boosting application segment represents the fastest-growing area, driven by energy infrastructure investments.
ISO 8573 standards for compressed air quality and the EU's CE marking for machinery safety govern product design and market access in key regions. In the United States, EPA regulations concerning methane emissions from natural gas infrastructure influence compressor selection and maintenance protocols. Vendor success depends on developing compressors that can efficiently handle alternative fuels like hydrogen and operate within stricter environmental emissions frameworks.
Market Dynamics
The imperative to decarbonize energy infrastructure while meeting transmission demand creates the central tension in the booster compressor market. This dynamic forces manufacturers to engineer equipment that handles new fuel compositions like hydrogen while complying with tightening methane emission controls.
Growth Catalysts
- Chinese Infrastructure Investment:National pipeline expansion projects in China, driven by dual carbon goals, are creating sustained demand for new booster compressor stations for natural gas transmission and storage.
- Hydrogen Blending Mandates:The transition towards hydrogen-blended natural gas requires compressors with advanced materials and seals capable of handling the unique properties of hydrogen, stimulating new product development cycles.
- Emissions Regulations:The US EPA's methane emission rules for the oil and gas sector compel operators to upgrade or replace older, leak-prone compressors with modern, low-emission units to ensure compliance.
Market Restraints
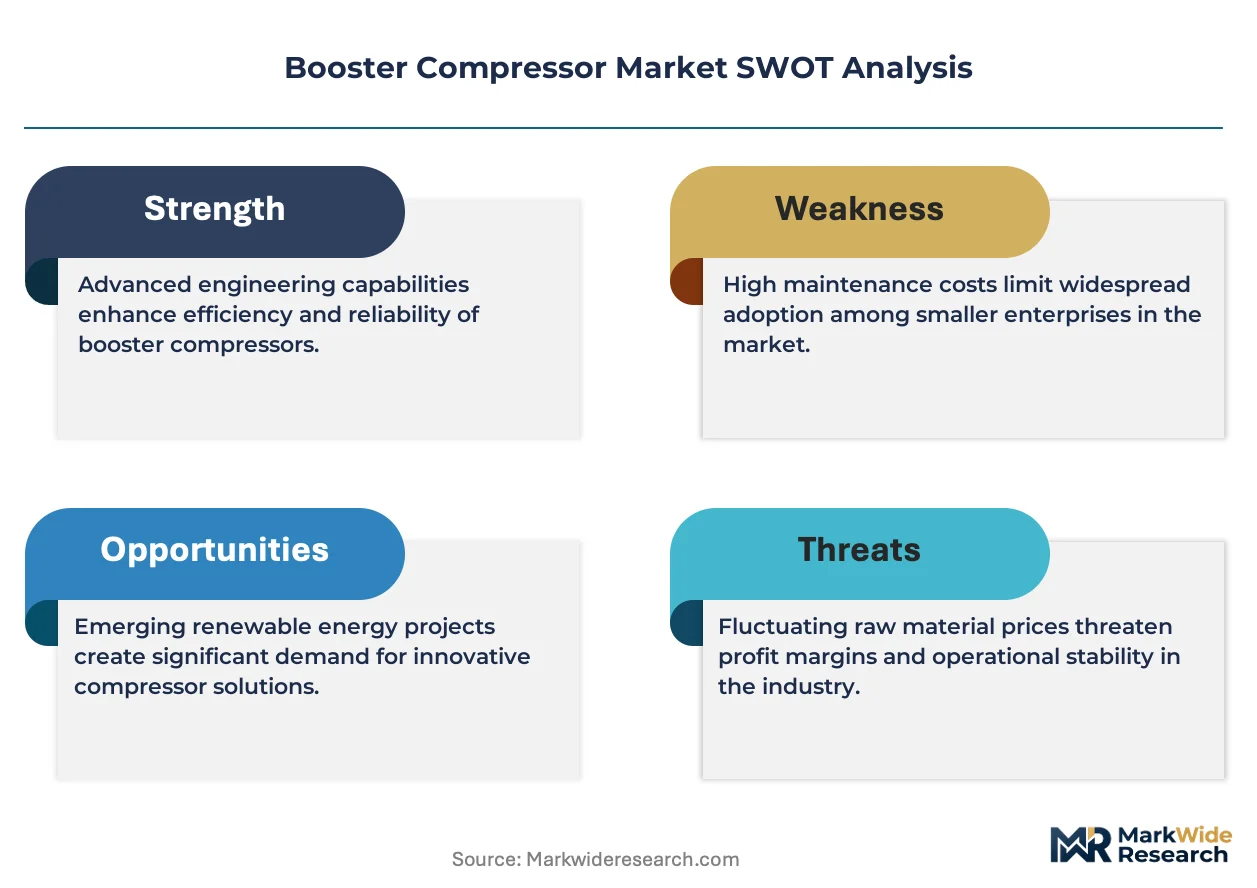
- High Capital Costs:The significant upfront investment for high-pressure, application-specific booster compressors, particularly for large-scale transmission, can deter investment for smaller operators or in uncertain economic climates.
- Material Science Limitations:Handling highly corrosive or pure gases, including hydrogen and carbon dioxide for CCUS, pushes the limits of current sealing technologies and metallic alloys, constraining operational reliability.
- Technical Skill Scarcity:A shortage of technicians with the specialized expertise to service and maintain advanced, high-pressure reciprocating and centrifugal compressors limits aftermarket growth and impacts equipment uptime.
Strategic Opportunities
- Carbon Capture and Storage (CCUS):Emerging CCUS projects create a new application segment, requiring high-pressure compressors to transport and inject captured carbon dioxide into geological storage sites.
- Food-Grade and Pharmaceutical Air:Developing oil-free compressors that meet the stringent ISO 8573 Class 0 air quality standard opens high-value niches in the food, beverage, and pharmaceutical manufacturing industries.
- Retrofit and Modernization Services:The large installed base of natural gas infrastructure in North America and Europe presents a substantial opportunity for service-based revenue from retrofitting compressors to handle new gas blends.
Industry Challenges
- Legacy System Integration:Integrating new, digitally controlled booster compressors with existing, often decades-old, plant control systems and primary compressors presents significant technical and operational hurdles for end-users.
- Fragmented Regulatory Compliance:Navigating the disparate requirements of the EU's CE marking, US EPA standards, and various national rules increases the complexity and cost of designing and certifying products for a global customer base.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Booster Compressor Market |
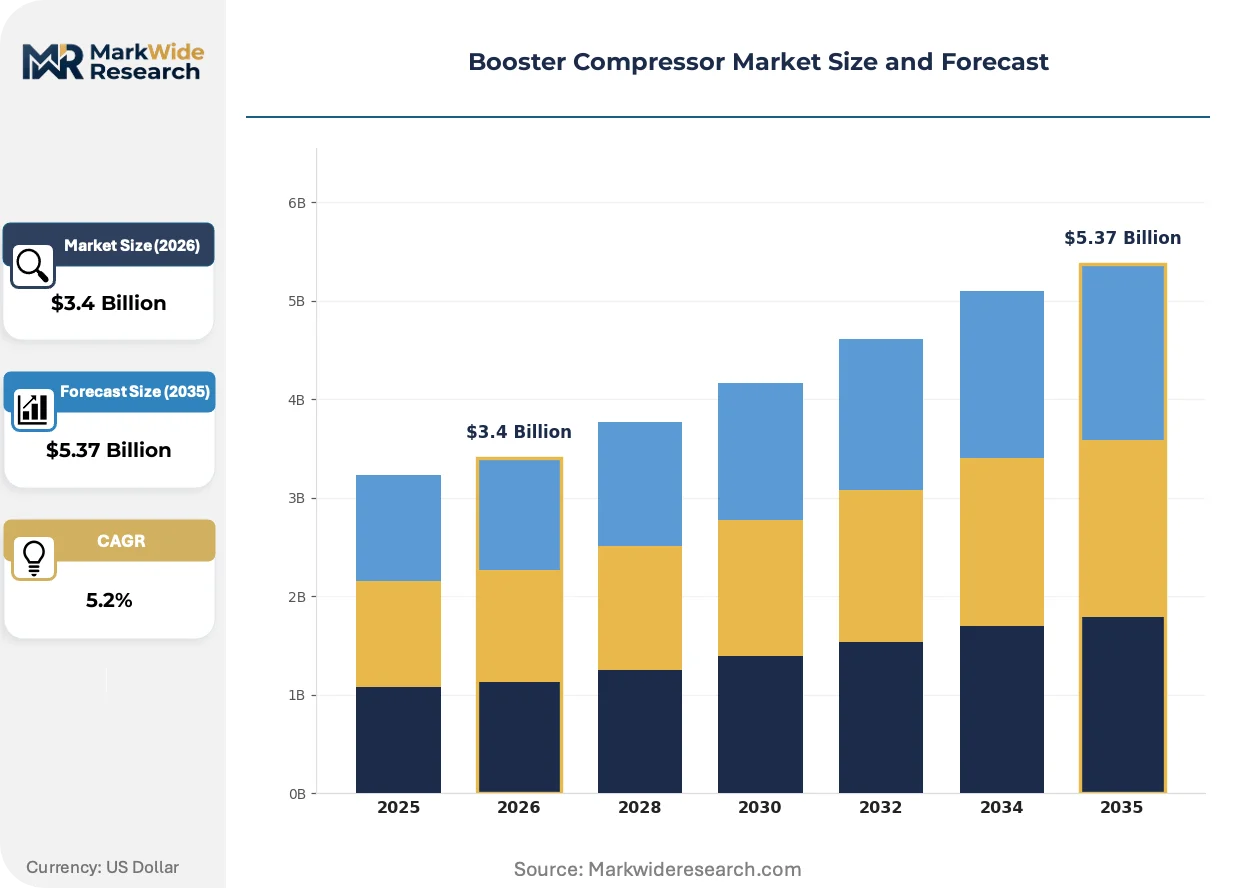
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.37 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reciprocating, Centrifugal, Screw, Diaphragm Technology: Magnetic Bearing, Oil-Lubricated, Gas-Lubricated, Dry Gas Seal Application: Natural Gas Boosting, Petrochemical Processing, Pipeline Transmission, Air Separation End User Industry: Oil & Gas Exploration, Chemical Manufacturing, Power Generation, Semiconductor Fabrication |
| Companies Covered | Atlas Copco AB, Ingersoll Rand, Baker Hughes Company, Kaeser Kompressoren, Gardner Denver, Bauer Kompressoren, BOGE Compressed Air Systems, Siemens Energy AG, Hitachi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Booster Compressor Market Strategic Shifts & Innovations
Intelligent systems and fuel flexibility are becoming standard requirements, not premium features. The market is shifting from a focus on mechanical efficiency alone to total lifecycle performance, encompassing energy use, emissions compliance, and predictive operational management through digital overlays.
Remote monitoring technologies, integrating Industrial IoT sensors and predictive analytics, are a primary focus. Midstream gas operators are the principal adopters, seeking to maximize asset availability and minimize unplanned downtime in remote pipeline stations. This technology is digitizing asset management, shifting maintenance from a reactive schedule to a data-driven, predictive optimization model.
European Union climate policy, specifically the F-Gas Regulation, is influencing compressor design beyond its intended scope of refrigeration. The regulation's phase-down of hydrofluorocarbons is compelling manufacturers to innovate with alternative, natural refrigerants or different thermodynamic cycles in specialized gas compression applications. This affects the chemical and industrial gas sectors, which must now invest in systems compatible with these next-generation substances.
A preference for operational expenditure (OpEx) over capital expenditure (CapEx) is altering purchasing behavior. This trend manifests as a move towards long-term leasing or "Air as a Service" contracts, where vendors are responsible for equipment, maintenance, and uptime for a fixed fee. This model is gaining traction in general industrial and automotive manufacturing in Europe, favoring suppliers with robust service networks and financial strength.
Booster Compressor Market Segmentation
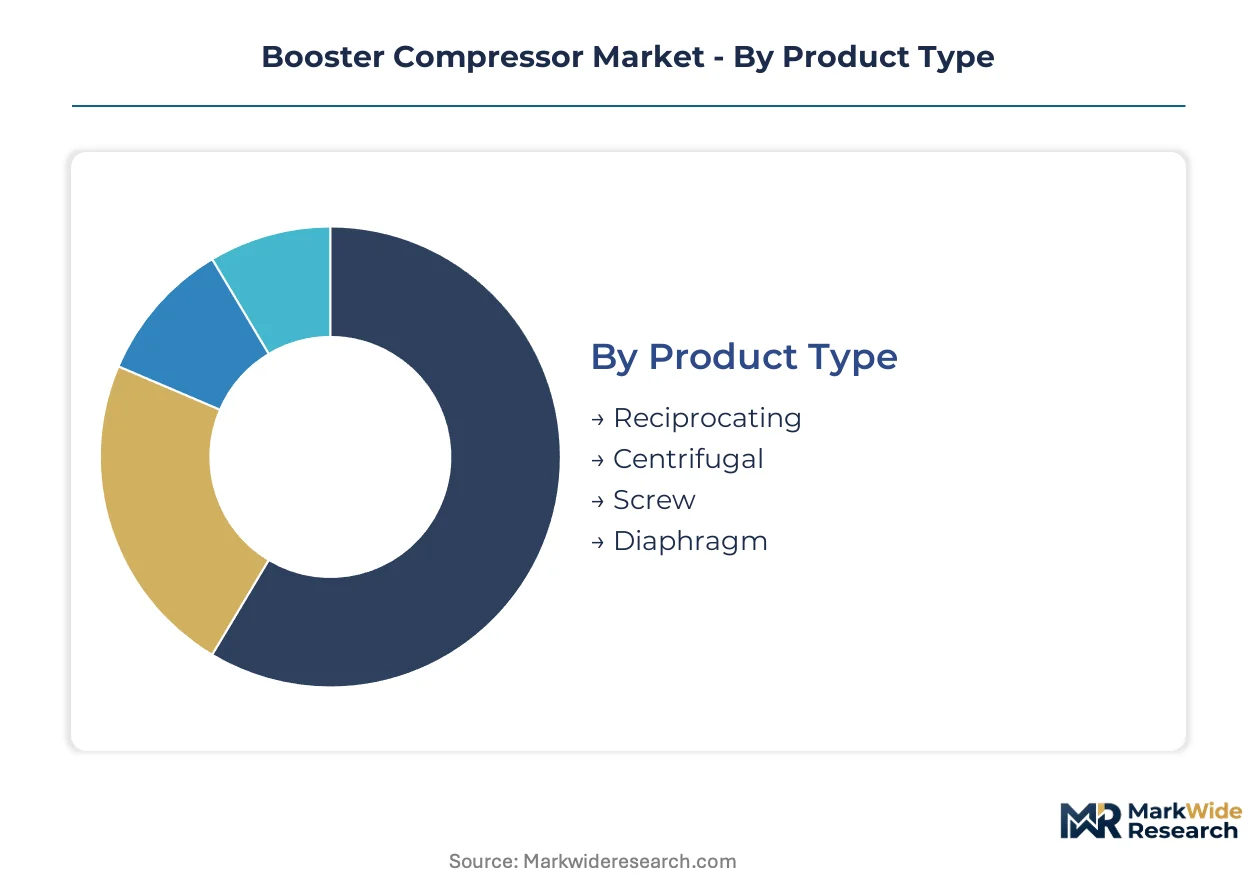
The Booster Compressor Market segmentation offers a granular view of market dynamics, highlighting specific demand drivers and technological preferences across various industrial applications. This detailed breakdown helps stakeholders understand where investment concentrates and how different product and technology choices meet diverse operational requirements.
Product Type:
The product type segmentation reveals a mix of mature and emerging compressor designs, each optimized for distinct operational envelopes and performance characteristics.
- Reciprocating:These compressors utilize pistons to deliver high-pressure, low-flow gas, excelling in applications requiring precise pressure control and efficiency. Demand for reciprocating units is expanding in natural gas boosting for pipeline transmission in China.
- Centrifugal:Centrifugal compressors achieve high flow rates and continuous operation through rotating impellers, making them suitable for large-scale industrial processes. Their adoption is increasing in petrochemical processing plants requiring high-volume gas movement.
- Screw:Screw compressors provide continuous flow with good efficiency for medium-pressure applications, finding utility in general industrial air compression.
- Diaphragm:Diaphragm compressors prevent process gas contamination by using a flexible membrane, crucial for handling corrosive or ultra-pure gases in specialized chemical processes.
Reciprocating compressors handle the majority of throughput for high-pressure applications; Centrifugal units are the fastest mover on share for continuous flow operations.
Technology:
Technology choices often reflect a balance between initial capital outlay and long-term operational efficiency, influencing compressor selection across diverse industrial settings.
- Oil-Lubricated:These traditional compressors employ oil for lubrication and sealing, offering robust performance and widespread availability across many industrial applications. Their proven reliability remains a key factor for midstream gas operators in North America.
- Dry Gas Seal:Dry gas seals eliminate contact between rotating and stationary parts, preventing contamination and reducing maintenance needs for critical processes. Adoption is growing in natural gas infrastructure due to stricter methane emission regulations from the US EPA.
- Magnetic Bearing:Magnetic bearing technology removes physical contact, reducing friction and wear for enhanced efficiency and reliability in specialized high-speed applications.
- Gas-Lubricated:Gas-lubricated seals utilize process gas itself for lubrication, minimizing contamination risks in applications handling sensitive or high-purity media.
Oil-lubricated systems see widespread adoption due to their proven reliability, while dry gas seals are gaining momentum for their environmental benefits.
Application:
Application segments delineate demand volume across critical industrial processes, each with specific pressure and flow requirements for booster compressors.
- Natural Gas Boosting:This segment involves increasing natural gas pressure for pipeline transmission and storage, representing a primary growth area for booster compressors. Energy infrastructure investments in China are driving significant demand in this area.
- Pipeline Transmission:Booster compressors facilitate the long-distance transport of natural gas through extensive pipeline networks, maintaining pressure and flow efficiency. Large-scale projects in Europe are upgrading existing infrastructure to handle hydrogen blends.
- Petrochemical Processing:Booster compressors support various operations within petrochemical plants, including gas recovery and feedstock compression.
- Air Separation:These compressors are essential for separating atmospheric air into its constituent gases like oxygen, nitrogen, and argon for industrial use.
Significant investment concentrates in natural gas boosting, with petrochemical processing also requiring specialized compressor solutions.
End User Industry:
End-user industries represent distinct customer types with varied operational demands and regulatory compliance needs, shaping the specific requirements for booster compressor systems.
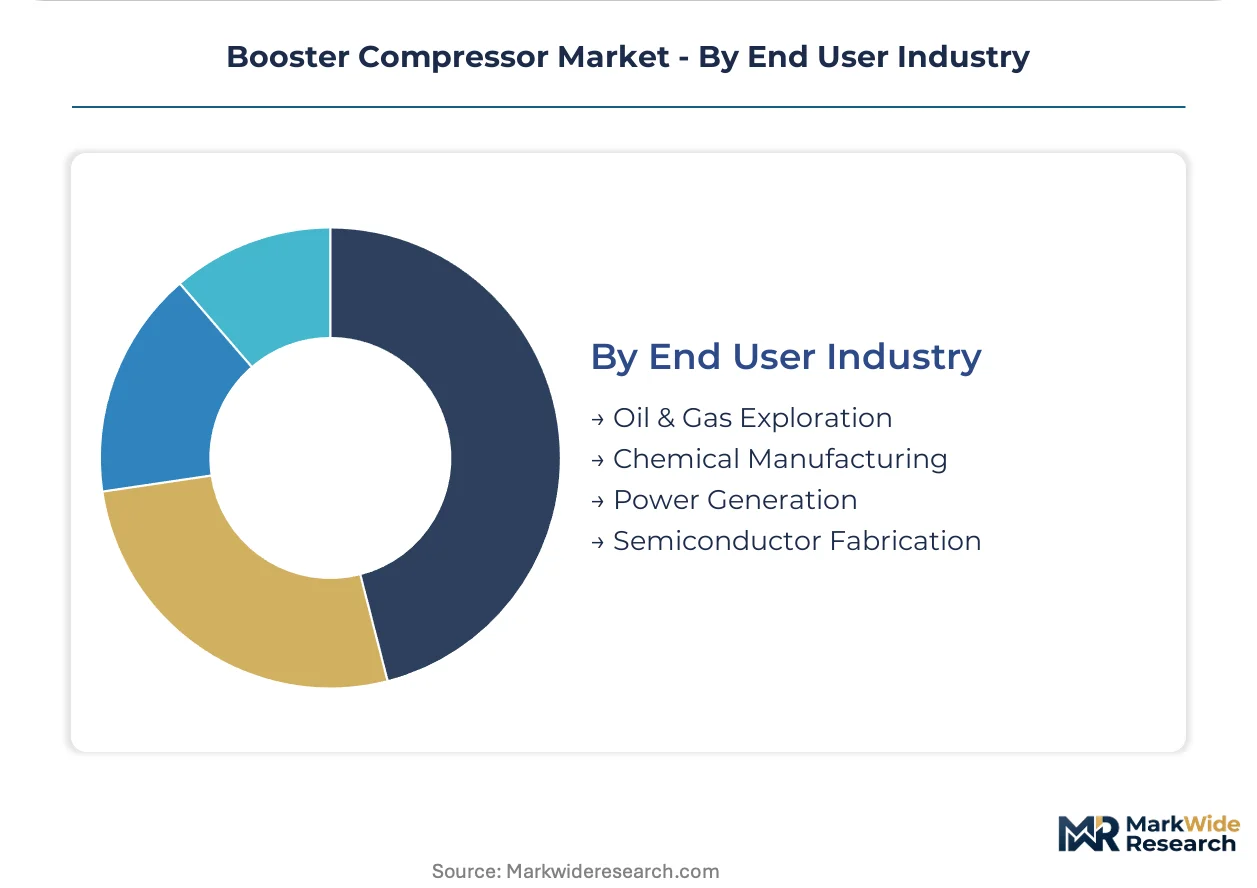
- Oil & Gas Exploration:This sector utilizes booster compressors for wellhead gas compression, gas lift, and enhanced oil recovery, crucial for maximizing resource extraction. Stricter methane emission rules from the US EPA influence compressor upgrades in this industry.
- Chemical Manufacturing:Chemical plants require booster compressors for processes involving gas transfer, reaction, and purification, often handling corrosive or toxic media. Specialized materials are necessary for hydrogen production facilities.
- Power Generation:Booster compressors support power plants for gas turbine fuel supply, carbon capture, and other auxiliary processes.
- Semiconductor Fabrication:This industry demands ultra-high purity air and gas compression, utilizing oil-free compressors to prevent contamination of sensitive manufacturing environments.
Demand is primarily shaped by the oil and gas sector's infrastructure projects, while chemical manufacturing presents a diverse range of specialized requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global natural gas pipeline network underwrites the diverse regional demand for booster compressors. These critical infrastructure assets facilitate energy transmission and distribution across continents. Operators require specialized compression solutions to maintain efficient flow and meet growing energy needs.
China
Demand for booster compressors in China is driven by extensive national pipeline expansion projects and increasing natural gas consumption. The dual carbon goals set by the Chinese government compel investments in efficient energy infrastructure. Major industrial zones like the Yangtze River Delta are seeing significant new booster compressor station deployments for natural gas transmission.
United States
The vast natural gas pipeline system in the United States requires continuous investment in booster compressors for pressure maintenance and throughput. US EPA regulations regarding methane emissions from oil and gas operations directly influence compressor upgrades and replacements. The Permian Basin in Texas, a major production hub, is a key area for new low-emission compressor installations.
Germany
Germany's energy transition initiatives and the need to upgrade its natural gas grid for potential hydrogen blending drive booster compressor demand. The EU's F-Gas Regulation indirectly influences compressor design through broader climate policy. Industrial regions like North Rhine-Westphalia are focusing on modernizing existing pipeline infrastructure to enhance energy security.
India
India's expanding city gas distribution networks and national pipeline projects are boosting demand for natural gas compressors. Government initiatives like the PLI scheme for manufacturing support domestic production capabilities for energy equipment. Major industrial corridors, including those around Gujarat, are attracting investments in new gas infrastructure development.
Booster Compressor Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, providing critical sub-assemblies. The booster compressor market exhibits a tiered structure, with global diversified industrial conglomerates alongside specialized equipment manufacturers. Strategic archetypes include large-scale solution providers, mid-market niche players, and regional service-focused firms. Companies pursue strategic partnerships for technology co-development and expand their service networks to maintain market share.
On the premium-tier vector, Atlas Copco AB exemplifies a global leader with a broad portfolio and extensive service capabilities, catering to diverse industrial applications. Ingersoll Rand occupies a position as a provider of proven and reliable compression solutions, particularly for midstream operations where uptime is critical. Baker Hughes Company anchors the high-specification segment for large-scale pipeline transmission projects, representing specialized engineering expertise for complex energy infrastructure. These entities operate across diverse geographies, leveraging their established reputations and technical prowess to address stringent industrial demands.
| Leading Market Players |
|---|
| Atlas Copco AB |
| Ingersoll Rand |
| Baker Hughes Company |
| Kaeser Kompressoren |
| Gardner Denver |
| Bauer Kompressoren |
| BOGE Compressed Air Systems |
| Siemens Energy AG |
| Hitachi |
| Others |
Cost & Logistics Intelligence
Undercapacity in specialized component manufacturing, particularly for hydrogen-compatible materials, drives supplier behavior and influences pricing posture for advanced booster compressors. This dynamic fosters long-term contract negotiations and strategic partnerships for securing critical inputs.
Pricing Analysis
EU CE marking and ISO 8573 standards dictate the pricing tier structure for booster compressors, segmenting offerings by certified performance and air quality. Pricing stratifies across premium, standard, and economy tiers, with differentiation driven by customization level for specific industrial processes and comprehensive after-sales service packages. Pricing softness reflects high capital costs for advanced units, especially for smaller operators. Large-scale infrastructure projects prioritize long-term reliability and regulatory compliance, exhibiting lower price sensitivity than general industrial buyers.
Supply Chain Analysis
Extended payment terms for large capital equipment purchases facilitate project financing across the booster compressor supply chain. Component manufacturing concentrates in Germany, the United States, and China, reflecting established industrial bases. Raw material dependencies include specialized metallic alloys for hydrogen compatibility and advanced sealing technologies. Single-source vulnerability for critical digital control components represents a structural supply chain risk. Distribution relies on direct sales channels and extensive local service networks provided by major OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a substitution defense, as incumbents must navigate the threat of alternative energy sources and evolving gas compositions.
For Market Incumbents: Entrench core market share by expanding service networks, particularly in regions with aging natural gas infrastructure like North America and Europe. Invest strategically in R&D for hydrogen compression technologies to address new fuel compositions. Leverage existing certification investments (ISO 8573, CE marking) to maintain a competitive edge against emerging players in specialized applications. Focus on digital integration for predictive maintenance to enhance asset availability and minimize downtime, countering the threat of stringent emissions regulations.
For New Entrants and Emerging Players: Establish a beachhead in niche applications requiring specialized capabilities, such as carbon capture and storage (CCUS) or food-grade air compression. The emerging CCUS segment, requiring high-pressure CO2 compressors, represents a penetrable white space. Pursue a technology licensing model or "Air as a Service" contracts, particularly in general industrial and automotive manufacturing, to overcome the high capital cost barrier for end-users. Focus on developing oil-free compressors meeting ISO 8573 Class 0 standards for high-value pharmaceutical and food industries.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across the hydrogen-ready compressor sub-segment, signaling increased investment requirements. Long-term viability rests on the global energy transition and sustained infrastructure investments in natural gas and alternative fuels. Target specialist firms with proven expertise in hydrogen-compatible materials, advanced sealing technologies, or digital monitoring solutions. The pace of new hydrogen blending mandates and CCUS project approvals serves as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Hydrogen-Compatible Compressors | Addresses new fuel compositions and expands market reach into green energy infrastructure projects. |
| Expand Global Service Network | Enhances aftermarket revenue and supports the installed base, ensuring operational reliability for end-users. |
| Invest in Digital Monitoring Solutions | Improves asset uptime and enables predictive maintenance, crucial for remote pipeline operations. |
| Target Carbon Capture and Storage (CCUS) | Opens a new, high-growth application segment requiring specialized high-pressure compression technology. |
| Offer "Air as a Service" Contracts | Aligns with customer preference for OpEx models, securing long-term revenue streams for vendors. |
Research Approach
Desk research of industry association reports, government energy policies, and company annual filings preceded structured interviews with plant managers, R&D directors, procurement leads, and regulatory compliance officers. This approach combined primary insights with secondary validation, ensuring a comprehensive understanding of market dynamics. Bottom-up and top-down triangulation methods were employed to cross-verify data points and refine market sizing estimates.
The forecast framework established a baseline set of assumptions regarding global energy demand and infrastructure development across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user industry, and regional infrastructure development. Compound Annual Growth Rates (CAGRs) were derived from historical trends, identified market drivers, and expert projections. Key industry-specific forecast inputs included planned natural gas pipeline expansion projects and regulatory timelines for methane emission reductions.
Stress conditions across geopolitical stability and technological adoption rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions documented throughout this study. Geopolitical shifts affecting energy supply or unforeseen material science breakthroughs could prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
PAG Compressor Oil Market
Compressors
Europe Compressor Market
Compressors
Reciprocating Hydrogen Compressor Market
Compressors
Liquid Ring Compressors Market
Compressors
Compressed Air Lubricators Market
Compressors
Integrally Geared Centrifugal Compressor Market
Compressors
Process Gas Compressors Market
Compressors
Portable Air Compressor Market
Compressors
Regenerative Blowers Market
Compressors
Oil Filled Air Compressor Market
Compressors
North America Hydrogen Compressor Market
Compressors
Oil-Injected Screw Compressor Market
Compressors
Asia-Pacific Booster Compressor Market
Compressors
Air and Gas Compressor Market
Compressors
Rental Air Compressors Market
Compressors
CNG Compressor Market