
 Compressor Rental Market | 2026-2036
Compressor Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Compressor Rental Market Analysis
Class-0 oil-free certification is redrawing competitive boundaries in the compressor rental landscape. Atlas Copco leverages its oil-free technology leadership to command premium positioning in pharmaceutical and food-grade applications. United Rentals sustains unmatched fleet scale across North American construction corridors. Ingersoll Rand anchors its rental portfolio through deep integration with climate and industrial compression expertise.
Compressor rental involves the short-term provision of positive-displacement or dynamic compression equipment, typically delivering 100–2,000 CFM at pressures from 100–500 PSI, for industrial processes requiring on-site compressed air, gas handling, or pneumatic power. The primary purpose centers on eliminating capital lock-up while matching capacity to project duration and seasonal demand. Portable diesel units dominate mining and remote construction deployments where grid connectivity remains absent. Electric compressors claim expanding share in manufacturing and urban construction as site electrification advances. Dewatering applications generate the most intensive utilization rates across flood remediation and underground infrastructure projects.
EPA Tier 4 Final emissions mandates and OSHA workplace noise exposure limits shape fleet investment cycles and equipment retirement timelines across the United States. The Department of Transportation's highway weight restrictions further constrain trailer-mounted compressor design and regional deployment logistics. Stakeholders must weigh carbon intensity regulations against total cost of ownership when structuring multi-year rental agreements and fleet renewal schedules.
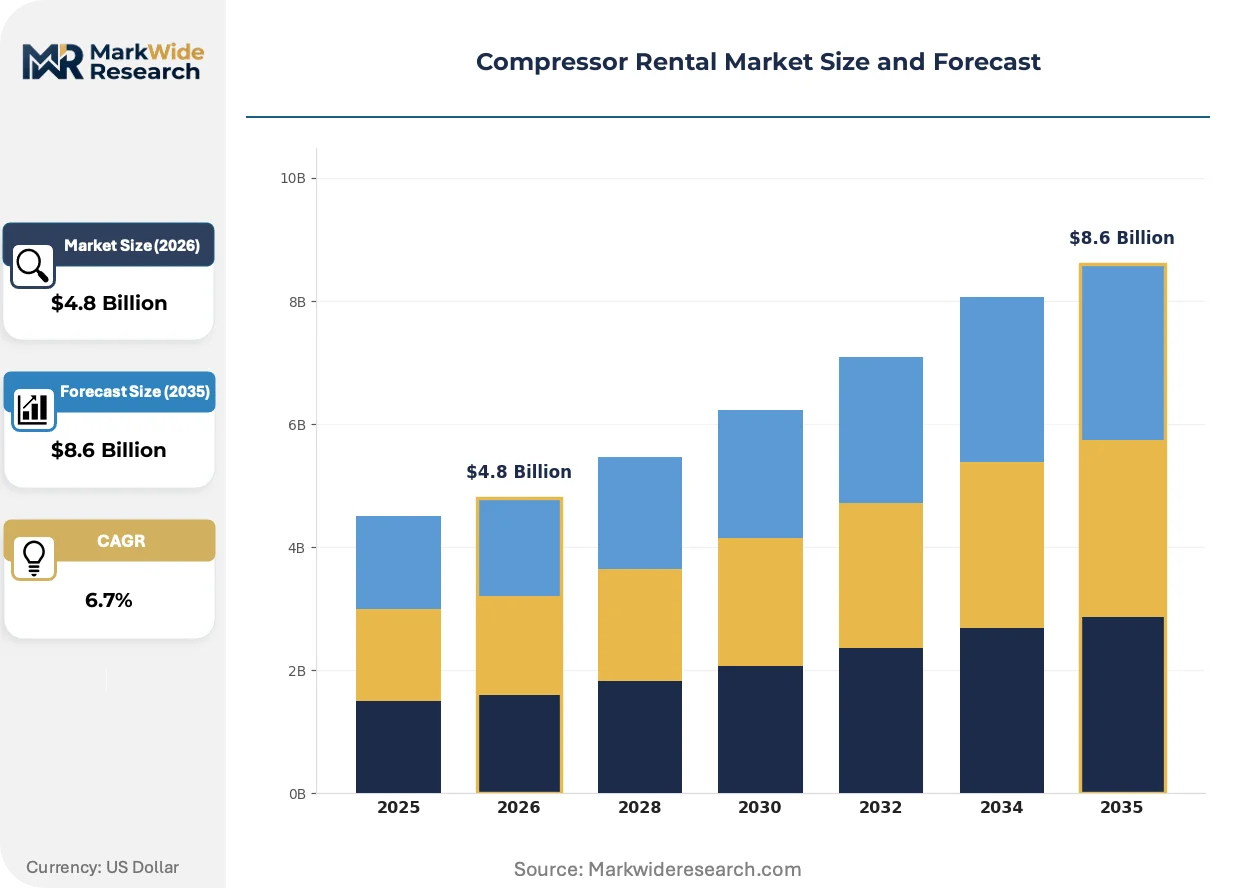
Market Dynamics
Construction firms are abandoning capital-intensive compressor ownership for rental models, while EPA Tier 4 Final emissions mandates force fleet turnover toward cleaner diesel and electric alternatives.
Growth Catalysts
- Petrochemical Turnaround Cycles:The United States Gulf Coast corridor generates concentrated short-term demand as refineries execute scheduled maintenance, requiring rapid compressor deployment without long-term asset commitment.
- OSHA Noise Exposure Limits:Stricter workplace acoustic standards push contractors toward newer rental fleets with advanced sound attenuation rather than aging owned equipment.
- Electric Compressor Adoption:Site electrification in urban construction and manufacturing enables grid-connected electric units to displace diesel for indoor and noise-sensitive applications.
Market Restraints
- Diesel Engine Cost Inflation:Tier 4 Final aftertreatment systems and DEF consumption raise operating costs for portable diesel fleets, compressing rental margins on legacy equipment.
- Fleet Concentration Risk:Major rental providers dominate metropolitan hubs, leaving remote mining and energy extraction sites with limited supplier choice and extended logistics lead times.
- Grid Connectivity Gaps:Electric compressor penetration stalls at off-grid construction and remote pipeline maintenance sites where diesel remains the sole viable power source.
Strategic Opportunities
- Class-0 Oil-Free Certification:Pharmaceutical and food-grade manufacturers face zero-tolerance contamination policies, creating premium rental demand for certified oil-free compression systems.
- Flood Remediation Dewatering:Climate-intensified storm frequency drives emergency compressor deployment for municipal dewatering operations, generating highest-utilization revenue streams.
- IRA Clean Energy Incentives:United States tax credits for electrification and emissions reduction accelerate customer willingness to specify electric rental units over conventional diesel.
Industry Challenges
- Certified Technician Scarcity:EPA emissions diagnostics and oil-free compressor maintenance require specialized training that rental field operations struggle to staff at scale.
- DOT Highway Weight Compliance:Trailer-mounted compressor design must balance airflow capacity against federal axle load limits, constraining equipment portability across state lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compressor Rental Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tank Mounted, Portable, Electric, Diesel End User: Construction, Mining, Oil & Gas, Manufacturing Application: Dewatering, Sandblasting, Air Tool Operations, Pneumatic Conveying Distribution Channel: Direct Sales, Online Rental Platforms, Dealerships, Rental Agencies |
| Companies Covered | Atlas Copco, United Rentals, Ingersoll Rand, Caterpillar, Ashtead Group, Hertz Equipment Rental Corporation, Aggreko, Loxam Group, Sunbelt Rentals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compressor Rental Market Emerging Trajectories
Digital fleet telemetry and predictive maintenance algorithms are compressing equipment downtime and reshaping how rental providers price utilization risk.
Variable-speed drive (VSD) technology is fragmenting the traditional fixed-speed compressor rental market. VSD units modulate motor speed to match real-time air demand, cutting fuel consumption by fifteen to thirty-five percent versus load-unload controls. Mining contractors in Western Australia and oil sands operators in Alberta are specifying VSD for continuous-duty applications. The technology is fragmenting rental fleet standardization, forcing providers to maintain dual inventory pools and specialized technician certifications.
EPA Tier 4 Final compliance deadlines have eliminated non-certified diesel engine production for rental compressors above 25 horsepower. Equipment manufacturers have consolidated engine supplier relationships around Cummins and Perkins platforms with integrated selective catalytic reduction. The regulatory compression most severely affects smaller regional rental fleets lacking capital for fleet renewal, accelerating consolidation toward national providers with structured turnover programs.
Telematics-enabled usage billing is displacing flat-rate rental contracts in municipal and industrial accounts. Sensors reporting runtime, load factor, and location allow providers to invoice against actual compressed air delivered rather than calendar days. Water treatment utilities in Germany and automotive assembly plants in the United States have adopted this model. The shift transfers operational risk to rental providers while locking customers into multi-year telemetry subscriptions.
Compressor Rental Market Segmentation
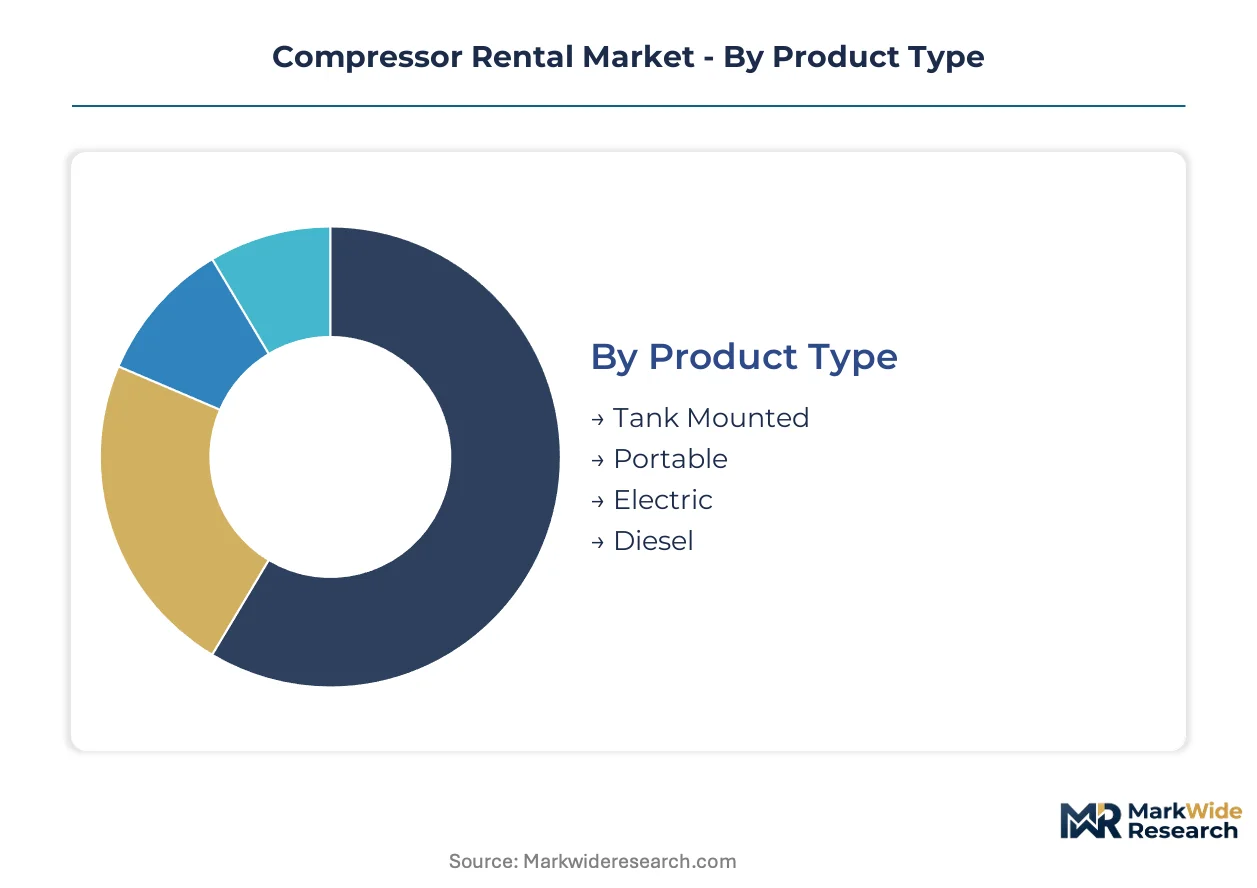
Compressor rental demand fragments across power sources, mobility requirements, and end-use contamination standards. Each segment carries distinct margin profiles tied to regulatory compliance burdens and utilization intensity.
Product Type:
Margins concentrate in oil-free electric units where pharmaceutical and food-grade certifications command rental premiums. Diesel portable units generate volume but face Tier 4 Final compliance cost pressures.
- Tank Mounted:Stationary receivers integrated with compression modules serve permanent manufacturing installations requiring consistent pressure storage. Demand clusters in automotive assembly plants across Michigan and Ohio where OSHA noise limits favor enclosed configurations over open-frame portables.
- Portable:Trailer-mounted or skid-based units deploy to construction sites, mines, and pipeline maintenance corridors without fixed infrastructure. Mining contractors in Western Australia and Alberta oil sands operators specify these for rapid relocation between extraction zones.
- Electric:Grid-connected units eliminate diesel aftertreatment complexity and indoor emissions concerns. Urban construction sites in Germany and manufacturing facilities in South Korea are rotating specifications toward electric as site electrification advances.
- Diesel:Off-grid power independence sustains dominance in remote pipeline maintenance and emergency dewatering where grid connectivity remains absent.
Portable holds installed capacity. Electric is rotating up the share rankings.
End User:
Application intensity varies sharply: petrochemical turnarounds compress demand into narrow windows while manufacturing spreads utilization across calendar years.
- Construction:General contractors and specialty trades rent compressors for pneumatic tools, shotcrete application, and temporary site power. Infrastructure stimulus in the United States and highway expansion in India are expanding fleet deployment to bridge and tunnel projects.
- Mining:Underground and open-pit extraction operations require continuous compressed air for drilling, ventilation, and material handling. Copper mines in Chile and iron ore operations in Western Australia sustain the highest annual utilization hours.
- Oil & Gas:Upstream drilling, midstream pipeline maintenance, and downstream refinery turnarounds create episodic demand spikes. The United States Gulf Coast petrochemical corridor generates concentrated short-term deployment during scheduled maintenance cycles.
- Manufacturing:Automotive, electronics, and packaging plants rent backup capacity or supplement owned equipment during production ramps. Semiconductor fabrication facilities in Taiwan and South Korea specify Class-0 oil-free certification for zero-tolerance contamination environments.
Manufacturing holds installed capacity. Oil & Gas is rotating up the share rankings.
Application:
Emergency response applications capture steepest pricing power due to time-critical deployment requirements.
- Dewatering:Flood remediation, tunnel construction, and municipal drainage operations deploy high-volume compressors to drive pump systems. Climate-intensified storm frequency in the United States Gulf Coast and Central Europe is expanding municipal emergency fleet contracts.
- Sandblasting:Surface preparation for coatings and corrosion removal in marine, infrastructure, and industrial maintenance. Shipyards in South Korea and offshore platform operators in the North Sea specify moisture-free compressed air for coating adhesion standards.
- Air Tool Operations:Pneumatic hammers, drills, and impact wrenches on construction sites and assembly lines. General building contractors represent the volume base with standardized CFM and PSI requirements.
- Pneumatic Conveying:Bulk material transport through pipeline systems in food processing, pharmaceuticals, and cement manufacturing. Powder handling facilities in Germany and dairy processing plants in the Netherlands require oil-free air to prevent product contamination.
Air Tool Operations holds installed capacity. Dewatering is rotating up the share rankings.
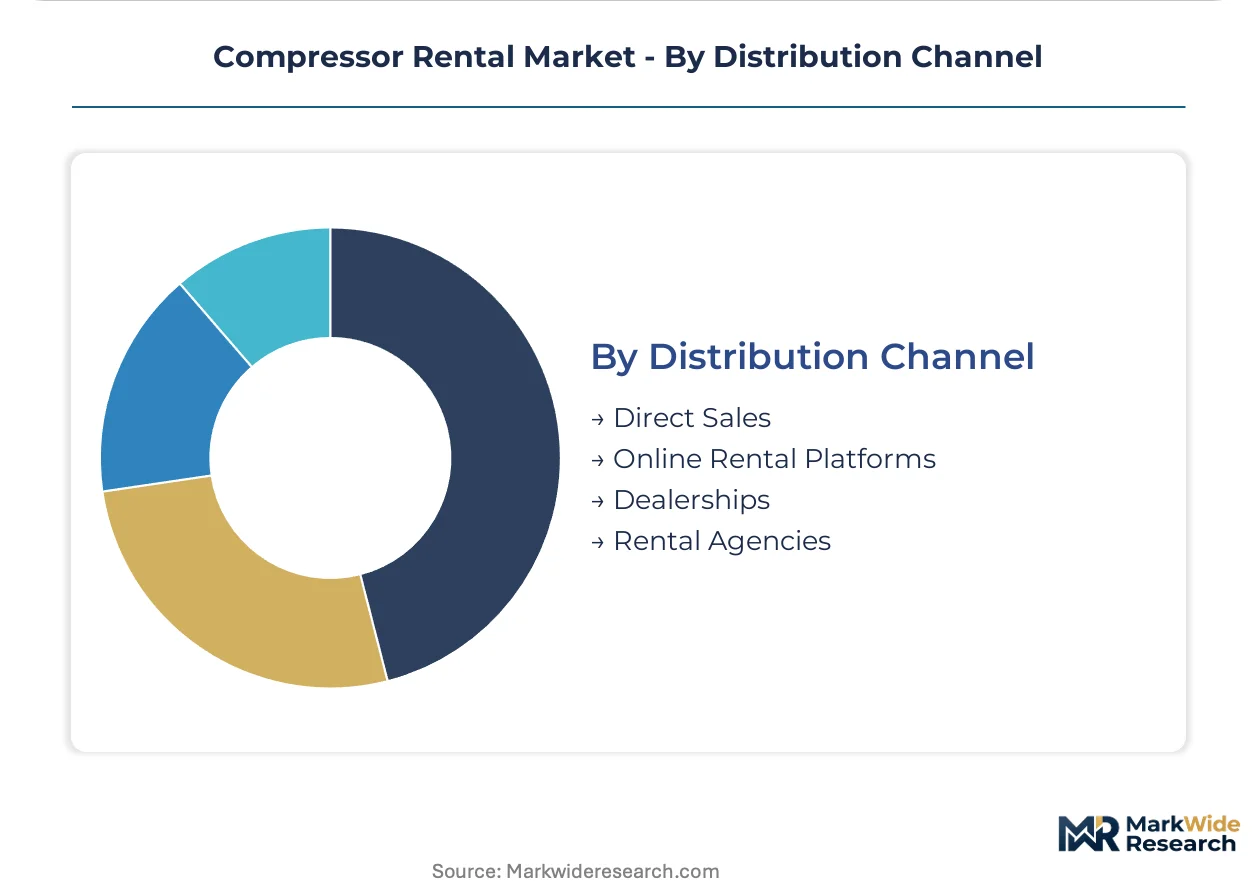
Distribution Channel:
Channel economics diverge between high-touch rental agencies and low-margin digital platforms scaling through self-service logistics.
- Direct Sales:National rental providers maintain dedicated account teams for industrial and municipal clients with multi-year framework agreements. Water treatment utilities in Germany and automotive OEMs in the United States negotiate telemetry-enabled usage billing through direct procurement channels.
- Online Rental Platforms:Digital marketplaces aggregate fleet availability and enable price-transparent booking with automated logistics coordination. Independent contractors in urban construction corridors are adopting platform-based procurement for short-duration projects.
- Dealerships:Equipment dealers extend rental services alongside sales operations, particularly in secondary markets. Regional construction equipment distributors in Texas and Alberta maintain compressor fleets as ancillary to excavator and loader rentals.
- Rental Agencies:Specialized compressor rental firms with technical service capabilities and field technician networks. These providers dominate petrochemical turnaround deployment where rapid mobilization and emissions-certified equipment are mandatory.
Rental Agencies holds installed capacity. Online Rental Platforms is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German compressor rental fleets supply process industries across Central Europe while United States Gulf Coast operators export turnaround expertise to Latin American refineries.
United States
Petrochemical turnarounds along the Texas-Louisiana corridor drive concentrated short-term demand for emissions-certified portable units. EPA Tier 4 Final mandates accelerate fleet turnover toward SCR-equipped diesel and electric alternatives. Houston anchors the densest rental depot network, with providers positioning rapid-response inventory for refinery maintenance windows.
Germany
Automotive assembly plants in Baden-Württemberg and Bavaria specify Class-0 oil-free compressors for zero-tolerance contamination environments. REACH chemical safety regulations and EU Green Deal emissions targets pressure rental fleets toward electric grid-connected systems. The Rhine-Ruhr industrial belt sustains year-round manufacturing demand distinct from project-driven construction cycles.
China
Semiconductor fabrication facilities in Shanghai and Jiangsu province require oil-free certification for chip manufacturing processes. MIIT industrial emissions standards and provincial dual carbon goals accelerate electric compressor specifications in coastal manufacturing zones. The Yangtze River Delta concentrates the highest density of grid-connected rental deployments for electronics production.
Australia
Iron ore and copper mining operations in Western Australia sustain the highest annual utilization hours for continuous-duty portable fleets. State-level workplace noise regulations push contractors toward newer sound-attenuated rental equipment over aging owned assets. The Pilbara region generates episodic demand spikes tied to expansion projects and pit dewatering requirements.
Saudi Arabia
Downstream refinery maintenance and NEOM construction megaprojects create dual demand streams for diesel and electric compressor fleets. The national petroleum regulator enforces emissions compliance timelines aligned with Saudi Vision 2030 industrial diversification. The Eastern Province petrochemical complex mirrors United States Gulf Coast turnaround patterns with concentrated seasonal deployment needs.
Compressor Rental Market Vendor Landscape
Listed leaders compete with private specialists across fleet scale and technical certification depth. The market structures around three tiers: national rental networks with telemetry-enabled billing, regional equipment dealers with ancillary compressor fleets, and specialized oil-free providers serving pharmaceutical and food-grade applications. Consolidation accelerates as Tier 4 Final compliance costs eliminate smaller diesel fleet operators. Dominant competitive moves include telematics platform integration and multi-year framework agreements with municipal utilities.
Within the premium certification tier, Atlas Copco exemplifies oil-free technology leadership while United Rentals anchors scale-driven positioning across North American construction corridors. Ingersoll Rand occupies a position bridging climate and industrial compression expertise. These three represent distinct archetypes: technology-specialized, volume-scaled, and vertically integrated industrial portfolios.
| Leading Market Players |
|---|
| Atlas Copco |
| United Rentals |
| Ingersoll Rand |
| Caterpillar |
| Ashtead Group |
| Hertz Equipment Rental Corporation |
| Aggreko |
| Loxam Group |
| Sunbelt Rentals |
| Others |
Supply Flow & Price Mechanics
Multi-year framework agreements with telemetry-enabled usage billing lock in supply access for municipal utilities and automotive OEMs while anchoring price visibility across volatile diesel aftertreatment cost cycles. These contracts transfer operational risk to rental providers in exchange for guaranteed fleet utilization, compressing spot-market exposure for Tier 4 Final certified equipment.
Pricing Analysis
Current-generation electric compressor rentals command fifteen to thirty-five percent premiums over prior-generation fixed-speed diesel units, while next-generation VSD-equipped portables occupy a mid-tier position. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade—Class-0 oil-free units for pharmaceutical applications sit at the premium extreme, construction-grade portables anchor the economy tier. Cost compression in the diesel portable segment is intensifying because Tier 4 Final aftertreatment systems and DEF consumption raise operating burdens. General contractors exhibit highest price sensitivity due to standardized CFM requirements and abundant supplier choice, while semiconductor fabricators show lowest sensitivity given zero-tolerance contamination policies.
Supply Chain Analysis
Germany and the United States anchor manufacturing of precision compression modules and emissions-certified engine packages, while China concentrates electric motor and control system production. Diesel engine blocks draw from Cummins and Perkins platforms with integrated selective catalytic reduction, electric drives rest on rare-earth magnet supply from Chinese processors, and sound-attenuated enclosures feed from German sheet metal fabricators. Single-source vulnerability in rare-earth magnet processing creates chokepoint exposure for electric fleet expansion. Distribution runs through national rental networks with field technician capabilities, regional equipment dealers with ancillary fleets, and emerging digital platforms enabling automated logistics coordination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Tier 4 Final emissions mandates and accelerating site electrification are disrupting fleet composition economics, compressing diesel equipment lifecycles while opening premium positioning for grid-connected electric and certified oil-free systems.
For Market Incumbents: Fortify telemetry-enabled usage billing platforms to lock in multi-year municipal and industrial accounts before digital marketplaces scale. Deepen backward integration into VSD control system sourcing to defend margins against rare-earth price volatility. Prioritize Class-0 certification investment for pharmaceutical corridor penetration.
For New Entrants and Emerging Players: Emergency dewatering response capabilities represent the most penetrable service-layer gap where incumbents under-serve municipal storm preparedness contracts. Target flood-prone Gulf Coast municipalities with rapid-deployment fleet positioning and 24-hour mobilization guarantees. Pursue climate-intensified storm frequency as the go-to-market angle for highest-utilization revenue streams.
For Investors and Strategic Acquirers: Regional oil-free specialists with pharmaceutical certification depth and established field technician networks present the most compelling acquisition target archetype for portfolio diversification. Long-term viability hinges on electrification transition pacing and emissions regulation stringency. Watch IRA clean energy incentive uptake rates as the signal to monitor for electric fleet adoption inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Enables usage-based billing models that transfer operational risk from customers to rental providers. |
| Class-0 Certification Investment | Opens premium positioning in pharmaceutical and food-grade applications with zero-tolerance contamination policies. |
| Electric Fleet Expansion | Aligns rental portfolios with EPA Tier 4 Final mandates and IRA clean energy incentive structures. |
| Field Technician Network Scaling | Addresses certified technician scarcity for emissions diagnostics and oil-free compressor maintenance. |
| Emergency Response Capability Buildout | Captures climate-intensified dewatering demand from municipal storm preparedness programs. |
Methodological Framework
Operator-level perspectives from rental fleet managers, petrochemical maintenance directors, municipal procurement officers, and compressor field technicians anchored the qualitative base for this analysis. Primary interview findings combined with secondary validation from EPA regulatory filings, SEC 10-K equipment rental disclosures, customs trade data on compression module imports, and OSHA workplace noise exposure databases. Bottom-up segment sizing triangulated against top-down market envelope estimates derived from national rental fleet capacity disclosures.
Sensitivity analysis tested forecast robustness across diesel-electric mix scenarios, emissions compliance timeline variations, and petrochemical turnaround cycle intensity assumptions throughout the projection horizon. Segmentation dimensions modeled include power source type, mobility configuration, end-use contamination standard, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and rental penetration trend extrapolation. Industry-specific forecast inputs incorporated Tier 4 Final fleet turnover schedules and site electrification adoption curves.
Material uncertainties—petrochemical turnaround timing shifts, rare-earth supply disruption events, and emissions regulation enforcement intensity variations—sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory compliance deadlines and technology cost curves. Recalibration cycles align with material shifts in EPA enforcement patterns, IRA incentive program modifications, and climate-intensified emergency response demand spikes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Reciprocating Hydrogen Compressor Market
Compressors
Oil-Injected Screw Compressor Market
Compressors
Reciprocating Compressor Market
Compressors
Asia-Pacific Centrifugal Compressor Market
Compressors
Portable Compressor Market
Compressors
Air Compressor Market
Compressors
Turbocompressor Market
Compressors
Portable Air Compressor Market
Compressors
Stationary Air Compressor Market
Compressors
Compressed Air Lubricators Market
Compressors
CNG Compressor Market
Compressors
Europe Compressor Market
Compressors
Scroll Compressor Market
Compressors
Oil Free Compressor Market
Compressors
North America Centrifugal Compressor Market
Compressors
Rental Air Compressors Market