
 Desiccant Compressed Air Dryer Market | 2026-2036
Desiccant Compressed Air Dryer Market Size, Share, and Industry Trends Forecast 2026-2036
Desiccant Compressed Air Dryer Market Insights
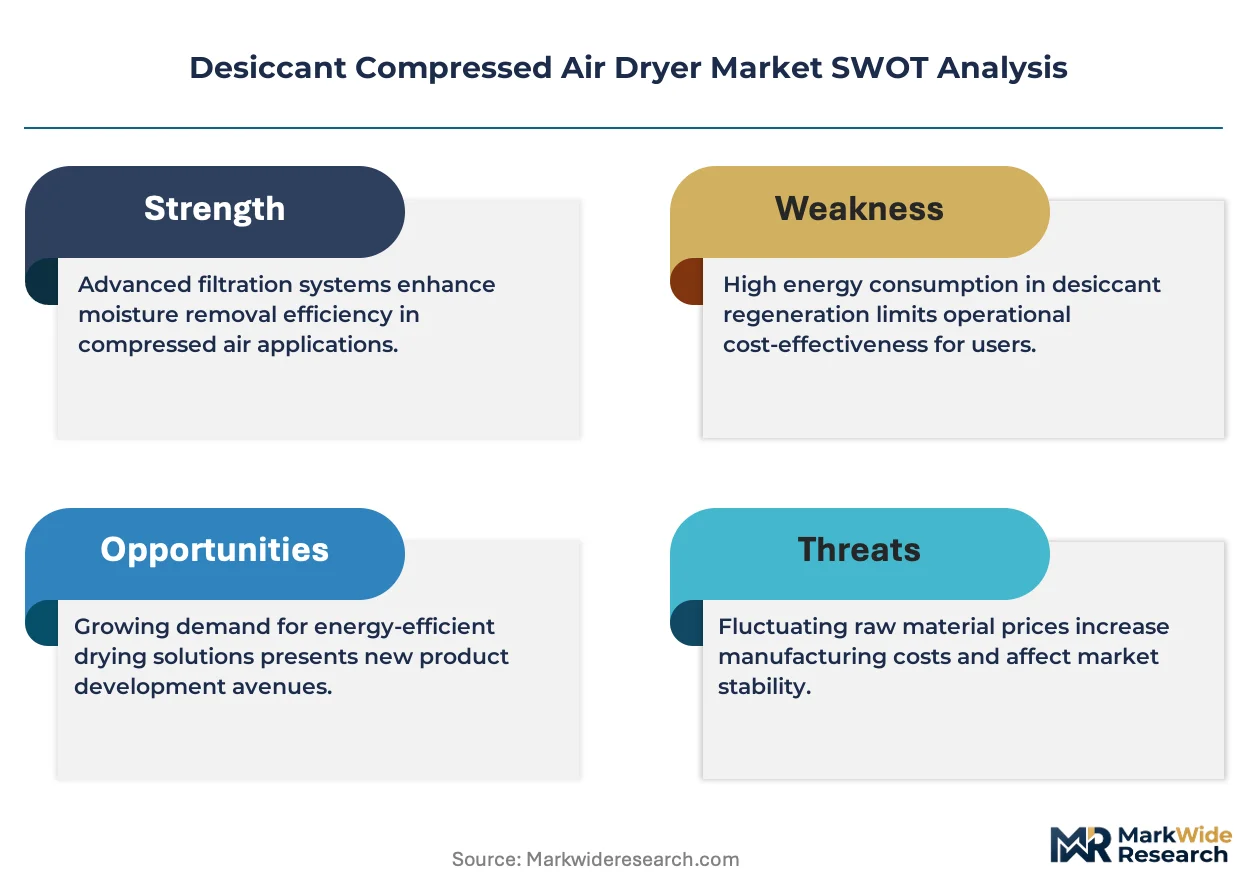
Food processing facilities is reorganizing procurement priorities for compressed air purity, shifting capital toward desiccant systems that guarantee sub-zero pressure dew points. Atlas Copco leverages its rotary drum desiccant technology to anchor premium positions in European dairy and beverage plants. Kaeser Kompressoren sustains manufacturing scale advantages through captive production of desiccant media and valve assemblies. Donaldson Company specializes in filtration-integrated dryer architectures that compete on total cost of ownership metrics against standalone drying units.
A desiccant compressed air dryer removes water vapor from compressed air streams through adsorption onto activated alumina, silica gel, or molecular sieve media, achieving pressure dew points as low as minus seventy degrees Celsius to protect pneumatic equipment and product integrity. Stationary dryers dominate installed capacity in heavy manufacturing settings where continuous operation and high volumetric throughput justify permanent infrastructure, while modular dryer configurations are gaining traction in distributed pharmaceutical cleanrooms that demand scalable redundancy and rapid commissioning cycles. Heatless technology occupies the largest share of unit shipments due to lower capital requirements, though blower purge systems are displacing older heated designs in energy-conscious automotive assembly plants where purge air losses drive operating cost differentials.
The United States EPA enforces National Emission Standards for Hazardous Air Pollutants that constrain oil-lubricated compressor effluent, indirectly elevating desiccant dryer demand as facilities migrate to oil-free air systems requiring more aggressive moisture control. ISO 8573-1 air quality classifications in Europe and North America mandate specific humidity thresholds that only desiccant technologies reliably achieve for Class 1 and Class 2 specifications. Stakeholders must monitor evolving energy efficiency labeling schemes and carbon border adjustment mechanisms that will restructure total cost calculations for heated versus heatless dryer architectures across industrial clusters.
Market Dynamics
The EU F-Gas Regulation is compressing the installed base of refrigerant-based drying systems and redirecting capital flows toward desiccant architectures across European industrial corridors. This regulatory compression is reshaping competitive positioning among dryer manufacturers and forcing accelerated R&D cycles in adsorption media and purge recovery systems.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants is eliminating refrigerant dryer options in pharmaceutical and food processing facilities, creating mandatory upgrade cycles toward heatless and blower purge desiccant systems.
- Pharmaceutical cleanroom expansion:Sterile manufacturing protocols under FDA and EMA guidelines require minus forty degrees Celsius pressure dew points that only molecular sieve desiccant configurations reliably sustain.
- Automotive paint shop networks:Germany's automotive corridor is retrofitting compressed air infrastructure to achieve Class 1 air quality per ISO 8573-1, driving specification upgrades across supplier tiers.
Market Restraints
- Activated alumina price volatility:Supply concentration in Chinese bauxite refining creates input cost instability for desiccant media manufacturers, compressing margin structures for heatless dryer producers.
- Heatless purge air losses:The fifteen to twenty percent compressed air consumption penalty in heatless designs creates lifetime cost disadvantages versus blower purge alternatives in high-duty-cycle applications.
- Refrigerant dryer residual stock:Secondary markets in Eastern Europe and Southeast Asia absorb retired refrigerant units, delaying desiccant replacement cycles in price-sensitive industrial segments.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO's alignment with EU GMP standards is compelling domestic API producers to install desiccant dryers for export certification, opening underserved territory for premium system vendors.
- Modular cleanroom architectures:Distributed pharmaceutical production is creating demand for containerized desiccant skids that enable rapid commissioning and scalable redundancy without permanent infrastructure.
- Carbon border adjustment mechanisms:The EU CBAM is incentivizing energy-efficient blower purge designs over heated desiccant systems, rewarding manufacturers with lower carbon intensity in their supply chains.
Industry Challenges
- Adsorption media certification timelines:FDA validation requirements for molecular sieve materials in pharmaceutical applications extend qualification cycles to eighteen to twenty-four months, delaying revenue recognition.
- Legacy pneumatic integration:Retrofitting desiccant dryers into existing compressed air networks requires valve manifold reconfiguration and control system upgrades that disrupt continuous manufacturing operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Desiccant Compressed Air Dryer Market |
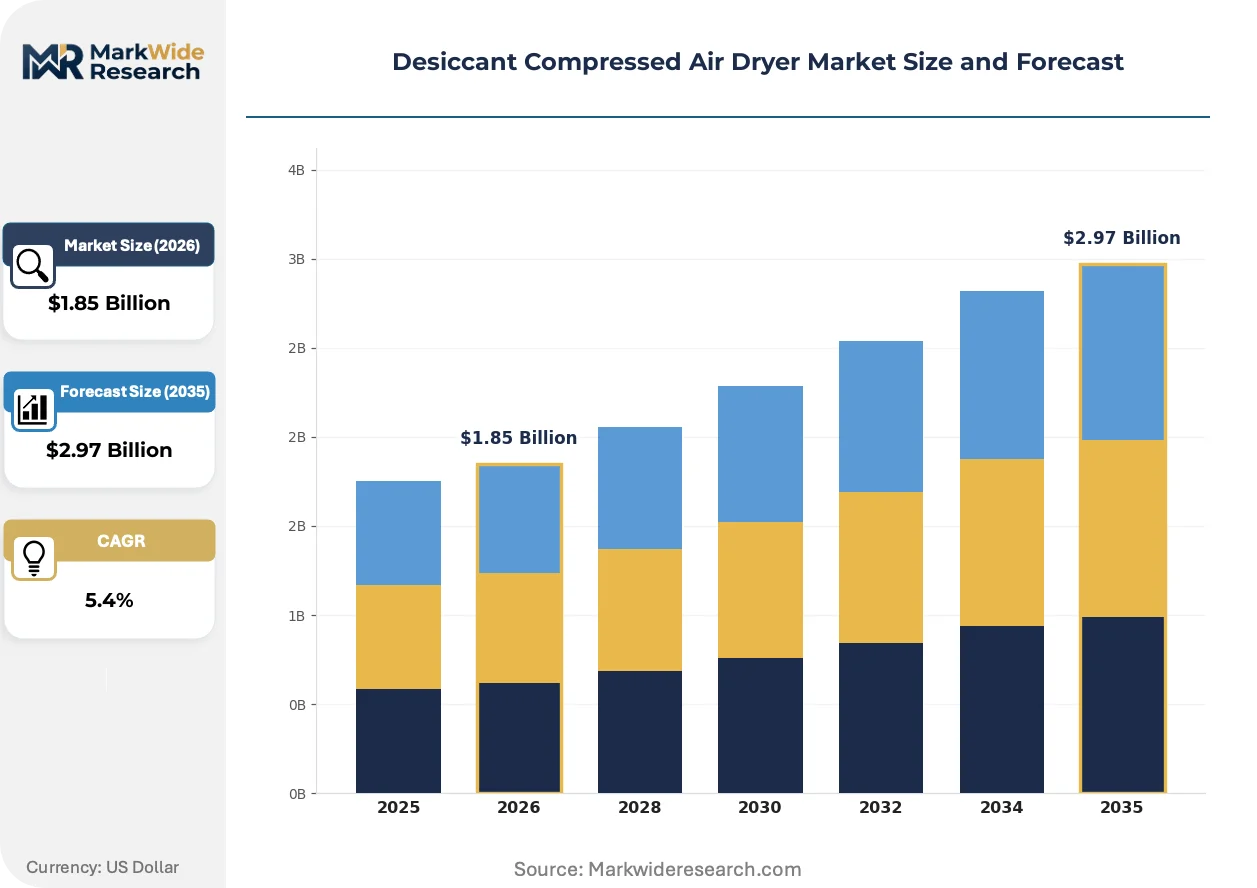
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Dryers, Stationary Dryers, Rigid Dryers, Modular Dryers Technology: Heatless, Heated, Heat Recovery, Blower Purge End User: Manufacturing, Food Processing, Pharmaceuticals, Automotive Application: Moisture Control, Air Quality Improvement, Equipment Protection, Surface Drying |
| Companies Covered | Atlas Copco, Ingersoll Rand, Parker Hannifin, SPX Flow, Kaeser Kompressoren, Gardner Denver, Donaldson Company, SMC Corporation, BEKO Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Desiccant Compressed Air Dryer Market Trends and Innovations
Adsorption technology is bifurcating between premium blower purge architectures and compact heatless designs, with each branch serving distinct operational profiles. This divergence is fragmenting R&D investment and creating specialized supplier ecosystems rather than consolidated full-line competitors.
Rotary drum desiccant systems are bifurcating the market between continuous-duty automotive plants and intermittent-use pharmaceutical operations. Atlas Copco's drum technology eliminates switching valves and reduces purge losses to three to five percent, attracting German automotive paint shops with twenty-four-seven compressed air demand. The technology is bifurcating procurement patterns by compressing the addressable market for traditional twin-tower heatless designs into smaller-scale or capital-constrained installations.
The EPA's National Emission Standards for Hazardous Air Pollutants is constraining oil-lubricated compressor effluent across US manufacturing facilities. This indirect pressure is elevating oil-free air system specifications that require more aggressive moisture control, pushing petrochemical and electronics producers toward desiccant architectures. Food processing facilities in California and Texas are responding fastest, driven by concurrent FDA food safety modernization inspections.
Compressed air service contracting is displacing equipment ownership in European dairy and beverage plants. End-users now specify guaranteed dew point performance rather than capital equipment, transferring operational risk to OEM service arms. This model is concentrating most visibly in the Netherlands and Denmark, where cooperative dairy structures favor operational expenditure over balance-sheet asset ownership.
Desiccant Compressed Air Dryer Market Segmentation
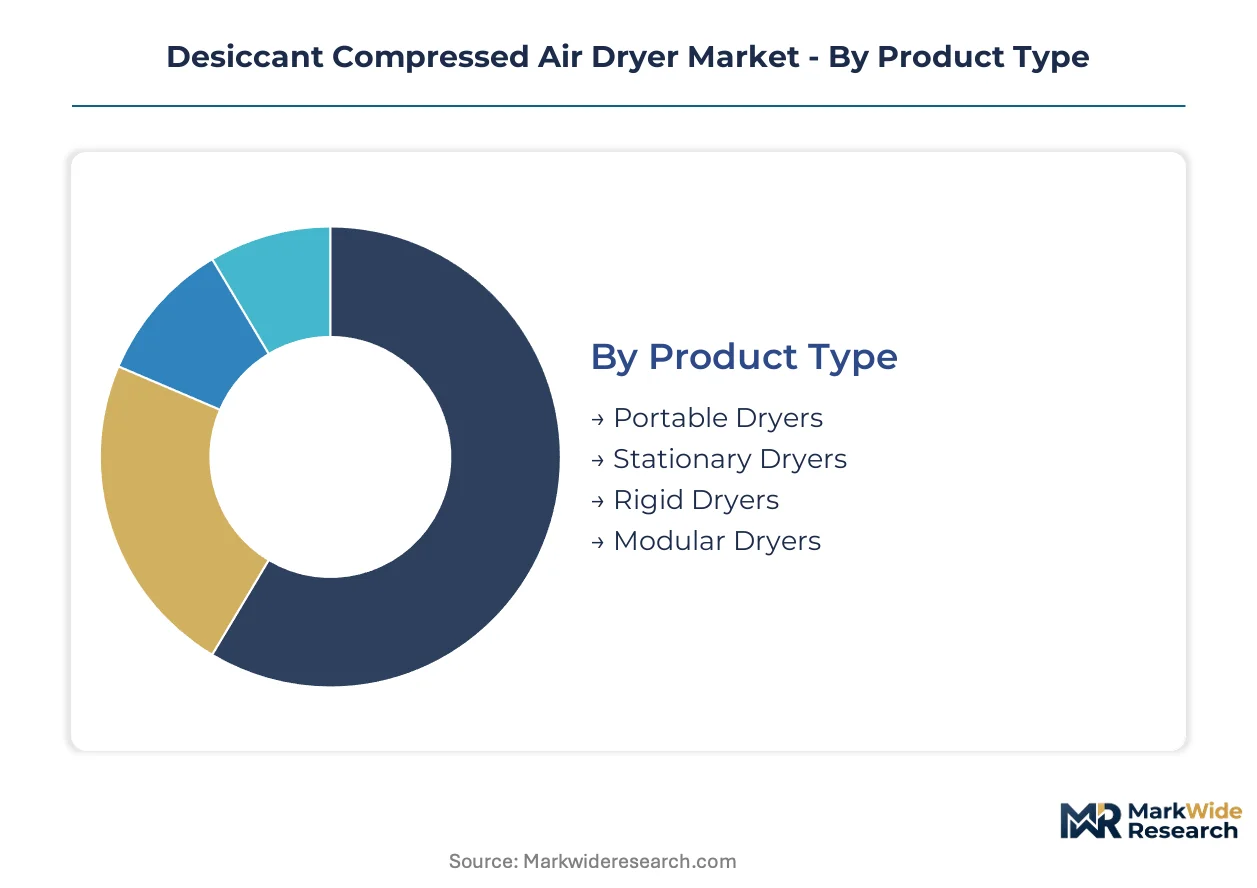
Desiccant dryer procurement patterns diverge sharply across operational contexts, with permanent infrastructure investments competing against modular deployments for capital allocation. Technology selection increasingly hinges on purge efficiency metrics rather than upfront capital, reshaping vendor competitive dynamics.
Product Type:
Portable configurations face the most severe substitution pressure from rental fleets and service contracting models that eliminate ownership entirely.
- Portable Dryers:Compact skid-mounted units deploy rapidly to construction sites and temporary manufacturing setups. Demand clusters in German automotive supplier parks where seasonal production surges require flexible air treatment capacity without permanent infrastructure commitment.
- Stationary Dryers:Fixed installations anchor heavy manufacturing compressed air networks with continuous-duty architectures. German chemical producers along the Rhine corridor specify these for dew points below minus forty degrees Celsius in 24/7 process operations.
- Rigid Dryers:Heavy-duty welded-frame designs withstand corrosive petrochemical environments. Refinery operators in Rotterdam and Antwerp specify rigid housings for offshore platform air systems.
- Modular Dryers:Containerized skids enable scalable redundancy for distributed pharmaceutical cleanrooms. Dutch and Danish dairy cooperatives favor operational expenditure models with guaranteed dew point performance over asset ownership.
Stationary dryers retain volume leadership; modular configurations hold the steepest expansion curve.
Technology:
Capital requirements stratify sharply across thermal regimes, with energy-conscious operators migrating toward architectures that minimize compressed air losses.
- Heatless:Twin-tower designs consume 15-20% of dried air as purge, favoring intermittent-duty applications with lower utilization rates. Small-scale food processors in Italy and Spain select heatless units where capital constraints outweigh lifetime energy costs.
- Heated:External heat sources reduce purge consumption to 6-8%, requiring higher capital outlay for heating elements and controls. Polish and Czech manufacturing clusters specify heated designs for mid-duty cycles where energy costs justify incremental investment.
- Heat Recovery:Regenerative systems capture exhaust thermal energy, cutting fuel consumption in high-throughput environments. Swedish pulp and paper mills deploy heat recovery dryers to meet national carbon intensity targets.
- Blower Purge:External blowers supply regeneration air, slashing purge losses to 2-3% and displacing older heated designs. German automotive paint shops specify blower purge systems under ISO 8573-1 Class 1 requirements for continuous operation.
Heatless technology dominates unit shipments; blower purge architectures are climbing the fastest.
End User:
Regulatory stringency varies dramatically across sectors, with pharmaceutical and food safety mandates forcing specification upgrades that manufacturing and automotive can defer.
- Manufacturing:General industrial applications span metal fabrication to electronics assembly with moderate dew point requirements. French aerospace suppliers specify desiccant systems for precision machining where moisture-induced corrosion threatens tooling accuracy.
- Food Processing:Hygienic design requirements under EU hygiene package directives mandate stainless steel construction and oil-free air certification. Italian pasta and confectionery producers retrofit compressed air networks to meet FSSAI-equivalent export standards for Asian markets.
- Pharmaceuticals:Sterile manufacturing protocols require molecular sieve configurations sustaining minus forty degrees Celsius dew points. Irish and Swiss API producers install redundant desiccant trains to satisfy FDA and EMA validation requirements.
- Automotive:Paint shop networks demand Class 1 air quality per ISO 8573-1 to prevent coating defects. German OEM assembly plants specify blower purge systems with dew point monitoring integrated into plant-wide SCADA architectures.
Manufacturing retains the broadest installed base; pharmaceutical applications are gaining share fastest.
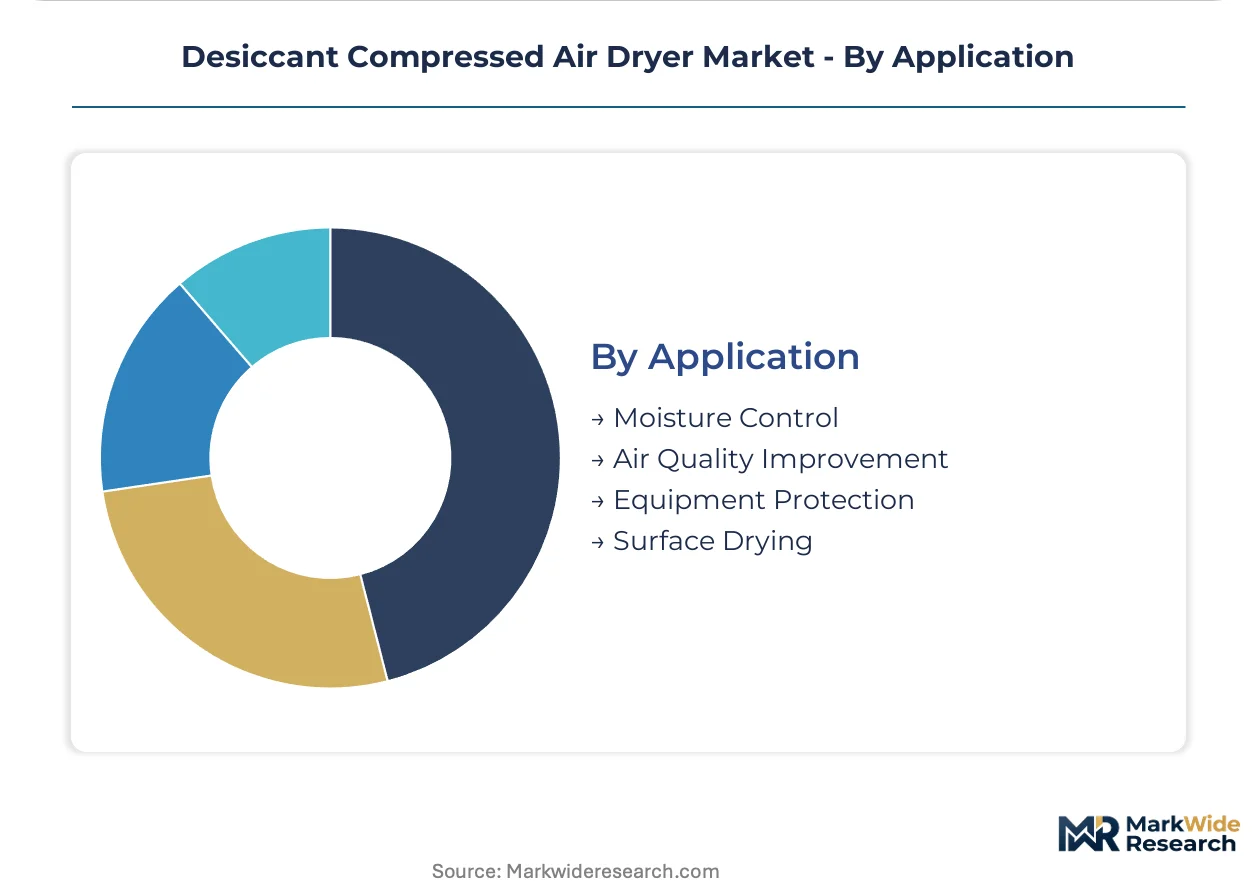
Application:
Functional requirements determine media selection and system architecture, with critical process protection commanding premium specifications over general utility applications.
- Moisture Control:Core desiccant function achieving pressure dew points from minus twenty to minus seventy degrees Celsius. Nordic electronics manufacturers specify activated alumina beds for semiconductor fabrication where moisture-induced defects destroy yield.
- Air Quality Improvement:Particulate and oil vapor removal combined with moisture reduction through integrated filtration. Belgian chocolate producers combine desiccant drying with activated carbon stages to prevent flavor contamination.
- Equipment Protection:Corrosion prevention in pneumatic tools and control systems extends asset life. Austrian woodworking machinery fleets deploy point-of-use desiccant dryers to protect seasonal equipment from humidity damage.
- Surface Drying:Rapid moisture removal from product surfaces in coating and packaging operations. Spanish ceramic tile producers use desiccant-treated air to accelerate glaze setting without thermal energy input.
Moisture control anchors revenue concentration; air quality improvement applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Germany's centrality in European desiccant dryer demand, connecting industrial clusters from Rotterdam to the Black Sea with continuous barge freight for petrochemical and automotive supply chains.
Germany
Automotive paint shops along the Neckar and Rhine valleys specify blower purge systems for ISO 8573-1 Class 1 compliance. The F-Gas Regulation accelerates refrigerant dryer phase-out across Baden-Württemberg manufacturing. Stuttgart's supplier parks anchor the steepest specification upgrades in automotive compressed air networks.
United States
Pharmaceutical API producers in Massachusetts and North Carolina install molecular sieve configurations for FDA sterile manufacturing protocols. The EPA's National Emission Standards constrain oil-lubricated compressor effluent, elevating oil-free system specifications. Houston's petrochemical corridor drives demand for rigid-frame desiccant architectures in corrosive process environments.
India
CDSCO's alignment with EU GMP standards compels domestic pharmaceutical exporters to install desiccant dryers for certification compliance. The PLI scheme for active pharmaceutical ingredients subsidizes capital equipment upgrades. Maharashtra's API manufacturing belt around Mumbai and Pune represents the fastest-expanding installed base in Asia-Pacific.
China
Semiconductor fabrication facilities in the Yangtze River Delta specify activated alumina beds for moisture control in chip manufacturing. MIIT's industrial energy efficiency mandates favor heat recovery desiccant architectures. Shanghai's Pudong Zhangjiang Hi-Tech Park concentrates demand for ultra-low dew point systems in advanced node production.
Switzerland
Swissmedic's pharmaceutical validation requirements extend molecular sieve qualification cycles for sterile manufacturing. The country's precision instrumentation sector demands minus seventy degrees Celsius dew points for metrology applications. Basel's Novartis and Roche supplier ecosystems anchor premium desiccant system specifications.
Desiccant Compressed Air Dryer Market Competitive Landscape
Listed leaders compete with private specialists across technology tiers, with publicly traded OEMs commanding scale advantages in blower purge architectures while family-owned fabricators dominate heatless configurations for capital-constrained segments. The vendor base stratifies into three archetypes: integrated compressor-dryer manufacturers, standalone dryer specialists, and filtration-integrated system providers. Consolidation pressure concentrates among mid-tier heatless producers facing activated alumina cost volatility. Capacity expansion and purge recovery R&D represent the dominant competitive moves across all tiers.
Among European integrated manufacturers, Atlas Copco and Kaeser Kompressoren exemplify divergent strategic positions. Atlas Copco occupies the premium continuous-duty tier through rotary drum technology adoption in German automotive corridors. Kaeser Kompressoren represents captive supply chain integration, with in-house desiccant media production insulating margin structures from bauxite refining volatility. Donaldson Company anchors the filtration-integrated archetype, competing on total cost of ownership metrics against standalone drying units in North American dairy and beverage applications.
| Leading Market Players |
|---|
| Atlas Copco |
| Ingersoll Rand |
| Parker Hannifin |
| SPX Flow |
| Kaeser Kompressoren |
| Gardner Denver |
| Donaldson Company |
| SMC Corporation |
| BEKO Technologies |
| Others |
Pricing and Supply Chain Analysis
ISO 8573-1 air quality classifications simultaneously gate supplier qualification and stratify price tiers across the desiccant dryer market, compressing procurement options for facilities requiring Class 1 certification while expanding margin capture for vendors with validated molecular sieve configurations.
Pricing Analysis
Volume-discount tiering structures separate blower purge premium systems from heatless standard units and modular economy configurations. Price differentiation hinges on ISO 8573-1 certification grade and captive desiccant media production, with Kaeser Kompressoren's backward integration insulating margins from activated alumina volatility. Cost compression in heatless tiers is intensifying because Chinese bauxite refining concentration feeds input instability. Small-scale food processors in Southern Europe exhibit highest price sensitivity, while German automotive OEMs prioritize lifecycle operating cost over capital outlay.
Supply Chain Analysis
China dominates activated alumina production through bauxite refining concentration, while Germany anchors blower purge system assembly and the United States leads molecular sieve certification for pharmaceutical applications. Desiccant media manufacturing rests on Chinese bauxite, German valve engineering, and Swiss precision instrumentation. Single-source vulnerability concentrates in Chinese raw material supply, with Rotterdam-Antwerp petrochemical corridors serving as the primary distribution hub for European heavy industry.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified molecular sieve supply and validated blower purge engineering represent scarce capabilities that concentrate margin capture among incumbent OEMs with captive R&D pipelines, leaving price-competitive heatless segments exposed to commodity input volatility.
For Market Incumbents: Compound certification advantages by accelerating FDA and EMA validation cycles for pharmaceutical-grade molecular sieve configurations before CDSCO mandates tighten in India. Defend margin structures through backward integration into desiccant media production, mirroring Kaeser Kompressoren's captive supply model that insulates against Chinese bauxite price swings. For New Entrants and Emerging Players: Lead with modular containerized architectures targeting India's Maharashtra API belt, where PLI scheme subsidies compress capital barriers for domestic pharmaceutical exporters. Penetrate the underserved heat recovery segment in Nordic pulp and paper applications by partnering with Swedish carbon intensity compliance consultants for rapid technical validation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across blower purge architectures as automotive OEMs specify integrated SCADA monitoring and dew point guarantee contracting. Long-term viability favors targets with validated pharmaceutical certifications and service-contract revenue streams over pure equipment manufacturers. Watch for inflection when EU CBAM carbon border adjustments penalize heated desiccant energy intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Desiccant Media | Kaeser Kompressoren's captive alumina production shields margins from Chinese bauxite volatility. |
| Pharmaceutical Certification Acceleration | FDA and EMA validation cycles for molecular sieve materials compress competitor entry timelines. |
| Modular Cleanroom Architecture Launch | Containerized skids address Dutch and Danish dairy cooperative preference for operational expenditure models. |
| Blower Purge Energy Efficiency Positioning | EU CBAM carbon border adjustments reward lower-carbon intensity drying architectures. |
| Service Contract Revenue Expansion | Guaranteed dew point performance contracts displace equipment ownership in European beverage plants. |
Research Methodology
Cross-validation between primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and pharmaceutical validation specialists anchors the qualitative findings, while secondary sources including SEC filings, customs trade data, and ISO certification registries provide quantitative triangulation. Bottom-up installed base estimates reconcile with top-down industrial compressed air demand projections across the analysis window.
Sensitivity analysis frameworks test forecast robustness against activated alumina price volatility, EU F-Gas Regulation phase-out acceleration, and CDSCO pharmaceutical mandate adoption curves. Segmentation dimensions span technology type, end-use industry, application function, and regional regulatory cluster. CAGRs derive from vintage equipment replacement cycles and greenfield capacity expansion announcements in automotive and pharmaceutical corridors.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or abrupt Chinese export restriction scenarios would require recalibration. Forecasts reflect assumptions on pharmaceutical cleanroom buildout rates and automotive paint shop specification upgrades. Recalibration cycles align with material shifts in F-Gas Regulation implementation timelines and carbon border adjustment mechanism scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Automotive Compressors Market
Compressors
Asia-Pacific Centrifugal Compressor Market
Compressors
Positive-Displacement Hydrogen Compressor Market
Compressors
Industrial Air Compressor Market
Compressors
North America Centrifugal Compressor Market
Compressors
Hydrogen Compressor Market
Compressors
Chlorine Compressors Market
Compressors
Positive Displacement Gas Compressor Market
Compressors
Process Gas Compressors Market
Compressors
Asia-Pacific Compressor Oil Market
Compressors
Russia Reciprocating Compressor Market
Compressors
Stationary Air Compressor Market
Compressors
Rotary Air Compressor Market
Compressors
Compressor Rental Market
Compressors
Gas Compressors Market
Compressors
Compressed Air Lubricators Market