
 Laser Indirect Ophthalmoscope Market | 2026-2036
Laser Indirect Ophthalmoscope Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Indirect Ophthalmoscope Market Foresight
Germany is tilting toward expanded ophthalmic laser manufacturing capacity as Carl Zeiss Meditec AG leverages its precision optics heritage to dominate European supply chains. Lumenis Ltd anchors its position through sustained R&D intensity in solid-state laser platforms for posterior segment surgery. NIDEK Co., Ltd competes by controlling distribution networks across Asian ophthalmology clinics, while Ellex Medical Lasers Ltd specializes in compact diode architectures for emerging markets.
A laser indirect ophthalmoscope projects an intense, coherent light beam through a condensing lens to illuminate and treat the peripheral retina during dilated fundus examination, typically operating at wavelengths between 532 nm and 810 nm with adjustable spot sizes from 50 to 500 microns for precise photocoagulation. The device enables real-time visualization and laser delivery without corneal contact, serving as the standard tool for panretinal photocoagulation in proliferative diabetic retinopathy. Handheld configurations now lead volume shipments among product types due to their utility in operating room and bedside settings, while optical coherence tomography integration represents the fastest-growing technology segment as clinicians demand multimodal diagnostic-therapeutic platforms. Ophthalmology clinics command the largest end-user margin pool because their high procedure throughput justifies premium equipment investments.
The FDA enforces 21 CFR 1040 laser performance standards for ophthalmic devices, while the EU Medical Device Regulation requires notified body certification under Class IIa rules for retinal laser systems. ISO 10993 biocompatibility testing and IEC 60601-1 electrical safety standards further shape product development timelines and market access costs. Stakeholders must monitor evolving reimbursement coding for office-based laser procedures against hospital outpatient department payment differentials.
Market Dynamics
The FDA's tightened 21 CFR 1040 laser performance standards are compressing product development timelines while Medicare reimbursement coding revisions are redirecting capital equipment flows toward outpatient settings.
Growth Catalysts
- Diabetic retinopathy prevalence:Hospital-based ophthalmology departments are scaling laser photocoagulation capacity to manage proliferative diabetic retinopathy caseloads.
- EU Medical Device Regulation:Class IIa certification requirements for retinal laser systems are accelerating quality upgrades across European supply chains.
- Handheld device portability:Operating room and bedside utility is expanding addressable procedure volumes beyond traditional clinic settings.
Market Restraints
- Premium component costs:Precision optics and solid-state laser diodes concentrate supply among German and Japanese specialty manufacturers.
- Technical wavelength limitations:Current 532-810 nm operating ranges restrict treatment efficacy for certain peripheral retinal pathologies.
- Regulatory friction:FDA premarket submission requirements for modified laser devices extend commercialization timelines.
Strategic Opportunities
- Optical coherence tomography convergence:Multimodal diagnostic-therapeutic platforms are creating premium equipment categories.
- Asian clinic networks:Distribution control across ophthalmology clinics in Japan and South Korea offers volume expansion potential.
- Compact diode architectures:Emerging market price sensitivity is rewarding simplified device configurations.
Industry Challenges
- Biocompatibility certification timelines:ISO 10993 testing protocols delay market access for redesigned laser delivery systems.
- Electrical safety compliance:IEC 60601-1 standards revisions require engineering resource reallocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Indirect Ophthalmoscope Market |
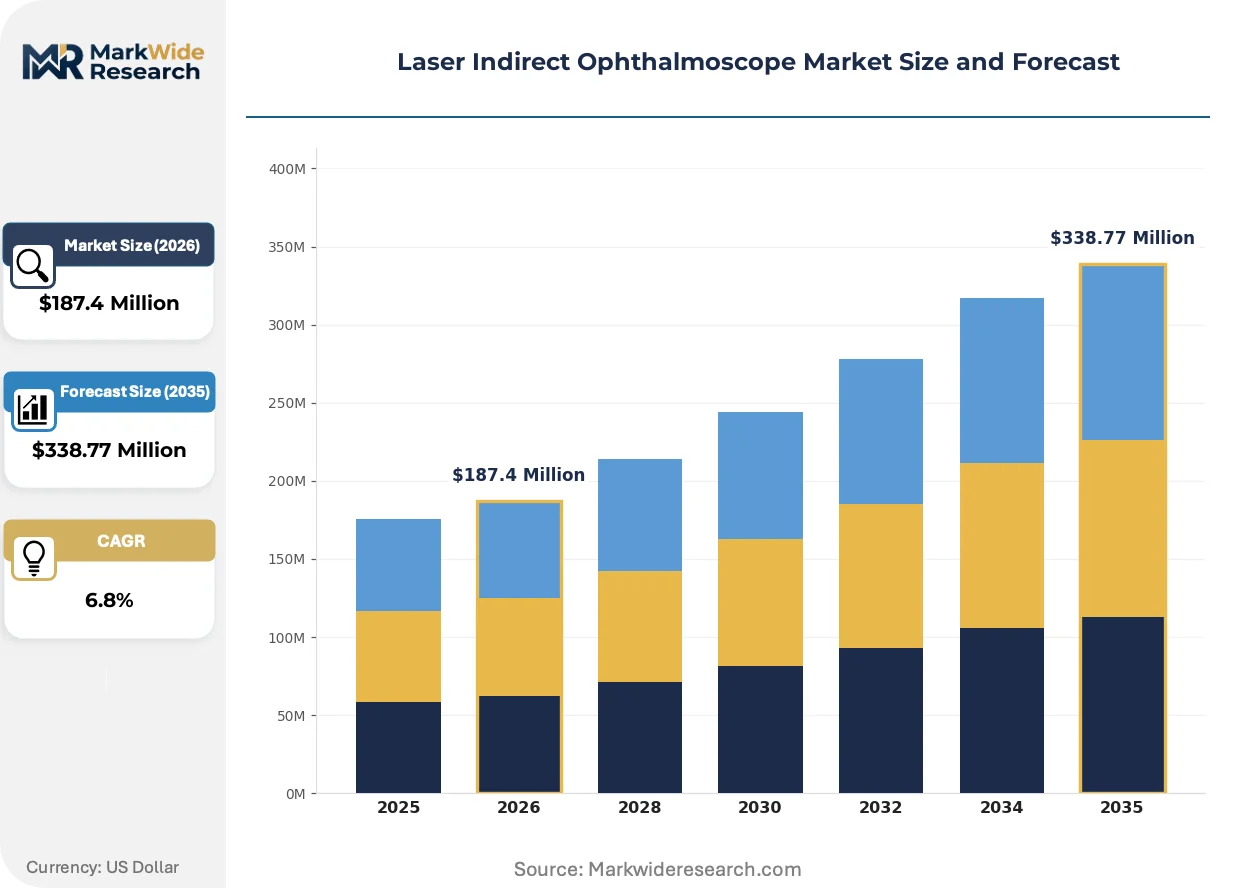
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Desk-mounted, Portable, Adaptive Technology: Fluorescein Angiography, Optical Coherence Tomography, Digital Imaging, Non-invasive End User: Ophthalmology Clinics, Hospitals, Research Laboratories, Eye Care Centers Application: Diabetic Retinopathy, Glaucoma, Retinal Detachment, Macular Degeneration |
| Companies Covered | Carl Zeiss Meditec AG, Lumenis Ltd, Topcon Corporation, IRIDEX Corporation, NIDEK Co., Ltd, Ellex Medical Lasers Ltd, Keeler Ltd, Optos plc, Heidelberg Engineering GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Indirect Ophthalmoscope Market Shifts & Advancements
Device architecture is pivoting toward integration-heavy platforms while regulatory stringency and procurement centralization reshape competitive requirements.
Multimodal platforms combining laser indirect ophthalmoscopy with spectral-domain optical coherence tomography are virtualizing standalone diagnostic workflows. Ophthalmology clinics with high procedure throughput are adopting these integrated systems fastest. The technology is virtualizing separate capital equipment purchases into single-platform investments.
The EU Medical Device Regulation's Class IIa rules for retinal laser systems are tightening notified body certification requirements. Manufacturers must demonstrate clinical equivalence under stricter technical documentation standards. European supply chains are responding by consolidating quality management systems.
Hospital outpatient departments are unbundling after-sales service contracts from equipment purchases. Third-party service providers are displacing manufacturer captive service networks. This pattern is most visible in United States Medicare reimbursement zones where capital budget scrutiny intensifies.
Laser Indirect Ophthalmoscope Market Segmentation
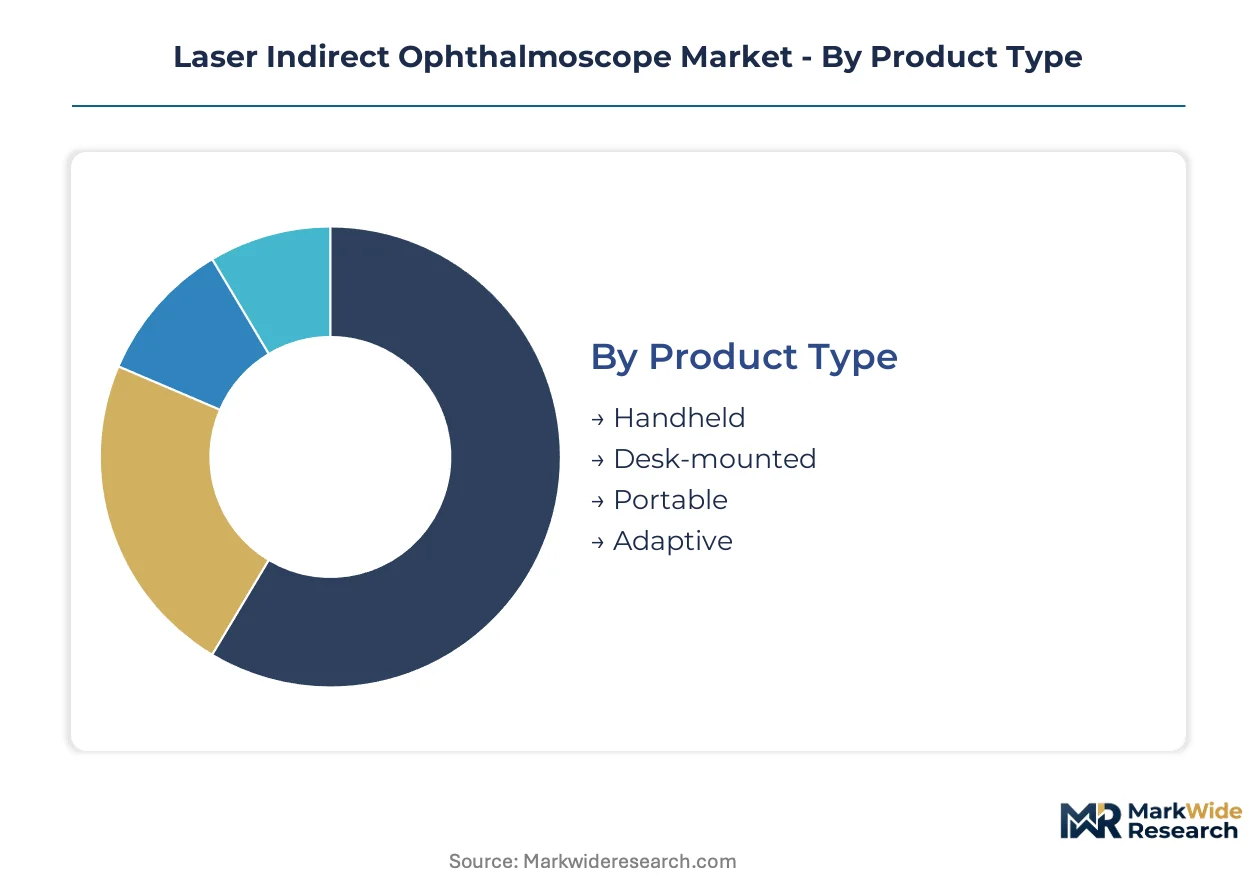
Device configuration and imaging modality choices determine capital expenditure patterns across ophthalmology settings. Segmentation reveals where service contract bundling concentrates and which technology integrations command premium positioning.
Product Type:
After-sales-service intensity varies sharply across physical configurations, with handheld units requiring frequent calibration support while desk-mounted systems demand scheduled optical alignment protocols.
- Handheld:Battery-powered units with integrated diode lasers and wireless connectivity enable bedside and operating room deployment without fixed infrastructure. Ophthalmology clinics in the United States prioritize these for high-throughput diabetic retinopathy screening programs where mobility between examination lanes accelerates patient flow.
- Desk-mounted:Stationary configurations with stabilized optical benches and integrated slit lamp interfaces deliver superior beam stability for complex posterior segment procedures. Hospital outpatient departments in Germany specify these for panretinal photocoagulation suites where procedure volume justifies dedicated installation.
- Portable:Compact cart-based systems with collapsible delivery arms balance mobility with optical performance for multi-site deployment.
- Adaptive:Modular platforms with swappable laser sources and upgradeable control electronics extend equipment lifecycle through field reconfiguration.
Handheld configurations hold the largest share; momentum sits with adaptive architectures.
Technology:
Cost tier stratification separates integrated diagnostic platforms from standalone therapeutic devices, with multimodal systems commanding three to five times the capital outlay of single-function units.
- Optical Coherence Tomography:Spectral-domain engines combined with laser delivery enable real-time cross-sectional guidance during photocoagulation. Asian ophthalmology clinics in Japan and South Korea adopt these fastest for macular pathology management where precise depth targeting improves outcomes.
- Fluorescein Angiography:Sodium fluorescein excitation modules with barrier filter sets support leakage pattern identification prior to laser application. Research laboratories in the United States deploy these for clinical trial endpoints requiring standardized documentation.
- Digital Imaging:High-resolution sensors with automated fundus mapping streamline documentation workflows for high-volume screening programs.
- Non-invasive:Confocal scanning approaches without exogenous dye administration reduce adverse event liability for routine monitoring applications.
Digital imaging commands current installed base; optical coherence tomography integration is climbing the fastest.
End User:
Volume concentration determines procurement sophistication, with high-throughput settings negotiating enterprise pricing while smaller purchasers accept list pricing with extended payment terms.
- Ophthalmology Clinics:Specialized facilities with dedicated retinal services generate procedure volumes that amortize premium equipment investments within compressed payback periods. Clinics in Medicare reimbursement zones leverage outpatient procedure coding to justify capital allocations for laser photocoagulation capacity expansion.
- Hospitals:Integrated health systems with ophthalmology departments consolidate purchasing across multiple sites to extract volume discounts from manufacturers. German hospital networks particularly emphasize this approach under centralized procurement frameworks.
- Research Laboratories:Academic medical centers with NIH or EU Horizon funding prioritize investigational device configurations for protocol-specific requirements.
- Eye Care Centers:Community-based facilities with mixed optometry-ophthalmology staffing select simplified interfaces for cross-disciplinary utilization.
Ophthalmology clinics hold the largest share; hospitals are gaining share fastest through consolidation.
Application:
Clinical indication severity shapes wavelength and spot size specifications, with proliferative conditions demanding broader treatment fields than focal pathologies.
- Diabetic Retinopathy:Panretinal photocoagulation for proliferative disease requires adjustable spot sizes from 200 to 500 microns with 532 nm or 577 nm wavelength selection. United States hospital outpatient departments scale this capacity fastest given Medicare reimbursement alignment with disease prevalence trends.
- Macular Degeneration:Subthreshold laser protocols with precise thermal dosing demand integrated real-time temperature monitoring and automated endpoint detection.
- Glaucoma:Transscleral diode applications for refractory cases utilize longer 810 nm wavelengths with specialized goniolens delivery systems.
- Retinal Detachment:Perfluorocarbon-assisted drainage with intraoperative laser retinopexy requires sterile draping compatibility and foot pedal ergonomics for surgical suite integration.
Diabetic retinopathy holds the largest share; macular degeneration applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision optics manufacturers concentrate supply for laser delivery components, while reimbursement policy divergence across national health systems fragments demand patterns for capital equipment procurement.
United States
Medicare reimbursement codes for outpatient retinal procedures steer hospital purchasing decisions toward laser photocoagulation capacity expansion. FDA 21 CFR 1040 laser performance standards compress product development timelines for device manufacturers. The Boston-Cambridge medical technology cluster hosts concentrated R&D activity for multimodal diagnostic-therapeutic platforms.
Germany
Hospital procurement centralization under regional health network frameworks extracts volume discounts from equipment suppliers. EU Medical Device Regulation Class IIa certification requirements accelerate quality management system upgrades across manufacturing facilities. The Jena-Heidelberg precision optics corridor anchors European supply chain concentration for solid-state laser components.
Japan
Aging demographics elevate diabetic retinopathy screening program scale-up as a national health priority. PMDA medical device review pathways shape commercialization timelines for modified laser systems. The Tokyo-Osaka ophthalmology clinic corridor generates concentrated procedure volumes justifying premium equipment investments.
China
Expanding tier-two hospital ophthalmology departments drive demand for cost-optimized diode laser configurations. NMPA medical device registration requirements extend market access timelines for imported retinal laser systems. The Yangtze River Delta manufacturing basin hosts emerging domestic assembly capacity for compact handheld units.
South Korea
High-volume ophthalmology clinic chains prioritize optical coherence tomography integration for competitive differentiation. MFDS medical device quality management standards align with EU MDR technical documentation requirements. The Seoul Capital Area concentrates domestic demand for multimodal diagnostic-therapeutic platforms.
Laser Indirect Ophthalmoscope Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying precision optics and solid-state laser diodes. Market structure consolidates around three to five full-system manufacturers while fragmenting across upstream material suppliers. Two strategic archetypes dominate: diversified medical technology conglomerates leveraging cross-divisional R&D scale, and focused ophthalmic laser specialists defending niche positions through application-specific expertise. Competitive moves concentrate on technology licensing partnerships for multimodal platform integration and geographic distribution network expansion into Asian clinic markets.
Among Germany-based precision optics conglomerates, Carl Zeiss Meditec AG occupies a position exemplifying heritage-driven vertical control over optical component supply. Israeli laser platform specialists Lumenis Ltd and Japanese ophthalmic equipment manufacturers NIDEK Co., Ltd represent contrasting archetypes of R&D-intensive solid-state development versus distribution network control across Asian markets. Ellex Medical Lasers Ltd, an Australia-based laser device specialist, sits within the compact architecture tier serving emerging market price sensitivity.
| Leading Market Players |
|---|
| Carl Zeiss Meditec AG |
| Lumenis Ltd |
| Topcon Corporation |
| IRIDEX Corporation |
| NIDEK Co., Ltd |
| Ellex Medical Lasers Ltd |
| Keeler Ltd |
| Optos plc |
| Heidelberg Engineering GmbH |
| Others |
Supply & Pricing Matrix
Single-source dependency on Japanese solid-state laser diode manufacturers compresses margin structures for mid-tier equipment producers while simultaneously widening the premium-to-economy price spread across ophthalmology clinics and hospital outpatient departments. This concentration dynamic forces buyers into either captive supply relationships with German precision optics houses or simplified diode architectures sourced from emerging Asian assembly basins.
Pricing Analysis
FDA 21 CFR 1040 laser performance standards dictate the pricing tier structure by imposing differential compliance burdens across certification grades. Three-tier pricing structure across premium, standard, and economy levels segments by ISO 10993 biocompatibility tier and after-sales service bundling intensity. Cost compression in the economy tier is intensifying because Chinese domestic manufacturers are flooding tier-two hospital procurement channels with handheld units lacking full FDA equivalence. Ophthalmology clinics in Medicare reimbursement zones show least price sensitivity due to compressed capital payback periods, while community eye care centers in emerging markets exhibit highest elasticity.
Supply Chain Analysis
Precision-grade optical feedstock draws from German specialty glass manufacturers, Japanese laser diode foundries, and Taiwanese optical coating operations. Solid-state gain media, condensing lens assemblies, and spectral filter sets constitute the critical component triad. Single-source vulnerability concentrates in 810 nm diode emitters where two Japanese suppliers control qualified ophthalmic-grade output. Distribution runs through manufacturer-direct hospital contracts in developed markets and distributor-mediated clinic networks across Asia-Pacific.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as optical coherence tomography convergence forces standalone laser manufacturers into interoperability partnerships or obsolescence. The ecosystem shift toward multimodal diagnostic-therapeutic integration redefines viable scale thresholds for capital equipment suppliers.
For Market Incumbents: Pre-empt component supply disruption by securing long-term offtake agreements with Jena-Heidelberg precision optics houses or qualifying secondary diode sources through accelerated FDA 510(k) pathways. Defend installed base stickiness through software companion development for OCT-guided photocoagulation protocols, neutralizing emerging Asian competitors with hardware-only positioning. Channel control through GPO contracts at consolidated US hospital systems remains the critical defensive lever against price erosion. For New Entrants and Emerging Players: Establish a beachhead in compact handheld configurations for Chinese tier-two hospital ophthalmology departments where NMPA registration timelines favor domestic assembly over imported systems. The most penetrable white space sits in subthreshold laser protocols for early-stage macular degeneration, where real-time temperature monitoring capabilities remain underdeveloped outside premium European platforms. A go-to-market angle through third-party service contract displacement—unbundling maintenance from equipment purchase—aligns with US outpatient department procurement centralization trends. For Investors and Strategic Acquirers: EU Medical Device Regulation Class IIa implementation reshapes the acquisition landscape by elevating quality management system maturity to primary diligence criterion. Long-term viability centers on targets with notified body-certified technical documentation libraries and established European distribution infrastructure. The acquisition target archetype is mid-scale ophthalmic laser specialists with captive OCT integration pipelines but constrained Asian market access. Watch FDA premarket submission backlogs as the signal for competitive timing windows.| Strategic Initiative | Industry Significance |
|---|---|
| OCT Platform Integration | Multimodal convergence virtualizes separate capital purchases into single-platform investments for high-throughput clinics. |
| CE Marking Pathway Acceleration | EU MDR Class IIa certification compresses commercialization timelines for redesigned laser delivery systems. |
| Hospital System Partnership | Medicare reimbursement alignment with US outpatient procedure coding steers consolidated purchasing decisions. |
| Software Companion Development | Real-time guidance algorithms for subthreshold dosing differentiate premium tiers from hardware-commoditized competitors. |
| Reimbursement Strategy | CPT code capture for office-based laser procedures against HOPD payment differentials determines capital budget flows. |
Research Methodology
A spread of perspectives from retinal surgeons, hospital purchasing committee chairs, biomedical engineers at GPOs, and regulatory affairs leads at laser device manufacturers converged on the working assumptions. Primary interviews across these stakeholder categories were cross-referenced against FDA 510(k) premarket notification databases, CMS Medicare reimbursement coding archives, EU notified body certification registries, and Japanese PMDA medical device approval records. Bottom-up procedure volume estimates from ophthalmology clinics and hospital outpatient departments were reconciled with top-down capital equipment shipment data through iterative triangulation.
Demand-supply balance dynamics across the analysis window were modeled through segmented adoption curves for handheld versus desk-mounted configurations, technology integration intensity, and end-user procurement sophistication. The projection framework incorporated product type, imaging modality, application severity, and regional regulatory cluster as core segmentation dimensions. CAGRs were derived from fitted S-curve penetration models calibrated to historical equipment replacement cycles and reimbursement policy inflection points. Forecast inputs included diabetic retinopathy prevalence trajectories, EU MDR implementation compliance costs, and Medicare outpatient procedure volume trends.
Stress conditions across FDA premarket review duration, Japanese diode supply disruption scenarios, and Chinese domestic manufacturing scale-up rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about reimbursement stability and regulatory equivalence recognition between jurisdictions. Cross-checking against hospital capital budget disclosure patterns in SEC 10-K filings of consolidated health systems is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Europe Ophthalmology Market
Ophthalmology
Vision Care Market
Ophthalmology
Ocular Hypertension Treatment Market
Ophthalmology
Global Ophthalmic Knives Market
Ophthalmology
Ophthalmic Ultrasound Systems Market
Ophthalmology
Orthokeratology Market
Ophthalmology
Conjunctivitis Market
Ophthalmology
Global Ophthalmic Viscoelastic Devices Market
Ophthalmology
Macular Edema and Macular Degeneration Market
Ophthalmology
Fungal Eye Infection Market
Ophthalmology
Age-Related Macular Degeneration Market
Ophthalmology
Ophthalmic Suspension Market
Ophthalmology
Diabetes Associated Ophthalmic Treatment Market
Ophthalmology
Keratoconus Treatment Market
Ophthalmology
Global Aphakia Market
Ophthalmology
Retinal Detachment Diagnostic Market