
 USA Automotive and Aircraft Interior Genuine Leather Aftermarket Market | 2026-2036
USA Automotive and Aircraft Interior Genuine Leather Aftermarket Market Size, Share, and Industry Trends Forecast 2026-2036
USA Automotive and Aircraft Interior Genuine Leather Aftermarket Market Analytics
Artisan leatherworking talent is bifurcating between heritage hand-craft methods and digital cutting automation, constraining throughput for premium restoration shops while unlocking scalable production for mid-tier suppliers. Lear Corporation leverages captive tanning partnerships to sustain consistent hide quality across automotive seat programs. WOLLSDORF LEDER SCHMIDT & Co. Ges.m.b.H anchors European hide sourcing networks that extend into U.S. aircraft upholstery channels. Katzkin Leather, Inc. dominates direct-to-consumer replacement seat kit distribution through dealership and installer networks.
The USA Automotive and Aircraft Interior Genuine Leather Aftermarket comprises replacement and refurbishment of full-grain, top-grain, and corrected-grain leather components for vehicle and aircraft cabins, typically tanned with chromium salts or vegetable extracts to achieve durability ratings exceeding 100,000 double rubs under ASTM D4157. These materials restore aesthetic and functional cabin integrity when OEM surfaces degrade from UV exposure, abrasion, or aging. Leather seats for luxury vehicles and motorhomes occupy the largest margin pool due to high per-unit value and customization intensity, while trim kits distributed through specialty stores represent the fastest-growing channel as DIY restoration participation rises. Commercial aircraft upholstery competes on FAA burn-certification compliance, creating a narrower supplier base than automotive segments.
FAA Technical Standard Order C25b governs aircraft interior material flammability, while EPA effluent guidelines under the Clean Water Act constrain tannery discharge in Kentucky and Tennessee processing hubs. NHTSA Federal Motor Vehicle Safety Standard 302 shapes automotive leather burn-performance requirements that aftermarket suppliers must mirror for street-legal installations. Stakeholders must monitor how California Air Resources Board amendments to volatile organic compound rules for adhesive systems reshape manufacturing location decisions and supplier qualification timelines.
Market Dynamics
California's Proposition 65 enforcement on chromium VI in leather finishing is elevating compliance costs for tanneries serving aftermarket suppliers, compressing margins for small-batch restoration shops while favoring scaled operators with captive chemistry controls.
Growth Catalysts
- FAA Technical Standard Order C25b:Aircraft interior material flammability mandates sustain demand for certified leather upholstery among commercial aviation refurbishment clusters in Texas and Florida.
- UV degradation patterns in Sun Belt states:Accelerated leather aging from solar exposure drives replacement cycles for luxury vehicle and motorhome cabins across Arizona, Nevada, and Southern California.
- Vegetable tanning revival:Chrome-free processing methods attract environmentally conscious collectors restoring classic automobiles, opening premium price tiers for heritage tanneries.
Market Restraints
- Hide supply concentration:North American steerhide availability fluctuates with cattle cycle conditions in Texas and Nebraska, creating input cost volatility for chromium-tanned automotive grades.
- Substitution by synthetic microfiber:Alcantara and polyurethane alternatives capture mid-tier aircraft seat refurbishment contracts where FAA burn-certification costs outweigh leather's aesthetic premium.
- EPA effluent guidelines:Clean Water Act constraints on tannery discharge in Kentucky and Tennessee processing hubs limit capacity expansion for suppliers serving aftermarket channels.
Strategic Opportunities
- Southeast restoration corridor:Classic car collector density across Georgia, Alabama, and the Carolinas remains underserved by premium hand-craft upholstery specialists.
- Digital cutting automation:CNC patterning technology converges with cloud-based vehicle interior databases to enable made-to-order seat kit production without dealer network intermediaries.
- California Air Resources Board VOC amendments:Stricter adhesive system rules create qualification barriers that favor early-compliant suppliers with in-house bonding capabilities.
Industry Challenges
- Artisan leatherworking bifurcation:Heritage hand-craft methods and digital cutting automation require divergent skill sets, constraining workforce flexibility for restoration shops seeking throughput scaling.
- FAA burn-certification timeline compression:Commercial aircraft upholstery approval cycles extend supplier qualification periods, freezing out smaller tanneries from aviation aftermarket participation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USA Automotive and Aircraft Interior Genuine Leather Aftermarket Market |
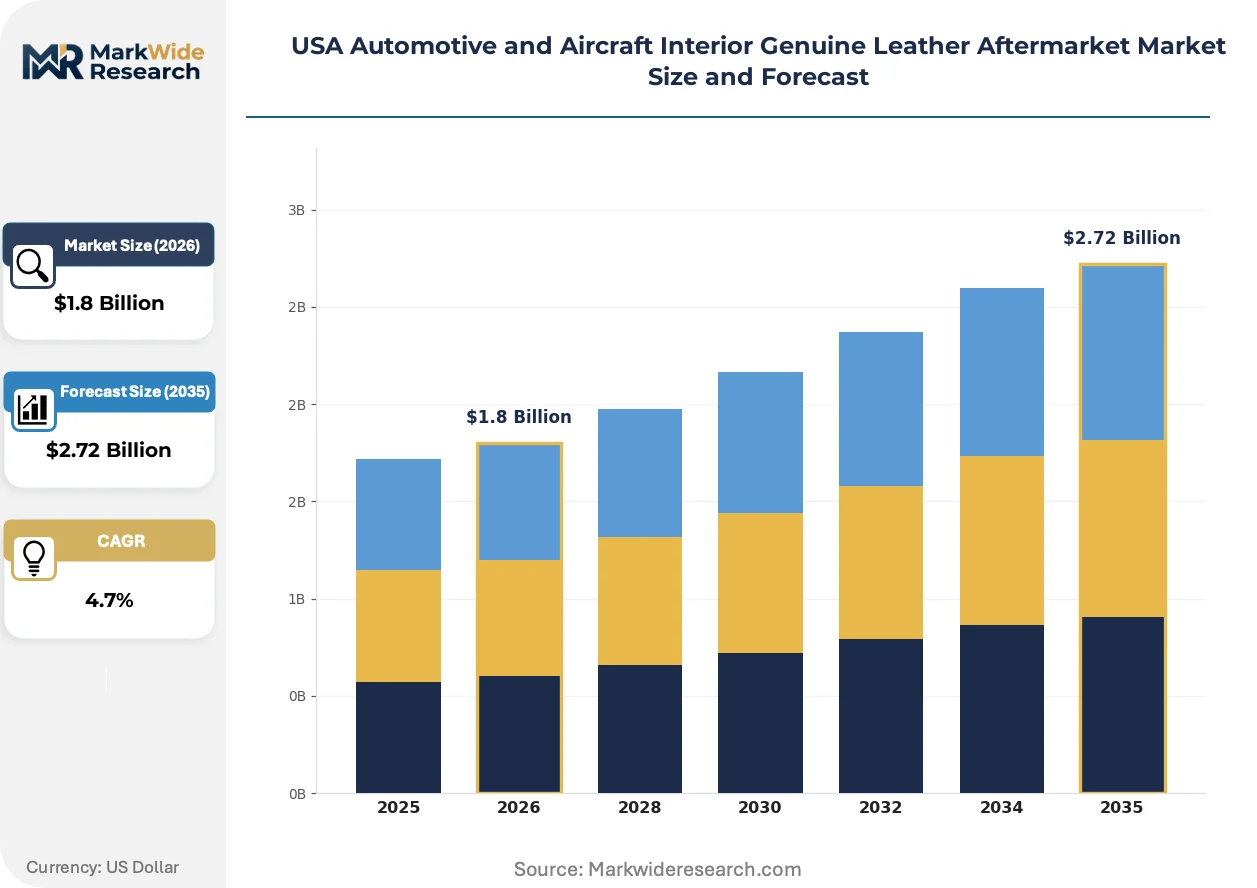
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Leather Seats, Upholstery, Steering Covers, Trim Kits Application: Luxury Vehicles, Commercial Aircraft, Motorhomes, Boats Distribution Channel: Online Retailers, Specialty Stores, Dealerships, Trade Shows End User: Vehicle Owners, Fleet Operators, Upholsterers, Aviation Enthusiasts |
| Companies Covered | Lear Corporation, WOLLSDORF LEDER SCHMIDT & Co. Ges.m.b.H, Bader GmbH & Co. KG, Leather Resource Of America Inc., Katzkin Leather, Inc., Hydes Leather, Carroll Leather, Townsend Leather Company, Inc., Spectra Interior Products, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USA Automotive and Aircraft Interior Genuine Leather Aftermarket Market Evolving Landscape
Leather finishing chemistry and pattern digitization are reshaping how aftermarket suppliers balance customization depth against production velocity. These shifts are compressing the traditional trade-off between artisan quality and scalable output.
Water-based polyurethane topcoat systems are fragmenting the dominance of solvent-borne finishes in automotive leather restoration. Custom shops in Dallas-Fort Worth and Miami-Opa Locka are adopting these low-VOC alternatives to preempt California market exclusion. The technology is fragmenting supplier tiers—large tanneries with R&D capacity capture OEM-adjacent contracts while smaller finishers lose access to coastal distribution channels.
NHTSA Federal Motor Vehicle Safety Standard 302 shapes automotive leather burn-performance requirements that aftermarket suppliers must mirror for street-legal installations. The regulation's test protocols—horizontal burn rate measurement—favor heavier, full-grain hides over corrected-grain alternatives. Suppliers serving the motorhome segment in Indiana and Ohio manufacturing corridors are reformulating foam substrates to compensate, preserving leather surface integrity while meeting flame-spread thresholds.
Collector preference for period-correct materials is rotating demand toward heritage tannage methods. Enthusiasts restoring pre-1970s American muscle cars now specify vegetable-tanned hides processed in traditional oak bark liquors, rejecting chrome-tanned uniformity. This pattern concentrates procurement through specialty distributors in Pennsylvania and Wisconsin who maintain relationships with surviving European heritage tanneries, bypassing mainstream automotive leather supply chains entirely.
USA Automotive and Aircraft Interior Genuine Leather Aftermarket Market Segmentation
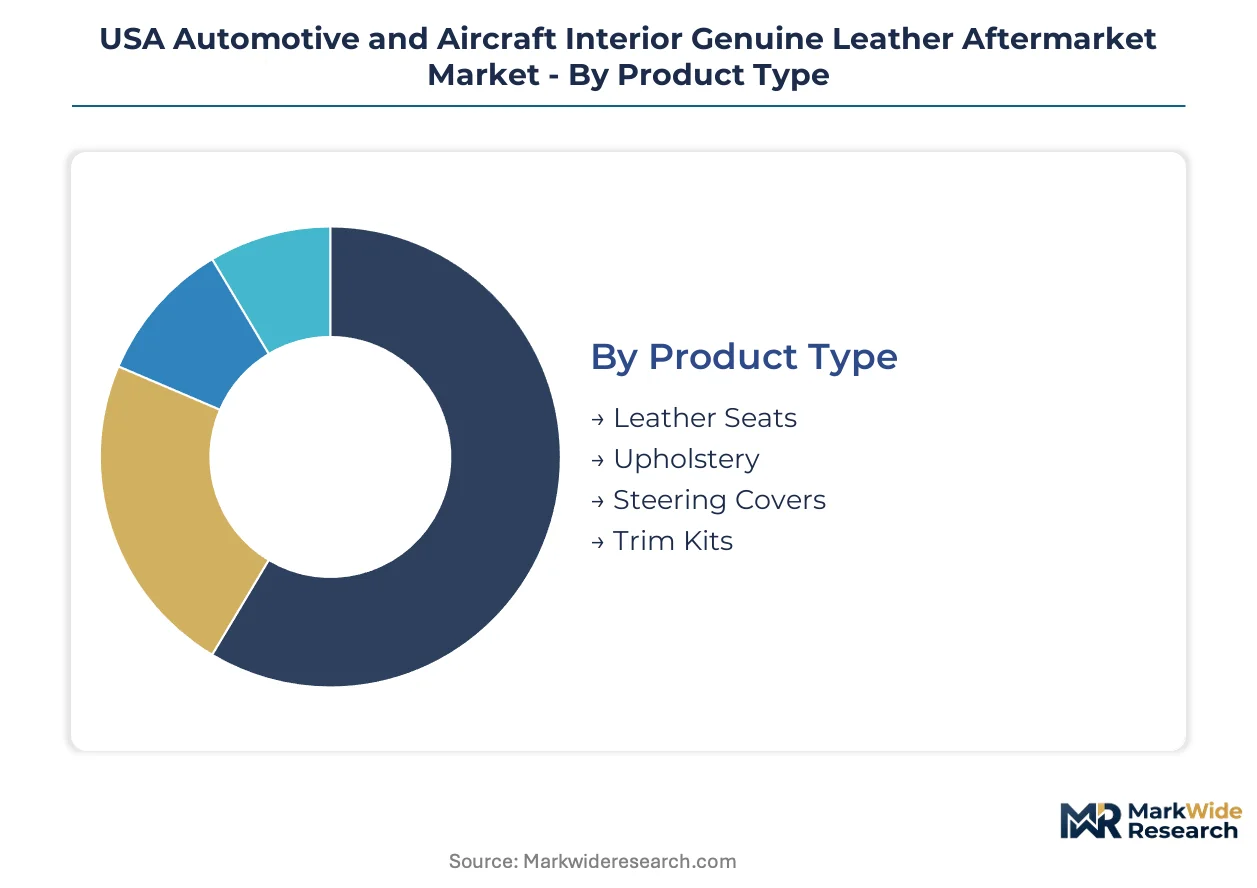
Segmentation in the USA leather aftermarket reveals distinct procurement patterns across vehicle types and buyer sophistication. Restoration specialists, aviation refurbishment clusters, and DIY consumers each access materials through separate channel structures with incompatible service expectations.
Product Type:
Domestic demand concentrates in seat replacement and trim restoration, while specialty upholstery exports serve Caribbean and Latin American aircraft maintenance bases.
- Leather Seats:Full-grain and top-grain hides dominate luxury vehicle and motorhome cabin restoration in Texas and Florida. UV degradation cycles in Sun Belt states compress replacement intervals for seat surfaces exposed through panoramic roof configurations.
- Upholstery:Aircraft seat covers and interior panels require FAA Technical Standard Order C25b burn-certification, narrowing qualified suppliers to tanneries with dedicated aviation testing protocols. Miami-Opa Locka and Dallas-Fort Worth refurbishment clusters source exclusively from these certified channels.
- Steering Covers:Aftermarket wraps in corrected-grain leather serve aging vehicle fleets in Rust Belt states where full interior restoration is uneconomical.
- Trim Kits:Pre-cut door panel and dashboard coverings flow through online retailers to DIY restorers across the Southeast collector corridor.
Leather seats command the established base. The steepest expansion runs through trim kits.
Application:
Cost tier stratification separates chrome-tanned volume production from vegetable-tanned heritage premiums demanded by restoration purists.
- Luxury Vehicles:Mercedes-Benz, BMW, and Lexus owners in California and Arizona drive demand for OEM-matching full-grain replacements. Proposition 65 compliance on chromium VI finishing elevates tannery qualification thresholds for suppliers serving this segment.
- Commercial Aircraft:Regional jet and business aviation refurbishment in Florida and Texas sustains demand for certified leather meeting FAA flammability mandates. Burn-testing costs exclude smaller tanneries from aviation aftermarket participation.
- Motorhomes:Indiana and Ohio manufacturing corridors generate replacement demand for heavy-duty seat coverings rated beyond 100,000 double rubs under ASTM D4157.
- Boats:Marine upholstery in coastal Florida and California requires salt-resistant finishing treatments that diverge from automotive tanning chemistries.
Luxury vehicles command the established base. Commercial aircraft shows the steepest expansion trajectory.
Distribution Channel:
Volume concentration favors direct-to-consumer digital platforms, while premium restoration work flows through installer networks requiring technical support.
- Online Retailers:CNC-patterned seat kits with cloud-based vehicle interior databases enable made-to-order production without dealer intermediaries. California Air Resources Board VOC adhesive rules reshape fulfillment center location decisions for these channels.
- Specialty Stores:Brick-and-mortar shops in Pennsylvania and Wisconsin maintain heritage tannery relationships for period-correct vegetable-tanned hides bypassing mainstream supply chains.
- Dealerships:Katzkin-affiliated installer networks dominate OEM-adjacent replacement programs with captive quality consistency.
- Trade Shows:SEMA and regional aviation gatherings concentrate bulk procurement decisions for fleet operators and refurbishment shops.
Dealerships command the established base. Online retailers gain share fastest.
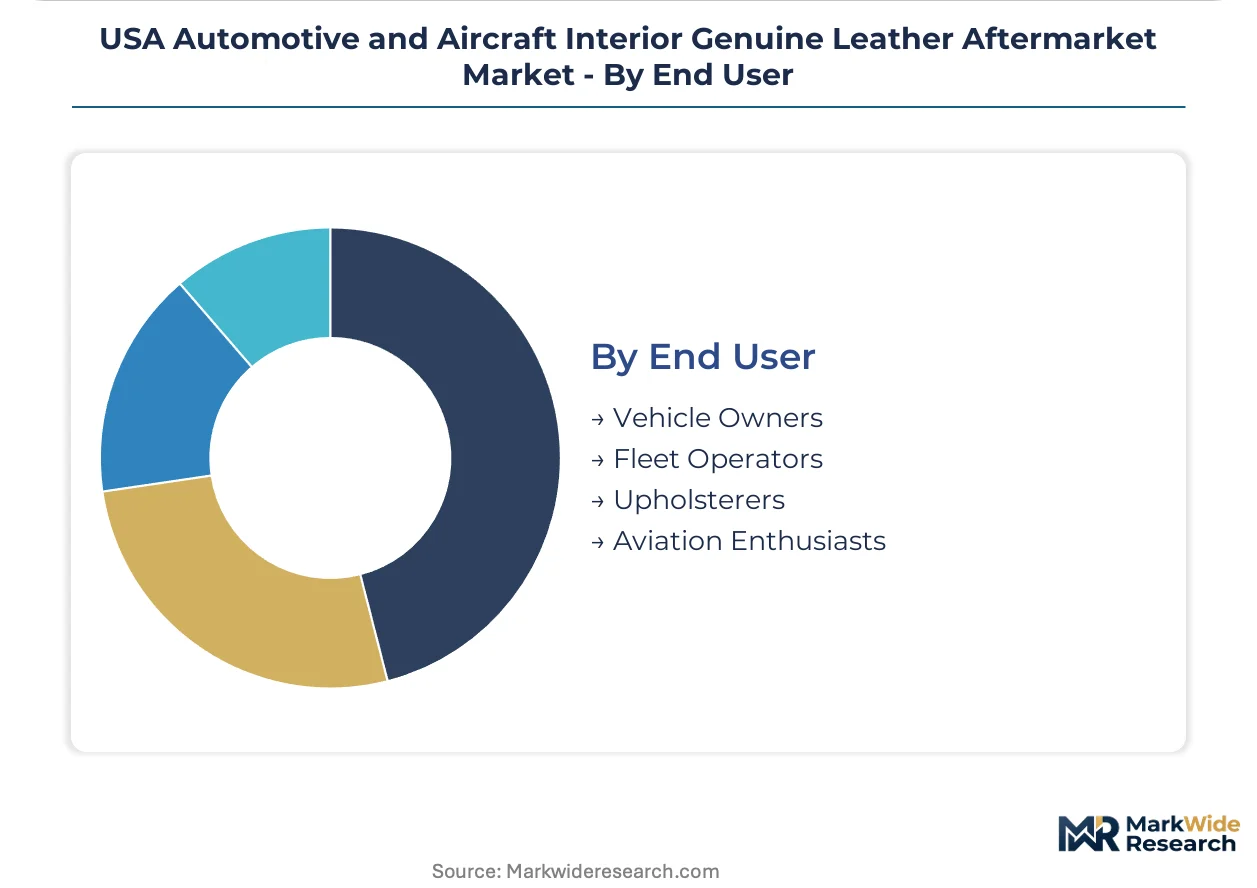
End User:
Customer type determines service intensity, from hands-on collectors specifying heritage tannage methods to fleet buyers prioritizing turnaround velocity.
- Vehicle Owners:DIY restoration participation rises across Georgia, Alabama, and the Carolinas as digital cutting automation reduces skill barriers for seat kit installation.
- Fleet Operators:Commercial motorhome and executive transportation fleets in Nevada and Arizona negotiate volume contracts for UV-resistant leather grades.
- Upholsterers:Independent shops in the Southeast restoration corridor face artisan talent bifurcation between hand-craft heritage methods and automated production systems.
- Aviation Enthusiasts:Private aircraft owners in Florida and Texas source certified materials through specialized aviation upholstery shops with FAA approval authority.
Vehicle owners command the established base. Fleet operators show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across U.S. states diverge sharply between Sun Belt replacement cycles driven by UV degradation and Southeast restoration demand anchored in collector culture.
California
Luxury vehicle owners in Los Angeles and Orange Counties drive OEM-matching full-grain replacement demand for Mercedes-Benz, BMW, and Lexus cabins. Proposition 65 enforcement on chromium VI in leather finishing elevates compliance costs for tanneries serving aftermarket suppliers. San Diego-based restoration shops specialize in period-correct interiors for classic Porsche and Ferrari collectors.
Texas
Dallas-Fort Worth anchors the nation's largest aircraft refurbishment cluster, generating concentrated demand for FAA-certified leather upholstery under Technical Standard Order C25b. Houston's executive transportation fleets negotiate volume contracts for UV-resistant seat coverings. EPA effluent guidelines constrain tannery discharge in neighboring Louisiana processing hubs that serve Texas distributors.
Florida
Miami-Opa Locka and Fort Lauderdale host commercial aviation upholstery specialists serving Caribbean and Latin American maintenance bases. Salt-resistant finishing treatments for marine applications diverge from automotive tanning chemistries along the Gold Coast. Naples and Palm Beach classic car collectors drive heritage vegetable-tanned hide procurement through specialty distributors.
Southeast
Georgia, Alabama, and the Carolinas form an underserved restoration corridor where DIY participation rises as digital cutting automation reduces installation skill barriers. Atlanta and Charlotte upholstery shops face artisan talent bifurcation between hand-craft heritage methods and automated production systems. NHTSA Federal Motor Vehicle Safety Standard 302 shapes burn-performance requirements for street-legal installations across the region.
Midwest
Indiana and Ohio manufacturing corridors generate replacement demand for heavy-duty motorhome seat coverings rated beyond 100,000 double rubs under ASTM D4157. Chicago-area fleet operators prioritize turnaround velocity over customization depth for executive transportation vehicles. Detroit's proximity to OEM engineering centers influences aftermarket suppliers pursuing OEM-adjacent quality consistency.
USA Automotive and Aircraft Interior Genuine Leather Aftermarket Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive tanning partnerships and FAA certification protocols creating separation between scaled operators and regional restoration shops. The market structure rewards backward integration into hide sourcing and chemistry control while penalizing small-batch finishers facing California compliance barriers. Three archetypes dominate: tannery-integrated manufacturers with captive quality systems, aviation-certified specialists with dedicated testing protocols, and direct-to-consumer kit distributors leveraging digital patterning. Competitive moves concentrate on geographic expansion into the Southeast restoration corridor and technology licensing for CNC-patterned production systems.
Within the integrated manufacturing tier, Lear Corporation exemplifies tannery-captive operations sustaining consistent hide quality across automotive seat programs. WOLLSDORF LEDER SCHMIDT & Co. Ges.m.b.H anchors European hide sourcing networks extending into U.S. aircraft upholstery channels. Katzkin Leather, Inc. occupies a position as the dominant direct-to-consumer replacement seat kit distributor through dealership and installer networks.
| Leading Market Players |
|---|
| Lear Corporation |
| WOLLSDORF LEDER SCHMIDT & Co. Ges.m.b.H |
| Bader GmbH & Co. KG |
| Leather Resource Of America Inc. |
| Katzkin Leather, Inc. |
| Hydes Leather |
| Carroll Leather |
| Townsend Leather Company, Inc. |
| Spectra Interior Products |
| Others |
Value Network & Pricing Analysis
Scale economies at Lear Corporation's captive tanning operations establish cost floors that smaller restoration shops cannot match, compressing mid-tier competitors while elevating price premiums for FAA-certified aviation grades. This concentration of chemistry control and hide sourcing among integrated manufacturers reshapes how aftermarket suppliers compete on both cost and compliance dimensions.
Pricing Analysis
Long-term offtake agreements between major distributors and heritage tanneries dominate premium restoration channels, while spot purchasing prevails for corrected-grade automotive hides. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified aviation upholstery from chrome-tanned automotive grades and DIY trim kits. Cost compression in mid-tier automotive segments is intensifying because California Proposition 65 compliance investments favor scaled operators. Fleet operators in Texas and Florida show lowest price sensitivity due to burn-certification requirements, while DIY restorers in the Southeast corridor drive hardest bargains on uncertified trim components.
Supply Chain Analysis
Strait of Hormuz transit underwrites much of the specialty chemical feedstock for chrome-free tanning alternatives, exposing U.S. tanneries to geopolitical supply interruptions. North American steerhide availability draws from Texas and Nebraska cattle cycles, while European heritage tanneries in Austria and Italy anchor vegetable-tanned premium sourcing. Single-source vulnerability concentrates in chromium sulfate suppliers serving Kentucky and Tennessee processing hubs. Distribution runs through captive installer networks for OEM-adjacent replacement, specialty distributors for heritage restoration, and direct-to-consumer platforms for CNC-patterned seat kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where FAA burn-certification protocols and California chemical compliance create switching costs that freeze out unqualified competitors. Network effects concentrate among tannery-integrated manufacturers with established aviation testing relationships.
For Market Incumbents: Shield market position by deepening backward integration into hide sourcing networks across Texas and Nebraska, securing cattle cycle price stability against volatile input costs. Invest in dedicated FAA testing protocols to extend certification moats that exclude smaller tanneries from aviation aftermarket participation. Channel control through captive installer networks remains essential for defending margin position against digital direct-to-consumer entrants. For New Entrants and Emerging Players: Lead with digital cutting automation targeting the Southeast restoration corridor where artisan talent scarcity constrains incumbent throughput. White-space concentration in Georgia, Alabama, and the Carolinas offers penetrable entry points for cloud-based vehicle interior databases enabling made-to-order seat kit production. Go-to-market execution should emphasize online retailer partnerships bypassing traditional dealership networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors tannery-integrated manufacturers with captive chemistry controls and established regulatory compliance infrastructure. Long-term viability across the projection horizon rests on acquisition targets possessing FAA certification authority and California Proposition 65 compliance systems. The signal to monitor is California Air Resources Board VOC amendment enforcement reshaping adhesive system qualification timelines and manufacturing location decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hide Sourcing | Captive supply of Texas and Nebraska steerhide insulates against cattle cycle price volatility. |
| FAA Certification Investment | Technical Standard Order C25b approval unlocks commercial aviation refurbishment clusters in Texas and Florida. |
| Digital Cutting Automation Deployment | CNC patterning technology reduces skill barriers for DIY restorers across the Southeast corridor. |
| California Compliance System Buildout | Proposition 65 chemistry controls and CARB VOC adhesive rules secure coastal market access. |
| Heritage Tannery Partnership | European vegetable-tanning relationships capture period-correct restoration premiums from classic car collectors. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with tannery operations directors, FAA certification specialists, aftermarket distributor procurement leads, and classic car restoration shop owners; and secondary validation through customs records, EPA effluent compliance filings, NHTSA Federal Motor Vehicle Safety Standard 302 test reports, and aircraft interior material flammability databases. Bottom-up demand modeling across vehicle class, propulsion architecture, and regional restoration corridor density triangulated against top-down value chain analysis.
Across the modeling period, the analytical framework projected volume and value outputs by segmenting across product type, application, distribution channel, and end-user sophistication. CAGRs were derived from regression analysis of replacement cycle frequencies, UV degradation patterns in Sun Belt states, and aviation refurbishment cluster activity. Forecast inputs incorporated cattle cycle conditions in Texas and Nebraska, California regulatory amendment trajectories, and digital cutting automation adoption curves.
Underlying assumptions cover stable FAA certification timeline structures and California chemical enforcement intensity, with deviation risk concentrated in EPA effluent guideline amendments affecting Kentucky and Tennessee processing capacity. Practitioners should keep alternative scenarios live as Proposition 65 litigation patterns and vegetable tanning revival demand curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Europe Automotive Wrap Films Market
Automotive Interior & Exterior
Automotive Smart Dashboard Display Market
Automotive Interior & Exterior
Interior Materials for Pet-Friendly Vehicle Cabins Market
Automotive Interior & Exterior
Latin America Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Seating Systems Market
Automotive Interior & Exterior
Power Sunroof Market
Automotive Interior & Exterior
Automotive Soft Trim Interior Materials Market
Automotive Interior & Exterior
PVC and PU Leather for Automotive Market
Automotive Interior & Exterior
Automotive Intelligent Rear-View Mirror Market
Automotive Interior & Exterior
Automotive Overhead Console Market
Automotive Interior & Exterior
US Automotive Wrap Films Market
Automotive Interior & Exterior
Decorative Car Accessories Market
Automotive Interior & Exterior
Automotive Tinting Film Market
Automotive Interior & Exterior
Automotive Sealants Market
Automotive Interior & Exterior
Zero Gravity Seat Market
Automotive Interior & Exterior
Car Organizer Market