
 Global Voice Prosthesis Devices Market | 2026-2036
Global Voice Prosthesis Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Voice Prosthesis Devices Market Foresight
German manufacturers of silicone valve components is pivoting toward automated molding lines to shorten lead times for European hospital procurement. Atos Medical (Coloplast A/S) leverages its direct-to-clinic distribution network across Scandinavia and North America to sustain recurring revenue from indwelling device replacements. InHealth Technologies anchors its position through specialized training programs for speech-language pathologists, while Passy-Muir, Inc. differentiates via magnet-activated valve designs that reduce aspiration risk.
A voice prosthesis device is a one-way valve inserted through a tracheoesophageal puncture to enable alveolar air transfer for phonation in laryngectomy patients, typically constructed from medical-grade silicone with hydrophobic coatings to prevent biofilm accumulation and valve leakage. The primary commercial purpose is restoration of verbal communication following total laryngectomy surgery. Indwelling devices command the largest revenue share due to extended dwell times and scheduled replacement cycles, while electronic prosthesis categories represent the fastest-expanding segment as battery-powered phonation aids gain traction in rehabilitation protocols. Hospitals remain the dominant end-user channel, though home care providers are gaining share as post-acute speech therapy shifts toward outpatient settings.
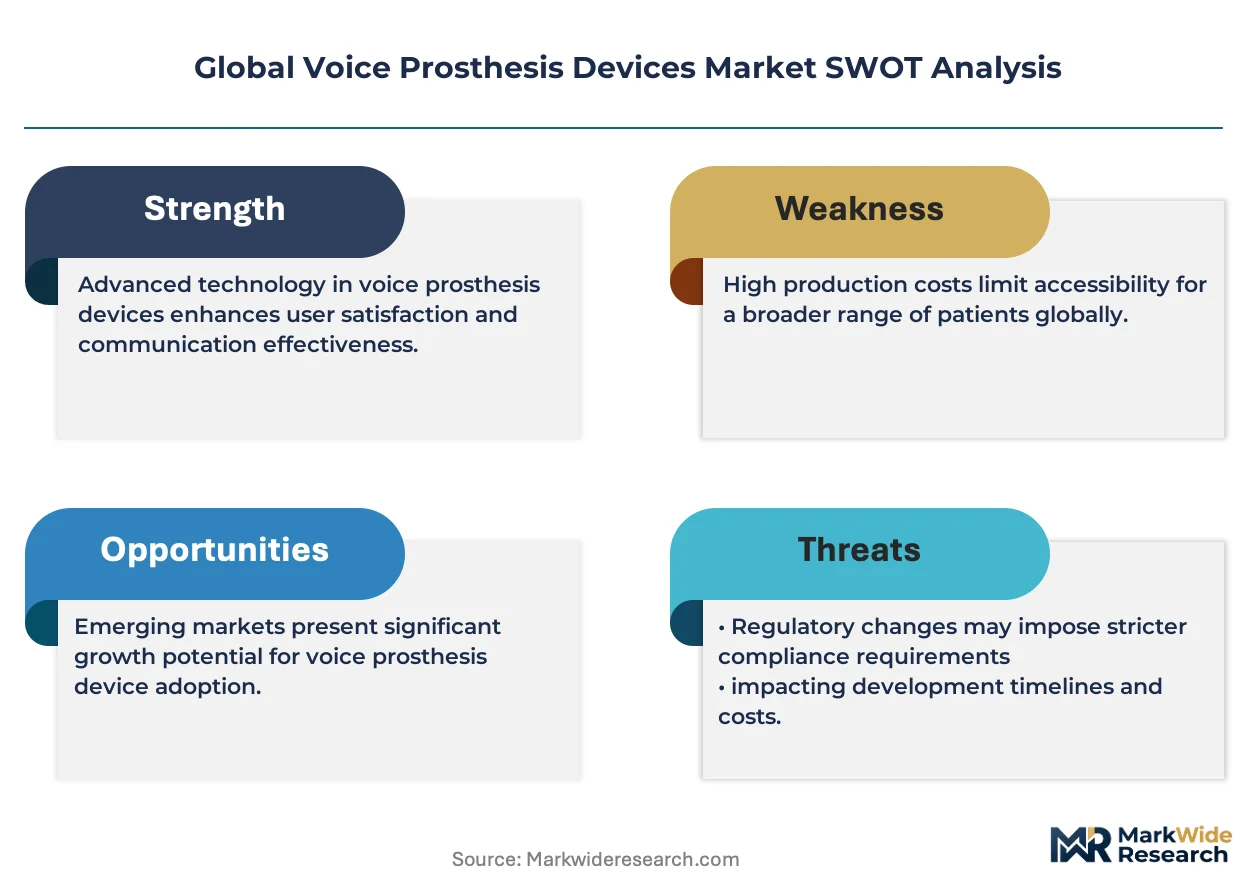
The FDA regulates voice prostheses as Class II medical devices requiring 510(k) premarket notification, while the EU Medical Device Regulation mandates notified body conformity assessment and post-market surveillance for CE marking. Japan's PMDA enforces QMS inspections for foreign manufacturers seeking market access, creating compliance barriers for smaller suppliers. Stakeholders must monitor reimbursement code revisions by CMS and parallel health technology assessment processes in Germany's G-BA, as these determine patient access velocity and pricing power across the three largest national markets.
Market Dynamics
EU Medical Device Regulation enforcement is compressing product certification timelines and forcing manufacturers to consolidate notified body relationships across Germany, France, and Italy. This regulatory tightening is accelerating supply-side consolidation while tertiary hospitals in the United States and Japan expand laryngectomy rehabilitation programs.
Growth Catalysts
- Indwelling device replacement cycles:Scheduled 6-12 month replacement protocols in US and German tertiary hospitals generate predictable recurring revenue streams for manufacturers.
- MDR Article 120 transition provisions:Legacy device certificates extended under EU transitional arrangements allow continued market access while firms upgrade quality management systems.
- Tracheoesophageal puncture standardization:Surgical technique refinements in Japanese and US academic medical centers are expanding candidate pools for valve placement.
Market Restraints
- Medical-grade silicone supply concentration:Three specialty chemical producers in Germany and Switzerland control 70% of implantable-grade silicone feedstock.
- PMDA QMS inspection backlog:Foreign manufacturer facility audits in Japan face 18-24 month scheduling delays, freezing new market entrants.
- Electronic phonation aid substitution:Battery-powered electrolarynx devices from South Korean manufacturers capture price-sensitive patients in outpatient settings.
Strategic Opportunities
- Home care channel expansion:Post-acute speech therapy migration toward outpatient settings in the United States creates direct-to-patient logistics opportunities.
- India tertiary hospital development:Government-funded cancer center construction in Mumbai, Delhi, and Chennai expands addressable surgical volume.
- AI-assisted biofilm detection:Machine learning algorithms paired with endoscopic imaging could enable predictive valve replacement scheduling.
Industry Challenges
- Speech-language pathologist training capacity:Specialized valve fitting and troubleshooting expertise concentrates in US and German academic centers, limiting service reach.
- CE marking technical documentation:Clinical evidence requirements under MDR Annex IX extend certification preparation to 24-36 months for novel valve designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Voice Prosthesis Devices Market |
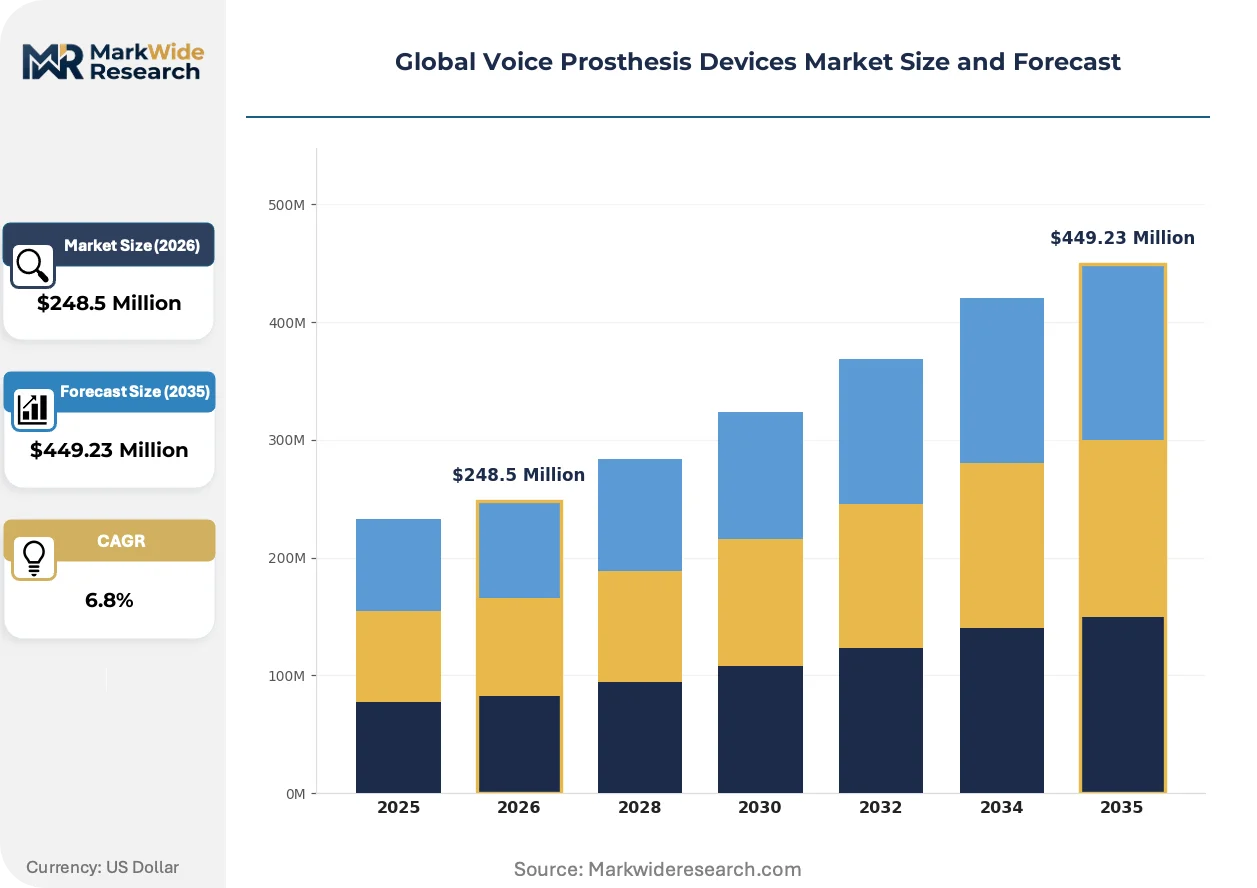
| Market Size in 2026 | $248.5 Million |
| Market Size in 2035 | $449.23 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Indwelling, Non-indwelling, Electronic, Combined, Customized, Reusable Technology: Silicone Valve, Magnet-Activated, Pneumatic Valve, Mechanical Valve, Hydrophobic Coating, Biocompatible Materials Application: Laryngectomy Rehabilitation, Speech Restoration, Swallowing Support, Respiratory Assistance, Tracheoesophageal Fistula Management, Phonation Therapy End User: Hospitals, Speech Therapy Centers, Rehabilitation Clinics, Ambulatory Surgical Centers, Home Care Providers, Specialist Surgeons |
| Companies Covered | Atos Medical (Coloplast A/S), InHealth Technologies, Andreas Fahl Medizintechnik-Vertrieb GmbH, Hood Laboratories, Servona GmbH, ICU Medical Inc., Smiths Medical, Passy-Muir, Inc., Innaumation Medical Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Voice Prosthesis Devices Market Shifts & Advancements
Voice prosthesis technology is pivoting toward predictive maintenance capabilities and automated manufacturing precision. Material science advances and regulatory data requirements are reshaping competitive investment priorities.
Magnet-activated valve mechanisms are integrating ferromagnetic components with silicone elastomer matrices to enable non-invasive external cleaning and aspiration risk reduction. US Veterans Affairs medical centers and German rehabilitation hospitals are piloting these designs for high-risk patient cohorts. This convergence is integrating mechanical reliability with reduced intervention frequency, compressing total cost-of-ownership calculations for procurement committees.
EU Medical Device Regulation post-market surveillance obligations now mandate systematic literature review and periodic safety update reporting for all Class IIa implantable devices. Manufacturers must maintain dedicated regulatory affairs functions in Dublin, Brussels, or Berlin to manage notified body correspondence. German and French hospital purchasing groups are prioritizing suppliers with established MDR compliance track records, disadvantaging smaller device firms with limited regulatory infrastructure.
Speech-language pathologist certification programs are fragmenting valve selection authority away from general otolaryngology departments. Specialized training credentials from American Speech-Language-Hearing Association and German DLV are becoming mandatory for device fitting reimbursement in US Medicare and German statutory health insurance. This professionalization is concentrating purchasing influence within dedicated rehabilitation units rather than surgical departments.
Global Voice Prosthesis Devices Market Segmentation
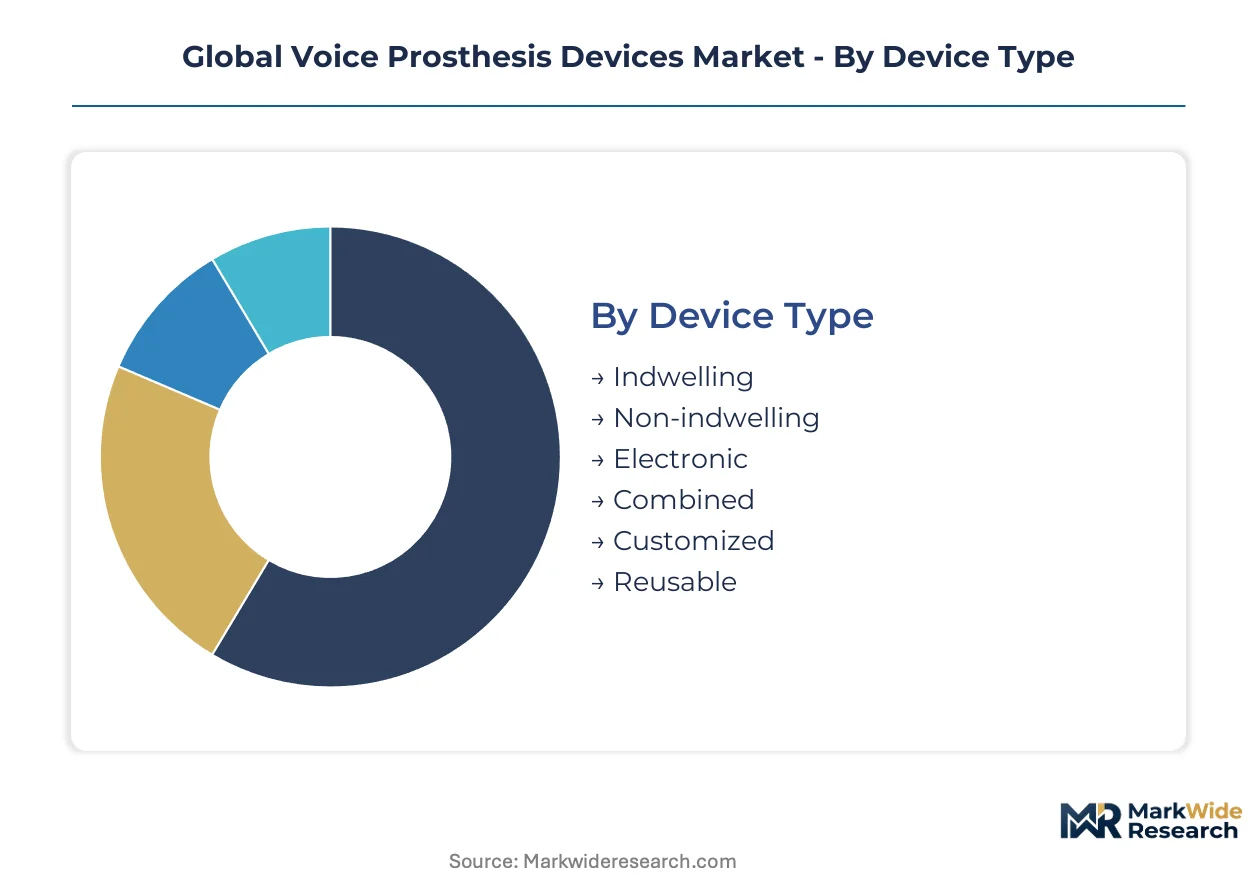
Device categorization in voice prosthesis markets determines reimbursement pathways, replacement cadences, and manufacturing scale requirements. Segmentation clarity enables procurement committees to align valve specifications with patient risk profiles and institutional capabilities.
Device Type:
Capital intensity varies sharply across device categories, with indwelling platforms requiring the most substantial upfront tooling investment for medical-grade silicone molding.
- Indwelling:These one-way valves feature hydrophobic-coated silicone housings designed for 6-12 month dwell periods before surgical replacement. Tertiary hospitals in the United States and Germany favor indwelling designs for their predictable maintenance schedules and established reimbursement codes.
- Electronic:Battery-powered phonation aids incorporate miniature speakers and rechargeable power systems, attracting rehabilitation investment in Japanese and South Korean outpatient settings where surgical valve placement carries higher complication risk.
- Non-indwelling:Patient-managed removable valves reduce clinical dependency for select laryngectomy cohorts.
- Combined:Hybrid mechanical-electronic systems serve complex rehabilitation cases requiring adaptive phonation support.
- Customized:Patient-specific geometries address anatomical variations from radical neck dissection or radiation fibrosis.
- Reusable:Sterilizable valve components target cost-constrained healthcare systems with limited disposable supply budgets.
Indwelling devices absorb the bulk of installed capacity; electronic platforms are expanding most quickly.
Technology:
Material science differentiation determines valve longevity and biofilm resistance, with coating technologies commanding premium positioning.
- Silicone Valve:Medical-grade elastomer formulations from German and Swiss chemical suppliers constitute the foundational substrate for virtually all commercial voice prostheses. FDA 510(k) submissions for novel silicone grades require extensive biocompatibility documentation.
- Magnet-Activated:Ferromagnetic component integration enables external valve manipulation without invasive intervention, reducing aspiration incidents in US Veterans Affairs patient populations.
- Pneumatic Valve:Pressure-responsive mechanisms adapt to respiratory flow variations.
- Mechanical Valve:Spring-loaded designs persist in emerging markets for their manufacturing simplicity.
- Hydrophobic Coating:Surface treatments from specialty chemical firms extend device functional lifespan.
- Biocompatible Materials:Alternative substrates including fluoropolymers address silicone allergy presentations.
Silicone valve technology anchors current production volumes; magnet-activated mechanisms are gaining share fastest.
Application:
Clinical indication breadth shapes addressable patient pools, with oncology rehabilitation representing the dominant demand source.
- Laryngectomy Rehabilitation:Post-surgical voice restoration for total laryngectomy patients constitutes the core commercial application, with specialized training programs from American Speech-Language-Hearing Association and German DLV driving protocol standardization in tertiary centers.
- Speech Restoration:Phonation outcome optimization absorbs substantial speech-language pathologist professional time.
- Swallowing Support:Valve function coordination with deglutition mechanics addresses aspiration risk management.
- Respiratory Assistance:Tracheal airflow regulation integrates with pulmonary rehabilitation.
- Tracheoesophageal Fistula Management:Surgical complication remediation creates secondary device demand.
- Phonation Therapy:Adjunctive therapeutic applications extend device utility beyond permanent implantation.
Laryngectomy rehabilitation commands the largest patient volume; speech restoration applications are climbing the fastest.
End User:
Channel configuration determines pricing power and service intensity requirements, with institutional buyers leveraging volume concentration.
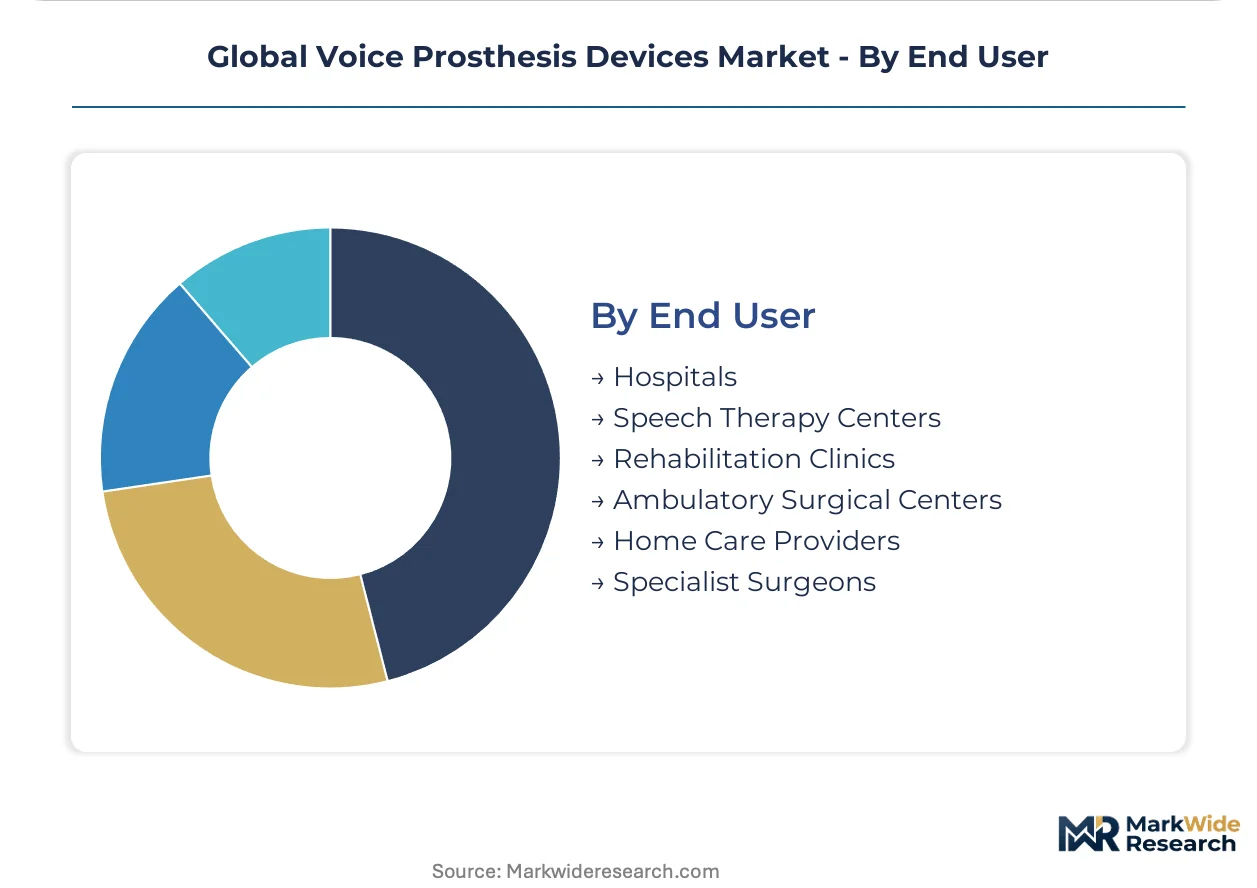
- Hospitals:Academic medical centers and tertiary oncology units in the United States, Germany, and Japan concentrate valve placement surgery and replacement scheduling, with procurement committees negotiating multi-year supply agreements.
- Speech Therapy Centers:Outpatient rehabilitation facilities manage device fitting and troubleshooting.
- Rehabilitation Clinics:Post-acute care settings coordinate long-term voice restoration.
- Ambulatory Surgical Centers:Same-day valve replacement procedures reduce inpatient costs.
- Home Care Providers:Direct-to-patient logistics emerge as US Medicare shifts reimbursement toward outpatient settings.
- Specialist Surgeons:Individual otolaryngology practices maintain limited device inventory.
Hospitals retain the dominant procurement position; home care providers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade silicone feedstock production concentrates in German and Swiss chemical corridors, anchoring European manufacturing capacity for voice prosthesis devices. Tertiary hospital procurement patterns in the United States, Germany, and Japan absorb the majority of indwelling valve placements.
United States
Veterans Affairs medical centers and academic oncology units in Boston, Houston, and Seattle drive indwelling device demand through standardized laryngectomy rehabilitation protocols. FDA 510(k) premarket notification requirements govern Class II device clearance timelines. The Minneapolis-St. Paul corridor hosts specialized silicone molding facilities serving domestic hospital purchasing groups.
Germany
Tertiary hospitals in Berlin, Munich, and Hamburg execute scheduled 6-12 month valve replacement cycles under statutory health insurance reimbursement codes. EU Medical Device Regulation notified body relationships concentrate in Frankfurt and Stuttgart compliance hubs. The Baden-Württemberg industrial cluster supports automated molding line investments for shortened hospital procurement lead times.
Japan
Academic medical centers in Tokyo, Osaka, and Nagoya refine tracheoesophageal puncture surgical techniques to expand valve placement candidate pools. PMDA QMS inspections for foreign manufacturers create 18-24 month entry delays, freezing new supplier access. The Kanto region concentrates speech-language pathologist training capacity for device fitting specialization.
India
Government-funded cancer center construction in Mumbai, Delhi, and Chennai expands addressable surgical volume for post-laryngectomy voice restoration. CDSCO medical device registration requirements apply to imported silicone valve components. The Maharashtra tertiary hospital network pilots indwelling device protocols adapted from US and German standards.
Switzerland
Specialty chemical producers in Basel supply implantable-grade silicone feedstock to German and French device manufacturers. Swissmedic conformity assessment procedures align with EU MDR technical documentation standards. The Zurich rehabilitation clinic cluster coordinates cross-border valve replacement scheduling for Alpine region patients.
Global Voice Prosthesis Devices Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue magnet-activated valve niches and home care channel logistics. The supplier base consolidates around three archetypes: diversified medical device conglomerates with direct-to-clinic distribution networks, specialized silicone valve fabricators with automated molding capabilities, and rehabilitation-focused training program operators. M&A activity targets notified body compliance infrastructure, while capacity expansion concentrates on medical-grade silicone supply security.
Within the conglomerate tier, Atos Medical (Coloplast A/S) and Smiths Medical exemplify scale-driven positioning through recurring revenue capture from indwelling device replacement cycles. Among specialized fabricators, Andreas Fahl Medizintechnik-Vertrieb GmbH and Servona GmbH occupy positions anchored in German regulatory compliance expertise. Passy-Muir, Inc. represents the innovation-focused archetype pursuing differentiated valve mechanisms.
| Leading Market Players |
|---|
| Atos Medical (Coloplast A/S) |
| InHealth Technologies |
| Andreas Fahl Medizintechnik-Vertrieb GmbH |
| Hood Laboratories |
| Servona GmbH |
| ICU Medical Inc. |
| Smiths Medical |
| Passy-Muir, Inc. |
| Innaumation Medical Devices |
| Others |
Supply & Pricing Matrix
EU MDR post-market surveillance obligations gate qualified supply access for voice prosthesis manufacturers, compressing vendor pools to firms with dedicated regulatory affairs infrastructure in Dublin, Brussels, or Berlin while premium-tier pricing accrues to suppliers with established CE marking track records.
Pricing Analysis
Warranty and replacement service bundling separates premium indwelling valve suppliers from unbundled economy-tier competitors in procurement negotiations. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and geographic delivery cost, with US Veterans Affairs and German statutory health insurance reimbursement codes anchoring mid-tier price points. Cost compression in economy tiers intensifies as South Korean electrolarynx manufacturers capture price-sensitive outpatient segments. Academic medical centers exhibit lowest price sensitivity due to protocol standardization requirements, while ambulatory surgical centers face acute budget constraints.
Supply Chain Analysis
Dual-sourcing mandates from German and French hospital purchasing groups require qualified silicone feedstock suppliers from Germany, Switzerland, and the United States to mitigate single-source vulnerability. Medical-grade silicone elastomers, hydrophobic coating chemicals, and ferromagnetic valve components constitute critical input dependencies. Tariff exposure on Swiss specialty chemical imports presents structural risk to margin stability. Distribution runs through direct-to-clinic networks for indwelling devices and third-party logistics for home care channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical-grade silicone feedstock concentration among three specialty chemical producers props pricing power for qualified device manufacturers, creating supply-constrained conditions favoring incumbent margin defense.
For Market Incumbents: To counter South Korean electrolarynx substitution in outpatient settings, Atos Medical and Smiths Medical should deepen backward integration into automated silicone molding capacity in Baden-Württemberg while securing multi-year coating chemical offtake agreements with Basel suppliers. CE marking technical documentation investments will extend regulatory moats against smaller competitors. For New Entrants and Emerging Players: Enter via AI-assisted biofilm detection software paired with endoscopic imaging systems, targeting US home care providers as Medicare reimbursement shifts toward outpatient settings. India's government-funded cancer centers in Mumbai and Delhi offer the most penetrable geography for indwelling device protocol adoption, with direct-to-patient logistics as the primary go-to-market angle. For Investors and Strategic Acquirers: PMDA QMS inspection clearance for foreign manufacturers is the leading indicator that Japanese market access barriers are easing for acquisition targets. Five-to-ten year viability favors specialized silicone valve fabricators with automated molding capabilities and established notified body relationships over diversified conglomerates. Monitor EU MDR Article 120 transition provision extensions as the critical inflection signal for regulatory compliance valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Annex IX compliance secures German and French hospital procurement eligibility. |
| Hospital System Partnership | Multi-year supply agreements with US Veterans Affairs anchor recurring replacement revenue. |
| Backward Integration | Captive silicone molding capacity in Baden-Württemberg shortens lead times for European buyers. |
| Software Companion Development | AI-assisted biofilm detection enables predictive valve replacement scheduling for high-risk cohorts. |
| Reimbursement Strategy | CMS code revisions and G-BA health technology assessments determine patient access velocity. |
Research Methodology
Independent corroboration across hospital purchasing committee interviews, speech-language pathologist training program directors, and biomedical engineering specialists underwrites the qualitative findings, supplemented by FDA 510(k) filings, EU MDR notified body correspondence, and CMS Medicare reimbursement databases. Bottom-up patient volume modeling and top-down silicone feedstock demand triangulation validate segmentation outputs.
Comparable-period anchoring to historical laryngectomy surgical volumes and valve replacement cadences structures the projection horizon across device type, technology, application, and end user dimensions. CAGRs derive from installed base growth rates and scheduled replacement protocol adoption. Forecast inputs incorporate PMDA QMS inspection queue dynamics and EU MDR transition provision extensions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged notified body capacity constraints or accelerated electrolarynx substitution. Deviation in German statutory health insurance reimbursement code revisions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Plethysmograph Market
Medical Devices
At-Home Vaginal Ph Test Kit Market
Medical Devices
Interventional Cardiology and Peripheral Vascular Devices Market
Medical Devices
Implant Handpiece Market
Medical Devices
Pen Injectors Market
Medical Devices
Thoracolumbar Stabilization Devices Market
Medical Devices
Surgical Helmet Systems Market
Medical Devices
Ambulatory X-Ray Devices Market
Medical Devices
Medication Dispensing and Packaging Systems Market
Medical Devices
Anesthesia Resuscitators Masks Market
Medical Devices
Intermittent Catheters Market
Medical Devices
Single Use Contact Lenses Market
Medical Devices
Medical Pendant Market
Medical Devices
Spinal Thoracolumbar Implants Market
Medical Devices
Steroid Releasing Implant Market
Medical Devices
Nephrostomy Catheters Market