
 Global Veterinary Rapid Test Market | 2026-2036
Global Veterinary Rapid Test Market Size, Share, and Industry Trends Forecast 2026-2036
Global Veterinary Rapid Test Market Foresight
Point-of-care bundling is pivoting toward integrated assay platforms that combine immunoassay cartridges with cloud-connected result readers, compressing buyer evaluation into single-vendor decisions. Zoetis leverages its diagnostics-to-pharmaceuticals integration to lock in clinic loyalty through combined vaccine and testing protocols. IDEXX Laboratories sustains technology leadership in proprietary catalyst chemistry that shortens result turnaround in busy companion animal practices. Thermo Fisher Scientific anchors its position through manufacturing scale that supplies private-label rapid tests to third-party distributors across North America and Western Europe.
Veterinary rapid tests are membrane-based or cartridge-format immunoassays that detect pathogen antigens, host antibodies, or biochemical markers in whole blood, serum, or fecal samples within minutes, typically using colloidal gold or enzyme-conjugated reporter systems visualized through colorimetric change. These devices serve primarily to enable immediate clinical decision-making at the point of care, reducing reliance on centralized laboratory turnaround and allowing veterinarians to initiate treatment or isolation protocols during the same patient visit. Lateral flow assays occupy the largest volume position due to their minimal equipment requirements and suitability for field deployment on livestock operations, while molecular diagnostics segments attract premium positioning through nucleic acid amplification specificity that immunoassays cannot match. Deployment through mobile clinics and on-farm testing represents the fastest-growing structural channel, as veterinary service models adapt to large-animal practitioners who cannot transport herds to fixed facilities.
The FDA Center for Veterinary Medicine oversees assay validation claims for products marketed in the United States, while the EU IVDR imposes notified body conformity assessment on manufacturers seeking CE marking for sale across European member states. ISO 17025 accreditation requirements for reference laboratories in countries including Australia and Japan create downstream demand pull for rapid tests that can demonstrate traceable correlation to certified methods. Stakeholders must monitor how evolving equivalence standards between rapid assay formats and reference laboratory methods reshape reimbursement eligibility and purchasing specifications across integrated veterinary health networks.
Market Dynamics
Corporate veterinary group consolidation is compressing procurement cycles and forcing manufacturers to deliver integrated assay platforms with cloud-connected result management rather than standalone test kits.
Growth Catalysts
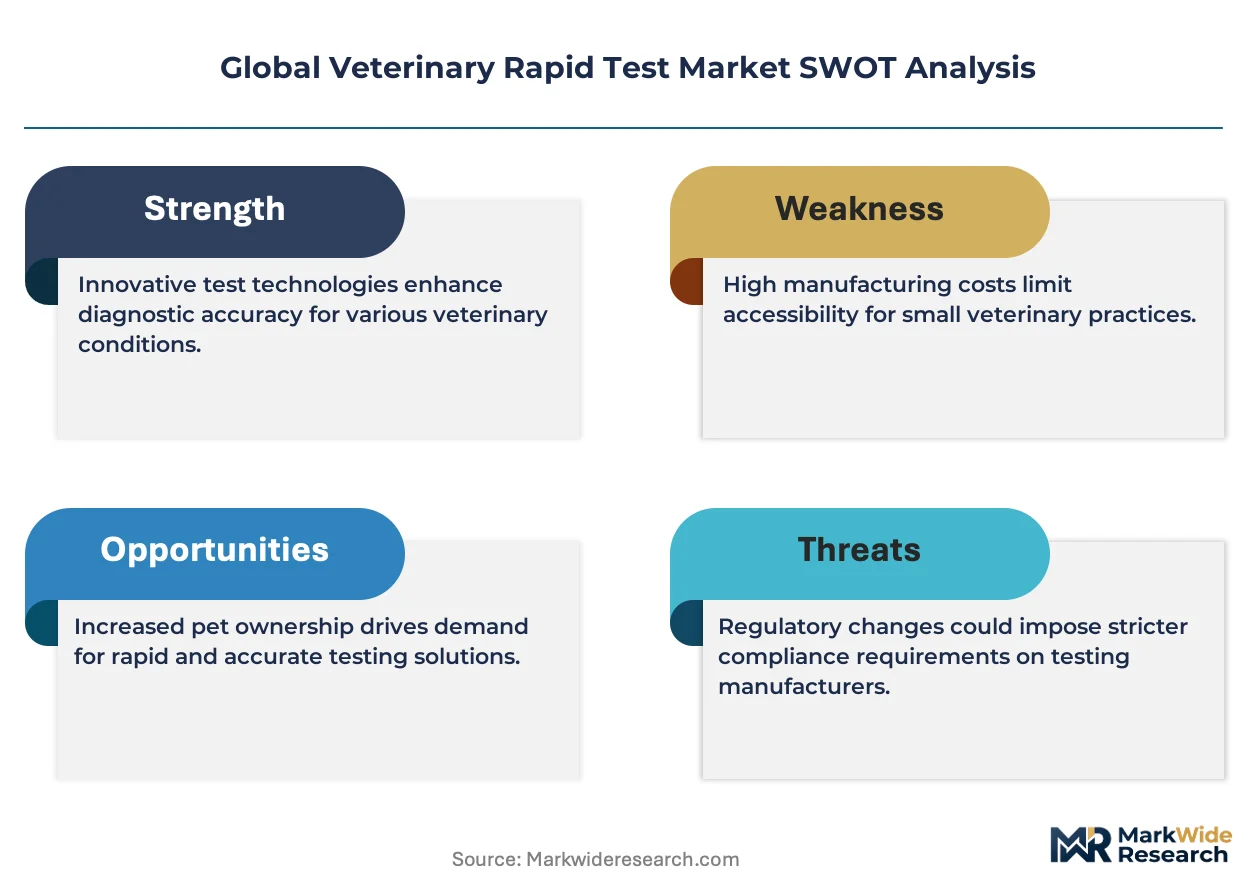
- EU IVDR conformity assessment:The tightened performance documentation requirements for in vitro diagnostic reagents sold across member states is elevating quality barriers and favoring established manufacturers with robust technical files.
- Point-of-care bundling:Integrated assay platforms that combine immunoassay cartridges with digital result readers are consolidating buyer evaluation into single-vendor decisions, locking in recurring consumable revenue streams.
- Mobile clinic deployment:Veterinary service models adapting to large-animal practitioners who cannot transport herds to fixed facilities are driving demand for field-deployable lateral flow formats with minimal equipment requirements.
Market Restraints
- Gold nanoparticle supply concentration:Colloidal gold reporter systems depend on concentrated raw material suppliers, exposing test manufacturers to price volatility and supply disruption risks.
- Reference laboratory correlation costs:ISO 17025 accreditation requirements for traceable method equivalence in Australia and Japan impose validation burdens that smaller manufacturers struggle to fund.
- Molecular diagnostic substitution:Nucleic acid amplification platforms are capturing premium positioning through superior specificity that immunoassays cannot match, pressuring membrane-based format margins.
Strategic Opportunities
- Brazil livestock extension:ANVISA regulatory pathways for veterinary diagnostics present white space for manufacturers with established CE marking to leverage technical documentation for accelerated market entry.
- Pharmaceutical-diagnostic protocol integration:Combined vaccine and testing protocols are creating loyalty lock-in opportunities for manufacturers with companion animal pharmaceutical portfolios.
- Telemedicine result transmission:Cloud-connected readers enabling real-time consultation with remote specialists are opening subscription revenue models beyond hardware and consumable sales.
Industry Challenges
- Multiplex assay development timelines:Combining multiple pathogen targets on single cartridges requires extended validation cycles against individual assay performance claims, stretching R&D resources.
- Cross-platform data integration:Clinic networks operating mixed-vendor environments face interoperability friction when consolidating rapid test results with centralized laboratory information management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Veterinary Rapid Test Market |
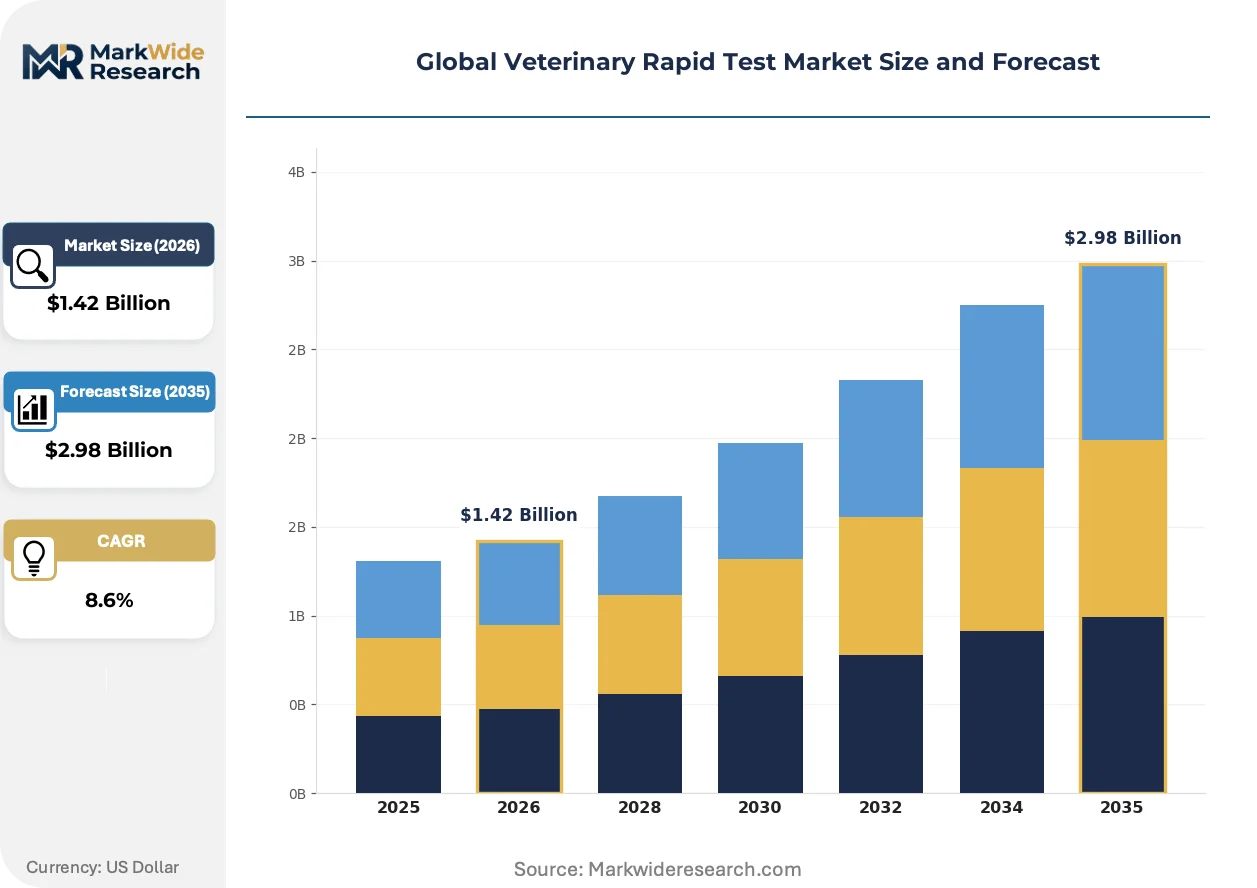
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunoassays, Molecular Diagnostics, Lateral Flow Assays, ELISA Kits Application: Disease Detection, Pregnancy Testing, Food Safety, Parasite Identification, Antibiotic Residue Screening End User: Veterinary Clinics, Diagnostic Laboratories, Research Institutes, Livestock Farms, Zoos Deployment: Point of Care, In-Lab Testing, Mobile Clinics, On-Farm Testing |
| Companies Covered | Zoetis, IDEXX Laboratories, Virbac, Heska Corporation, Thermo Fisher Scientific, Neogen Corporation, Biopanda Reagents, Fassisi GmbH, BioNote, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Veterinary Rapid Test Market Shifts & Advancements
Digital connectivity and assay multiplexing are converging to transform veterinary rapid testing from isolated point-of-care tools into integrated diagnostic nodes within broader animal health data ecosystems.
Fluorescent microsphere detection technology is automating quantitative result interpretation that previously required visual judgment or separate reader devices. Large corporate veterinary groups in the United States are standardizing procurement of these platforms across multi-site clinic networks to eliminate operator-dependent variability. This automation is compressing training requirements and enabling centralized quality oversight across geographically dispersed practices.
The EU MDR and IVDR frameworks are tightening clinical evidence requirements for devices seeking CE marking across European member states. Manufacturers must now submit performance evaluation reports with traceable reference method correlation data, extending conformity assessment timelines. Companion animal clinics in Germany and France are responding by consolidating supplier relationships toward vendors with established notified body certifications.
Consolidated buying by corporate veterinary groups is displacing independent practice procurement autonomy with standardized assay menus and volume-based contracting. Multi-site clinic networks are mandating approved vendor lists that exclude smaller manufacturers lacking national distribution scale. This concentration is most visible in the United States, where veterinary practice aggregation has reached levels unseen in European or Asia-Pacific markets.
Global Veterinary Rapid Test Market Segmentation
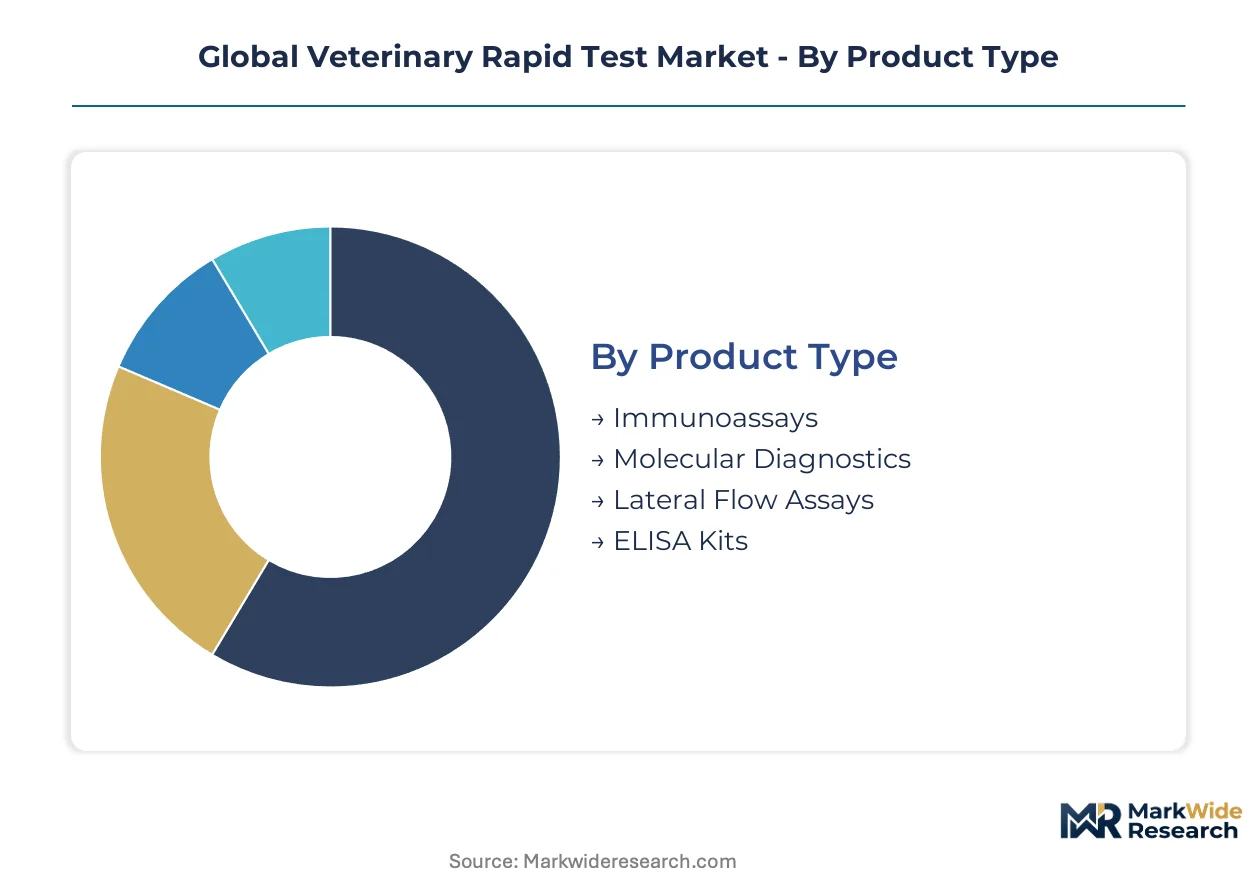
Veterinary rapid test segmentation reflects divergent technical requirements between companion animal clinics demanding speed and livestock operations prioritizing field durability. Manufacturers configure assay chemistry, reader connectivity, and packaging specifications differently across these axes to capture procurement budgets.
Product Type:
Detection chemistry and signal amplification methods differentiate performance ceilings and manufacturing complexity across formats.
- Lateral Flow Assays:Membrane-based colloidal gold or fluorescent microsphere systems deliver visual results within 10-15 minutes without powered equipment. Demand concentrates in livestock farms across Australia and Brazil where grid electricity is unreliable and herd-side screening must proceed without laboratory infrastructure.
- Molecular Diagnostics:Isothermal amplification and CRISPR-based nucleic acid detection achieve pathogen-specific identification unmatched by immunoassay sensitivity. Companion animal specialty clinics in Germany and Japan absorb premium pricing for respiratory and vector-borne disease panels where treatment selection depends on species-level pathogen discrimination.
- Immunoassays:Enzyme-linked and chemiluminescent formats provide quantitative antibody titers for vaccine response monitoring in equine and production animal settings.
- ELISA Kits:Microplate-based batch processing serves high-throughput diagnostic laboratories with automated wash stations and spectrophotometric readers.
Lateral flow assays lead on scale; molecular diagnostics lead on momentum.
Application:
Clinical utility and regulatory screening mandates shape assay menu priorities across end-use environments.
- Disease Detection:Pathogen antigen and antibody identification for canine parvovirus, feline leukemia, and bovine viral diarrhea dominates procurement volumes. United States corporate veterinary groups standardize these panels across multi-site networks to enable immediate isolation decisions during single-visit consultations.
- Antibiotic Residue Screening:Beta-lactam and tetracycline detection in milk and tissue samples enforces EU MRL compliance for dairy export certification. French and Dutch dairy cooperatives mandate on-farm testing before tanker collection to prevent batch rejection at processing plants.
- Pregnancy Testing:Progesterone and pregnancy-associated glycoprotein assays enable breeding management in equine and cattle operations.
- Food Safety:Salmonella and E. coli rapid screening supports slaughterhouse HACCP verification and retail meat certification.
- Parasite Identification:Fecal antigen detection for heartworm, giardia, and helminth eggs guides deworming protocols in companion animal practices.
Disease detection commands the largest installed base; antibiotic residue screening is climbing the fastest on regulatory enforcement.
End User:
Procurement sophistication and volume concentration vary sharply between fragmented independent practices and consolidated institutional buyers.
- Veterinary Clinics:Companion animal and mixed practices in the United States drive integrated platform adoption. Corporate group standardization mandates cloud-connected readers with unified result databases across hundreds of locations.
- Livestock Farms:Cattle, swine, and poultry operations in Brazil and Australia require dust-resistant, battery-operated formats for pen-side screening without veterinary staff present.
- Diagnostic Laboratories:Reference facilities in Japan and Australia demand ISO 17025-traceable correlation data for rapid test equivalence claims.
- Research Institutes:Academic veterinary schools and pharmaceutical field trial sites utilize rapid assays for preliminary screening before confirmatory testing.
- Zoos:Exotic animal collections require species-validated assay modifications for non-domestic host antibody detection.
Veterinary clinics absorb the highest per-site consumable spend; livestock farms represent the steepest expansion trajectory in unit volume.
Deployment:
Physical testing location determines environmental specifications, connectivity requirements, and operator training depth.
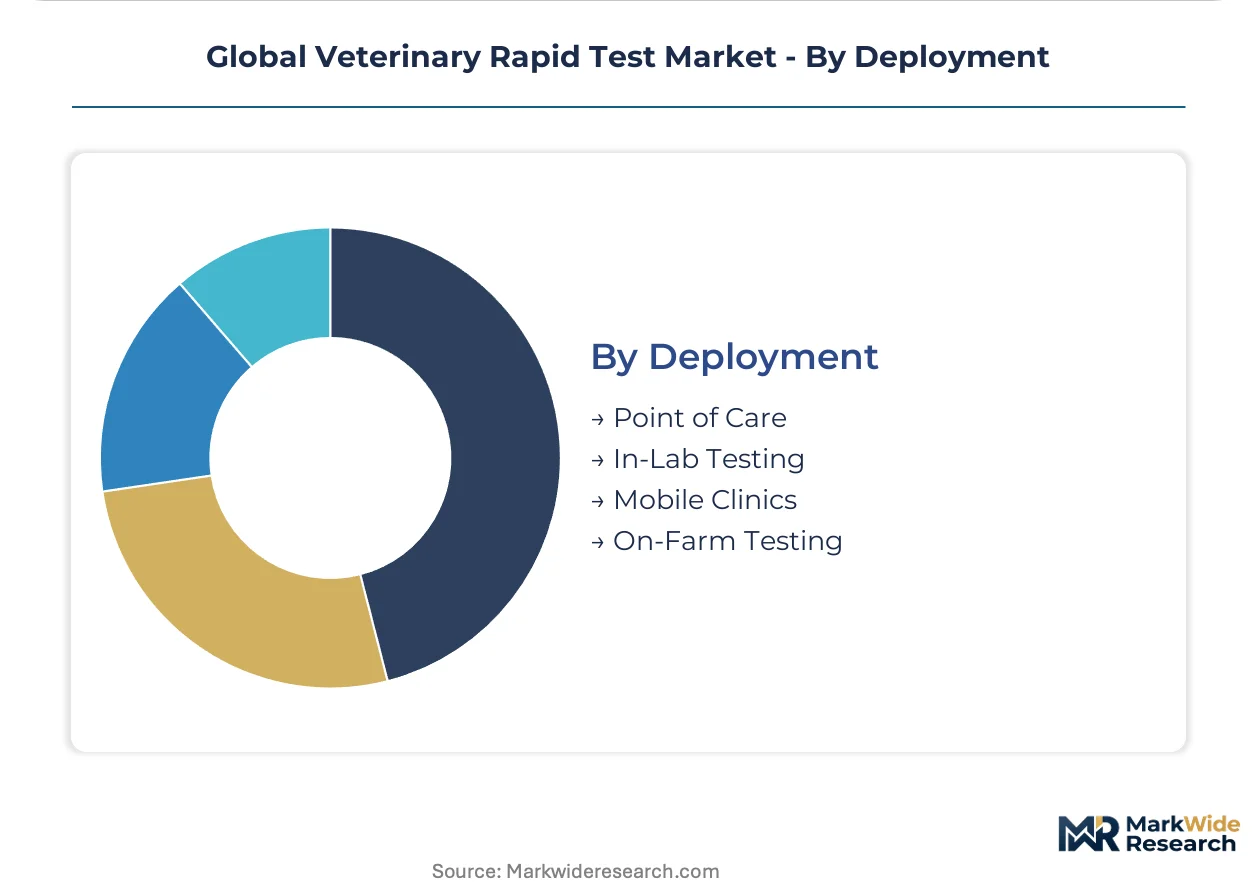
- Point of Care:In-clinic testing with immediate result integration into electronic medical records. United States and German companion animal practices prioritize WiFi-enabled readers that auto-populate patient files and trigger prescription workflows.
- On-Farm Testing:Large-animal practitioners in Argentina and New Zealand deploy weatherproof kits with extended temperature stability for field conditions. Mobile refrigeration and solar charging accessories extend operational range beyond grid-dependent facilities.
- In-Lab Testing:Controlled environment processing with batch validation and quality control documentation for regulatory submission.
- Mobile Clinics:Vehicle-based vaccination and screening programs in rural United States counties and Australian station properties.
Point of care dominates value capture; on-farm testing is gaining share fastest on large-animal service model transformation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The veterinary rapid test industry traces its commercial origins to the United States, where companion animal clinic consolidation first created procurement scale for point-of-care diagnostics. European and Asia-Pacific markets subsequently developed distinct regulatory pathways that now shape manufacturer market entry strategies.
United States
Corporate veterinary group consolidation has compressed procurement cycles across multi-site clinic networks spanning Texas, California, and the Midwest. FDA Center for Veterinary Medicine oversight of assay validation claims creates compliance barriers that favor established technical file documentation. Greater Boston and Research Triangle Park host reference laboratory clusters that demand ISO 17025-traceable correlation data for rapid test equivalence.
Germany
Companion animal clinics in Bavaria and North Rhine-Westphalia are expanding point-of-care testing menus for canine and feline infectious diseases. EU IVDR notified body conformity assessment elevates quality barriers for CE marking across member states. Stuttgart and Munich industrial corridors concentrate manufacturing scale for private-label rapid test supply into Western European distribution channels.
France
Dairy cooperatives in Brittany and Normandy mandate on-farm antibiotic residue screening before tanker collection to prevent EU MRL batch rejection. ANSM oversight of clinical evidence requirements extends conformity assessment timelines for devices seeking market access. Lyon and Paris veterinary school clusters drive species-validated assay modifications for non-domestic host antibody detection.
Brazil
Livestock operations across São Paulo and Minas Gerais require dust-resistant, battery-operated lateral flow formats for pen-side screening without veterinary staff present. ANVISA regulatory pathways for veterinary diagnostics present white space for manufacturers with established CE marking to leverage technical documentation. Campinas and São Paulo research institutes utilize rapid assays for preliminary pharmaceutical field trial screening.
Australia
Cattle and sheep stations in New South Wales and Queensland deploy weatherproof kits with extended temperature stability for field conditions beyond grid-dependent facilities. TGA alignment with ISO 17025 accreditation requirements for reference laboratories creates downstream demand pull for traceable method equivalence. Sydney and Melbourne diagnostic laboratory clusters standardize procurement of cloud-connected readers with unified result databases.
Global Veterinary Rapid Test Market Competitive Landscape
Premium-margin players sit above commodity-margin players across assay chemistry sophistication and digital connectivity integration. The vendor base organizes into three tiers: integrated pharmaceutical-diagnostic conglomerates, standalone diagnostics specialists, and private-label contract manufacturers. Strategic archetypes include platform bundlers locking in recurring consumable revenue, chemistry innovators defending proprietary detection methods, and scale operators supplying distributor house brands. Dominant competitive moves encompass M&A for assay portfolio expansion and backward integration into colloidal gold raw material supply.
Within the integrated pharmaceutical-diagnostic tier, Zoetis and IDEXX Laboratories exemplify platform bundlers that compress buyer evaluation into single-vendor decisions. Virbac represents the European specialist archetype with companion animal health concentration. Thermo Fisher Scientific anchors the manufacturing scale tier, supplying private-label rapid tests to third-party distributors. Neogen Corporation occupies a position bridging livestock diagnostics with food safety screening applications.
| Leading Market Players |
|---|
| Zoetis |
| IDEXX Laboratories |
| Virbac |
| Heska Corporation |
| Thermo Fisher Scientific |
| Neogen Corporation |
| Biopanda Reagents |
| Fassisi GmbH |
| BioNote |
| Others |
Supply & Pricing Matrix
Fluorescent microsphere detection technology is automating quantitative result interpretation and simultaneously compressing per-test manufacturing costs while concentrating production scale among vendors with capital-intensive reader platform investments. This chemistry transition rewards integrated assay-reader bundling that locks clinics into recurring consumable commitments, reshaping how procurement budgets allocate between upfront hardware and ongoing test cartridge expenditure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates cloud-connected integrated platforms from standalone lateral flow kits and unbranded private-label strips. Premium tiers command certification-grade markups for EU IVDR-notified body documentation and FDA Center for Veterinary Medicine technical files, while economy positioning serves Brazilian livestock farms with minimal regulatory documentation. Cost compression in the standard tier is intensifying because molecular diagnostic platforms are capturing premium positioning through superior specificity, forcing immunoassay manufacturers to absorb margin erosion. Corporate veterinary groups in the United States exhibit the lowest price sensitivity due to volume-based contracting leverage, whereas independent companion animal practices in France remain most responsive to per-unit test costs.
Supply Chain Analysis
Domestic-content mandates in Brazil and India are reshaping sourcing patterns for regional distribution, compelling manufacturers to establish local assembly operations or forfeit government procurement eligibility. Colloidal gold nanoparticle production concentrates in China and the United States, with membrane substrate fabrication anchored in Germany and Japan. Raw material dependencies span gold salt precursors, nitrocellulose membranes, and fluorescent microsphere beads. Single-source vulnerability in gold nanoparticle supply exposes test manufacturers to price volatility when mining output fluctuates. Distribution runs through third-party veterinary distributors in North America and direct sales forces in Western Europe, with livestock-focused markets in Australia and Brazil favoring agricultural supply cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where manufacturers with established EU IVDR technical files can leverage equivalent documentation for accelerated ANVISA registration in Brazil, capturing margin premiums before local competitors achieve conformity assessment.
For Market Incumbents: To counter molecular diagnostic substitution in companion animal specialty clinics, incumbents must deepen backward integration into colloidal gold raw material supply and accelerate multiplex assay development to match nucleic acid amplification panel breadth. Channel control through exclusive distribution agreements with corporate veterinary groups in the United States remains essential for locking in recurring consumable revenue against emerging platform bundlers. For New Entrants and Emerging Players: CRISPR-based isothermal amplification kits present a technology-first wedge for penetrating Japanese and German companion animal specialty clinics where pathogen-specific identification commands premium pricing. White-space concentration appears in Brazilian livestock extension, where ANVISA regulatory pathways favor entrants with pre-existing CE marking. A go-to-market angle partnering with agricultural supply cooperatives for pen-side lateral flow deployment bypasses established veterinary distributor relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among private-label contract manufacturers lacking integrated reader platforms or pharmaceutical portfolios. Long-term viability over the coming decade hinges on cloud connectivity subscription revenue models displacing transactional test kit sales. Acquisition targets should display notified body certification depth across multiple geographies. The signal to watch is corporate veterinary group procurement standardization velocity, which determines consumable lock-in potential for platform bundlers.| Strategic Initiative | Industry Significance |
|---|---|
| EU IVDR Notified Body Certification | CE marking technical files unlock market access across Germany, France, and Netherlands. |
| Cloud-Connected Reader Platform Launch | WiFi-enabled result transmission enables subscription revenue beyond hardware sales. |
| Multiplex Assay Portfolio Expansion | Single-cartridge pathogen panels match molecular diagnostic specificity in companion animal clinics. |
| Backward Integration into Gold Nanoparticle Supply | In-house colloidal gold production mitigates raw material price volatility exposure. |
| ANVISA Regulatory Pathway Acceleration | Brazilian livestock market entry leverages existing CE marking documentation for faster approval. |
Research Methodology
Multiple input streams — regulatory filing analysis, procurement database extraction, and field-level stakeholder dialogue — were reconciled to construct market estimates. Primary interviews captured perspectives from veterinary diagnostic product managers, clinic network procurement directors, reference laboratory quality officers, and agricultural cooperative supply managers. Secondary validation drew from FDA Center for Veterinary Medicine 510(k) summaries, EU IVDR notified body certification registries, TGA veterinary device listings, and ANVISA regulatory submission databases. Bottom-up unit demand modeling and top-down revenue triangulation were cross-checked for convergence.
Data-stream reconciliation applied analytical frameworks across the projection horizon without year-specific anchoring. Segmentation dimensions encompassed detection chemistry, signal amplification method, target pathogen panel, end-user procurement sophistication, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to normalized base-year estimates, incorporating veterinary service model transformation rates and corporate group consolidation trajectories as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU IVDR implementation delays, gold commodity price spikes, and molecular diagnostic platform cost curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Canine Separation Anxiety Treatment Market
Veterinary
Bovine Mastitis Market
Veterinary
Global Veterinary Monitoring Equipment Market
Veterinary
Veterinary Vaccines Market
Veterinary
Global Equine Supplement Products Market
Veterinary
Veterinary Antimicrobial Susceptibility Testing Market
Veterinary
US Surgical Pet Collar Market
Veterinary
Mexico Veterinary Healthcare Market
Veterinary
Feline Atopic Dermatitis Treatment Market
Veterinary
CBD Pet Market
Veterinary
Veterinary Clostridium Vaccine Market
Veterinary
Spay and Neuter Market
Veterinary
Veterinary Faecal Filters Market
Veterinary
Mastitis Market
Veterinary
Pet Cancer Therapeutics Market
Veterinary
Global Swine Vaccines Market