
 Integrated Video Surveillance Systems Market | 2026-2036
Integrated Video Surveillance Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Integrated Video Surveillance Systems Market Analytics
4K resolution and AI-enhanced analytics tiers is redrawing procurement standards across municipal and enterprise buyers. Hangzhou Hikvision Digital Technology Co., Ltd. leverages its vertically integrated sensor manufacturing to dominate mid-market camera volumes. Axis Communications AB differentiates through open-platform architecture that sustains third-party software integration. Bosch Security Systems anchors European premium installations with cybersecurity-hardened edge devices.
Integrated video surveillance systems combine networked cameras, storage infrastructure, and video management software to enable real-time monitoring, forensic search, and automated threat detection across distributed sites. These systems typically process video streams at 30 frames per second with H.265 compression to balance storage efficiency against forensic clarity. IP Cameras command the largest revenue share as analog infrastructure ages out of enterprise and government estates. AI Analytics represents the fastest-expanding technology segment, with edge-based inference reducing bandwidth costs and cloud latency for real-time alerting. Cloud-based Solutions are gaining traction among multi-site retail operators seeking centralized policy management without on-premise server maintenance.
FCC equipment authorization governs radio-frequency transmission in US surveillance hardware, while the EU AI Act imposes risk-classification obligations on biometric identification systems sold across member states. India's BIS certification mandates electromagnetic compatibility testing for all imported security electronics, creating a compliance gateway for international vendors. Stakeholders must weigh sovereign data residency requirements against cloud analytics scalability when architecting cross-border deployment strategies.
Market Dynamics
Edge AI inference is fragmenting the traditional centralized video analytics architecture, forcing vendors to redistribute compute loads between camera, gateway, and cloud tiers while managing latency-sensitive applications.
Growth Catalysts
- Smart city infrastructure mandates:Southeast Asian metropolitan centers in Vietnam, Indonesia, and Thailand are accelerating procurement of AI-enabled camera networks for traffic management and public safety modernization.
- GDPR and EU AI Act compliance frameworks:European biometric identification deployments now require risk-classification documentation, creating certified vendor preference effects across municipal tenders.
- H.265 and H.266 codec transitions:Compression efficiency gains are reducing storage infrastructure costs for multi-site retail and logistics operators managing thousands of camera streams.
Market Restraints
- Sensor supply concentration:CMOS image sensor fabrication concentrates among Taiwanese and South Korean foundries, exposing camera OEMs to geopolitical disruption risks.
- GDPR biometric consent requirements:European facial recognition deployments face operational friction from explicit consent mandates in public spaces, limiting automated identification use cases.
- Edge device thermal constraints:On-camera AI inference at 30 frames per second generates heat dissipation challenges that degrade processor longevity in outdoor installations.
Strategic Opportunities
- India urban security modernization:Delhi, Mumbai, and Bangalore municipal corporations are tendering large-scale camera network upgrades with domestic manufacturing preference clauses under PLI scheme incentives.
- Cloud-native video management platforms:Multi-site retail operators are adopting centralized policy management without on-premise server maintenance, displacing traditional VMS licensing models.
- Convergence of radar and video analytics:Perimeter security applications are integrating millimeter-wave detection with visual verification to reduce false alarm rates in critical infrastructure protection.
Industry Challenges
- Embedded systems firmware security:Edge camera vulnerabilities require continuous patch management across distributed estates with limited IT staffing at remote sites.
- BIS electromagnetic compatibility certification:International vendors face 12-18 month approval timelines for Indian market entry, compressing product refresh cycles against competitor offerings.
- Legacy analog infrastructure integration:Hybrid deployments must bridge coaxial cable plant with IP backhaul, complicating bandwidth planning and power-over-ethernet retrofit economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Integrated Video Surveillance Systems Market |
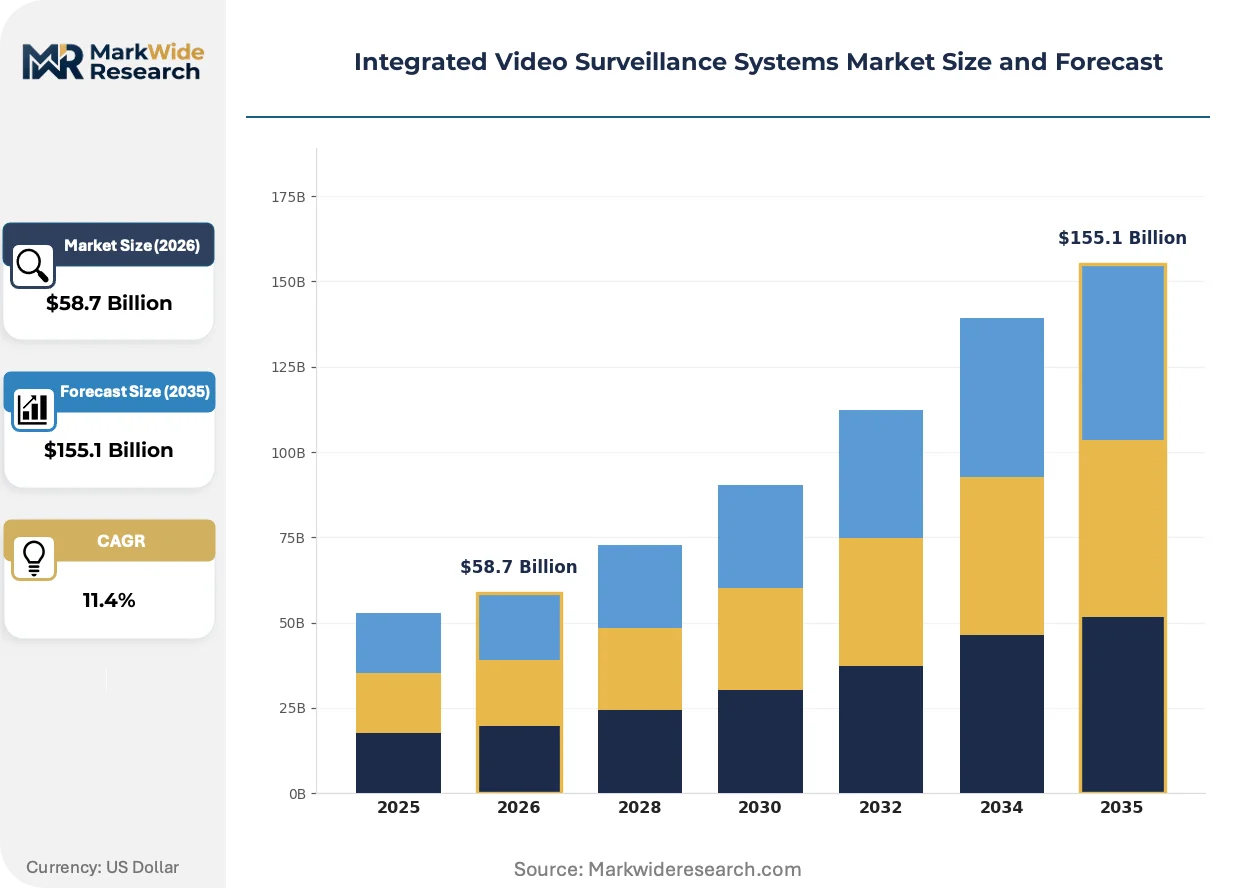
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $155.1 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Cameras, IP Cameras, Hybrid Systems, Video Recorders Technology: Cloud-based Solutions, On-premise Solutions, AI Analytics, Edge Computing End User: Retail Stores, Government Facilities, Transportation Hubs, Residential Areas Installation: Indoor Systems, Outdoor Systems, Mobile Units, Integrated Solutions |
| Companies Covered | Hangzhou Hikvision Digital Technology Co., Ltd., Dahua Technology Co., Ltd., Axis Communications AB, Honeywell International Inc., Hanwha Vision Co., Ltd., Motorola Solutions, Inc., Bosch Security Systems, Genetec Inc., Teledyne FLIR LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Integrated Video Surveillance Systems Market Evolving Landscape
Video surveillance technology is undergoing three simultaneous transitions: compute redistribution toward edge devices, regulatory fragmentation of biometric deployment rules, and procurement model unbundling of hardware from software services.
Edge-based AI inference is fragmenting the traditional cloud-centric analytics model. On-camera processors now execute real-time object detection and behavioral classification without continuous stream transmission to central servers. Municipal traffic management authorities in Singapore and Dubai are deploying these capabilities at intersection scale. This redistribution is compressing bandwidth costs while creating new vendor competition between semiconductor suppliers and traditional camera manufacturers.
The EU AI Act risk-classification framework is reshaping biometric system deployment protocols across European member states. High-risk designation for real-time remote identification in publicly accessible spaces imposes conformity assessment obligations before market placement. German and French municipal police procurement tenders now require explicit algorithmic impact documentation. Vendors are responding by segmenting product portfolios between biometric-capable and privacy-preserving variants.
Buyers are unbundling hardware acquisition from software subscription commitments. Large retail chains in the United States are negotiating camera purchases separately from video management platform licenses, then selecting cloud analytics providers through competitive tender. This disintermediation is eroding traditional integrated system margins. The pattern is most visible among multi-site operators with centralized security operations centers seeking vendor flexibility.
Integrated Video Surveillance Systems Market Segmentation
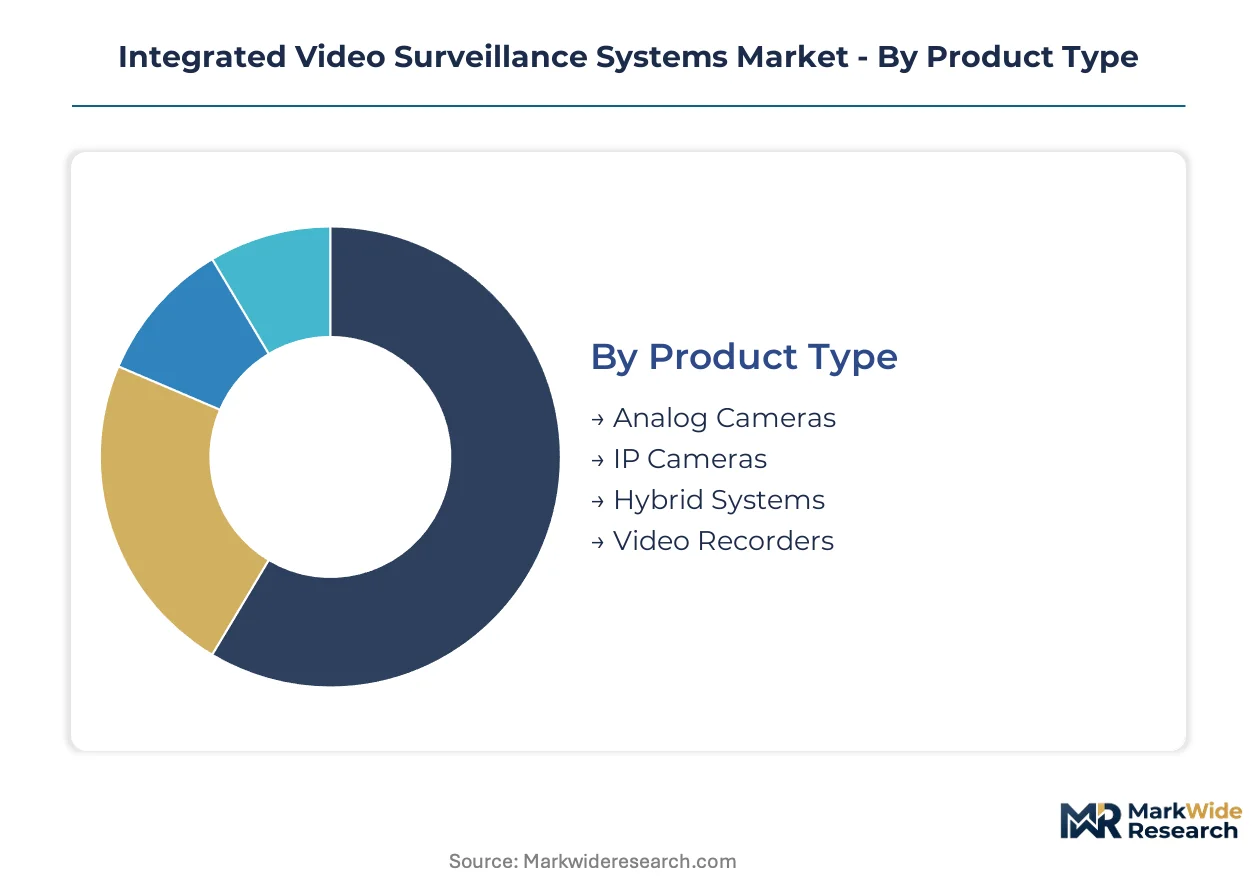
Video surveillance procurement splits across four dimensions that determine system architecture, compliance obligations, and total cost of ownership. Buyers weight these categories differently based on site criticality, data residency requirements, and legacy infrastructure constraints.
Product Type:
Margin pools concentrate in IP camera hardware and hybrid transition systems as analog replacement cycles accelerate across enterprise estates.
- IP Cameras:Network-addressable devices deliver H.265 compressed streams at 30 frames per second with Power-over-Ethernet connectivity. Demand clusters in India's urban security modernization programs across Delhi, Mumbai, and Bangalore where municipal tenders specify ONVIF-compliant interoperability.
- Hybrid Systems:Bridge architectures accommodate coaxial cable plant while enabling IP backhaul for gradual infrastructure migration. Southeast Asian commercial developers favor these configurations to preserve existing wiring investments during smart city retrofits.
- Analog Cameras:Legacy CVBS output devices persist in cost-constrained residential and small retail deployments.
- Video Recorders:NVR and DVR appliances provide local storage redundancy for sites with intermittent cloud connectivity.
IP Cameras holds installed capacity. Hybrid Systems is rotating up the share rankings.
Technology:
Deployment models diverge sharply between bandwidth-intensive cloud architectures and latency-sensitive edge inference configurations.
- AI Analytics:Computer vision algorithms execute object detection, behavioral classification, and anomaly flagging across video streams. Singapore and Dubai traffic management authorities deploy these capabilities at intersection scale for real-time incident response.
- Cloud-based Solutions:Centralized video management platforms enable multi-site policy administration without on-premise server maintenance. US retail chains negotiate these subscriptions separately from hardware procurement to preserve vendor flexibility.
- Edge Computing:On-camera processors reduce bandwidth costs and cloud latency for time-sensitive alerting applications.
- On-premise Solutions:Local VMS deployments satisfy sovereign data residency requirements in European and Middle Eastern jurisdictions.
On-premise Solutions holds installed capacity. AI Analytics is climbing the fastest.
End User:
Application environments dictate camera specifications, retention policies, and integration complexity across facility types.
- Government Facilities:Critical infrastructure protection mandates cybersecurity-hardened edge devices with encrypted storage and firmware attestation. EU AI Act risk-classification obligations apply to biometric identification deployments in publicly accessible spaces.
- Transportation Hubs:Airports, seaports, and rail terminals require perimeter radar-video convergence and millimeter-wave detection for intrusion verification. India's BIS certification creates compliance gateways for international vendors supplying these installations.
- Retail Stores:Loss prevention and customer analytics drive demand for discreet dome cameras and cloud-native management platforms.
- Residential Areas:Gated communities and apartment complexes prioritize cost-optimized WiFi cameras with mobile app interfaces.
Government Facilities holds installed capacity. Transportation Hubs is gaining share fastest.
Installation:
Environmental exposure determines enclosure ratings, thermal management, and power delivery specifications.
- Outdoor Systems:Weather-sealed housings with IP66/67 ratings and integrated heaters sustain operation across temperature extremes. Edge AI inference at 30 frames per second generates heat dissipation challenges that degrade processor longevity in these deployments.
- Indoor Systems:Climate-controlled environments enable compact form factors and lower power consumption for office, retail, and hospitality applications.
- Mobile Units:Vehicle-mounted and trailer-based surveillance serves temporary event security and construction site monitoring.
- Integrated Solutions:Multi-sensor platforms combine visible, thermal, and radar modalities for unified threat detection.
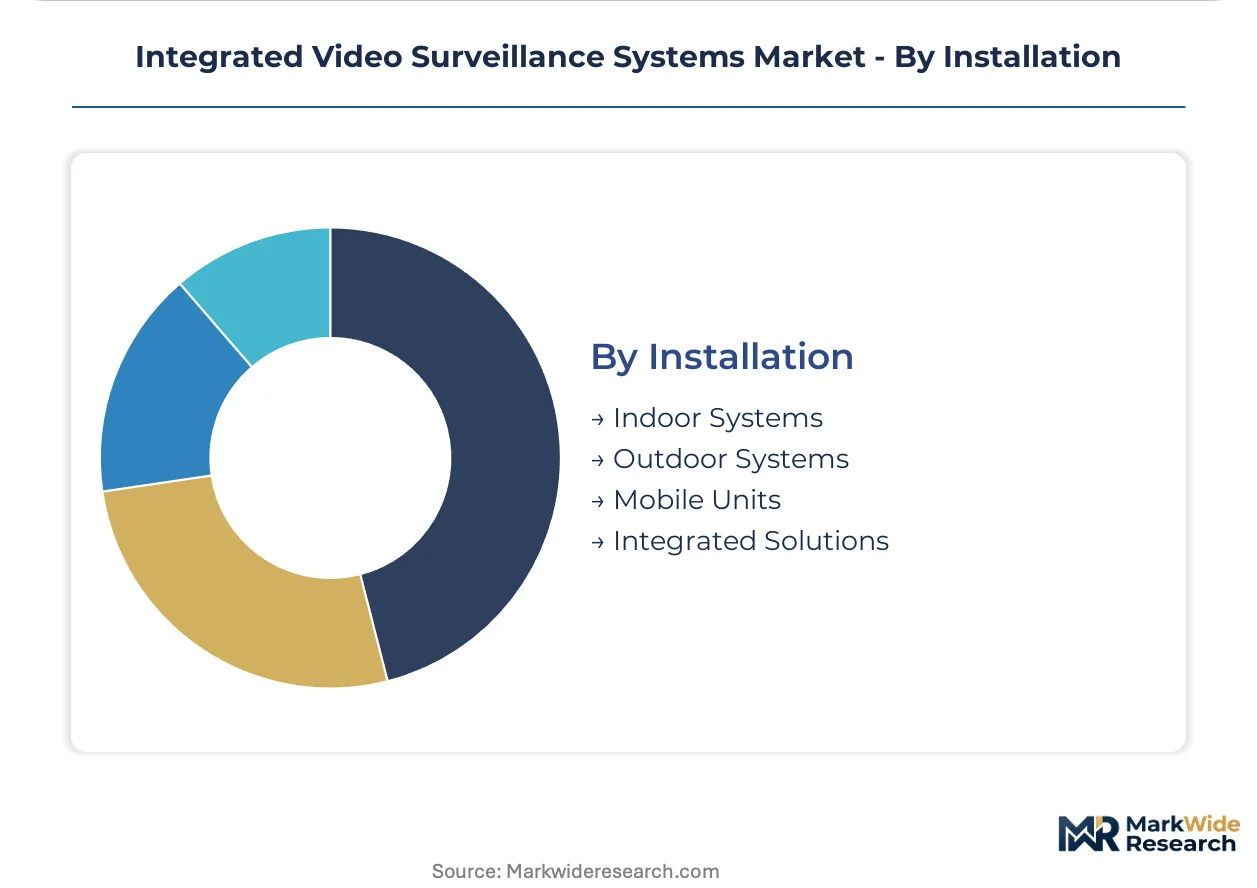
Indoor Systems holds installed capacity. Outdoor Systems is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from Chinese and Taiwanese camera manufacturers dominate international procurement, while import dependencies for CMOS sensors concentrate exposure in South Korean and Japanese foundries. European and Indian markets are tightening certification gateways, reshaping vendor access patterns.
United States
Federal smart city grants and critical infrastructure protection mandates drive municipal procurement of AI-enabled networks. FCC equipment authorization governs radio-frequency transmission in surveillance hardware, creating compliance filters for international suppliers. Deployment clusters concentrate in Texas urban corridors and California transportation hubs where edge analytics integration is accelerating.
China
Domestic security modernization and Belt and Road export financing sustain manufacturing scale. MIIT standards and GB certification frameworks regulate network security features in connected devices. Hangzhou and Shenzhen anchor production ecosystems where vertically integrated sensor-to-camera supply chains achieve cost compression.
India
Urban security tenders across Delhi, Mumbai, and Bangalore are expanding camera network density under municipal modernization programs. BIS certification mandates electromagnetic compatibility testing for all imported security electronics, creating 12-18 month approval timelines. Domestic manufacturing preference clauses under PLI scheme incentives are redirecting procurement toward local assembly operations.
Germany
Industrial facility protection and transportation infrastructure drive demand for cybersecurity-hardened edge devices. GDPR biometric consent requirements and EU AI Act risk-classification obligations impose conformity assessments on facial recognition deployments. Bavaria and North Rhine-Westphalia host the densest concentration of critical infrastructure sites requiring perimeter radar-video convergence.
Singapore
Smart nation traffic management and public safety digitization programs deploy intersection-scale AI analytics. The national cybersecurity agency mandates supply chain attestation for government surveillance contracts. Deployment intensity clusters in the central business district and port terminals where real-time incident response capabilities are operational priorities.
Integrated Video Surveillance Systems Market Competitive Landscape
Concentration sits with diversified electronics conglomerates and specialized security technology firms competing across hardware, software, and integration service layers. The vendor base stratifies between scale-driven manufacturers with captive component supply and niche specialists focused on open-platform interoperability. Three archetypes dominate: vertically integrated hardware producers, open-architecture software platform vendors, and cybersecurity-focused premium installers. Competitive moves center on backward integration into semiconductor sourcing and strategic partnerships with cloud analytics providers to unbundle traditional system offerings.
Among Chinese manufacturers, Hangzhou Hikvision Digital Technology Co., Ltd. and Dahua Technology Co., Ltd. exemplify scale-driven archetypes with integrated production capabilities. Axis Communications AB occupies a position representing open-platform specialists prioritizing third-party software interoperability. These three anchors illustrate the structural tension between closed hardware-software bundles and modular procurement patterns gaining traction among enterprise buyers.
| Leading Market Players |
|---|
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Dahua Technology Co., Ltd. |
| Axis Communications AB |
| Honeywell International Inc. |
| Hanwha Vision Co., Ltd. |
| Motorola Solutions, Inc. |
| Bosch Security Systems |
| Genetec Inc. |
| Teledyne FLIR LLC |
| Others |
Value Network & Pricing Analysis
H.265-to-H.266 codec migration is redistributing value capture from storage infrastructure vendors toward compression-technology licensors while compressing bandwidth economics for multi-site operators. This transition simultaneously concentrates licensing revenue with standards-essential patent holders and erodes hardware-based storage margins across municipal and enterprise procurement.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in integrated video surveillance systems. Price differentiation hinges on cybersecurity certification tier—UL 2900-1 versus IEC 62443-4-2 compliance—and volume scale commitments from multi-site retail operators. Cost compression in economy camera tiers is intensifying because Chinese manufacturers with captive sensor production are exporting at compressed margins. Government facilities demonstrate lowest price sensitivity due to mandate-driven procurement timelines, while small residential installers exhibit highest elasticity to per-unit hardware costs.
Supply Chain Analysis
Taiwan and South Korea anchor CMOS image sensor wafer fabrication for surveillance camera OEMs. Camera assembly draws from Chinese printed circuit board manufacturing and Japanese optical lens grinding, with final integration concentrating in Shenzhen and Hangzhou production ecosystems. Single-source vulnerability sits with Taiwanese foundry concentration for advanced node sensors, exposing procurement timelines to geopolitical disruption. Distribution runs through regional security integrators and direct municipal tender channels, with cloud-native platforms disintermediating traditional hardware-software bundle vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edge AI firmware engineering talent scarcity constrains vendor differentiation in real-time analytics, compressing competitive advantage to semiconductor partnerships and thermal management IP. The capability gap between inference-optimized camera architectures and legacy centralized systems is widening faster than specialist hiring pipelines can fill.
For Market Incumbents: Compound defensive moats through backward integration into sensor design and exclusive foundry capacity commitments at Taiwanese fabs. Threat from open-platform software vendors displacing hardware-software bundles demands accelerated R&D in on-camera thermal dissipation solutions. Certification investment in EU AI Act conformity assessment procedures anchors municipal tender preference in European markets. For New Entrants and Emerging Players: Cloud-native video management platform gaps in mid-market retail chains present white-space opportunities where incumbents under-serve with legacy on-premise licensing. India's BIS certification bottlenecks create penetrable entry barriers for domestic assembly partnerships under PLI scheme incentives. Go-to-market execution should prioritize channel partnerships with regional security integrators over direct municipal sales cycles. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed video analytics software platforms lacking hardware integration capabilities. Five-to-ten year viability framing favors vendors with edge compute IP and sovereign cloud deployment credentials. The signal to watch is BIS certification timeline compression for Indian market access, indicating regulatory arbitrage opportunities for compliant entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Processor Development | On-camera inference capabilities reduce bandwidth costs for Singapore traffic management authorities. |
| EU AI Act Certification Investment | Conformity assessment documentation unlocks German and French municipal police procurement tenders. |
| Domestic Assembly Partnership | PLI scheme incentives redirect Indian urban security tenders toward local manufacturing operations. |
| Cloud-Native Platform Launch | Centralized policy management displaces traditional VMS licensing for US retail chain operators. |
| Thermal Management IP Acquisition | Heat dissipation solutions extend processor longevity in outdoor edge AI deployments. |
Research Methodology
Operator-level perspectives from municipal security procurement officers, cloud platform engineering leads, regional systems integrators, and edge semiconductor product managers anchored the qualitative base. Primary interview data combined with secondary validation from FCC equipment authorization databases, EU AI Act implementation guidance, Indian BIS certification registries, and customs trade records. Bottom-up camera shipment estimates and top-down infrastructure spending projections were triangulated to constrain forecast variance.
Sensitivity analysis across the analysis window tested demand elasticity to municipal budget cycles, codec transition timelines, and biometric deployment regulatory shifts. Segmentation dimensions modeled include product architecture, deployment topology, end-use facility criticality, and environmental exposure rating. CAGRs were derived from installed base replacement curves and greenfield smart city procurement pipelines, with inputs from H.266 adoption trajectories and edge inference cost curves.
Forecasts assume regulatory continuity in FCC equipment authorization, EU AI Act risk-classification frameworks, and Indian BIS electromagnetic compatibility regimes; material policy shifts would require re-modeling. Recalibration cycles align with material shifts in municipal tender award patterns and foundry capacity allocation announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
AI Surveillance System Market
Video Surveillance Systems
Smart Home Security Camera Market
Video Surveillance Systems
North America Surveillance Analog Camera Market
Video Surveillance Systems
Asia-Pacific Surveillance Analog Camera Market
Video Surveillance Systems
Night Vision Camera Market
Video Surveillance Systems
Camera Alarm System Market
Video Surveillance Systems
United Kingdom Surveillance Analog Camera Market
Video Surveillance Systems
India Surveillance Analog Camera Market
Video Surveillance Systems
India Surveillance Camera Market
Video Surveillance Systems
China Surveillance Analog Camera Market
Video Surveillance Systems
China Video Surveillance Market
Video Surveillance Systems
Video Surveillance As a Service Market
Video Surveillance Systems
Cellular Interception Market
Video Surveillance Systems
Video Surveillance Market
Video Surveillance Systems
Asia-Pacific Surveillance Camera Market
Video Surveillance Systems
Wireless Home Security Camera Market