
 Japan Surveillance IP Cameras Market | 2026-2036
Japan Surveillance IP Cameras Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Surveillance IP Cameras Market Insights
Buyer concentration in Japan's surveillance IP camera market is shifting as municipal governments consolidate procurement through framework agreements while smaller retail chains fragment demand with cloud-managed deployments. Panasonic i-PRO Sensing Solutions Co., Ltd. leverages its domestic manufacturing footprint to anchor large-scale transportation contracts. Canon Inc. competes through imaging sensor specialization that sustains premium positioning in government tenders. Sony Corporation dominates CMOS sensor supply to third-party camera OEMs, extending its influence across the value chain.
Surveillance IP cameras in Japan are network-connected digital video capture devices transmitting compressed video streams over Ethernet or wireless protocols, typically supporting H.265 encoding, Power over Ethernet, and ONVIF interoperability for centralized management platforms. Their primary commercial purpose spans security monitoring, operational oversight, and automated incident detection across physical infrastructure. Dome cameras lead indoor commercial installations where discreet positioning matters, while PTZ cameras command premium pricing in transportation hubs requiring active operator control. Network technology continues displacing analog legacy systems, though hybrid configurations persist in hospitality retrofit projects where infrastructure replacement costs constrain full migration.
METI's cybersecurity guidelines for critical infrastructure shape procurement specifications, while JIS standards define environmental resilience ratings for outdoor installations exposed to Japan's seismic and typhoon risks. The Personal Information Protection Commission enforces data handling protocols that constrain cloud storage architectures and favor edge-processing designs. Stakeholders must monitor evolving encryption mandates and local data sovereignty interpretations as municipalities weigh centralized versus distributed system architectures.
Market Dynamics
Edge AI processing capabilities embedded directly into camera hardware are compressing bandwidth requirements and enabling municipal governments to deploy real-time analytics without centralized infrastructure dependency.
Growth Catalysts
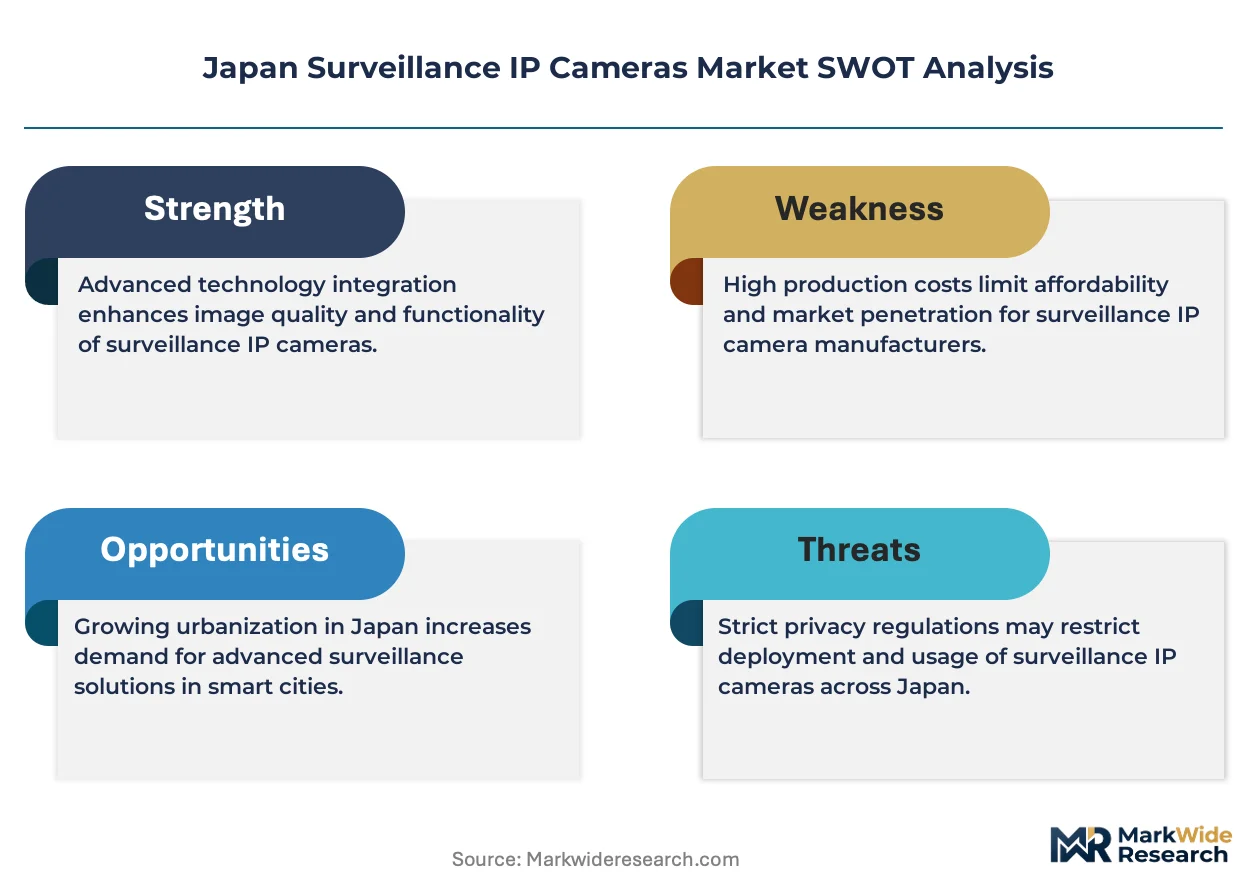
- METI Cybersecurity Guidelines:Procurement specifications for critical infrastructure mandate encrypted transmission protocols, accelerating replacement cycles in transportation and energy facilities.
- Seismic Resilience Mandates:JIS environmental ratings for outdoor installations drive demand for hardened enclosures in typhoon-prone coastal prefectures and earthquake-vulnerable zones.
- Cloud-Managed Deployments:Smaller retail chains fragment demand through subscription-based platforms, expanding addressable market beyond traditional enterprise buyers.
Market Restraints
- CMOS Sensor Supply Concentration:Domestic production capacity constraints create vulnerability to upstream component bottlenecks from specialized foundry partners.
- Data Sovereignty Interpretations:The Personal Information Protection Commission's evolving local storage requirements increase compliance costs for cloud-architected systems.
- Analog Legacy Infrastructure:Hospitality retrofit projects face capital barriers to full IP migration, perpetuating hybrid configurations with limited upgrade pathways.
Strategic Opportunities
- Osaka Industrial Corridor Modernization:Manufacturing security infrastructure upgrades present concentrated demand for integrated video-analytics platforms.
- Disaster Preparedness Networks:Municipal framework agreements for unified command centers create multi-year procurement pipelines with standardized specifications.
- ONVIF Interoperability Convergence:Open protocol adoption enables third-party software integration, expanding value capture beyond hardware margins.
Industry Challenges
- Edge-AI Engineering Talent Scarcity:Embedded computer vision expertise remains concentrated among semiconductor suppliers, constraining in-house development timelines.
- Certification Timeline Compression:JIS testing protocols for environmental resilience extend product launch cycles, delaying revenue recognition for new form factors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Surveillance IP Cameras Market |
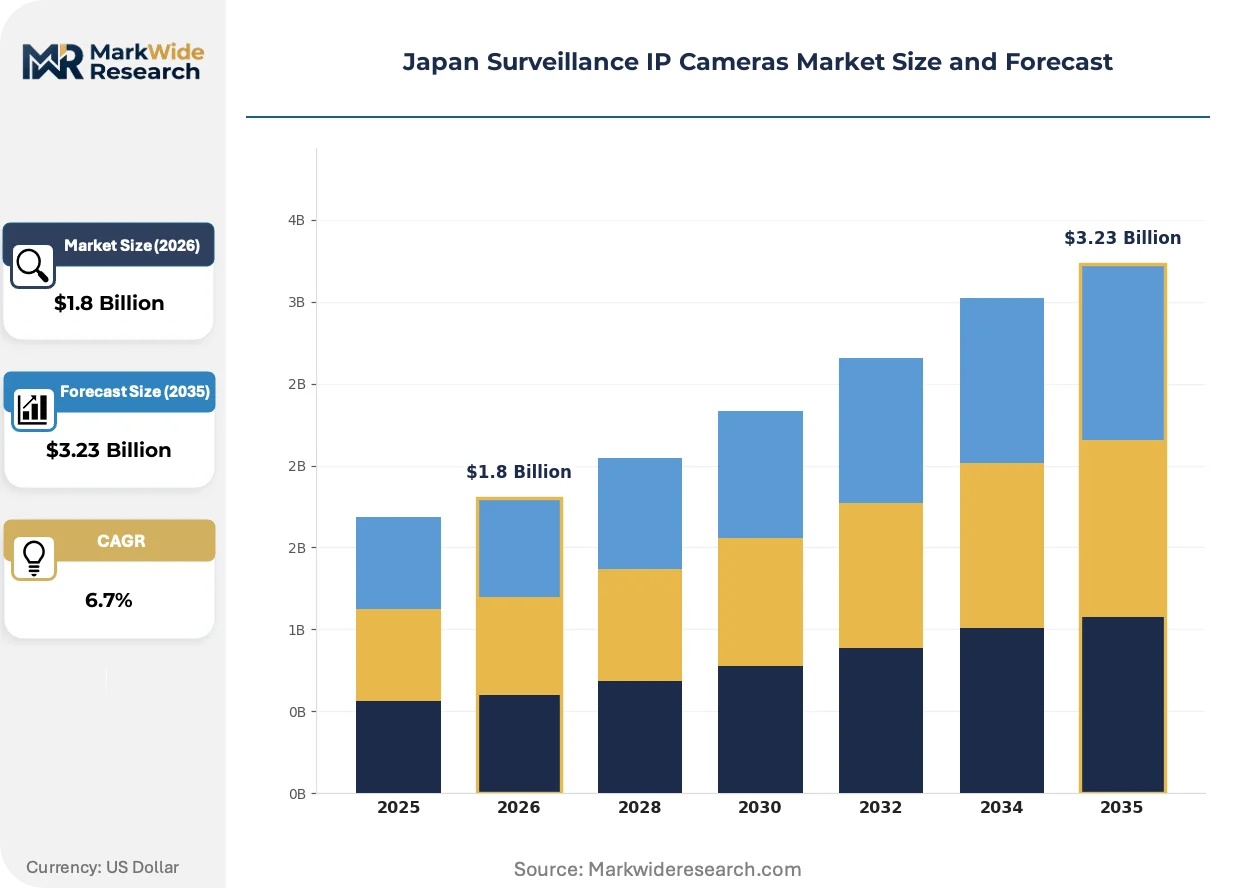
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Box Cameras, Dome Cameras, PTZ Cameras, Bullet Cameras Technology: Analog, Network, Wireless, Hybrid End User: Retail, Hospitality, Transportation, Government Installation Type: Indoor, Outdoor, Covert, Portable |
| Companies Covered | Hangzhou Hikvision Digital Technology Co., Ltd., Canon Inc., Sony Corporation, Safie Inc., NEC Corporation, Panasonic i-PRO Sensing Solutions Co., Ltd., Dahua Technology Co., Ltd., Bosch Security Systems B.V., Japan Security System Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Surveillance IP Cameras Market Trends and Innovations
Hardware-software convergence is redefining competitive differentiation as processing migrates from centralized servers to camera endpoints, compressing total cost of ownership for large-scale deployments.
H.265 encoding is overtaking H.264 compression in municipal transportation contracts, reducing storage overhead by half while maintaining forensic image quality. Tokyo Metropolitan Government's subway network has standardized on this codec for its platform surveillance refresh. The bandwidth savings are overtaking infrastructure upgrade budgets toward analytics software procurement rather than network expansion.
METI's cybersecurity guidelines for critical infrastructure are reshaping procurement specifications across energy and transportation sectors, mandating end-to-end encryption and hardware-rooted security modules. Camera OEMs must now certify compliance through third-party penetration testing before framework agreement eligibility. Municipal buyers in Kansai and Chubu regions have delayed awards pending vendor certification completion.
Framework agreement consolidation is concentrating procurement authority among prefectural governments, displacing fragmented municipal purchasing. Smaller municipalities in Hokkaido and Kyushu now access pre-negotiated terms through regional cooperative purchasing bodies. This aggregation is compressing vendor margins while extending contract durations and technical support obligations.
Japan Surveillance IP Cameras Market Segmentation
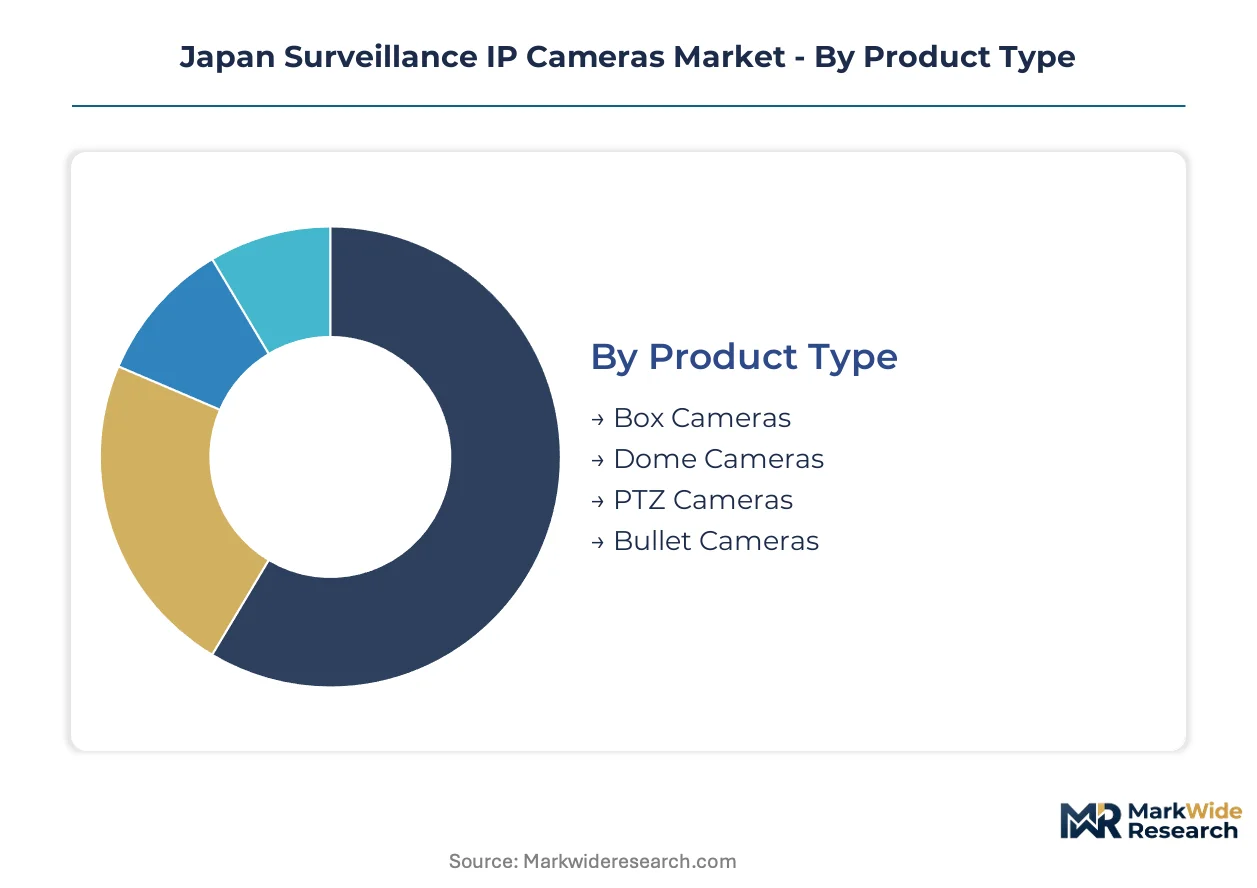
Segmentation in Japan's surveillance IP camera market reveals how procurement authority, environmental exposure, and network architecture reshape vendor priorities. Buyers diverge sharply across municipal framework agreements, industrial security mandates, and hospitality retrofit constraints.
Product Type:
Dome cameras and PTZ units command premium positioning through divergent deployment economics and operator interaction models.
- Dome Cameras:Enclosed hemispherical housings with vandal-resistant polycarbonate domes enable discreet ceiling mounting in retail corridors and hotel lobbies. Tokyo's dense commercial districts favor these units for aesthetic integration where visible security infrastructure conflicts with brand environments.
- PTZ Cameras:Motorized pan-tilt-zoom mechanisms with optical zoom ranges exceeding 30x allow active operator tracking across transportation platforms and perimeter zones. Osaka's industrial security teams deploy these for real-time incident response where human oversight remains mandatory.
- Box Cameras:Modular lens-interchangeable bodies suit custom focal length requirements in legacy analog retrofit scenarios.
- Bullet Cameras:Weather-sealed cylindrical housings with integrated IR illumination target cost-sensitive outdoor perimeter applications.
Volume sits with dome cameras; growth tilts toward PTZ units.
Technology:
Network architecture choices fragment across infrastructure replacement cycles and bandwidth availability rather than pure feature differentiation.
- Network:Ethernet-based digital transmission with H.265 encoding and ONVIF protocol support enables centralized management platforms. Municipal governments in Kansai and Chubu regions specify these for unified command center integration where multi-vendor interoperability is non-negotiable.
- Wireless:Wi-Fi 6 and private 5G connectivity eliminate cabling constraints in heritage building retrofits and temporary event deployments. Coastal prefectures facing typhoon damage leverage these for rapid infrastructure restoration where fiber restoration timelines extend weeks.
- Analog:Coaxial-based legacy systems persist in hospitality properties where full IP migration capital costs exceed operational budgets.
- Hybrid:Dual-protocol encoders bridge analog camera investments with network recording platforms, extending upgrade pathways for phased capital deployment.
Network technology captures dominant volume; wireless configurations gain share fastest in disaster-preparedness applications.
End User:
Procurement scale and compliance intensity separate municipal buyers from fragmented commercial operators.
- Government:Prefectural framework agreements with METI cybersecurity certification requirements and JIS environmental resilience mandates. Multi-year procurement pipelines concentrate in transportation authorities and disaster management agencies.
- Transportation:Subway operators and airport authorities demanding PTZ control integration with access management systems and real-time passenger analytics.
- Retail:Cloud-managed subscription platforms enable smaller chains to bypass capital expenditure barriers through operational expenditure models.
- Hospitality:Hybrid analog-network configurations dominate where aesthetic constraints and infrastructure replacement costs limit full IP adoption.
Government verticals anchor procurement volume; transportation analytics deployments show steepest expansion trajectory.
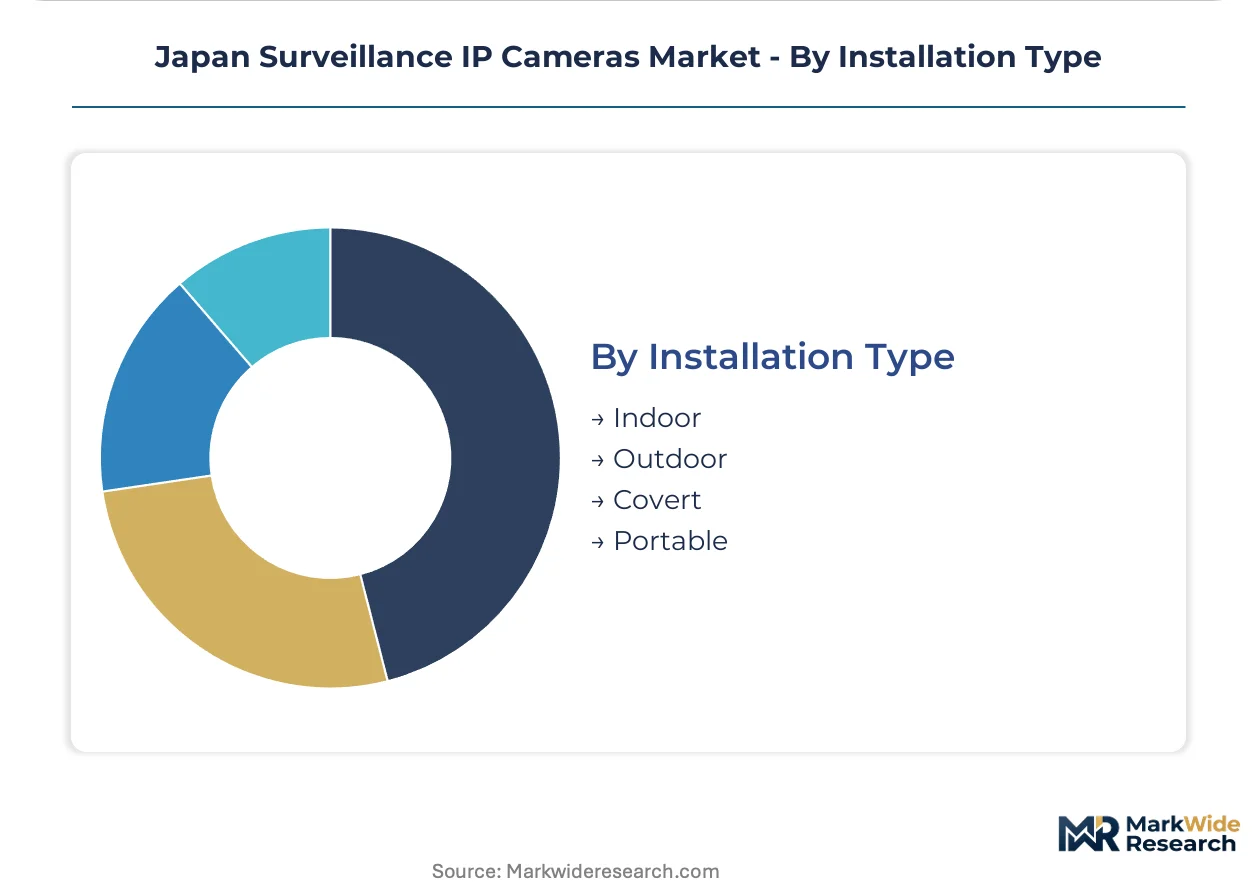
Installation Type:
Environmental exposure ratings and concealment requirements drive specification divergence more than pure imaging performance.
- Outdoor:IP66+ ingress protection with JIS seismic ratings and extended temperature operation for typhoon-prone coastal installations and earthquake-vulnerable zones.
- Indoor:Climate-controlled environments with PoE power delivery and discrete form factors for commercial and institutional settings.
- Covert:Miniaturized sensor packages concealed within environmental fixtures for loss prevention and investigative applications.
- Portable:Battery-powered rapid-deployment units for temporary event security and emergency response scenarios.
Outdoor installations dominate capital allocation; covert configurations expand in retail loss prevention programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Japan's major metropolitan corridors where municipal governments are consolidating procurement through framework agreements. Prefectural authorities in disaster-prone zones are accelerating video surveillance network expansion for public safety and emergency response capabilities.
Kanto/Tokyo
Tokyo Metropolitan Government's subway network standardization on H.265 encoding is reducing storage overhead while redirecting infrastructure budgets toward analytics software procurement. METI cybersecurity guidelines mandate end-to-end encryption for critical infrastructure tenders, compressing vendor certification timelines. Dense commercial corridors in Shinjuku and Shibuya favor dome cameras for aesthetic integration where visible security conflicts with brand environments.
Kansai/Osaka
Osaka's industrial security teams deploy PTZ cameras with 30x optical zoom for real-time incident response across manufacturing facilities and transportation hubs. JIS environmental resilience ratings govern outdoor installations in this typhoon-exposed coastal zone. The Osaka Industrial Corridor modernization is generating concentrated demand for integrated video-analytics platforms among manufacturing security infrastructure operators.
Chubu/Nagoya
Transportation authorities in Aichi Prefecture are integrating PTZ control systems with access management platforms for real-time passenger analytics. Municipal buyers have delayed procurement awards pending vendor completion of METI cybersecurity certification requirements. Nagoya's automotive manufacturing clusters are driving demand for hardened camera enclosures meeting seismic resilience mandates.
Kyushu
Smaller municipalities in Kyushu access pre-negotiated procurement terms through regional cooperative purchasing bodies, aggregating demand and compressing vendor margins. Cloud-managed subscription platforms are enabling smaller retail chains to bypass capital expenditure barriers. Fukuoka's commercial districts are fragmenting demand through operational expenditure models rather than traditional enterprise purchasing.
Hokkaido
Prefectural framework agreements are displacing fragmented municipal purchasing across Hokkaido's dispersed population centers. Edge AI processing capabilities are enabling deployment of real-time analytics without centralized infrastructure dependency in remote locations. Sapporo's disaster preparedness networks are creating multi-year procurement pipelines with standardized specifications for unified command centers.
Japan Surveillance IP Cameras Market Competitive Landscape
Japanese producers anchor the domestic tier; Chinese specialists hold scale-driven positions in component supply. The vendor base organizes around three strategic archetypes: domestic integrated manufacturers with transportation sector dominance, semiconductor suppliers extending influence across CMOS sensor value chains, and foreign specialists competing through imaging sensor differentiation. Competitive moves concentrate on framework agreement consolidation and cybersecurity certification completion.
Among domestic integrated manufacturers, Panasonic i-PRO Sensing Solutions Co., Ltd. and Canon Inc. exemplify the transportation and government tender archetype. Sony Corporation occupies a position representing semiconductor suppliers whose CMOS sensor production extends influence across third-party camera OEM value chains. Foreign specialists including Hangzhou Hikvision Digital Technology Co., Ltd. and Dahua Technology Co., Ltd. sit within the scale-driven tier competing on volume and cost efficiency.
| Leading Market Players |
|---|
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Canon Inc. |
| Sony Corporation |
| Safie Inc. |
| NEC Corporation |
| Panasonic i-PRO Sensing Solutions Co., Ltd. |
| Dahua Technology Co., Ltd. |
| Bosch Security Systems B.V. |
| Japan Security System Corporation |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists with deep ties to Japan's precision manufacturing clusters anchor component sourcing for surveillance IP cameras, translating captive production control into pricing discipline that resists commoditization pressure from volume-driven foreign competitors.
Pricing Analysis
Volume sits with economy-tier dome cameras for retail and hospitality retrofits, while margins concentrate in premium PTZ units certified for METI cybersecurity compliance and JIS seismic resilience. Three-tier pricing structure across premium, standard, and economy levels separates government framework agreement winners from fragmented commercial buyers. Cost compression in the standard tier is intensifying because Chinese specialists are flooding cloud-managed subscription platforms with feature-matched hardware. Municipal transportation authorities show least price sensitivity due to multi-year procurement pipelines with technical support obligations, while smaller retail chains in Kyushu and Hokkaido prioritize operational expenditure models over capital deployment.
Supply Chain Analysis
METI's local-content preferences for critical infrastructure procurement are reshaping sourcing patterns, favoring domestic assembly of edge-AI processing modules over pure import dependency. CMOS sensor fabrication rests on Taiwan and South Korea for advanced node production, while Japan maintains captive supply of specialized image signal processors and hardened enclosure materials. Raw material dependencies include rare-earth elements for lens coatings, copper for PoE cabling infrastructure, and polycarbonate resins for vandal-resistant dome housings. Single-source vulnerability concentrates in specialized foundry capacity for AI accelerator chips. Distribution runs through regional systems integrators with METI certification credentials who bridge camera OEMs and prefectural procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's surveillance IP camera market is executing a technology-transition phase as edge-AI processing displaces centralized server architectures, compressing total cost of ownership for municipal buyers while fragmenting competitive advantage across semiconductor and software domains.
For Market Incumbents: Acquire embedded computer vision engineering teams to close capability gaps with semiconductor suppliers who currently dominate AI accelerator design. Panasonic i-PRO and Canon must deepen backward integration into CMOS sensor packaging to defend margin position against Chinese volume competitors. Certification investment in METI cybersecurity compliance represents a critical lever for framework agreement eligibility as municipalities delay awards pending vendor completion.
For New Entrants and Emerging Players: The mid-tier price gap between premium government-certified PTZ units and economy retail dome cameras offers white-space entry for hybrid-protocol specialists targeting hospitality retrofit demand. Cloud-managed subscription platforms in Kyushu and smaller Hokkaido municipalities represent the most penetrable geography, where regional cooperative purchasing bodies have fragmented incumbent relationships. A software-first go-to-market angle emphasizing ONVIF interoperability and third-party analytics integration bypasses capital-intensive manufacturing scale requirements.
For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated mid-cap specialists with JIS certification assets and established prefectural transportation relationships in Kansai and Chubu regions. Long-term viability over a multi-year horizon hinges on securing position before framework agreement consolidation fully concentrates procurement authority. The signal to monitor is completion velocity of METI cybersecurity certifications, as delayed vendor approvals are currently freezing municipal award timelines and creating acquisition windows for qualified targets.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Hardware Integration | Embedded processing in camera endpoints reduces bandwidth costs for Tokyo Metropolitan Government deployments. |
| Backward Integration into Sensor Packaging | Domestic CMOS assembly capacity mitigates Taiwan foundry bottleneck exposure for critical infrastructure tenders. |
| Cloud-Managed Platform Launch | Subscription models unlock smaller retail chains in Kyushu bypassing capital expenditure barriers. |
| METI Cybersecurity Certification | Third-party penetration testing completion enables framework agreement eligibility for transportation sector contracts. |
| ONVIF Interoperability Partnership | Open protocol adoption expands software value capture beyond hardware margins for municipal buyers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across camera OEM product managers, prefectural procurement officers, transportation authority security directors, and systems integration specialists. METI cybersecurity guideline documents, JIS standard certification databases, and Personal Information Protection Commission enforcement records provided regulatory context. Bottom-up shipment estimates from component suppliers and top-down procurement budget analysis from municipal framework agreements were triangulated to validate market sizing.
Granularity-level modeling tracked product type, network architecture, end-user vertical, and installation environment across the projection horizon. Segment-level CAGRs were derived from installed base replacement cycles, edge-AI adoption curves, and framework agreement award timelines. Forecast inputs incorporated seismic resilience mandate compliance rates, H.265 encoding penetration in transportation contracts, and cloud-managed subscription growth in fragmented retail segments.
Inputs from METI certification registries and prefectural procurement databases were available through the study window; gaps in real-time municipal budget execution data introduce uncertainty bands around near-term award timing. Forecasts reflect assumptions regarding edge-AI cost reduction trajectories and cybersecurity guideline evolution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Smart Camera System Market
Video Surveillance Systems
Japan Surveillance Camera Market
Video Surveillance Systems
Smart Doorbell Camera Market
Video Surveillance Systems
United Kingdom Video Surveillance Market
Video Surveillance Systems
Video Surveillance and Vsaas Market
Video Surveillance Systems
Surveillance Camera Systems Market
Video Surveillance Systems
Crawler Camera System Market
Video Surveillance Systems
Wearable and Body-Worn Cameras Market
Video Surveillance Systems
Latin America Video Surveillance Market
Video Surveillance Systems
Asia-Pacific Video Surveillance Storage Market
Video Surveillance Systems
United States Surveillance Storage Market
Video Surveillance Systems
North America Crawler Camera System Market
Video Surveillance Systems
Europe Video Surveillance Systems Market
Video Surveillance Systems
China Surveillance Storage Market
Video Surveillance Systems
Mexico Surveillance Analog Camera Market
Video Surveillance Systems
Security Camera Software Market