
 North America Vascular Graft Market | 2026-2036
North America Vascular Graft Market Size, Share, and Industry Trends Forecast 2026-2036
North America Vascular Graft Market Insights
Single-source procurement for ePTFE graft components is consolidating toward dual-source arrangements across major North American manufacturers. W. L. Gore & Associates leverages its proprietary expanded polytetrafluoroethylene manufacturing to sustain premium positioning in coronary bypass applications. Medtronic anchors its vascular graft portfolio through backward integration into biological tissue processing. Terumo Corporation competes on heparin-bonded surface technologies that reduce thrombogenicity in dialysis access grafts.
A vascular graft is a tubular prosthesis implanted to bypass, replace, or reinforce damaged blood vessels, typically fabricated from polyester, expanded polytetrafluoroethylene, or biological tissue and engineered to withstand pulsatile arterial pressures exceeding 120 mmHg while maintaining patency. Synthetic grafts dominate coronary bypass and aortic aneurysm repair due to standardized mechanical performance and immediate availability, whereas bioprosthetic segments command margin premiums in infected fields or redo operations where host tissue integration proves critical. Hospitals remain the primary end-user channel, though cardiac centers capture growing volumes for complex aortic reconstructions requiring hybrid open-endovascular approaches.
FDA premarket notification and premarket approval pathways govern commercial entry, while ISO 7198 and ASTM F2312 standards define fatigue resistance and compliance testing protocols that manufacturers must satisfy. Health Canada and the FDA coordinate on biocompatibility evaluation frameworks for novel biological tissue sources, tightening documentation requirements for xenograft materials. Stakeholders must monitor evolving CMS reimbursement determinations for endovascular versus open surgical graft placements, as coding revisions will directly shift site-of-service economics and manufacturer contracting leverage.
Market Dynamics
Dialysis access procedure volumes in southeastern United States hospitals are compressing graft procurement timelines and forcing manufacturers to reconfigure regional inventory positioning. The FDA's updated biocompatibility documentation requirements for xenograft materials are simultaneously extending product development cycles while elevating compliance costs for biological tissue processors.
Growth Catalysts
- ISO 7198 fatigue resistance standards:Updated cardiovascular implant testing protocols are accelerating validation of next-generation polyester grafts for aortic aneurysm repair, enabling faster commercialization of compliant woven structures.
- Heparin-bonded surface engineering:Advanced antithrombogenic coatings are reducing thrombosis rates in dialysis access grafts, expanding addressable patient populations with elevated bleeding risk profiles.
- Southeastern United States demographic concentration:Aging populations and cardiovascular disease prevalence in Florida, Georgia, and Alabama are elevating procedure volumes at cardiac centers performing complex aortic reconstructions.
Market Restraints
- Expanded polytetrafluoroethylene supply concentration:Single-source dependence on proprietary ePTFE manufacturers creates vulnerability in synthetic graft component availability during production disruptions.
- FDA premarket approval pathway duration:Extended regulatory review timelines for novel biological tissue sources compress commercialization windows and elevate capital requirements for product development.
- Biological tissue processing cost structure:Xenograft material sourcing and sterilization protocols impose margin pressure that limits price competitiveness against standardized synthetic alternatives.
Strategic Opportunities
- Hybrid open-endovascular procedure expansion:Complex aortic reconstruction techniques are creating demand for graft systems compatible with both surgical and catheter-based delivery methods.
- Health Canada-FDA biocompatibility coordination:Harmonized documentation frameworks for novel biological tissue sources are streamlining cross-border product registration and accelerating North American market entry.
- Cardiac center channel development:Specialized cardiovascular institutions are capturing growing volumes for high-complexity procedures, creating premium positioning opportunities beyond general hospital procurement.
Industry Challenges
- Biological tissue processing certification timelines:Xenograft material qualification protocols require extended validation cycles that delay product launches and compress revenue recognition windows.
- CMS reimbursement coding uncertainty:Pending determinations for endovascular versus open surgical graft placements are freezing hospital capital commitment decisions and manufacturer contracting negotiations.
- Dual-source procurement reconfiguration:Transitioning from single-source to multi-source ePTFE component arrangements requires supply chain restructuring that disrupts established quality assurance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Vascular Graft Market |
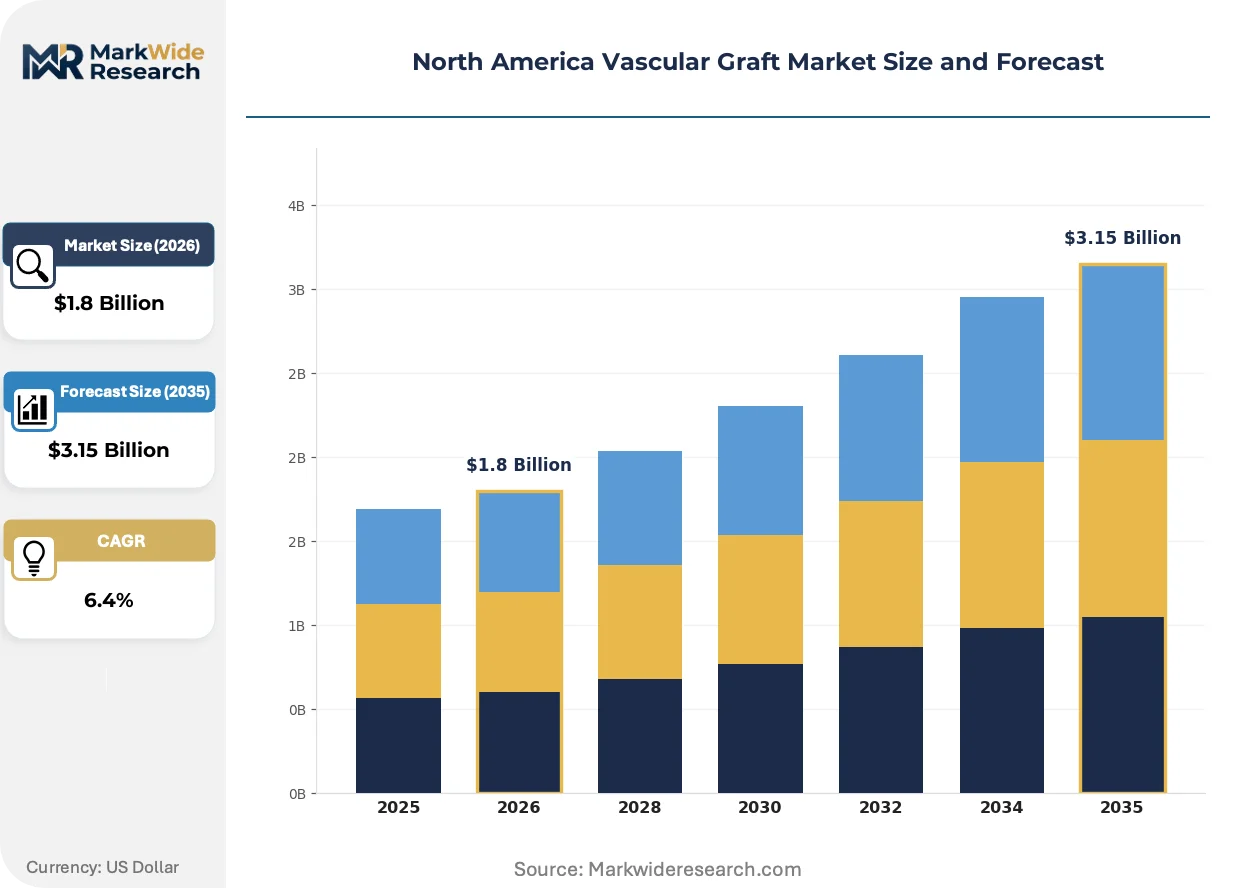
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autologous, Synthetic, Bioprosthetic, Composite Application: Coronary Bypass, Peripheral Vascular, Aortic Aneurysm, Dialysis Access End User: Hospitals, Cardiac Centers, Outpatient Clinics, Specialty Clinics Material: Polyester, Polyurethane, ePTFE, Biological Tissue |
| Companies Covered | Medtronic, W. L. Gore & Associates, Terumo Corporation, B. Braun SE, Becton, Dickinson and Company, Cardinal Health, Cook Medical, LeMaitre Vascular, Getinge AB, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Vascular Graft Market Trends and Innovations
Surface engineering and procedural technique convergence are redefining graft performance benchmarks and procurement criteria across North American cardiovascular centers. These developments are compressing traditional product lifecycle patterns while elevating regulatory scrutiny.
Antithrombogenic coating technologies are decentralizing thrombosis risk management from systemic anticoagulation protocols to localized graft surface engineering. Cardiac centers in high-volume southeastern United States markets are adopting heparin-bonded and phosphorylcholine-coated grafts at accelerated rates for dialysis access procedures. This surface-functionalization shift is decentralizing competitive advantage from material sourcing scale to proprietary coating chemistry capabilities.
FDA coordination with Health Canada on biocompatibility evaluation frameworks is tightening documentation requirements for xenograft materials derived from novel biological tissue sources. Manufacturers must now satisfy dual-jurisdiction validation protocols before commercial launch, extending development timelines by twelve to eighteen months. Biological graft segments face the most acute compliance burden as sterilization validation and immunogenicity testing standards converge across the two regulatory regimes.
Hospital procurement committees are consolidating synthetic graft purchasing through regional cardiac center networks rather than individual institutional contracts. This buyer concentration is displacing fragmented distributor relationships with direct manufacturer agreements negotiated at health system level. The southeastern United States demonstrates the most visible procurement consolidation, where aging demographics and elevated cardiovascular disease prevalence have concentrated procedure volumes at select high-capability institutions.
North America Vascular Graft Market Segmentation
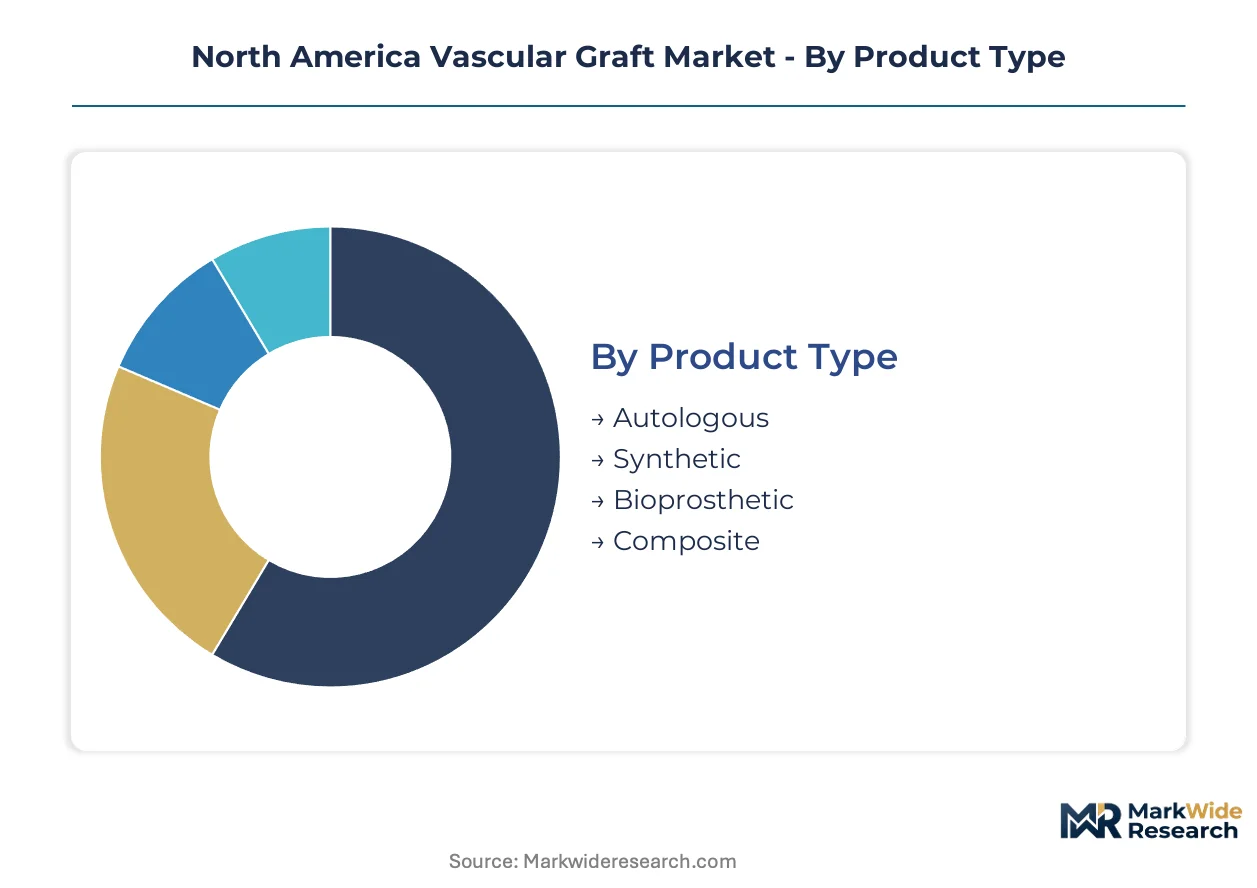
Vascular graft procurement decisions across North America diverge sharply by clinical setting and anatomical target, with material selection and surface engineering specifications driving contract negotiations at cardiac centers and hospital systems.
Product Type:
Standardization dominates synthetic manufacturing while biological grafts require extensive customization for tissue matching and immunogenicity profiles.
- Synthetic:Expanded polytetrafluoroethylene and polyester woven structures deliver standardized mechanical performance for coronary bypass and aortic procedures. Demand concentrates at southeastern United States cardiac centers where high procedural volumes favor immediate graft availability over biological sourcing timelines.
- Bioprosthetic:Xenograft and allograft tissues processed through proprietary decellularization protocols command premium positioning in infected fields and redo operations. Florida and Georgia hospitals drive adoption where aging demographics elevate complex case complexity requiring host tissue integration.
- Autologous:Patient-derived saphenous vein and radial artery harvests remain the gold standard for coronary bypass durability.
- Composite:Hybrid constructions combining synthetic frameworks with biological coatings address thrombogenicity in high-flow applications.
Most installed capacity flows through Synthetic. Expansion is steepest in Bioprosthetic.
Application:
Procedure reimbursement rates and site-of-service economics create distinct margin tiers across anatomical targets.
- Coronary Bypass:Arterial and venous graft configurations for myocardial revascularization demand compliance with pulsatile pressures exceeding 120 mmHg. Cardiac centers in the southeastern United States capture concentrated volumes where cardiovascular disease prevalence sustains high-throughput surgical programs.
- Dialysis Access:Arteriovenous fistula and graft placements for hemodialysis vascularization represent recurring intervention needs. Alabama and Georgia hospitals report compressed procurement timelines as procedure volumes strain regional inventory positioning.
- Aortic Aneurysm:Thoracic and abdominal reconstruction grafts require fatigue resistance validation under ISO 7198 protocols.
- Peripheral Vascular:Lower extremity bypass applications favor synthetic conduits for femoropopliteal reconstruction.
Synthetic grafts dominate Coronary Bypass procurement. Dialysis Access is climbing the fastest as end-stage renal disease prevalence rises.
End User:
Capital commitment thresholds and case complexity stratify purchasing authority across institutional settings.
- Hospitals:General acute care facilities maintain broad vascular surgery capabilities with standardized synthetic graft inventories. The southeastern United States demonstrates visible procurement consolidation as health systems centralize purchasing through regional cardiac center networks.
- Cardiac Centers:Specialized cardiovascular institutions perform complex aortic reconstructions requiring hybrid open-endovascular graft systems. Florida facilities lead adoption of heparin-bonded surface technologies for high-risk patient populations.
- Outpatient Clinics:Ambulatory settings capture dialysis access maintenance procedures with limited graft placement scope.
- Specialty Clinics:Vascular surgery-focused practices concentrate peripheral intervention volumes.
Hospitals retain the largest installed base. Cardiac Centers are gaining share fastest through complex procedure migration.
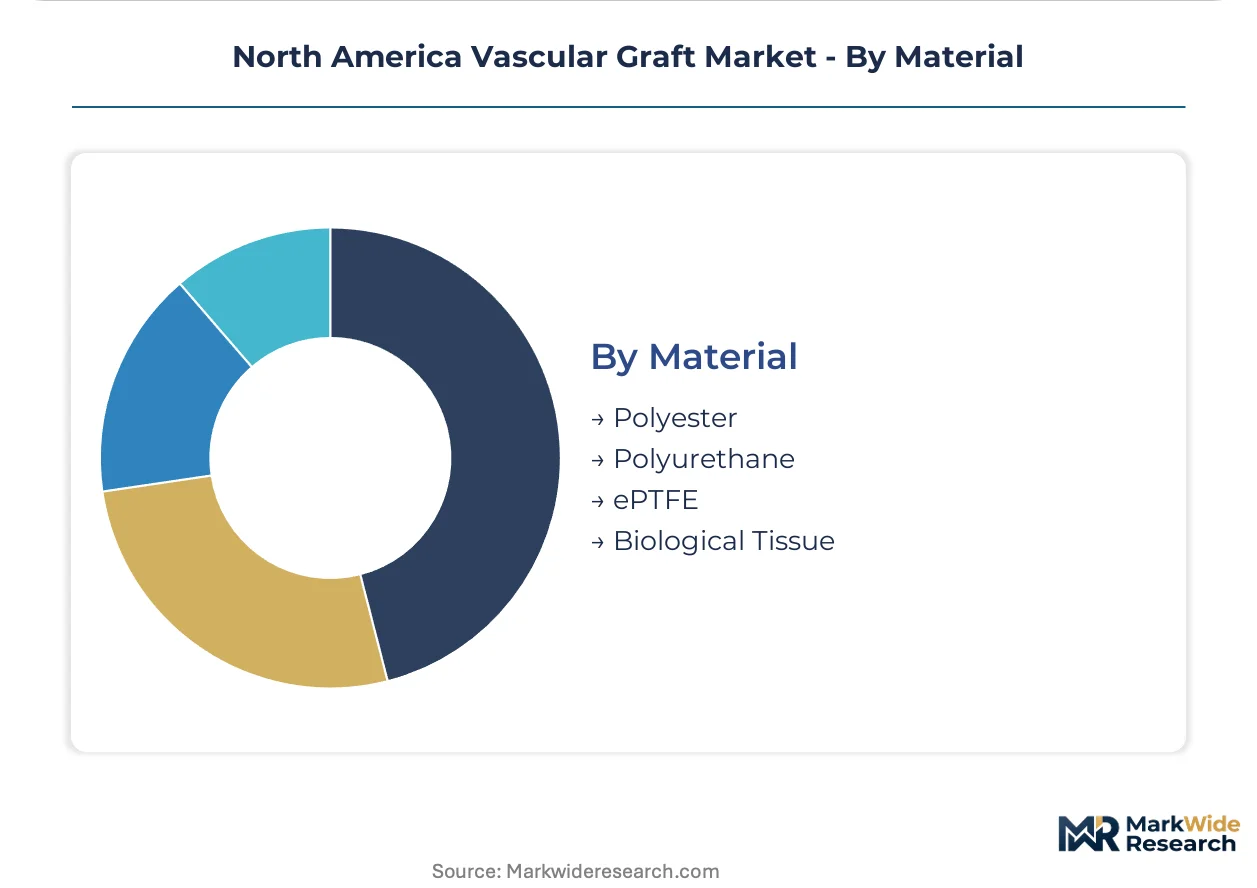
Material:
Supply chain configuration and regulatory documentation burden separate commodity synthetics from biological alternatives.
- ePTFE:Expanded polytetrafluoroethylene manufactured through proprietary stretching protocols delivers microporous structures for tissue ingrowth. W. L. Gore & Associates anchors North American supply with backward-integrated production controlling quality assurance from resin to finished graft.
- Biological Tissue:Bovine pericardium and porcine aortic sources require dual-jurisdiction FDA and Health Canada validation before commercial launch. Xenograft processors face extended sterilization qualification cycles that delay revenue recognition.
- Polyester:Woven and knitted polyethylene terephthalate structures dominate aortic aneurysm repair for mechanical durability.
- Polyurethane:Elastomeric segments address compliance-matched applications in pediatric and small-diameter vessels.
ePTFE commands the largest production footprint. Biological Tissue faces the steepest expansion constraints from regulatory documentation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The southeastern United States industrial corridor anchors North American vascular graft demand through concentrated cardiac center networks and elevated cardiovascular procedure volumes.
United States
Florida, Georgia, and Alabama cardiac centers drive synthetic graft procurement for dialysis access and aortic reconstruction procedures. FDA premarket approval pathways govern commercial entry for novel biological tissue sources, extending development timelines for xenograft processors. The Atlanta and Miami metropolitan clusters concentrate manufacturer inventory positioning to serve compressed procurement timelines at high-volume hospitals.
Canada
Ontario and Quebec health systems coordinate vascular graft purchasing through provincial cardiac care networks. Health Canada biocompatibility evaluation frameworks align with FDA documentation standards for novel biological materials, streamlining cross-border registration for manufacturers. Toronto and Montreal cardiac centers adopt heparin-bonded surface technologies for complex aortic procedures requiring hybrid surgical approaches.
Mexico
Mexico City and Monterrey metropolitan hospitals expand vascular surgery capabilities to serve growing end-stage renal disease populations requiring dialysis access grafts. The national pharmaceutical regulator enforces biocompatibility standards aligned with international ISO protocols for imported cardiovascular implants. Northern border state medical centers concentrate procurement relationships with US-based manufacturers for immediate graft availability.
North America Vascular Graft Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized surface engineering and biological tissue processing capabilities. The vendor base stratifies across three tiers: integrated conglomerates with backward-linked material production, mid-scale specialists focused on antithrombogenic coating technologies, and regional fabricators serving localized procurement networks. Dominant competitive moves include strategic partnerships for dual-source ePTFE component arrangements and portfolio diversification into hybrid open-endovascular graft systems.
Among diversified medical technology conglomerates, Medtronic anchors the biological tissue processing segment through integrated manufacturing capabilities. W. L. Gore & Associates exemplifies the proprietary material tier through captive expanded polytetrafluoroethylene production controlling quality assurance from resin to finished graft. Terumo Corporation occupies a position within the surface engineering specialist tier, representing advanced antithrombogenic coating capabilities for thrombosis-sensitive applications.
| Leading Market Players |
|---|
| Medtronic |
| W. L. Gore & Associates |
| Terumo Corporation |
| B. Braun SE |
| Becton, Dickinson and Company |
| Cardinal Health |
| Cook Medical |
| LeMaitre Vascular |
| Getinge AB |
| Others |
Pricing and Supply Chain Analysis
PTFE resin price indices cascade through North American vascular graft manufacturing, compressing margins for polyester processors while amplifying pricing power for backward-integrated ePTFE producers. Cost pass-through mechanics stratify procurement tiers across hospital systems and cardiac centers.
Pricing Analysis
Input-cost pass-through from proprietary ePTFE resin suppliers concentrates pricing power among manufacturers with captive material production. Three-tier pricing structure across premium heparin-bonded, standard synthetic, and economy polyester levels reflects certification grade and surface engineering complexity. Pricing pressure stems from CMS reimbursement coding uncertainty freezing hospital capital commitments. Dialysis access procurement committees at southeastern United States hospitals demonstrate highest price sensitivity; cardiac centers performing complex aortic reconstructions exhibit lowest sensitivity due to outcome-based procurement criteria.
Supply Chain Analysis
Reverse-logistics flows for explanted biological grafts remain underdeveloped, with most xenograft tissue processors lacking refurbishment protocols for returned products. Manufacturing concentration centers on United States, Germany, and Japan for ePTFE stretching equipment and proprietary resin formulations. Raw material dependencies include medical-grade PTFE resin, bovine pericardium from regulated herds, and pharmaceutical-grade heparin sodium. Single-source vulnerability pervades proprietary ePTFE membrane supply. Distribution runs through regional cardiac center networks consolidating formerly fragmented hospital procurement relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America vascular graft procurement functions as a geographic-arbitrage play between United States FDA premarket approval costs and Health Canada streamlined biocompatibility documentation, with the latter offering faster cross-border registration pathways.
For Market Incumbents: Deepen backward integration into biological tissue processing to defend margin position against synthetic price erosion. Secure dual-source ePTFE component arrangements to mitigate single-source supply disruption risks. Accelerate heparin-bonded surface engineering R&D to maintain premium positioning as antithrombogenic coatings become table stakes. For New Entrants and Emerging Players: Launch via direct contracting with southeastern United States cardiac center networks bypassing established GPO relationships. Target dialysis access graft segments where procurement timelines compress and inventory positioning advantages favor agile suppliers. Pursue Health Canada-FDA harmonized biocompatibility pathways to accelerate North American market entry against entrenched competitors. For Investors and Strategic Acquirers: Asymmetric upside sits with surface engineering specialists possessing proprietary antithrombogenic coating chemistry. Five-to-ten year viability hinges on hybrid open-endovascular graft system capabilities bridging surgical and catheter-based delivery. Acquisition target archetype: mid-scale biological tissue processors with validated xenograft sterilization protocols. Monitor FDA premarket approval pathway duration trends as inflection indicator for development cycle economics.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Extended FDA review timelines compress commercialization windows for novel biological tissue sources. |
| Hospital System Partnership | Direct agreements with southeastern United States cardiac center networks displace fragmented distributor relationships. |
| Backward Integration | Captive ePTFE resin-to-graft production controls quality assurance and insulates margin from input volatility. |
| Reimbursement Strategy | CMS coding determinations for endovascular versus open surgical placements shift site-of-service economics. |
| CE Marking Pathway | Health Canada-EU regulatory alignment streamlines cross-border registration for North American manufacturers. |
Research Methodology
Coverage spans United States, Canada, and Mexico, with primary inputs from each jurisdiction's regulatory and procurement stakeholders. Primary interviews incorporated vascular surgeons, hospital purchasing committee directors, biomedical engineers, GPO contracts managers, and regulatory affairs leads at cardiovascular device manufacturers. Secondary validation drew from FDA 510(k) and PMA filings, Health Canada medical device licenses, CMS Medicare reimbursement databases, hospital procurement records, and ISO 7198 standard documentation. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue allocations.
Granularity-level modeling deployed product type, application, end user, and material dimensions at the country level, with sub-regional clustering for United States southeastern state cardiac centers. CAGRs derived from logistic adoption curves fitted to historical procedure volumes and projected demographic shifts. Forecast inputs included end-stage renal disease prevalence trajectories, cardiovascular disease incidence patterns, and regulatory approval pipeline status.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged FDA premarket approval delays or abrupt CMS reimbursement recalibration. Forecasts reflect documented assumptions regarding ISO standard adoption timelines and health system consolidation trajectories. Practitioners should monitor FDA-Health Canada biocompatibility framework harmonization progress and southeastern United States cardiac center procurement committee formation patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Bioresorbable Coronary Stents Market
Cardiovascular Devices
Extracorporeal Membrane Oxygenation (ECMO) Market
Cardiovascular Devices
Interventional Cardiology Market
Cardiovascular Devices
Renal Denervation Devices Market
Cardiovascular Devices
Percutaneous Coronary Intervention Market
Cardiovascular Devices
Vascular Access Catheters Market
Cardiovascular Devices
Global Aortic Valve Market
Cardiovascular Devices
Branched Stent Grafts Market
Cardiovascular Devices
Infusion System Market
Cardiovascular Devices
Balloon Catheters Market
Cardiovascular Devices
Epinephrine Auto-Injectors Market
Cardiovascular Devices
Latin America Compression Therapy Market
Cardiovascular Devices
Germany Cardiovascular Devices Market
Cardiovascular Devices
Arteriovenous (Av) Fistula Needle Market
Cardiovascular Devices
Global Coil Wound Devices Market
Cardiovascular Devices
Point-Of-Care Cholesterol Monitoring Device Market